
 Sports Protection Equipment Market | 2026-2036
Sports Protection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Protection Equipment Market Intelligence
Multi-source sourcing toward hybrid in-house and outsourced manufacturing is rebalancing cost structures across the sports protection equipment supply chain. Nike Inc. leverages its scale to control premium material streams for helmet shells and face masks. Adidas AG anchors European distribution through specialized retail partnerships in Germany and France. BRG Sports sustains North American market presence with deep product specialization in football and hockey protective systems.
Sports protection equipment encompasses engineered wearable apparatus designed to absorb, disperse, or deflect kinetic energy from collisions, incorporating multi-density EVA foam liners bonded to polycarbonate or thermoplastic outer shells. These systems serve to reduce traumatic injury incidence across organized athletic competition and recreational activity. Helmets and pads capture the dominant share of product-type revenue due to mandatory-use policies in contact sports. Mouthguards represent the fastest-expanding category as dental injury awareness rises among school teams and recreational players. Material innovation concentrates in polycarbonate and thermoplastic segments where impact-resistance-to-weight ratios determine competitive positioning.
NOCSAE certification requirements in the United States govern football helmet performance testing, while the EU PPE Regulation mandates conformity assessment for protective gear sold across European member states. China's GB standards and MIIT directives shape domestic manufacturing specifications for export-oriented producers. Stakeholders must monitor evolving biomechanical research that could trigger updates to impact-threshold standards and force material platform transitions before regulatory deadlines.
Market Dynamics
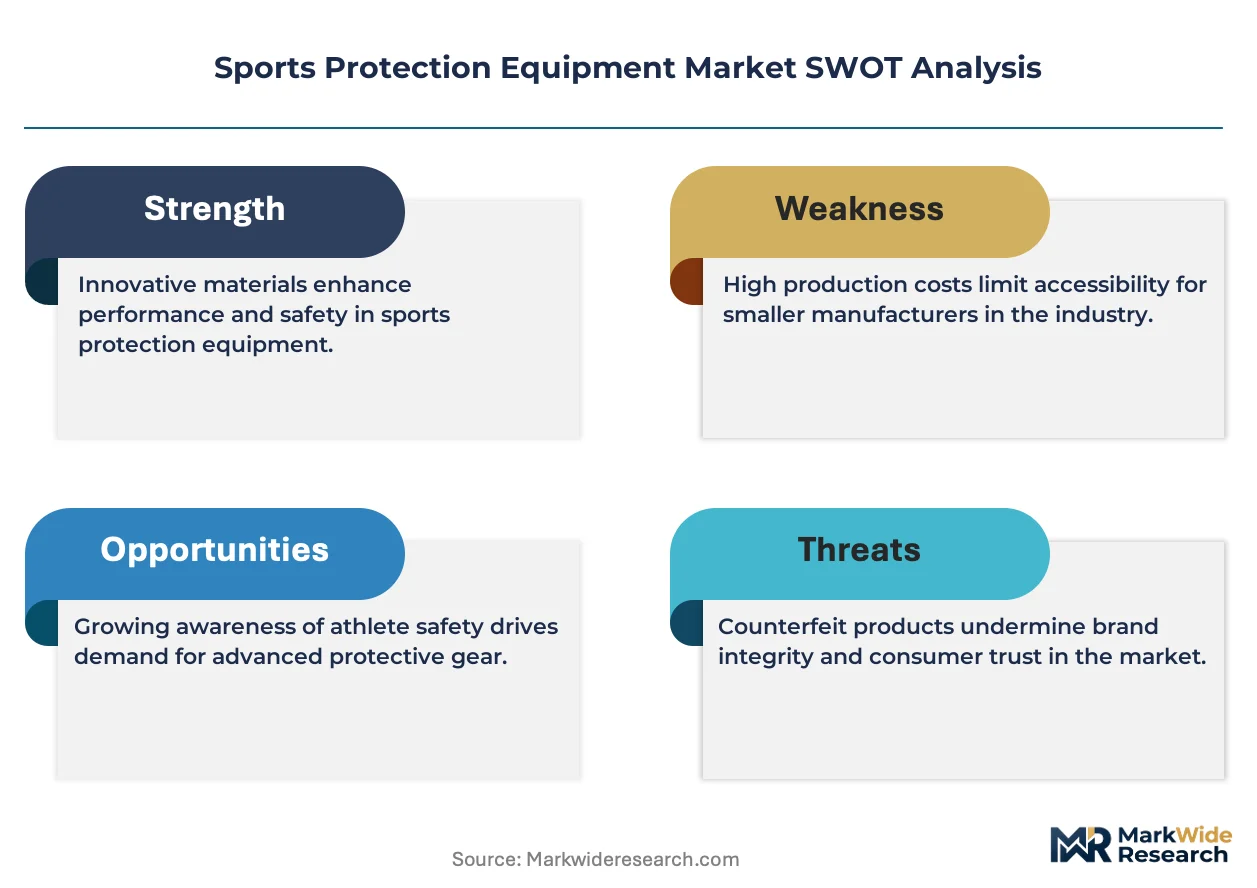
NOCSAE certification deadlines and EU PPE conformity assessments are compressing material upgrade cycles, forcing manufacturers to retire legacy foam platforms before amortization. This regulatory velocity is consolidating procurement around suppliers with in-house testing labs and pre-certified component libraries.
Growth Catalysts
- NOCSAE standard revisions:Updated impact-threshold testing for football helmets accelerates replacement demand across U.S. collegiate and high school programs. Equipment managers face mandatory re-certification windows.
- China's sports academy expansion:Provincial governments in Sichuan and Guangdong are funding professional-grade protective gear procurement for youth development pipelines. Domestic manufacturers scale polycarbonate shell production to capture this institutional demand.
- Multi-density EVA foam bonding:Advanced lamination techniques improve energy dispersion without weight penalties. Hockey and lacrosse equipment lines adopt these liners as baseline specifications.
Market Restraints
- Polycarbonate resin price volatility:Petrochemical feedstock fluctuations compress margin structures for helmet shell producers. Long-term supply agreements with Saudi and Korean resin suppliers carry volume minimums that strain mid-tier manufacturers.
- Testing infrastructure concentration:NOCSAE-accredited laboratories cluster in Ohio and Texas, creating certification bottlenecks for Asian and European entrants seeking U.S. market access.
- Biomechanical research gaps:Limited longitudinal data on repetitive sub-concussive impacts slows regulatory consensus on next-generation performance thresholds.
Strategic Opportunities
- India's school sports mandate expansion:Ministry of Education directives requiring protective gear for contact sports in government schools create first-mover openings for certified importers. BIS standards alignment remains the entry barrier.
- Smart sensor integration:Convergence of accelerometer arrays with traditional helmet architectures enables real-time impact monitoring. Youth leagues represent the initial adopter segment.
- Direct-to-team e-commerce channels:Equipment managers bypass traditional sporting goods retailers through manufacturer portals with custom fitting tools and bulk configuration interfaces.
Industry Challenges
- Biomechanical engineer scarcity:Specialized talent for impact simulation and materials modeling concentrates at elite research universities and large manufacturers, constraining R&D scaling for mid-market players.
- Multi-jurisdiction certification parallelism:Simultaneous NOCSAE, CE marking, and GB standard compliance requires redundant testing protocols that extend product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Protection Equipment Market |
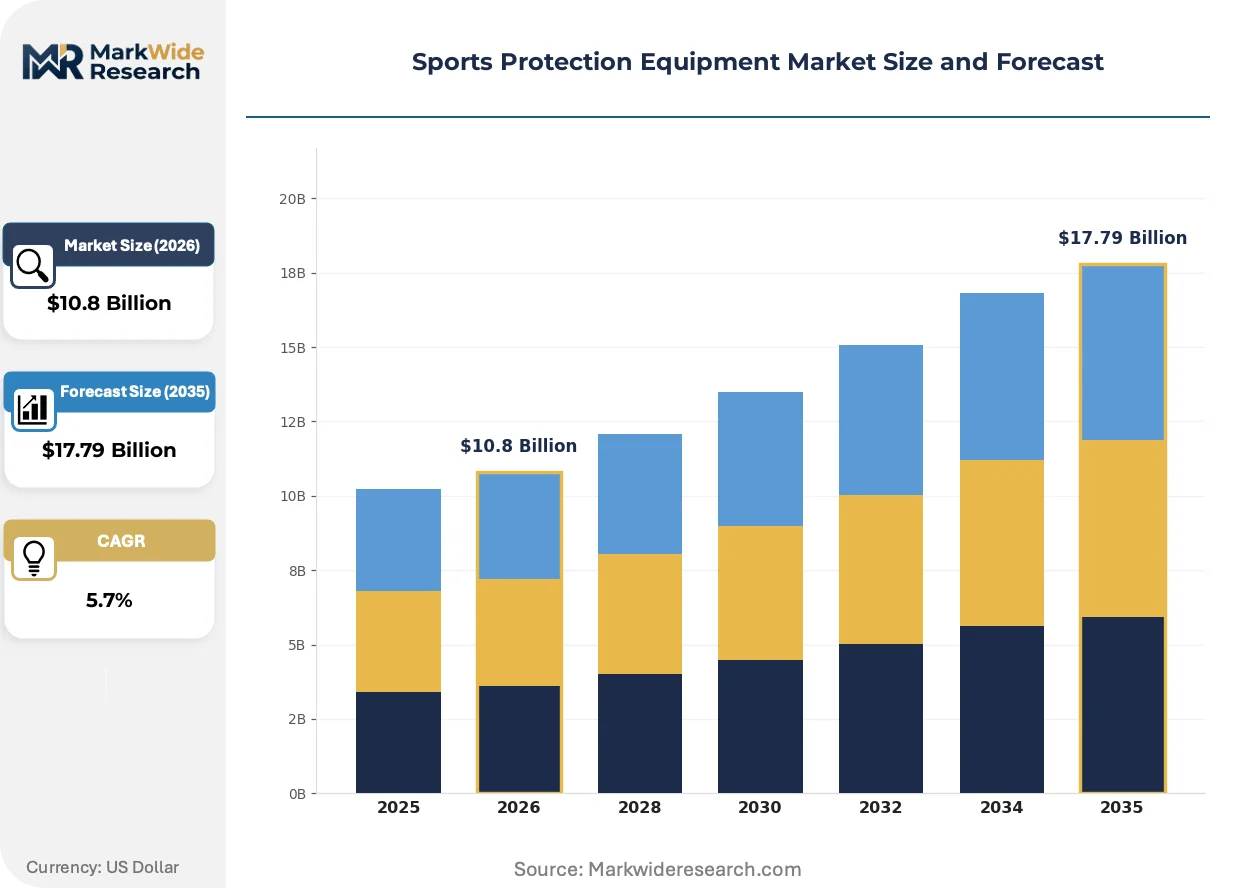
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $17.79 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helmets, Pads, Guards, Mouthguards, Gloves, Shin Guards Material: Polycarbonate, EVA Foam, Neoprene, Nylon, Silicone, Thermoplastic Application: Contact Sports, Water Sports, Winter Sports, Cycling, Martial Arts, Equestrian End User: School Teams, Professional Athletes, Recreational Players, Sports Academies |
| Companies Covered | Nike Inc., Adidas AG, Amer Sports, Under Armour, Puma SE, BRG Sports, Schutt Sports, Bauer Hockey, Riddell Sports Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Protection Equipment Market Strategic Shifts & Innovations
Material science advances and sensor miniaturization are reconfiguring product architectures across contact sports. Manufacturers now compete on real-time data integration and adaptive fit systems rather than passive protection alone.
Non-Newtonian shear-thickening fluids embedded in flexible pad layers is consolidating the traditional foam-and-shell paradigm. These materials remain soft during normal motion but stiffen instantaneously under impact. NCAA football programs and professional rugby clubs in New Zealand and England are piloting these systems for position-specific protection. The technology is consolidating supplier tiers by rewarding chemistry capabilities over conventional molding expertise.
EU PPE Regulation 2016/425 enforcement intensifies conformity assessment documentation for protective gear sold across member states. Notified bodies in Germany and France are expanding audit scope to include supply chain chemical compliance beyond finished-product testing. Mouthguard and facial protection manufacturers face the steepest compliance ramps as these categories shift from sports accessories to regulated PPE classification.
Youth league administrators now mandate dental injury waivers tied to certified mouthguard use, altering procurement authority structures. School district risk managers have displaced individual coaches as primary equipment decision-makers, consolidating purchasing into annual bid contracts with specified certification requirements. This shift concentrates order volumes with suppliers holding NOCSAE and ADA Seal acceptance documentation, most visible in Texas and Florida public school systems.
Sports Protection Equipment Market Segmentation
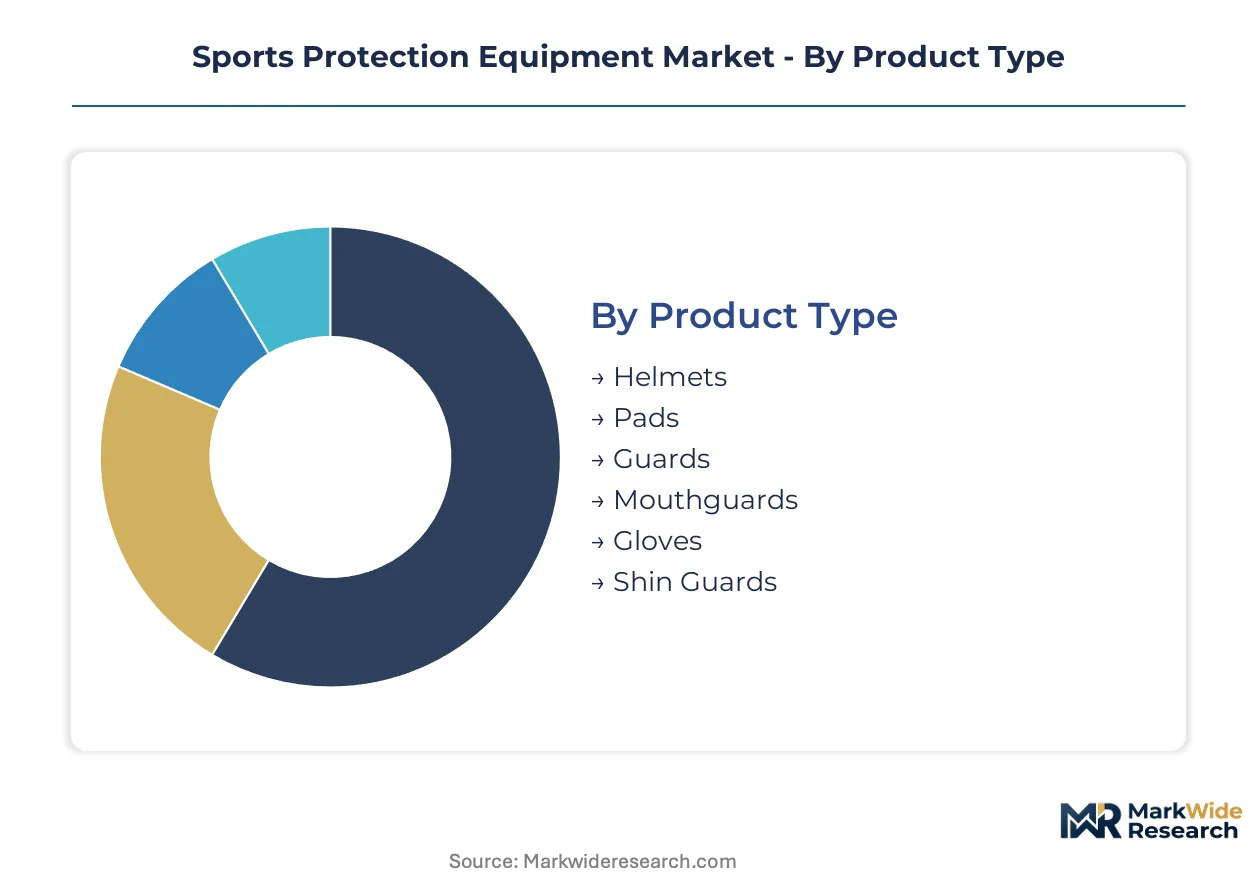
Sports protection equipment segmentation reveals how material science, sport-specific biomechanics, and procurement authority structures fragment demand across distinct technical specifications. Equipment managers, coaches, and individual athletes each impose different performance thresholds and certification requirements that reshape manufacturing priorities.
Product Type:
Customization intensity varies dramatically across this category, from mandatory standardized helmets to personalized mouthguard molding services that dental practices now bundle with team contracts.
- Helmets:Multi-density foam liners bonded to polycarbonate shells absorb and disperse impact energy across football, hockey, and cycling applications. NOCSAE certification requirements in the United States compress replacement cycles for collegiate and high school programs. Most installed capacity flows through Helmets. Expansion is steepest in Mouthguards.
- Pads:Shoulder, hip, and thigh pads incorporate segmented foam arrays that maintain mobility while distributing collision forces across contact sport athletes. Texas and Florida public school systems consolidate annual bid contracts around specified pad configurations, displacing individual coach purchasing authority.
- Guards:Elbow, knee, and wrist guards target joint protection across skateboarding, roller sports, and aggressive inline disciplines.
- Mouthguards:Thermoplastic boil-and-bite systems and custom dental impressions prevent traumatic dental injuries. School district risk managers now mandate certified mouthguard use with injury waivers, creating procurement concentration around ADA Seal acceptance documentation.
- Gloves:Padded palm constructions and reinforced knuckle protection serve boxing, MMA, baseball batting, and cycling grip applications.
- Shin Guards:Hard shell or foam-sleeve designs protect against direct impact in soccer, baseball catching, and martial arts sparring.
Volume manufacturing clusters around Helmets and Pads due to mandatory-use policies. Mouthguards are gaining share fastest as dental injury liability reshapes school procurement.
Material:
Cost tier stratification separates premium impact-engineered compounds from commodity foam substitutes, with resin price volatility compressing margins at the mid-market boundary.
- Polycarbonate:High-impact thermoplastic resins form rigid helmet shells and face mask structures where strength-to-weight ratios determine competitive positioning. Petrochemical feedstock fluctuations from Saudi and Korean suppliers strain long-term volume commitments for shell producers.
- EVA Foam:Ethylene-vinyl acetate closed-cell structures provide lightweight energy absorption in multi-density liner laminations. Advanced bonding techniques now displace single-density foam platforms across hockey and lacrosse equipment lines.
- Neoprene:Synthetic rubber sheets deliver compression and thermal insulation in joint sleeves and wetsuit-integrated protection.
- Nylon:Woven ballistic fabrics reinforce cut-resistant glove palms and abrasion-facing pad exteriors.
- Silicone:Medical-grade formulations enable custom-fit mouthguard molding with dental practice distribution channels.
- Thermoplastic:Injection-moldable polymers allow complex geometries in shin guards and lightweight helmet components with shorter production cycles than thermoset alternatives.
Polycarbonate and EVA Foam absorb the majority of material procurement spend. Silicone mouthguard compounds are expanding most quickly through dental channel partnerships.
Application:
Customer type fragmentation separates institutional bulk purchasers from individual recreational buyers, with certification requirements and liability exposure driving divergent specification thresholds.
- Contact Sports:Football, hockey, rugby, and lacrosse equipment face the most stringent NOCSAE and EU PPE conformity mandates. Equipment managers at U.S. collegiate programs face mandatory re-certification windows that accelerate replacement demand.
- Water Sports:Impact vests, helmets, and wetsuit-integrated padding serve wakeboarding, kiteboarding, and competitive sailing where buoyancy and hydrodynamics constrain design freedom.
- Winter Sports:Ski and snowboard helmets incorporate ventilation systems and goggle integration features distinct from contact sport designs.
- Cycling:Road, mountain, and BMX helmet categories split between aerodynamic road racing shells and extended-coverage gravity discipline designs.
- Martial Arts:Headgear, gloves, shin guards, and mouthguards balance protection against mobility requirements for striking and grappling disciplines.
- Equestrian:Riding helmets face distinct ASTM certification paths with coverage and retention system specifications tailored to fall dynamics from height.
Contact Sports command the deepest certification infrastructure and highest average unit values. Cycling helmets are climbing the fastest as urban mobility programs and e-bike adoption expand addressable demand.
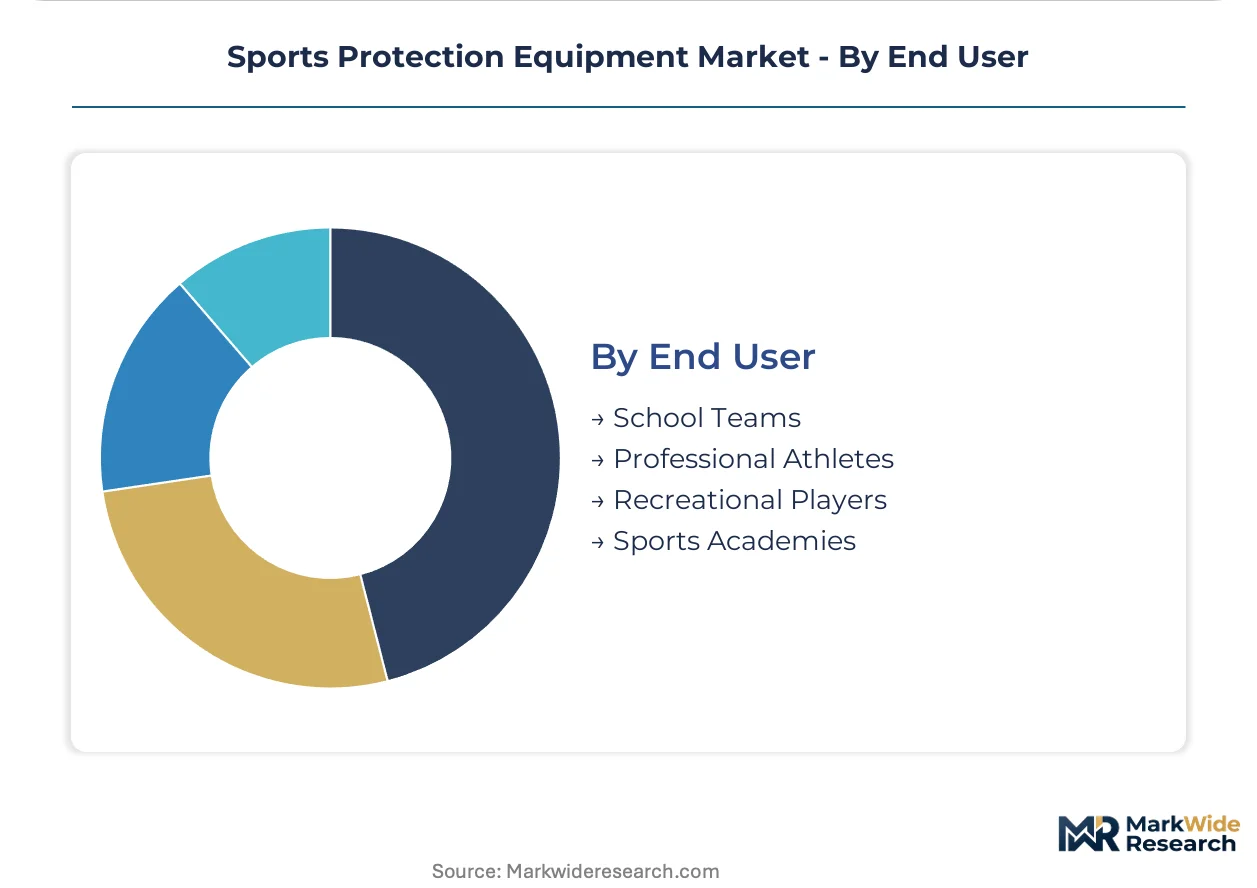
End User:
Procurement authority structures have shifted dramatically, with risk managers and district administrators displacing coaches as primary decision-makers across institutional segments.
- School Teams:Public school districts in Texas and Florida now consolidate protective gear purchasing into annual bid contracts with specified NOCSAE and ADA documentation requirements. This concentration rewards suppliers with pre-certified component libraries.
- Professional Athletes:Elite competitors demand position-specific customization and early access to emerging materials like non-Newtonian shear-thickening fluid pads. NCAA football programs and professional rugby clubs in New Zealand pilot these systems.
- Recreational Players:Individual adult participants purchase through sporting goods retail and direct-to-consumer channels with price sensitivity and brand recognition driving selection.
- Sports Academies:Provincial governments in Sichuan and Guangdong fund professional-grade protective gear procurement for youth development pipelines, creating institutional demand concentration for domestic Chinese manufacturers.
School Teams generate the most predictable volume through multi-year district contracts. Sports Academies are expanding most quickly as China's domestic development infrastructure scales polycarbonate shell production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong Province anchors production capacity for polycarbonate helmet shells serving domestic sports academies and export markets. Provincial government procurement programs in Sichuan and Guangdong are scaling professional-grade protective gear for youth development pipelines. Certification bottlenecks at NOCSAE-accredited laboratories in Ohio and Texas constrain Asian and European manufacturers seeking U.S. market entry.
United States
Texas and Florida public school systems consolidate annual bid contracts for football helmets and pads, displacing individual coach purchasing authority. NOCSAE certification requirements compress replacement cycles for collegiate and high school programs facing mandatory re-certification windows. Equipment managers in Ohio and Texas cluster near NOCSAE-accredited testing laboratories, creating geographic concentration in certification infrastructure.
China
Domestic sports academies in Sichuan and Guangdong provinces expand procurement of professional-grade protective gear for youth development pipelines. MIIT directives and GB standards shape manufacturing specifications for export-oriented polycarbonate shell producers. The Pearl River Delta concentrates injection-molding capacity serving both domestic institutional demand and North American helmet component orders.
Germany
Notified bodies in Germany expand audit scope under EU PPE Regulation 2016/425 to include supply chain chemical compliance beyond finished-product testing. Specialized retail partnerships in Germany and France anchor European distribution networks for premium protective gear. Bavaria-based testing laboratories serve conformity assessment demand from manufacturers across Central European markets.
India
Ministry of Education directives requiring protective gear for contact sports in government schools create first-mover openings for certified importers. BIS standards alignment remains the primary entry barrier for foreign manufacturers seeking institutional procurement contracts. Maharashtra and Gujarat industrial corridors develop domestic molding capacity to serve school sports mandate expansion.
Sports Protection Equipment Market Key Industry Players
Global majors compete with regional champions across certification infrastructure and material supply chains, producing a tiered structure where scale-driven players control premium resin streams while specialized fabricators dominate sport-specific segments. The vendor base separates into three strategic archetypes: diversified sporting goods conglomerates with in-house testing capabilities, pure-play protection equipment specialists with deep product line concentration, and regional manufacturers scaling domestic capacity to capture institutional procurement. Dominant competitive moves include backward integration into polycarbonate resin sourcing and geographic expansion through notified body partnerships for EU PPE conformity assessment.
Among diversified sporting goods conglomerates, Nike Inc. and Adidas AG exemplify the scale-driven archetype with integrated control over material procurement and distribution infrastructure. BRG Sports occupies a position within the protection equipment specialist tier, representing deep product specialization in football and hockey protective systems. These three companies anchor competitive positioning across the certification-intensive institutional procurement channel.
| Leading Market Players |
|---|
| Nike Inc. |
| Adidas AG |
| Amer Sports |
| Under Armour |
| Puma SE |
| BRG Sports |
| Schutt Sports |
| Bauer Hockey |
| Riddell Sports Group |
| Others |
Cost & Logistics Intelligence
Captive polycarbonate resin sourcing through long-term offtake agreements with Saudi and Korean petrochemical suppliers anchors pricing power for helmet shell manufacturers while exposing mid-tier competitors to margin compression during feedstock volatility cycles. This integration choice separates premium-positioned players with volume-backed resin commitments from price-takers forced into spot market exposure.
Pricing Analysis
Petrochemical feedstock pass-through clauses in resin supply contracts transmit polycarbonate price swings directly into helmet shell manufacturing costs within one to two quarters. Three-tier pricing structure across premium, standard, and economy levels separates NOCSAE-certified collegiate equipment from recreational-grade alternatives, with certification grade and volume scale as the primary differentiation drivers. Pricing pressure stems from polycarbonate resin volatility that strains mid-tier manufacturers locked into long-term volume minimums. School district procurement teams exhibit the highest price sensitivity through consolidated annual bid contracts, while professional athletes and sports academies prioritize performance specifications over unit cost.
Supply Chain Analysis
NOCSAE and EU PPE certification gating concentrates qualified supply among manufacturers with in-house testing laboratories and pre-certified component libraries, creating procurement bottlenecks for unaccredited entrants. Manufacturing capacity clusters in China, the United States, and Germany, with the Pearl River Delta anchoring injection-molding operations for polycarbonate shells. Raw material dependencies rest on Saudi and Korean petrochemical feedstocks, multi-density EVA foam compounds, and medical-grade silicone formulations. Single-source vulnerability around NOCSAE-accredited testing laboratories in Ohio and Texas creates certification chokepoints for Asian and European manufacturers seeking U.S. market access. Distribution runs through specialized sporting goods retailers, direct-to-team e-commerce portals, and dental practice channels for custom mouthguard fitting services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sports protection equipment market functions as a stable compounder anchored by mandatory-use policies in organized athletics that institutionalize replacement demand regardless of discretionary spending cycles.
For Market Incumbents: Extend certification infrastructure advantages by accelerating pre-certified component library expansion before NOCSAE standard revisions trigger mandatory platform transitions. Deepen backward integration into polycarbonate resin sourcing through captive offtake agreements with Saudi and Korean suppliers to defend margin position against petrochemical volatility. Channel control through direct-to-team e-commerce portals with custom fitting tools consolidates procurement relationships with equipment managers displacing traditional retailers.
For New Entrants and Emerging Players: Capture India's school sports mandate expansion by aligning product portfolios with BIS standards before domestic molding capacity in Maharashtra and Gujarat reaches scale. Target provincial sports academy procurement in Sichuan and Guangdong through partnerships with domestic Chinese manufacturers lacking NOCSAE certification for export markets. Smart sensor integration for real-time impact monitoring offers a differentiated go-to-market angle among youth leagues seeking liability reduction through data-driven safety protocols.
For Investors and Strategic Acquirers: Roll-up economics work for regional protection equipment specialists with deep product line concentration in single sports because certification infrastructure investments create durable moats against unaccredited competitors. The five-to-ten year viability window favors manufacturers with established notified body relationships for EU PPE conformity assessment and NOCSAE-accredited testing capabilities. Acquisition target archetypes include mid-tier helmet and pad producers with underutilized certification assets and dental channel mouthguard specialists with ADA Seal acceptance. The signal to watch is biomechanical research publication velocity that could trigger accelerated impact-threshold standard revisions and force material platform transitions ahead of amortization schedules.
| Strategic Initiative | Industry Significance |
|---|---|
| NOCSAE Pre-Certification Investment | Accelerates U.S. market entry by compressing product launch timelines through accredited testing partnerships. |
| Backward Integration into Resin Sourcing | Secures volume-backed polycarbonate supply commitments with Saudi and Korean petrochemical suppliers. |
| Smart Sensor Platform Development | Enables real-time impact monitoring convergence with traditional helmet architectures for youth league adoption. |
| Dental Channel Partnership Expansion | Captures mouthguard procurement concentration through ADA Seal acceptance and custom molding service bundling. |
| Direct-to-Team E-Commerce Launch | Bypasses traditional sporting goods retailers with bulk configuration interfaces for equipment managers. |
Research Approach
Bottom-up sports academy and school district procurement modeling reconciled against top-down polycarbonate shell production tracking forms the analytical core of this study. Primary interviews with equipment managers at U.S. collegiate programs, NOCSAE laboratory directors, sports academy procurement officers in Sichuan and Guangdong, dental practice distributors, and petrochemical supply planners combined with secondary validation. Secondary sources include NOCSAE certification databases, EU PPE notified body audit records, U.S. public school district bid contract filings, Chinese MIIT directive publications, and polycarbonate resin trade flow data from customs authorities. Bottom-up and top-down triangulation reconciles institutional procurement volumes against manufacturing capacity utilization.
Historical trendline analysis of helmet and pad replacement cycles, mouthguard adoption rates, and material platform transitions informs the projection framework across the analysis window. Segmentation dimensions modeled include product type, material composition, application discipline, and end-user procurement authority structure. CAGRs derive from fitted growth curves applied to certified equipment penetration rates and sports academy infrastructure buildout trajectories. Industry-specific forecast inputs incorporate NOCSAE standard revision probability assessments and provincial government funding commitments for youth development pipelines.
Polycarbonate resin price volatility, NOCSAE standard revision timing, and BIS standards implementation delays are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding certification infrastructure capacity and regulatory enforcement intensity. A model refresh is warranted upon material change in NOCSAE impact-threshold testing protocols or EU PPE Regulation audit scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Rowing Oars Market
Sports Equipment
Middle East and Africa Stand-Up Paddleboard Market
Sports Equipment
Bicycle Crankset Market
Sports Equipment
Ladderball Market
Sports Equipment
Bike Saddles Market
Sports Equipment
Mixed Martial Arts Equipment Market
Sports Equipment
Ice Hockey Equipment Market
Sports Equipment
Football Equipment Market
Sports Equipment
Tennis Pole Market
Sports Equipment
GCC Running Gear Market
Sports Equipment
Mouthguard Market
Sports Equipment
Figure Skating Equipment Market
Sports Equipment
Europe Ski Gear and Equipment Market
Sports Equipment
Gym Rubber Flooring Market
Sports Equipment
Global Golf Accessories Market
Sports Equipment
Global Darts Market