
 Power Sports Market | 2026-2036
Power Sports Market Size, Share, and Industry Trends Forecast 2026-2036
Power Sports Market Analysis
The EU Green Deal is rebalancing power sports procurement toward lower-emission platforms across European distribution channels. Polaris Inc. anchors North American side-by-side manufacturing scale through captive engine production and dealer network density. Yamaha Motor Co., Ltd. leads marine propulsion electrification with integrated battery-electric personal watercraft development. BRP Inc. specializes in Ski-Doo snowmobile thermal efficiency improvements that sustain cold-climate market share against seasonal demand fluctuation.
Power sports encompass motorized recreational vehicles engineered for off-highway terrain, water surfaces, or snow-covered environments, typically featuring displacement engines from 50cc to over 1000cc with chassis systems optimized for traction, flotation, or suspension travel exceeding 12 inches. These vehicles serve commercial tour operations, competitive racing circuits, and private leisure consumers requiring specialized performance outside standard transportation infrastructure. Motorcycles retain the largest revenue pool across product categories due to established aftermarket parts economics and licensing accessibility, while electric fuel type variants represent the fastest-expanding margin segment as battery energy density improves and charging infrastructure penetrates trailhead locations. Recreational users dominate end-user volume, though professional racers command disproportionate accessory spending through sponsorship-linked equipment turnover.
EPA emission certification under 40 CFR Part 1051 governs off-road recreational engine exhaust limits, compelling manufacturers to invest in direct injection and catalytic after-treatment systems that raise production costs but barrier non-compliant imports. The EU F-Gas Regulation and REACH chemical restrictions additionally constrain refrigerant choices in climate-controlled vehicle cabins and material composition in hull manufacturing. California Air Resources Board zero-emission vehicle mandates for 2035 onward are accelerating electric platform development commitments. Stakeholders must monitor state-level trail access policy divergence between emission-restrictive and recreation-promoting jurisdictions to align product portfolio regionalization with distribution channel investment.
Market Dynamics
Power sports manufacturers face a structural pivot as EPA emission certification under 40 CFR Part 1051 forces gasoline engine architecture redesigns while battery-electric platforms capture trail access advantages in emission-restrictive states.
Growth Catalysts
- California Air Resources Board zero-emission mandates:The 2035 phase-out of gasoline-powered recreational vehicles in California is compelling manufacturers to accelerate electric platform development and secure charging infrastructure partnerships at trailhead locations.
- Off-road recreational tourism fleet expansion:Commercial tour operators in Colorado and Florida are scaling side-by-side and personal watercraft purchases to capture inbound adventure tourism demand.
- Lithium-ion energy density improvements:Battery pack gravimetric energy density advances above 300 Wh/kg are enabling electric ATV range parity with 400cc gasoline equivalents for single-day trail use.
Market Restraints
- Catalytic after-treatment cost inflation:EPA-compliant direct injection systems and exhaust catalysts add $800-$1,200 per gasoline unit, compressing margin on entry-level displacement categories.
- Seasonal demand concentration in snowbelt states:Ski-Doo and snowmobile revenue collapses 60-70% during April-September, forcing working capital intensity that electric platforms cannot yet offset.
- Substitution by electric mountain bikes:Class 1 and Class 3 e-MTBs priced under $6,000 are capturing casual trail riders who previously purchased entry-level ATVs.
Strategic Opportunities
- EU Green Deal procurement rebalancing:European distribution channels are prioritizing lower-emission platforms, creating first-mover advantage for manufacturers with certified electric or hybrid lineups.
- Integrated battery-electric personal watercraft:Marine propulsion electrification remains underdeveloped relative to land vehicles, offering white space for hull-integrated battery thermal management innovation.
- Subscription-based fleet management:Commercial operators are piloting usage-based pricing models that bundle vehicles, maintenance, and trail permits into monthly service contracts.
Industry Challenges
- Power electronics thermal management expertise:Battery-electric propulsion requires motor controller and inverter engineering capabilities foreign to legacy gasoline engine houses, forcing talent acquisition in automotive-adjacent labor markets.
- Multi-jurisdictional certification timelines:Separate EPA, CARB, and EU F-Gas compliance pathways for engine exhaust, evaporative emissions, and refrigerant systems extend product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Sports Market |
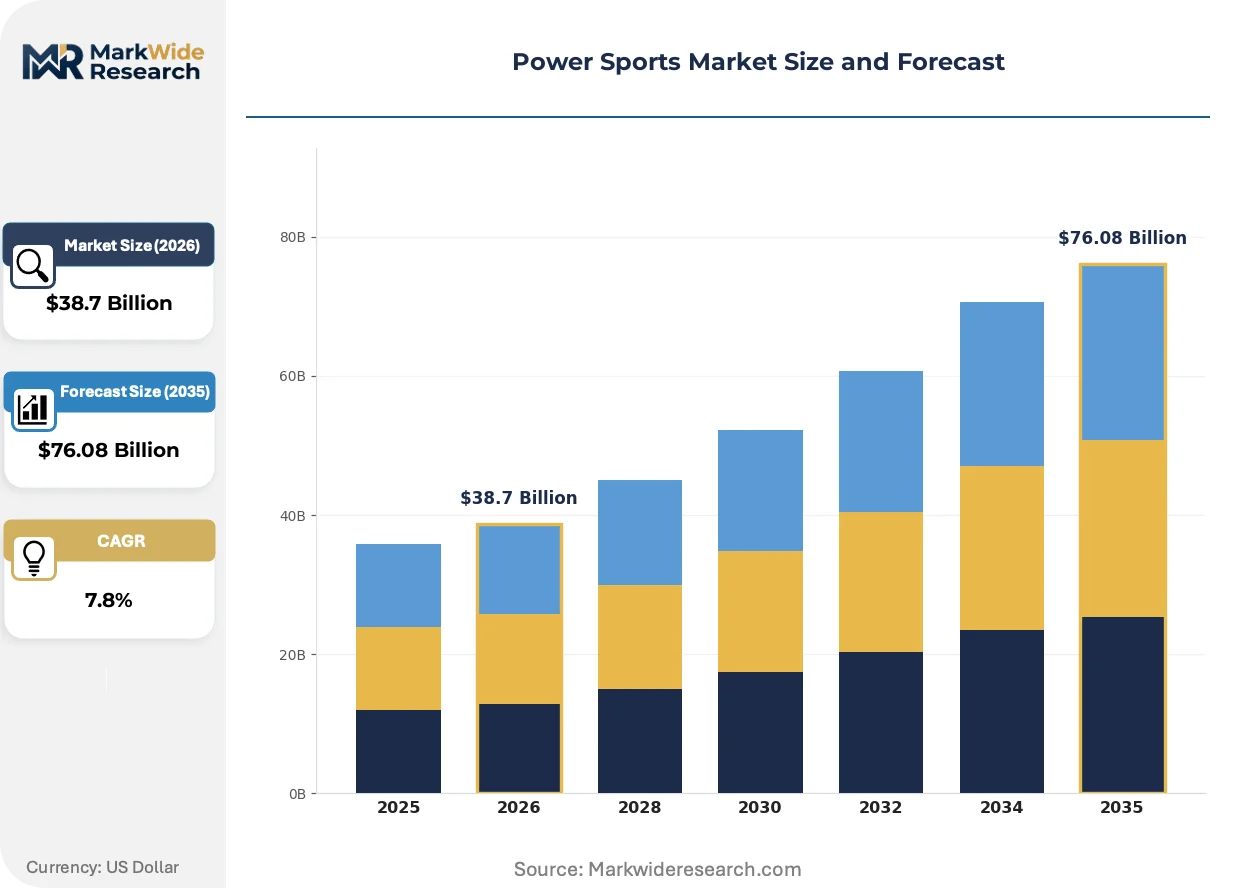
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $76.08 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ATVs, Motorcycles, Snowmobiles, Personal Watercraft End User: Recreational Users, Professional Racers, Enthusiasts, Tour Operators Fuel Type: Gasoline, Electric, Diesel, Hybrid Distribution Channel: Online Retail, Dealerships, Specialty Stores, Expos |
| Companies Covered | Honda Motor Co., Ltd., Harley-Davidson Inc., Polaris Inc., Textron Inc., Suzuki Motor Corporation, Yamaha Motor Co., Ltd., Kawasaki Heavy Industries, Ducati Motor Holding, BRP Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Sports Market Emerging Trajectories
Battery-swappable architecture and solid-state cell chemistry are redrawing competitive boundaries in power sports propulsion. These shifts compress development cycles while fragmenting supplier relationships across automotive and marine heritage.
Solid-state battery prototypes are decentralizing range anxiety solutions for electric ATVs by enabling 15-minute fast-charge protocols at remote trailheads without grid infrastructure upgrades. Backcountry tour operators in Utah and Idaho are piloting mobile swap stations that eliminate downtime between ride sessions. This topology is compressing the total cost of ownership gap against gasoline equivalents for commercial fleet operators.
REACH chemical restrictions and EU F-Gas Regulation are forcing hull manufacturers to reformulate fiberglass resins and eliminate HFC-based climate control refrigerants in enclosed cabin side-by-sides. European importers now require full material disclosure documentation that adds 6-8 weeks to customs clearance. Marine personal watercraft with integrated HVAC systems face the steepest compliance cost escalation.
Recreational buyers are consolidating purchases through manufacturer-direct digital channels that bypass traditional dealer markups on accessories and extended warranties. Younger entrants in the Arizona and Nevada markets complete 70% of research online before contacting a single physical location. Dealer networks are responding with experiential showrooms that monetize test ride events rather than inventory turnover.
Power Sports Market Segmentation
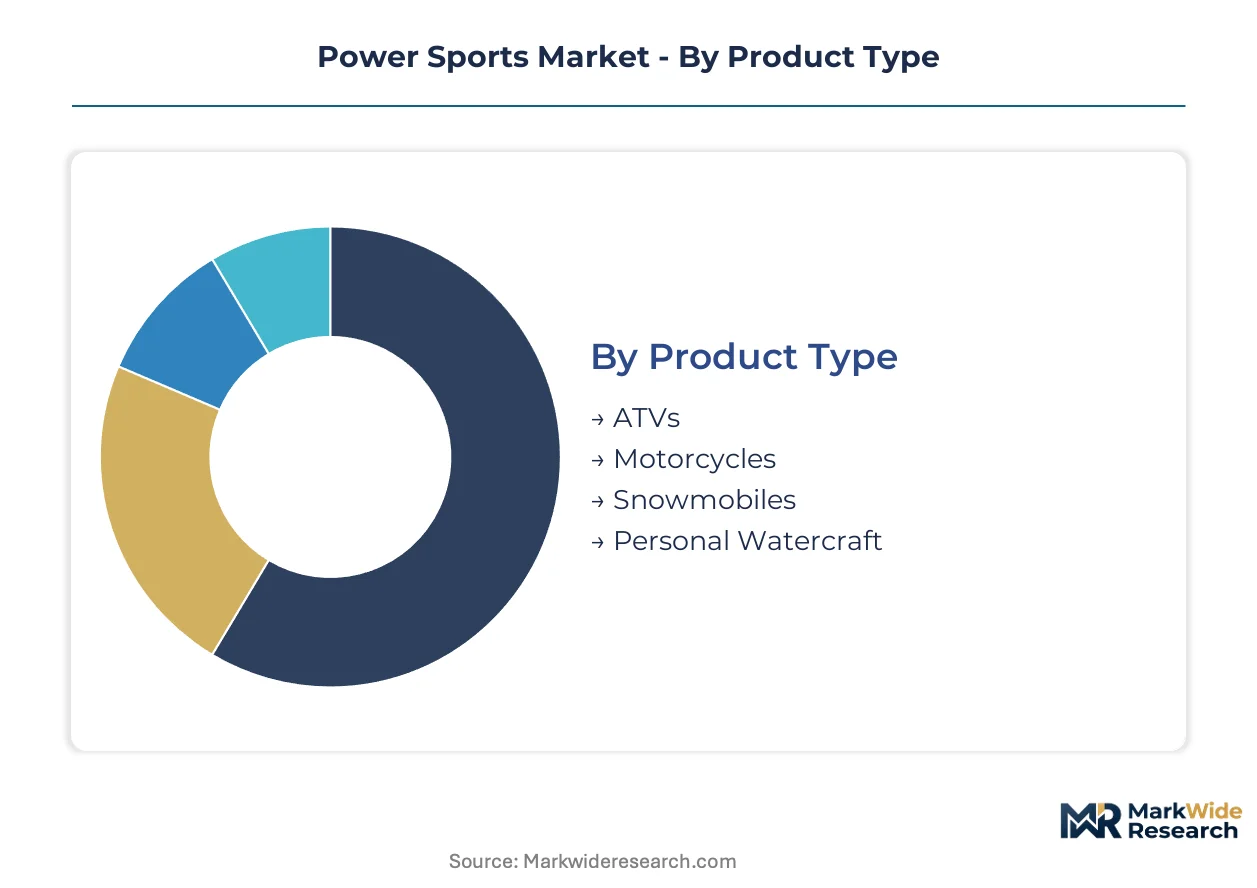
Power sports manufacturers calibrate portfolio depth against distinct replacement cycles across vehicle categories. Upgrade timing varies from annual accessory turnover among professional racers to 7-10 year chassis replacement among recreational snowmobile owners.
Product Type:
Replacement intensity differs sharply across vehicle architectures, with high-hour commercial units demanding faster refresh than leisure-oriented platforms.
- Motorcycles:Engine displacement spans 50cc to over 1000cc with chassis systems optimized for pavement or dirt traction. Established aftermarket parts economics in Arizona and Nevada sustain annual upgrade spending among licensed private owners. Licensing accessibility across state DMVs preserves volume concentration in this segment.
- ATVs:Four-wheel terrain vehicles feature suspension travel exceeding 12 inches and displacement engines governed by EPA 40 CFR Part 1051 emission limits. Fleet purchasers in Colorado and Utah are scaling side-by-side configurations to capture inbound adventure tourism demand.
- Snowmobiles:Cold-climate platforms with thermal efficiency improvements sustaining market share against seasonal demand fluctuation. Ski-Doo configurations dominate snowbelt states with 60-70% revenue concentration during October-March.
- Personal Watercraft:Hull-integrated marine propulsion systems with displacement engines or emerging battery-electric alternatives. Yamaha Motor development programs are advancing integrated battery thermal management for zero-emission variants in Florida coastal markets.
Volume placements concentrate in Motorcycles; the faster expansion belongs to Personal Watercraft.
End User:
Customer acquisition cost and lifetime value diverge substantially across participation intensity levels, from casual trail access to sponsored competition circuits.
- Recreational Users:Private leisure consumers requiring specialized performance outside standard transportation infrastructure. This segment commands the largest addressable population across California, Colorado, and Florida trail networks.
- Professional Racers:Competitive circuit participants with sponsorship-linked equipment turnover commanding disproportionate accessory spending. Teams replace chassis and powertrain components on compressed cycles aligned with race calendars.
- Enthusiasts:High-involvement owners performing aftermarket modifications and cross-category vehicle ownership. Their technical engagement sustains specialty retailer foot traffic in Arizona and Nevada markets.
- Tour Operators:Commercial fleet managers piloting subscription-based pricing models bundling vehicles, maintenance, and trail permits. Utah and Idaho backcountry operators are testing mobile battery swap stations for electric ATV fleets.
Revenue scale tilts toward Recreational Users; margin expansion is steepest among Tour Operators.
Fuel Type:
Powertrain architecture selection increasingly determines trail access permissions under tightening emission mandates from California Air Resources Board and EPA.
- Gasoline:Displacement engines from 50cc to over 1000cc with direct injection and catalytic after-treatment systems adding $800-$1,200 per unit for EPA compliance. This architecture retains installed base dominance where charging infrastructure remains sparse.
- Electric:Battery-electric platforms with lithium-ion energy density advances above 300 Wh/kg enabling range parity with 400cc gasoline equivalents. CARB zero-emission mandates for 2035 onward are accelerating manufacturer development commitments.
- Diesel:Compression-ignition variants limited to utility-focused ATV configurations in agricultural and commercial applications. Cold-start performance constraints restrict adoption in snowmobile and personal watercraft categories.
- Hybrid:Dual-powertrain architectures combining thermal engines with electric assist for torque supplementation. Development programs remain nascent relative to full-electric platforms across Polaris and BRP product pipelines.
Installed base remains gasoline-heavy; product development investment is concentrating in Electric.
Distribution Channel:
Channel economics are restructuring as digital research behavior reshapes physical touchpoint requirements across younger demographic cohorts.
- Dealerships:Traditional franchised networks with captive service bays and manufacturer-aligned inventory financing. Dealer density anchors Polaris Inc. market position across North American rural markets.
- Online Retail:Manufacturer-direct digital channels capturing consolidated purchases that bypass traditional markups on accessories and extended warranties. Arizona and Nevada entrants complete 70% of research online before physical contact.
- Specialty Stores:Independent retailers focused on aftermarket parts, customization services, and technical consultation. Enthusiast engagement sustains this channel against manufacturer-direct encroachment.
- Expos:Seasonal event-based selling at competitive racing circuits and outdoor recreation festivals. Demo ride conversions at these venues outperform static showroom close rates for entry-level displacement categories.
Transaction volume still flows through Dealerships; channel investment is shifting toward Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration in the United States and Japan contrasts with consumption growth in European and select Asian markets. Regulatory divergence is fragmenting product specifications across jurisdictions.
United States
Recreational tourism fleet operators in Colorado and Utah are scaling side-by-side purchases to capture inbound adventure demand. EPA 40 CFR Part 1051 emission certification tightens annually, compelling catalytic after-treatment investments. Minneapolis-St. Paul anchors Polaris Inc. manufacturing scale through captive engine production and dense rural dealer networks.
Germany
EU Green Deal procurement rebalancing favors lower-emission platform imports across Bavarian and Baden-Württemberg distribution channels. REACH chemical restrictions and F-Gas Regulation constrain hull resin formulations and cabin refrigerant choices. Stuttgart industrial clusters host specialty aftermarket retailers serving cross-border Austrian and Swiss enthusiast demand.
Japan
Marine propulsion electrification programs target Florida and Southeast Asian coastal markets from Hamamatsu engineering centers. METI technology roadmaps coordinate solid-state battery development timelines with automotive sector spillover. Tokyo-Yokohama corporate headquarters concentrate R&D investment decisions for integrated personal watercraft thermal management.
Canada
Ski-Doo snowmobile thermal efficiency improvements sustain Quebec and Ontario market positions against seasonal revenue fluctuation. Provincial trail permit systems in British Columbia and Alberta favor zero-emission vehicle access policies. Valcourt manufacturing heritage anchors BRP Inc. cold-climate product development against Scandinavian competitor encroachment.
Australia
Queensland and New South Wales coastal operators pilot battery-electric personal watercraft for reef tourism environmental compliance. TGA-equivalent state-level vehicle safety frameworks govern ATV registration and trail access permissions. Perth engineering consultancies specialize in remote-area charging infrastructure for mining-site utility vehicle electrification.
Power Sports Market Vendor Landscape
The competitive structure tilts toward diversified vehicle manufacturers with captive powertrain production. Consolidation pressures concentrate among gasoline-engine heritage houses facing electric platform competency gaps. Three archetypes dominate: integrated marine-land specialists, seasonal-vehicle thermal efficiency leaders, and motorcycle-scale aftermarket parts economists. Capacity expansion and strategic charging infrastructure partnerships constitute the dominant competitive moves.
Within the diversified powertrain tier, Honda Motor Co., Ltd., Yamaha Motor Co., Ltd., and Polaris Inc. exemplify contrasting geographic and technological positioning. Honda Motor Co., Ltd. occupies a position spanning motorcycle licensing accessibility and marine propulsion heritage. Yamaha Motor Co., Ltd. anchors integrated battery-electric personal watercraft development commitment. Polaris Inc. sits within the North American side-by-side manufacturing scale archetype through rural dealer network density.
| Leading Market Players |
|---|
| Honda Motor Co., Ltd. |
| Harley-Davidson Inc. |
| Polaris Inc. |
| Textron Inc. |
| Suzuki Motor Corporation |
| Yamaha Motor Co., Ltd. |
| Kawasaki Heavy Industries |
| Ducati Motor Holding |
| BRP Inc. |
| Others |
Supply Flow & Price Mechanics
California Air Resources Board zero-emission mandates for 2035 onward are forcing manufacturers to absorb battery-electric platform development costs while maintaining gasoline unit competitiveness. This dual-track investment compresses margins and fragments pricing power across emission-restrictive and recreation-promoting state jurisdictions.
Pricing Analysis
Range-per-charge benchmarks anchor value-based pricing for electric ATVs and personal watercraft as commercial fleet operators calculate total cost of ownership against gasoline equivalents. Three-tier pricing structure across premium, standard, and economy levels separates CARB-certified zero-emission platforms from EPA-compliant gasoline units and entry-level displacement categories. Pricing pressure stems from catalytic after-treatment cost inflation adding $800-$1,200 per gasoline unit. Entry-level recreational buyers exhibit highest price sensitivity, while tour operators prioritize uptime value over acquisition cost.
Supply Chain Analysis
Domestic-content requirements under the US Inflation Reduction Act are reshaping battery cell sourcing toward North American assembly plants. Power electronics manufacturing concentrates in Japan, South Korea, and Taiwan, while lithium raw material processing feeds from Australia and Chile. The supply chain draws from rare earth magnet dependencies for electric motor production. Single-source vulnerability in semiconductor foundry capacity for inverter controllers threatens production continuity. Distribution runs through franchised dealer networks with captive service financing in rural markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
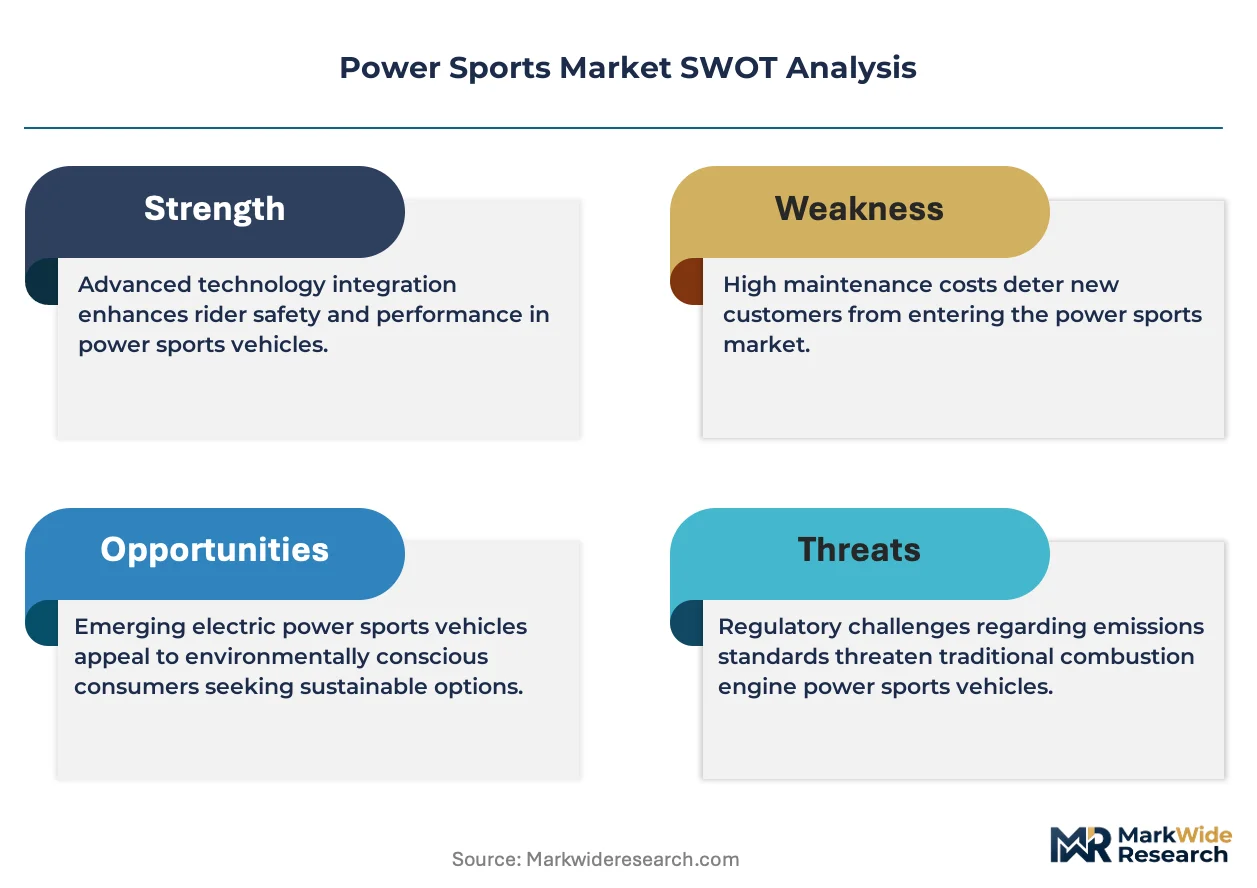
EPA 40 CFR Part 1051 emission certification functions as a cost-of-compliance moat, raising production barriers that favor incumbent manufacturers with established catalytic after-treatment engineering and regulatory affairs infrastructure.
For Market Incumbents: Acquire power electronics thermal management talent from automotive-adjacent labor markets to close electric propulsion competency gaps. Consolidate dealer network density in Colorado and Utah trail corridors to defend against manufacturer-direct digital encroachment. Battery-electric platform development commitments represent the critical defensive lever against CARB zero-emission mandates. For New Entrants and Emerging Players: Enter via integrated battery-electric personal watercraft development, where marine propulsion electrification remains underdeveloped relative to land vehicles. Target Florida coastal markets with hull-integrated thermal management innovation as the most penetrable geography. Pursue subscription-based fleet management pilots with commercial tour operators as the primary go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors diversified manufacturers with captive powertrain production and established EPA certification pathways. Long-term viability hinges on electric platform competency acquisition within a five-to-ten year technology transition horizon. Watch battery energy density advances above 300 Wh/kg as the inflection signal for electric ATV range parity with gasoline equivalents.| Strategic Initiative | Industry Significance |
|---|---|
| Charging Infrastructure Partnership | Trailhead charging networks in California and Colorado secure electric platform access advantages under CARB mandates. |
| Battery Supply Agreement | Lithium-ion cell procurement from North American assembly plants satisfies domestic-content requirements under IRA provisions. |
| Power Electronics Talent Acquisition | Motor controller engineering capabilities from automotive labor markets close competency gaps in electric propulsion. |
| Dealer Network Consolidation | Franchised rural density in Utah and Idaho defends market position against manufacturer-direct digital channels. |
| Solid-State Battery Development | Fifteen-minute fast-charge protocols at remote trailheads compress total cost of ownership against gasoline equivalents. |
Methodological Framework
Document review covered EPA certification filings, EU F-Gas Regulation guidance, and state-level trail access policy databases, complemented by interviews with power sports product development executives, commercial fleet procurement managers, dealer network operations heads, and aftermarket parts distributors. Secondary validation drew from SEC 10-K disclosures, vehicle registration data, and customs trade records. Bottom-up unit economics triangulated against top-down market sizing across gasoline, electric, and hybrid propulsion architectures.
Segment-level projections incorporate product type, fuel category, end-user intensity, and distribution channel dynamics across the modeling period. CAGRs derive from replacement cycle analysis, regulatory phase-in schedules, and energy density improvement trajectories. Battery pack cost curves and charging infrastructure penetration rates inform electric platform adoption assumptions. Snowmobile seasonal demand concentration and personal watercraft coastal market seasonality shape quarterly allocation models.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated CARB mandate enforcement or lithium supply disruption scenarios. Projections reflect assumptions regarding EPA certification timeline stability and battery chemistry transition pathways. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Kitesurf Kites Market
Outdoor and Adventure Activities
Paragliding Equipment Market
Outdoor and Adventure Activities
Recreational Sports Activities Market
Outdoor and Adventure Activities
North America Climbing Gears Market
Outdoor and Adventure Activities
Mountain Bike Market
Outdoor and Adventure Activities
Hammocks Market
Outdoor and Adventure Activities
Hiking Cleats Market
Outdoor and Adventure Activities
Adventure Gear Market
Outdoor and Adventure Activities
Parasailing Equipment Market
Outdoor and Adventure Activities
Trekking Poles Market
Outdoor and Adventure Activities
Hydration Packs Market
Outdoor and Adventure Activities
Global Inflatable Outdoor Leisure Product Market
Outdoor and Adventure Activities
North America Personal Watercraft Market
Outdoor and Adventure Activities
Hunting Rangefinder Market
Outdoor and Adventure Activities
Spain Artificial Turf Market
Outdoor and Adventure Activities
Skiing Equipment Market