
 Europe Sports Management Software Market | 2026-2036
Europe Sports Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sports Management Software Market Analytics
Direct-to-club software licensing is reconfiguring how European sports organizations procure management platforms. SAP SE leverages its enterprise resource planning heritage to anchor multi-module contracts with Bundesliga football clubs. SportEasy SAS competes through mobile-first design that dominates amateur league administration across France. IBM extends its Watson analytics stack into athlete performance optimization for elite rugby and cricket federations.
Europe sports management software encompasses cloud-native and on-premises platforms that integrate scheduling algorithms, ticketing APIs, biometric analytics engines, and membership databases for athletic organizations. These systems process real-time match data, automate fixture generation, and enforce role-based access controls across coaching staff. Cloud-based deployment leads structural adoption as Football Association clubs in England migrate legacy server infrastructure to scalable architectures. Subscription-based pricing captures the dominant revenue pool by converting perennial license buyers into recurring revenue relationships. Ticketing solutions represent the fastest-growing product segment as post-pandemic venues prioritize contactless entry and dynamic pricing capabilities.
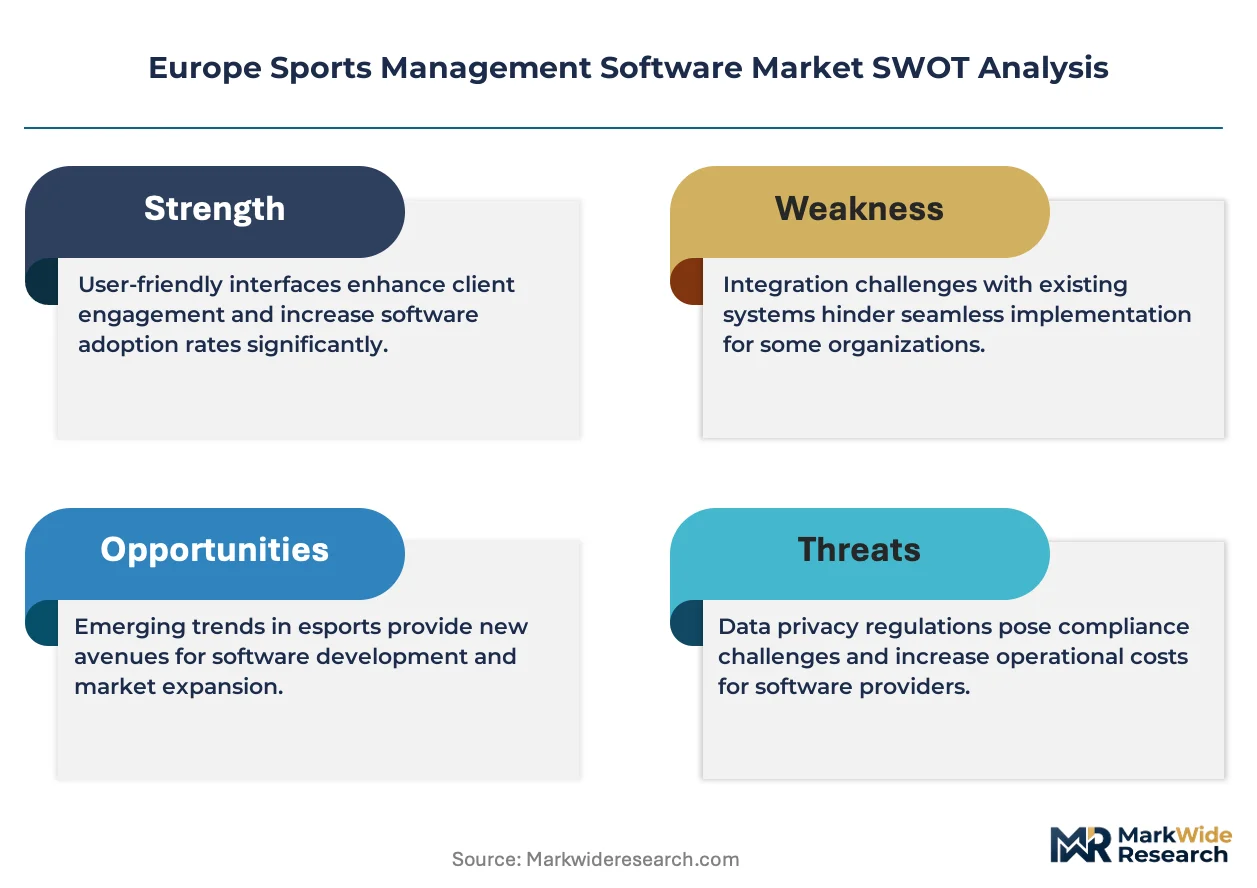
The EU AI Act and GDPR impose strict processing constraints on athlete biometric analytics, compelling vendors to deploy edge-computing architectures that minimize central data storage. EMA frameworks for health-monitoring wearables intersect with sports technology standards, creating dual compliance obligations for integrated platforms. Stakeholders must monitor how the EU Green Deal's digital infrastructure requirements alter data center location strategies and carbon disclosure obligations for cloud-hosted services.
Market Dynamics
Cloud migration among English Football Association clubs is compressing deployment cycles and forcing incumbent vendors to re-architect legacy server-based systems for containerized environments. This infrastructure shift is reconfiguring procurement patterns across amateur and professional tiers.
Growth Catalysts
- League digitization mandates:Bundesliga and La Liga broadcasting agreements now require real-time data feeds, compelling clubs to upgrade management platforms.
- GDPR-compliant edge analytics:Biometric processing at venue perimeters satisfies EU data residency requirements while enabling live performance dashboards.
- Contactless venue entry:Post-pandemic stadium operators in France and the United Kingdom prioritize integrated ticketing APIs over standalone access control.
Market Restraints
- AI Act compliance costs:Biometric analytics vendors face dual certification obligations under EMA health-device frameworks and EU AI Act risk classifications.
- Legacy data silos:Decades of on-premises membership databases in German amateur leagues resist API-based integration with modern scheduling modules.
- Specialized talent scarcity:DevOps engineers with both sports-domain knowledge and GDPR audit experience command premium compensation in London and Paris markets.
Strategic Opportunities
- Eastern European amateur leagues:Polish and Romanian football federations lack digitized fixture management, presenting first-mover advantages for mobile-native platforms.
- EU Green Deal data center requirements:Carbon disclosure obligations for cloud-hosted services create differentiation for vendors with Nordic renewable-energy server locations.
- Wearables-to-platform convergence:Integration of GPS tracking vests with training load algorithms opens subscription revenue streams beyond traditional software licensing.
Industry Challenges
- Multi-jurisdiction certification timelines:Vendors targeting both French CNIL biometric guidelines and German KBA data standards face sequential rather than parallel approval processes.
- Intergenerational user adoption:Coaching staff aged 50-plus at traditional cricket and rugby clubs resist touchscreen interfaces optimized for younger administrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sports Management Software Market |
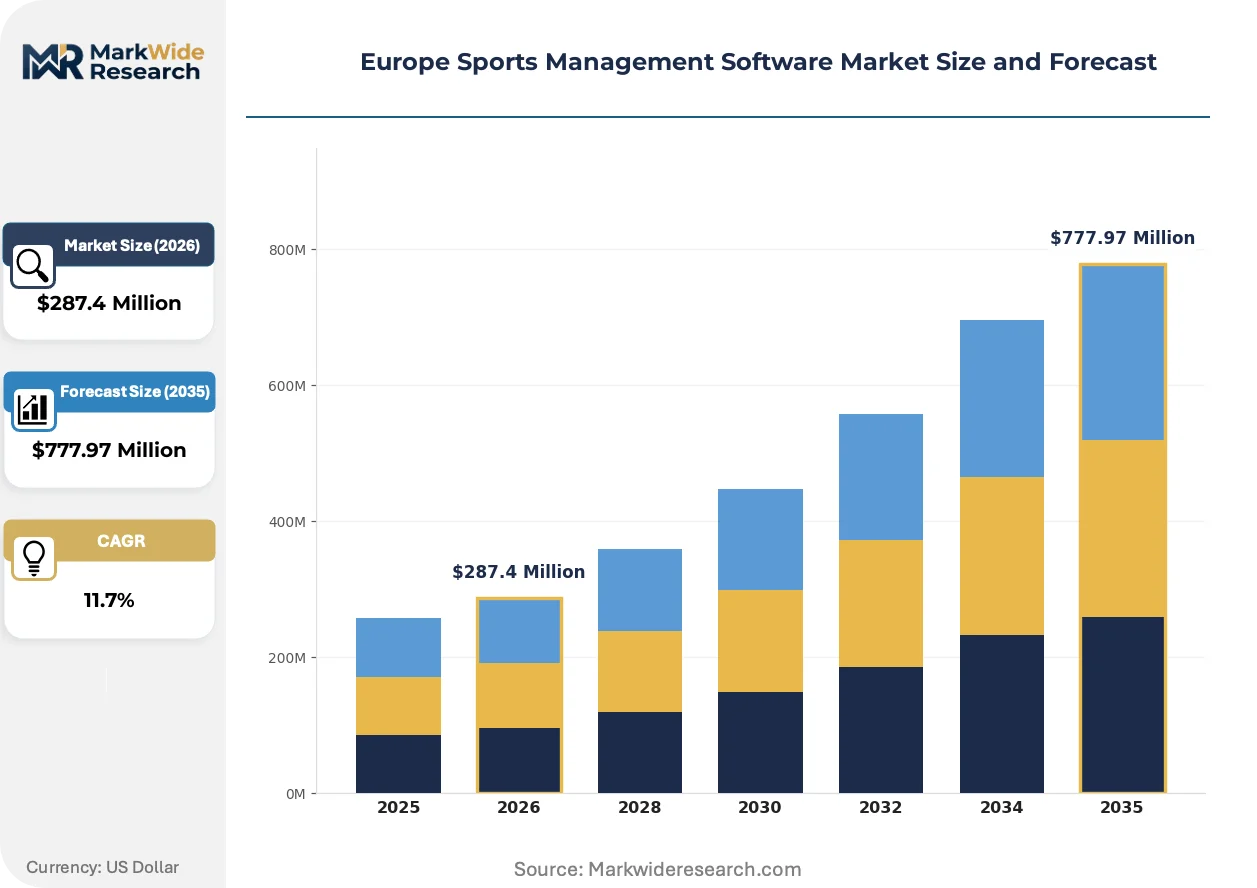
| Market Size in 2026 | $287.4 Million |
| Market Size in 2035 | $777.97 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scheduling Software, Ticketing Solutions, Analytics Tools, Athlete Management Systems End User: Teams, Leagues, Event Organizers, Fitness Centers Deployment: Cloud-Based, On-Premises, Hybrid, Mobile Solutions Pricing Model: Subscription-Based, One-Time License, Freemium, Pay-Per-Use |
| Companies Covered | SAP SE, Sportlyzer LLC, SportEasy SAS, F3M, Jonas Club Software, LeagueApps, Active Network LLC, IBM, SportsEngine Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sports Management Software Market Evolving Landscape
Real-time data architectures are displacing batch-processing workflows across European sports organizations. Three developments are compressing competitive timelines and redefining platform requirements.
Edge-computing deployments for biometric analytics are collapsing the latency between athlete monitoring and coaching intervention. Premier League medical departments now process heart-rate variability and GPS metrics within 200 milliseconds of capture. This compression eliminates the overnight data-sync cycles that previously separated training sessions from performance reviews.
The EU AI Act's risk-tier classification system is mandating algorithmic audit trails for predictive injury models. Vendors must document training data provenance and bias-testing protocols before deploying machine-learning modules in Spanish and Italian top-flight clubs. German football federations are responding by requiring vendor-provided conformity assessments as standard procurement terms.
Software procurement through league-level master service agreements is consolidating vendor relationships that previously fragmented at individual clubs. The English Football League's collective bargaining approach aggregates 72 clubs into standardized platform contracts. This concentration disadvantages point solutions lacking multi-tenant scalability while rewarding modular suites with open APIs.
Europe Sports Management Software Market Segmentation
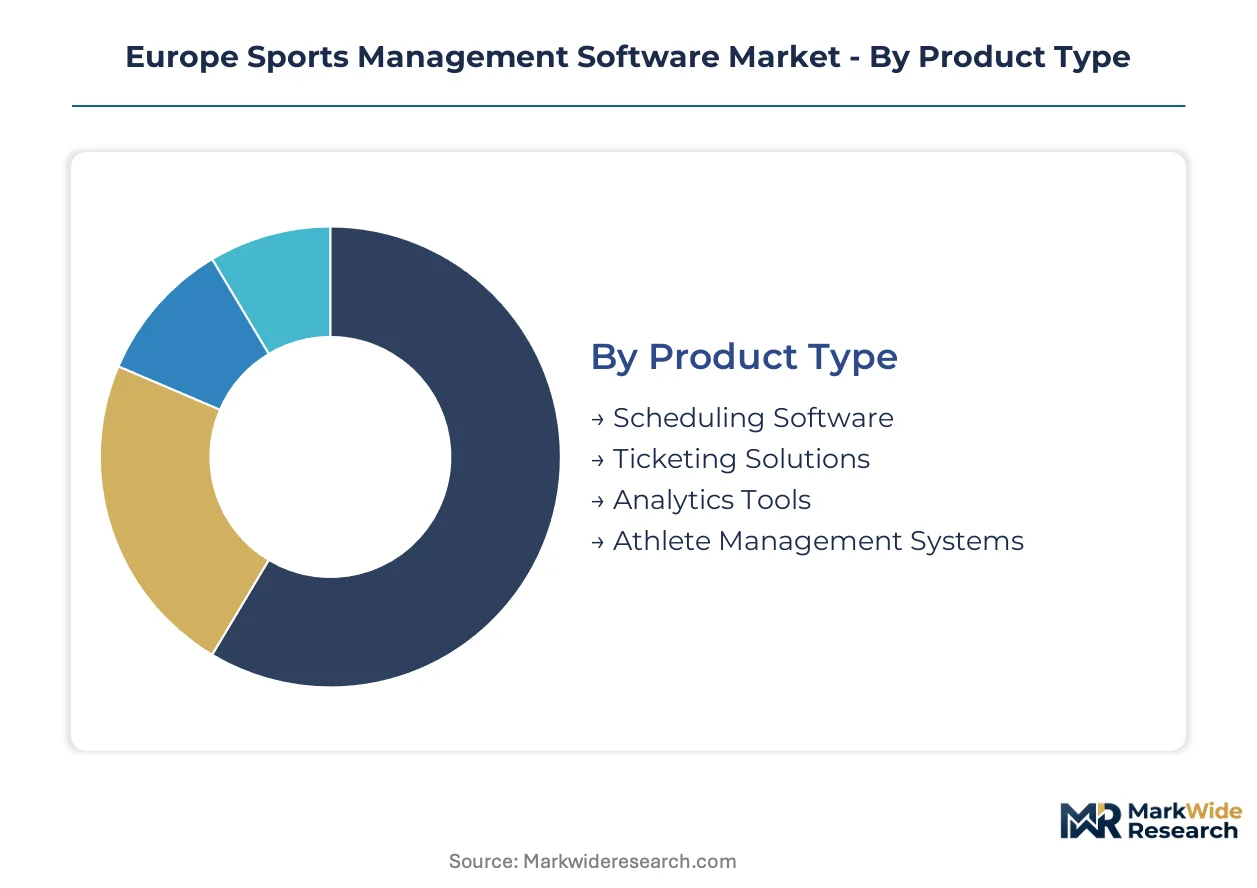
European sports organizations display divergent procurement patterns across amateur clubs, elite leagues, and multi-venue operators. Segmentation reveals how deployment constraints, compliance obligations, and user sophistication reshape vendor product strategies.
Product Type:
Mature scheduling modules anchor legacy procurement budgets while emerging analytics tools capture incremental investment from biometric-conscious federations.
- Scheduling Software:Automated fixture generation algorithms integrate with national league databases across England and Germany. Bundesliga clubs demand real-time conflict resolution that synchronizes with broadcast schedules.
- Ticketing Solutions:Contactless entry APIs with dynamic pricing engines dominate post-pandemic venue upgrades in France and the United Kingdom. These systems process mobile wallet transactions while enforcing GDPR-compliant attendee data retention limits.
- Analytics Tools:Predictive injury models and performance dashboards face EU AI Act algorithmic audit requirements.
- Athlete Management Systems:Centralized biometric repositories serve medical departments at elite Spanish football clubs.
Scheduling Software handles the majority of throughput; Ticketing Solutions is the fastest mover on share.
End User:
Cost tier stratification separates enterprise-grade league contracts from self-service amateur club subscriptions.
- Teams:Individual club procurement concentrates in German amateur football where volunteer administrators prioritize mobile-native interfaces over feature depth.
- Leagues:Collective bargaining power aggregates 72 English Football League clubs into standardized platform contracts with open API requirements.
- Event Organizers:Multi-sport tournament operators demand modular systems that scale from local competitions to international championships.
- Fitness Centers:Boutique gym chains across France adopt membership management modules with class scheduling and payment processing integration.
Leagues command the highest contract values; Fitness Centers are expanding most quickly as boutique operators digitize.
Deployment:
Volume concentration favors cloud architectures as English Football Association clubs abandon on-premises server rooms.
- Cloud-Based:Containerized environments enable elastic scaling during championship finals when concurrent user loads spike tenfold. Nordic renewable-energy data centers attract vendors seeking EU Green Deal carbon disclosure compliance.
- On-Premises:Legacy installations persist in German amateur leagues with decades of membership data resisting API-based migration.
- Hybrid:Edge-computing configurations process biometric data at venue perimeters while centralizing administrative functions remotely.
- Mobile Solutions:Smartphone-first platforms dominate French amateur league administration where volunteer coaches lack desktop access.
Cloud-Based deployment captures the dominant volume; Hybrid configurations are climbing the fastest as edge analytics expand.
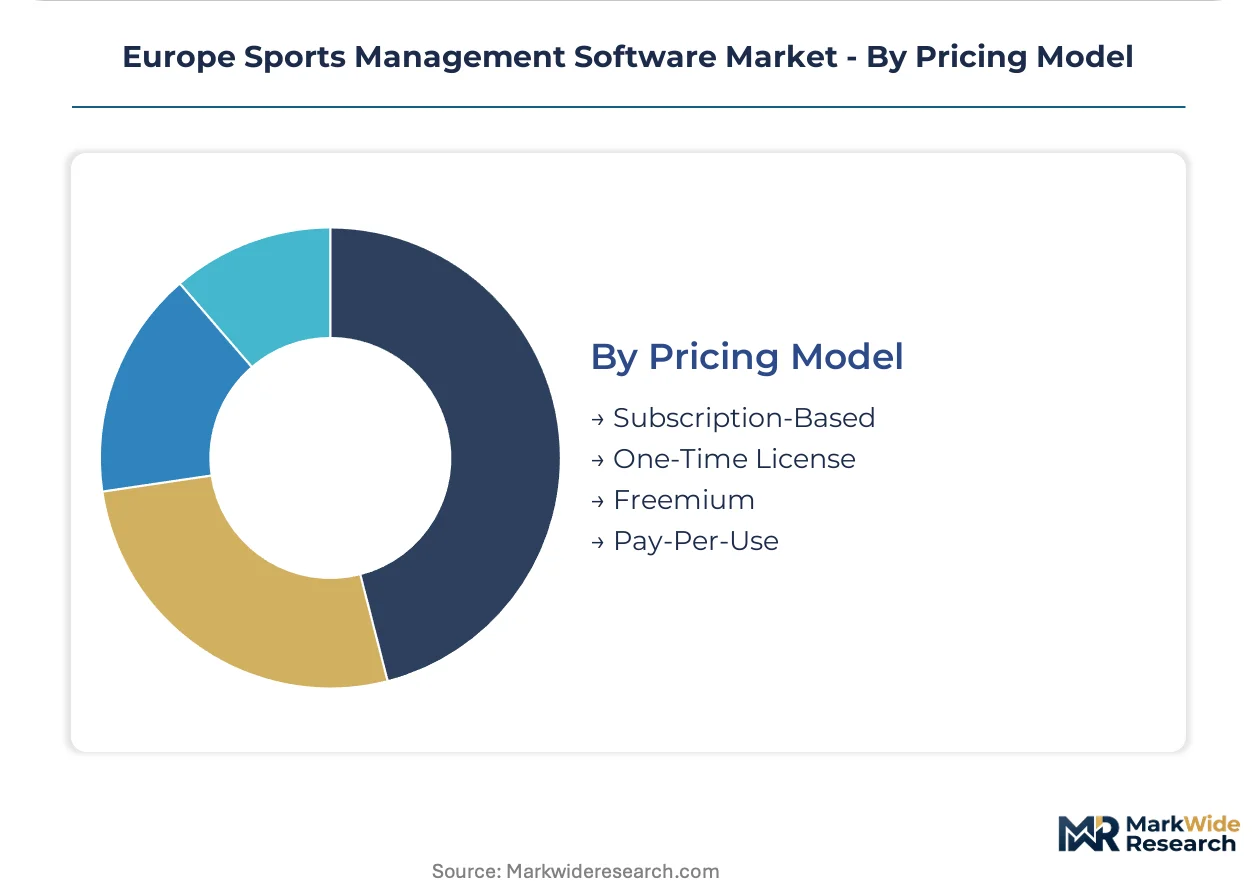
Pricing Model:
Customer type and application criticality determine whether organizations prefer predictable subscriptions or usage-calibrated payments.
- Subscription-Based:Recurring revenue relationships convert perennial license buyers into multi-year contracts with embedded upgrade guarantees.
- One-Time License:Capital expenditure treatment appeals to municipal stadium operators with rigid annual budget cycles.
- Freemium:Tiered entry points capture amateur clubs in Poland and Romania with basic scheduling before upselling analytics modules.
- Pay-Per-Use:Transaction-based pricing aligns venue costs with actual attendance, prioritizing seasonal operators with irregular event calendars.
Subscription-Based pricing dominates professional tiers; Pay-Per-Use is gaining share fastest among seasonal venue operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in English and German league contracts while French amateur clubs drive volume through mobile-first subscriptions. Nordic renewable-energy data centers attract vendors seeking EU Green Deal carbon compliance. Eastern European federations present first-mover gaps in digitized fixture management.
United Kingdom
English Football League collective bargaining aggregates 72 clubs into standardized platform contracts with open API requirements. GDPR and CNIL guidelines from France influence biometric data handling across Premier League medical departments. London-based software vendors anchor enterprise-grade deployments for elite rugby and cricket federations.
Germany
Bundesliga broadcasting agreements mandate real-time data feeds, compelling clubs to upgrade management infrastructure. KBA data standards and EU AI Act compliance create dual certification obligations for biometric analytics vendors. Bavaria's amateur football leagues resist API-based migration from decades-old on-premises membership databases.
France
Volunteer administrators in French amateur leagues prioritize mobile-native interfaces over feature depth, creating volume opportunities for smartphone-first platforms. CNIL biometric guidelines intersect with EU AI Act risk classifications for predictive injury models. Paris-based DevOps talent commands premium compensation for GDPR audit expertise.
Spain
La Liga digitization requirements synchronize club management platforms with broadcast scheduling systems. EU AI Act algorithmic audit trails are mandatory for machine-learning modules deployed in top-flight football medical departments. Barcelona and Madrid clubs lead edge-computing adoption for venue-perimeter biometric processing.
Poland
Polish football federations lack digitized fixture management, presenting first-mover advantages for mobile-native scheduling platforms. EMA frameworks for health-monitoring wearables create compliance templates for integrated sports technology. Warsaw and Krakow amateur clubs represent untapped subscription revenue for freemium platform entry.
Europe Sports Management Software Market Competitive Landscape
Enterprise software heritage and mobile-native specialists split the market between modular suite contracts and volume amateur subscriptions. The vendor base concentrates around three strategic archetypes: ERP-anchored conglomerates, mobile-first SaaS platforms, and analytics-integrated technology stacks. Consolidation pressures favor multi-tenant scalability over point solutions. M&A activity targets API-based integration capabilities while geographic expansion focuses on Eastern European amateur league digitization.
Within the ERP-anchored tier, SAP SE exemplifies enterprise resource planning heritage applied to multi-module Bundesliga contracts. SportEasy SAS occupies the mobile-first position dominating French amateur league administration. IBM represents the analytics-integrated archetype extending Watson capabilities into elite rugby and cricket federations.
| Leading Market Players |
|---|
| SAP SE |
| Sportlyzer LLC |
| SportEasy SAS |
| F3M |
| Jonas Club Software |
| LeagueApps |
| Active Network LLC |
| IBM |
| SportsEngine Inc. |
| Others |
Value Network & Pricing Analysis
London's concentration of DevOps engineering talent with GDPR audit expertise feeds directly into premium pricing for compliance-heavy biometric analytics modules. Vendors competing for Bundesliga and Premier League contracts absorb elevated personnel costs that downstream buyers negotiate against standardized SaaS tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order Bundesliga deployments from self-service French amateur subscriptions. Subscription-based SaaS tiers dominate professional segments while freemium entry points capture Polish and Romanian volume. Price differentiation hinges on GDPR certification depth and real-time data processing latency guarantees. Pricing pressure intensifies as league-level master service agreements consolidate procurement power across 72 English Football League clubs. Municipal stadium operators display highest price sensitivity due to rigid annual budget cycles.
Supply Chain Analysis
Tariff exposure between EU member states and third-country cloud infrastructure providers dominates vendor location strategies. Software development concentrates in Germany, the United Kingdom, and France with Nordic renewable-energy data centers serving EU Green Deal compliance requirements. Raw material dependencies center on semiconductor components for edge-computing hardware, biometric sensor arrays, and containerized orchestration licenses. Single-source vulnerability persists for specialized GDPR audit talent pools in London and Paris. Distribution runs through direct-to-club licensing channels and league-level collective bargaining frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment. EU AI Act compliance obligations and GDPR certification requirements create switching costs that protect incumbent positions.
For Market Incumbents: Entrench through deeper API-based integration with legacy membership databases resisting migration in German amateur leagues. Acquire mobile-native platforms serving French volunteer administrators to preempt SaaS displacement. Threat: SportEasy SAS and similar mobile-first entrants capture volume tiers through superior UX. Lever: vertical integration into edge-computing hardware for venue-perimeter biometric processing. For New Entrants and Emerging Players: Polish and Romanian football federations lacking digitized fixture management represent the most penetrable entry point for mobile-native scheduling platforms. Eastern European amateur leagues offer first-mover advantages before incumbent ERP vendors re-architect for containerized deployment. Go-to-market: freemium tiered entry with basic scheduling before upselling analytics modules compliant with EMA health-monitoring frameworks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with modular API architectures and multi-tenant scalability. Long-term viability rests on platforms that absorb sequential multi-jurisdiction certification timelines across French CNIL and German KBA standards. Acquisition target archetype: mobile-first SaaS platforms with established Eastern European user bases. Signal to watch: league-level master service agreement consolidation rates as indicator of platform concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-based connectivity with legacy Bundesliga membership databases reduces switching friction. |
| Geographic Expansion | Eastern European amateur league digitization captures volume before ERP incumbents adapt. |
| Acquisition of Specialist Firm | Mobile-native French platforms add GDPR-compliant biometric processing capabilities. |
| Product Launch | Edge-computing modules satisfy EU AI Act risk-tier requirements for La Liga medical departments. |
| Strategic Partnership | Nordic renewable-energy data center alliances secure EU Green Deal carbon disclosure compliance. |
Research Methodology
Initial hypotheses were tested against primary input from sports technology CTOs, league procurement officers, club operations directors, and GDPR compliance consultants and refined through secondary validation. Primary fieldwork encompassed Bundesliga and Premier League platform deployments, French amateur league mobile adoption patterns, and Spanish biometric analytics implementations. Secondary sources included EMA framework documentation, EU AI Act regulatory filings, league broadcasting agreement terms, and vendor SEC disclosures. Bottom-up club-level deployment estimates were triangulated against top-down league contract aggregations.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions modeled encompass deployment model, organization tier, integration complexity, and regional regulatory cluster. CAGRs were derived from club-level subscription trajectories, league contract renewal rates, and biometric analytics module attach rates. Industry-specific inputs included English Football League collective bargaining outcomes and German KBA certification timeline data.
Practitioners should monitor EU AI Act enforcement patterns and league digitization mandate acceleration for early signals of forecast revision. Forecasts reflect assumptions regarding GDPR compliance cost trajectories and cloud migration rates among German amateur federations. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
UK Spectator Sports Market
Sports & Fitness Technology
Virtual Reality Fitness Market
Sports & Fitness Technology
Football Merchandise Market
Sports & Fitness Technology
Global Sports Management Software Market
Sports & Fitness Technology
Asia Pacific Sports Promoter Market
Sports & Fitness Technology
Stadium and Arena Management Solution Market
Sports & Fitness Technology
Crossfit Apparel Market
Sports & Fitness Technology
Asia-Pacific Fantasy Sports Market
Sports & Fitness Technology
UK Sports Team and Clubs Market
Sports & Fitness Technology
Europe Sports Team and Clubs Market
Sports & Fitness Technology
Smart Court (Sports) Market
Sports & Fitness Technology
Sports Sponsorship Market
Sports & Fitness Technology
North America Sports Management Software Market
Sports & Fitness Technology
Germany Sports Teams and Clubs Market
Sports & Fitness Technology
Sportswear Rental and Rotation Market
Sports & Fitness Technology
Smart Trainers Market