
 Winter Sporting Goods Market | 2026-2036
Winter Sporting Goods Market Size, Share, and Industry Trends Forecast 2026-2036
Winter Sporting Goods Market Intelligence
The legacy network of skilled ski technicians and custom boot fitters is unwinding the traditional, high-touch retail service model. This shift benefits large operators like Amer Sports Corporation, which leverages its multi-brand portfolio including Salomon and Atomic. Rossignol Group sustains its premium position by anchoring its brand in alpine racing heritage. Burton Snowboards dominates the snowboarding niche through strong brand loyalty and direct-to-consumer channel control.
Winter sporting goods are equipment purpose-built for activities on snow and ice, including skiing, snowboarding, and ice hockey. Performance characteristics are engineered through advanced materials like carbon fiber and fiberglass, which provide specific flex patterns and critical weight reductions. Skis and snowboards represent the core product types, with fiberglass and carbon fiber being essential material inputs for high-end models. The Recreational Users segment constitutes the primary end-user market, predominantly reached through specialty store and online retailer distribution channels.
Product safety and European market access are governed by the CE marking for personal protective equipment like helmets. Manufacturing processes often adhere to ISO 9001 quality management standards for consistency and reliability. In parallel, Health Canada enforces specific safety regulations for ice hockey equipment. The industry's move toward circular economy principles in materials sourcing will define the next phase of competitive differentiation.
Market Dynamics
The convergence of material science advancements with a strong consumer push for sustainability is the central force shaping the winter sporting goods market. This dynamic compels manufacturers to innovate beyond performance metrics, integrating circular economy principles into product design and sourcing.
Growth Catalysts
- Sustainable Material Innovation:The adoption of bio-based resins and recycled fabrics, driven by consumer demand and anticipated EU environmental policies, is expanding product offerings and attracting environmentally conscious buyers.
- Government Health and Sports Initiatives:National campaigns in countries like Canada and China promoting active lifestyles and winter sports participation are broadening the base of recreational users and stimulating first-time equipment purchases.
- Expansion of All-Season Resorts:Ski resorts in the United States and France are investing in year-round attractions, which maintains brand visibility and provides a stable channel for ancillary winter gear sales during shoulder seasons.
Market Restraints
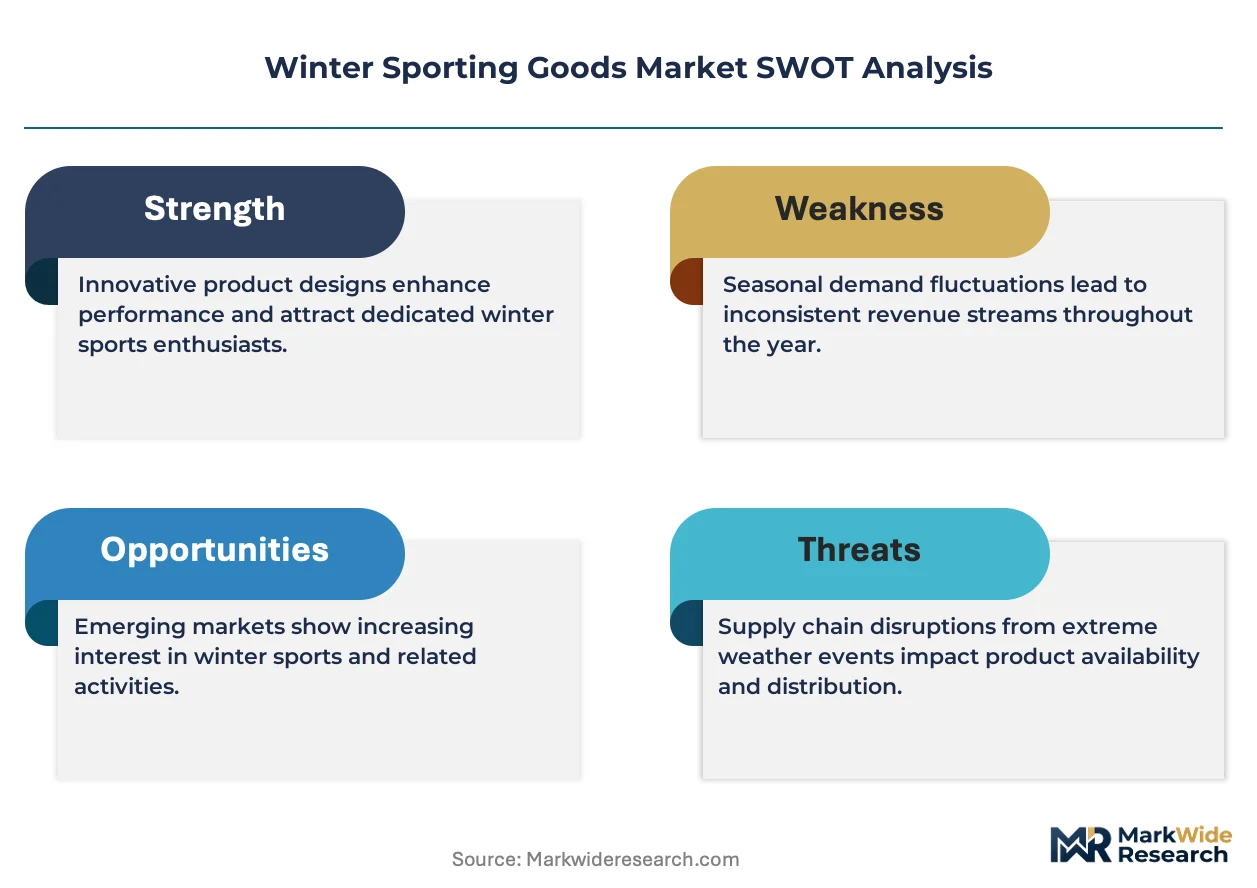
- Climate Dependency and Variability:Unpredictable snowfall and shorter winter seasons in key European alpine regions directly impact participation rates and create demand uncertainty for manufacturers and retailers.
- Raw Material Price Volatility:The cost of performance materials like carbon fiber and specialized polymers is influenced by demand from larger industries, creating pricing pressure on high-end equipment.
- High Barrier to Entry for New Users:The significant initial investment required for quality skis, snowboards, and safety equipment can deter casual or first-time participants, limiting market expansion.
Strategic Opportunities
- Rental and Subscription Service Models:Offering equipment-as-a-service lowers the upfront cost for consumers, providing a channel to engage new users and generate recurring revenue streams from trial-oriented customers.
- Smart and Connected Equipment:Integrating sensors into skis, bindings, and helmets for performance analytics and safety alerts opens a new market for data-driven products targeting performance-focused athletes.
- Emerging Market Penetration:A growing middle class and government support for winter sports in China present a significant opportunity for market entry and brand building in a previously untapped region.
Industry Challenges
- Skilled Technician Scarcity:The diminishing network of experienced boot fitters and ski service technicians creates a bottleneck in the high-touch service model that premium equipment and customization depend on.
- Managing Product Lifecycles:Developing effective take-back and recycling programs for composite products like skis and snowboards presents a significant logistical and technical challenge for achieving circularity goals.
- Channel Conflict:Balancing direct-to-consumer sales strategies with the need to support and maintain relationships with third-party specialty retail partners creates inherent channel friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Winter Sporting Goods Market |
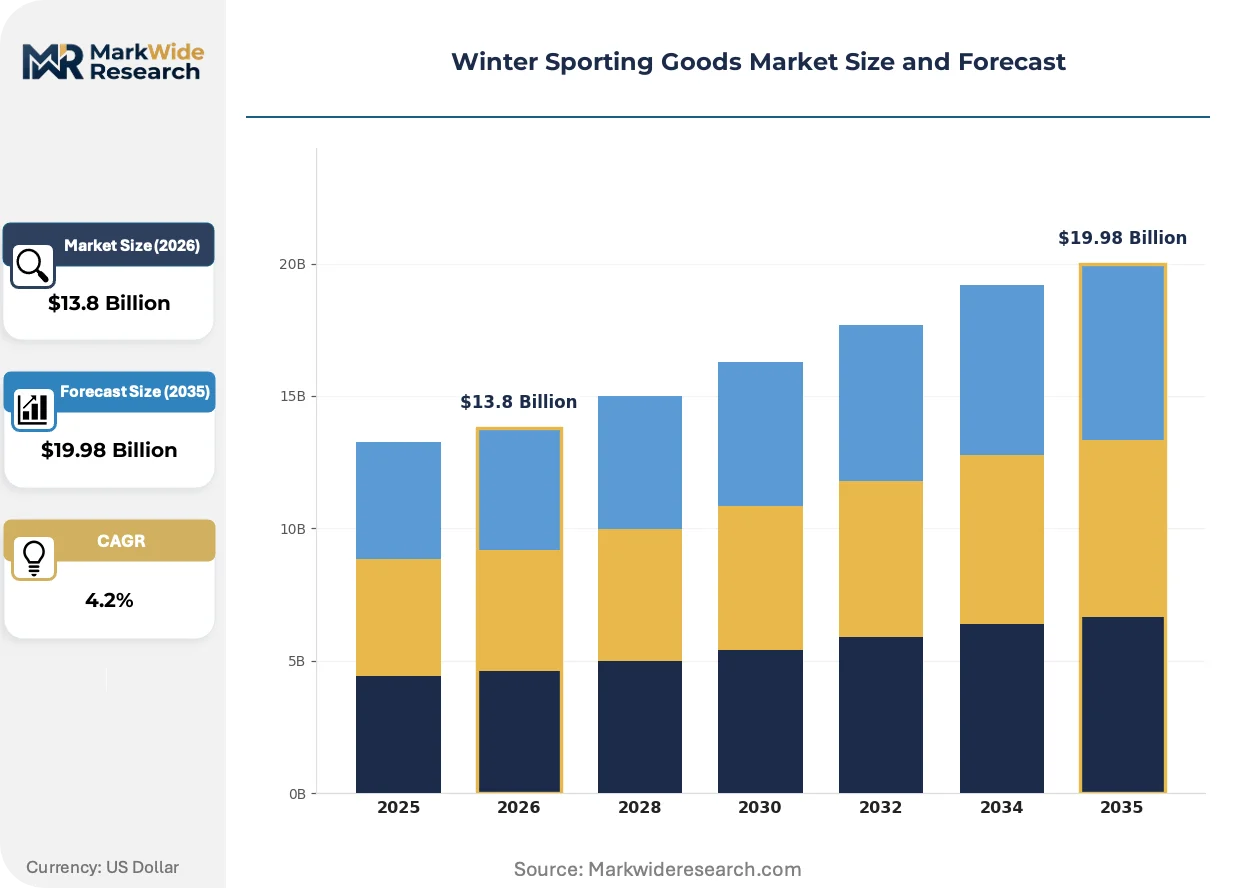
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $19.98 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skis, Snowboards, Ice Hockey Gear, Snowshoes Material: Fiberglass, Carbon Fiber, Aluminum, Synthetic Fabrics End User: Recreational Users, Professional Athletes, Schools, Rental Services Distribution Channel: Online Retailers, Specialty Stores, Sporting Goods Chains, Department Stores |
| Companies Covered | Amer Sports Corporation, Rossignol Group, Burton Snowboards, Bauer Hockey, K2 Sports, Tecnica Group, Fischer Sports, Decathlon SA, Head NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Winter Sporting Goods Market Strategic Shifts & Innovations
The market's evolution is defined by the integration of digital technologies into physical equipment and a systemic shift toward sustainable manufacturing. These forces are altering product design, regulatory compliance, and the consumer's relationship with their gear.
Advanced composite materials incorporating embedded sensors are becoming a hallmark of high-performance equipment. Performance-oriented recreational users and competitive athletes are adopting this technology to gain real-time feedback on technique and conditions. This trend is miniaturizing bulky, external performance trackers directly into the ski or snowboard, creating a seamless and integrated user experience.
European Union regulations, particularly the Ecodesign for Sustainable Products Regulation, are compelling a shift in manufacturing philosophy. This policy framework mandates greater product durability, reparability, and material recyclability. The ski and snowboard categories are most affected, prompting manufacturers to invest in R&D for modular designs and end-of-life processing for composite materials.
A behavioral shift from long-term ownership to short-term access is altering distribution models. The traditional specialty store purchase is being challenged by manufacturer-operated subscription services and sophisticated, digitally-enabled rental platforms at resorts. This trend is most pronounced in destination ski areas in the Rocky Mountains and the Alps, where tourists prioritize convenience and access to the latest equipment.
Winter Sporting Goods Market Segmentation
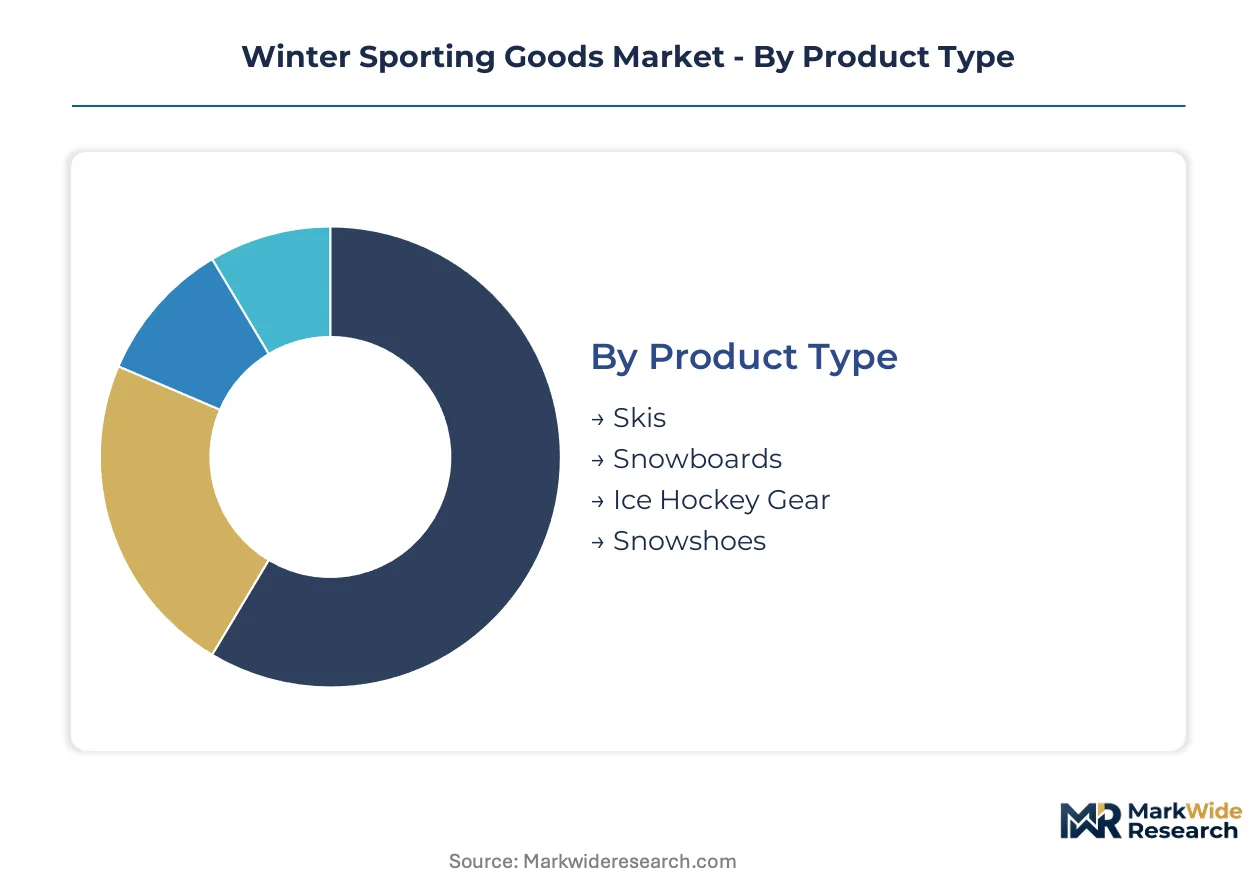
The winter sporting goods market segments reflect distinct product applications, material compositions, user demographics, and purchasing behaviors. Understanding these divisions helps manufacturers tailor product development and optimize distribution strategies for specific consumer needs.
Product Type:
The geographic spread of demand for winter sporting goods dictates specific product type concentration across various regions.
- Skis:These traditional winter sports instruments consist of a flexible base, bindings, and edges, engineered for gliding over snow. Demand for high-performance skis concentrates heavily in the alpine regions of France, Austria, and the Rocky Mountain states of the United States.
- Snowboards:Single boards designed for descending snow-covered slopes, snowboards incorporate various flex patterns and shapes for different riding styles. Growth in snowboarding equipment is particularly strong among younger recreational users in Japan and North American resorts.
- Ice Hockey Gear:This category encompasses protective equipment, sticks, and skates essential for ice hockey players. Participation in Canada and the northern United States drives consistent demand for ice hockey equipment.
- Snowshoes:Lightweight frames with webbing or decking, snowshoes facilitate walking over deep snow by distributing weight. Recreational snowshoeing sees steady interest in national parks and wilderness areas across the United States.
Skis holds the largest share; momentum sits with Snowboards.
Material:
The cost tier of winter sporting goods is heavily influenced by the advanced materials used in their construction, driving differentiation in performance and price points.
- Carbon Fiber:A high-strength, lightweight material often integrated into premium skis and snowboards for enhanced stiffness and reduced swing weight. Demand for carbon fiber components stems from professional athletes and performance-oriented recreational users seeking marginal gains.
- Fiberglass:This widely used composite material provides a balance of flexibility, durability, and cost-effectiveness in ski and snowboard construction. Fiberglass remains a foundational input for a broad range of mid-tier and entry-level winter sports equipment.
- Aluminum:Primarily utilized in ski bindings, poles, and certain ice hockey equipment components for its strength-to-weight ratio and corrosion resistance. Manufacturers leverage aluminum for critical structural elements requiring robust performance.
- Synthetic Fabrics:Advanced textiles like Gore-Tex and various polyesters form the basis of technical outerwear, gloves, and boot liners. These fabrics provide insulation, waterproofing, and breathability for user comfort.
Demand for Fiberglass remains robust, while Carbon Fiber sees rapid expansion.
End User:
Performance requirements versus casual use define the primary application areas for winter sporting goods across different consumer groups.
- Recreational Users:Individuals participating in winter sports for leisure, exercise, or enjoyment, typically seeking versatile and user-friendly equipment. This segment represents the largest volume driver for skis, snowboards, and related accessories.
- Professional Athletes:Elite competitors who demand the highest performance, durability, and precision from their equipment. Professional athletes often require custom-fitted gear and specialized materials for competitive advantage.
- Schools:Educational institutions offering winter sports programs or physical education classes, requiring durable and accessible equipment for student use. Schools frequently purchase equipment in bulk for their ski clubs or ice hockey teams.
- Rental Services:Businesses that provide temporary access to winter sports equipment at resorts and specialty shops. Rental services cater to tourists and new participants, offering a low-commitment entry point to winter activities.
Recreational Users drives market volume, with Professional Athletes experiencing significant growth.
Distribution Channel:
Customer preferences for convenience versus specialized advice shape the distribution landscape for winter sporting goods.
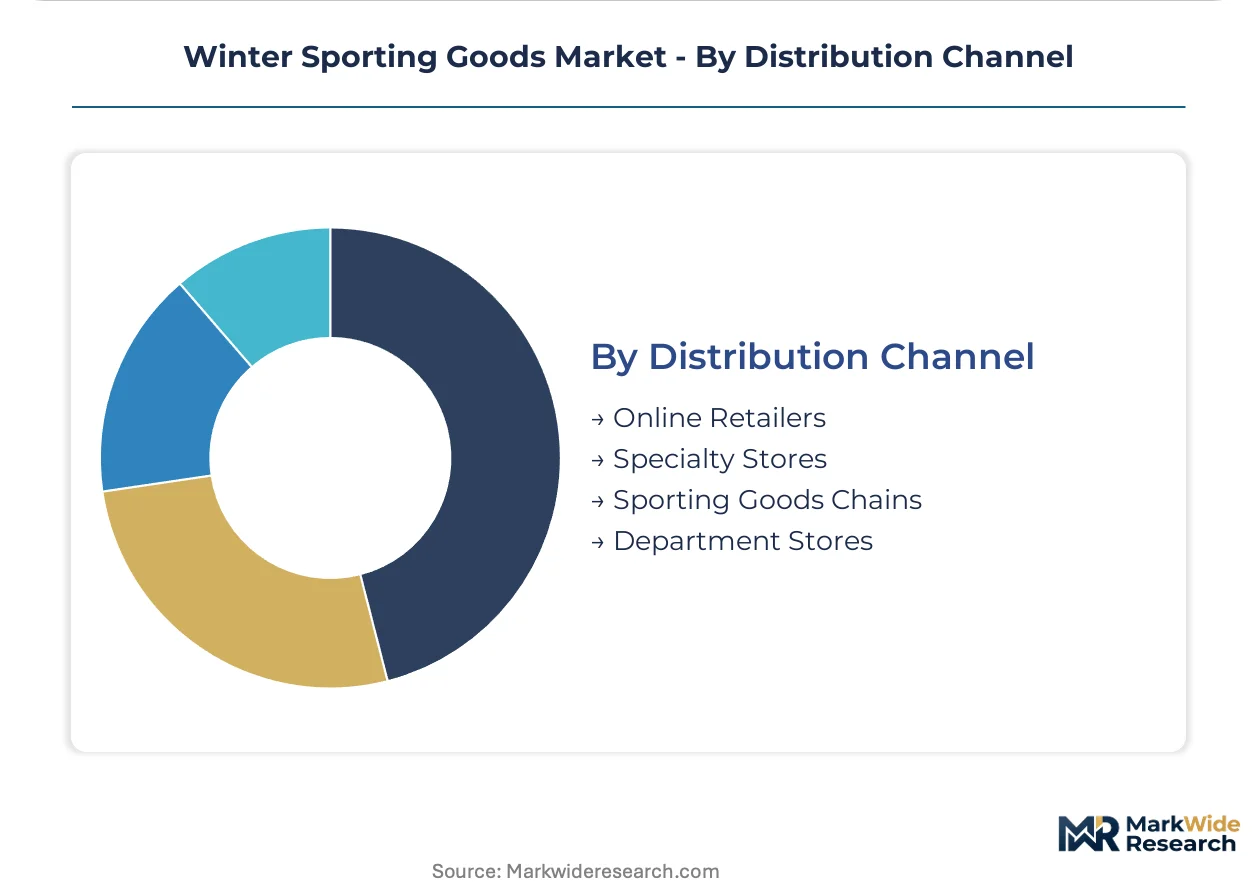
- Online Retailers:E-commerce platforms offering a wide selection of winter sporting goods, often at competitive prices and with direct shipping. This channel appeals to consumers prioritizing convenience and product comparison.
- Specialty Stores:Brick-and-mortar establishments providing expert advice, custom fitting services, and a curated selection of high-performance gear. Specialty stores remain crucial for premium equipment sales and personalized customer service.
- Sporting Goods Chains:Larger retail outlets carrying a broad range of sporting equipment, including winter sports gear, across multiple brands. These chains offer accessibility and a diverse product assortment to a wider consumer base.
- Department Stores:General merchandise retailers that may feature seasonal sections for winter sporting goods, often focusing on more accessible and entry-level products. Department stores cater to occasional buyers and gift purchases.
Specialty Stores commands substantial sales, as Online Retailers expands its reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry exists between highly developed winter sports markets and emerging regions. Established markets like the United States and France command premium pricing for specialized equipment, while countries such as China are more price-sensitive during initial market penetration phases. This dynamic influences product development and distribution strategies across different geographies.
United States
Recreational users in the United States drive demand for both high-performance skis and snowshoes, particularly in national parks and mountain resorts. State-level environmental protection agencies often encourage the use of sustainable materials in consumer goods, influencing manufacturing practices. The Rocky Mountain states, including Colorado and Utah, serve as a significant hub for specialty retail and equipment testing.
Canada
Canadian consumers exhibit strong demand for ice hockey equipment and general winter sports gear, supported by national campaigns promoting active lifestyles. Health Canada enforces specific safety regulations for ice hockey equipment, ensuring product compliance for manufacturers. Major cities like Montreal and Toronto house significant retail infrastructure and ice hockey equipment manufacturers.
France
French alpine regions concentrate demand for high-performance skis, sustained by a robust tradition of winter sports and all-season resorts. The European Union's Ecodesign for Sustainable Products Regulation is compelling manufacturers to innovate in product durability and recyclability. The Auvergne-Rhône-Alpes region, encompassing major ski destinations, is a focal point for equipment sales and rental services.
Japan
Younger recreational users in Japan significantly contribute to the growth of snowboarding equipment, embracing diverse riding styles. Japanese Industrial Standards (JIS) often guide quality and safety benchmarks for winter sporting goods sold domestically. Hokkaido, with its renowned ski resorts, attracts a substantial number of winter sports tourists and equipment sales.
China
China presents a significant opportunity for market entry, driven by a growing middle class and government support for winter sports participation. The country's dual carbon goals are increasingly influencing manufacturers to adopt sustainable material inputs and production processes. Beijing and the Northeast provinces are developing winter sports infrastructure, fostering new equipment demand.
Winter Sporting Goods Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the winter sporting goods market. The market exhibits a tiered structure, with established brands focusing on innovation and premium positioning, while other players target broader accessibility. Strategic partnerships and portfolio diversification are common competitive moves among major industry participants.
Among the established multi-brand portfolios, Amer Sports Corporation leverages its extensive reach to cater to diverse consumer segments. Rossignol Group exemplifies a premium brand strategy, anchoring its market position in alpine racing heritage and high-end product offerings. Burton Snowboards dominates the snowboarding niche through strong brand loyalty and direct-to-consumer channel control, representing a specialized market leader.
| Leading Market Players |
|---|
| Amer Sports Corporation |
| Rossignol Group |
| Burton Snowboards |
| Bauer Hockey |
| K2 Sports |
| Tecnica Group |
| Fischer Sports |
| Decathlon SA |
| Head NV |
Cost & Logistics Intelligence
Average inventory turnover of winter sporting goods, spanning 90-120 days for specialty retailers, heavily influences both the supply chain's seasonal configuration and the pricing power of manufacturers. This seasonal demand necessitates precise inventory management to mitigate obsolescence risks.
Pricing Analysis
Geographic price differentiation exists, with premium pricing commanded in established markets like the United States and France for high-performance equipment. The pricing model primarily follows a tiered premium-mid-economy differentiation, driven by material composition like carbon fiber content and specialized manufacturing processes. Raw material price volatility, particularly for advanced polymers, creates downward pricing pressure for high-end models. Recreational users represent the most price-sensitive segment, while professional athletes prioritize performance over cost.
Supply Chain Analysis
Extended lead times for composite material production, such as carbon fiber and fiberglass, anchor the upstream supply chain for winter sporting goods. Geographic supply concentrates in East Asia for general manufacturing and Europe for specialized components, with raw material dependencies on global chemical and textile suppliers. Commodity price volatility for specialized polymers poses a significant structural risk. Downstream distribution runs through a hybrid model, balancing online retailers with specialty stores providing high-touch services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase, driven by renewed enthusiasm for outdoor activities and government health initiatives promoting winter sports participation. This momentum offers strategic avenues for various market participants.
For Market Incumbents: Secure long-term supply agreements for sustainable materials, leveraging economies of scale to mitigate raw material price volatility. Invest in advanced R&D for modular product designs, addressing the looming threat of stringent EU Ecodesign regulations. Deepen direct-to-consumer channels while optimizing specialty store relationships to counter channel conflict and climate variability impacts.
For New Entrants and Emerging Players: Anchor in niche segments by offering innovative rental and subscription service models, lowering the high barrier to entry for new users. Target emerging markets like China with localized product offerings and accessible price points. A go-to-market angle focused on smart, connected equipment for performance analytics provides a distinct competitive advantage.
For Investors and Strategic Acquirers: Long-term, this sits as a growth-oriented play because expanding recreational user bases and sustainable material innovations drive market expansion. Acquisition targets should focus on specialized material developers or digital platform providers enhancing equipment-as-a-service models. The signal to watch is the adoption rate of circular economy principles by major brands, indicating future competitive differentiation.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Material R&D | Manufacturers invest in bio-based resins and recycled fabrics to meet EU Ecodesign for Sustainable Products Regulation. |
| Rental and Subscription Platform Development | New service models lower upfront costs for consumers, engaging new users in destination ski areas. |
| Smart Equipment Integration | Sensors in skis and helmets provide performance analytics, appealing to performance-focused athletes. |
| Emerging Market Entry (China) | A growing middle class in China presents significant opportunity for brand building and equipment demand. |
| Direct-to-Consumer Channel Expansion | Brands like Burton Snowboards strengthen customer loyalty and gain control over product distribution. |
Research Approach
The analysis maps winter sports equipment, accessories, and apparel sub-sectors, each validated through primary interviews with industry stakeholders. This involved conversations with product developers, specialty store owners, resort operators, and ski technicians. Secondary research leveraged national sports participation surveys, trade association reports, and company financial filings to triangulate data. Both bottom-up and top-down approaches ensured comprehensive market sizing and segment analysis.
Outputs were validated against external benchmarks, ensuring consistency across the modeling period. The analytical framework modeled segmentation dimensions including product type, material, end-user, distribution channel, and performance tier. Compound Annual Growth Rates were derived from historical trends and projected market dynamics. Key forecast inputs included winter sports participation rates and raw material cost indices.
Material uncertainties — climate change impacts on snowfall and geopolitical events affecting supply chains — sit outside the modeled envelope, reflecting inherent market variability. Forecasts reflect assumptions documented through extensive primary and secondary research. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
BMX Bikes Market
Sports Equipment
Tennis Racquet Market
Sports Equipment
Tennis Ball Machine Market
Sports Equipment
Global Wakeboarding Equipment Market
Sports Equipment
Volleyball Equipment Market
Sports Equipment
Germany Horse Riding Equipment Market
Sports Equipment
Gym Rubber Flooring Market
Sports Equipment
Curling Equipment Market
Sports Equipment
Global Kinesio Tape Market
Sports Equipment
US Sports Flooring Market
Sports Equipment
Juggling Clubs Market
Sports Equipment
Figure Skating Equipment Market
Sports Equipment
Boxing Gear Market
Sports Equipment
UAE Horse Riding Equipment Market
Sports Equipment
Bowling Lane Panels Market
Sports Equipment
Global Mountain Bicycles Market