
 Cycling Helmet Market | 2026-2036
Cycling Helmet Market Size, Share, and Industry Trends Forecast 2026-2036
Cycling Helmet Market Analysis
Modular fit-system bundling is hardening as the dominant configuration pattern, with premium brands pairing adjustable retention mechanisms with replacement liner subscriptions to extend product lifecycles. Specialized Bicycle Components leverages in-house retention-system R&D to sustain margin control across its helmet portfolio. Trek Bicycle Corporation anchors North American distribution through owned retail and dealer networks. KASK dominates European road and track cycling with Italian manufacturing specialization.
A cycling helmet is a protective headgear device constructed from an outer polycarbonate or carbon fiber shell bonded to an expanded polystyrene (EPS) impact-absorbing liner, engineered to dissipate kinetic energy during collision events and reduce traumatic brain injury risk. The primary commercial purpose spans recreational safety compliance, competitive aerodynamic performance, and urban commuter liability protection. Road helmets command the largest revenue pool due to high replacement frequency among club cyclists, while MIPS-equipped models represent the fastest-expanding feature segment as insurers and retailers push rotational-impact protection. Carbon fiber material grades concentrate margin capture at the premium tier, though polycarbonate volumes anchor mass-market accessibility.
CPSC standards govern impact attenuation and retention system integrity for US market access, while CE marking under the EU's Personal Protective Equipment Regulation mandates third-party conformity assessment for European distribution. Germany's KBA-influenced traffic safety discourse and France's ANSM-monitored sports equipment liability frameworks further shape regional product requirements. Stakeholders must monitor evolving e-bike speed classifications across jurisdictions, as helmet performance thresholds face recalibration to address higher-impact collision profiles from motorized bicycle adoption.
Market Dynamics
MIPS rotational-impact technology is compressing replacement cycles as insurers and retailers coalesce around brain-injury liability mitigation, forcing legacy EPS-only architectures toward obsolescence.
Growth Catalysts
- E-bike speed reclassification:Germany's KBA and France's ANSM are recalibrating helmet performance thresholds to address collision profiles from motorized bicycles exceeding 25 km/h.
- CE marking expansion:The EU's Personal Protective Equipment Regulation mandates third-party conformity assessment, creating compliance-driven replacement demand across European distribution channels.
- Modular fit-system bundling:Premium brands pair adjustable retention mechanisms with replacement liner subscriptions, extending product lifecycles and anchoring recurring revenue streams.
Market Restraints
- Carbon fiber supply concentration:Premium-tier material grades depend on Japanese and German specialty chemical suppliers, exposing margin capture to input volatility.
- CPSC certification friction:US market access requires impact attenuation and retention system integrity testing that delays product launches by 8-14 months.
- Polycarbonate substitution ceiling:Mass-market accessibility anchors on petroleum-derived shell materials vulnerable to energy price shocks and sustainability scrutiny.
Strategic Opportunities
- Urban commuter underpenetration:Municipal bike-sharing programs in Copenhagen, Amsterdam, and Paris lack helmet integration, creating white space for rental-system partnerships.
- Insurer-driven MIPS mandates:Liability carriers in the Netherlands and Belgium are introducing premium discounts for rotational-impact-equipped models, accelerating feature adoption.
- Direct-to-consumer channel expansion:Owned retail networks and subscription-based liner replacement bypass traditional dealer markups in North America.
Industry Challenges
- Retention-system R&D talent scarcity:In-house adjustable mechanism design requires biomechanical engineering expertise concentrated in Italian and German manufacturing clusters.
- Multi-jurisdiction certification complexity:Simultaneous CPSC, CE marking, and emerging KBA-influenced state-level mandates fragment testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cycling Helmet Market |
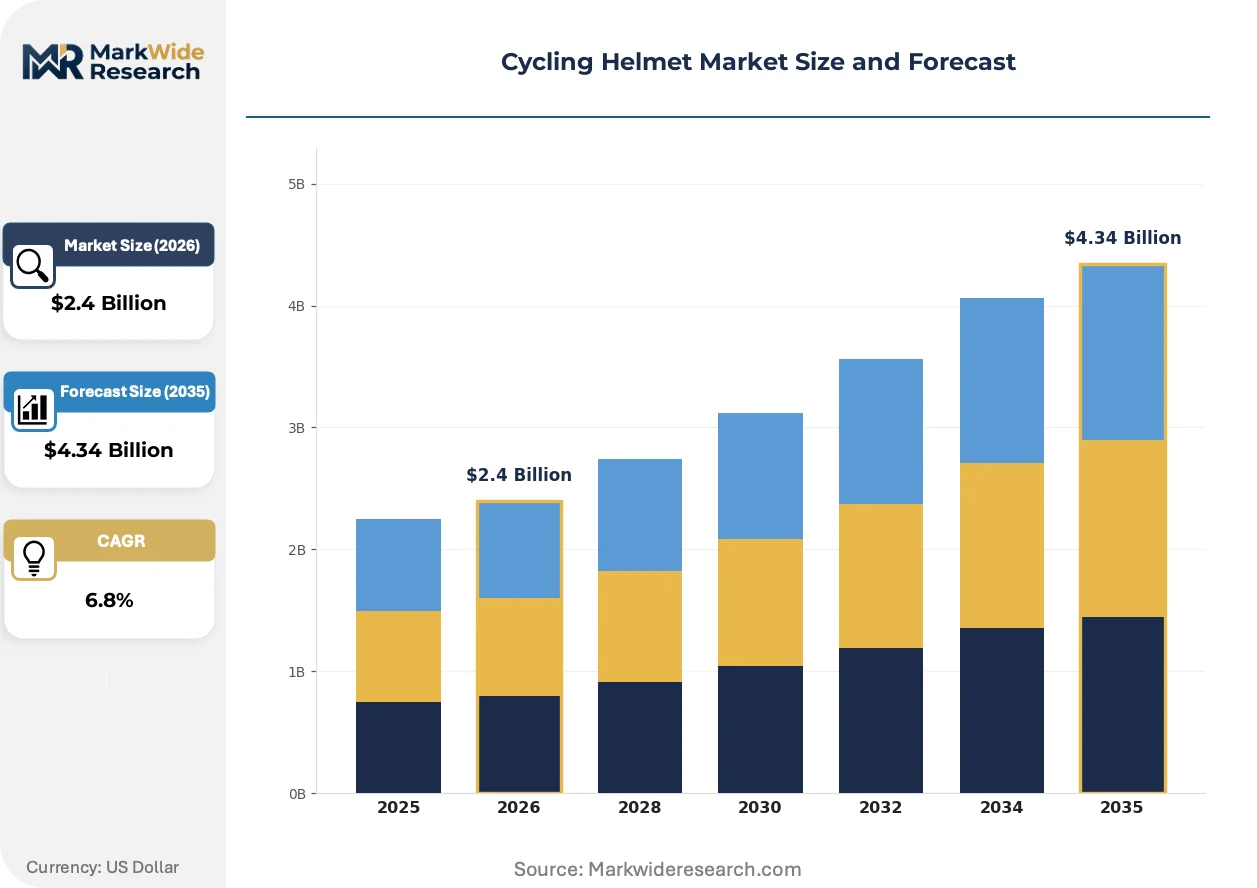
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Road, Mountain, BMX, Commuter Material: Polycarbonate, Fiberglass, Carbon Fiber, EPS Feature: Ventilation, MIPS, Adjustable Fit, Lightweight Customer Type: Recreational Cyclists, Professional Athletes, Kids, Women |
| Companies Covered | Specialized Bicycle Components, Trek Bicycle Corporation, Vista Outdoor, Dorel Sports, KASK, POC Sports, MET-Helmets, Uvex Group, Scott Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cycling Helmet Market Emerging Trajectories
Helmet architecture is bifurcating between aerodynamic performance optimization for competitive cycling and modular safety-system integration for urban mobility, with material science and regulatory pressure as the twin forcing functions.
Multi-density EPS liners paired with low-friction MIPS layers are converging with carbon fiber shell reinforcement to deliver rotational-impact protection without weight penalties. Competitive road cyclists and track specialists in Italy and Belgium are adopting these configurations at replacement frequencies of 18-24 months. This convergence is compressing R&D amortization timelines and forcing mid-tier brands toward private-label sourcing.
Germany's KBA-influenced traffic safety discourse is accelerating mandate discussions across multiple Länder, with Bavaria and Baden-Württemberg examining compulsory helmet laws for e-bike riders. The industrial consequence is a surge in testing laboratory capacity expansion by TÜV and DEKRA. Road and commuter helmet SKUs face recalibration to address 32 km/h impact thresholds, with German manufacturers pre-positioning inventory ahead of legislative finalization.
Subscription-based liner replacement is displacing traditional point-of-sale transactions among club cyclists and daily commuters. Specialized retailer networks in the US and direct-to-consumer platforms in Germany are capturing recurring revenue through fit-system maintenance programs. This pattern is most visible in urban corridors where bike-sharing adoption correlates with helmet ownership gaps.
Cycling Helmet Market Segmentation
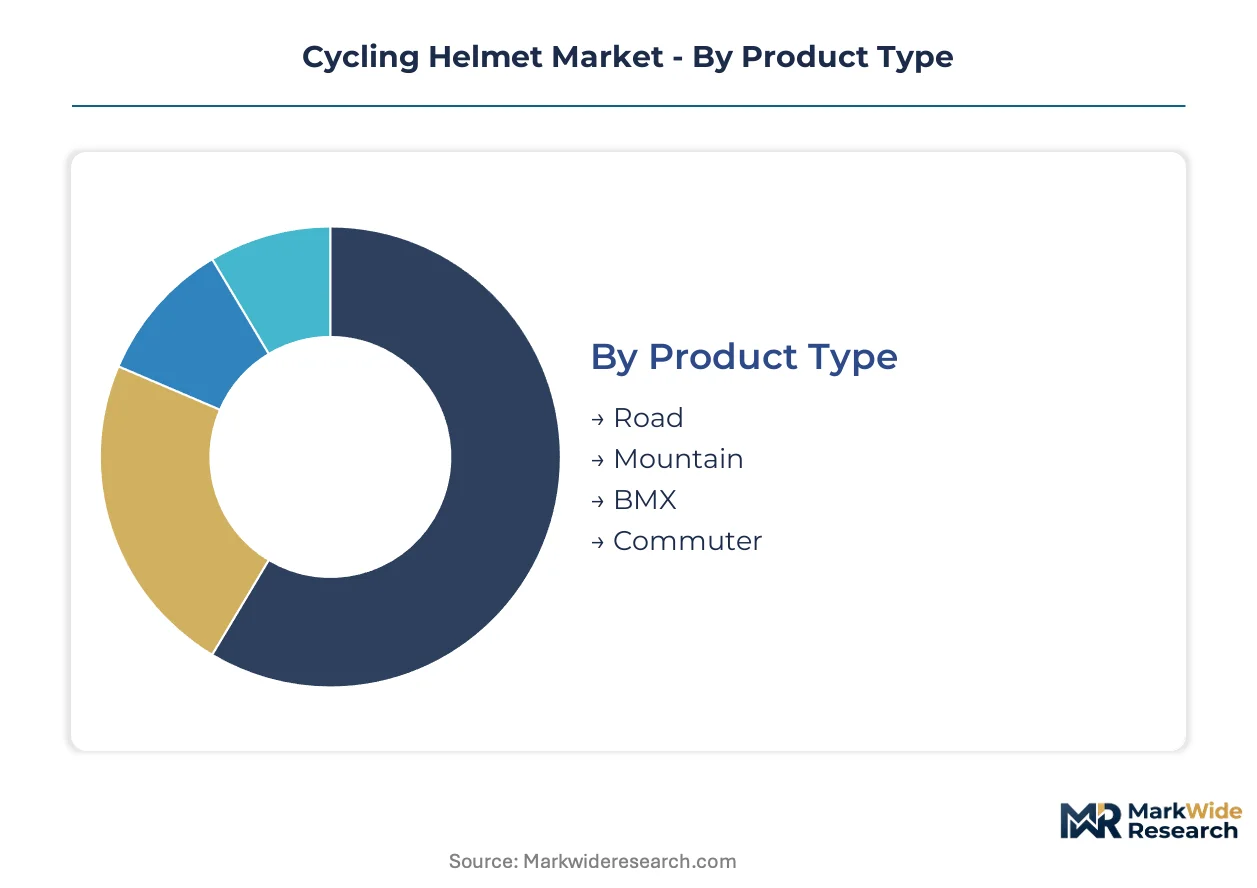
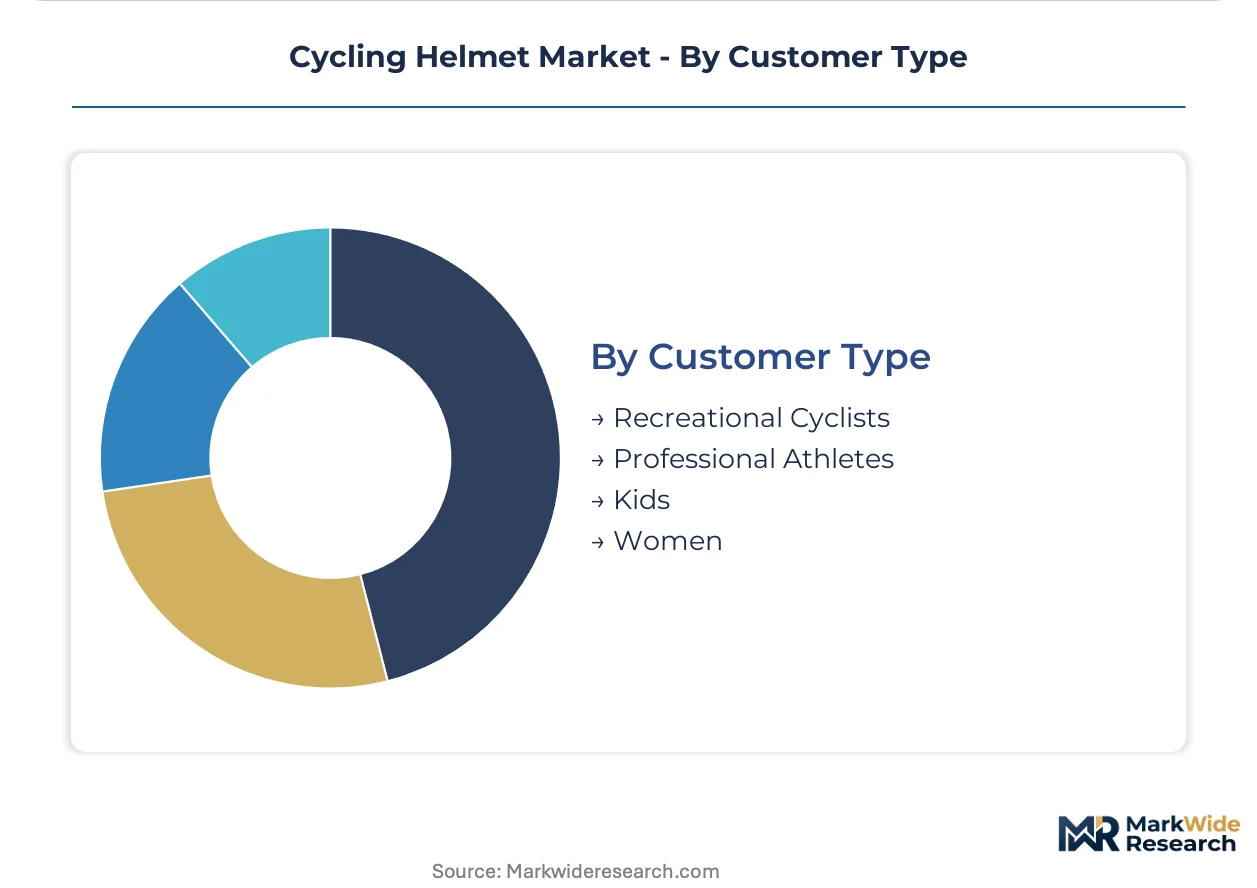
Cycling helmet purchasing decisions diverge sharply between competitive performance optimization and urban liability protection. Segmentation reveals how material science, safety certification tiers, and end-use intensity fragment demand across price bands and replacement cycles.
Product Type:
Riders select helmet architecture based on impact velocity expectations and aerodynamic priorities rather than price alone.
- Road:Sleek polycarbonate or carbon fiber shells with extensive ventilation channels dominate club cycling and competitive racing. Germany's Autobahn-proximate training routes and Belgium's Flanders classics circuit concentrate replacement demand among amateur racers seeking CE-certified impact protection.
- Mountain:Extended rear coverage and visor integration address variable terrain impacts and branch deflection. Demand clusters in the French Alps and Italian Dolomites where enduro cycling parks drive seasonal purchase spikes and faster EPS liner degradation from UV exposure.
- BMX:Hardened shells with full-face options prioritize repeated low-speed impact resilience over ventilation. Urban skate parks in Copenhagen and Amsterdam anchor volume through municipal youth programs.
- Commuter:Integrated lighting mounts and casual styling bridge safety compliance with workplace arrival aesthetics. Paris and Berlin bike-sharing corridors show ownership gaps that rental-system partnerships could address.
Volume sits with Road helmets; growth tilts toward Commuter configurations as municipal cycling infrastructure expands.
Material:
Shell composition determines margin capture potential and regulatory pathway complexity across certification regimes.
- Polycarbonate:Petroleum-derived thermoplastic injection molding enables mass-market price accessibility. Volume concentrates in big-box retail and entry-level commuter SKUs vulnerable to energy price volatility.
- Fiberglass:Composite layup delivers intermediate strength-to-weight ratios for mid-tier road and mountain applications. Italian manufacturers leverage regional glass fiber supply chains for domestic production.
- Carbon Fiber:Aerospace-grade prepreg autoclave curing yields premium-tier shells with sub-200g weights. Japanese Toray and German SGL Carbon supply concentration exposes margin capture to specialty chemical input constraints.
- EPS:Expanded polystyrene liners bond to all shell types for kinetic energy dissipation; multi-density configurations now pair with MIPS layers in premium architectures.
Polycarbonate anchors unit volume; carbon fiber claims the steepest expansion trajectory as rotational-impact protection mandates spread.
Feature:
Feature bundling now extends product lifecycles through subscription economics rather than one-time hardware sales.
- Ventilation:Channel geometry and port placement differentiate summer racing configurations from enclosed winter commuter designs. Italian and Spanish markets prioritize airflow optimization for Mediterranean climate conditions.
- MIPS:Low-friction layer inserts reduce rotational brain injury risk during oblique impacts. Dutch and Belgian insurers now mandate this feature for premium discounts, compressing legacy EPS-only replacement cycles.
- Adjustable Fit:Dial-based retention systems enable circumference and vertical positioning customization. Premium brands pair these mechanisms with replacement liner subscriptions to capture recurring revenue.
- Lightweight:Sub-250g targets for competitive road cycling drive carbon fiber adoption and EPS density reduction, trading impact absorption margins for aerodynamic gains.
Adjustable fit systems command the broadest adoption; MIPS integration is climbing fastest as liability frameworks tighten.
Customer Type:
End-user physiology and risk tolerance fragment sizing, styling, and certification requirements across demographic cohorts.
- Recreational Cyclists:Weekend road and trail riders prioritize comfort and ventilation over racing weight. German and Austrian alpine tourism corridors concentrate seasonal purchase timing.
- Professional Athletes:UCI WorldTour teams and track specialists demand wind-tunnel-validated aerodynamics with 18-24 month replacement schedules. Belgian classics and Italian Grand Tour stages drive visibility-driven sponsorship value.
- Kids:Scaled shell geometries with cartoon-themed graphics address parental safety compliance. French and Dutch school cycling programs create institutional procurement channels.
- Women:Ponytail-compatible retention systems and reduced shell volumes address anatomical fit gaps previously served by unisex downsizing. Urban commuter adoption in Scandinavian capitals shows strongest growth.
Recreational cyclists dominate unit volume; women-specific designs are expanding most quickly as fit-system R&D addresses historical underpenetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing clusters concentrate in Italy and Germany while consumption spreads across urban commuter corridors in Northern Europe and North American metropolitan areas. This production-consumption divide shapes logistics networks and certification requirements across jurisdictions.
Germany
KBA-influenced mandate discussions in Bavaria and Baden-Württemberg are accelerating replacement demand among e-bike commuters. CE marking under the EU's Personal Protective Equipment Regulation governs all domestic distribution. Stuttgart's industrial belt hosts precision retention-system engineering facilities serving premium European brands.
United States
CPSC certification friction delays product launches by 8-14 months for importers, creating first-mover advantages for domestic R&D operations. NHTSA-adjacent safety discourse influences municipal helmet ordinance adoption in Pacific Northwest cities. Boulder and Portland anchor testing laboratory clusters for impact attenuation validation.
Italy
Wind-tunnel-validated aerodynamics drive 18-24 month replacement cycles among professional road cyclists in Lombardy and Veneto. ANSM-monitored sports equipment liability frameworks shape product specifications for export markets. Treviso province concentrates carbon fiber shell fabrication and retention-system manufacturing.
Netherlands
Insurer-driven MIPS mandates introduce premium discounts for rotational-impact-equipped models, compressing legacy EPS-only architectures. Municipal bike-sharing programs in Amsterdam and Utrecht lack helmet integration, creating rental-system partnership opportunities. Rotterdam's logistics hub facilitates distribution across Benelux commuter corridors.
France
ANSM liability frameworks and Paris bike-sharing expansion are converging to elevate commuter helmet ownership rates. CE marking mandates third-party conformity assessment through notified bodies. Auvergne-Rhône-Alpes hosts enduro cycling parks driving seasonal mountain helmet demand and faster EPS liner degradation from UV exposure.
Cycling Helmet Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered pricing bands. The vendor base organizes around three strategic archetypes: vertically integrated bicycle OEMs with captive helmet portfolios, Italian manufacturing specialists with regional supply chain control, and diversified outdoor equipment conglomerates with multi-brand distribution leverage. Competitive moves concentrate on modular fit-system R&D and direct-to-consumer channel expansion.
Within the pure-play specialist tier, KASK and POC Sports exemplify European manufacturing concentration with Italian and Swedish origins respectively. Specialized Bicycle Components occupies a position representing bicycle OEM vertical integration, while Trek Bicycle Corporation anchors North American distribution scale. These three companies sit within distinct competitive vectors—premium European specialization, integrated R&D control, and mass-market retail penetration—without overlapping strategic positioning.
| Leading Market Players |
|---|
| Specialized Bicycle Components |
| Trek Bicycle Corporation |
| Vista Outdoor |
| Dorel Sports |
| KASK |
| POC Sports |
| MET-Helmets |
| Uvex Group |
| Scott Sports |
| Others |
Supply Flow & Price Mechanics
Biomechanical engineering talent concentration in Italian and German manufacturing clusters widens labor-cost differentials between premium and mass-market tiers, compressing mid-tier margins while sustaining pricing power at the rotational-impact protection frontier.
Pricing Analysis
Margin tightening in polycarbonate-based entry tiers reflects petroleum-derived input volatility and big-box retail procurement consolidation. Three-tier pricing structure across premium carbon fiber, intermediate fiberglass, and economy polycarbonate levels separates MIPS-equipped subscription bundles from transactional EPS-only sales. Price differentiation traces to CE marking certification grade and retention-system customization depth. Daily commuters exhibit highest price sensitivity; UCI WorldTour team procurement shows lowest elasticity.
Supply Chain Analysis
Retention-system engineering workforce scarcity in Treviso province and Stuttgart's industrial belt constrains capacity expansion across European manufacturing nodes. Raw material sourcing draws from Japanese Toray and German SGL Carbon for aerospace-grade prepreg, Italian glass fiber suppliers for mid-tier composites, and petroleum-derived polycarbonate feedstock for mass-market injection molding. Single-source vulnerability concentrates in carbon fiber specialty chemical inputs. Distribution runs through owned retail networks in North America and dealer channels across European cycling corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon fiber prepreg autoclave curing capacity scarcity props pricing premiums for sub-200g rotational-impact architectures, constraining volume expansion at the safety-technology frontier.
For Market Incumbents: Acquire in-house retention-system R&D capabilities to counter MIPS licensing cost compression and private-label sourcing encroachment from mid-tier brands. Pre-position inventory ahead of KBA-influenced e-bike helmet mandate finalization across Bavaria and Baden-Württemberg. Anchor backward integration into multi-density EPS liner production to defend margin structure against petroleum feedstock volatility. For New Entrants and Emerging Players: Municipal bike-sharing operators in Amsterdam, Copenhagen, and Paris represent an underserved buyer archetype with unmet helmet integration requirements. Rental-system partnerships with integrated fit-system maintenance subscriptions offer the most penetrable go-to-market angle. Target insurer-driven MIPS mandate acceleration in the Netherlands and Belgium through liability-carrier distribution channels. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play European manufacturing specialists given CE marking compliance complexity and Italian supply chain control. Long-term viability favors retention-system engineering capabilities and carbon fiber shell fabrication expertise over brand-dependent marketing plays. Watch TÜV and DEKRA testing laboratory capacity expansion rates as inflection indicators for mandate-driven replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| MIPS Technology Licensing | Rotational-impact protection integration accelerates insurer-driven premium tier adoption across Dutch and Belgian markets. |
| Subscription Liner Replacement | Recurring revenue capture through fit-system maintenance programs displaces traditional point-of-sale transactions among club cyclists. |
| Direct-to-Consumer Channel Expansion | Owned retail networks bypass dealer markups and capture customer relationship data for retention-system customization. |
| E-bike Impact Threshold Recalibration | Pre-positioning inventory ahead of KBA-influenced mandate discussions defends market share in German Länder corridors. |
| Carbon Fiber Backward Integration | Upstream control over aerospace-grade prepreg curing reduces exposure to Japanese and German specialty chemical supplier concentration. |
Methodological Framework
Multi-period observation of municipal bike-sharing adoption rates, e-bike speed reclassification proceedings, and MIPS integration penetration anchored the trend analysis, supplemented by interviews with helmet product managers at bicycle OEMs, retention-system biomechanical engineers, TÜV certification specialists, Dutch insurance underwriters, and European dealer network operators. Secondary validation drew from CPSC certification filings, CE marking conformity assessment records, KBA traffic safety discourse documentation, and customs trade data for carbon fiber prepreg imports. Bottom-up SKU-level volume aggregation triangulated against top-down regional demand modeling.
Input-output matrices mapped polycarbonate, fiberglass, and carbon fiber shell production through EPS liner bonding, MIPS layer integration, and retention-system assembly to end-use segmentation across road, mountain, BMX, and commuter applications. CAGRs derived from replacement cycle compression analysis, e-bike adoption velocity, and regulatory mandate probability-weighted scenarios. Industry-specific forecast inputs incorporated insurer premium discount policy diffusion rates and municipal infrastructure investment commitments.
Revisions become necessary when KBA mandate finalization timelines shift, carbon fiber specialty chemical supply disruptions materialize, or MIPS patent licensing structures alter competitive cost structures. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Speed Hurdle Market
Sports Equipment
Cleat Market
Sports Equipment
United States Running Gear Market
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
Golf Equipment Market
Sports Equipment
Padel Balls Market
Sports Equipment
Tennis Ball Machine Market
Sports Equipment
Rowing Boats Market
Sports Equipment
Smart Boxing Gear Market
Sports Equipment
Sports Fishing Equipment Market
Sports Equipment
Europe Kickboxing Equipment Market
Sports Equipment
Basketball Gear Market
Sports Equipment
BMX Bikes Market
Sports Equipment
Global Horse Riding Equipment Market
Sports Equipment
Wetsuits Market
Sports Equipment
Europe Archery Equipment Market