
 Surfboard Market | 2026-2036
Surfboard Market Size, Share, and Industry Trends Forecast 2026-2036
Surfboard Market Intelligence
Wave pool operators and surf tourism resorts is decoupling from traditional ocean-dependent retail channels as artificial wave venues multiply across inland markets. Firewire leverages sustainable construction methods to anchor premium positioning in environmentally conscious segments. Channel Islands competes through elite athlete sponsorship networks that sustain brand prestige among professional riders. Cobra International dominates Southeast Asian manufacturing scale, supplying OEM volume to multiple labels while controlling regional export logistics.
A surfboard is a hydrodynamic planing vessel constructed from foam cores laminated with fiberglass and resin, typically measuring 5 to 12 feet in length, designed to convert wave energy into forward propulsion for standing riders. Polyurethane blanks remain the dominant core material due to established shaping workflows and cost efficiency, though epoxy systems gain ground from superior durability and reduced volatile organic compound emissions during cure. Shortboards capture the professional and advanced skill tier where margin pools concentrate around custom geometry and limited production runs. Fish shapes represent the fastest-growing product type among recreational surfers seeking hybrid performance in variable wave conditions. Distribution through specialty shops persists as the preference for hands-on rocker and rail inspection before purchase.
EPA regulations on styrene emissions govern domestic manufacturing facility compliance, while REACH restrictions in Europe constrain specific resin chemistries available to importers. California's Proposition 65 labeling requirements create friction for brands distributing polyurethane-based products without reformulated catalyst systems. ISO 4892 weathering standards influence warranty terms and material selection for boards sold across multiple climate zones. Stakeholders must monitor how regional chemical restrictions cascade through supply chains and determine whether localized production or resin reformulation delivers lower total compliance cost.
Market Dynamics
Artificial wave venue proliferation is decoupling surfboard demand from coastal geography, creating inland procurement channels that bypass traditional ocean-dependent retail networks and reshape distribution economics.
Growth Catalysts
- REACH resin restrictions:European chemical constraints accelerate bio-based epoxy adoption, opening premium positioning for compliant manufacturers.
- Wave pool infrastructure:Indoor surf venues in landlocked regions generate sustained equipment procurement independent of seasonal ocean conditions.
- Polyurethane catalyst reformulation:California's Proposition 65 enforcement drives R&D investment in low-emission cure systems.
Market Restraints
- Petrochemical input volatility:Styrene and polyurethane precursor prices fluctuate with crude oil indices, compressing margin predictability for foam-core producers.
- Southeast Asian manufacturing concentration:Thai and Vietnamese OEM facilities control regional export logistics, creating single-source vulnerability for multiple labels.
- Durability-performance tradeoff:Epoxy systems reduce volatile organic compound emissions but add weight, limiting adoption in high-performance shortboard segments.
Strategic Opportunities
- Desert climate wave parks:UAE and Saudi Arabia surf tourism investments create demand for boards engineered to extreme heat and chlorinated water conditions.
- Subscription-based equipment access:Rental-to-own models at artificial venues reduce entry cost barriers for novice surfers.
- ISO 4892 weathering certification:Standardized durability testing enables warranty differentiation across multi-climate distribution.
Industry Challenges
- Master shaper talent scarcity:Hand-finishing expertise concentrates among aging craftspeople, constraining custom shortboard volume scaling.
- Dual certification timelines:Boards sold across EPA-regulated US facilities and REACH-governed European import channels require parallel compliance documentation.
- Legacy polyurethane workflow integration:Established shaping bays resist epoxy system retooling due to capital equipment lock-in.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surfboard Market |
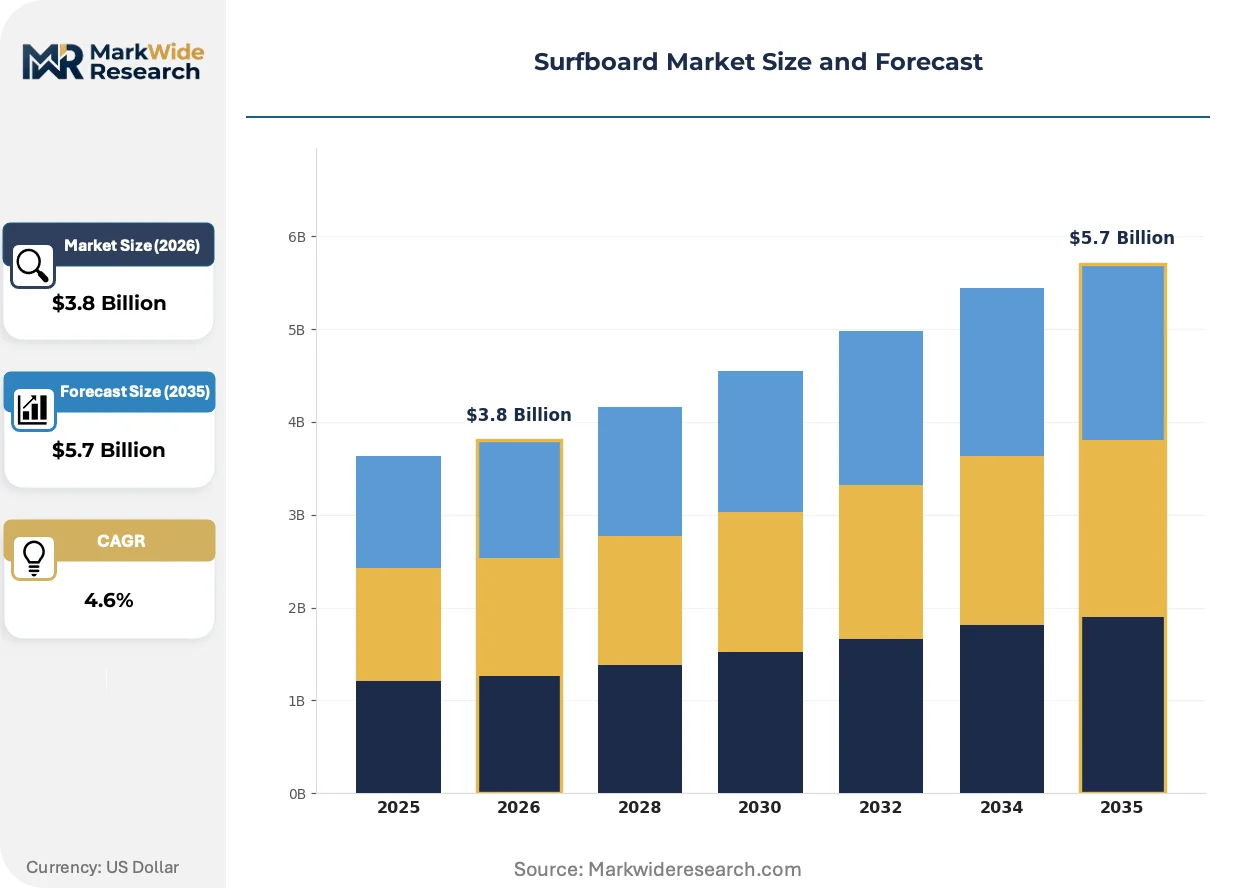
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shortboard, Longboard, Fish, Funboard Material: Polyurethane, Epoxy, Wood, Foam Skill Level: Beginner, Intermediate, Advanced, Professional Distribution Channel: Retail Stores, Online, Specialty Shops, Custom Orders |
| Companies Covered | Channel Islands, Album Surfboards, Firewire, Lib Tech, Pukas, Lost Surfboards, Cobra International, Almond Surfboards, Pyzel Surfboards, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surfboard Market Strategic Shifts & Innovations
Material science advances and regulatory chemistry constraints are converging to redefine construction standards, while artificial venue proliferation severs the historical link between surfboard consumption and coastal population density.
Epoxy resin systems are consolidating market position in recreational and rental segments where durability outweighs weight sensitivity. Wave pool operators and surf schools prioritize board longevity over performance optimization, accepting marginal mass penalties. This adoption pattern is consolidating procurement volume around standardized epoxy constructions that reduce replacement frequency and simplify inventory management.
California's Proposition 65 labeling mandates create friction for polyurethane-based products distributed without reformulated catalyst systems. Manufacturers face facility compliance costs or product reformulation investments to maintain access to the state's retail channels. Shortboard producers serving professional riders remain most affected, as elite athletes resist epoxy weight penalties despite regulatory pressure.
Direct-to-venue supply contracts are displacing traditional specialty shop intermediation for artificial wave operators. Bulk procurement agreements with wave pool developers specify volume, replacement schedules, and damage tolerance thresholds. This channel shift concentrates most visible in Australia, where coastal municipalities and inland surf tourism projects simultaneously expand infrastructure procurement.
Surfboard Market Segmentation
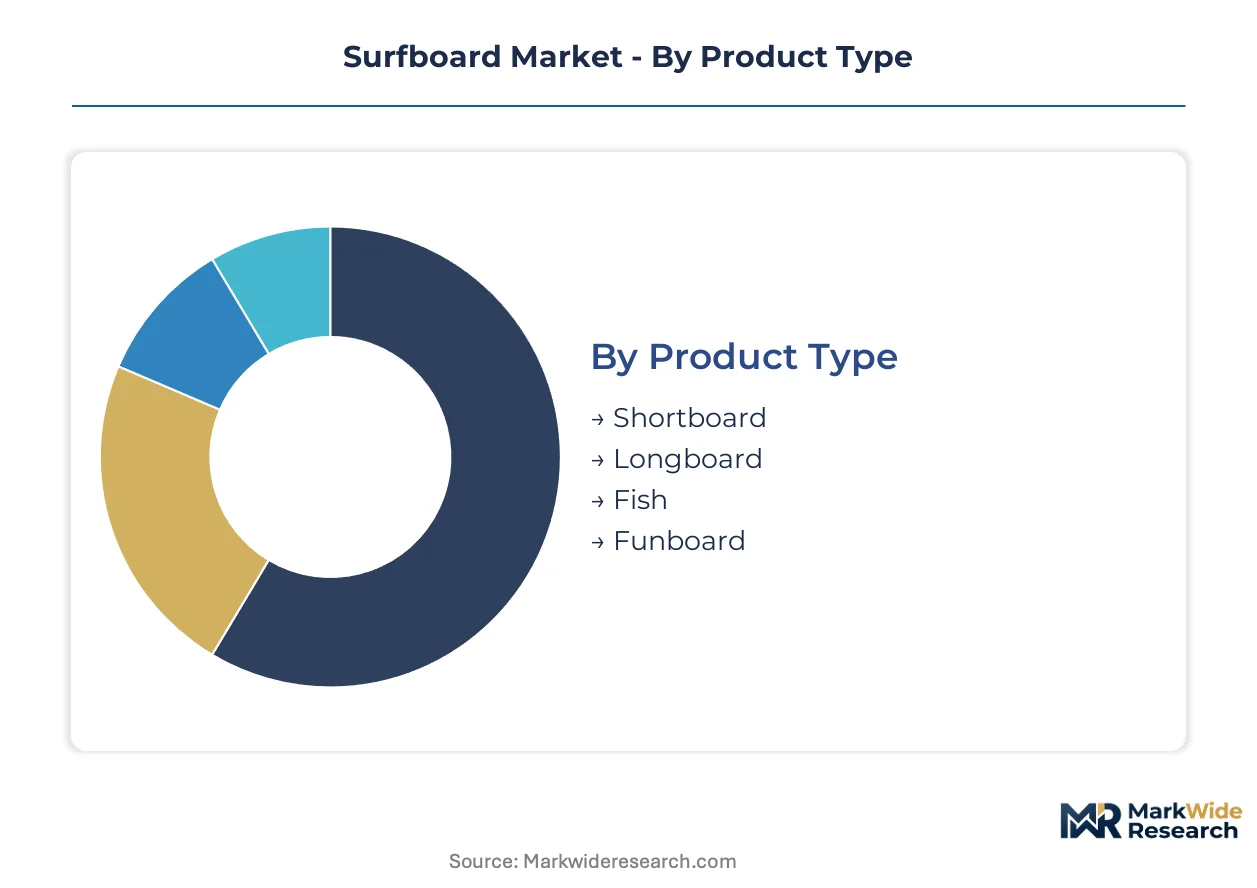
Surfboard segmentation reveals divergent margin structures across construction methods and rider proficiency tiers. Product type and material selection determine whether manufacturers compete on volume durability or elite performance customization.
Product Type:
Standalone recreational boards dominate procurement volumes while embedded venue fleets reshape distribution economics for specific geometries.
- Shortboard:Narrow, pointed-nose designs measuring 5 to 7 feet prioritize maneuverability and aerial capability. Professional riders and advanced surfers in Australia and California drive demand where wave pool operators now specify reinforced constructions for artificial venue durability.
- Fish:Wide, swallow-tailed shapes with reduced length provide hybrid performance across variable wave conditions. Recreational surfers seeking versatility in inconsistent surf represent the fastest-expanding user base as coastal municipalities invest in beginner-accessible infrastructure.
- Longboard:Traditional 9 to 12-foot lengths emphasize stability and nose riding for cruising-oriented surfers.
- Funboard:Mid-length hybrids bridge shortboard responsiveness with longboard paddle ease for transitioning skill levels.
Shortboard leads volumes today; Fish is gaining share fastest.
Material:
Cost tier stratification separates mass-market durability plays from premium lightweight constructions targeting elite performance segments.
- Polyurethane:Dominant foam-core construction laminated with fiberglass and polyester resin maintains established shaping workflows. California's Proposition 65 enforcement pressures manufacturers toward reformulated catalyst systems or facility compliance investments.
- Epoxy:Expanded polystyrene cores with epoxy resin laminates deliver superior impact resistance and reduced volatile organic compound emissions. Wave pool operators and surf schools across UAE and Saudi Arabia prioritize epoxy durability for chlorinated water and extreme heat exposure.
- Wood:Traditional hollow or solid timber constructions serve boutique custom markets and sustainability-positioned brands.
- Foam:Soft-top constructions with polyethylene decks target beginner rental programs and injury-conscious surf schools.
Polyurethane retains volume leadership; Epoxy climbs the fastest as regulatory pressure and venue procurement align.
Skill Level:
Application-specific requirements create distinct procurement channels from mass rental fleets to individualized custom geometry.
- Professional:Elite athletes demand hand-finished custom shapes with precise rocker and rail profiles. Sponsorship networks and competition circuits concentrate demand among established labels with master shaper access.
- Advanced:Experienced recreational surfers seek performance-oriented constructions with customization options for local break conditions.
- Intermediate:Transitioning riders drive volume through retail and online channels seeking forgiving geometries that accelerate skill development.
- Beginner:Entry-level surfers rely on rental programs and soft-top purchases at surf schools and artificial wave venues.
Intermediate and Beginner tiers concentrate procurement volume; Professional commands highest per-unit margins.
Distribution Channel:
Customer type determines whether transactions prioritize physical inspection or convenience-driven remote fulfillment.
- Specialty Shops:Hands-on rocker and rail inspection remains preferred for high-performance shortboard purchases. Established coastal retailers in Australia and California maintain relationships with local shapers for custom order facilitation.
- Custom Orders:Direct collaboration between rider and shaper enables precise dimensional specification for professional and advanced segments.
- Retail Stores:Mass-market sporting goods chains handle beginner and intermediate volume with standardized epoxy constructions.
- Online:Direct-to-consumer platforms serve geographically dispersed surfers with detailed specification transparency and return policies.
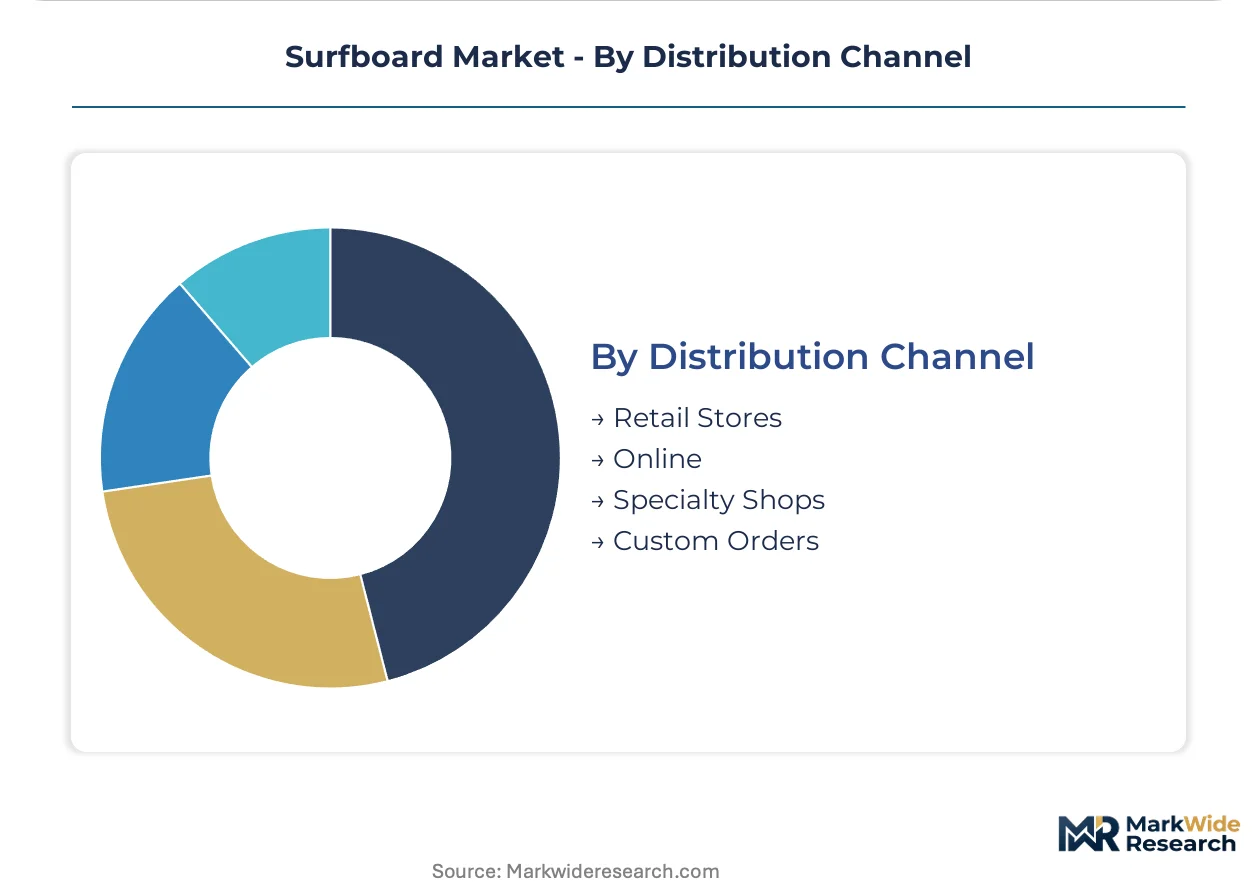
Specialty Shops anchor premium transactions; venue-direct procurement is displacing traditional intermediation fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing migration patterns reflect divergent chemical compliance costs across jurisdictions. Producers relocate to avoid California's Proposition 65 labeling mandates and REACH restrictions, while coastal tourism investments concentrate procurement in specific markets.
United States
California's Proposition 65 enforcement pressures domestic manufacturers toward reformulated polyurethane catalyst systems or facility compliance investments. The EPA governs styrene emissions from foam-core production facilities under Clean Air Act provisions. San Clemente and Santa Barbara host dense clusters of specialty shapers serving elite athletes and custom shortboard demand.
Australia
Coastal municipalities invest heavily in surf tourism infrastructure across Queensland and New South Wales, driving recreational board procurement. The TGA enforces product safety standards for water sports equipment distributed domestically. Gold Coast manufacturers supply both local retail channels and export markets across the Asia-Pacific region.
Thailand
Cobra International anchors Southeast Asian OEM manufacturing scale, supplying volume production to multiple international labels. The country's Board of Investment offers incentives for sports equipment manufacturing facilities. Chonburi Province concentrates fiberglass lamination and resin finishing operations serving global export logistics.
Germany
REACH restrictions constrain specific resin chemistries available to importers and domestic fabricators, accelerating bio-based epoxy adoption. The KBA does not directly regulate surfboard production, though ECHA chemical registrations govern material inputs. Munich and Hamburg host distribution hubs for European specialty retail channels.
United Arab Emirates
Desert climate wave parks in Dubai and Abu Dhabi generate demand for boards engineered to extreme heat and chlorinated water conditions. The MOHAP oversees product safety certification for recreational equipment distributed domestically. Artificial venue operators procure epoxy constructions prioritizing durability over weight optimization.
Surfboard Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with custom shapers commanding premium margins in professional tiers while OEM fabricators capture volume in recreational and rental channels. The market structures around three distinct tiers: heritage labels with athlete sponsorship networks, sustainability-positioned innovators, and scale-driven contract manufacturers. Consolidation remains limited by master shaper talent scarcity and regional brand loyalty. Competitive moves center on direct-to-venue supply contracts and bio-resin formulation partnerships.
Within the heritage specialist tier, Channel Islands and Lost Surfboards exemplify brands leveraging elite athlete relationships to sustain prestige positioning. Firewire occupies a sustainability-focused niche through environmentally conscious construction methods. At the contract manufacturing end, Cobra International anchors Southeast Asian production scale, supplying OEM volume to multiple labels while controlling regional export logistics.
| Leading Market Players |
|---|
| Channel Islands |
| Album Surfboards |
| Firewire |
| Lib Tech |
| Pukas |
| Lost Surfboards |
| Cobra International |
| Almond Surfboards |
| Pyzel Surfboards |
| Others |
Cost & Logistics Intelligence
Styrene and polyurethane precursor costs feed directly from crude oil indices through foam-core blank manufacturers to finished board pricing tiers, with California's Proposition 65 compliance investments layering additional margin pressure on domestic producers serving specialty retail channels.
Pricing Analysis
Retailer markup compression concentrates in mass-market epoxy constructions where wave pool operators negotiate volume-direct contracts bypassing traditional distribution layers. Price differentiation separates hand-finished custom shortboards from standardized rental fleet geometries, with certification grade and customization level commanding premium positioning. Pricing pressure intensifies as bio-based resin R&D costs amortize across limited production runs. Beginner rental programs exhibit highest price sensitivity, while professional riders demonstrate lowest sensitivity to per-unit cost.
Supply Chain Analysis
Refurbishment flows remain minimal given surfboard structural degradation patterns, though warranty replacement programs create limited reverse logistics volume from artificial venue operators. Manufacturing concentrates in Thailand, Vietnam, and Australia, with Cobra International anchoring Southeast Asian OEM scale. Raw material dependencies center on fiberglass roving, epoxy resin systems, and expanded polystyrene blanks. Single-source vulnerability concentrates in Thai export logistics controlling multiple label distribution. Distribution runs through specialty shops for premium transactions and direct-to-venue contracts for artificial wave procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as artificial venue proliferation and regulatory chemistry constraints simultaneously shift procurement toward durable epoxy specifications and bio-compliant constructions.
For Market Incumbents: Deepen master shaper apprenticeship pipelines to defend custom shortboard margins against talent scarcity erosion. Anchor backward integration into bio-resin formulation partnerships to secure California Proposition 65 compliance without sacrificing performance tier access. Facility retooling investments in low-emission cure systems represent critical defensive positioning.
For New Entrants and Emerging Players: REACH restrictions in Europe open a window for bio-based epoxy specialists to capture premium positioning among environmentally conscious recreational segments. Target desert climate wave park operators in UAE and Saudi Arabia with heat-engineered constructions as the most penetrable geography. Pursue direct-to-venue supply contracts as the primary go-to-market angle, bypassing established specialty shop intermediation.
For Investors and Strategic Acquirers: Consolidation pressure builds where master shaper talent scarcity constrains custom volume scaling among fragmented heritage labels. Long-term viability favors sustainability-positioned innovators with proven bio-resin formulations and artificial venue procurement relationships. Monitor wave pool operator capital expenditure announcements as the key inflection signal for equipment procurement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Resin Formulation Partnership | Secures California Proposition 65 compliance for polyurethane-dependent heritage brands. |
| Direct-to-Venue Supply Contract | Locks artificial wave operator procurement volume bypassing specialty retail intermediation. |
| Master Shaper Apprenticeship Program | Addresses talent scarcity constraining custom shortboard production scaling. |
| Desert Climate Engineering Certification | Captures UAE and Saudi Arabia wave park procurement with heat-resistant constructions. |
| ISO 4892 Weathering Certification Investment | Enables warranty differentiation across multi-climate distribution channels. |
Research Approach
Direct dialogue with surfboard manufacturers, wave pool operators, specialty shop owners, and chemical suppliers grounds the analysis in operational reality. Primary interviews triangulate with secondary validation from customs trade data, EPA emission filings, ECHA chemical registrations, and coastal municipality infrastructure budgets. Bottom-up segmentation modeling and top-down market sizing converge across the analysis window.
Segmentation outputs reflect product type, material construction, rider skill tier, and distribution channel dimensions modeled throughout the projection horizon. CAGRs derive from volume trajectory analysis incorporating artificial venue buildout schedules, regulatory compliance cost absorption, and recreational participation rate assumptions. Forecast inputs incorporate wave pool operator capital deployment patterns and bio-resin adoption curves.
Revisions become necessary when wave pool operator capital expenditure cycles shift, regional chemical restrictions tighten beyond modeled scenarios, or master shaper talent scarcity accelerates beyond replacement rates. Practitioners should monitor artificial venue construction permits, ECHA bio-resin registration timelines, and coastal municipality tourism infrastructure allocations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
North America Kickboxing Equipment Market
Sports Equipment
Dirt Bike Market
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
GCC Running Gear Market
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
Rally Sport Riding Gear Market
Sports Equipment
France Artificial Turf Market
Sports Equipment
Sports Flooring Market
Sports Equipment
Europe Stand-Up Paddleboard Market
Sports Equipment
Tennis Ball Machine Market
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
Portable Basketball Hoops Market
Sports Equipment
Ice Hockey Equipment Market
Sports Equipment
Boxing Gear Market
Sports Equipment
Trampoline Market
Sports Equipment
Middle East and Africa Stand-Up Paddleboard Market