
 Synchrophasors Market | 2026-2036
Synchrophasors Market Size, Share, and Industry Trends Forecast 2026-2036
Synchrophasors Market Intelligence
Modular phasor measurement unit packaging is restructuring buyer choice across transmission utilities and grid operators. Siemens Energy leverages its hardware-software bundling strategy to capture integrated wide-area monitoring contracts, while Schweitzer Engineering Laboratories sustains dominance in North American relay-PMU convergence through specialized protection engineering. NR Electric competes aggressively on manufacturing scale in Asia, offering standardized chassis configurations that reduce deployment lead times for state grid corporations.
Synchrophasors are precision time-synchronized devices that sample voltage and current waveforms at rates exceeding 30 samples per second, timestamped via GPS to enable phase-angle comparison across geographically dispersed points on the power grid. Their primary commercial purpose is real-time visibility into grid stability conditions that conventional SCADA systems cannot resolve due to sub-second blind spots. Phasor measurement unit hardware commands the dominant margin pool given calibration-intensive manufacturing and metrology certification requirements, while software segments for analytics and visualization represent the fastest-expanding revenue line as utilities shift toward cloud-hosted asset management platforms. Grid monitoring applications absorb the bulk of deployed units, though frequency control implementations are gaining traction in markets with high inverter-based resource penetration.
IEEE C37.118 and IEC 61850 standards govern PMU interoperability and substation communication protocols, directly shaping product development roadmaps and procurement specifications for equipment vendors seeking utility qualification. NERC reliability standards in the United States and the EU Cybersecurity Act in Europe impose mandatory performance and data security requirements that filter market access to certified suppliers. Stakeholders must monitor evolving synchronization requirements for distributed energy resource integration and assess whether their analytics architectures can accommodate the tenfold data volume growth expected from next-generation sampling rates.
Market Dynamics
The synchrophasors market is being structurally reshaped by the mandatory integration of phasor measurement units into transmission reliability compliance frameworks, with grid operators facing binding performance thresholds that legacy SCADA architectures cannot satisfy.
Growth Catalysts
- NERC CIP reliability mandates:North American transmission operators must deploy time-synchronized monitoring to meet disturbance monitoring and data recording requirements, creating procurement pull for certified PMU hardware.
- Inverter-based resource penetration:Wind and solar farms in Germany and China require sub-second stability visibility that conventional measurement intervals miss, forcing grid modernization budgets toward synchrophasor infrastructure.
- IEC 61850 protocol adoption:European utilities are standardizing substation communication architectures around this framework, eliminating interoperability friction that previously slowed multi-vendor PMU deployment.
Market Restraints
- GPS dependency vulnerability:Phasor measurement units require continuous satellite synchronization; jamming or spoofing risks in contested electromagnetic environments create operational uncertainty for critical infrastructure operators.
- Metrology-grade manufacturing concentration:Calibration laboratories capable of IEEE C37.118 certification are concentrated in Germany, the United States, and Japan, creating qualification bottlenecks for new market entrants.
- Copper and rare-earth magnet cost volatility:PMU current transformers and GPS receiver components face input price swings that compress hardware margins and complicate long-term utility budgeting.
Strategic Opportunities
- India transmission digitization:The country's central electricity regulator is mandating wide-area monitoring for regional load dispatch centers, opening deployment pathways for PMU vendors with localized manufacturing partnerships.
- Cloud-hosted analytics convergence:Synchrophasor data streams are integrating with utility digital twins, enabling subscription-based stability monitoring services that shift revenue from capital hardware to recurring software.
- Distributed energy resource synchronization standards:Emerging IEEE 1547 requirements for inverter-based resources create demand for distribution-level phasor measurement at voltage classes below traditional transmission PMUs.
Industry Challenges
- Substation cybersecurity hardening:PMU networks expand the attack surface for critical infrastructure; operators must implement IEC 62351 encryption and access controls that add deployment complexity and commissioning timeline risk.
- Phasor data concentrator integration:Legacy energy management systems require middleware adaptation to ingest 30-60 sample-per-second streams, stretching utility IT resources and vendor support capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synchrophasors Market |
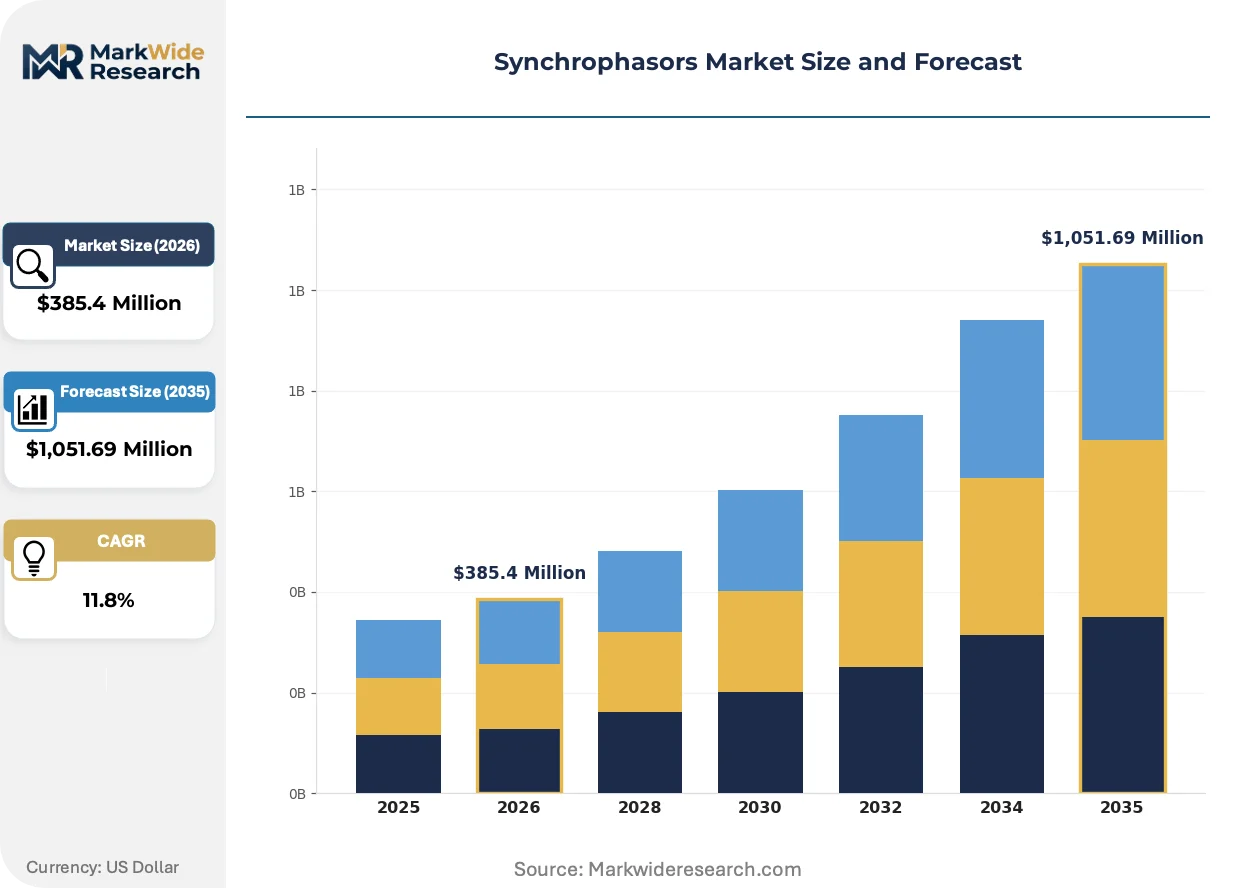
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,051.69 Million |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phasor Measurement Unit, Network Communication, Data Processing Unit, Software End User: Utilities, Grid Operators, Research Institutions, Industry Players Technology: Wide Area Measurement, Digital Signal Processing, Cloud Computing, IoT Application: Grid Monitoring, Frequency Control, Fault Detection, Load Balancing |
| Companies Covered | General Electric Company, Schneider Electric, Schweitzer Engineering Laboratories, NR Electric, Arbiter Systems, ABB, Toshiba Corporation, Vizimax, Siemens Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synchrophasors Market Strategic Shifts & Innovations
Hardware-software decoupling is restructuring how grid operators procure stability monitoring capability, with functional specialization replacing bundled system sales and analytics layers migrating toward utility cloud environments.
Micro-PMU form factors are modularizing across distribution network applications, enabling voltage angle measurement at medium-voltage feeders previously uneconomical for full-scale phasor measurement units. California and Australian distribution utilities are piloting these compact devices for inverter-dominated circuit monitoring. The technology is modularizing procurement decisions, allowing operators to deploy targeted measurement nodes without full substation reconstruction.
EU Cybersecurity Act certification requirements are forcing PMU vendors to re-architect firmware and communication stacks for formal security evaluation, adding 12-18 month qualification timelines that filter supplier pools. German TSOs and Nordic transmission operators now mandate certified components for new wide-area monitoring investments. European vendors with established notified body relationships are capturing disproportionate share of public procurement frameworks.
Subscription-based stability analytics are displacing perpetual license models as US municipal utilities and cooperative grids seek operational expenditure treatment for monitoring capabilities. Software vendors are unbundling visualization and event analysis from hardware sales, creating recurring revenue streams that alter vendor-customer relationships. This pattern is most visible among mid-sized North American utilities with constrained capital budgets and outsourced IT functions.
Synchrophasors Market Segmentation
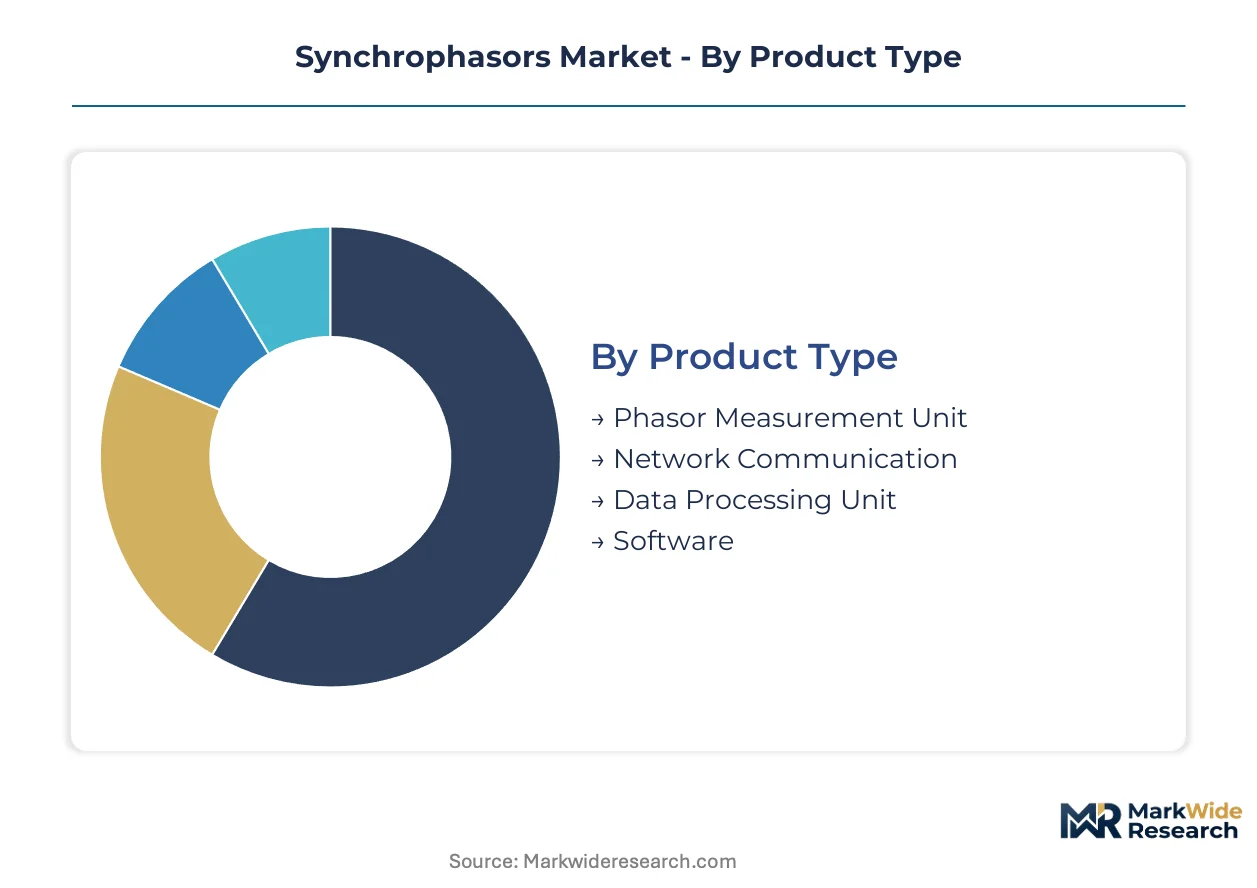
Synchrophasor procurement patterns diverge sharply across hardware, software, and service layers, with each segment commanding distinct margin structures and qualification barriers. Understanding these divisions reveals where vendor consolidation concentrates and where new entrants can still penetrate.
Product Type:
Manufacturing capability for metrology-grade hardware clusters in Germany, the United States, and Japan, creating tiered access based on calibration laboratory proximity.
- Phasor Measurement Unit:These precision sampling devices require GPS-synchronized timestamping and IEEE C37.118 certification. Demand concentrates among transmission utilities in the United States and China where NERC mandates and state grid modernization programs fund large-scale deployment. Calibration-intensive production limits qualified suppliers.
- Software:Analytics and visualization platforms are migrating toward cloud-hosted delivery models. North American municipal utilities with constrained capital budgets drive subscription revenue growth as they shift from perpetual licenses to operational expenditure treatment.
- Network Communication:Protocol gateways and secure data links enable PMU-to-control-center connectivity. European TSOs specify IEC 61850 compliance, filtering vendor pools to those with certified protocol stacks.
- Data Processing Unit:Edge computing hardware for substation-local phasor aggregation. Chinese state grid corporations deploy standardized chassis configurations to reduce commissioning timelines.
Today's leader: Phasor Measurement Unit. Tomorrow's challenger: Software.
End User:
Capital allocation authority determines purchasing behavior, with regulated utilities following multi-year procurement cycles while research institutions drive experimental specifications.
- Utilities:Investor-owned and public power entities command the dominant procurement volume. United States transmission owners face binding NERC CIP reliability thresholds that mandate PMU deployment for disturbance monitoring compliance.
- Grid Operators:Regional transmission organizations and independent system operators purchase wide-area monitoring systems. German TSOs and Nordic operators now require EU Cybersecurity Act certification for new investments.
- Research Institutions:Universities and national laboratories pilot next-generation sampling rates and distributed energy resource synchronization. These buyers influence standards development but represent limited commercial volume.
- Industry Players:Large industrial facilities with captive generation deploy PMUs for power quality monitoring. This segment trails utility-scale deployment but grows with inverter-based onsite solar expansion.
Grid Operators absorb the highest per-site expenditure. Utilities deliver the deepest volume pipeline.
Technology:
Functional specialization is displacing bundled system sales, with analytics layers decoupling from hardware and migrating toward utility cloud environments.
- Wide Area Measurement:The foundational synchrophasor capability enabling phase-angle comparison across geographically dispersed grid nodes. This technology anchors transmission-level stability monitoring in North America and Europe.
- Digital Signal Processing:Algorithms extracting phasor estimates from high-sample-rate waveform captures. Advances here determine measurement accuracy and response latency for frequency control applications.
- Cloud Computing:Utility digital twins and hosted analytics platforms integrate synchrophasor streams. Subscription models for stability monitoring services are gaining traction among mid-sized North American cooperatives.
- IoT:Sensor networking for distribution-level micro-PMU deployment. California and Australian utilities pilot these compact devices for inverter-dominated circuit monitoring.
Wide Area Measurement holds installed base dominance. Cloud Computing is climbing the fastest.
Application:
Grid stability challenges vary by generation mix, with high renewable penetration markets demanding sub-second visibility that conventional SCADA cannot provide.
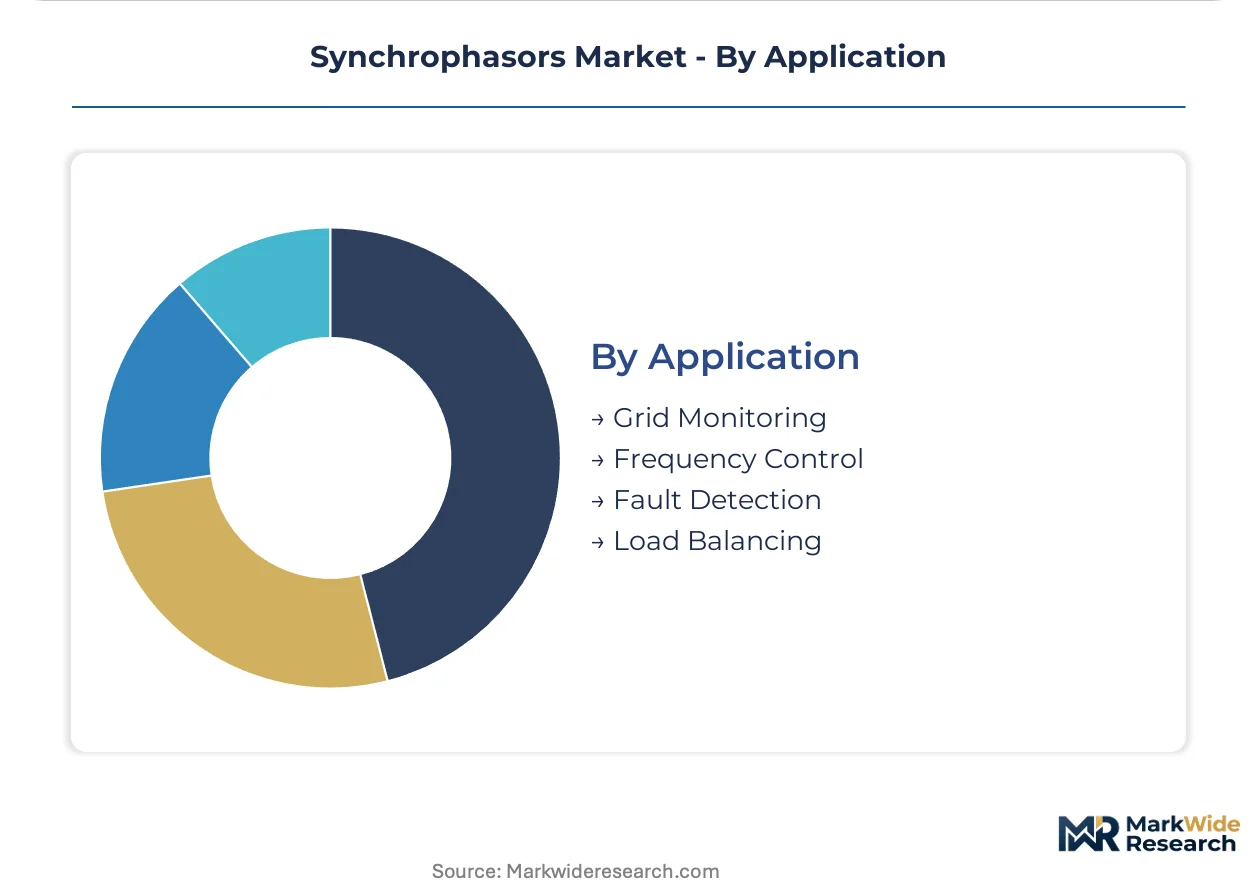
- Grid Monitoring:Real-time stability visibility across transmission corridors. This application absorbs the bulk of deployed units, particularly in China and Germany where variable renewable integration strains conventional measurement intervals.
- Frequency Control:Sub-second response to generation-load imbalances. Wind and solar penetration in Germany and western United States drives implementation as inverter-based resources displace synchronous inertia.
- Fault Detection:Rapid identification and location of transmission disturbances. Indian regional load dispatch centers are mandating wide-area monitoring for this purpose.
- Load Balancing:Dynamic redistribution of power flows to relieve congestion. This application grows with market-based dispatch mechanisms and cross-border trading.
Grid Monitoring commands current deployment share. Frequency Control shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synchrophasor technology achieved commercial scale in the United States following the 2003 Northeast blackout, which exposed critical blind spots in conventional grid monitoring. This historical foundation established North America as the proving ground for wide-area measurement systems before deployment patterns diversified across Europe and Asia-Pacific.
United States
FERC Order 693 and subsequent NERC CIP reliability mandates compel transmission owners to deploy time-synchronized disturbance monitoring across interconnection boundaries. The PJM and ERCOT regional transmission organizations anchor procurement volume, with Texas utilities accelerating PMU installation to manage wind generation volatility across the Panhandle and West Texas renewable zones.
Germany
Grid operators TenneT and 50Hertz face binding stability requirements under the EU Cybersecurity Act as inverter-based resources displace synchronous generation. The country's calibration laboratory concentration in Munich and Berlin supports metrology-grade manufacturing, while northern transmission corridors connecting offshore wind farms drive specialized phasor measurement deployment.
China
State Grid Corporation and China Southern Power Grid mandate wide-area monitoring for regional load dispatch centers under CEA technical guidelines. The Yangtze River Delta cluster surrounding Shanghai concentrates manufacturing capacity for standardized chassis configurations, reducing deployment lead times for ultra-high voltage transmission projects.
India
The Central Electricity Regulatory Commission mandates phasor measurement units for five regional load dispatch centers to enable sub-second fault detection across the national grid. Maharashtra and Gujarat host pilot programs for distribution-level monitoring, with Mumbai's islanded grid requiring specialized synchronization protocols.
Japan
METI grid modernization funding targets frequency control applications as renewable penetration rises in Hokkaido and Kyushu. The Chubu region around Nagoya maintains precision manufacturing capabilities for GPS receiver components, supporting domestic PMU assembly while Tokyo utilities pilot cloud-hosted analytics integration.
Synchrophasors Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification intensity and software bundling depth. The market structures around three tiers: integrated energy conglomerates with hardware-software convergence strategies, specialized protection engineering firms with relay-PMU hybrid expertise, and scale-focused manufacturers competing on deployment velocity. Consolidation pressures favor entities with in-house calibration laboratories and notified body relationships. Dominant competitive moves include strategic partnerships for cloud analytics integration and geographic expansion through localized manufacturing joint ventures.
Within the integrated systems tier, Siemens Energy and General Electric occupy positions exemplifying bundled wide-area monitoring contract capture. Schweitzer Engineering Laboratories anchors the specialized protection engineering segment, representing North American dominance in relay-converged architectures. NR Electric exemplifies the scale-driven manufacturing archetype, with standardized configurations serving state grid procurement frameworks across Asia.
| Leading Market Players |
|---|
| General Electric Company |
| Schneider Electric |
| Schweitzer Engineering Laboratories |
| NR Electric |
| Arbiter Systems |
| ABB |
| Toshiba Corporation |
| Vizimax |
| Siemens Energy |
| Others |
Cost & Logistics Intelligence
Copper price volatility on the London Metal Exchange cascades through synchrophasor manufacturing into three distinct hardware tiers. Raw material swings compress margins for current transformer assemblies while calibration-intensive metrology certification preserves premium pricing for IEEE C37.118-qualified units.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement. Certification grade and volume scale drive price differentiation, with NERC-mandated transmission utilities absorbing premium tiers while municipal cooperatives gravitate toward subscription-based software offerings. Cost compression in economy hardware is intensifying because Chinese state grid procurement favors standardized chassis configurations. Municipal utilities with constrained capital budgets exhibit highest price sensitivity; German TSOs under EU Cybersecurity Act mandates show lowest.
Supply Chain Analysis
India's phased domestic-content mandates for transmission infrastructure are reshaping sourcing patterns for PMU assembly. Manufacturing concentrates in Germany, the United States, and Japan where calibration laboratories anchor metrology-grade production. The supply chain draws from copper for current transformers, rare-earth magnets for GPS receivers, and precision timing oscillators. Single-source vulnerability concentrates in German calibration certification. Distribution runs through utility procurement frameworks and EPC contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The synchrophasors market functions as a regulatory compounder where NERC CIP reliability mandates in the United States generate recurring procurement cycles that outpace organic grid investment growth.
For Market Incumbents: Extend calibration laboratory capacity into India and Southeast Asia before localized certification requirements harden. Lock in multi-year wide-area monitoring contracts with German TSOs facing EU Cybersecurity Act deadlines. Vertical integration into GPS receiver assembly mitigates rare-earth magnet cost volatility threatening hardware margins. For New Entrants and Emerging Players: CEA technical guidelines in India open a window for distribution-level micro-PMU deployment where incumbent presence remains thin. Target fault detection applications at regional load dispatch centers with cloud-hosted analytics partnerships. Pursue joint ventures with state grid corporations for manufacturing localization rather than direct hardware competition. For Investors and Strategic Acquirers: Asymmetric upside sits with software vendors unbundling visualization from hardware sales. Five-to-ten-year viability favors entities with recurring revenue streams from utility digital twin integration. Acquisition focus: analytics platforms with live utility deployments. Watch for IEEE 1547 distributed energy resource synchronization standards as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Expansion | NERC CIP mandates in the United States require IEEE C37.118 certification capacity that concentrates supplier pools. |
| Cloud Analytics Platform Launch | Subscription revenue models shift municipal utility budgets from capital expenditure to operational treatment. |
| Micro-PMU Distribution Partnership | California and Australian utilities pilot compact devices for inverter-dominated circuit monitoring applications. |
| EU Cybersecurity Act Certification | German TSOs and Nordic operators now mandate certified components for public procurement frameworks. |
| Localized Manufacturing Joint Venture | Indian state grid procurement favors domestic assembly partnerships under central electricity regulatory pressure. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged utility planning officers at regional transmission organizations, protection engineering leads at investor-owned utilities, grid operators at independent system operators, and procurement managers at state grid corporations. Secondary validation drew from FERC filings, NERC reliability standard documentation, IEC technical committee publications, and utility capital expenditure disclosures. Bottom-up deployment tracking and top-down regulatory mandate analysis were triangulated against manufacturer production data.
Segment-weighting approaches modeled hardware, software, and service layers across product type, end user, technology, and application dimensions. CAGRs were derived from installation base expansion rates correlated with regulatory compliance deadlines. Forecast inputs included NERC CIP implementation timelines, EU Cybersecurity Act certification requirements, and renewable penetration curves affecting frequency control demand across the projection horizon.
Revisions become necessary when regulatory enforcement intensity shifts, GPS synchronization vulnerability triggers alternative timing technology adoption, or distributed energy resource standards accelerate distribution-level deployment. Forecasts reflect documented assumptions about calibration laboratory capacity expansion and utility IT resource availability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Asia-Pacific DC Distribution Networks Market
Power Systems
Flyback Transformer Market
Power Systems
US Variable Frequency Drive Market
Power Systems
North America Micro Inverter Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
Automotive Inverters Market
Power Systems
Switch Mode Power Supply (SMPS) Market
Power Systems
Electric Vehicle Inverter Market
Power Systems
Power Integrated Modules Market
Power Systems
Shunt Voltage References Market
Power Systems
Module-Level Power Electronics (MLPE) Market
Power Systems
Low Voltage DC Circuit Breaker Market
Power Systems
Asia-Pacific Electric Vehicle Power Inverter Market
Power Systems
Thyristor Market
Power Systems
Global Excitation Systems Market
Power Systems
Battery Voltage Supervisor Market