
 Battery Balancer Market | 2026-2036
Battery Balancer Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Balancer Market Insights
Project finance for battery gigafactories is rewriting competitive access to the battery balancer value chain. Texas Instruments leverages its analog semiconductor heritage to dominate integrated balancer IC supply for automotive-grade BMS platforms. Analog Devices anchors high-precision measurement channels within multi-cell monitoring architectures. Infineon Technologies competes through SiC-integrated gate drivers that pair with active balancing topologies in European EV programs.
A battery balancer is an electronic subsystem that redistributes charge among series-connected cells to maintain voltage uniformity within ±10-50 mV tolerance bands, typically employing switched-capacitor networks or inductive DC/DC converters to prevent premature capacity fade in lithium-ion packs. Active balancers using DC/DC conversion technology command the highest engineering margins due to their energy recovery efficiency and thermal advantages over resistive bleeding approaches. Passive balancer demand persists in cost-constrained consumer electronics where resistive dissipation remains acceptable, while hybrid architectures are gaining traction in renewable energy storage installations requiring both maintenance-free operation and capital expenditure discipline.
The US NHTSA and EPA coordinate battery safety and lifecycle emissions rules that mandate cell-level monitoring in electrified vehicle platforms, pushing OEMs toward certified balancer modules. Europe's ECHA REACH restrictions and CE marking requirements for battery systems constrain material choices in balancer PCB assemblies and connector chemistries. China's NMPA and MIIT enforce GB/T standards for traction battery consistency that directly specify balancing response times and fault thresholds. Stakeholders must monitor how regulatory divergence in test protocols between these jurisdictions reshapes qualification timelines and platform engineering costs.
Market Dynamics
Active balancing topologies are compressing development cycles as automakers demand cell-level voltage uniformity tolerances tighter than ±20 mV across 800V architectures, forcing suppliers to abandon passive resistor networks in favor of inductive DC/DC recovery systems.
Growth Catalysts
- China's GB/T traction battery standards:NMPA and MIIT enforcement of cell consistency mandates specifies balancing response thresholds, compelling domestic EV manufacturers to upgrade from passive to active architectures.
- Stationary energy storage deployment:Utility-scale lithium-ion installations in solar-plus-storage configurations require maintenance-free hybrid balancers that combine switched-capacitor speed with inductive efficiency.
- German automotive cluster concentration:OEMs and tier-one suppliers co-locating BMS development with cell production in Stuttgart and Munich corridors accelerates specification tightening for automotive-grade balancers.
Market Restraints
- Inductor ferrite core supply concentration:Japanese and Taiwanese ferrite suppliers control high-frequency magnetic material output, exposing active balancer manufacturers to input cost volatility and allocation constraints.
- Silicon carbide MOSFET qualification timelines:Infineon and STMicroelectronics SiC device certification for automotive AEC-Q100 stretches 18-24 months, gating active balancer module release schedules.
- Passive balancer substitution persistence:Cost-constrained consumer electronics and two-wheeler EV segments in Southeast Asia continue specifying resistive bleeding circuits below dollar-per-cell price floors.
Strategic Opportunities
- India PLI scheme for advanced chemistry cell manufacturing:Production-linked incentives for domestic gigafactories create first-mover advantage for balancer suppliers establishing local PCB assembly and test capacity.
- Solid-state battery interface convergence:Lithium-metal anode architectures with ceramic electrolytes require redesigned balancing algorithms and voltage sensing ranges, opening IP licensing positions.
- Second-life battery repurposing channels:Retired automotive packs entering stationary storage applications demand retrofit balancer modules with wider voltage operating windows and degraded-cell compatibility.
Industry Challenges
- Embedded firmware talent scarcity:BMS algorithm development requires combined power electronics and battery electrochemistry expertise concentrated in Munich, Detroit, and Shenzhen hiring markets.
- Multi-jurisdiction certification parallelism:Simultaneous NHTSA FMVSS, ECE R100, and GB/T qualification testing extends platform engineering timelines and duplicates validation expenditure.
- Legacy 400V system integration friction:800V-native active balancers require voltage isolation redesigns when retrofitted to first-generation EV architectures with 96-series cell configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Balancer Market |
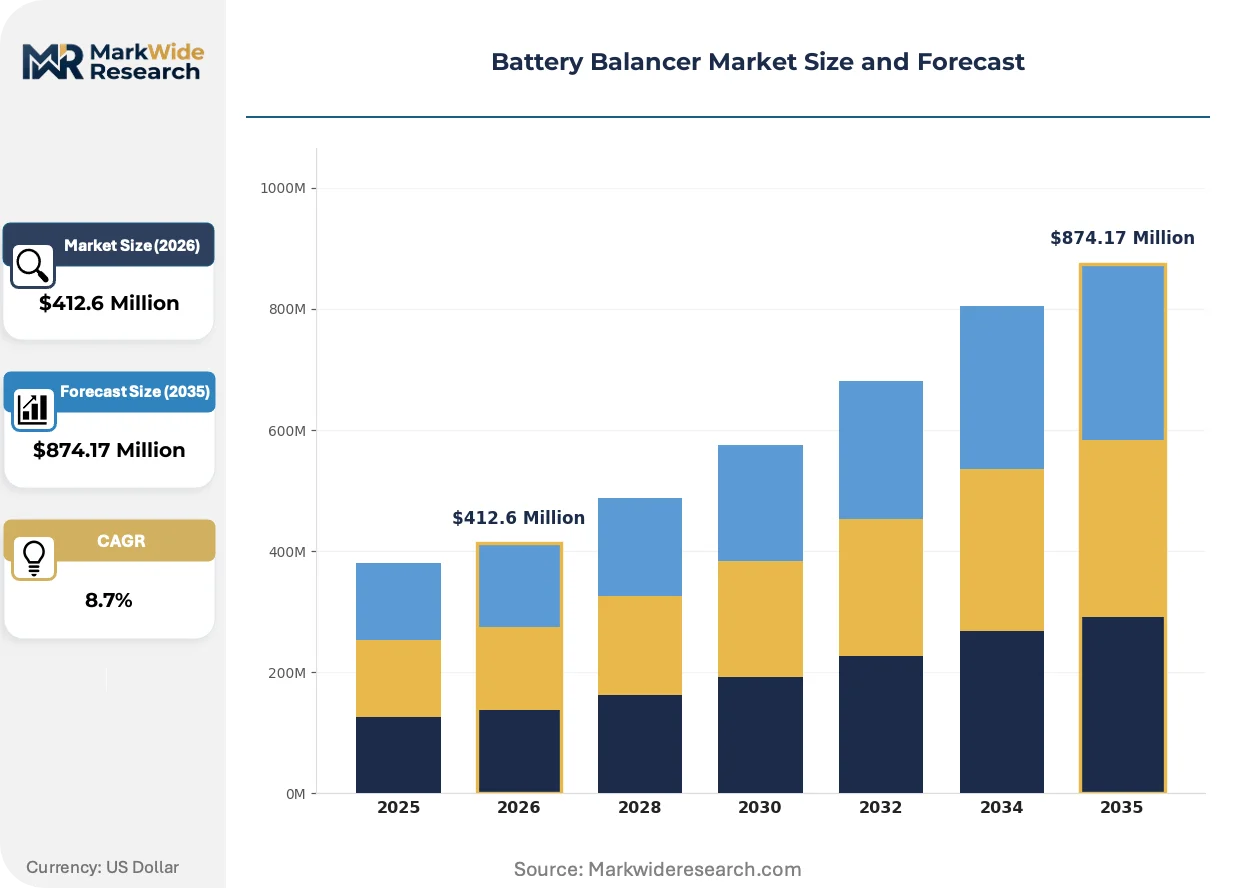
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Balancers, Passive Balancers, Hybrid Balancers, Smart Balancers Technology: DC/DC Conversion, Capacitive Coupling, Energy Harvesting, Wireless Communication Application: Electric Vehicles, Renewable Energy Storage, Uninterruptible Power Supply, Consumer Electronics End User: Automotive Manufacturers, Energy Companies, Electronics Manufacturers, Research Institutions |
| Companies Covered | Texas Instruments, Analog Devices, NXP Semiconductors, Infineon Technologies, Renesas Electronics, Lithium Balance, Eberspächer, Sensata Technologies, Balancer Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Balancer Market Trends and Innovations
Transformer-coupled active balancing is compressing thermal budgets and enabling energy recovery efficiencies above 90%, while regulatory divergence across automotive safety frameworks fragments qualification protocols.
Transformer-coupled resonant converters with integrated magnetics are rendering obsolete discrete inductor-based flyback architectures in high-voltage EV applications. Premium European OEMs specify these modules for 800V platforms launching 2025-2027. The technology is rendering obsolete mid-tier suppliers dependent on through-hole magnetic component supply chains.
REACH restrictions on halogenated flame retardants in PCB assemblies constrain material choices for balancer control boards sold into European markets. ECHA substance of very high concern listings for specific brominated compounds force laminate substrate substitutions and requalification testing. German tier-one suppliers are responding by consolidating PCB sourcing to vendors with pre-certified halogen-free material libraries.
Cell manufacturers are consolidating balancer procurement under long-term framework agreements rather than spot purchasing, compressing supplier margins and favoring analog semiconductor houses with captive foundry capacity. Direct OEM-balancer IC relationships are displacing traditional module vendor intermediaries in North American EV programs. This concentration is most visible in Detroit-area purchasing offices where Ford and GM have established dedicated power electronics commodity management functions.
Battery Balancer Market Segmentation
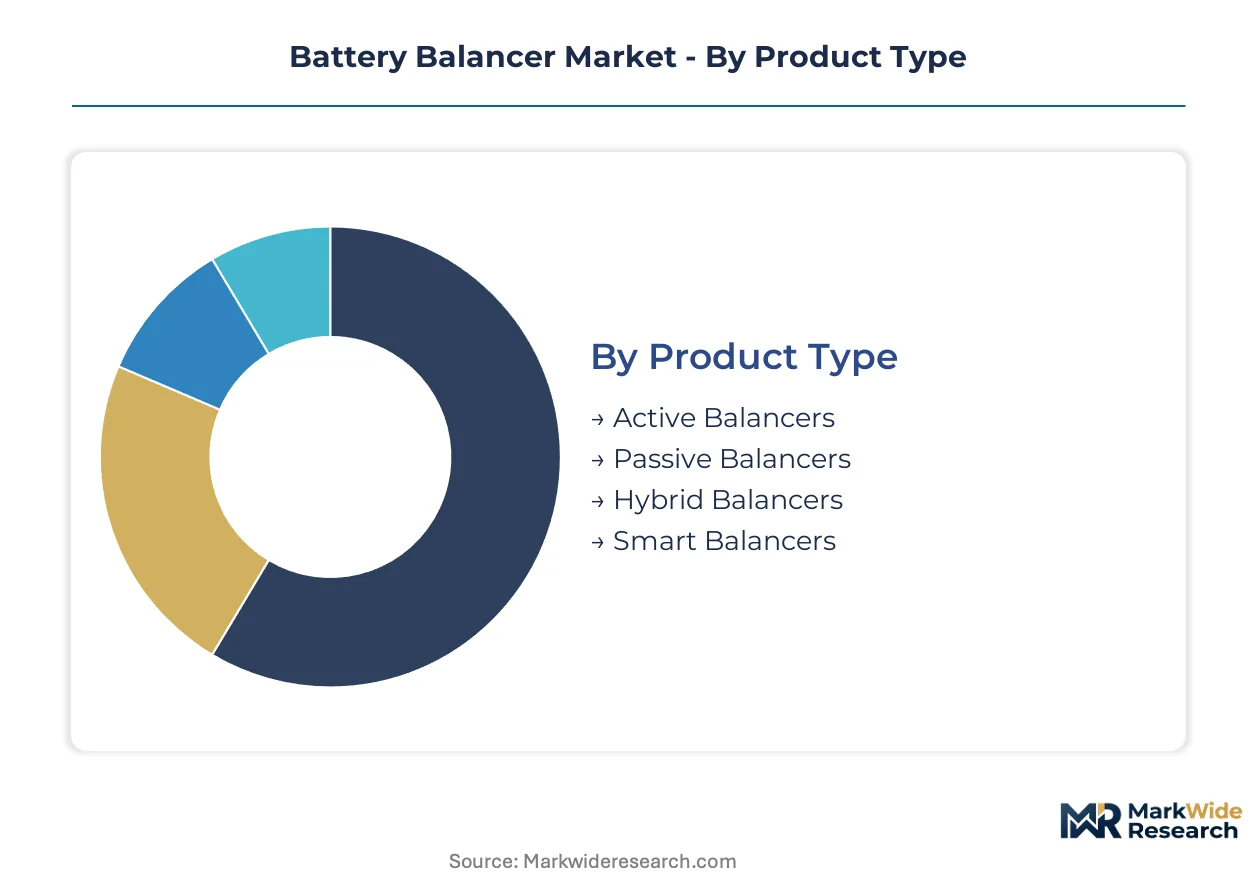
Balancing architectures diverge sharply across voltage classes and duty cycles, with automotive-grade specifications imposing tolerances an order of magnitude tighter than consumer applications. Procurement patterns cluster around cell chemistry, pack configuration, and regulatory jurisdiction rather than generic price tiers.
Product Type:
Cost tier separates maintenance-intensive bleeding circuits from energy-recovery systems commanding engineering premiums in high-voltage traction applications.
- Active Balancers:Inductive DC/DC converters or switched-capacitor networks transfer charge between cells rather than dissipating it as heat. Demand concentrates in Germany where 800V EV platforms from Stuttgart and Munich automakers specify ±20 mV uniformity tolerances across series strings.
- Passive Balancers:Resistor bleeding circuits shunt excess charge from high-voltage cells during charge termination. Southeast Asian two-wheeler EV manufacturers and cost-constrained consumer electronics OEMs specify these below dollar-per-cell price floors where thermal dissipation remains acceptable.
- Hybrid Balancers:Architectures combine switched-capacitor speed with inductive efficiency for utility-scale solar-plus-storage installations requiring capital discipline alongside maintenance-free operation.
- Smart Balancers:Firmware-enabled modules integrate predictive algorithms and wireless telemetry for second-life battery repurposing channels demanding wider voltage windows.
Passive balancers command the established base. The steepest expansion runs through active architectures.
Technology:
Application thermal budgets and energy recovery targets determine topology selection across voltage isolation requirements.
- DC/DC Conversion:Flyback, buck-boost, and resonant converter topologies achieve recovery efficiencies above 90% in transformer-coupled configurations. European premium OEMs specify these for 800V platforms launching through 2027.
- Capacitive Coupling:Switched-capacitor networks eliminate magnetic components for reduced EMI and faster balancing response in compact consumer electronics packs.
- Energy Harvesting:Photovoltaic or thermal gradient harvesting extends balancer autonomy in remote renewable storage installations lacking auxiliary power.
- Wireless Communication:RF or inductive coupling eliminates galvanic isolation components in modular pack architectures requiring cell-level telemetry without wiring harnesses.
Capacitive coupling retains volume leadership in consumer segments. DC/DC conversion climbs the fastest in automotive traction.
Application:
Customer duty cycles and safety certification requirements fragment specifications across mobility, grid, and portable power domains.
- Electric Vehicles:Traction battery packs with 400V and 800V architectures mandate active balancing for cycle life extension under NHTSA FMVSS and ECE R100 thermal runaway containment rules.
- Renewable Energy Storage:Utility-scale lithium-ion installations in solar-plus-storage configurations specify hybrid balancers combining maintenance-free operation with decade-scale service life.
- Uninterruptible Power Supply:Lead-acid and lithium-ion backup systems in data centers and telecommunications specify passive or smart balancers for float-charge voltage uniformity.
- Consumer Electronics:Smartphone, laptop, and power tool packs prioritize compact switched-capacitor solutions where resistive dissipation and charging frequency permit simplified architectures.
Consumer electronics anchors unit volume. Renewable energy storage exhibits the steepest value expansion trajectory.
End User:
Procurement concentration and technical specification authority determine channel structure and margin capture.
- Automotive Manufacturers:Detroit-area OEMs have established dedicated power electronics commodity management functions, displacing traditional module vendor intermediaries with direct IC supplier relationships.
- Energy Companies:Utility and independent power producer procurement frameworks favor long-term service agreements with predictive maintenance integration.
- Electronics Manufacturers:Contract assemblers and brand OEMs specify balancers at board level, prioritizing BOM cost minimization over energy recovery efficiency.
- Research Institutions:National laboratories and university programs drive next-cell chemistry validation, including solid-state lithium-metal architectures requiring redesigned sensing ranges.
Electronics manufacturers dominate unit shipments. Automotive OEMs capture the fastest value growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and GB/T battery safety standards are tightening cell-level voltage uniformity requirements, while German automakers co-locate BMS development with cell production to accelerate specification cycles. These policy and industrial clustering dynamics are reshaping regional procurement patterns for active balancing systems.
China
Domestic EV manufacturers are expanding procurement of active balancing systems to extend lithium-ion pack cycle life under NMPA and MIIT enforcement of GB/T traction battery consistency standards. The country's dual carbon goals mandate tighter cell-level voltage uniformity thresholds, compelling upgrades from passive resistor networks. Yangtze River Delta battery gigafactories in Jiangsu and Zhejiang provinces concentrate balancer module assembly capacity to serve CATL and BYD supply chains.
Germany
Automakers and tier-one suppliers co-locate BMS development with cell production in Stuttgart and Munich corridors, accelerating specification tightening for automotive-grade balancers. ECHA REACH restrictions on halogenated flame retardants in PCB assemblies constrain material choices for balancer control boards sold into European markets. Baden-Württemberg's premium OEM engineering centers specify transformer-coupled active balancing modules for 800V platforms launching through 2027.
United States
Detroit-area OEMs have established dedicated power electronics commodity management functions, displacing traditional module vendor intermediaries with direct IC supplier relationships. NHTSA and EPA coordination of battery safety and lifecycle emissions rules mandates cell-level monitoring in electrified vehicle platforms. Michigan and Ohio battery cell manufacturing investments by Ford and GM are pulling balancer procurement decisions into regional purchasing offices.
India
Production-linked incentives for domestic gigafactories under the PLI scheme for advanced chemistry cell manufacturing create first-mover advantage for balancer suppliers establishing local PCB assembly capacity. Central Electricity Authority grid codes for utility-scale storage are specifying maintenance-free hybrid balancer architectures. Tamil Nadu and Gujarat's emerging battery manufacturing clusters are attracting component suppliers to co-locate test and validation facilities.
Japan
Japanese and Taiwanese ferrite suppliers control high-frequency magnetic material output for inductor cores, exposing active balancer manufacturers to input cost volatility and allocation constraints. METI battery safety guidelines for stationary energy storage are driving demand for decade-scale service life specifications. Osaka-based magnetic component specialists supply transformer-coupled resonant converter architectures to European premium OEM programs.
Battery Balancer Market Competitive Landscape
On the supply side, the industry is consolidating around analog semiconductor houses with captive foundry capacity and automotive-grade certification heritage. Discrete magnetic component vendors and firmware specialists occupy mid-tier positions, while contract assemblers compete on BOM cost minimization for consumer electronics. Three archetypes dominate: integrated circuit suppliers with BMS platform integration, magnetic component specialists with high-frequency ferrite expertise, and module vendors with multi-jurisdiction certification capabilities. Competitive moves center on direct OEM relationships displacing intermediaries, and long-term framework agreements compressing spot purchasing margins.
Within the integrated circuit supplier archetype, Texas Instruments leverages its analog semiconductor heritage, Analog Devices anchors high-precision measurement channels, and Infineon Technologies competes through SiC-integrated gate drivers. These three companies exemplify the shift toward direct automotive OEM relationships and away from traditional module vendor channels. Each occupies a distinct position: Texas Instruments represents the broad analog platform play, Analog Devices exemplifies precision signal chain specialization, and Infineon Technologies anchors the power semiconductor integration vector. Their collective presence concentrates engineering specification authority in semiconductor houses rather than downstream module assemblers.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| NXP Semiconductors |
| Infineon Technologies |
| Renesas Electronics |
| Lithium Balance |
| Eberspächer |
| Sensata Technologies |
| Balancer Tech |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Yangtze River Delta PCB assembly plants is compressing module vendor margins while amplifying pricing power for analog semiconductor houses with captive foundry capacity. This utilization asymmetry drives tier-one suppliers toward direct IC procurement and forces mid-tier assemblers into cost-pass-through contracts with diminishing margin retention.
Pricing Analysis
Certification level creates the primary spread between automotive-grade AEC-Q100 qualified modules and consumer electronics variants. Three-tier pricing structure across premium active balancing, standard hybrid architectures, and economy passive bleeding circuits reflects this divergence. Pricing pressure stems from long-term framework agreements consolidating procurement under analog semiconductor houses with captive capacity. Consumer electronics contract assemblers exhibit highest price sensitivity, while German premium OEMs prioritize uniformity tolerance over unit cost.
Supply Chain Analysis
Foundry concentration at TSMC and GlobalFoundries anchors wafer supply for automotive-grade balancer ICs, while Foxconn and Jabil hold contract assembly capacity for module-level integration. Magnetic component sourcing draws from Japanese and Taiwanese ferrite specialists for high-frequency inductor cores. Single-source vulnerability in SiC MOSFET qualification timelines stretches 18-24 months at Infineon and STMicroelectronics. Distribution runs through direct OEM procurement offices displacing traditional module vendor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Active balancing adoption is accelerating as 800V EV platforms and China's GB/T enforcement tighten cell uniformity mandates. This regulatory-technological inflection compresses development cycles and concentrates specification authority in semiconductor houses with automotive certification heritage.
For Market Incumbents: Harden AEC-Q100 certification moats through expanded automotive-grade testing capacity in Michigan and Baden-Württemberg corridors. Deepen backward integration into high-frequency ferrite sourcing to offset Japanese supplier allocation constraints. Consolidate firmware talent in Munich and Shenzhen hiring markets to defend algorithm development positions against fabless entrants.
For New Entrants and Emerging Players: Build out local PCB assembly and test capacity in Tamil Nadu and Gujarat to capture PLI scheme first-mover advantage in India's emerging gigafactory clusters. Target second-life battery repurposing channels requiring retrofit balancers with degraded-cell compatibility. Pursue solid-state battery interface licensing positions as lithium-metal architectures redefine voltage sensing ranges.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across transformer-coupled resonant converter sub-segments as European premium OEMs specify integrated magnetics for 800V platforms. Acquisition target archetypes include magnetic component specialists with high-frequency ferrite expertise and firmware houses with combined power electronics and electrochemistry capabilities. Monitor SiC MOSFET qualification timeline compression as inflection indicator for active balancer module release schedules.
| Strategic Initiative | Industry Significance |
|---|---|
| Automotive-Grade Certification Investment | AEC-Q100 qualification accelerates direct OEM procurement relationships in Detroit and Stuttgart corridors. |
| Backward Integration into Magnetic Components | In-house ferrite core production mitigates Japanese supplier concentration and allocation volatility. |
| Geographic Manufacturing Footprint Expansion | Local assembly capacity in Tamil Nadu captures India's PLI scheme incentives for domestic gigafactories. |
| Technology Licensing for Solid-State Interfaces | IP positions in lithium-metal sensing ranges open recurring revenue streams from next-cell chemistry validation. |
| Second-Life Battery Channel Development | Retrofit balancer modules address wider voltage windows in repurposed automotive packs entering stationary storage. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with BMS platform engineers at German tier-one suppliers, power electronics procurement managers at Detroit-area OEMs, and cell manufacturing executives at Yangtze River Delta gigafactories. Secondary validation drew from NHTSA FMVSS filings, ECHA REACH substance registrations, MIIT GB/T standard publications, and SEC 10-K disclosures from analog semiconductor houses. Bottom-up cell-level demand modeling and top-down pack deployment forecasts were triangulated to reconcile volume estimates.
Calibration against historical deployment trajectories anchored growth projections across the modeling period without year-specific anchoring. Segmentation dimensions included balancing architecture, voltage class, cell chemistry, and regional regulatory cluster. CAGRs were derived from slope analysis of technology adoption curves and policy enforcement timelines. Forecast inputs incorporated SiC MOSFET qualification velocity, ferrite core allocation patterns, and firmware talent availability in concentrated hiring markets.
Sensitivities concentrate around GB/T enforcement consistency in China, REACH substance listing revisions in Europe, and NHTSA thermal runaway rulemaking in the United States. Forecasts reflect assumptions about active balancing cost parity achievement and hybrid architecture adoption in utility-scale storage. Quarterly review of automotive platform voltage migration and magnetic component lead times is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Hybrid Inverters Market
Power Systems
Distribution Voltage Regulator Market
Power Systems
Switching Regulators Power Management IC Market
Power Systems
Wireless Battery Monitoring System Market
Power Systems
Digital Inverter Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Thyristor Surge Protectors Market
Power Systems
Silicon Carbide Power Devices Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
Photovoltaic Inverters Market
Power Systems
Asia Pacific Battery Management System Market
Power Systems
Global Frequency Converter Market
Power Systems
Smart Junction Box and Power Distribution Box Systems Market
Power Systems
EV Power Module Market
Power Systems
Series Reactor Market
Power Systems
Synchrophasors Market