
 Shunt Reactor Market | 2026-2036
Shunt Reactor Market Size, Share, and Industry Trends Forecast 2026-2036
Shunt Reactor Market Analysis
Maintenance contracts and digital condition monitoring is rebalancing how shunt reactor value gets captured, shifting revenue from hardware sales toward lifecycle service agreements. Siemens Energy anchors European extra-high-voltage projects through its transformer and reactor manufacturing scale. Hitachi Energy differentiates through its power electronics integration and software-defined grid solutions. General Electric competes in North American utility upgrades with specialized oil-immersed reactor designs for aging transmission infrastructure.
A shunt reactor is an inductive device connected in parallel to power systems to absorb reactive power, maintain voltage stability, and reduce Ferranti effect in long transmission lines, typically rated from tens to hundreds of megavars with insulation classes spanning medium voltage through extra high voltage. Oil-immersed designs dominate installed base due to proven thermal performance and compact footprint for substation deployment, while dry-type units are gaining share in urban and environmentally sensitive installations where fire risk and oil containment drive specification. Transmission systems represent the largest application segment by installed value, though renewable energy integration is the fastest-growing demand pool as wind and solar farms require dynamic reactive compensation for grid code compliance.
IEC 60076-6 governs reactor performance testing and loss measurement protocols, while IEEE C57.21 shapes North American construction and thermal evaluation standards; both frameworks push manufacturers toward lower noise limits and reduced no-load losses. The EU Green Deal and associated F-Gas Regulation indirectly tighten requirements for oil-immersed units through broader decarbonization accountability in grid infrastructure procurement. Stakeholders must track how national regulators in China, India, and Germany align local grid codes with evolving IEC and IEEE amendments to anticipate certification burdens and qualification timelines.
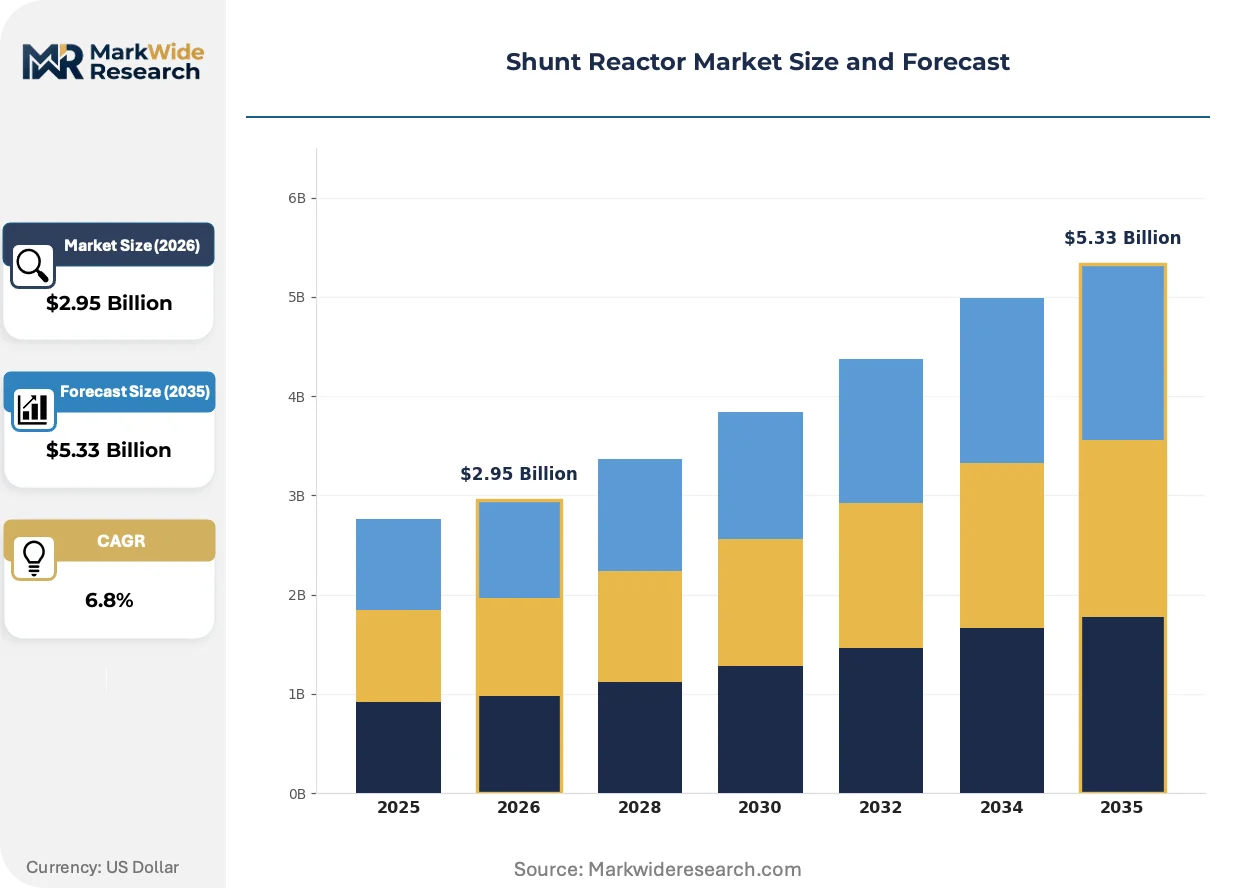
Market Dynamics
Grid operators across China, India, and Germany are mandating dynamic reactive compensation for inverter-based renewable interconnections, forcing reactor manufacturers to accelerate digital integration and service-based revenue models ahead of hardware commoditization.
Growth Catalysts
- EU Green Deal grid modernization:Transmission operators in Germany and France must upgrade extra-high-voltage corridors, creating specification pull for advanced shunt reactors with integrated monitoring.
- Inverter-based renewable penetration:Wind and solar farms in China and India require grid-code-compliant reactive power absorption, expanding addressable demand beyond traditional transmission utilities.
- F-Gas Regulation spillover effects:Oil-immersed reactor designs gain procurement preference as EU infrastructure buyers face broader decarbonization accountability in high-voltage equipment selection.
Market Restraints
- Copper and grain-oriented electrical steel volatility:Core material cost swings compress manufacturing margins and complicate long-term contract pricing for reactor producers.
- Chinese supply concentration:Domestic manufacturers control critical transformer-grade core steel capacity, creating import dependency risks for European and Indian reactor fabricators.
- IEC 60076-6 certification timelines:Extended type-testing protocols for extra-high-voltage units delay product qualification and revenue recognition by 12-18 months.
Strategic Opportunities
- India transmission expansion:State-owned Power Grid Corporation of India is tendering 765 kV corridor projects, creating entry points for reactor suppliers with localized manufacturing partnerships.
- Digital twin integration:Convergence of power electronics with cloud-based asset management enables predictive maintenance contracts that capture lifetime value beyond initial equipment sale.
- Offshore wind interconnection:North Sea and Baltic Sea projects demand compact, low-noise dry-type reactors for platform-mounted reactive compensation in environmentally sensitive marine zones.
Industry Challenges
- High-voltage insulation engineering talent scarcity:Specialized expertise in extra-high-voltage dielectric design concentrates at a handful of European and Japanese engineering centers, constraining expansion capacity.
- Legacy SCADA integration complexity:Digital condition monitoring systems must interface with decades-old substation control architectures, extending deployment timelines and inflating commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shunt Reactor Market |
| Market Size in 2026 | $2.95 Billion |
| Market Size in 2035 | $5.33 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Air-Core, Oil-Immersed, Dry-Type, Water-Cooled Application: Power Generation, Transmission Systems, Renewable Energy, Industrial Plants End User: Utility Companies, Manufacturers, Energy Suppliers, Infrastructure Developers Voltage Level: High Voltage, Medium Voltage, Low Voltage, Extra High Voltage |
| Companies Covered | Siemens Energy AG, Hitachi Energy Ltd., General Electric, ABB, Mitsubishi Electric Corporation, CG Power and Industrial Solutions Limited, Fuji Electric Co., Hyosung Heavy Industries, Toshiba Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shunt Reactor Market Emerging Trajectories
Reactive compensation hardware is converging with power electronics and software-defined control, compressing the traditional separation between passive inductive devices and active grid stabilization systems.
Silicon carbide power semiconductors is electrifying shunt reactor control by enabling faster switching and reduced thermal losses in hybrid reactive compensation systems. Offshore wind developers in the North Sea are piloting these integrated solutions for platform-based voltage regulation. The technology is electrifying competitive positioning by forcing pure hardware manufacturers to acquire power electronics capabilities or cede high-margin project segments.
China's MIIT dual carbon implementation guidelines are tightening efficiency benchmarks for grid infrastructure equipment, indirectly accelerating domestic reactor loss-reduction programs. Manufacturers must demonstrate reduced no-load losses to qualify for state grid procurement tenders. Domestic producers are responding with amorphous metal core trials and advanced cooling designs to meet the stricter thermal performance thresholds.
Utility procurement teams are unbundling hardware purchase from lifecycle service obligations, separating capital equipment bids from 15-20 year maintenance and digital monitoring contracts. European transmission operators pioneered this split-tender approach, and India's central utilities are adopting similar frameworks for greenfield 765 kV projects. This restructuring favors reactor suppliers with established service networks over pure manufacturing specialists.
Shunt Reactor Market Segmentation
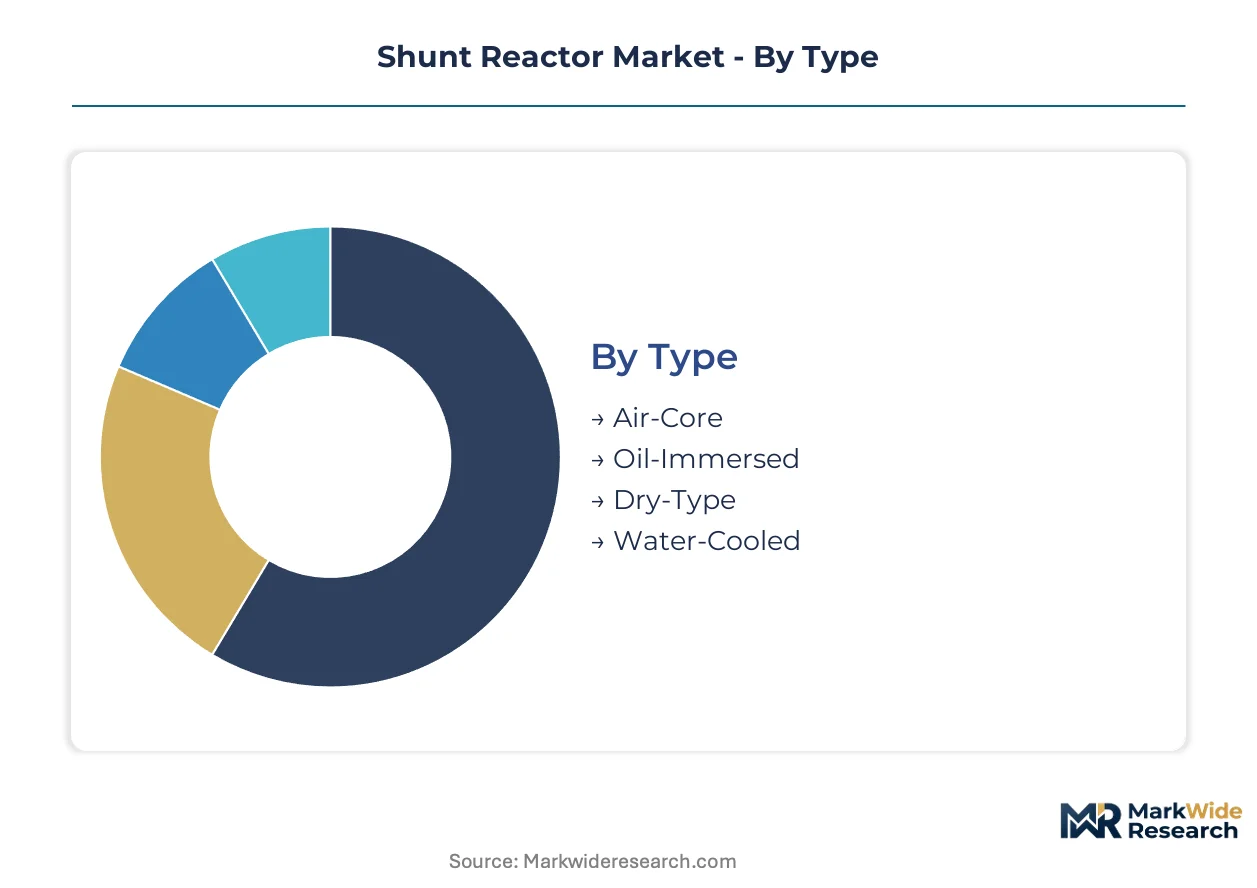
Shunt reactor procurement splits across four distinct classification systems, each reshaping supplier qualification requirements and contract structures. Technology type determines thermal management architecture, while voltage tier dictates insulation engineering complexity and manufacturing capital intensity.
Type:
Oil-immersed designs demand the heaviest upfront capital commitment due to tank fabrication, oil processing infrastructure, and fire containment engineering. Air-core units require substantial copper winding investment but avoid fluid handling systems.
- Oil-Immersed:Mineral oil or synthetic ester fluid provides dielectric insulation and thermal management in a sealed tank construction. Demand concentrates in German and Chinese extra-high-voltage transmission corridors where compact substation footprint outweighs fire risk mitigation costs. IEC 60076-6 loss measurement protocols favor these designs for ratings above 100 MVAr.
- Dry-Type:Epoxy resin or cast resin insulation eliminates fluid leakage risk and enables indoor installation. Urban substations in India and offshore wind platforms in the North Sea specify these units where environmental sensitivity or space constraints override thermal performance advantages of oil-filled alternatives.
- Air-Core:Open winding construction with natural convection cooling suits outdoor installations with generous site clearances. Mining and heavy industrial complexes in Australia and Brazil deploy these for medium-voltage reactive compensation where maintenance access is prioritized.
- Water-Cooled:Closed-loop cooling circuits enable extreme power density in space-constrained environments. Offshore converter platforms and urban underground substations in Japan and South Korea pilot these for ratings where air or oil thermal limits bind.
Most installed capacity flows through oil-immersed designs. Expansion is steepest in dry-type units.
Application:
Transmission utilities anchor volume procurement with standardized specifications, while renewable developers drive specification innovation through grid code compliance mandates.
- Transmission Systems:Long-distance extra-high-voltage corridors absorb reactive power to control Ferranti effect voltage rise. State Grid Corporation of China and Power Grid Corporation of India tender these as bundled substation packages with 30-40 year asset life assumptions.
- Renewable Energy:Wind and solar farms require dynamic reactive compensation for inverter synchronization and voltage ride-through compliance. Offshore wind interconnection projects in the German Baltic Sea specify hybrid reactor-statcom configurations.
- Power Generation:Thermal and nuclear plant switchyards install fixed shunt reactors for generator step-up transformer voltage regulation. Legacy coal plants in Poland and Romania upgrade these during flue gas desulfurization retrofits.
- Industrial Plants:Steel mills, cement kilns, and chemical complexes deploy medium-voltage units for power factor correction and arc furnace flicker mitigation. Integrated steelworks in India and Vietnam specify these for captive power plant synchronization.
Transmission systems absorb the majority of capital expenditure. Renewable energy integration commands the steepest specification escalation.
End User:
Utility procurement frameworks separate hardware capital from lifecycle service obligations, favoring suppliers with maintenance network density over pure manufacturing scale.
- Utility Companies:Transmission system operators in Germany, China, and India issue multi-year framework agreements with technical specifications aligned to national grid codes. These buyers unbundle equipment purchase from 15-20 year digital monitoring contracts.
- Energy Suppliers:Independent power producers and renewable developers procure reactor-transformer packages through engineering-procurement-construction contractors. Offshore wind consortia in the North Sea specify these as platform-integrated systems.
- Infrastructure Developers:Greenfield industrial zone and data center power infrastructure projects specify medium-voltage units for substation buildouts. Hyperscale data center campuses in India and Singapore drive demand for dry-type designs with redundant cooling.
- Manufacturers:Original equipment manufacturers integrate reactors into switchgear assemblies and mobile substations for mining and emergency response applications. These buyers prioritize weight reduction and modular transportability.
Utility companies dominate procurement volume. Energy suppliers are gaining share fastest through renewable project development.
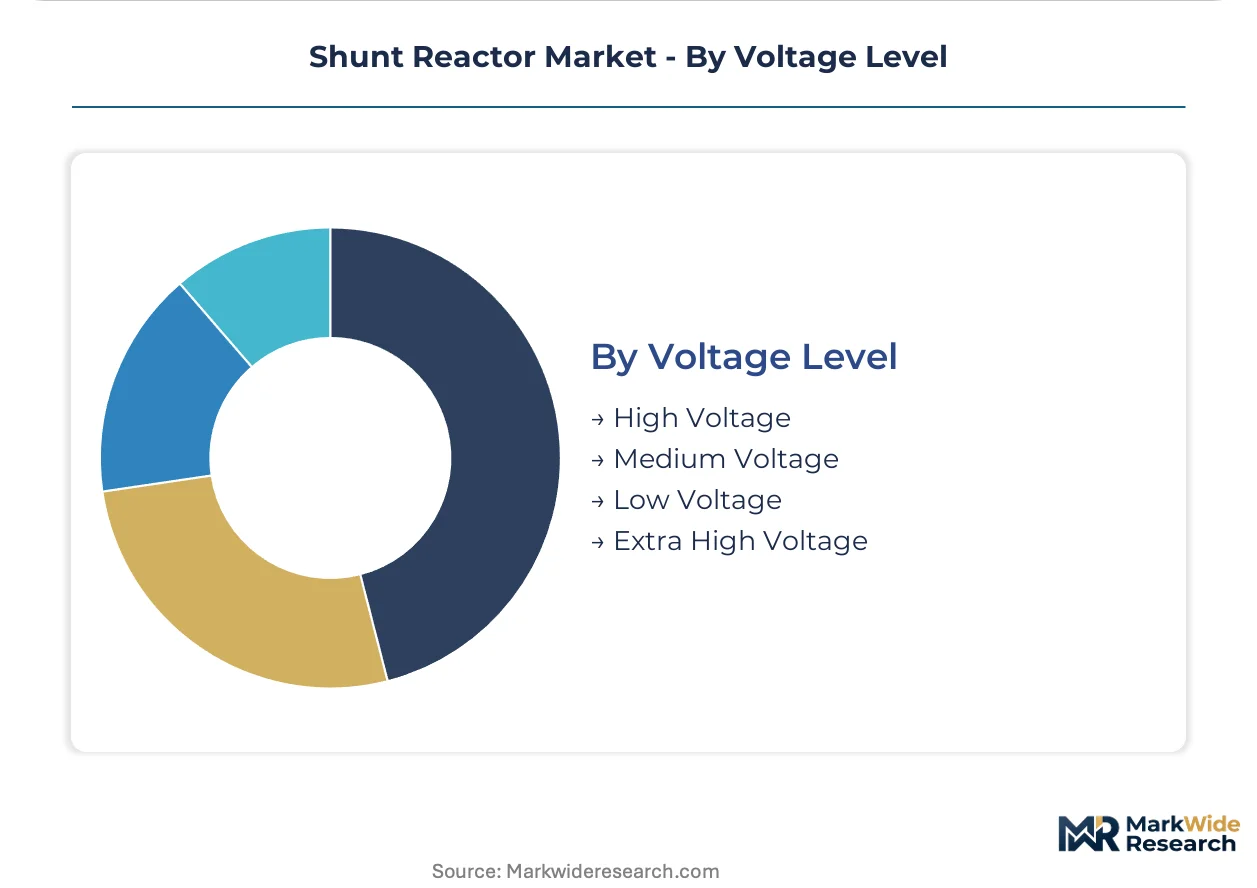
Voltage Level:
Extra-high-voltage manufacturing requires specialized cleanroom winding facilities and impulse test laboratories that constrain supplier entry.
- Extra High Voltage:Ratings above 345 kV serve inter-regional transmission corridors and ultra-high-voltage direct current converter stations. Chinese 765 kV and 1100 kV projects concentrate global demand for these units.
- High Voltage:69 kV through 345 kV ratings cover bulk power substations and renewable collection systems. Indian transmission expansion targets this tier for regional grid strengthening.
- Medium Voltage:1 kV through 69 kV units address distribution substations and industrial power factor correction. Urban underground networks in Japan and South Korea specify dry-type designs in this range.
- Low Voltage:Below 1 kV applications are rare in transmission contexts, limited to specialized laboratory and testing equipment. This tier captures minimal commercial significance in grid infrastructure markets.
High voltage absorbs the largest share of manufacturing capacity. Extra high voltage is climbing the fastest as interconnection projects multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys more extra-high-voltage shunt reactor capacity than any other single country, while Germany concentrates European demand through its North Sea offshore wind interconnection buildout.
China
State Grid Corporation tenders 765 kV and 1100 kV corridor projects that absorb the majority of global extra-high-voltage reactor manufacturing. MIIT dual carbon guidelines tighten efficiency benchmarks for grid infrastructure procurement. Manufacturing clusters in Shenyang and Xi'an house specialized cleanroom winding facilities serving domestic ultra-high-voltage direct current converter stations.
Germany
Transmission system operators TenneT and 50Hertz mandate dynamic reactive compensation for inverter-based renewable interconnections in the North Sea and Baltic Sea. EU Green Deal grid modernization directives accelerate specification upgrades for extra-high-voltage equipment. Industrial concentration in Berlin and Nuremberg anchors European reactor engineering expertise and impulse test laboratory capacity.
India
Power Grid Corporation of India is tendering 765 kV greenfield corridor projects requiring localized manufacturing partnerships. Central Electricity Authority grid code amendments align reactive power standards with evolving IEC frameworks. Manufacturing zones in Gujarat and Maharashtra host joint ventures between domestic fabricators and European technology licensors.
United States
FERC Order 2023 compliance deadlines drive utility upgrades for aging transmission infrastructure across the Midwest and Texas interconnections. Independent system operators in PJM and ERCOT specify oil-immersed designs for bulk power substation reinforcement. Industrial corridors in Pennsylvania and Ohio concentrate legacy manufacturing capacity for high-voltage transformer and reactor production.
Japan
Tokyo Electric Power and Chubu Electric deploy dry-type reactors in urban underground substations where fire risk mitigation overrides thermal performance trade-offs. METI efficiency standards push manufacturers toward reduced no-load loss designs. Manufacturing clusters in Nagoya and Osaka specialize in epoxy resin insulation systems for medium-voltage through high-voltage ratings.
Shunt Reactor Market Vendor Landscape
Top-tier vendors anchor extra-high-voltage project execution, while mid-tier fabricators compete on regional manufacturing proximity and localized service networks. The market structures around three strategic archetypes: integrated power equipment conglomerates with transformer and reactor manufacturing scale, power electronics specialists converging reactive compensation with semiconductor-based control, and regional fabricators serving national utility procurement frameworks. Dominant competitive moves include backward integration into core steel supply and technology licensing partnerships for digital condition monitoring capabilities.
Within the integrated conglomerate tier, Siemens Energy AG and Hitachi Energy Ltd. represent contrasting geographic anchors for European and Asia-Pacific utility procurement respectively. General Electric occupies a position exemplifying North American-focused oil-immersed specialization for transmission infrastructure upgrades. These three entities illustrate how vendor origin shapes regulatory alignment and grid code certification pathways across distinct regional markets.
| Leading Market Players |
|---|
| Siemens Energy AG |
| Hitachi Energy Ltd. |
| General Electric |
| ABB |
| Mitsubishi Electric Corporation |
| CG Power and Industrial Solutions Limited |
| Fuji Electric Co. |
| Hyosung Heavy Industries |
| Toshiba Corporation |
| Others |
Supply Flow & Price Mechanics
Backward integration into grain-oriented electrical steel production anchors supply positioning and pricing power for reactor manufacturers facing volatile core material costs. Chinese domestic mills control critical transformer-grade steel capacity, forcing European and Indian fabricators to absorb margin compression or pursue captive supply arrangements.
Pricing Analysis
Capacity additions in China's ultra-high-voltage manufacturing clusters are reshaping price floors for extra-high-voltage reactor tenders. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification tier and after-sales bundling. Price differentiation stems from IEC 60076-6 qualification status and localized service network density. Cost compression in the economy tier is intensifying because Chinese state-owned utilities leverage domestic manufacturing scale for 765 kV and 1100 kV projects. Renewable developers and offshore wind consortia exhibit the lowest price sensitivity due to grid code compliance mandates and platform installation constraints.
Supply Chain Analysis
Dual-sourcing qualification requirements from German transmission operators TenneT and 50Hertz mandate qualified secondary suppliers for critical reactor components. Manufacturing draws from China, Germany, and India for core steel winding, tank fabrication, and epoxy resin insulation systems respectively. Raw material dependencies center on grain-oriented electrical steel, copper windings, and mineral oil or synthetic ester dielectric fluids. Single-source vulnerability concentrates in Chinese transformer-grade steel capacity, creating import dependency exposure for European fabricators. Distribution runs through utility framework agreements and engineering-procurement-construction contractors for renewable integration projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shunt reactor market functions as a stable compounder anchored by transmission infrastructure renewal cycles and mandatory grid code upgrades for renewable interconnection. Regulatory-driven replacement demand insulates the sector from cyclical volatility.
For Market Incumbents: To counter hardware commoditization from Chinese state-owned manufacturers, Siemens Energy and Hitachi Energy should deepen digital condition monitoring capabilities and secure 15-20 year lifecycle service contracts. Backward integration into silicon carbide power semiconductor sourcing protects margins in hybrid reactive compensation segments.
For New Entrants and Emerging Players: Engineering-procurement-construction contractors represent the most accessible channel for reactor suppliers lacking utility framework agreement status. India's 765 kV greenfield corridor expansion offers the most penetrable geography through localized manufacturing joint ventures. Dry-type reactor specialization for offshore wind platforms enables premium positioning without competing on extra-high-voltage oil-immersed scale.
For Investors and Strategic Acquirers: Roll-up economics work for regional service networks because utility procurement frameworks increasingly unbundle hardware purchase from long-term maintenance obligations. Mid-cap fabricators with established impulse test laboratory access and national grid code certification present viable acquisition targets. Watch for MIIT efficiency benchmark tightening in China as a signal for accelerated domestic loss-reduction investment and potential technology licensing demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Condition Monitoring Integration | Captures lifecycle value beyond initial equipment sale for TenneT and 50Hertz framework agreements. |
| Silicon Carbide Power Semiconductor Sourcing | Enables hybrid reactor-statcom configurations for North Sea offshore wind voltage regulation. |
| Localized Manufacturing Partnership | Qualifies suppliers for Power Grid Corporation of India 765 kV tender requirements. |
| Amorphous Metal Core Development | Meets MIIT dual carbon efficiency benchmarks for State Grid Corporation procurement eligibility. |
| Service Network Density Expansion | Aligns with European utility split-tender approaches separating capital from maintenance contracts. |
Methodological Framework
Bottom-up transmission utility modeling reconciled against top-down reactor manufacturing capacity tracking forms the analytical core of this study. Primary interviews with transmission planning officers, EPC contractors, reactor engineering directors, and utility procurement managers combined with secondary validation from IEC standard documentation, FERC filings, EIA transmission infrastructure data, and national grid operator capex disclosures. Triangulation across supply-side facility audits and demand-side tender analysis ensures cross-verified volume and value estimates.
Historical trendline analysis of extra-high-voltage corridor deployment patterns and renewable interconnection mandates shaped the projection framework across the analysis window. Segmentation dimensions modeled include reactor technology type, voltage tier, application segment, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to utility capital expenditure trajectories and grid code amendment timelines. Forecast inputs incorporated MIIT efficiency benchmark evolution and EU Green Deal grid modernization directive implementation pacing.
Revisions become necessary when copper and grain-oriented electrical steel price volatility exceeds historical bands or when IEC 60076-6 certification timelines extend materially. Forecasts reflect assumptions regarding state-owned utility procurement continuity and offshore wind interconnection project sanctioning rates. Deviation in Chinese domestic manufacturing capacity expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Wireless Battery Monitoring System Market
Power Systems
Global Synchronous Motor Market
Power Systems
Automotive Power Semiconductor Market
Power Systems
Asia Pacific Low Voltage Drives Market
Power Systems
Three-Phase String Inverter Market
Power Systems
Global Power Discrete and Modules Market
Power Systems
Shunt Voltage References Market
Power Systems
Global Frequency Converter Market
Power Systems
Global Chip Power Inductor Market
Power Systems
Global Automatic Voltage Stabilizer Market
Power Systems
Switching Regulators Power Management IC Market
Power Systems
Japan Surge Protector Market
Power Systems
Static VAR Compensator (SVC) Market
Power Systems
Embedded Power Generation Market
Power Systems
Global Telecom Tower Power System Market
Power Systems
Electric Vehicle Power Inverter Market