
 USB Power Adapters Market | 2026-2036
USB Power Adapters Market Size, Share, and Industry Trends Forecast 2026-2036
USB Power Adapters Market Insights
The capital-intensity divergence between in-house semiconductor fabrication and outsourced power-management IC sourcing is rotating competitive advantage toward vertically integrated players. Apple Inc. leverages captive chip design to sustain margin control across its adapter ecosystem. Anker Innovates anchors its position through dedicated GaN R&D labs and direct-to-consumer channel dominance. Samsung Electronics competes by bundling adapters with flagship smartphone lines across multiple price tiers.
USB power adapters are compact AC-to-DC conversion devices that transform mains electricity into standardized low-voltage DC output, typically 5V to 20V with power delivery up to 240W under USB Power Delivery 3.1 specifications, serving to recharge or operate portable consumer electronics. Wall chargers maintain the largest volume position due to universal residential and workplace deployment, while GaN-based fast charging technology captures the fastest expansion trajectory as thermal efficiency gains enable smaller form factors at higher wattages. Multi-port adapters concentrate margin pools in corporate and travel segments where simultaneous device charging commands price premiums over single-output alternatives.
The EU Common Charger Directive enforces USB-C harmonization across portable devices, compelling redesign cycles and inventory transitions for manufacturers serving European markets. The US Department of Energy's efficiency standards and China's GB 4943.1 safety certification create layered compliance thresholds that filter subscale producers from premium distribution channels. Stakeholders must monitor regulatory divergence between efficiency mandates and interoperability standards when allocating regional product development resources.
Market Dynamics
The USB Power Adapters Market is being fundamentally restructured by gallium nitride semiconductor adoption, which decomposes thermal management constraints and enables wattage-density improvements that silicon-based designs cannot match.
Growth Catalysts
- EU Common Charger Directive:The mandate for USB-C harmonization across portable devices forces universal compatibility upgrades, accelerating replacement cycles for legacy proprietary connectors.
- GaN thermal efficiency gains:Power density improvements enable 100W+ outputs in sub-50cc enclosures, satisfying laptop and gaming device requirements previously served by bulky OEM adapters.
- China electronics manufacturing concentration:Domestic brands in Shenzhen and Dongguan drive volume procurement of multi-port fast chargers, compressing unit economics for export markets.
Market Restraints
- Silicon carbide substrate costs:Raw material volatility for wide-bandgap semiconductors constrains margin expansion for mid-tier adapter producers.
- South Korean component dependency:Power-management IC sourcing concentrates among Seoul-based foundries, creating single-source vulnerability for GaN controller supply.
- USB Power Delivery 3.1 certification complexity:Extended validation timelines for EPR mode adapters delay product launches by 4-6 months versus prior standards.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Production-linked incentives attract adapter assembly investments targeting domestic smartphone penetration and export to Middle East markets.
- Automotive USB-C integration:In-cabin charging ports for electric vehicles create specification demand for 48V-to-5V conversion modules with vibration tolerance.
- Direct-to-consumer channel expansion:Amazon and brand-owned storefronts bypass distributor markups, capturing margin previously allocated to retail partners.
Industry Challenges
- GaN device characterization expertise:Shortage of power electronics engineers capable of optimizing switching frequencies above 500kHz limits R&D throughput for tier-two manufacturers.
- Multi-jurisdiction safety certification backlog:Simultaneous UL, CE, and PSE approval requirements strain testing laboratory capacity, extending time-to-revenue for new product families.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USB Power Adapters Market |
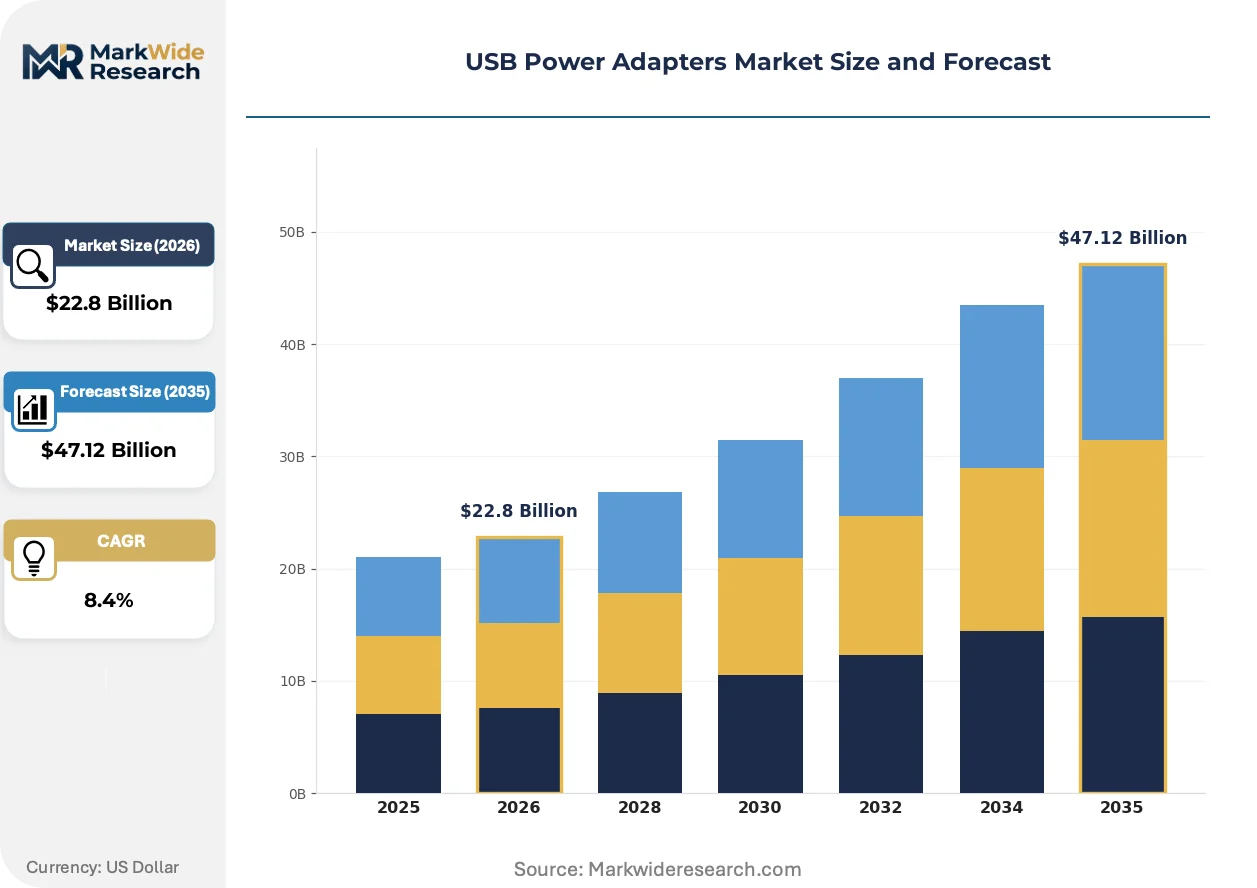
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $47.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall Chargers, Car Chargers, Multi-Port Adapters, Travel Adapters End User: Individual Consumers, Corporate Users, Educational Institutions, Retail Businesses Technology: Fast Charging, Standard Charging, Wireless Charging, Solar Power Compatibility: Smartphones, Tablets, Laptops, Wearable Devices |
| Companies Covered | Apple Inc., Samsung Electronics, Anker Innovations, Belkin International, Xiaomi Corporation, Huawei Technologies, Sony Corporation, TP-Link Technologies, UGREEN, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USB Power Adapters Market Trends and Innovations
Active power semiconductor substitution is compressing adapter form factors while regulatory harmonization and channel disintermediation redistribute value capture across the value chain.
GaN-on-silicon power transistors is decomposing the thermal dissipation bottleneck that previously constrained wattage-per-cubic-centimeter ratios. Gaming laptop manufacturers and mobile workstation vendors are adopting 140W-240W GaN adapters as standard bundled accessories. The structural consequence is collapsing enclosure sizes for equivalent power outputs, rendering legacy silicon-based designs uncompetitive in premium segments.
REACH substance restrictions on halogenated flame retardants are forcing PCB laminate reformulation for adapters sold into European markets. Manufacturers must qualify new substrate materials or face distribution channel exclusion. The directive most severely impacts low-cost single-port adapters where material substitution erodes already thin margins.
Enterprise IT procurement departments are consolidating adapter purchasing under managed device programs, displacing individual employee reimbursement models. Channel partners specializing in mobile device management platforms are capturing this volume, particularly in North American financial services and healthcare verticals where asset tracking requirements dominate supplier selection criteria.
USB Power Adapters Market Segmentation
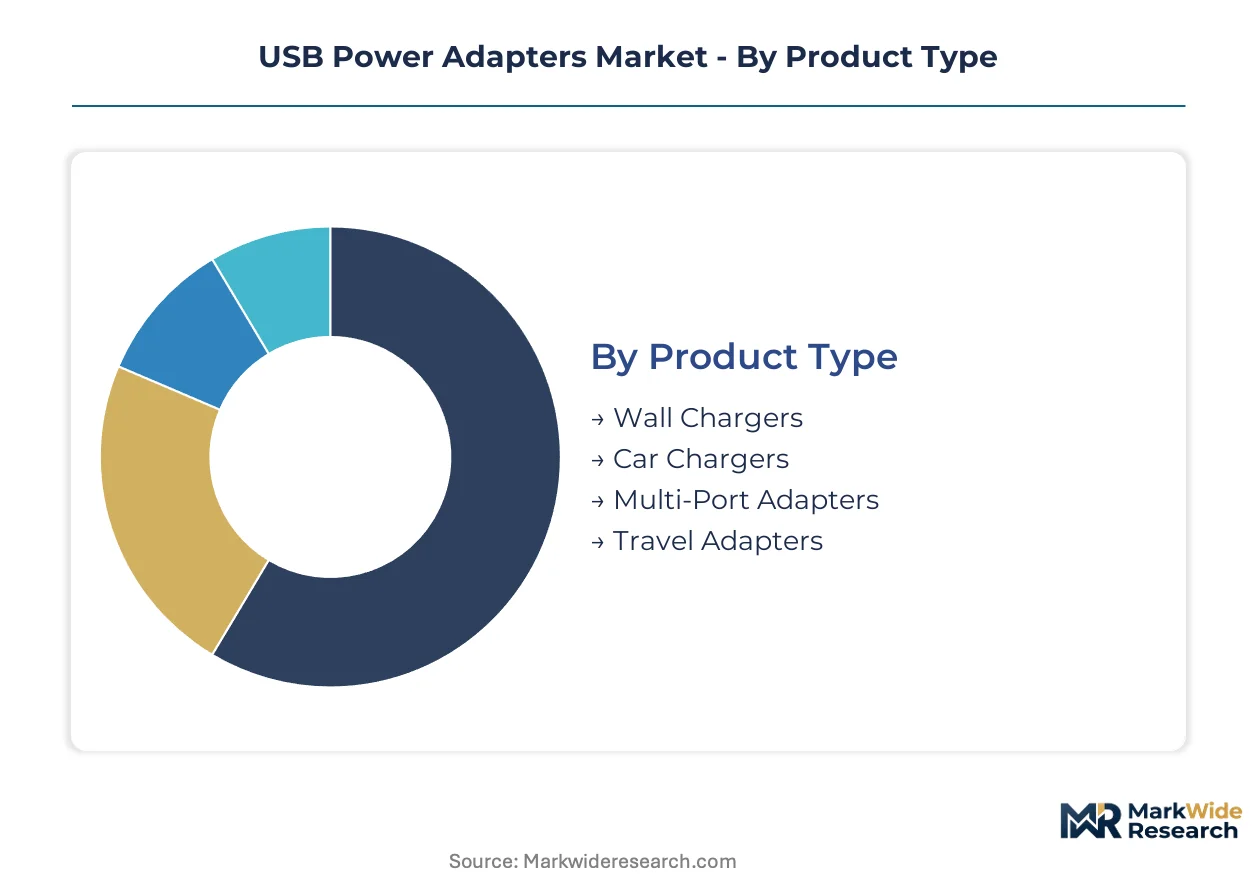
USB power adapter segmentation reveals how wattage density, port configuration, and certification tiers split margin capture across consumer and enterprise channels. Product architecture and semiconductor technology choices determine which segments command sustainable pricing power versus commodity pressure.
Product Type:
Margin pools concentrate in multi-port configurations where simultaneous charging capabilities justify premium positioning over single-output alternatives.
- Wall Chargers:AC-to-DC converters designed for residential and workplace mains connection, delivering 5V to 240V outputs. Demand clusters in China manufacturing corridors where Shenzhen-based electronics brands drive volume procurement for bundled smartphone programs. Thermal efficiency mandates from the US Department of Energy filter subscale producers from premium distribution channels.
- Multi-Port Adapters:Consolidated charging hubs enabling simultaneous device powering through 2-6 USB-C or USB-A outputs. Corporate IT procurement departments in North American financial services and healthcare verticals favor these under managed device programs where asset tracking requirements dominate supplier selection. GaN semiconductor integration enables 100W+ density in sub-50cc enclosures.
- Car Chargers:DC-to-DC converters drawing 12V automotive electrical systems for mobile device replenishment during vehicle operation.
- Travel Adapters:Multi-prong interchangeable plug systems accommodating regional voltage and pin configurations for international mobility.
The dominant share belongs to Wall Chargers, while Multi-Port Adapters are closing the gap fastest.
End User:
Volume concentration shifts toward institutional procurement models that displace individual reimbursement structures.
- Corporate Users:Enterprise organizations purchasing adapters under centralized mobile device management platforms. North American financial services firms and healthcare systems prioritize asset tracking and warranty standardization over unit cost minimization. Channel partners specializing in MDM integration capture this consolidated spend.
- Individual Consumers:Retail purchasers acquiring adapters through Amazon marketplace and brand-owned direct-to-consumer storefronts. Shenzhen and Dongguan manufacturing clusters supply cost-optimized single-port units for price-sensitive segments. REACH substance restrictions on halogenated flame retardants force PCB laminate reformulation for European-bound inventory.
- Educational Institutions:K-12 and university systems procuring standardized charging infrastructure for one-to-one device programs.
- Retail Businesses:Commercial establishments deploying customer-facing charging stations as amenity infrastructure.
Corporate Users capture the steepest margin expansion, while Individual Consumers retain absolute volume leadership.
Technology:
Semiconductor substrate choices determine thermal performance ceilings and enclosure size constraints.
- Fast Charging:USB Power Delivery 3.1 and proprietary protocols enabling 18W to 240W outputs through elevated voltage and amperage negotiation. Gaming laptop manufacturers and mobile workstation vendors adopt 140W-240W GaN adapters as standard bundled accessories. USB Power Delivery 3.1 EPR mode certification complexity extends validation timelines by 4-6 months versus prior standards.
- Standard Charging:Legacy 5V/2.4A specifications without power negotiation protocols. Demand persists in emerging market entry-level smartphones and subsidized device programs where cost minimization overrides speed requirements. Silicon-based designs face margin compression as GaN alternatives penetrate mid-tier price bands.
- Wireless Charging:Inductive power transfer through Qi and proprietary coil architectures eliminating physical connector dependency.
- Solar Power:Photovoltaic panel integration for off-grid or emergency charging applications in outdoor recreation and developing region deployments.
Fast Charging commands premium positioning, while Wireless Charging is expanding most quickly through automotive and furniture integration.
Compatibility:
Device power requirements stratify adapter specifications across voltage and amperage tiers.
- Laptops:Mobile computing platforms requiring 45W to 240W sustained delivery for system operation and battery replenishment. The EU Common Charger Directive mandates USB-C harmonization, compelling redesign cycles for legacy barrel-connector adapters serving European markets. GaN thermal efficiency gains enable sub-50cc enclosures previously requiring bulky OEM designs.
- Smartphones:Handheld communication devices representing the highest unit volume application with 18W to 65W typical requirements. China domestic brands drive specification convergence toward 65W-80W as standard flagship capability. Multi-jurisdiction safety certification backlogs strain testing laboratory capacity for new product families.
- Tablets:Mid-size computing devices with 18W to 45W power requirements bridging smartphone and laptop segments.
- Wearable Devices:Low-power accessories requiring 5W to 15W delivery through specialized pogo-pin or magnetic attachment systems.
Smartphones dominate absolute unit shipments, while Laptop compatibility requirements are driving the steepest wattage escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes USB power adapters through domestic electronics manufacturing clusters and export-oriented procurement, while European markets prioritize regulatory compliance and standardization over volume throughput.
China
Shenzhen and Dongguan electronics brands drive volume procurement for bundled smartphone programs and aftermarket distribution. MIIT enforces GB 4943.1 safety certification that filters subscale producers from premium channels. The Pearl River Delta manufacturing corridor concentrates GaN fast charger assembly for export markets.
United States
Enterprise IT procurement departments consolidate adapter purchasing under managed device programs in financial services and healthcare verticals. The Department of Energy maintains efficiency standards that constrain thermal dissipation specifications. California-based technology firms anchor premium GaN adapter distribution through direct-to-consumer channels.
Germany
Industrial automation and automotive electronics manufacturers specify high-reliability adapters for embedded applications. REACH substance restrictions on halogenated flame retardants force PCB laminate reformulation for European-bound inventory. Bavaria's precision electronics cluster sources certified adapters for industrial equipment integration.
India
Domestic smartphone penetration drives adapter demand through both bundled programs and replacement purchases. The PLI scheme for electronics manufacturing attracts assembly investments targeting domestic consumption and Middle East export. Maharashtra and Karnataka host contract manufacturers scaling production for regional brands.
Japan
Mobile workstation and gaming device manufacturers adopt high-wattage GaN adapters as standard accessories. METI oversees technical standards harmonization with international USB Power Delivery specifications. The Kanto region's electronics distribution networks prioritize compact form factors for space-constrained residential environments.
USB Power Adapters Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the USB power adapters market. Captive semiconductor design and direct-to-consumer channel control separate the upper tier from contract-dependent assemblers. Three archetypes dominate: vertically integrated technology ecosystems, dedicated charging accessory specialists, and diversified consumer electronics conglomerates. Competitive moves concentrate on GaN R&D laboratory investment and strategic bypass of distributor markups through Amazon marketplace and brand-owned storefronts.
Within the integrated technology ecosystem tier, Apple Inc. and Samsung Electronics exemplify players leveraging captive chip design and bundled distribution to sustain margin control. Among dedicated charging accessory specialists, Anker Innovations occupies a position representing the direct-to-consumer channel dominance archetype. These three companies anchor the competitive structure through contrasting approaches to semiconductor sourcing and customer access.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Anker Innovations |
| Belkin International |
| Xiaomi Corporation |
| Huawei Technologies |
| Sony Corporation |
| TP-Link Technologies |
| UGREEN |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization above 85% across Shenzhen and Dongguan assembly corridors compresses unit economics for export-bound adapters while simultaneously elevating price floors for GaN-enabled premium tiers. This scale concentration rewards vertically integrated players with captive semiconductor sourcing, leaving contract-dependent assemblers exposed to margin erosion from raw material volatility and certification backlog delays.
Pricing Analysis
After-market replacement revenue and extended warranty programs anchor lifetime value capture for adapter specialists. Three-tier pricing structure across premium, standard, and economy levels stratifies by GaN semiconductor integration and USB Power Delivery 3.1 certification grade. Price differentiation hinges on thermal efficiency benchmarks and multi-port configuration density. Cost compression in economy-tier silicon-based units intensifies because Shenzhen manufacturers divert excess capacity toward export spot markets. Individual consumers through Amazon marketplace channels exhibit highest price sensitivity, while corporate IT procurement under managed device programs prioritize asset tracking standardization over unit cost.
Supply Chain Analysis
Container availability constraints across the Shenzhen-Los Angeles trade lane elevate inbound logistics costs for North American-bound inventory. Manufacturing concentration centers on China, South Korea, and Taiwan, with the Pearl River Delta hosting GaN fast charger final assembly and Seoul-based foundries supplying power-management ICs. Raw material dependencies span gallium nitride substrates, silicon carbide wafers, and halogen-free PCB laminates. Single-source vulnerability for GaN controller supply from Seoul-based foundries exposes mid-tier producers to allocation rationing during capacity crunches. Distribution runs through Amazon marketplace and brand-owned direct-to-consumer storefronts, bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GaN semiconductor substitution and EU Common Charger Directive harmonization are compressing legacy silicon adapter margins while opening premium positioning for thermal-efficient designs. This regulatory-technology inflection rewards players with captive R&D laboratories and certification pre-positioning.
For Market Incumbents: Shield premium positioning by deepening backward integration into GaN-on-silicon transistor sourcing and accelerating USB Power Delivery 3.1 EPR certification pipelines ahead of competitor validation timelines. Consolidate channel control through exclusive Amazon marketplace storefront arrangements that displace third-party reseller price competition. Prioritize managed device program partnerships with North American financial services and healthcare verticals where asset tracking requirements filter out low-cost alternatives. For New Entrants and Emerging Players: Enterprise IT procurement gaps in Middle East and India markets present white-space opportunities where PLI scheme incentives attract assembly investment for regional brand supply. Target automotive USB-C integration specifications for electric vehicle 48V-to-5V conversion modules, where vibration tolerance requirements and extended temperature ratings create qualification barriers for incumbent consumer-electronics specialists. Pursue direct-to-consumer launch through TikTok Shop and brand-owned storefronts to bypass established Amazon marketplace saturation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among GaN R&D laboratories with captive semiconductor characterization capabilities and pre-certified product families. Long-term viability across the projection horizon favors vertically integrated specialists with Shenzhen assembly presence and direct-to-consumer channel control. Acquisition target archetype: mid-tier producers with certification backlog clearance and stranded inventory transitioning to USB-C harmonization. Monitor GaN device characterization engineer hiring velocity at tier-two manufacturers as inflection indicator for R&D throughput constraints.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor R&D Laboratory Investment | Anker Innovations anchors market position through dedicated thermal efficiency research facilities in Shenzhen. |
| Direct-to-Consumer Channel Expansion | Brand-owned storefronts bypass Amazon marketplace commission structures, capturing margin previously allocated to retail partners. |
| USB Power Delivery 3.1 EPR Certification Pre-Positioning | Early validation clearance accelerates product launch timelines by 4-6 months versus competitors facing laboratory backlog. |
| Backward Integration into Power-Management IC Sourcing | Apple Inc. sustains margin control through captive chip design across its adapter ecosystem. |
| Managed Device Program Partnership Development | Channel partners specializing in MDM platforms capture consolidated enterprise spend in financial services and healthcare verticals. |
Research Methodology
The analysis maps wall charger, multi-port adapter, car charger, and travel adapter sub-sectors, each validated through procurement directors at electronics brands, power electronics engineers at GaN semiconductor foundries, and channel partners at mobile device management platforms. Primary interviews with Shenzhen-based contract manufacturing executives and North American enterprise IT asset managers combined with secondary validation from MIIT GB standard filings, US Department of Energy efficiency certifications, and EU Common Charger Directive implementation timelines. Bottom-up unit shipment modeling and top-down value aggregation triangulate market size estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by product architecture, semiconductor technology, port configuration, and certification tier, with regional regulatory divergence modeled as a separate dimension. CAGRs derive from fitted growth curves calibrated to historical replacement cycle data and GaN penetration trajectories. Industry-specific forecast inputs include USB Power Delivery 3.1 adoption velocity and REACH substance restriction compliance costs.
Forecasts assume regulatory continuity in EU Common Charger Directive enforcement, US Department of Energy efficiency standards, and China MIIT GB 4943.1 certification requirements; material policy shifts would require re-modeling. Semiconductor substrate price volatility and multi-jurisdiction safety certification laboratory capacity constraints represent specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Linear Voltage Regulators Market
Power Systems
Grid Tie Inverter Market
Power Systems
Central Battery Systems Market
Power Systems
Space DC-DC Converters Market
Power Systems
Asia-Pacific Automotive DC-DC Converters Market
Power Systems
Superconducting Magnet Systems Market
Power Systems
Power Diode Market
Power Systems
Automotive Power Electronics Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
North America Electric Vehicle Power Inverter Market
Power Systems
Global Gan Power Device Market
Power Systems
Telecom Battery Market
Power Systems
Grid Forming Inverters Market
Power Systems
High Current Power Supply for Electrophoresis Market
Power Systems
Asia-Pacific Shunt Reactors Market
Power Systems
PV Inverter Market