
 Acousto Optic Devices Market | 2026-2036
Acousto Optic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Acousto Optic Devices Market Analysis
The EU F-Gas Regulation is shifting procurement criteria for precision optical systems across European semiconductor fabs and research installations. Coherent Corp. leverages in-house crystal growth to control tellurium dioxide supply for modulator cores. Gooch and Housego PLC anchors its position through dedicated acousto-optic fabrication facilities in the UK and US. Hamamatsu Photonics K.K. differentiates via vertical integration from photodetector arrays through to finished beam steering assemblies.
Acousto optic devices employ piezoelectric transducers bonded to optical-grade crystals—typically tellurium dioxide, fused silica, or germanium—to impose refractive index gratings via traveling acoustic waves, enabling precise control of laser beam intensity, frequency, and direction with microsecond response times. Modulators capture the dominant revenue pool in telecommunications and materials processing where continuous-wave laser power requires rapid amplitude control. Surface acoustic wave technology is expanding fastest in compact optical sensing nodes for industrial automation, displacing bulk wave architectures in space-constrained deployments.
The US FDA governs acousto-optic components integrated into surgical laser systems through 21 CFR 1040 laser product performance standards, while the EU MDR extends conformity requirements to medical imaging subassemblies incorporating programmable filters. China's MIIT enforces GB standards on fiber-based devices deployed in national telecom infrastructure, creating divergent certification burdens for multi-region suppliers. Stakeholders must track how REACH amendments on critical raw materials affect tellurium dioxide sourcing economics and whether India's PLI scheme for telecom equipment draws assembly capacity toward domestic acousto-optic module production.
Market Dynamics
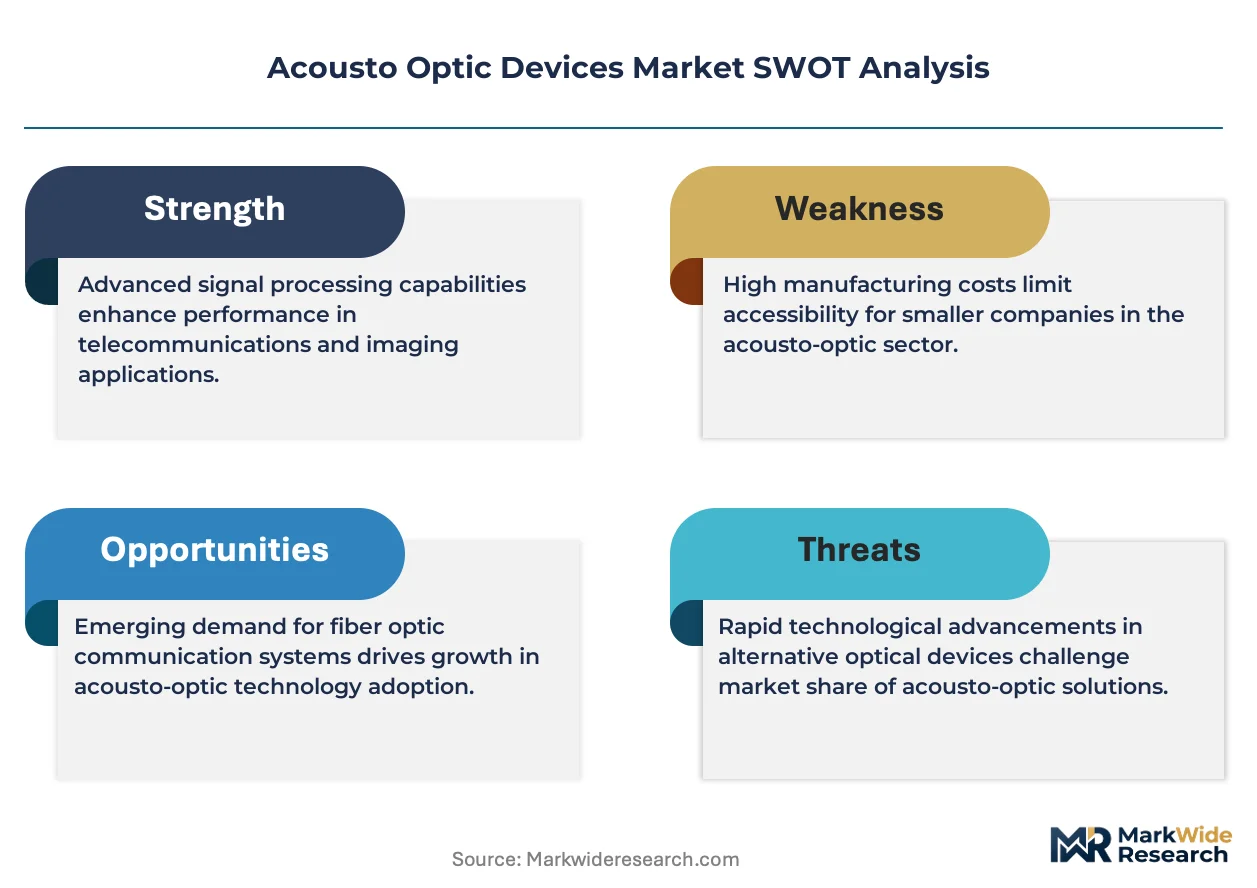
The EU F-Gas Regulation is forcing thermal management redesigns in precision optical equipment, compressing development cycles and tilting procurement criteria toward compliant cooling architectures across semiconductor fabs and research installations.
Growth Catalysts
- Laser tuning demand:Semiconductor manufacturing lines are pulling acousto-optic modulator volumes from defense and medical imaging buyers, concentrating orders in high-throughput wafer processing applications.
- Surface acoustic wave expansion:Compact optical sensing nodes for industrial automation are displacing bulk wave architectures in space-constrained deployments, accelerating adoption in robotic inspection systems.
- German photonics cluster:Applied research institutes around Jena and Berlin feed directly into component suppliers, creating tight feedback loops between crystal fabrication and end-use prototyping.
Market Restraints
- Tellurium dioxide supply concentration:Crystal growth capabilities for modulator cores concentrate in a handful of specialized suppliers, exposing buyers to raw material availability shocks.
- REACH amendment friction:Critical raw materials scrutiny on tellurium compounds is tightening sourcing economics and extending qualification timelines for new supply relationships.
- Fiber laser substitution:Direct diode and fiber-based alternatives are eroding addressable share in low-power materials processing segments where acousto-optic precision is over-specified.
Strategic Opportunities
- India PLI scheme leverage:Telecom equipment production incentives are drawing assembly capacity toward domestic acousto-optic module fabrication for national fiber infrastructure builds.
- China MIIT certification gap:Divergent GB standards on fiber-based devices create first-mover advantages for suppliers who front-load multi-region compliance investment.
- Medical imaging unbundling:Programmable filter subassemblies are separating from complete system sales, opening component-level contracts with EU MDR-registered imaging OEMs.
Industry Challenges
- Piezoelectric transducer bonding expertise:Specialized fabrication technicians capable of acoustic impedance matching between crystal substrates and RF drivers remain scarce across European and North American facilities.
- Dual certification timelines:Simultaneous FDA 21 CFR 1040 laser product standards and EU MDR conformity assessments for surgical laser systems extend market entry cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acousto Optic Devices Market |
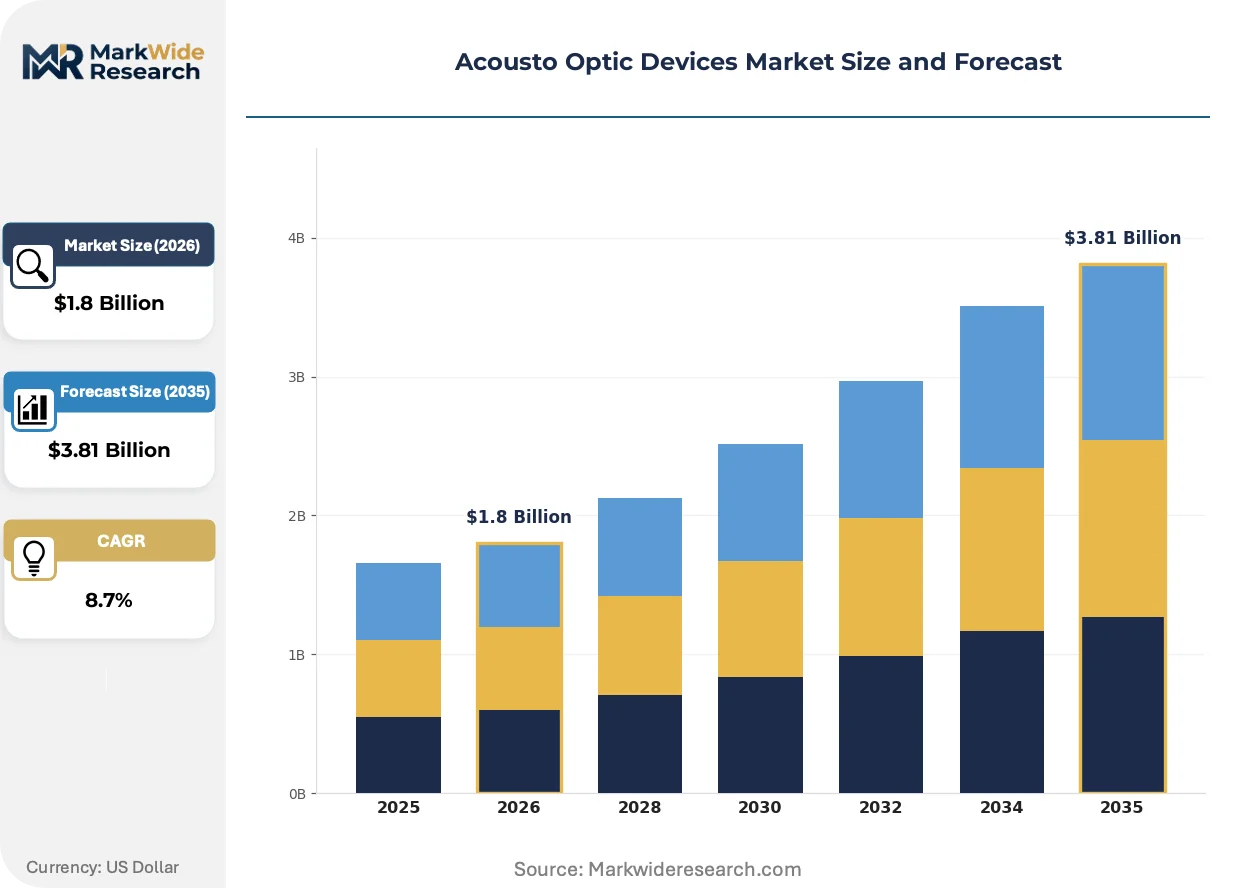
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modulators, Deflectors, Programmable Filters, Q-switches Technology: Fiber-based, Bulk Wave, Integrated, Surface Acoustic Wave End User: Telecommunications, Medical Imaging, Defense, Industrial Testing Application: Laser Tuning, Beam Steering, Signal Processing, Optical Sensing |
| Companies Covered | Gooch and Housego PLC, Brimrose Corporation of America, Isomet Corporation, Coherent Corp., L3Harris Technologies Inc., AMS Technologies AG, IntraAction Corp., AA Opto Electronic, Hamamatsu Photonics K.K., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acousto Optic Devices Market Emerging Trajectories
Acousto-optic technology is compressing response times while expanding into ambient-condition sensing nodes, reshaping how laser systems manage beam properties without mechanical actuation.
Surface acoustic wave architectures are automating beam steering in compact industrial inspection heads. Machine vision integrators in automotive assembly plants are adopting these solid-state solutions at pace, replacing galvo-mirror assemblies. The technology is automating real-time defect detection workflows that previously required offline metrology stations.
REACH amendments on critical raw materials are tightening documentation burdens for tellurium dioxide supply chains. ECHA's evolving substance restrictions are forcing crystal growers to requalify alternative optical-grade materials. European modulator suppliers are responding by accelerating fused silica and germanium substrate development programs.
Buying committees in semiconductor capital equipment are unbundling acousto-optic subassemblies from complete laser system contracts. Tier-one wafer processing OEMs are establishing direct component sourcing relationships, bypassing traditional laser integrator channels. This pattern is most visible in Germany and South Korea, where fab operators specify modulator performance independently of source laser procurement.
Acousto Optic Devices Market Segmentation
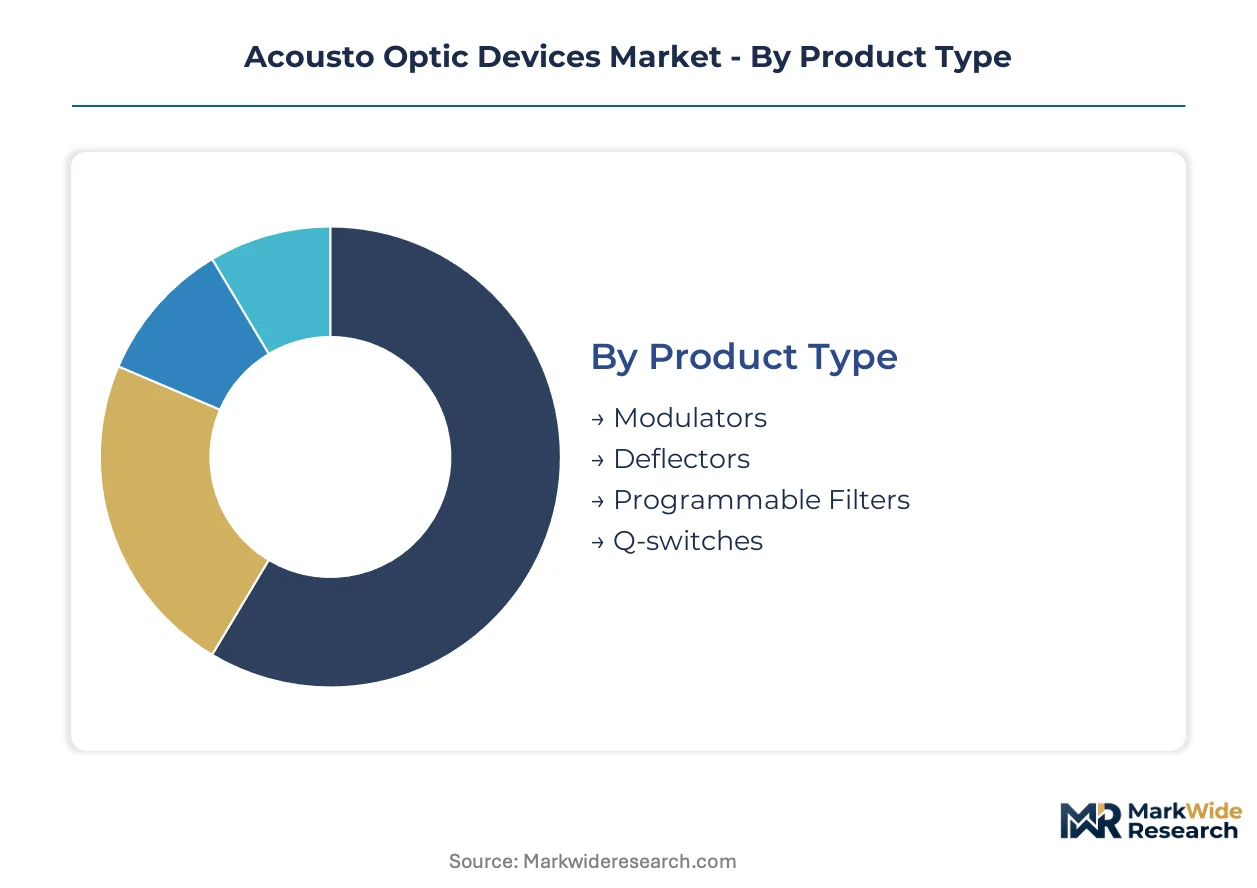
Acousto-optic device procurement patterns diverge sharply across application contexts, with semiconductor capital equipment buyers prioritizing rapid amplitude control while medical imaging OEMs emphasize programmable spectral filtering. Understanding these segment boundaries reveals where component suppliers can bypass traditional laser integrator channels.
Product Type:
Upgrade cycles in precision optical equipment accelerate when thermal management architectures face regulatory redesign, forcing buyers to reassess modulator performance specifications against new cooling constraints.
- Modulators:These devices impose traveling acoustic waves onto tellurium dioxide or fused silica crystals to vary laser beam intensity with microsecond response times. Semiconductor manufacturing lines in Germany and South Korea are pulling volumes from defense contractors, concentrating orders in high-throughput wafer processing where continuous-wave laser power demands rapid amplitude control.
- Deflectors:Beam deflection occurs through frequency-shifted diffraction gratings generated by piezoelectric transducers bonded to optical-grade substrates. Machine vision integrators in automotive assembly plants are adopting solid-state deflection for robotic inspection systems, displacing mechanical galvo-mirror assemblies in space-constrained deployments.
- Programmable Filters:Spectral selection devices enable wavelength-tunable operation in dense wavelength-division multiplexing systems.
- Q-switches:Pulsed laser cavity control components manage optical feedback for high-peak-power materials processing applications.
Modulators sit at the top of the volume ranking, with deflectors climbing the fastest as industrial automation replaces mechanical beam steering.
Technology:
Cost tier differentiation separates premium crystal-growth-dependent architectures from emerging thin-film alternatives that reduce tellurium dioxide exposure.
- Fiber-based:Acousto-optic interaction occurs within optical fiber cores, enabling compact packaging for telecom infrastructure. China's MIIT enforces divergent GB standards on these devices, creating compliance barriers that favor suppliers with front-loaded multi-region certification investment.
- Surface Acoustic Wave:Interdigitated transducers on piezoelectric substrates generate acoustic waves at the material surface rather than through bulk propagation. REACH amendments on critical raw materials are accelerating fused silica and germanium substrate development programs as European crystal growers requalify alternative optical-grade materials.
- Bulk Wave:Traditional architectures propagate acoustic energy through entire crystal volumes for high-power handling.
- Integrated:Silicon photonics-compatible implementations merge acousto-optic functionality with CMOS fabrication processes.
Fiber-based technology holds the dominant revenue position, while surface acoustic wave architectures gain share fastest in compact sensing nodes.
End User:
Customer type fragmentation creates divergent procurement rhythms, with defense buyers emphasizing long-term supply security and semiconductor fabs prioritizing throughput optimization.
- Telecommunications:National fiber infrastructure builds drive demand for wavelength-selective components. India's PLI scheme for telecom equipment is drawing assembly capacity toward domestic acousto-optic module fabrication, redirecting supply chain gravity.
- Semiconductor Manufacturing:Laser tuning applications in wafer processing equipment concentrate order volumes from tier-one OEMs establishing direct component sourcing relationships.
- Medical Imaging:Programmable filter subassemblies are separating from complete system sales under EU MDR conformity requirements, opening component-level contracts with registered imaging OEMs.
- Defense:Secure communications and directed energy applications demand specialized packaging for harsh environments.
Telecommunications maintains volume leadership, with semiconductor manufacturing expanding most quickly as laser tuning requirements intensify.
Application:
Margin structures vary by functional complexity, with beam steering commanding premium pricing in industrial automation while signal processing faces commoditization in legacy telecom segments.
- Laser Tuning:Rapid frequency and amplitude adjustment enables precision materials processing and spectroscopic analysis. EU F-Gas Regulation compliance is tightening procurement criteria for precision optical systems across European semiconductor fabs, compressing development cycles for thermal-managed tuning architectures.
- Beam Steering:Non-mechanical angular deflection eliminates inertial limitations of mirror-based systems. FDA 21 CFR 1040 laser product performance standards govern surgical laser system integrations, extending dual certification timelines with EU MDR assessments.
- Signal Processing:Radio-frequency spectrum analysis and frequency-shifting operations in test equipment.
- Optical Sensing:Environmental and structural monitoring through interferometric detection schemes.
Laser tuning dominates current revenue, with beam steering gaining share fastest as solid-state architectures displace mechanical alternatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acousto-optic device manufacturing traces its commercial roots to post-war optics laboratories in Germany and the United States, where crystal growth techniques for tellurium dioxide modulators first achieved industrial scale. German research institutes in Jena established the foundational fabrication protocols that spread to UK and US defense contractors during the Cold War. Today's production geography reflects this bifurcated heritage, with precision crystal growth concentrating in Central European clusters and RF-integrated packaging gravitating toward East Asian electronics manufacturing centers.
Germany
Semiconductor capital equipment manufacturers in Dresden and Munich drive modulator demand for laser tuning in wafer processing. The EU F-Gas Regulation forces thermal management redesigns in precision optical systems, compressing procurement cycles for compliant cooling architectures. Applied research institutes around Jena feed directly into component suppliers, creating tight feedback loops between crystal fabrication and end-use prototyping.
United States
Defense contractors and directed energy programs sustain demand for high-power modulator cores with specialized harsh-environment packaging. FDA 21 CFR 1040 laser product performance standards govern surgical laser system integrations, extending dual certification timelines with EU MDR assessments. Photonics manufacturing concentrates in Greater Boston and the Southwest, where defense primes maintain captive crystal growth capabilities.
China
National fiber infrastructure builds drive wavelength-selective component demand for dense wavelength-division multiplexing systems. MIIT enforces divergent GB standards on fiber-based devices, creating compliance barriers that favor suppliers with front-loaded multi-region certification investment. Yangtze River Delta electronics assemblers are expanding acousto-optic module fabrication capacity for domestic telecom equipment production.
Japan
Machine vision integrators in automotive assembly plants adopt solid-state beam deflection for robotic inspection systems. METI industrial automation initiatives accelerate surface acoustic wave adoption in compact sensing nodes. Hamamatsu anchors photodetector-through-assembly vertical integration, controlling component supply from crystal substrates to finished beam steering modules.
India
The PLI scheme for telecom equipment draws assembly capacity toward domestic acousto-optic module fabrication for national fiber infrastructure builds. TRAI spectrum allocation policies shape demand patterns for wavelength-tunable components in expanding 5G backhaul networks. Bengaluru and Hyderabad electronics manufacturing clusters host emerging packaging operations for fiber-based device assembly.
Acousto Optic Devices Market Vendor Landscape
Premium-margin players sit above commodity-margin players across crystal growth control and RF driver integration capabilities. The vendor base stratifies into three tiers: integrated photonics conglomerates with captive crystal supply, specialized acousto-optic fabricators with dedicated bonding facilities, and contract assemblers serving price-sensitive telecom segments. Two competitive moves dominate current positioning: backward integration into tellurium dioxide crystal growth to secure raw material access, and strategic partnerships with semiconductor capital equipment OEMs to bypass traditional laser integrator channels.
Among UK and US-based specialists, Gooch and Housego PLC and Brimrose Corporation of America exemplify the dedicated fabrication archetype, occupying positions built on proprietary bonding expertise and long-standing defense relationships. Coherent Corp. represents the integrated conglomerate tier, leveraging in-house crystal growth to control modulator core supply. These three anchors illustrate how competitive positioning diverges between captive supply strategies and specialized component focus.
| Leading Market Players |
|---|
| Gooch and Housego PLC |
| Brimrose Corporation of America |
| Isomet Corporation |
| Coherent Corp. |
| L3Harris Technologies Inc. |
| AMS Technologies AG |
| IntraAction Corp. |
| AA Opto Electronic |
| Hamamatsu Photonics K.K. |
| Others |
Supply Flow & Price Mechanics
Tier-one semiconductor capital equipment OEMs concentrate procurement power in direct component sourcing relationships, compressing margin structures for modulator suppliers while amplifying price sensitivity in fiber-based telecom segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the acousto-optic device landscape, with FDA 21 CFR 1040 and EU MDR certification tiers commanding substantial premiums over uncertified industrial-grade alternatives. Price differentiation hinges on crystal growth provenance and thermal management compliance under EU F-Gas Regulation standards. Cost compression in fiber-based telecom modules is intensifying because India's PLI scheme draws assembly capacity toward domestic fabrication. Semiconductor manufacturing buyers exhibit lowest price sensitivity due to throughput-critical specifications, while contract assemblers serving price-sensitive telecom segments face relentless margin pressure.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Japan anchor hub-and-spoke patterns for precision optical components, with Jena-based crystal fabricators feeding directly into Dresden and Munich semiconductor equipment clusters. Tellurium dioxide, fused silica substrates, and piezoelectric transducers constitute critical input dependencies, with sourcing economics tethered to REACH amendment scrutiny on critical raw materials. Single-source vulnerability concentrates in specialized crystal growth capabilities for modulator cores. Distribution runs through semiconductor capital equipment OEMs establishing direct supplier relationships, bypassing traditional laser integrator channels in Germany and South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acousto-optic devices market compounds steadily as semiconductor manufacturing laser tuning requirements intensify across wafer processing applications, sustaining durable demand for precision optical components.
For Market Incumbents: To counter fiber laser substitution in low-power materials processing, Coherent Corp. and Gooch and Housego PLC should accelerate fused silica and germanium substrate development programs while deepening captive supply of tellurium dioxide crystal growth. Backward integration into raw material access and strategic partnerships with tier-one wafer processing OEMs in Germany and South Korea bypass threatened laser integrator channels. For New Entrants and Emerging Players: Direct digital sales channels to machine vision integrators in Japanese automotive assembly plants offer the most penetrable entry vector, with surface acoustic wave deflectors displacing mechanical galvo-mirror assemblies in space-constrained robotic inspection systems. Target India's PLI scheme telecom equipment production incentives for domestic acousto-optic module assembly, leveraging Bengaluru and Hyderabad electronics manufacturing clusters for fiber-based device packaging. For Investors and Strategic Acquirers: Semiconductor capital equipment OEMs are the most active acquirer in this space, seeking programmable filter subassembly capabilities under EU MDR conformity requirements. The acquisition target archetype comprises specialized acousto-optic fabricators with proprietary piezoelectric transducer bonding expertise and dedicated UK or US fabrication facilities. Watch REACH amendment enforcement on tellurium compounds as the inflection signal for alternative substrate qualification timelines and supply relationship requalification costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crystal Growth | Captive tellurium dioxide supply secures modulator core availability against REACH amendment sourcing friction. |
| Surface Acoustic Wave Product Line Expansion | Compact sensing nodes for Japanese automotive machine vision displace bulk wave architectures in robotic inspection. |
| India PLI Scheme Manufacturing Localization | Domestic acousto-optic module fabrication captures national fiber infrastructure build demand. |
| Dual FDA-EU MDR Certification Investment | Simultaneous surgical laser system compliance opens component-level contracts with registered imaging OEMs. |
| Direct OEM Partnership Bypass Strategy | Tier-one semiconductor capital equipment relationships circumvent threatened laser integrator channel concentration. |
Methodological Framework
Multiple input streams — primary interviews with crystal growth specialists, RF driver engineers, and semiconductor capital equipment procurement leads; secondary validation through SEC filings, ECHA substance restriction updates, and MIIT GB standard publications; customs and trade data on tellurium dioxide flows — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, technology architecture, end-use vertical, and application function segmentation dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from fitted growth curves calibrated against historical procurement patterns in telecommunications infrastructure and semiconductor manufacturing capital equipment. Crystal substrate qualification timelines under evolving REACH amendments and India's PLI scheme capacity absorption rates served as industry-specific forecast inputs.
Regulatory enforcement intensity on F-Gas thermal management compliance, REACH critical raw materials restrictions, and divergent multi-region certification timelines are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market
Optical Components
Package Shell for Optical Communication Modules Market
Optical Components
Distributed Fiber Optic Sensor (DFOS) Market
Optical Components
CW Fiber Amplifier Market
Optical Components
Spatial Light Modulator Market
Optical Components
CVD Sic Ring Market
Optical Components
Photomask Pellicle Market
Optical Components
South Korea Optical Detector Market
Optical Components
Polarizer Film Market
Optical Components
Flip-Chip VCSEL Market
Optical Components
Photointerrupter Market
Optical Components
Coherent Optical Equipment Market
Optical Components
Optical Waveguide Market
Optical Components
High Power Double-Clad Fiber Bragg Grating Market
Optical Components
Optical Frequency Domain Reflectometer Market
Optical Components
Global Optical Connectivity Solutions Market