
 Thermal Management Systems Market | 2026-2036
Thermal Management Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Management Systems Market Analytics
Software-defined thermal control is pivoting how vendors monetize hardware deployments, shifting revenue toward predictive analytics subscriptions and remote optimization services. Honeywell International Inc. leverages its building automation software stack to bundle thermal oversight into enterprise energy contracts. Vertiv Co. anchors its data center footprint with service agreements that guarantee power usage effectiveness through dynamic cooling adjustments. Delta Electronics, Inc. competes on liquid cooling controller integration, embedding firmware that enables real-time thermal load balancing for server racks.
Thermal management systems encompass engineered assemblies of heat transfer components, coolants, control electronics, and interface materials designed to maintain operating temperatures within specified ranges across mechanical and electrical equipment. These systems employ liquid loops, vapor chambers, conductive pads, or forced convection to dissipate heat flux densities that can exceed 100 W/cm² in advanced semiconductor packages. Active cooling and liquid cooling segments lead in absolute revenue due to their dominance in data center and electric vehicle applications, while nanofluids represent the fastest-growing technology category as researchers demonstrate enhanced thermal conductivity with stabilized nanoparticle suspensions. Thermal interface materials command premium margins because formulation expertise in silicone greases, phase change alloys, and graphite sheets creates significant differentiation barriers.
The EPA tailpipe standards and NHTSA fuel economy mandates in the United States force automotive suppliers to redesign thermal loops for battery-electric and hybrid powertrains. The EU F-Gas Regulation and CE marking requirements restrict refrigerant choices and impose testing protocols that shape product development roadmaps for European market access. Stakeholders must monitor how the EU AI Act and evolving energy efficiency labeling rules intersect with smart thermal control systems, as compliance complexity will determine which vendors can sustain cross-border deployment scale.
Market Dynamics
The collision between EPA and NHTSA tailpipe mandates and OEM battery energy density targets is forcing simultaneous redesign of thermal loops across powertrain architectures. Suppliers must now engineer systems that handle 100 W/cm² heat flux densities while meeting refrigerant restrictions under the EU F-Gas Regulation.
Growth Catalysts
- Electric vehicle battery pack cooling:OEMs pursuing higher energy densities require liquid-cooled architectures that stabilize cell temperatures during fast-charging cycles.
- Dual carbon goals in China:National production scaling targets for EVs concentrate demand for advanced thermal management assemblies.
- Data center power usage effectiveness mandates:Dynamic cooling adjustments are becoming contractual obligations in enterprise energy agreements.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger and cold plate manufacturing faces margin compression from commodity input swings.
- Refrigerant supply concentration:EU F-Gas Regulation phase-downs restrict hydrofluorocarbon availability for automotive and HVAC applications.
- Thermal interface material formulation complexity:Silicone grease and phase change alloy expertise remains concentrated among specialized compounders.
Strategic Opportunities
- India automotive thermal systems:PLI scheme incentives for domestic EV component manufacturing create localized assembly demand.
- Predictive analytics subscriptions:Software-defined thermal control enables recurring revenue from remote optimization services.
- Nanofluid coolants:Stabilized nanoparticle suspensions with enhanced thermal conductivity are penetrating high-performance computing and EV segments.
Industry Challenges
- Multiphysics simulation talent scarcity:CFD and thermal modeling expertise for liquid cooling controller firmware development commands premium compensation.
- CE marking and EU AI Act intersection:Smart thermal control systems face overlapping compliance timelines for safety and algorithmic transparency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Management Systems Market |
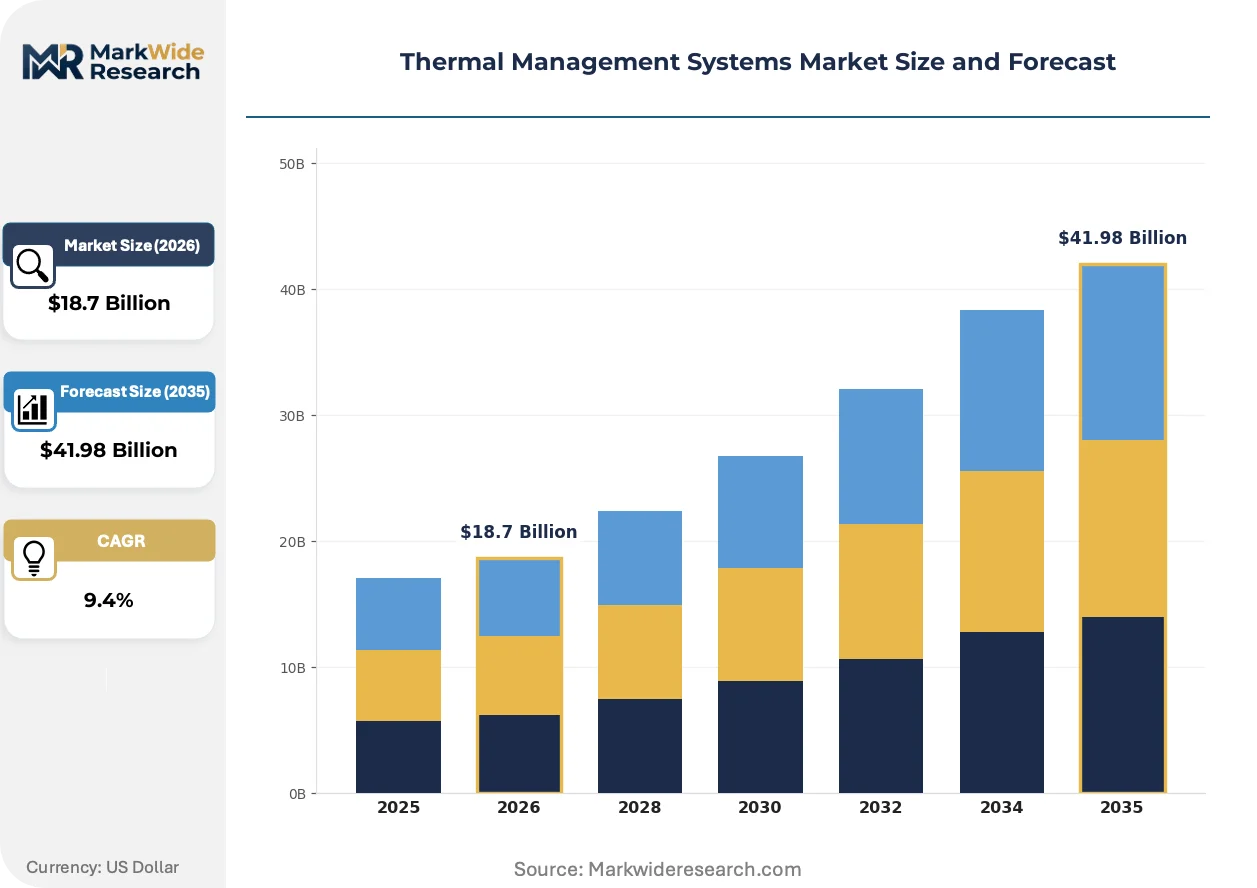
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Cooling, Passive Cooling, Heat Exchangers, Thermal Interface Materials End User: Consumer Electronics, Automotive, Aerospace, Data Centers Technology: Liquid Cooling, Air Cooling, Phase Change Materials, Nanofluids Application: HVAC Systems, Electronic Devices, Industrial Equipment, Renewable Energy |
| Companies Covered | Honeywell International Inc., Vertiv Co., Delta Electronics, Inc., Henkel, Parker-Hannifin Corporation, Boyd Corporation, Gentherm Incorporated, Laird Thermal Systems, Advanced Cooling Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Management Systems Market Evolving Landscape
Software-defined control architectures are displacing fixed-function thermal hardware across data center and automotive deployments. Vendors now compete on firmware integration and predictive capability rather than component specifications alone.
Liquid cooling with embedded controllers is expanding into server rack architectures. Hyperscale operators are adopting direct-to-chip cold plates with real-time thermal load balancing firmware. This expansion is compressing the addressable market for traditional air-cooled infrastructure and forcing incumbent HVAC suppliers to acquire liquid cooling IP.
The EU F-Gas Regulation is accelerating refrigerant transition timelines for automotive suppliers. Natural refrigerants and low-global-warming-potential alternatives are displacing conventional hydrofluorocarbons in heat pump and battery conditioning loops. European OEMs are responding by qualifying CO₂ and propane-based systems ahead of 2027 phase-down milestones.
Service unbundling is fragmenting how buyers procure thermal oversight. Data center operators are separating hardware capex from optimization subscriptions, with guarantees tied to measured power usage effectiveness. This pattern is most visible in North American and Western European enterprise contracts where energy cost accountability has shifted to thermal management vendors.
Thermal Management Systems Market Segmentation
Thermal management systems fragment across hardware configurations, cooling methodologies, and end-use thermal loads. Upgrade cycles vary dramatically — data center liquid cooling refreshes every 3-4 years while industrial HVAC installations persist for 15-20 years. Vendors must calibrate R&D pipelines and service architectures to these diverging replacement rhythms.
Product Type:
Replacement-cycle timing dictates how vendors structure service revenue and inventory commitments across hardware categories.
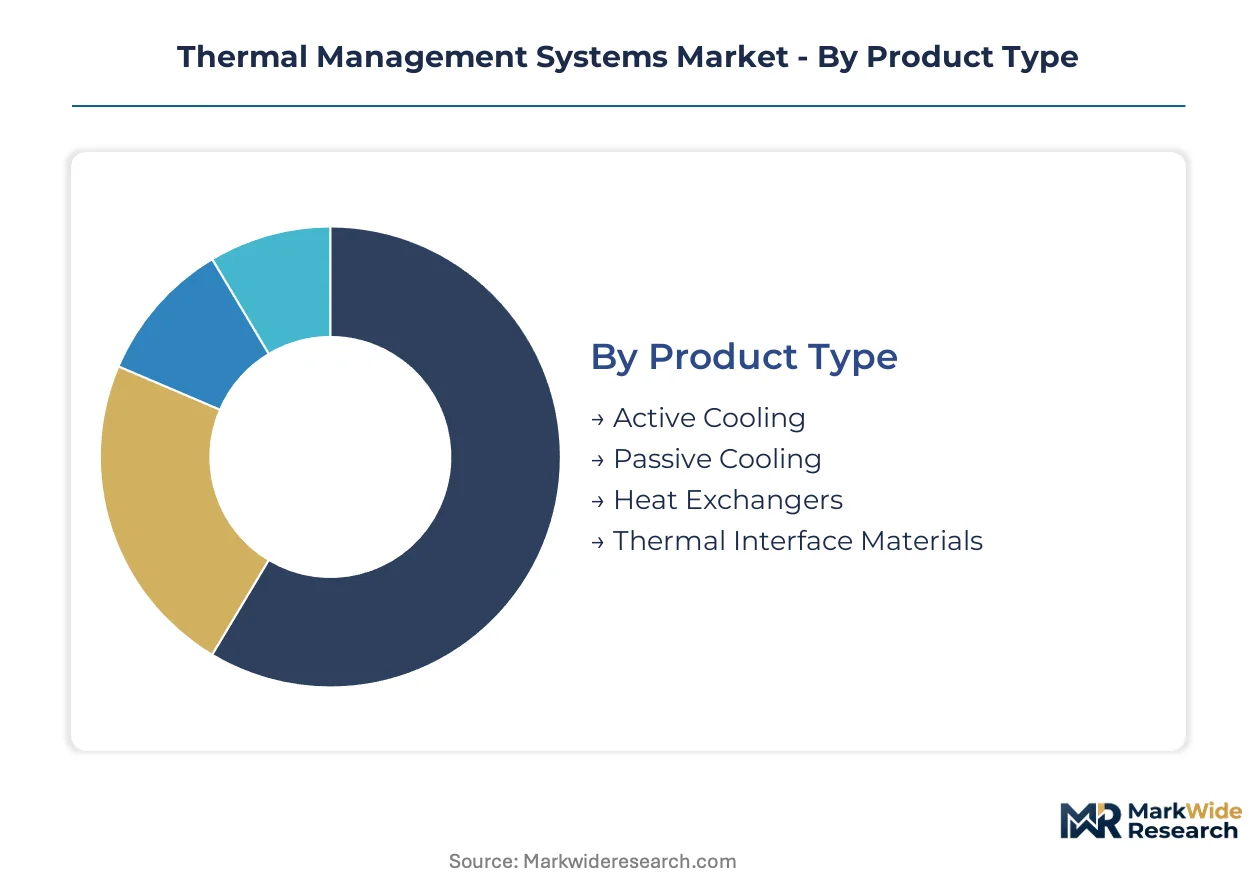
- Active Cooling:Pump-driven liquid loops and forced-air assemblies dominate high-heat-flux applications above 100 W/cm². Data center operators in the United States and Germany now specify active cooling as a contractual requirement in power usage effectiveness agreements.
- Thermal Interface Materials:Silicone greases, phase change alloys, and graphite sheets bridge component-to-heatsink junctions. Formulation expertise concentrates among specialized compounders serving semiconductor packaging facilities in Taiwan and South Korea.
- Passive Cooling:Heat sinks and natural convection designs serve cost-sensitive consumer electronics where acoustic neutrality matters.
- Heat Exchangers:Aluminum and copper assemblies transfer thermal energy between fluid loops in automotive and industrial process applications.
Active Cooling sits at the top of the volume ranking, with Thermal Interface Materials climbing the fastest.
End User:
Application-specific thermal budgets and reliability requirements create distinct procurement patterns across verticals.
- Automotive:Battery pack cooling and powertrain thermal loops handle escalating heat densities from fast-charging architectures. OEMs in China and the United States now qualify liquid-cooled systems for 800V platforms.
- Data Centers:Hyperscale operators deploy direct-to-chip cold plates with embedded controller firmware. Power usage effectiveness mandates from the EU Energy Efficiency Directive and corporate sustainability targets accelerate liquid cooling adoption.
- Consumer Electronics:Smartphones and laptops rely on vapor chambers and graphite sheets to manage processor thermal envelopes within millimeter-thin form factors.
- Aerospace:Satellites and avionics demand lightweight, radiation-hardened thermal control with extreme reliability margins.
Data Centers command the steepest expansion trajectory, while Aerospace maintains the highest specification premiums.
Technology:
Heat transfer efficiency and system complexity determine where each technology penetrates versus incumbent alternatives.
- Liquid Cooling:Closed-loop systems with dielectric or water-glycol coolants extract heat from concentrated sources. Server rack deployments in the United States and Netherlands now specify liquid cooling for AI training clusters exceeding 500 kW per rack.
- Nanofluids:Stabilized nanoparticle suspensions in ethylene glycol or water enhance thermal conductivity. Research demonstrations at national laboratories in Japan and Germany are accelerating qualification for electric vehicle battery conditioning.
- Air Cooling:Forced convection through finned heat sinks remains the default for low-to-moderate heat flux applications.
- Phase Change Materials:Paraffin and salt hydrate formulations absorb latent heat during solid-liquid transitions for transient thermal buffering.
Liquid Cooling leads absolute deployment volume, with Nanofluids gaining share fastest in high-performance computing and automotive segments.
Application:
Operating environment and thermal duty cycle shape hardware selection and maintenance protocols.
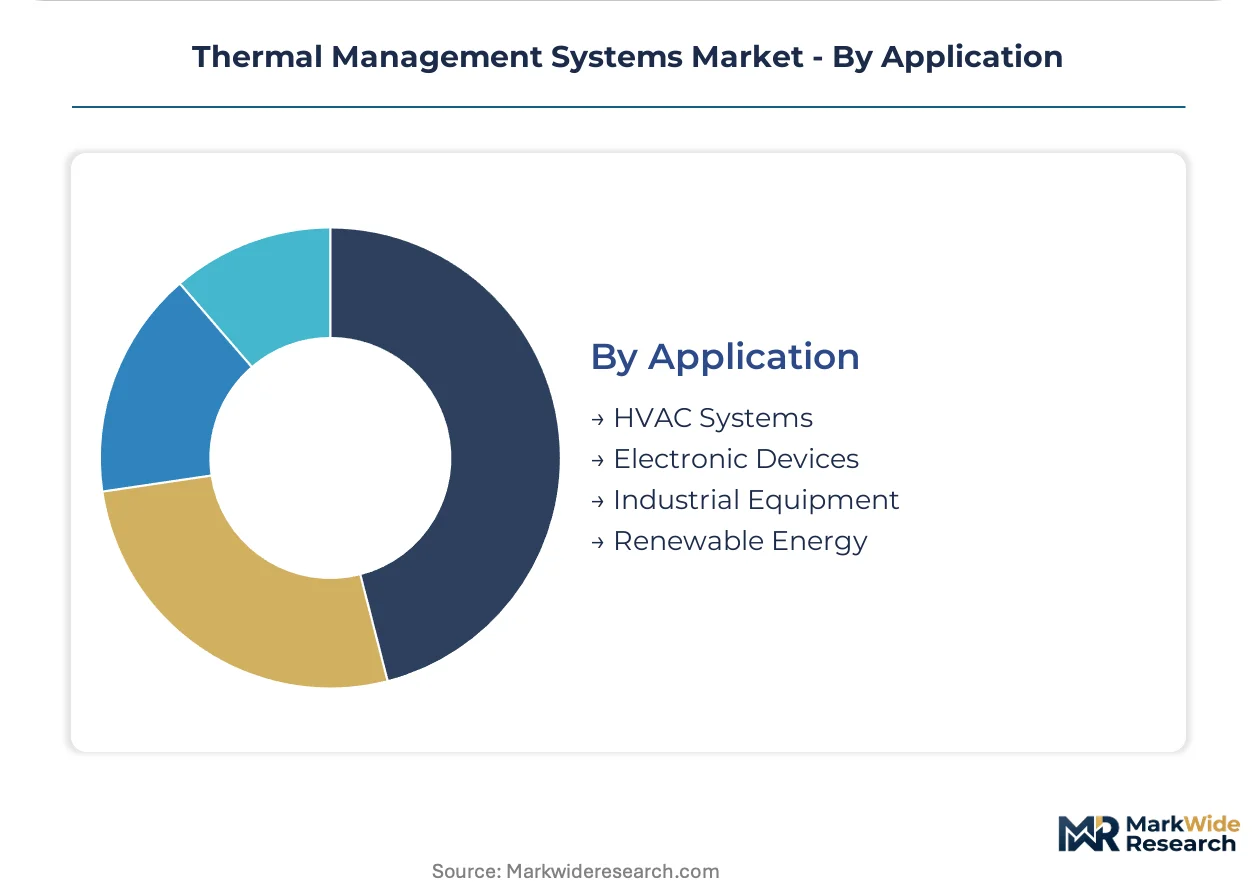
- Electronic Devices:Smartphones, servers, and power electronics require compact thermal solutions with rapid transient response. Consumer demand for thinner devices in South Korea and the United States compresses design margins.
- HVAC Systems:Building climate control and refrigeration loops face refrigerant transition pressure under the EU F-Gas Regulation. Natural refrigerant adoption in Germany and France is outpacing hydrofluorocarbon phase-down timelines.
- Industrial Equipment:Motor drives, welding systems, and process machinery deploy robust air-cooled or liquid-cooled architectures with extended service intervals.
- Renewable Energy:Solar inverters and wind turbine power electronics require outdoor-rated thermal management with wide temperature operating ranges.
Electronic Devices anchor current volume, while Renewable Energy applications are expanding most quickly alongside capacity installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting thermal management system production toward jurisdictions where compliance costs and energy pricing create manufacturing advantages. OEMs now site battery pack cooling assembly capacity based on F-Gas Regulation phase-down timelines and carbon border adjustment exposure.
United States
EPA tailpipe standards and NHTSA fuel economy mandates compress development timelines for automotive thermal architectures. The Inflation Reduction Act's domestic content bonuses accelerate localized battery cooling system production. Detroit-area suppliers now qualify liquid-cooled platforms for 800V fast-charging EVs.
Germany
EU F-Gas Regulation restrictions on hydrofluorocarbons force refrigerant transitions in automotive heat pumps. CE marking requirements and the EU AI Act impose overlapping compliance burdens on smart thermal control systems. Stuttgart industrial clusters are qualifying CO₂-based battery conditioning loops ahead of 2027 phase-down milestones.
China
Dual carbon goals and aggressive EV production scaling concentrate demand for advanced thermal management assemblies. MIIT efficiency mandates and GB standards shape product specifications for domestic battery manufacturers. Shenzhen and Shanghai suppliers now dominate liquid cooling controller production for export markets.
India
PLI scheme incentives for domestic EV component manufacturing create localized assembly demand for battery pack cooling systems. BIS certification requirements and DGFT import substitution policies protect emerging suppliers. Tamil Nadu and Gujarat industrial corridors are attracting thermal interface material compounders serving semiconductor packaging facilities.
Japan
METI energy efficiency directives and JIS standards govern data center cooling equipment specifications. National laboratory research on nanofluid suspensions accelerates qualification for high-performance computing applications. Tokyo and Osaka metropolitan areas host specialized vendors developing phase change materials for consumer electronics thermal buffering.
Thermal Management Systems Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with component suppliers commanding premium margins in thermal interface materials while system integrators capture volume in automotive and data center deployments. The vendor base organizes into three tiers: diversified industrial conglomerates with cross-sector thermal portfolios, pure-play cooling specialists with deep firmware capabilities, and regional fabricators serving cost-sensitive HVAC replacement markets. Consolidation pressure is intensifying as refrigerant transitions and software-defined control architectures raise R&D minimums. Strategic moves center on acquiring liquid cooling IP and bundling hardware with predictive analytics subscriptions.
Among diversified industrial conglomerates, Honeywell International Inc. and Parker-Hannifin Corporation exemplify scale-driven positions spanning building automation and aerospace thermal control. Vertiv Co. and Delta Electronics, Inc. anchor the specialist tier, with the former representing data center infrastructure integration and the latter exemplifying power electronics and cooling controller convergence. These named entities occupy positions where firmware-enabled service revenue now rivals hardware margins in enterprise contract structures.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Vertiv Co. |
| Delta Electronics, Inc. |
| Henkel |
| Parker-Hannifin Corporation |
| Boyd Corporation |
| Gentherm Incorporated |
| Laird Thermal Systems |
| Advanced Cooling Technologies, Inc. |
| Others |
Value Network & Pricing Analysis
EU F-Gas Regulation phase-down mandates gate qualified supply and premium-tier pricing access for refrigerant-dependent thermal systems. OEMs purchasing battery conditioning loops must certify suppliers against natural refrigerant compatibility thresholds, compressing the vendor pool and supporting price premiums for qualified assemblies.
Pricing Analysis
Capacity additions in China are reshaping price floors for liquid cooling controllers and heat exchanger assemblies. Three-tier pricing structure across premium, standard, and economy levels reflects firmware capability and thermal interface material grade differentiation. Cost compression in economy-tier air-cooled hardware is intensifying because aluminum price volatility feeds directly into cold plate manufacturing. Automotive OEMs demonstrate highest price sensitivity due to volume procurement leverage, while data center operators prioritize power usage effectiveness guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Tier 1 automotive suppliers and hyperscale data center operators mandate multi-supplier qualification for critical thermal components. Geographic concentration centers on China for liquid cooling controller production, Taiwan for thermal interface material compounding, and Germany for precision heat exchanger fabrication. Raw material dependencies rest on copper and aluminum for conductive assemblies, ethylene glycol for coolant formulations, and specialized nanoparticles for nanofluid development. Single-source vulnerability concentrates in stabilized nanoparticle suspension supply for emerging EV battery conditioning applications. Distribution runs through direct OEM contracts for automotive and data center verticals, with industrial HVAC channeling through regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal management systems function as a stable compounder anchored by irreversible electrification trends across automotive and data center infrastructure. Regulatory mandates on refrigerant phase-downs and power usage effectiveness create sustained upgrade cycles that outpace macroeconomic volatility.
For Market Incumbents: Acquire liquid cooling controller firmware IP to defend against software-defined thermal control disruption. Consolidate thermal interface material formulation expertise through selective compounder acquisitions in Taiwan and South Korea. Battery-electric platform standardization by OEMs threatens margin compression for hardware-only suppliers. For New Entrants and Emerging Players: Channel partnerships with industrial HVAC retrofit contractors offer lowest-friction entry into building automation thermal oversight. India's PLI scheme for domestic EV component manufacturing represents the most penetrable geography for battery pack cooling assembly. Co-development agreements with national laboratory nanofluid research programs provide technical credibility without captive R&D infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for regional thermal interface material compounders because customer qualification timelines create sticky relationships that resist price-based switching. Five-to-ten-year viability hinges on refrigerant transition execution and software service attach rates. The signal to watch is hyperscale data center operator direct-to-chip cold plate qualification timelines accelerating beyond incumbent HVAC supplier response capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Liquid Cooling IP | Vertiv and Delta Electronics demonstrate firmware-enabled service revenue now rivals hardware margins in enterprise contracts. |
| Natural Refrigerant System Qualification | German automotive clusters advancing CO₂-based battery conditioning loops ahead of EU F-Gas Regulation 2027 milestones. |
| Nanofluid Coolant Development Partnership | Japan's national laboratory research accelerates qualification for high-performance computing and EV battery segments. |
| India PLI Scheme Localization | Tamil Nadu and Gujarat corridors attract thermal interface material compounders serving semiconductor packaging facilities. |
| Predictive Analytics Subscription Launch | Honeywell bundles thermal oversight into enterprise energy contracts through building automation software stack integration. |
Research Methodology
Multiple input streams — primary interviews with thermal system procurement leads at automotive OEMs and data center operators, secondary validation through SEC filings and hyperscaler capex disclosures, and trade data reconciliation — were synthesized to construct market estimates. Conversations with plant engineers at battery manufacturing facilities, firmware development leads at cooling controller specialists, and channel partners for industrial HVAC distribution provided operational ground-truth. Bottom-up unit demand modeling across vehicle production databases and data center power capacity installations was cross-checked against top-down thermal content-per-application assumptions.
Data-stream reconciliation across product type, cooling technology, end-use vertical, and regional regulatory cluster dimensions anchored the analytical framework. CAGRs were derived from segment-level growth rate blending weighted by base-year revenue contribution. Forecast inputs incorporated EV platform voltage architecture transitions, EU F-Gas Regulation phase-down compliance timelines, and hyperscale operator power usage effectiveness contractual obligations across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to refrigerant substitution pace and nanofluid suspension stability breakthroughs. Deviation in Chinese EV production scaling or EPA tailpipe standard stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Global Power Semiconductor Switches Market
Power Systems
Static VAR Compensator (SVC) Market
Power Systems
Distribution Voltage Regulator Market
Power Systems
Three-Phase String Inverter Market
Power Systems
Converter Modules Market
Power Systems
Smart Junction Box and Power Distribution Box Systems Market
Power Systems
Photovoltaic Inverters Market
Power Systems
Switch Mode Power Supply (SMPS) Market
Power Systems
Power Integrated Modules Market
Power Systems
AC DC Power Adapter Market
Power Systems
South America DC Distribution Network Market
Power Systems
Global Synchronous Motor Market
Power Systems
Wireless Battery Monitoring System Market
Power Systems
Thermoelectric Generator (TEG) Market
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market
Power Systems
Charge Pumps Market