
 Electric Actuator Market | 2026-2036
Electric Actuator Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Actuator Market Intelligence
Asian actuator foundries is recalibrating output mixes toward servo-grade and piezoelectric variants as OEMs diversify supply sources. Emerson Electric Co. leverages its process automation platform to anchor long-term contracts with petrochemical operators. Bosch Rexroth specializes in electromechanical drive systems for precision robotics, while ABB controls a significant installed base across power generation and marine applications.
An electric actuator converts electrical energy into mechanical force to position valves, dampers, or machinery components with stroke accuracies typically within 0.1 millimeters and response times under 50 milliseconds. Linear actuators dominate factory floor installations where straight-line valve positioning remains the standard requirement, while servo actuators capture the fastest expansion in semiconductor and medical robotics due to closed-loop feedback demands. The industry vertical split shows industrial automation and automotive assembly lines as mature volume centers, whereas healthcare and aerospace applications concentrate margin pools because of certification burdens and low-volume precision requirements.
The U.S. EPA enforces leakage thresholds under the Clean Air Act that compel facilities to replace pneumatic actuators with electric alternatives, while the EU F-Gas Regulation accelerates this displacement across European chemical plants. China's GB standards for industrial equipment efficiency, administered by SAMR, mandate minimum performance tiers that filter lower-specification imports from Southeast Asian suppliers. Stakeholders must monitor how IEC 61508 functional safety certifications evolve into de facto market access requirements for oil and gas deployments.
Market Dynamics
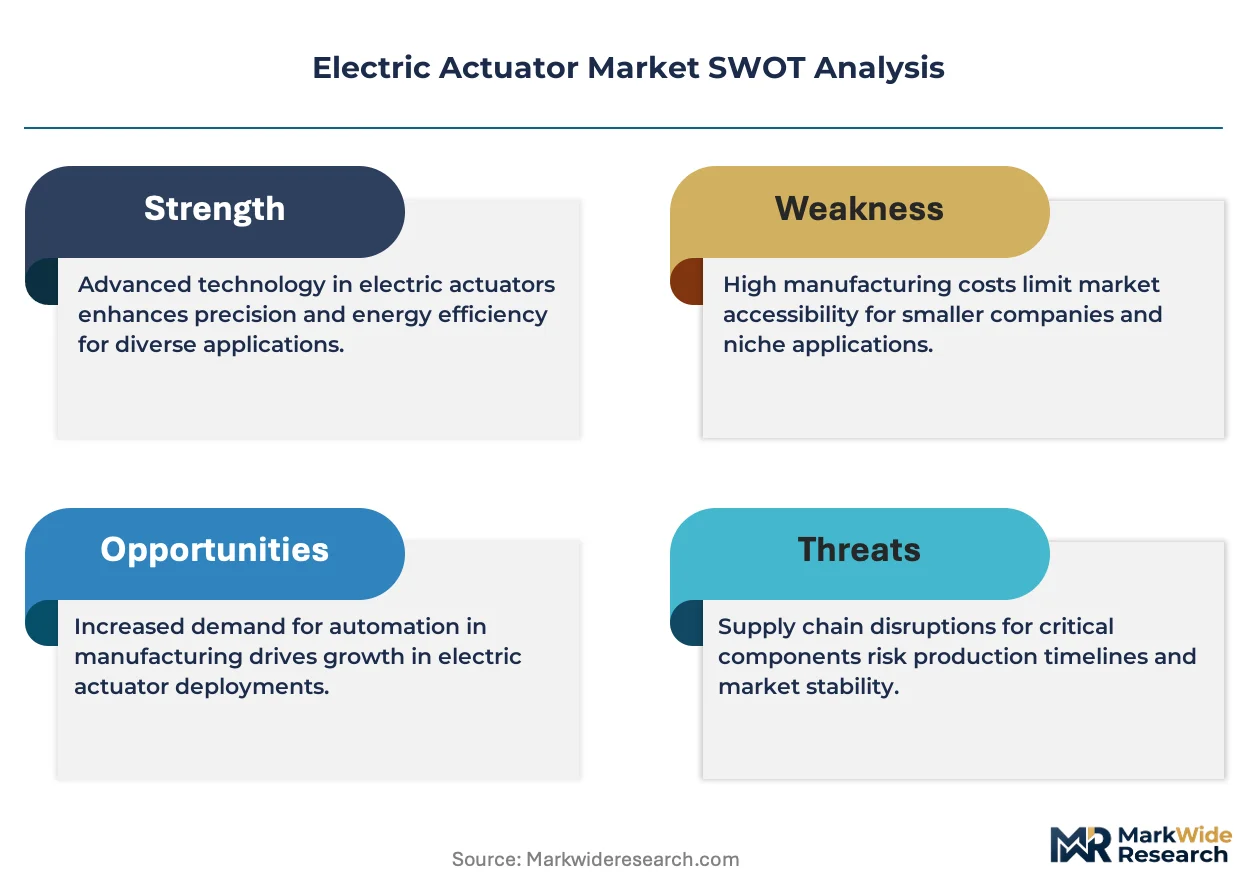
The displacement of pneumatic actuation by electric alternatives is compressing installed-base replacement cycles across process industries, with regulatory leakage mandates now dicting capital allocation timelines for facility operators.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon-based systems in European chemical plants is forcing direct electric actuator retrofits on valve assemblies previously served by gas-powered pneumatic units.
- Water treatment infrastructure:German and U.S. municipal utilities are procuring precision flow-control hardware to meet tightening effluent discharge standards under the EPA Clean Water Act and comparable state-level frameworks.
- Smart factory retrofits:China's eastern manufacturing corridor is absorbing high-torque electric positioning systems as legacy assembly lines integrate Industry 4.0 feedback architectures.
Market Restraints
- Permanent magnet cost volatility:Neodymium and dysprosium price swings from Chinese rare-earth processing concentration directly compress margin structures for servo-grade actuator producers.
- Foundry capacity bottlenecks:Asian casting and machining clusters face lead-time extensions for precision gearbox housings, constraining OEM output scalability.
- Pneumatic installed-base persistence:Compressed air infrastructure in mature automotive assembly plants creates switching-cost friction despite electric alternatives' efficiency advantages.
Strategic Opportunities
- Medical robotics certification:IEC 60601-1 compliance pathways for surgical positioning systems open premium-margin segments underserved by industrial-grade suppliers.
- India PLI scheme:Production-linked incentives for advanced manufacturing equipment create localized assembly incentives for mid-range linear actuator platforms.
- Digital twin integration:Convergence of electric actuators with real-time simulation software enables predictive maintenance contracts that capture recurring revenue streams.
Industry Challenges
- IEC 61508 functional safety certification:Oil and gas deployments require SIL-rated validation timelines that extend product qualification cycles and strain engineering bandwidth.
- Embedded software integration:Legacy distributed control systems in petrochemical facilities demand custom protocol gateways, complicating electric actuator commissioning and support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Actuator Market |
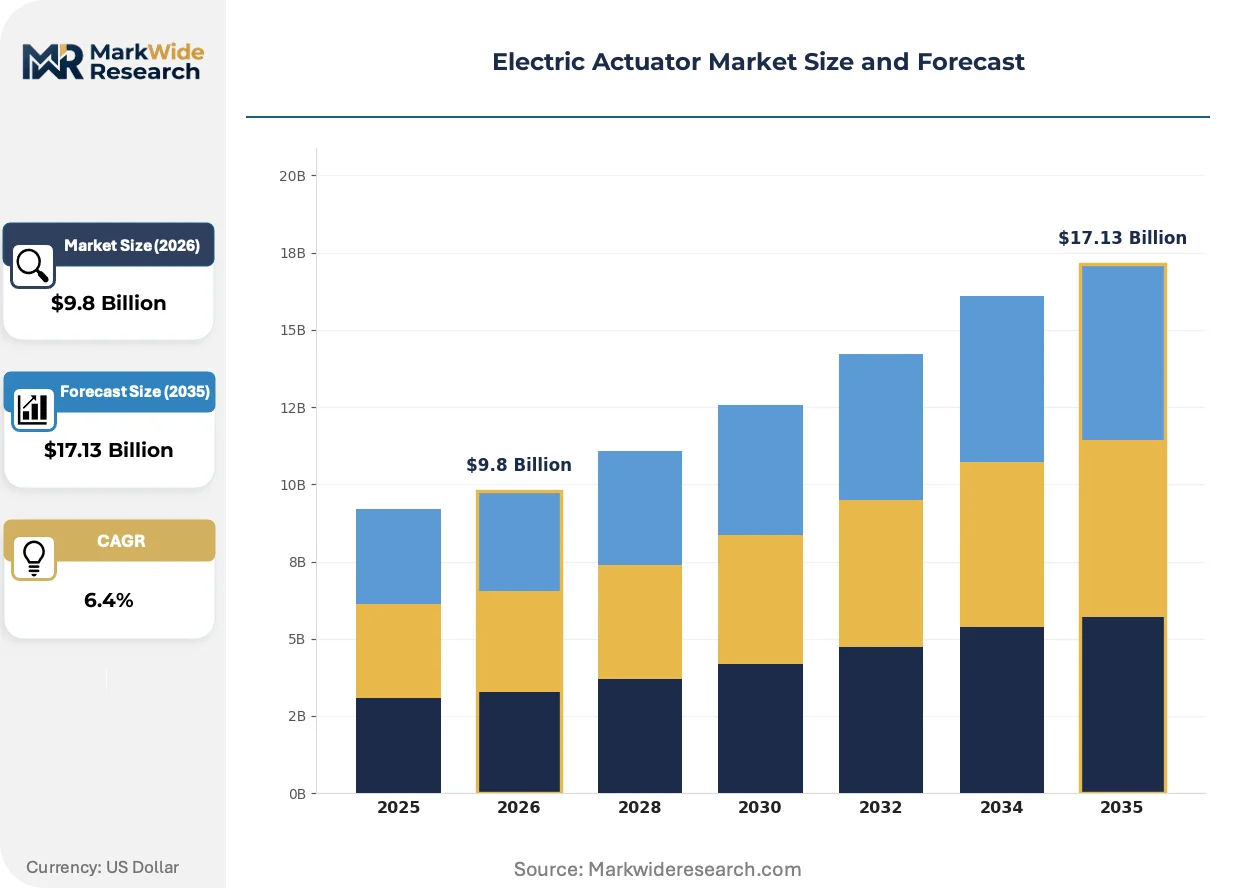
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.13 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Linear Actuators, Rotary Actuators, Servo Actuators, Voice Coil Motors Industry Vertical: Automotive, Aerospace, Robotics, Healthcare Technology: Electric, Piezoelectric, Magnetic, Hybrid Application: Manufacturing, Home Automation, HVAC Systems, Industrial Automation |
| Companies Covered | Rockwell Automation, Flowserve Corporation, Emerson Electric Co., Festo AG & Co. KG, Rotork plc, Parker Hannifin Corp, SMC Corporation, Bosch Rexroth, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Actuator Market Strategic Shifts & Innovations
Actuator architectures are bifurcating between commodity linear platforms and intelligent servo systems, with control electronics migration from centralized cabinets to edge-mounted drive modules.
Piezoelectric positioning stages are overtaking electromagnetic alternatives in semiconductor lithography and medical imaging applications where nanometer-scale resolution and zero-backlash response are non-negotiable. Taiwanese foundry equipment suppliers and German microscopy OEMs are standardizing on piezo stacks for wafer alignment stages. This shift is compressing addressable demand for conventional servo motors in precision positioning tiers above $50,000 per axis.
The U.S. EPA's methane emission reduction framework under the Inflation Reduction Act is accelerating electric actuator specification in natural gas transmission and storage facilities. Compressor station operators face escalating leak-detection repair thresholds that pneumatic systems cannot economically satisfy. Midstream infrastructure in the Permian Basin and Appalachian shale corridors is prioritizing electric valve automation to avoid penalty exposure.
Specification authority is migrating from maintenance departments to corporate sustainability offices, with procurement teams now weighting lifecycle carbon intensity alongside capital expenditure. Industrial distributors report elongated evaluation cycles as energy accounting and Scope 3 disclosure requirements complicate vendor qualification. This behavioral pivot is most pronounced in German automotive supply chains and Nordic process industries where CSRD reporting obligations have operationalized environmental procurement criteria.
Electric Actuator Market Segmentation
Electric actuator procurement decisions hinge on stroke precision, force requirements, and regulatory compliance burdens that vary sharply across motion-control architectures. Segment boundaries reflect not just technical specifications but certification pathways that gate market access in oil and gas, medical devices, and aerospace applications.
Type:
IEC 61508 functional safety certifications impose SIL-rated validation timelines on rotary and linear platforms destined for petrochemical facilities, while servo-grade variants face additional embedded software integration hurdles in legacy distributed control environments.
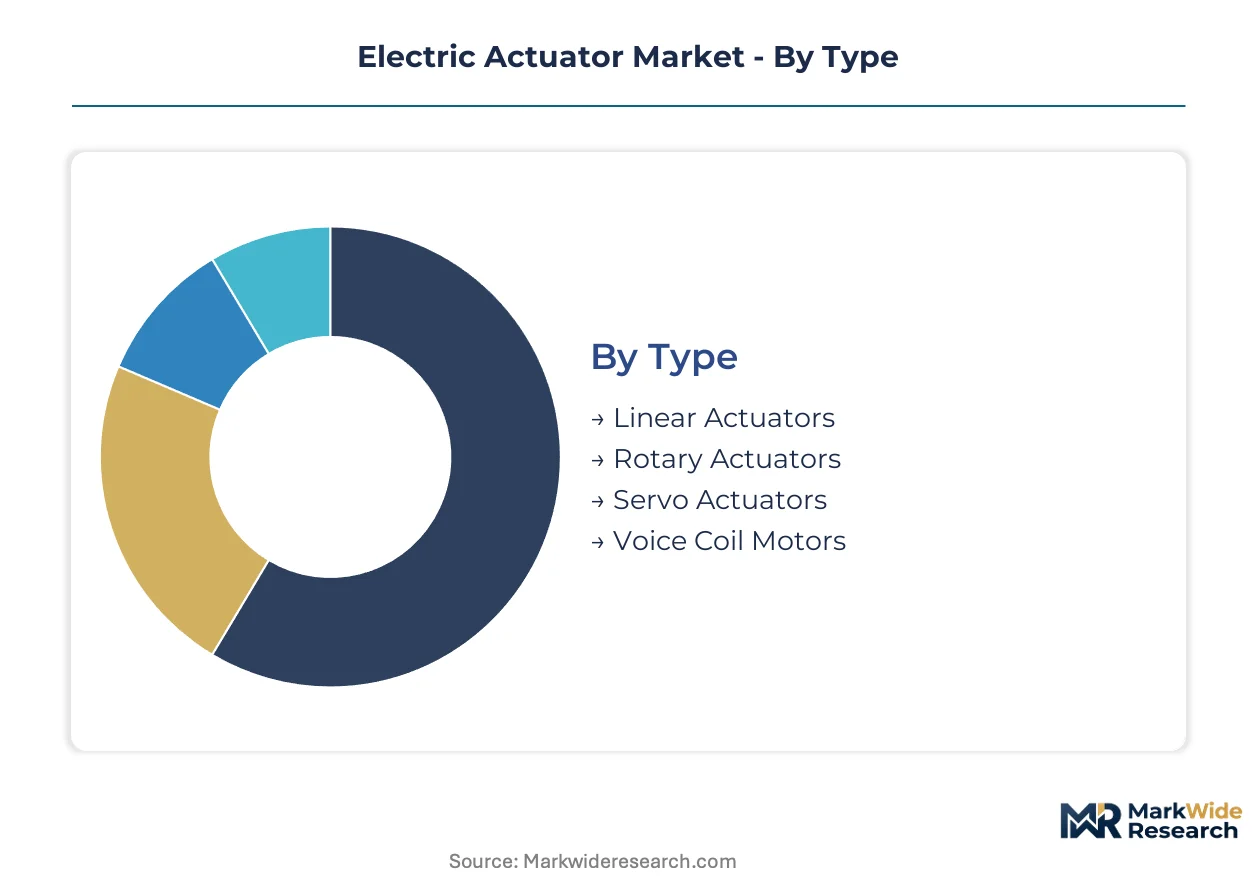
- Linear Actuators:These electromechanical devices convert rotational motor output into straight-line motion through lead screws or ball screws, achieving stroke accuracies within 0.1 millimeters. German automotive assembly plants and U.S. water treatment facilities specify these for valve positioning where straight-line force application remains the operational standard, though compressed air infrastructure in mature plants creates switching-cost friction despite efficiency advantages.
- Servo Actuators:Closed-loop feedback systems with response times under 50 milliseconds dominate semiconductor lithography and medical robotics where nanometer-scale resolution commands premium positioning. Taiwan's foundry equipment suppliers and German microscopy OEMs are absorbing these units fastest, with piezoelectric alternatives now compressing addressable demand above $50,000 per axis.
- Rotary Actuators:Torque-dense configurations for damper and butterfly valve control in power generation and marine applications.
- Voice Coil Motors:Direct-drive linear motors with zero cogging for optical focusing and precision dispensing equipment.
Linear actuators sit at the top of the volume ranking, with servo actuators climbing the fastest.
Industry Vertical:
Margin pools concentrate where certification burdens and low-volume precision requirements create defensive moats against commodity competition.
- Healthcare:Surgical positioning systems demand IEC 60601-1 compliance pathways that extend product qualification cycles and strain engineering bandwidth, opening premium-margin segments underserved by industrial-grade suppliers. Robotic surgery OEMs in the United States and Germany specify these for instrument manipulation where fault tolerance is non-negotiable.
- Aerospace:Flight control surface actuation and landing gear systems require DO-178C software assurance and DO-160 environmental qualification, with Boeing and Airbus tier-1 suppliers maintaining captive qualification laboratories that filter lower-specification entrants.
- Automotive:Battery assembly line automation and chassis positioning systems in EV manufacturing plants.
- Robotics:Collaborative robot joints and exoskeleton drive modules for logistics and rehabilitation applications.
Healthcare commands the steepest margin tier, with aerospace expanding most quickly as electric flight control retrofits accelerate.
Technology:
Permanent magnet cost volatility from Chinese rare-earth processing concentration directly compresses margin structures for electromagnetic variants, while piezoelectric stacks bypass this exposure through ceramic-based actuation.
- Piezoelectric:Ceramic-stack positioning stages deliver nanometer resolution and zero backlash for wafer alignment and medical imaging, with Taiwanese semiconductor equipment manufacturers and German microscopy OEMs standardizing on these architectures. This displacement is compressing servo motor demand in precision tiers where electromagnetic alternatives cannot match stiffness or settling time.
- Electric:Conventional electromagnetic architectures dominate factory floor installations where cost optimization outweighs extreme precision requirements.
- Magnetic:Linear motor configurations for high-speed transport and pick-and-place systems in electronics assembly.
- Hybrid:Combined electromagnetic and piezoelectric stages for multi-axis positioning with coarse-fine dual-range operation.
Electric platforms anchor installed-base volume, with piezoelectric systems gaining share fastest in lithography and microscopy.
Application:
Specification authority is migrating from maintenance departments to corporate sustainability offices, with procurement teams now weighting lifecycle carbon intensity alongside capital expenditure in industrial automation and building systems.
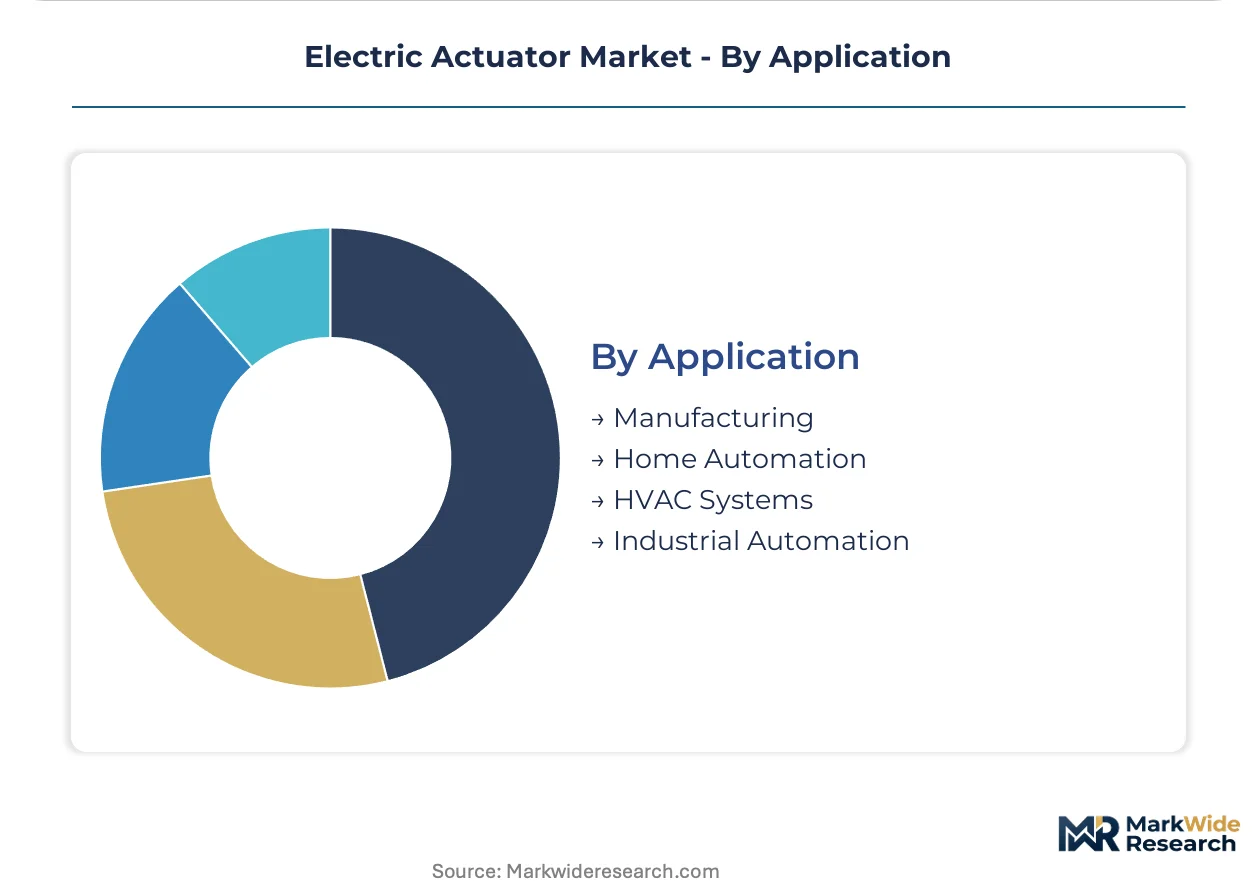
- Industrial Automation:Factory floor valve positioning, conveyor sorting, and robotic workcell integration absorb the majority of linear and rotary actuator shipments. China's eastern manufacturing corridor is retrofitting legacy assembly lines with high-torque electric positioning systems to integrate Industry 4.0 feedback architectures, while German automotive supply chains weight CSRD reporting obligations in vendor qualification.
- HVAC Systems:Damper and valve actuation in commercial buildings faces escalating efficiency mandates under China's GB standards and comparable frameworks, filtering lower-specification imports from Southeast Asian suppliers.
- Manufacturing:Discrete production equipment and material handling systems across process industries.
- Home Automation:Smart window shades, adjustable furniture, and residential climate control interfaces.
Industrial automation holds the largest installed base, with HVAC systems expanding most quickly as building efficiency codes tighten across multiple geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as actuator fabricators migrate toward jurisdictions with lower compliance costs for rare-earth processing and functional safety certification. Manufacturers now site precision-machining capacity in countries offering streamlined SIL validation pathways and subsidized industrial energy.
United States
Compressor station operators across the Permian Basin and Appalachian shale corridors are retrofitting valve automation systems to satisfy EPA methane emission thresholds under the Inflation Reduction Act. Municipal utilities in California and Texas are accelerating procurement of precision flow-control hardware for water treatment facilities facing tightened effluent standards. The EPA Clean Water Act is dictating capital allocation timelines for infrastructure operators in the Great Lakes region.
Germany
Automotive supply chains in Bavaria and Baden-Württemberg are weighting CSRD reporting obligations in vendor qualification for factory automation equipment. The EU F-Gas Regulation is forcing direct electric actuator retrofits on chemical plant valve assemblies previously served by gas-powered pneumatic units. Stuttgart and Munich industrial clusters are absorbing high-torque positioning systems for smart factory retrofits.
China
The eastern manufacturing corridor spanning Shanghai, Suzhou, and Ningbo is retrofitting legacy assembly lines with Industry 4.0 feedback architectures requiring servo-grade actuation. SAMR-administered GB standards for industrial equipment efficiency are filtering lower-specification imports from Southeast Asian suppliers. Yangtze River Delta foundries are recalibrating output mixes toward piezoelectric variants.
Japan
Semiconductor equipment manufacturers in the Tokyo and Osaka metropolitan areas are standardizing on piezoelectric positioning stages for wafer alignment systems. METI industrial efficiency frameworks are accelerating displacement of pneumatic actuation in precision manufacturing facilities. Nagoya-area automotive plants are integrating electromechanical drive systems for EV battery assembly automation.
India
The Production-Linked Incentive scheme for advanced manufacturing equipment is creating localized assembly incentives for mid-range linear actuator platforms in Gujarat and Maharashtra. BIS efficiency mandates are filtering substandard imports from regional suppliers. Pune and Ahmedabad industrial zones are emerging as fabrication hubs for servo-grade variants serving domestic automation demand.
Electric Actuator Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue medical robotics certification and piezoelectric specialization as differentiation vectors. The vendor base organizes around three archetypes: diversified industrial conglomerates with process automation platforms, electromechanical specialists with precision drive expertise, and regional fabricators serving cost-sensitive volume segments. Competitive intensity manifests through M&A activity targeting functional safety certification capabilities and strategic partnerships for rare-earth supply security.
Among diversified industrial conglomerates, Emerson Electric Co. and ABB exemplify the integrated automation platform archetype, anchoring long-term contracts through bundled process control offerings. Bosch Rexroth occupies a position within the precision electromechanical tier, representing German engineering specialization in servo drive systems. These three companies illustrate the competitive spectrum from broad automation portfolios to focused motion-control expertise.
| Leading Market Players |
|---|
| Rockwell Automation |
| Flowserve Corporation |
| Emerson Electric Co. |
| Festo AG & Co. KG |
| Rotork plc |
| Parker Hannifin Corp |
| SMC Corporation |
| Bosch Rexroth |
| ABB |
| Others |
Cost & Logistics Intelligence
The EU F-Gas Regulation and comparable EPA methane frameworks gate qualified supply access for electric actuator vendors, compressing margin structures for uncertified producers while elevating premium-tier pricing power for SIL-validated and IEC 60601-1 compliant platforms.
Pricing Analysis
Distributor margins in industrial automation channels absorb 15-25 point spreads between factory gate and end-user pricing, with direct-to-OEM contracts commanding steeper discounts for volume commitments above 500 units annually. Three-tier pricing structure across premium servo-grade, standard linear, and economy rotary variants reflects certification burden differentials, with IEC 61508 SIL-rated products capturing 40-60 percent premiums over uncertified alternatives. Cost compression in the standard tier is intensifying because Chinese foundry output expansion floods mid-range linear actuator segments. Municipal water utilities exhibit highest price sensitivity due to capital budget constraints, while semiconductor equipment OEMs demonstrate lowest sensitivity given nanometer-precision requirements.
Supply Chain Analysis
Precision machining workforce availability in Germany's Baden-Württemberg cluster and Japan's Nagoya corridor constrains gearbox housing output scalability, while China's Yangtze River Delta foundries face competing demand from electric vehicle drivetrain producers. Rare-earth magnet processing concentrates in Chinese Inner Mongolia and Jiangxi provinces, with neodymium and dysprosium supply drawing from concentrated refining capacity. Single-source vulnerability in permanent magnet feedstock exposes servo-grade producers to price volatility transmission. Distribution runs through industrial automation distributors in Europe and North America, direct OEM relationships in automotive and semiconductor verticals, and systems integrators for process industry retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric actuator market functions as a stable compounder, with regulatory displacement of pneumatic systems providing steady replacement-driven demand across process industries and infrastructure.
For Market Incumbents: To counter piezoelectric displacement in semiconductor lithography above $50,000 per axis, anchor long-term service contracts through predictive maintenance platforms and deepen captive magnet supply via backward integration into rare-earth processing partnerships in Australia or North America. For New Entrants and Emerging Players: The India PLI scheme in Gujarat and Maharashtra opens a window for localized assembly of mid-range linear actuators serving domestic automation demand, bypassing established European and Japanese incumbents. Target medical robotics certification as the most penetrable premium segment, leveraging IEC 60601-1 compliance gaps left by industrial-grade suppliers. Pursue strategic partnerships with Taiwanese semiconductor equipment manufacturers for piezoelectric stack integration. For Investors and Strategic Acquirers: Roll-up economics work for regional fabricators with functional safety certification capabilities because SIL validation timelines create defensive moats against commodity competition. Five-to-ten year viability hinges on exposure to regulatory retrofit cycles rather than greenfield capital expenditure. Watch EPA methane enforcement intensity in Permian Basin compressor stations as the inflection indicator for electric valve automation penetration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Magnet Supply | Captive neodymium sourcing from Australian or North American deposits insulates servo-grade margins from Chinese processing concentration. |
| IEC 61508 SIL Certification Investment | Oil and gas deployment access requires validation timelines that filter lower-specification competitors from petrochemical valve automation. |
| Predictive Maintenance Platform Development | Digital twin integration with electric actuators enables recurring revenue capture from industrial automation installed bases. |
| Medical Robotics Certification Pathway | IEC 60601-1 compliance opens surgical positioning segments with premium margins underserved by industrial-grade suppliers. |
| Localized Assembly Under India PLI Scheme | Production-linked incentives in Gujarat create cost-competitive fabrication hubs for mid-range linear actuator platforms. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with plant engineers at German automotive assembly facilities, maintenance directors at U.S. water treatment utilities, OEM procurement teams at semiconductor equipment manufacturers, and aftermarket service heads at industrial distributors with secondary validation against customs trade data, SEC filings from listed automation suppliers, EPA enforcement action records, and IEC certification registries. Bottom-up actuator shipment estimates triangulated against top-down process industry capital expenditure patterns.
Historical reference periods anchored the projection horizon through verified installed-base replacement cycles and regulatory compliance deadline clustering, with segmentation modeling across actuator type, industry vertical, technology architecture, and application. CAGRs derived from regression analysis of shipment volumes against macro industrial production indices and energy efficiency mandate implementation schedules, incorporating rare-earth price volatility scenarios and foundry capacity utilization assumptions.
Revisions become necessary when EPA methane enforcement thresholds tighten beyond current Inflation Reduction Act specifications, EU F-Gas Regulation phase-down accelerates, or Chinese rare-earth export restrictions materialize. Material deviation in these triggers warrants pause and re-evaluation of demand assumptions across oil and gas and European chemical plant retrofit segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Chemical Storage Tank and Bottle for Semiconductor Market
Industrial Equipment
Electron Beam Welding Systems Market
Industrial Equipment
Dust Collector Systems Market
Industrial Equipment
Precision Machine Market
Industrial Equipment
Global High Speed Dispenser Market
Industrial Equipment
Portable Laser Cleaning Machine Market
Industrial Equipment
Digital Tachometer Market
Industrial Equipment
Global Flat Glass Tempering Machines Market
Industrial Equipment
PCB Punching Machine Market
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
CNC Tool Storage System Market
Industrial Equipment
Global Strain Wave Gearing Devices Market
Industrial Equipment
United States Ball Bearing Market
Industrial Equipment
Cable Granulator Market
Industrial Equipment
Vacuum Concentrators Market
Industrial Equipment
Electronic Beam Machining Market