
 Portable Dishwasher Market | 2026-2036
Portable Dishwasher Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Dishwasher Market Intelligence
Skilled appliance technician availability is collapsing across North American and European service networks, compressing after-sales capacity just as unit volumes rise. Haier Group leverages its integrated compressor manufacturing base to control component lead times and shield margin structures. Robert Bosch GmbH sustains premium positioning through proprietary silence-engineering patents that command price premiums in noise-sensitive apartments. Samsung Electronics Co. Ltd. competes by embedding IoT diagnostics that reduce service truck rolls and offset technician scarcity.
A portable dishwasher is a freestanding or semi-integrated dishwashing appliance designed for relocation without permanent plumbing modification, typically operating through temporary faucet adapters or onboard water reservoirs with capacities between four and six place settings. These units employ thermoplastic tubs, recirculating wash pumps rated at 1,500–2,000 watts, and either condensing or fan-assisted drying systems to serve renters, recreational vehicles, and compact commercial kitchens where fixed installation is impractical. Countertop configurations occupy the volume leadership position due to lowest entry price and zero installation friction, though drawer formats are gaining fastest among kitchen renovation projects seeking ergonomic loading height. Energy Efficient feature sets concentrate margin pools as utility rebate programs and Ecodesign minimums push buyers toward heat-pump and low-water-consumption variants that manufacturers can price at structural premiums.
EPA Energy Star certification shapes US product access by setting maximum water and electricity consumption thresholds that non-compliant imports cannot clear for retail placement. Ecodesign and Energy Labelling regulations from the European Commission enforce comparable efficiency floors across EU member states, while China's GB standards administered by SAMR govern domestic safety and performance baselines. Stakeholders must monitor tightening water-use thresholds and technician workforce projections as dual constraints that will determine which product architectures and service models prove viable.
Market Dynamics
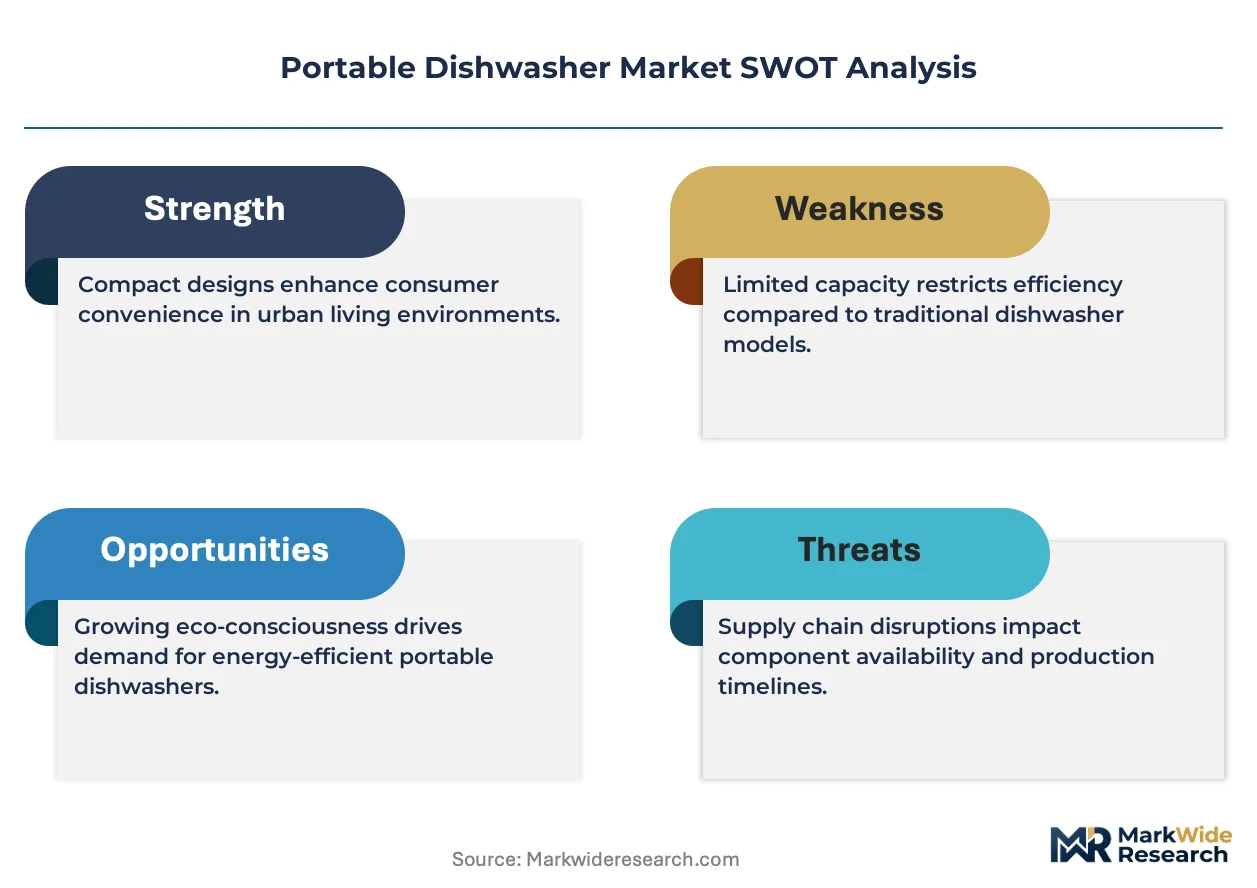
EPA Energy Star water-use thresholds and EU Ecodesign minimums are compressing product architectures while technician scarcity across North American and European service networks forces manufacturers toward predictive maintenance and modular component designs.
Growth Catalysts
- Single-person household formation:Germany, the United States, and Japan exhibit accelerating studio and micro-apartment construction where permanent dishwasher installation is structurally impractical, expanding addressable unit demand.
- EPA Energy Star certification requirements:Utility rebate programs tied to federal efficiency thresholds pull buyers toward heat-pump and low-water-consumption variants that manufacturers can position at premium price tiers.
- RV and recreational vehicle production:North American and Australian caravan manufacturing integrates portable dishwashers as standard fitments in mid-tier and above vehicle configurations, creating a dedicated commercial channel.
Market Restraints
- Copper and thermoplastic resin input volatility:Compressor motor windings and tub molding depend on commodity metals and petroleum-derived polymers subject to energy-price-driven cost swings.
- Integrated compressor supply concentration:East Asian component foundries control recirculating pump and heat-pump compressor output, exposing finished goods assemblers to geographic concentration risk.
- Countertop unit performance ceiling:Four-to-six place setting capacities and temporary faucet adapter flow rates impose hard functional limits versus fixed-installation alternatives.
Strategic Opportunities
- Underpenetrated Indian urban rental markets:Mumbai, Bangalore, and Delhi NCR micro-apartment construction outpaces fixed-appliance infrastructure, creating whitespace for reservoir-fed countertop configurations.
- IoT-enabled predictive maintenance:Embedded diagnostics that flag component degradation before failure reduce service truck rolls and offset collapsing technician availability in North America and Western Europe.
- EU Ecodesign tightening trajectory:Anticipated 2027 water-consumption threshold reductions will disqualify current baseline models, rewarding early heat-pump and condensing-dryer platform investments with regulatory-compliant shelf space.
Industry Challenges
- Appliance technician workforce collapse:North American and European vocational training pipelines fail to replace retiring service professionals, compressing after-sales capacity just as connected-unit volumes rise.
- Multi-jurisdiction certification timelines:Parallel EPA Energy Star, EU Ecodesign, and China GB standard testing extends product launch cycles and fragments R&D resource allocation.
- Legacy kitchen retrofit integration:Drawer-format units targeting renovation projects face ergonomic height standardization gaps and countertop structural load verification requirements that delay contractor specification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Dishwasher Market |
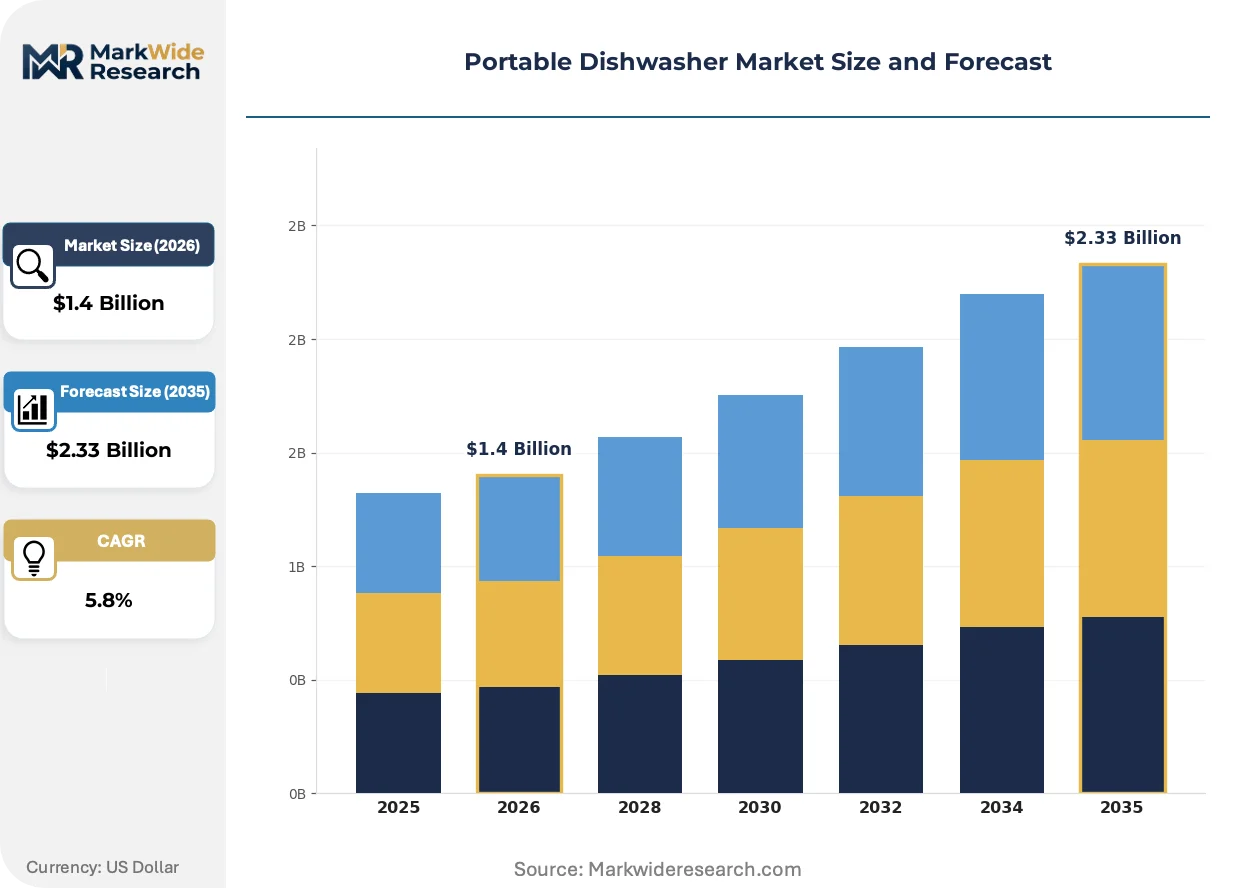
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Drawer, Standalone, Compact End User: Residential, Commercial, Hospitality, Studios Installation Type: Built-in, Portable, Modular, Tabletop Feature: Energy Efficient, Quiet Operation, Smart Technology, Adjustable Racks |
| Companies Covered | Panasonic Holdings Corporation, Haier Group Corporation, Samsung Electronics Co. Ltd., Electrolux AB, Whirlpool Corporation, Robert Bosch GmbH, Midea Group, Danby Products Ltd., LG Electronics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Dishwasher Market Strategic Shifts & Innovations
Product architectures are splitting between connected premium tiers and stripped-down economy configurations as regulatory floors harden and service infrastructure frictions intensify across major demand centers.
Heat-pump drying technology is bifurcating the efficiency-performance frontier in portable dishwasher design. Condensing systems recapture waste heat to reduce electricity draw below fan-assisted alternatives. Studio dwellers and RV owners in noise-sensitive environments adopt these units despite 40-60% purchase price premiums. The technology is compressing margin pools at the mid-tier while enabling structural premium capture at the efficiency-certified top end.
EU Ecodesign and Energy Labelling regulations from the European Commission enforce tightening water-consumption floors across member states. Non-compliant imports lose retail placement access in Germany, France, and Benelux distribution networks. Heat-pump and low-water variants gain shelf space as baseline models face delisting, accelerating manufacturer platform consolidation around certified architectures.
Rental procurement patterns are fragmenting traditional retail concentration. Property management firms and co-living operators in Berlin, Tokyo, and New York City negotiate direct volume arrangements with manufacturers for bulk countertop unit deployment. These B2B channels displace big-box appliance retail for multi-unit residential applications, compressing brand marketing spend efficiency and reshaping warranty servicing toward third-party facilities management contracts.
Portable Dishwasher Market Segmentation
Portable dishwasher segmentation reveals where manufacturers can extract premium pricing versus competing on volume. Category boundaries are hardening around installation friction, regulatory certification, and service model compatibility.
Product Type:
Margin pools concentrate in configurations that minimize installation labor and bypass technician-dependent service calls.
- Countertop:These units employ thermoplastic tubs and temporary faucet adapters requiring zero plumbing modification. Demand clusters in German and Japanese urban rental markets where lease restrictions prohibit permanent fixture installation. Studio dwellers absorb 40-60% price premiums for reservoir-fed variants that eliminate faucet dependency entirely.
- Drawer:Ergonomic loading height and semi-integrated aesthetics command specification in kitchen renovation projects. Contractor adoption in US metropolitan markets faces delays from countertop structural load verification requirements. Heat-pump drying variants in this format capture the steepest expansion trajectory among premium configurations.
- Standalone:Freestanding castor-mounted units serve RV and caravan manufacturing channels in North America and Australia. Standard fitment in mid-tier vehicle configurations creates dedicated commercial procurement volume.
- Compact:Reduced footprint variants target micro-apartment installations where square footage constraints override capacity requirements. Mumbai and Bangalore construction pipelines are rotating up the share rankings for this configuration.
Countertop holds installed capacity. Drawer is rotating up the share rankings.
End User:
Procurement patterns diverge sharply between individual purchase decisions and institutional volume arrangements.
- Residential:Single-person household formation in the United States, Germany, and Japan drives replacement cycles and first-time adoption. EPA Energy Star rebate eligibility shapes purchase decisions toward certified heat-pump variants.
- Commercial:Compact commercial kitchens in food service operations demand NSF-certified sanitation cycles. Installation flexibility outweighs capacity limitations for mobile catering and pop-up restaurant applications.
- Hospitality:Extended-stay hotel chains and serviced apartment operators specify drawer formats for suite kitchen retrofits. Procurement concentrates through facilities management contracts rather than retail channels.
- Studios:Co-living operators in Berlin, Tokyo, and New York City negotiate direct manufacturer arrangements for bulk countertop deployment. B2B pricing compression is offset by warranty servicing economies.
Residential dominates absolute unit volume. Studios is gaining share fastest in procurement channel restructuring.
Installation Type:
Technical architecture determines regulatory compliance pathways and aftermarket service intensity.
- Built-in:Semi-permanent installation with temporary plumbing connections bridges fixed and portable categories. German rental law compatibility sustains niche demand despite higher initial cost.
- Portable:True temporary connection via faucet adapters or reservoir systems defines core market functionality. EPA Energy Star certification thresholds disqualify non-compliant imports from US retail placement.
- Modular:Stackable or linkable configurations serve commercial food service and institutional catering. Expansion capacity without footprint increase justifies premium positioning.
- Tabletop:Minimal footprint variants for RV galley and marine applications prioritize vibration resistance and water containment. Australian caravan manufacturing integration is climbing the fastest among specialized channels.
Portable holds installed capacity. Tabletop is rotating up the share rankings in recreational vehicle applications.
Feature:
Certification-grade efficiency attributes command structural premiums while baseline configurations face margin compression.
- Energy Efficient:Heat-pump drying and low-water-consumption architectures meet EU Ecodesign minimums and EPA Energy Star thresholds. Utility rebate program eligibility enables 40-60% price positioning above fan-assisted alternatives.
- Quiet Operation:Silence-engineering patents command specification in noise-sensitive apartments and studio configurations. Bosch proprietary damping systems sustain premium positioning in German and US urban markets.
- Smart Technology:IoT-enabled diagnostics flag component degradation before failure, reducing service truck rolls. Samsung embedded sensors offset collapsing technician availability in North American and European networks.
- Adjustable Racks:Flexible loading configurations accommodate irregular cookware shapes in compact capacities. Differentiation utility diminishes as four-to-six place setting limits constrain practical adaptability.
Energy Efficient holds installed capacity. Smart Technology is rotating up the share rankings as service infrastructure frictions intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German renters favor drawer-format units for kitchen retrofits, while Japanese studio dwellers prioritize reservoir-fed countertop models that eliminate faucet dependency entirely. This consumption-mix differential reflects divergent housing stock constraints and lease enforcement patterns across mature urban markets.
United States
Single-person household formation in New York City and Los Angeles drives countertop adoption where permanent installation is prohibited. EPA Energy Star rebate programs pull buyers toward heat-pump certified variants. Austin and Denver co-living operators negotiate direct manufacturer volume arrangements for bulk deployment.
Germany
Micro-apartment construction in Berlin and Hamburg sustains demand for semi-integrated drawer configurations. EU Ecodesign water-consumption thresholds disqualify non-compliant imports from retail placement. Bavarian kitchen renovation contractors specify ergonomic loading-height units for premium retrofit projects.
Japan
Tokyo and Osaka studio dwellers absorb steep premiums for reservoir-fed countertop units that bypass lease restrictions. METI efficiency standards shape product development priorities for domestic manufacturers. Nagoya industrial clusters supply recirculating pump components to regional assemblers.
India
Mumbai and Bangalore micro-apartment pipelines outpace fixed-appliance infrastructure, creating whitespace for compact configurations. BIS safety standards govern domestic market access for imported units. Delhi-NCR co-living operators pilot bulk procurement programs for reservoir-fed countertop deployment.
Australia
Caravan manufacturing in Melbourne and Brisbane integrates portable dishwashers as standard fitments in mid-tier vehicle configurations. National appliance efficiency regulations align with EU Ecodesign trajectories. Perth and Adelaide rental markets show emerging countertop adoption among urban transient populations.
Portable Dishwasher Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in portable dishwasher manufacturing. Korean and Japanese electronics conglomerates leverage component manufacturing scale to control compressor and pump supply chains. German engineering specialists command premium positioning through silence-engineering patents. Chinese appliance groups compete on cost-optimized platform variants for emerging market penetration. Competitive moves concentrate on backward integration into heat-pump component production and IoT diagnostic capability licensing.
Within the integrated conglomerate tier, Haier Group Corporation and Samsung Electronics Co. Ltd. represent scale-driven archetypes that anchor volume leadership through captive supply chain control. Robert Bosch GmbH exemplifies the engineering-specialist position, occupying premium-tier placement through proprietary damping systems. These three companies collectively illustrate the strategic bifurcation between cost-optimized platform scale and certified-efficiency premium capture that defines current competitive positioning.
| Leading Market Players |
|---|
| Panasonic Holdings Corporation |
| Haier Group Corporation |
| Samsung Electronics Co. Ltd. |
| Electrolux AB |
| Whirlpool Corporation |
| Robert Bosch GmbH |
| Midea Group |
| Danby Products Ltd. |
| LG Electronics Inc. |
| Others |
Cost & Logistics Intelligence
Long-term offtake arrangements between East Asian compressor foundries and finished goods assemblers lock in component access and price visibility for heat-pump variants, while spot-market copper and thermoplastic resin exposure concentrates margin volatility in economy-tier countertop configurations. These contract structures insulate premium manufacturers from input swings but tether pricing power to geographic supply concentration.
Pricing Analysis
Long-term offtake contracts anchor pricing for heat-pump and condensing-dryer platforms, while spot-market exposure governs economy-tier countertop units. Price differentiation rests on EPA Energy Star certification tier and silence-engineering patent portfolios, with Bosch commanding structural premiums in noise-sensitive apartments. Cost compression in fan-assisted baseline models is intensifying because utility rebate programs disqualify non-certified imports from retail placement. Studio dwellers and co-living operators in Berlin and Tokyo show least price sensitivity for reservoir-fed configurations that eliminate faucet dependency.
Supply Chain Analysis
Inbound logistics costs through Shanghai-Ningbo and Busan port corridors shape landed cost structures for North American and European finished goods assemblers. Manufacturing gravity centers on China, South Korea, and Japan for recirculating pump and heat-pump compressor output, with Nagoya industrial clusters feeding regional component demand. Raw material dependencies draw from copper motor windings, petroleum-derived thermoplastic resins, and rare-earth magnetic materials for pump efficiency optimization. Single-source vulnerability concentrates in East Asian compressor foundries controlling heat-pump platform supply. Distribution runs through big-box retail in residential channels and direct manufacturer arrangements for co-living and property management B2B procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technician workforce collapse across North American and European service networks constrains after-sales capacity just as connected-unit volumes rise, making predictive maintenance capability and modular component design critical competitive differentiators rather than optional features.
For Market Incumbents:Compound proprietary silence-engineering and heat-pump platform investments to defend premium positioning against Korean electronics conglomerates embedding IoT diagnostics. Backward integration into compressor manufacturing shields margin structures from East Asian foundry concentration risk. Prioritize certification pre-positioning for anticipated EU Ecodesign water-consumption threshold tightening.
For New Entrants and Emerging Players:Differentiate on reservoir-fed countertop configurations targeting Mumbai, Bangalore, and Delhi NCR micro-apartment pipelines where fixed-appliance infrastructure lags construction completion. The most penetrable whitespace sits in Indian urban rental markets governed by BIS safety standards rather than efficiency certification tiers. Pursue direct procurement relationships with co-living operators and facilities management firms to bypass established retail channel concentration.
For Investors and Strategic Acquirers:Component-captive mid-tier specialists with captive heat-pump technology and established EPA Energy Star certification pathways represent the most defensible acquisition archetype. Long-term viability across the projection horizon hinges on regulatory compliance shelf space rather than volume scale alone. Monitor EU Ecodesign implementation timelines as the critical inflection signal for platform consolidation winners.
| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Platform Investment | Captures EPA Energy Star rebate eligibility and EU Ecodesign compliance shelf space in Germany and France. |
| IoT Diagnostic Capability Licensing | Reduces service truck rolls and offsets collapsing technician availability in North American networks. |
| Direct B2B Procurement Relationships | Bypasses retail margin compression with co-living operators in Berlin, Tokyo, and New York City. |
| Backward Integration into Compressor Manufacturing | Shields margin structures from East Asian foundry concentration risk and supply disruption. |
| Reservoir-Fed Configuration Development | Eliminates faucet dependency for lease-restricted renters in Japanese and Indian urban markets. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with appliance manufacturer product managers, EPA Energy Star certification specialists, European kitchen renovation contractors, North American RV manufacturing procurement leads, and Indian co-living facilities management executives. Secondary validation drew from EPA certification databases, EU Ecodesign regulatory filings, SAMR GB standard documentation, BIS safety standard registers, and customs trade flow records for compressor and pump component movements. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Across the analysis window, forecasts modeled product type segmentation by countertop, drawer, standalone, and compact configurations alongside installation type, end-user category, and feature-grade efficiency certification tiers. CAGRs were derived from regression analysis against single-person household formation rates, micro-apartment construction permits, and RV manufacturing output across key demand centers. Industry-specific inputs incorporated technician workforce projections and utility rebate program enrollment trajectories.
Material uncertainties — copper and thermoplastic resin commodity volatility, East Asian foundry disruption, and EU Ecodesign threshold acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding certification timeline adherence and service infrastructure degradation rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Portable Mini Fridge Market
Appliances
France Household Electric Grills Market
Appliances
Global Massage Chairs Market
Appliances
Israel Laundry Appliances Market
Appliances
North America Tumble Dryers Market
Appliances
Smart Microwave Oven Market
Appliances
Tumble Dryer Market
Appliances
Dishwasher Market
Appliances
Microwave Market
Appliances
Shared Shoe Washing Machine Market
Appliances
Cooler Connected to the Mains Market
Appliances
Asia-Pacific Tumble Dryers Market
Appliances
Asia-Pacific Washing Machine Market
Appliances
UK Residential Vacuum Cleaner Market
Appliances
North America Washing Machine Market
Appliances
North America Microwave Oven Market