
 Israel Laundry Appliances Market | 2026-2036
Israel Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Israel Laundry Appliances Market Foresight
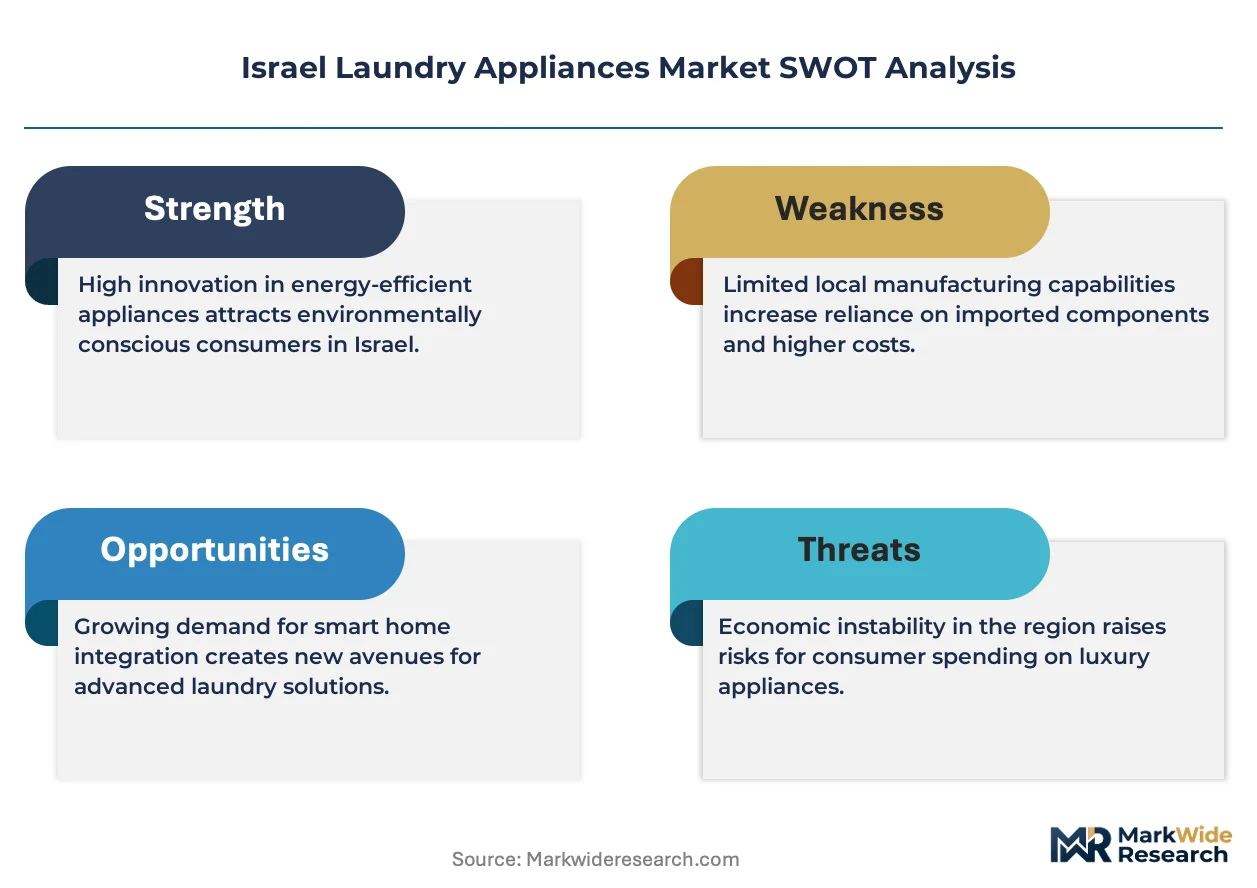
Leasing and pay-per-use financing models is rewriting competitive access in Israel's laundry appliances sector, lowering capital barriers for commercial laundries and hospitality operators. Electrolux leverages its European manufacturing footprint to sustain premium positioning in the Israeli market. Haier Group anchors its presence through cost-efficient supply chains serving price-sensitive household segments. Bosch differentiates on energy-efficient engineering aligned with national conservation mandates.
Israel laundry appliances encompass electrically powered machines designed for washing, drying, or combined treatment of textiles, typically operating at 220-240V with water consumption rates governed by efficiency labeling protocols. These systems serve residential, commercial, and institutional end users requiring automated fabric cleaning with programmable cycle controls. Front-load washing machines command the dominant product position due to superior water and energy efficiency ratings demanded by Israeli regulators. Smart appliances represent the fastest-expanding technology category as IoT-enabled remote monitoring gains traction in hospitality and multi-unit residential deployments. Heat pump dryers are capturing margin concentration in the premium tier where electricity cost sensitivity drives specification upgrades.
The Ministry of Environmental Protection enforces water efficiency standards that directly shape product eligibility and labeling requirements for laundry equipment sold in Israel. The Israel Standards Institute certifies electrical safety and energy performance, creating compliance thresholds that filter import access and domestic distribution. The central bank's consumer credit regulations influence household appliance financing terms. Stakeholders must monitor regulatory tightening on water consumption limits and the pace of smart grid integration to anticipate specification shifts and channel investment priorities.
Market Dynamics
Israel's mandatory water efficiency standards under the Ministry of Environmental Protection are compressing product eligibility and forcing specification upgrades across residential and commercial procurement channels.
Growth Catalysts
- Heat pump technology:Israeli electricity tariffs and Ministry of Environmental Protection water efficiency mandates are accelerating heat pump dryer adoption in premium residential and hospitality segments.
- Gush Dan urban density:Multi-family residential construction in Tel Aviv's metropolitan core is expanding shared laundry facility installations and machine placement volumes.
- Smart appliance protocols:IoT-enabled remote monitoring systems are gaining traction in hospitality and multi-unit residential deployments, creating specification pull-through for connected machines.
Market Restraints
- Import dependency:Domestic manufacturing absence concentrates supply risk on European and Asian production hubs, exposing distributors to shipping cost volatility and currency fluctuation.
- Water scarcity infrastructure:Aging municipal water distribution networks in peripheral districts create installation constraints for high-efficiency front-load systems requiring stable pressure.
- Capital intensity barriers:Commercial laundries face upfront equipment costs that strain small-operator balance sheets, limiting fleet modernization velocity despite operational savings.
Strategic Opportunities
- Pay-per-use financing:Leasing and subscription models for commercial operators lower capital barriers and create recurring revenue streams for distributors serving hospitality and institutional segments.
- Smart grid integration:Israel Standards Institute certification pathways for grid-responsive appliances position manufacturers to capture demand-response incentives as utility infrastructure modernizes.
- Jerusalem renovation wave:Heritage district housing stock upgrades present white-space demand for compact, high-efficiency machines suited to older building constraints.
Industry Challenges
- Certification timeline compression:Israel Standards Institute electrical safety and energy performance testing creates import delays that strain inventory planning for seasonal demand peaks.
- Technical service scarcity:Heat pump and smart appliance repair expertise concentrates in central district service networks, leaving peripheral regions underserved for maintenance response.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Israel Laundry Appliances Market |
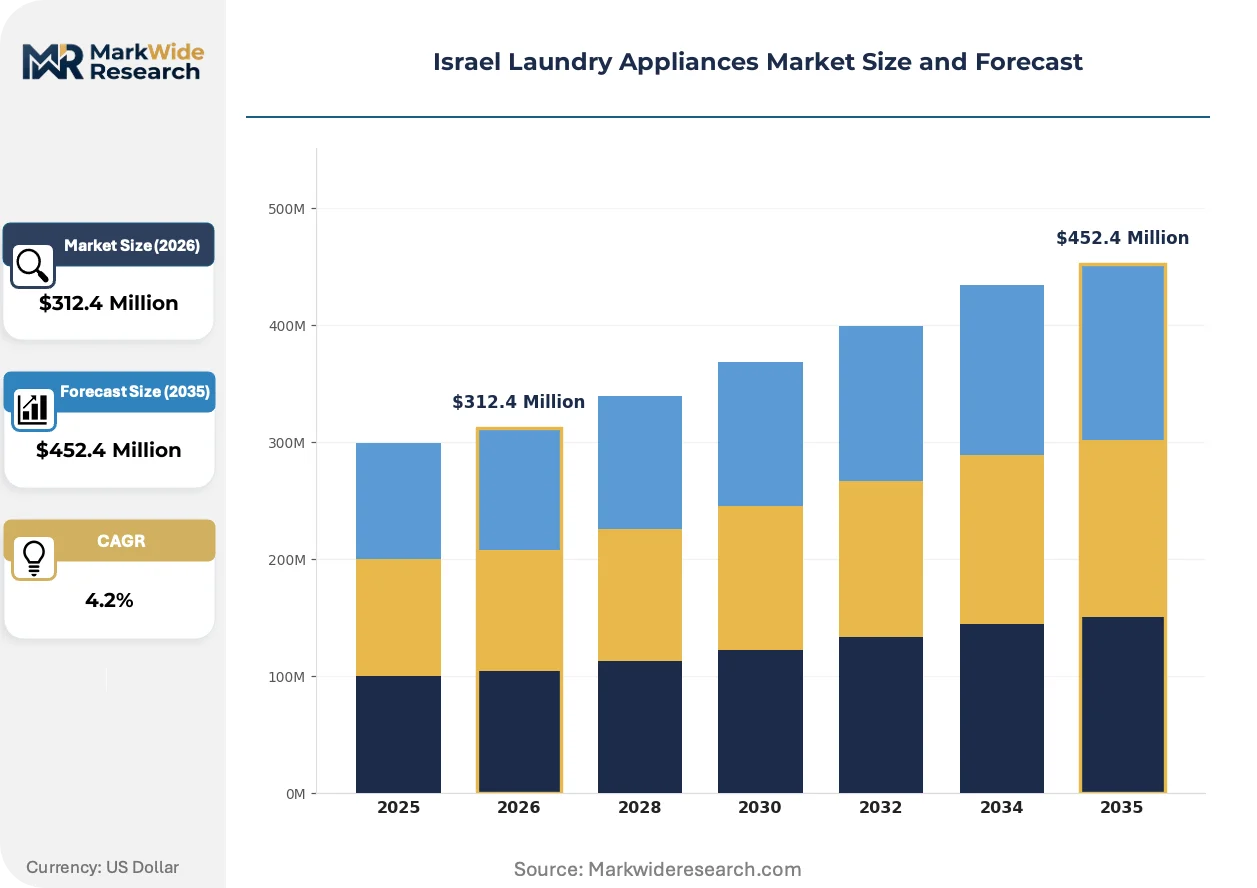
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $452.4 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Washer-Dryer Combos, Laundry Centers End User: Households, Hospitality, Institutions, Commercial Laundries Technology: Front-Load, Top-Load, Smart Appliances, Heat Pump Distribution Channel: Online Retail, Brick-and-Mortar, Wholesalers, Specialty Stores |
| Companies Covered | Alliance Laundry Systems, Candy Group, Bosch, Hitachi Appliances Inc, Haier Group, Electrolux, GD Midea Holding Co., Ltd, IFB Industries, LG Electronics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Israel Laundry Appliances Market Shifts & Advancements
Water efficiency mandates and electricity cost pressures are actively reshaping product specifications and procurement priorities across Israel's laundry appliance channels.
Heat pump drying technology is collapsing the operating cost gap between conventional electric dryers and premium alternatives. Hospitality operators in Eilat and Dead Sea resort corridors are specifying heat pump units at accelerating rates. The technology is collapsing resistance to dryer adoption in water-scarce regions where line-drying dominated.
The Ministry of Environmental Protection's tightening water consumption limits are disqualifying top-load washing machines from eligibility for efficiency labeling. Retailers are responding by contracting front-load SKUs and phasing out non-compliant inventory. Central district appliance chains are most exposed to this regulatory compression given their volume concentration.
Shared laundry facility management is fragmenting traditional household purchase patterns. Property developers in Tel Aviv's new multi-family towers are procuring commercial-grade machines through direct vendor relationships, bypassing retail channels. This channel shift is most visible in Gush Dan's high-rise residential pipeline where in-building amenity competition drives specification escalation.
Israel Laundry Appliances Market Segmentation
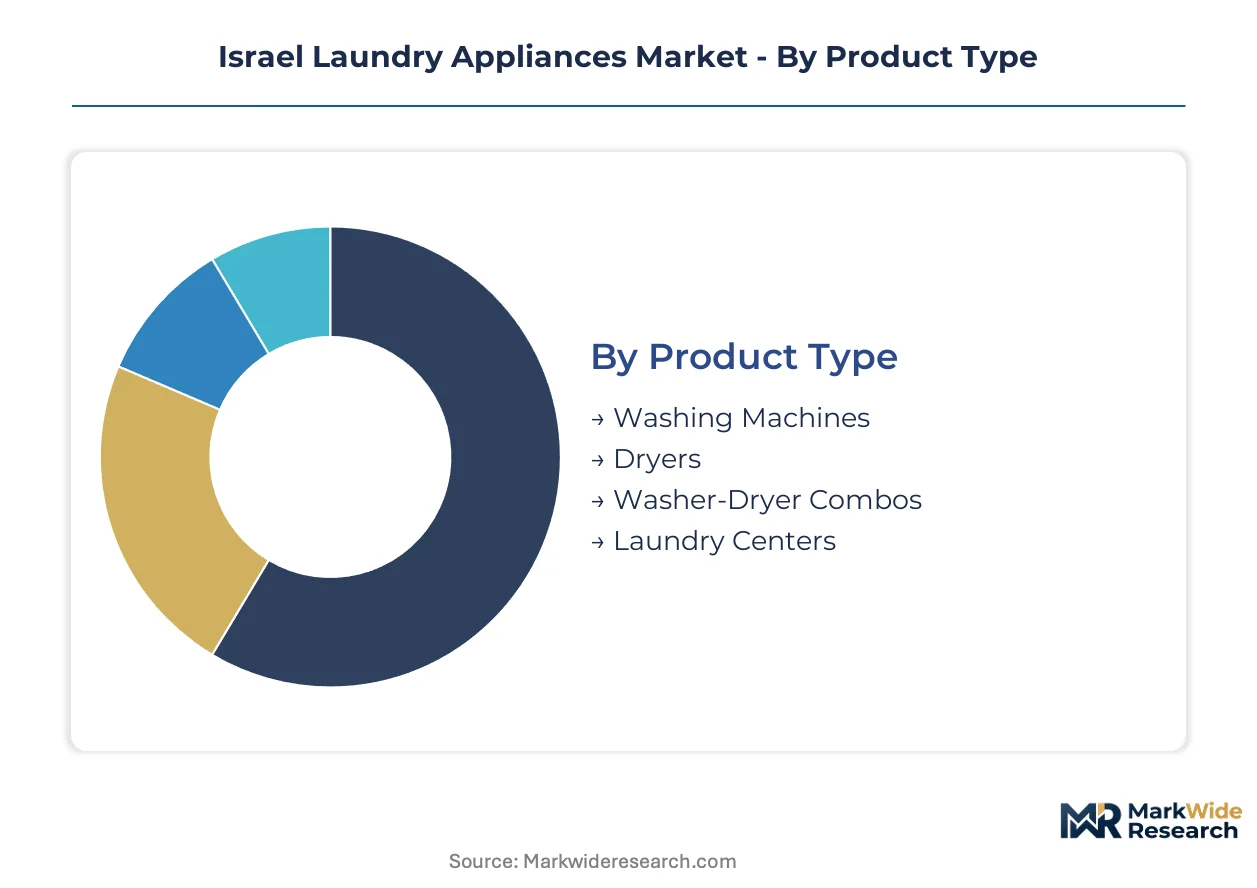
Israel's laundry appliance market fragments across four distinct dimensions, each reflecting competing pressures from water scarcity mandates, electricity cost sensitivity, and channel modernization. Understanding these segment boundaries reveals where specification upgrades concentrate and where pricing power erodes.
Product Type:
Mature categories dominate residential procurement while emerging formats capture hospitality and dense urban housing retrofit demand.
- Washing Machines:Front-load configurations with horizontal drum orientation and programmable cycle controls command specification preference under Ministry of Environmental Protection water efficiency mandates. Gush Dan apartment towers and Tel Aviv multi-family developments drive replacement cycles as aging top-load units face regulatory disqualification.
- Dryers:Heat pump and condenser technologies are displacing vented electric units in premium residential segments and Dead Sea resort corridors where humidity and dust render line-drying impractical. Electricity tariff sensitivity accelerates specification upgrades in hospitality procurement channels.
- Washer-Dryer Combos:Space-constrained Jerusalem heritage district renovations and compact Tel Aviv apartments favor integrated drum systems despite longer cycle times and reduced load capacity.
- Laundry Centers:Stacked vertical configurations serve commercial laundries and institutional operators in peripheral districts where floor space optimization outweighs unit cost premiums.
Washing machines retain volume leadership; heat pump dryers hold the steepest expansion curve.
End User:
Customer type determines specification intensity, with commercial operators prioritizing throughput metrics and residential buyers responding to efficiency labeling.
- Households:Central district consumers in Haifa, Tel Aviv, and Jerusalem drive front-load adoption through retail and online channels, with purchase decisions heavily influenced by Israel Standards Institute energy performance badges.
- Hospitality:Eilat and Dead Sea resort operators specify commercial-grade heat pump dryers and high-capacity washers through direct vendor relationships, bypassing retail markup.
- Institutions:Hospitals, military facilities, and educational campuses in the Negev and Galilee regions procure through tender processes that prioritize water consumption limits and durability warranties.
- Commercial Laundries:Small operators in peripheral districts face capital intensity barriers that slow fleet modernization despite operational savings from efficiency upgrades.
Households retain volume leadership; hospitality holds the steepest expansion curve.
Technology:
Regulatory compliance and operating cost pressures are bifurcating the technology landscape between mandated efficiency and premium connectivity.
- Front-Load:Horizontal drum orientation with tumble wash action delivers superior water and energy efficiency ratings required for Ministry of Environmental Protection labeling eligibility. Retailers in central district chains have phased out non-compliant top-load inventory.
- Smart Appliances:IoT-enabled remote monitoring and cycle programming gain traction in Tel Aviv high-rise shared laundry facilities and hospitality deployments where operational visibility reduces service response times.
- Top-Load:Vertical axis machines with agitator mechanisms face regulatory compression as water consumption limits disqualify them from efficiency certification, restricting sales to price-sensitive peripheral markets.
- Heat Pump:Closed-loop refrigerant systems extract moisture at lower temperatures, slashing electricity consumption by half versus conventional electric dryers in premium residential and commercial segments.
Front-load retains volume leadership; smart appliances hold the steepest expansion curve.
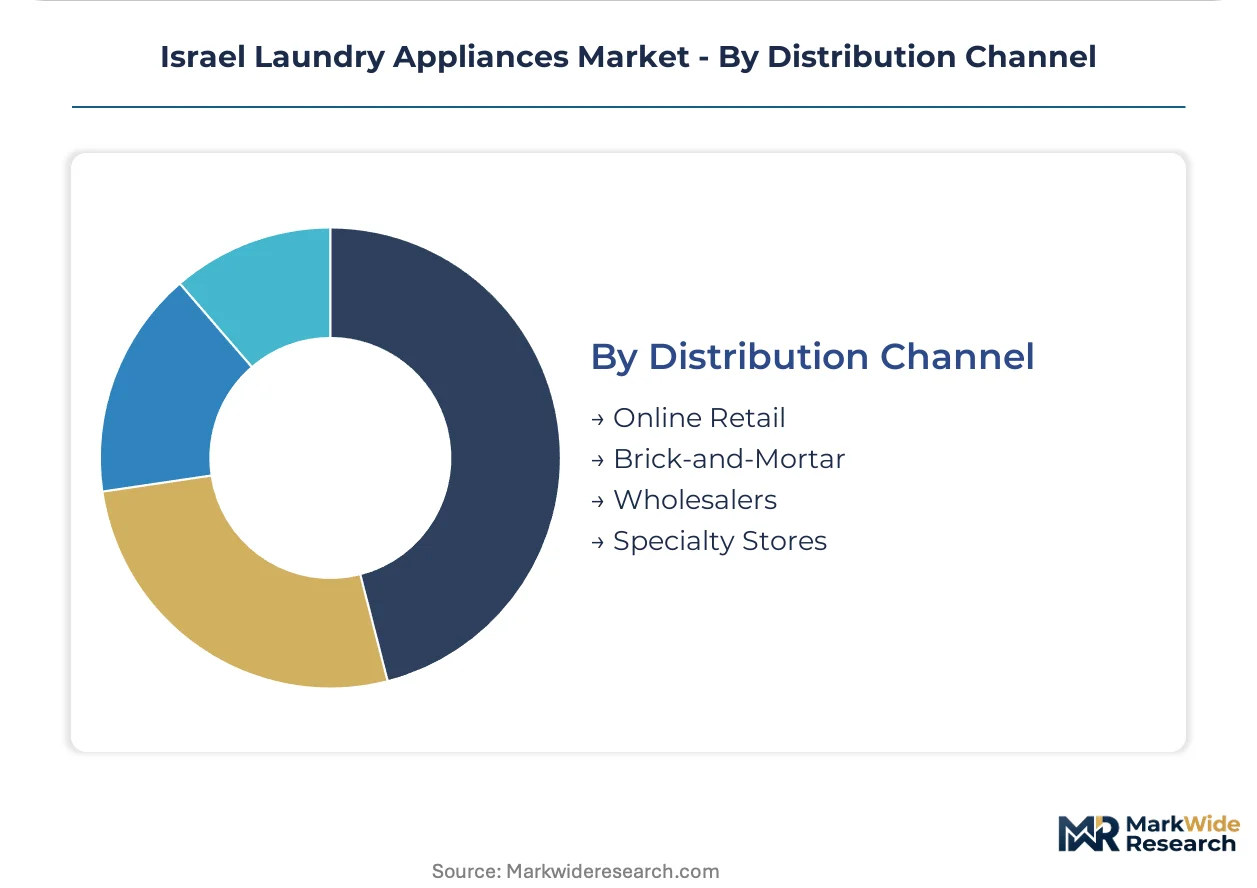
Distribution Channel:
Channel selection reflects purchase scale and specification complexity, with bulk procurement fragmenting traditional retail concentration.
- Brick-and-Mortar:Central district appliance chains in Tel Aviv, Haifa, and Jerusalem dominate household replacement cycles, leveraging floor displays and installation service bundling to justify price premiums over online alternatives.
- Online Retail:E-commerce platforms capture growing share among tech-savvy central district consumers comparing efficiency ratings and price transparency, though delivery logistics strain for bulky items in peripheral regions.
- Wholesalers:Direct vendor relationships with property developers and hospitality operators in Gush Dan bypass retail channels entirely, with volume procurement concentrating specification decisions among fewer decision-makers.
- Specialty Stores:Niche retailers serving commercial laundries and institutional buyers offer technical consultation and maintenance contracts that justify higher unit margins.
Brick-and-mortar retains volume leadership; online retail holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel's import-dependent laundry appliance sector sources predominantly from European and Asian manufacturing hubs, with domestic distribution networks concentrated in the central coastal corridor. Export flows remain minimal given the absence of indigenous production capacity.
Gush Dan Metropolitan Area
Tel Aviv's high-rise residential pipeline drives commercial-grade machine procurement for shared laundry facilities in new multi-family towers. The Ministry of Environmental Protection's water efficiency mandates compress product eligibility for developers seeking building permits. Ashdod and Petah Tikva anchor distribution logistics for European-imported front-load systems serving central district retail chains.
Jerusalem District
Heritage district housing renovations generate demand for compact washer-dryer combos suited to older building constraints and space limitations. The Israel Standards Institute certification requirements create import delays that strain inventory planning for seasonal replacement cycles. East Jerusalem and surrounding neighborhoods present underserved service networks for heat pump dryer maintenance.
Haifa Bay Area
Port infrastructure facilitates bulk import reception for hospitality operators along the northern coast and Galilee resort corridors. The Ministry of Environmental Protection's tightening water consumption limits accelerate fleet modernization among institutional buyers. Kiryat Bialik and surrounding industrial zones concentrate commercial laundry operations serving regional hospital and military procurement.
Negev and Southern District
Eilat resort operators specify heat pump dryers through direct vendor relationships bypassing retail markup channels. The Israel Standards Institute electrical safety testing creates compliance bottlenecks for Asian-sourced smart appliances targeting hospitality deployments. Be'er Sheva's institutional procurement through tender processes prioritizes durability warranties for educational and military campus installations.
Galilee and Northern Periphery
Aging municipal water distribution networks constrain high-efficiency front-load installations requiring stable pressure infrastructure. The Ministry of Environmental Protection's efficiency labeling protocols filter retail access for non-compliant top-load inventory in price-sensitive segments. Nazareth Illit and peripheral towns remain underserved for technical service expertise on connected appliance maintenance.
Israel Laundry Appliances Market Competitive Landscape
On the supply side, the industry is moderately consolidated around diversified appliance conglomerates with established European distribution footprints. Strategic archetypes separate premium engineering specialists, cost-optimized volume players, and commercial-grade equipment fabricators. Competitive positioning hinges on Israel Standards Institute certification velocity and heat pump technology portfolios. Dominant moves include direct vendor relationships with property developers and pay-per-use financing structures for hospitality operators.
Within the premium-tier vector, Electrolux and Bosch exemplify European engineering positioning aligned with national conservation mandates. Haier Group anchors the cost-efficient supply chain archetype serving price-sensitive household segments through scale-driven manufacturing. Alliance Laundry Systems occupies the commercial equipment specialist position targeting institutional and hospitality procurement channels with durability-focused specifications.
| Leading Market Players |
|---|
| Alliance Laundry Systems |
| Candy Group |
| Bosch |
| Hitachi Appliances Inc |
| Haier Group |
| Electrolux |
| GD Midea Holding Co., Ltd |
| IFB Industries |
| LG Electronics |
| Others |
Supply & Pricing Matrix
European manufacturing clusters in Poland and Turkey anchor capacity for Israel-bound laundry equipment, with their scale dynamics translating directly into distributor pricing power across Gush Dan's retail chains and hospitality procurement channels. Ministry of Environmental Protection water efficiency mandates compress product eligibility, forcing specification upgrades that concentrate margin capture among certified suppliers while squeezing non-compliant inventory.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures for commercial-grade machines serving hospitality and institutional segments. Price differentiation hinges on Israel Standards Institute certification tier and volume scale, with bulk procurement through direct vendor relationships commanding steepest discounts. Cost compression in the standard tier intensifies as Asian manufacturers expand front-load capacity. Small commercial laundries in peripheral districts exhibit highest price sensitivity, while Dead Sea resort operators prioritize operating cost reduction over upfront capital.
Supply Chain Analysis
Contract manufacturing concentrates with Electrolux facilities in Poland, Bosch operations in Germany, and Haier Group production hubs in China. Component sourcing draws from Italian pump assemblies, Turkish drum fabrications, and Chinese control module suppliers. Single-source vulnerability concentrates in heat pump compressor supply from European specialists. Distribution runs through Ashdod port logistics to central district appliance chains, with direct shipment bypass for Gush Dan property developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated hospitality operators and Gush Dan property developers, fragmenting traditional retail channel concentration as direct vendor relationships capture volume procurement.
For Market Incumbents: Pre-empt margin erosion from Asian cost competitors by deepening backward integration into heat pump compressor supply and accelerating Israel Standards Institute certification velocity for smart appliance portfolios. Secure exclusive supply agreements with Tel Aviv high-rise developers before channel fragmentation hardens. For New Entrants and Emerging Players: Pursue white-space opportunity in Jerusalem heritage district compact washer-dryer combos and Negev institutional tender processes where incumbent service networks remain thin. Target peripheral commercial laundries with pay-per-use financing structures that lower capital barriers and build installed base for aftermarket capture. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors commercial-grade equipment fabricators with durability-focused specifications and hospitality channel penetration over residential retail exposure. Acquisition targets should demonstrate heat pump technology portfolios and direct vendor relationships with Gush Dan developers. Monitor Ministry of Environmental Protection regulatory tightening pace as inflection indicator for specification upgrade velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Technology Licensing | Accelerates hospitality fleet modernization under Ministry of Environmental Protection electricity cost pressures. |
| Smart Grid Certification Pathway | Positions manufacturers for Israel Standards Institute demand-response incentives as utility infrastructure upgrades. |
| Direct Developer Partnership | Bypasses retail markup erosion in Gush Dan multi-family tower procurement channels. |
| Pay-per-Use Financing Launch | Lowers capital barriers for peripheral commercial laundries and creates recurring revenue streams. |
| Technical Service Network Expansion | Addresses heat pump maintenance scarcity in Jerusalem and Negev underserved regions. |
Research Methodology
A spread of perspectives from appliance distributor procurement heads, hospitality operations directors, Israel Standards Institute certification engineers, and Ministry of Environmental Protection policy staff converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through customs import records, Israel Central Bureau of Statistics housing construction data, and utility tariff filings. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction.
Demand-supply balance modeling anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, end user category, technology tier, and distribution channel. CAGRs derived from regression analysis of historical efficiency mandate adoption curves and electricity tariff sensitivity patterns. Heat pump technology penetration rates and smart appliance IoT deployment velocity served as industry-specific forecast inputs.
Sensitivities concentrate around Ministry of Environmental Protection water consumption limit revisions, shekel-euro exchange rate volatility, and Asian manufacturing hub shipping cost fluctuations. Quarterly review of Israel Standards Institute certification queue lengths and Gush Dan construction permit approvals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Europe Induction Hobs Market
Appliances
Household Side by Side Refrigerator Market
Appliances
Saudi Arabia Water Heater Market
Appliances
Asia Pacific Household Side by Side Refrigerator Market
Appliances
Intelligent Electric Rice Cooker Market
Appliances
Smart Microwave Oven Market
Appliances
Saudi Arabia Gas Hobs Market
Appliances
Small Appliances Market
Appliances
Washing Appliances Market
Appliances
Water Heater Market
Appliances
South Africa Laundry Appliances Market
Appliances
Global Home Ice Maker Market
Appliances
Oman Microwave Ovens Market
Appliances
Household Beauty Appliances Market
Appliances
Built-In Large Cooking Appliance Market
Appliances
Industrial Gas Stove Market