
 North America Washing Machine Market | 2026-2036
North America Washing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
North America Washing Machine Market Analytics
Subscription-based leasing and asset-light financing models are reshaping competitive dynamics in the North America washing machine market, lowering upfront barriers for property managers and rental housing operators. Whirlpool Corporation leverages its captive service network to sustain recurring revenue streams from institutional clients. GE Appliances anchors its position through backward integration into appliance financing and extended warranty programs. Speed Queen specializes in commercial-grade durability standards that differentiate its offerings in the multi-housing segment.
A washing machine is an electromechanical appliance engineered to clean textiles through automated agitation, spin cycles, and water extraction, typically operating at drum speeds between 800 and 1600 revolutions per minute with load capacities ranging from compact residential units to industrial-scale machines exceeding 20 kilograms. Its primary purpose is to reduce manual labor and water consumption relative to hand-washing methods across household, commercial, and institutional settings. Front load configurations command premium positioning due to superior energy efficiency and gentler fabric handling, while smart appliance technology represents the fastest-expanding technology segment as connected diagnostics and remote cycle management penetrate both replacement and new-build channels. The hospitality end user segment presents concentrated margin pools tied to brand-standard procurement contracts and accelerated replacement cycles.
The US Department of Energy enforces minimum efficiency standards under ENERGY STAR guidelines that directly constrain allowable water and electricity consumption per cycle, while the EPA administers WaterSense certification programs that shape product development priorities for manufacturers serving the North American market. Canada's Natural Resources Canada operates parallel EnerGuide labeling requirements that create dual-compliance obligations for cross-border suppliers. Stakeholders must monitor evolving federal efficiency rulemakings and provincial rebate programs to anticipate compliance costs and timing for next-generation platform investments.
Market Dynamics
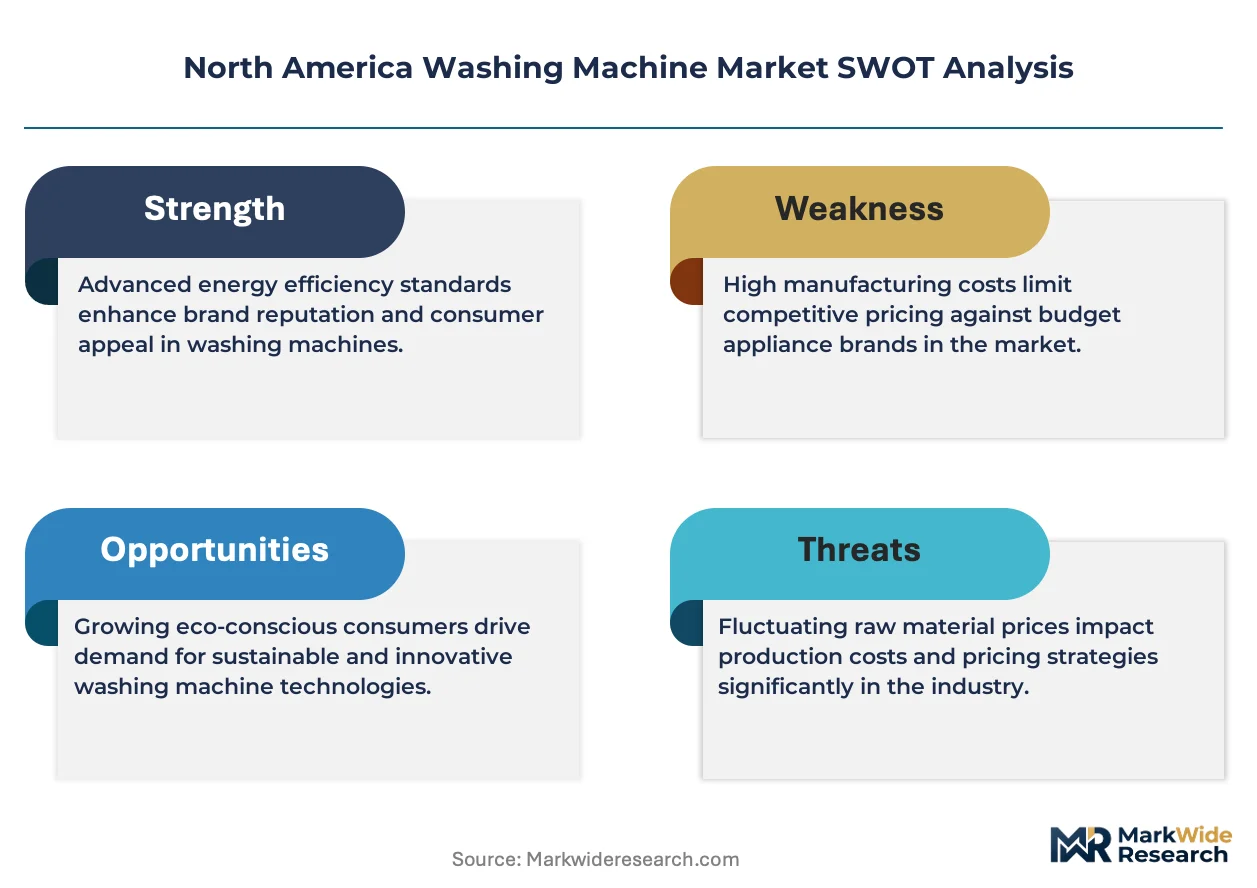
The North America washing machine market is being fundamentally restructured by ENERGY STAR 8.0 efficiency mandates from the US Department of Energy, which force manufacturers to redesign drum systems and motor architectures to meet stricter water extraction performance thresholds.
Growth Catalysts
- Multi-family housing construction:Developers in Texas, Florida, and Arizona are installing in-unit laundry appliances at record rates to attract migration-driven demand.
- WaterSense certification programs:The EPA's voluntary labeling initiative is pulling consumer preference toward front-load configurations that reduce per-cycle water consumption.
- Smart appliance integration:Connected diagnostic platforms are enabling predictive maintenance contracts that extend replacement cycles for commercial operators.
Market Restraints
- Steel and copper input volatility:Drum assemblies and motor windings face cost pressure from commodity price swings that compress OEM margins.
- Mexican component concentration:Cross-border supply dependencies expose assembly plants to customs delays and tariff uncertainty.
- Heat pump drying limitations:Technical constraints on low-temperature moisture removal restrict adoption in northern climates with high humidity.
Strategic Opportunities
- Canadian provincial rebate programs:Natural Resources Canada's EnerGuide-linked incentives in Ontario and British Columbia subsidize premium efficiency upgrades.
- Commercial laundry-as-a-service:Subscription models for apartment operators replace capital expenditure with per-load revenue sharing.
- AI-driven cycle optimization:Machine learning algorithms that adapt water levels to fabric sensors are converging with utility demand-response programs.
Industry Challenges
- Service technician specialization:Electronic control board diagnostics require training investments that legacy repair networks lack.
- Dual certification timelines:Simultaneous DOE and Natural Resources Canada approval processes delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Washing Machine Market |
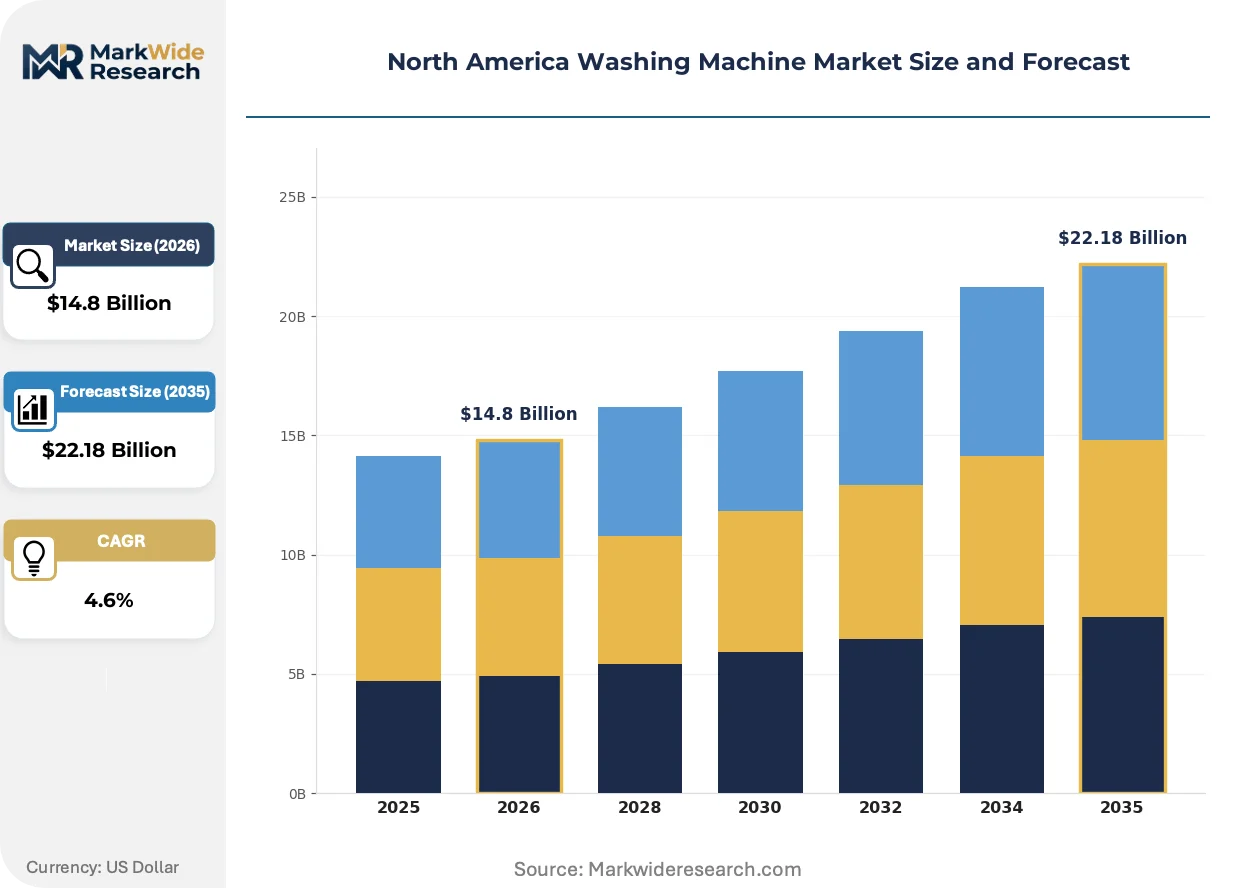
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Load, Top Load, Semi-Automatic, Washer-Dryer Combo Technology: Smart Appliance, Energy-Efficient, Steam Technology, Variable Speed End User: Households, Laundry Services, Hospitality, Commercial Use Distribution Channel: Online Retail, Specialist Stores, Hypermarkets, Distributors |
| Companies Covered | GE Appliances, Haier Smart Home, Whirlpool Corporation, Bosch Home Appliances, Hitachi, LG Electronics, Electrolux AB, Speed Queen, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Washing Machine Market Evolving Landscape
Sensor-integrated wash cycles and connected fleet management are compressing the traditional boundaries between residential convenience and commercial operational discipline. Manufacturers are racing to embed predictive capabilities that reduce service dispatch frequency.
Direct drive motor technology is eliminating belt-and-pulley systems in favor of rotor-mounted drums that reduce mechanical failure points. Multi-housing operators in the US Sun Belt are specifying these configurations for their 10-year durability ratings. This architecture is virtualizing the traditional service revenue model by enabling remote torque monitoring that flags bearing wear before catastrophic failure.
The US Department of Energy's pending ENERGY STAR 8.0 specification tightens integrated modified energy factor thresholds by 15% over current standards. Manufacturers serving California and New York must accelerate platform redesigns to maintain rebate eligibility. Front-load product lines face the steepest compliance engineering costs due to their complex water extraction mechanics.
Rental housing operators are unbundling appliance procurement from property acquisition, treating washers as subscription-managed assets rather than capital improvements. Institutional buyers now specify outcome-based performance contracts with uptime guarantees. This pattern concentrates in Sun Belt states where private equity multifamily acquisitions dominate new construction financing.
North America Washing Machine Market Segmentation
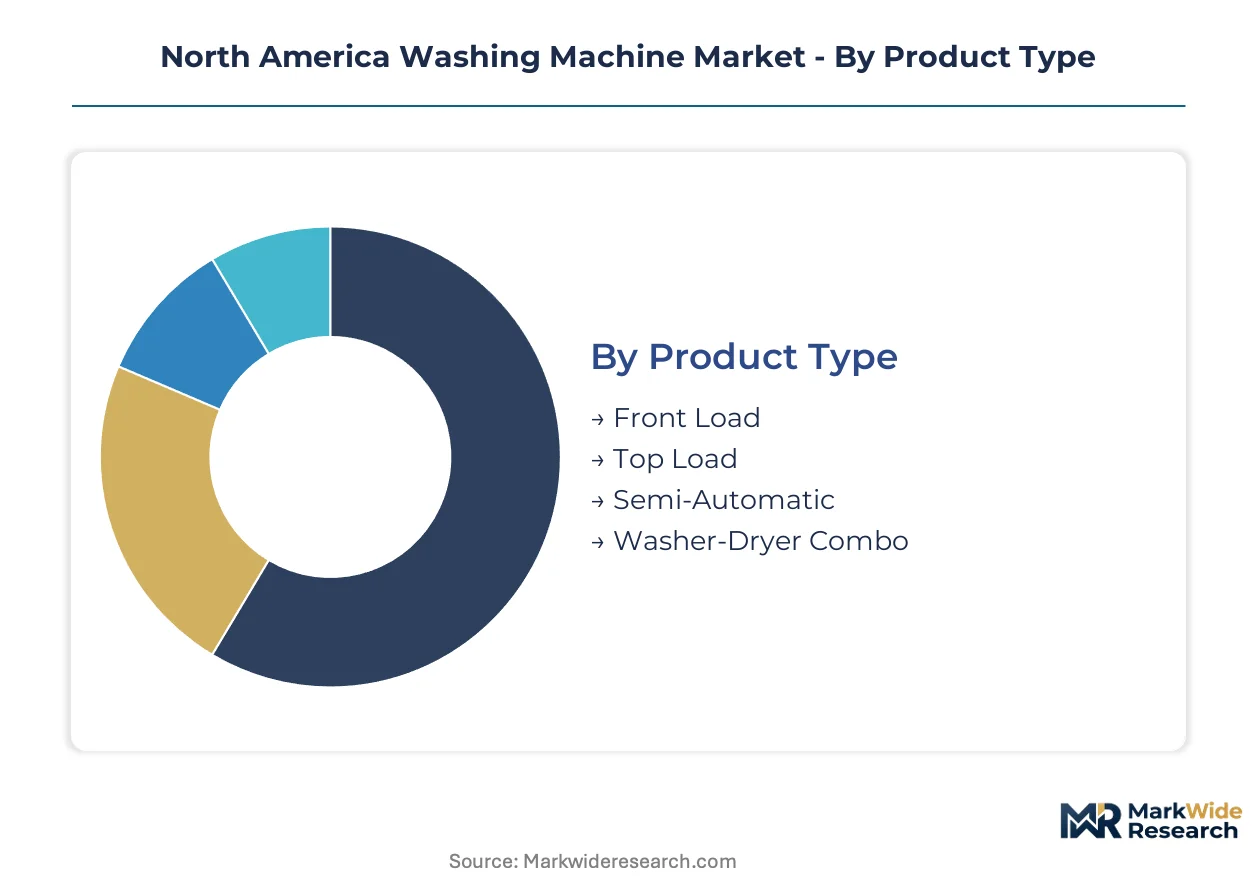
Segmentation in the North America washing machine market reveals divergent replacement cycles and margin structures across configuration types and end-use applications. Understanding these differences helps suppliers align platform investments with the highest-velocity revenue pools.
Product Type:
Replacement cycles stretch from 8 years for basic top-load units to 15 years for commercial-grade front-load installations, creating distinct aftermarket revenue profiles.
- Front Load:Horizontal-axis drum orientation enables superior water extraction at 1200-1600 RPM spin speeds. Demand concentrates in California and New York where ENERGY STAR rebate thresholds favor high-efficiency designs and water utility rates accelerate payback calculations.
- Top Load:Vertical-axis agitator systems dominate legacy installed base across the US Midwest and South. Replacement demand here ties to failure-driven purchases rather than efficiency upgrades, compressing average selling prices.
- Semi-Automatic:Twin-tub designs with manual water-fill requirements occupy niche roles in rural Canadian markets and off-grid installations.
- Washer-Dryer Combo:Ventless condensation drying suits urban multi-housing with space constraints. Adoption clusters in Manhattan, San Francisco, and Vancouver high-rise developments.
Top Load dominates installed base. Front Load is where expansion concentrates.
Technology:
Technology tiers separate warranty-backed premium positioning from price-competitive replacement segments, with connectivity features commanding 40-60% price premiums.
- Smart Appliance:WiFi-enabled diagnostic platforms with mobile cycle management. Demand concentrates in Texas and Florida multi-family developments where property managers prioritize remote fleet monitoring and predictive maintenance contracts.
- Energy-Efficient:Direct drive motors and sensor-driven water level optimization. Adoption accelerates in Ontario and British Columbia where provincial rebate programs offset upfront cost differentials.
- Steam Technology:High-temperature sanitization cycles targeting allergen reduction and commercial hygiene standards.
- Variable Speed:Inverter-controlled drum motors that adapt torque to load size and fabric type.
Energy-Efficient configurations anchor volume shipments. Smart Appliance is climbing the fastest.
End User:
End-user segmentation exposes radically different procurement behaviors, from failure-driven household replacement to contract-negotiated institutional fleet purchases.
- Households:Individual purchase decisions driven by failure events, kitchen renovations, or new home acquisitions. Replacement cycles average 10-12 years with seasonal concentration in spring moving periods.
- Hospitality:Brand-standard procurement contracts with 5-7 year forced replacement schedules. Demand concentrates in Orlando, Las Vegas, and Scottsdale resort corridors where occupancy rates justify accelerated capital rotation.
- Laundry Services:Coin-op and card-operated installations in urban density corridors.
- Commercial Use:On-premise laundry for hospitals, correctional facilities, and athletic organizations.
Households dominate installed base. Hospitality is gaining share fastest.
Distribution Channel:
Channel structure reflects the tension between immediate availability for failure replacement and extended decision cycles for new construction specification.
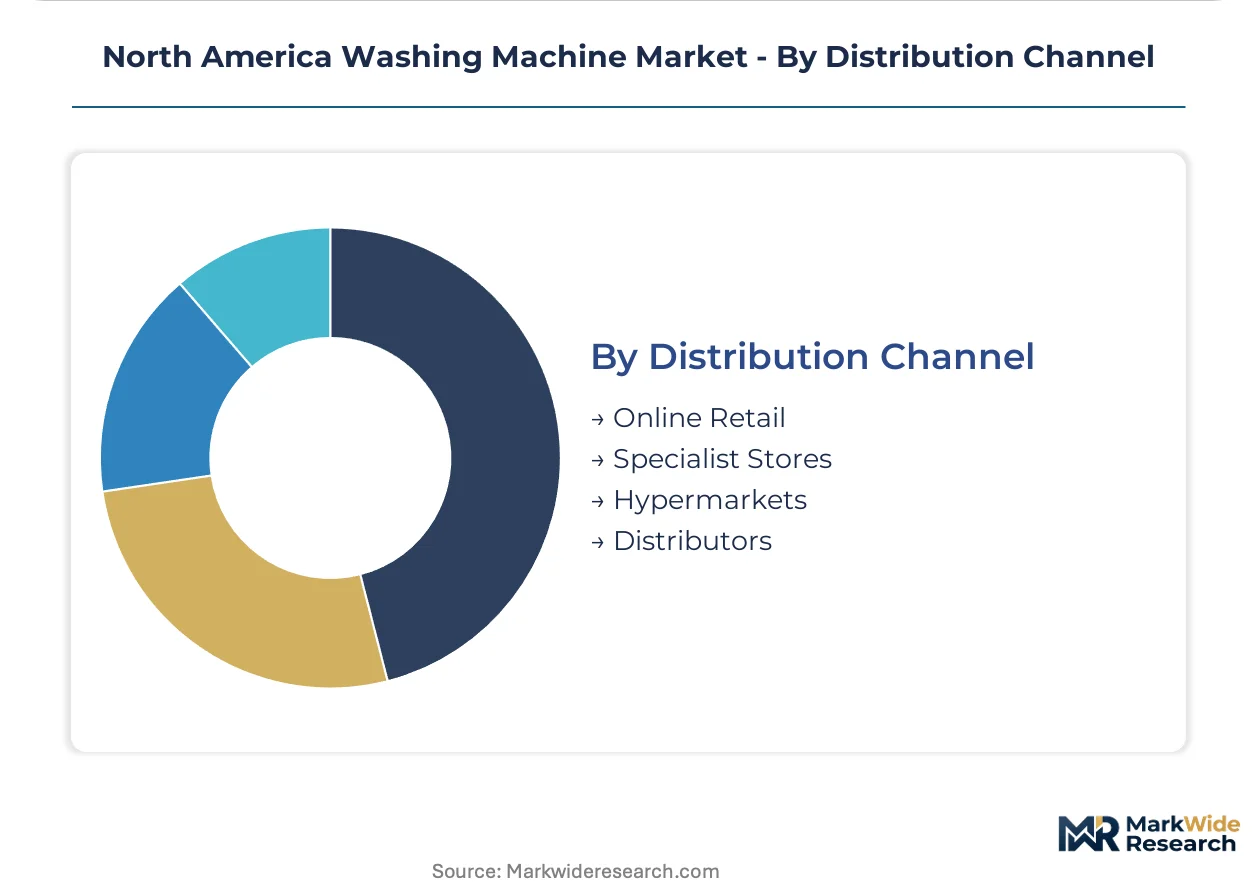
- Online Retail:Direct-to-consumer platforms with 2-5 day delivery windows. Growth concentrates in suburban markets where big-box travel time exceeds digital purchase convenience thresholds.
- Specialist Stores:Independent dealers with installation and haul-away services. Loyalty persists in older demographics and complex retrofit scenarios requiring site assessment.
- Hypermarkets:Mass merchants with promotional pricing and immediate inventory pickup.
- Distributors:B2B procurement channels serving multi-housing developers and institutional buyers with volume pricing and staging coordination.
Hypermarkets dominate installed base. Online Retail is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal rebate programs and state-level efficiency mandates are redirecting procurement patterns across North America. The US Department of Energy's ENERGY STAR 8.0 specification tightens water extraction thresholds. Provincial incentive schemes in Canada accelerate premium product turnover.
United States
Multi-family housing construction in Texas, Florida, and Arizona drives in-unit appliance installations at record rates. The EPA's WaterSense certification pulls consumer preference toward front-load configurations that reduce per-cycle water consumption. Developers in Houston, Phoenix, and Orlando specify connected diagnostic platforms for remote fleet management in institutional portfolios.
Canada
Natural Resources Canada's EnerGuide-linked rebate programs in Ontario and British Columbia subsidize premium efficiency upgrades. Provincial regulators enforce parallel certification timelines that delay cross-border product launches. Toronto and Vancouver high-rise developments cluster demand for ventless washer-dryer combos suited to space-constrained urban units.
Mexico
Appliance assembly plants in Nuevo León and Chihuahua face customs delays from cross-border component dependencies. The country's national energy efficiency regulator aligns with US DOE standards for export-bound production. Monterrey industrial corridors concentrate manufacturing capacity serving both domestic replacement cycles and re-export to US distributors.
North America Washing Machine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. Mass merchants and direct-to-consumer platforms now capture share from independent dealers in suburban markets. Three archetypes dominate: diversified home appliance conglomerates with captive service networks, commercial-grade durability specialists targeting multi-housing operators, and electronics manufacturers leveraging smart connectivity ecosystems. Consolidation pressures intensify through backward integration into financing programs and extended warranty revenue streams.
Among North American-based manufacturers, Whirlpool Corporation and GE Appliances exemplify the diversified conglomerate archetype with integrated service infrastructure. Speed Queen occupies a distinct position as the durability specialist serving institutional laundry operators. Korean electronics manufacturers LG Electronics and Samsung Electronics anchor the smart appliance vector with connected platform ecosystems. These five entities represent the competitive poles around which mid-tier and regional fabricators organize their positioning.
| Leading Market Players |
|---|
| GE Appliances |
| Haier Smart Home |
| Whirlpool Corporation |
| Bosch Home Appliances |
| Hitachi |
| LG Electronics |
| Electrolux AB |
| Speed Queen |
| Samsung Electronics |
| Others |
Value Network & Pricing Analysis
Mexican assembly concentration in Nuevo León and Chihuahua feeds directly into margin pools held by distributors serving multi-housing developers across Texas and Florida. Steel drum and copper motor winding costs transmit volatility through OEM pricing schedules, while ENERGY STAR certification tiers create divergent profitability across product lines.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with ENERGY STAR 8.0-compliant front-load configurations commanding substantial premiums over baseline top-load units. Three-tier pricing structure across premium connected models, certified efficient designs, and economy agitator systems segments buyer pools by replacement urgency and rebate eligibility. Pricing pressure stems from steel and copper commodity swings that compress OEM margins on drum assemblies and motor windings. Multi-housing developers exhibit lowest price sensitivity due to subscription financing models, while failure-driven household replacements in the Midwest show highest elasticity.
Supply Chain Analysis
Extended payment terms from appliance distributors to component suppliers have become standard practice across Mexican assembly corridors. Manufacturing concentrates in Mexico, China, and South Korea, with drum assemblies and electronic control boards feeding from Asian component networks. The supply chain rests on cross-border customs exposure and single-source vulnerability for specialized motor controllers. Distribution runs through mass merchant hypermarkets, direct-to-consumer platforms, and institutional procurement channels serving multi-family developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America washing machine market is approaching a platform-economics inflection as connected appliance ecosystems converge with utility demand-response programs and property management software stacks.
For Market Incumbents: Insulate service revenue streams by embedding predictive diagnostics that flag bearing wear and motor torque anomalies before catastrophic failure. Capture backward integration into captive financing programs that lock multi-housing operators into extended replacement cycles. Threat substitution from Korean electronics manufacturers with smart home ecosystems demands accelerated platform integration with property management software. For New Entrants and Emerging Players: Pursue white-space opportunities in commercial laundry-as-a-service subscriptions for Sun Belt apartment operators unbundling appliance procurement from property acquisition. Target Canadian provincial rebate corridors in Ontario and British Columbia where EnerGuide-linked incentives accelerate premium efficiency turnover. Go-to-market through utility demand-response partnerships that position AI-driven cycle optimization as grid stabilization infrastructure. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across smart appliance segments as software-defined service models replace hardware-centric revenue. Long-term viability over the coming decade hinges on recurring revenue attachment rates from predictive maintenance contracts and extended warranty programs. Acquisition targets should demonstrate installed base density in institutional multi-housing portfolios. The signal to monitor is utility rebate program expansion into connected fleet management as grid modernization accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Platform Integration | WiFi-enabled diagnostics from LG and Samsung converge with property management software for remote fleet oversight. |
| Backward Integration into Financing | GE Appliances and Whirlpool leverage captive lending programs to lock institutional buyers into replacement cycles. |
| Direct Drive Motor Transition | Elimination of belt-and-pulley systems reduces mechanical failure points and extends service intervals for multi-housing operators. |
| Provincial Rebate Program Alignment | EnerGuide-linked incentives in Ontario and British Columbia accelerate premium product turnover for cross-border suppliers. |
| AI-Driven Cycle Optimization | Machine learning algorithms adapting water levels to fabric sensors integrate with utility demand-response programs. |
Research Methodology
Initial hypotheses were tested against primary input from multi-housing procurement directors, appliance service network managers, and utility demand-response program administrators and refined through secondary validation. Primary fieldwork encompassed structured interviews with OEM platform engineers, aftermarket parts distributors, and ENERGY STAR certification specialists. Secondary sources included US Department of Energy efficiency rulemaking dockets, Natural Resources Canada EnerGuide databases, EPA WaterSense certification records, and customs trade data on steel and copper imports. Bottom-up shipment modeling triangulated against top-down construction permit correlations across Sun Belt metropolitan areas.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with replacement cycle segmentation by product configuration and end-use application driving volume allocations. Segmentation dimensions encompassed front-load versus top-load orientation, smart versus conventional technology tiers, and household versus hospitality versus commercial end-use categories. CAGRs derived from regression analysis against housing starts, migration patterns, and rebate program enrollment trajectories. Industry-specific forecast inputs incorporated ENERGY STAR 8.0 compliance timelines and provincial incentive program renewal schedules.
Sensitivities concentrate around steel and copper commodity volatility, cross-border tariff regime shifts, and ENERGY STAR specification delays. Forecasts reflect documented assumptions on replacement cycle elasticity and rebate program participation rates. Macroeconomic contraction in multi-family construction, regulatory deviation from efficiency mandates, or technological disruption from heat pump drying breakthroughs would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Conveyor Dishwasher Market
Appliances
Industrial Gas Stove Market
Appliances
Germany Consumer Appliances Market
Appliances
Asia-Pacific Electric Rice Cooker Market
Appliances
UAE Dishwasher Market
Appliances
Mexico Laundry Appliances Market
Appliances
Small Appliances Market
Appliances
Electric Rice Cooker Market
Appliances
Smart Ceiling Fan Market
Appliances
Fully Automatic Dishwasher Market
Appliances
Intelligent Electric Rice Cooker Market
Appliances
Refrigerator Repair Service Market
Appliances
Shared Shoe Washing Machine Market
Appliances
France Household Side by Side Refrigerator Market
Appliances
Household Vacuum Cleaners Market
Appliances
Microwave Oven Market