
 UK Residential Vacuum Cleaner Market | 2026-2036
UK Residential Vacuum Cleaner Market Size, Share, and Industry Trends Forecast 2026-2036
UK Residential Vacuum Cleaner Market Analytics
Online retail is tilting the competitive landscape for vacuum cleaner sales in the United Kingdom. Dyson leverages its direct-to-consumer digital platform to control pricing and capture customer data. SharkNinja competes aggressively through Amazon and major e-commerce portals with promotional bundling strategies. Vax sustains relevance via specialized online vacuum retailers and its own refurbished goods channel.
A residential vacuum cleaner is an electrically powered suction device designed for domestic floor and surface cleaning, typically operating at 400-900 watts under UK Ecodesign limits and employing cyclonic separation or filtered bag collection to trap particulates. Its primary commercial purpose is to remove dust, allergens, and debris from carpets, hard floors, and upholstery within private dwellings. Cordless stick models are capturing the fastest growth trajectory as lithium-ion battery density improves runtime beyond forty minutes per charge. Robotic units occupy an emerging premium tier where autonomous navigation and smart home integration command higher margins despite lower absolute volumes. Canister designs retain dominance among households with mixed flooring and pet ownership due to superior suction versatility and larger debris capacity.
The UK Office for Product Safety and Standards enforces electrical safety and energy labeling requirements that compel manufacturers to disclose annual energy consumption and dust re-emission class on all residential vacuum cleaners sold in Great Britain. BEIS energy efficiency mandates and forthcoming extended producer responsibility frameworks for electrical waste are reshaping material choices and end-of-life collection obligations across the supply chain. Stakeholders must monitor how potential divergence between UKCA and retained EU Ecodesign regulations after full border controls could fragment compliance costs and alter competitive positioning for imported versus domestically assembled units.
Market Dynamics
The UK Residential Vacuum Cleaner Market is being fundamentally restructured by the BEIS energy efficiency mandates and extended producer responsibility frameworks, which are forcing manufacturers to redesign motor architectures and establish domestic collection networks for end-of-life units before full border controls take effect.
Growth Catalysts
- Urban space constraints:London and Manchester apartment dwellers are prioritizing cordless stick designs that store vertically in compact utility closets. This demographic shift favors slim-form-factor engineering over traditional canister bulk.
- UK Ecodesign Regulations:The retained EU Ecodesign standards for energy-related products are tightening motor efficiency thresholds, compelling manufacturers to invest in brushless DC motor platforms that simultaneously reduce power draw and maintain suction performance.
- Lithium-ion density improvements:Battery cell chemistry advances are extending cordless runtime beyond forty minutes per charge, erasing the final performance gap that previously tethered consumers to corded alternatives.
Market Restraints
- Semiconductor supply concentration:Brushless motor controllers and battery management systems depend on fab capacity concentrated in East Asia, exposing UK assemblers to lead time volatility and tariff uncertainty.
- Raw material cost exposure:Neodymium magnet prices fluctuate with Chinese export quotas, directly impacting motor cost structures for premium cordless models targeting the efficiency tier.
- Technical ceiling on suction-per-watt:Physics limits on cyclonic separation efficiency are approaching asymptotic returns, constraining differentiation through pure performance metrics.
Strategic Opportunities
- Scottish Highlands penetration:Rural Scottish households with mixed flooring and pet ownership remain underserved by cordless marketing, presenting white space for ruggedized canister variants with extended hose reach.
- Smart home convergence:Integration of LiDAR mapping and Matter protocol compatibility is creating a premium autonomous tier where robotic units command subscription revenue through consumable replenishment automation.
- Refurbished goods channel expansion:The UK's forthcoming extended producer responsibility mandates incentivize manufacturer-controlled refurbishment programs that capture secondary market margin and satisfy compliance obligations simultaneously.
Industry Challenges
- UKCA marking divergence:Potential misalignment between retained EU Ecodesign standards and emerging UKCA technical specifications threatens dual certification burdens for imported components.
- Battery recycling infrastructure gaps:The absence of localized lithium-ion cell processing capacity forces manufacturers to fund expensive reverse logistics to continental European recyclers, compressing circular economy margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Residential Vacuum Cleaner Market |
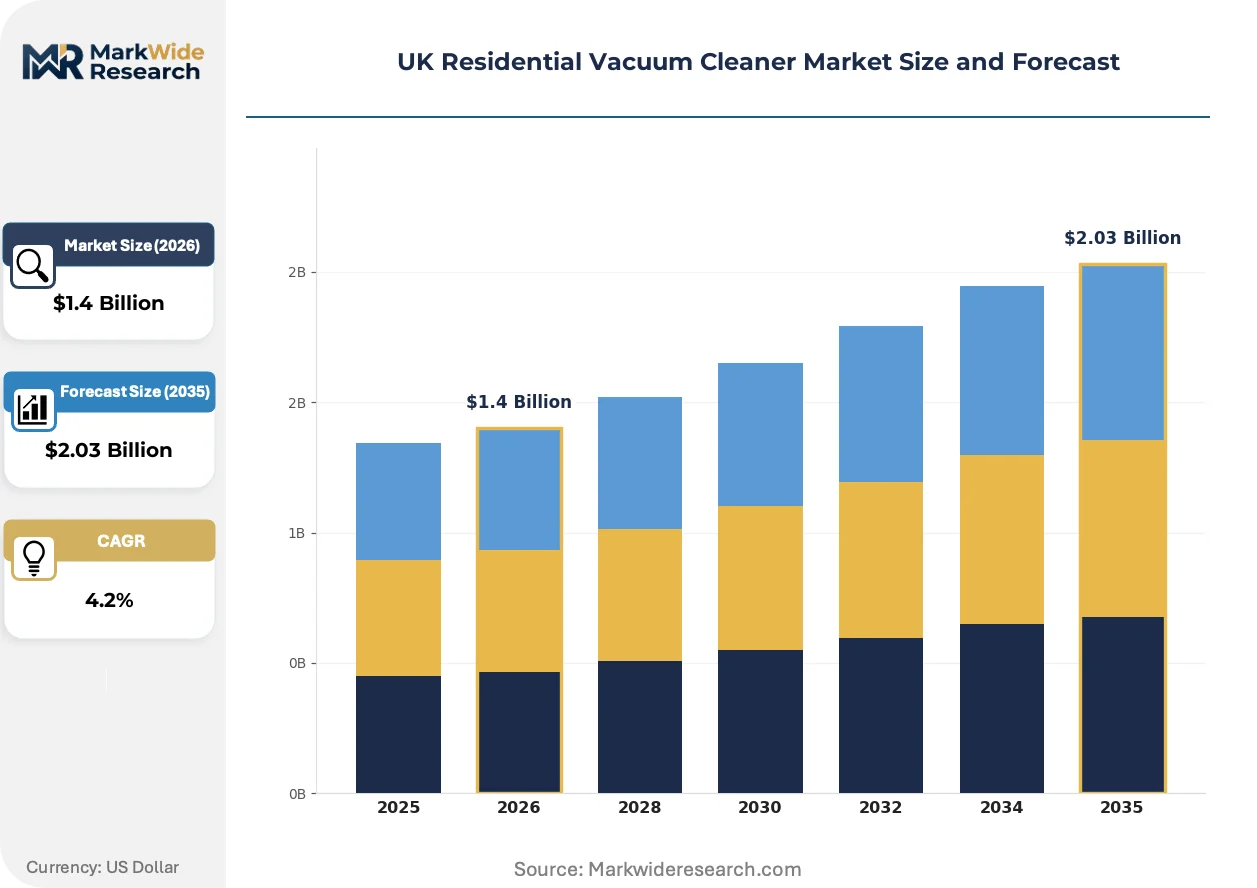
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.03 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upright, Canister, Robotic, Stick Technology: Corded, Cordless, Bagless, Hybrid End User: Households, Apartments, Hostels, Hotels Distribution Channel: Online, Specialty Stores, Supermarkets, Home Improvement Stores |
| Companies Covered | Dyson, SharkNinja, Vax, Hoover Candy Group, Miele, iRobot, Ecovacs Robotics, Nilfisk Group, Bissell, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Residential Vacuum Cleaner Market Evolving Landscape
Digital suction mapping and predictive maintenance algorithms are redefining how manufacturers capture recurring revenue from hardware that was previously a one-time transaction. Software-enabled differentiation is displacing raw specification competition across all price tiers.
Digital motor control firmware is virtualizing the traditional relationship between hardware suction power and cleaning efficacy. Premium manufacturers are embedding pressure sensors and surface-recognition algorithms that automatically modulate airflow based on real-time debris detection. This capability is virtualizing consumer purchasing criteria, shifting buyer attention from wattage ratings to software-enabled convenience features that justify subscription service attachments.
BEIS extended producer responsibility consultations are mandating modular design standards and standardized disassembly protocols for electrical waste. Manufacturers must now engineer snap-fit housing joints and universal screw patterns to facilitate automated recycling line processing. The cordless stick segment faces the steepest compliance redesign burden due to integrated battery pack architectures that complicate material separation.
Direct-to-consumer channel preference is fragmenting traditional retail relationships as buyers research replacement cycles through manufacturer apps rather than store associates. Younger household formations in England's metropolitan corridors are purchasing through proprietary digital platforms that bundle financing and trade-in programs. This behavioral shift concentrates customer data ownership with vertically integrated brands and erodes distributor margin pools that previously captured post-sale accessory revenue.
UK Residential Vacuum Cleaner Market Segmentation
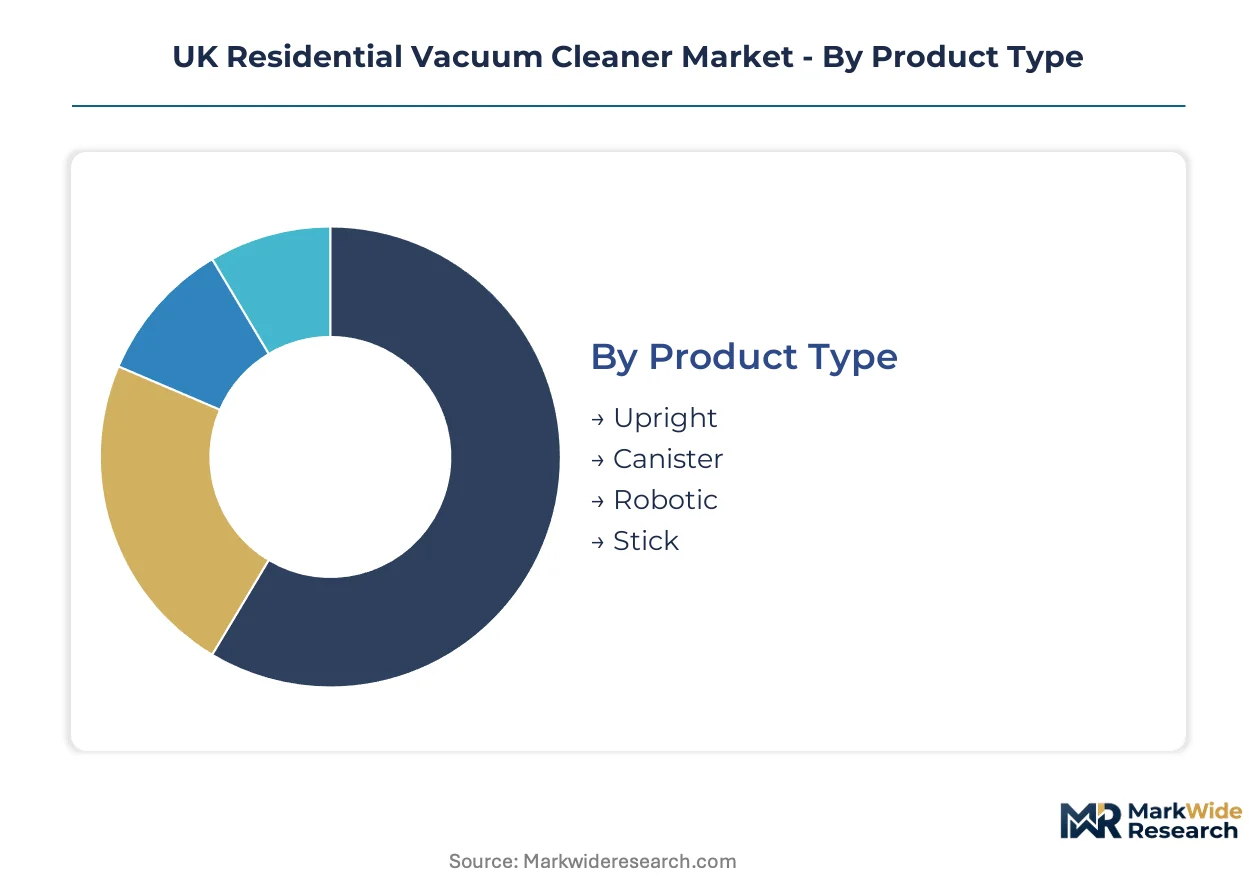
Segmentation in the UK residential vacuum cleaner market reveals how BEIS energy regulations and urban housing patterns split demand across incompatible use cases. Manufacturers must align motor efficiency investments with specific channel and end-user requirements to avoid stranded inventory.
Product Type:
Cordless stick models turn over fastest as London and Manchester apartment dwellers replace units every 3-4 years, while canister designs persist 7-10 years in rural households with mixed flooring needs.
- Upright:Traditional motorized brushroll designs dominate suburban semi-detached homes with wall-to-wall carpeting across England's Home Counties. BEIS motor efficiency thresholds are forcing brushless DC motor retrofits that add £40-60 to bill-of-materials costs.
- Canister:Separate suction unit with extended hose reach serves Scottish Highlands households and pet owners requiring superior debris capacity. Ruggedized variants with metal wands command premium positioning where cordless runtime limitations disqualify stick alternatives.
- Robotic:Autonomous LiDAR-enabled units with Matter protocol compatibility target tech-forward households in Bristol and Cambridge smart home clusters.
- Stick:Vertical-storage cordless designs with lithium-ion packs below 2.5kg capture metropolitan corridor demand where utility closet dimensions constrain form factor.
Canister designs anchor the volume base among established homeowners while stick models gain share at the steepest rate.
Technology:
Cost tiers separate corded efficiency compliance from cordless battery premiums, with hybrid architectures emerging to bridge the gap.
- Corded:Mains-powered units operating at 400-900 watts under retained EU Ecodesign limits dominate price-sensitive segments. BEIS labeling mandates require annual energy consumption disclosure on packaging, compressing margin for entry-tier assemblers.
- Cordless:Lithium-ion battery systems with brushless DC motors extend runtime beyond forty minutes, eliminating the final performance gap with corded alternatives. Cell chemistry improvements from Korean and Japanese suppliers determine competitive positioning.
- Bagless:Cyclonic separation chambers with HEPA filtration reduce recurring consumable costs, appealing to allergy-sensitive households in Birmingham and Leeds metropolitan areas.
- Hybrid:Dual-power architectures allowing corded operation with detachable battery packs target transitional users unconvinced by pure cordless reliability.
Corded technology retains the widest installed base while cordless configurations expand most quickly.
End User:
Customer type determines sensitivity to upfront cost versus total cost of ownership, with commercial operators prioritizing durability metrics.
- Households:Owner-occupied dwellings with mixed flooring drive canister and upright demand, particularly in England's suburban corridors where pet ownership rates exceed 40%.
- Apartments:Space-constrained urban dwellers in London, Manchester, and Edinburgh prioritize stick models with vertical storage and sub-3kg weight profiles.
- Hostels:High-turnover budget accommodation operators demand commercial-grade durability and rapid replacement parts availability.
- Hotels:Boutique and chain properties specify low-noise operation and rapid charge cycles for housekeeping efficiency.
Households generate the absolute volume while apartments drive the steepest product mix shift.
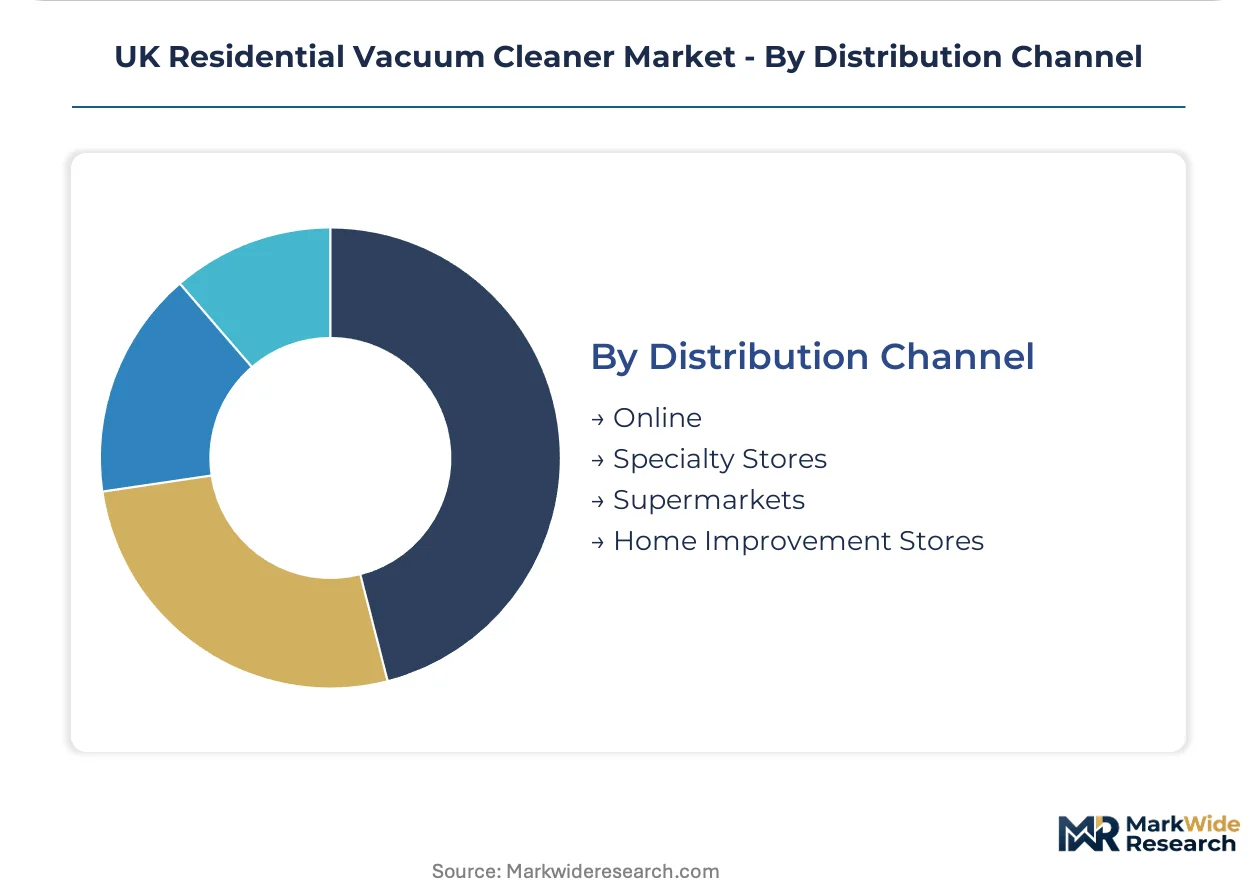
Distribution Channel:
Channel concentration determines margin capture, with direct-to-consumer platforms extracting data value that traditional retail cannot replicate.
- Online:Manufacturer-direct platforms and Amazon marketplace listings concentrate among younger household formations researching replacement cycles through mobile apps. Trade-in program bundling locks in repeat purchase behavior.
- Specialty Stores:Independent vacuum retailers in England's market towns sustain canister and commercial-grade sales through demonstration-based conversion.
- Supermarkets:Grocery multiples capture impulse purchases and entry-tier corded models through seasonal promotional cycles.
- Home Improvement Stores:B&Q, Wickes, and similar chains serve DIY-oriented homeowners undertaking renovation-triggered appliance upgrades.
Online channels capture the steepest growth trajectory while specialty stores defend the highest-margin canister segment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's metropolitan corridor commands 15-20% price premiums over Northern England for equivalent cordless stick specifications, while Scottish rural markets absorb higher logistics costs for canister variants with extended hose systems.
London and Southeast England
Space-constrained apartment dwellers in Greater London and commuter belt counties drive demand for sub-2.5kg stick models with vertical storage. BEIS energy labeling mandates require annual consumption disclosure at point of sale, compressing margin for entry-tier assemblers. Tech-forward households in Cambridge and Bristol smart home clusters pilot robotic units with Matter protocol integration.
Midlands
Owner-occupied suburban homes across Birmingham and Leicester metropolitan areas sustain canister demand for mixed flooring and pet hair removal. The retained EU Ecodesign regulations enforce 400-900 watt motor limits through the Office for Product Safety and Standards. Independent vacuum retailers in market towns defend high-margin demonstration-based conversion against online channel erosion.
North England
Manchester's urban core mirrors London's cordless preference, while surrounding Lancashire and Yorkshire retain corded upright penetration in older housing stock. Extended producer responsibility consultations are mandating modular design standards for end-of-life processing. Sheffield and Leeds manufacturing heritage supports domestic assembly operations for premium motor platforms.
Scotland
Rural Highlands households with mixed flooring and livestock exposure require ruggedized canister variants with metal wands and extended reach. The Scottish Environment Protection Agency enforces waste electrical equipment collection targets that exceed English baseline requirements. Edinburgh's compact Georgian tenements favor stick models, creating intra-regional product mix divergence.
Wales and Northern Ireland
Price-sensitive markets in South Wales valleys and Belfast metropolitan area concentrate entry-tier corded sales through supermarket promotional cycles. Divergence risk between UKCA marking and retained EU standards threatens dual certification burdens for importers. Local authority waste partnerships in Cardiff and Derry pilot manufacturer-funded battery reverse logistics schemes.
UK Residential Vacuum Cleaner Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying brushless DC motors and lithium-ion cells to multiple assemblers. The UK market structures around three archetypes: vertically integrated brands with direct-to-consumer digital platforms, appliance conglomerates leveraging retail scale, and robotic specialists extracting subscription revenue through consumable automation. Competitive moves concentrate on proprietary battery ecosystem lock-in and trade-in program bundling to compress replacement cycles.
Among UK-originated engineering houses, Dyson and Vax occupy positions that exemplify divergent channel strategies—one extracting margin through data-rich proprietary platforms, the other defending relevance via refurbished goods channels and specialized retail partnerships. SharkNinja, organized as a US-based limited liability structure, anchors the aggressive promotional tier through Amazon marketplace dominance and seasonal bundling tactics. These three collectively illustrate how origin and corporate form shape competitive optionality under BEIS regulatory pressure.
| Leading Market Players |
|---|
| Dyson |
| SharkNinja |
| Vax |
| Hoover Candy Group |
| Miele |
| iRobot |
| Ecovacs Robotics |
| Nilfisk Group |
| Bissell |
| Others |
Value Network & Pricing Analysis
Chinese neodymium export quota volatility compresses margin structures across both premium cordless tiers and entry-level corded segments, forcing assemblers to either absorb magnet cost spikes or pass them through to price-sensitive metropolitan buyers. This single-input dependency simultaneously widens the spread between efficiency-compliant brushless motor platforms and legacy brushed alternatives while concentrating supplier financing leverage with East Asian cell manufacturers.
Pricing Analysis
Configured-to-order pricing for modular stick designs with swappable battery packs commands £80-120 premiums over standard SKUs through manufacturer-direct platforms. Three-tier pricing structure across premium, standard, and economy levels separates Dyson's proprietary ecosystem from SharkNinja's promotional bundling and Vax's refurbished channel. Cost compression in the entry corded tier is intensifying because BEIS energy labeling mandates add compliance documentation costs that smaller assemblers cannot amortize. Apartment dwellers in London and Manchester show lowest price sensitivity for sub-2.5kg stick models, while Welsh and Northern Irish households concentrate in supermarket promotional cycles for basic corded units.
Supply Chain Analysis
Extended payment terms from Korean and Japanese lithium-ion cell suppliers now stretch 90-120 days, compressing working capital for UK assemblers lacking balance sheet depth. Brushless DC motors and battery management systems draw from concentrated fab capacity in Taiwan, South Korea, and China, with neodymium magnets and cobalt cathode materials feeding from Chinese processing hubs. Single-source vulnerability in semiconductor motor controllers exposes assemblers to tariff uncertainty as UKCA divergence risk mounts. Distribution runs through Amazon marketplace logistics and manufacturer-direct fulfillment centers, bypassing traditional distributor margin pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
BEIS extended producer responsibility mandates fragment competitive position by creating compliance-scale thresholds that favor mid-tier specialists over pure-play premium brands or undifferentiated volume assemblers.
For Market Incumbents: Harden proprietary battery ecosystem lock-in through trade-in program bundling that compresses replacement cycles below four years for stick models. Consolidate refurbishment channel control to satisfy forthcoming modular design mandates while capturing secondary market margin. Vertical integration into brushless motor firmware development defends against commoditization as cyclonic efficiency approaches physics limits. For New Entrants and Emerging Players: Scottish Highlands rural households with mixed flooring and livestock exposure present underpenetrated white space for ruggedized canister variants with metal wands and extended hose reach. Edinburgh's compact Georgian tenements favor premium stick configurations underserved by existing cordless marketing. Partner with independent vacuum retailers in Midlands market towns for demonstration-based conversion of allergy-sensitive households seeking HEPA filtration. For Investors and Strategic Acquirers: The UK's forthcoming full border controls and potential UKCA-Ecodesign divergence reshape the acquisition landscape by fragmenting compliance costs for imported versus domestically assembled units. Five-to-ten year viability favors targets with established reverse logistics networks and modular design IP. Monitor BEIS consultation timelines for extended producer responsibility implementation as the signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Expansion | Captures customer data and pricing control from Amazon-dependent competitors. |
| Modular Design Standard Adoption | Positions compliance advantage under BEIS extended producer responsibility mandates. |
| Battery Ecosystem Lock-In | Creates switching costs through proprietary cell formats and trade-in bundling. |
| Refurbished Goods Channel Buildout | Satisfies circular economy obligations while extracting secondary market margin. |
| Smart Home Protocol Integration | Commands subscription revenue through Matter-compatible robotic unit automation. |
Research Methodology
Desk research of customs import records, BEIS regulatory filings, and Office for Product Safety and Standards enforcement data preceded structured interviews with brushless motor procurement leads, lithium-ion cell supply planners, category buyers at major e-commerce platforms, and independent vacuum retailer owners. Primary fieldwork with appliance engineering directors and aftermarket service heads validated technical assumptions on cyclonic separation efficiency limits. Secondary sources included SEC filings of US-listed parent entities, UK retail audit data, and trade association energy consumption benchmarking. Bottom-up unit shipment estimates triangulated against top-down consumer expenditure flows.
Assumptions held BEIS Ecodesign motor efficiency thresholds at retained EU levels and lithium-ion cell chemistry improvements at observed Korean and Japanese supplier trajectories across the analysis window. The analytical framework modeled volume and value across product type, technology architecture, end-user segment, and distribution channel dimensions, with urban housing density as a cross-cutting demand modifier. CAGRs derived from regression of replacement cycle compression against cordless runtime extension. Forecast inputs incorporated semiconductor fab capacity utilization and neodymium price volatility indices.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese private-label assemblers or robotic subscription specialists would shift outcomes. Macroeconomic deviation in UK housing formation rates, regulatory acceleration of UKCA technical specifications, or breakthrough solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Bhutan and Nepal White Goods Market
Appliances
Asia Pacific Household Side by Side Refrigerator Market
Appliances
AI Washing Machine Market
Appliances
Cooker Hoods Market
Appliances
Cordless Vacuum Cleaner Market
Appliances
Tumble Dryer Market
Appliances
Domestic Food Preparation Appliances Market
Appliances
France Household Electric Grills Market
Appliances
Smart Microwave Oven Market
Appliances
Japan Massage Equipment Market
Appliances
Electric Rice Cooker Market
Appliances
Kuwait Dishwasher Market
Appliances
Smart Massage Appliances Market
Appliances
Mobile Refrigerators Market
Appliances
China Induction Hobs Market
Appliances
Personal Care Appliances Market