
 Asia-Pacific Washing Machine Market | 2026-2036
Asia-Pacific Washing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Washing Machine Market Outlook
The price-performance gap between premium front-loading units and basic top-loading models is hardening across the Asia-Pacific region. Midea Group leverages its vertical manufacturing footprint to dominate mass-market distribution in China. Haier Smart Home differentiates through connected-appliance ecosystems that command higher margins in urban Australia and South Korea. Samsung Electronics anchors its position with inverter-motor technology that reduces energy consumption for Southeast Asian consumers facing rising electricity tariffs.
A washing machine is an electromechanical appliance employing a rotating drum, water inlet systems, and programmable control modules to clean textiles through mechanical agitation, thermal cycling, and chemical detergent action, typically operating at spin speeds between 400 and 1600 revolutions per minute. Front-loading configurations achieve superior water and energy efficiency through horizontal-axis tumbling, while top-loading variants maintain stronger penetration in price-sensitive markets with shorter wash cycles. The 8-10 kg capacity band leads volume across multi-person households in India and Indonesia, whereas smart-technology integration represents the fastest-expanding margin pool as Wi-Fi-enabled units gain traction in Japan and Australian metropolitan markets. Commercial laundries and hotels constitute a concentrated but higher-margin end-user segment demanding above-10 kg capacities with industrial-grade durability cycles.
Japan's Ministry of Economy, Trade and Industry enforces Top Runner standards that mandate progressive efficiency improvements, while Australia's Water Efficiency Labelling and Standards scheme directly shapes consumer purchase decisions through visible star ratings. India's Bureau of Indian Standards has implemented compulsory registration for washing machines under its energy-labeling framework, tightening market access for uncertified imports. Stakeholders must monitor how China's dual carbon goals cascade into appliance efficiency mandates and whether India's PLI scheme for white goods manufacturing redraws regional supply configurations.
Market Dynamics
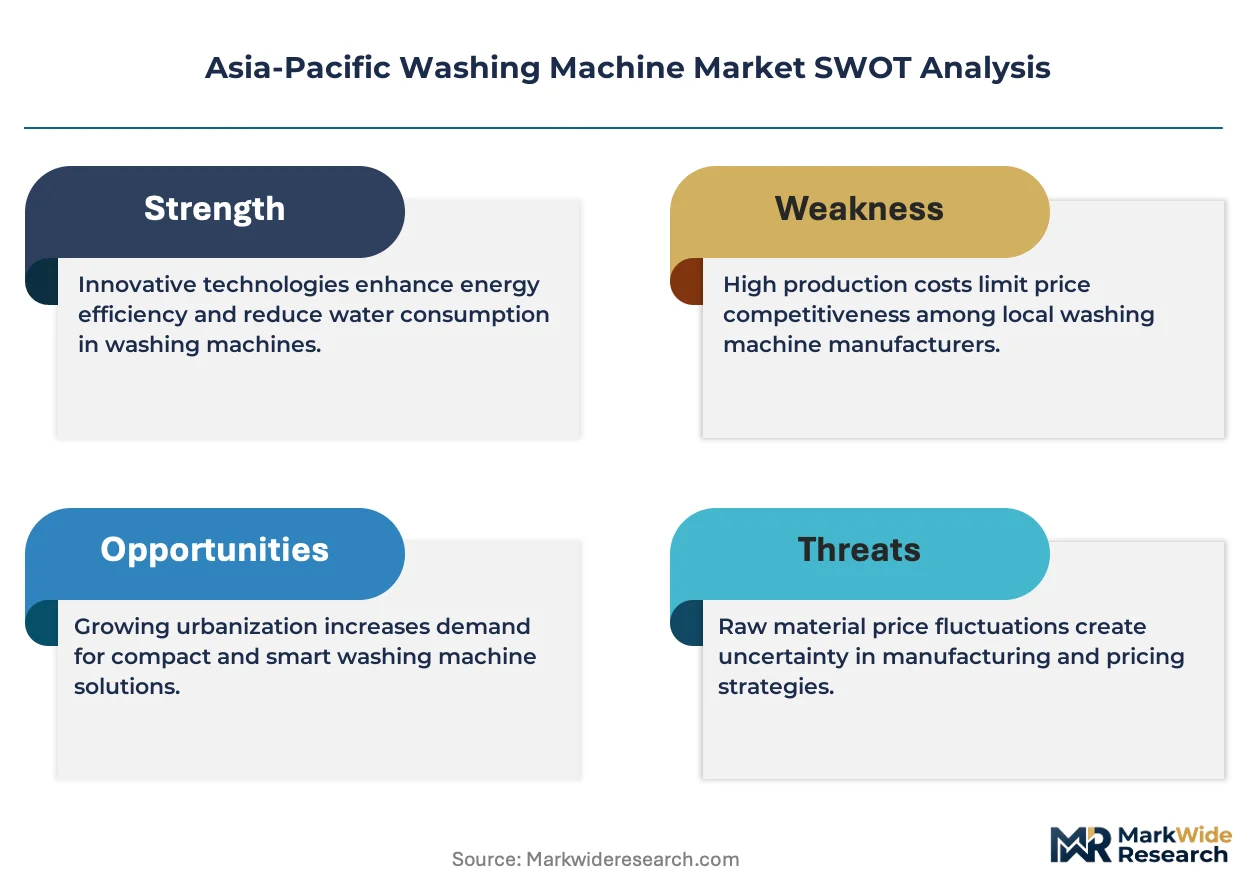
India's Bureau of Indian Standards water-efficiency mandates and China's dual carbon goals are compressing the cost-performance frontier for washing machine manufacturers across Asia-Pacific, forcing simultaneous redesign of motor systems, drum materials, and supply footprints.
Growth Catalysts
- India's PLI scheme for white goods:Production-linked incentives draw component suppliers toward Gujarat and Tamil Nadu manufacturing clusters, shortening lead times for domestic assembly.
- Urban replacement cycles:Tier-2 Indian cities and Vietnam's manufacturing corridors generate volume demand as first-generation appliances reach end-of-life.
- Inverter-motor diffusion:Variable-frequency drive technology cuts electricity consumption for Southeast Asian households facing tariff escalations.
Market Restraints
- Stainless steel price volatility:Drum and chassis input costs fluctuate with nickel and chromium spot markets, squeezing margin on mid-range units.
- Import certification friction:India's compulsory BIS registration blocks uncertified SKD kits at ports, delaying market entry for new suppliers.
- Manual washing persistence:Hand-wash habits in rural Indonesia and Philippines limit addressable market for automatic machines.
Strategic Opportunities
- Underpenetrated Vietnamese provinces:Central Highlands and Mekong Delta regions show low automatic-washer household penetration relative to Hanoi and Ho Chi Minh City.
- Wi-Fi-enabled ecosystem convergence:Smart-home integration with air conditioners and water heaters creates stickier customer relationships in Australian and South Korean metros.
- Commercial laundry services:Hotels and hospital chains in Thailand and Malaysia seek industrial-capacity units with 10 kg-plus drums and extended durability cycles.
Industry Challenges
- Embedded software talent scarcity:Connected-appliance firmware development lags hardware engineering capacity across the region.
- Multi-standard compliance timelines:Simultaneous BIS, JIS, and GB certification requirements extend product launch cycles for pan-Asia-Pacific portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Washing Machine Market |
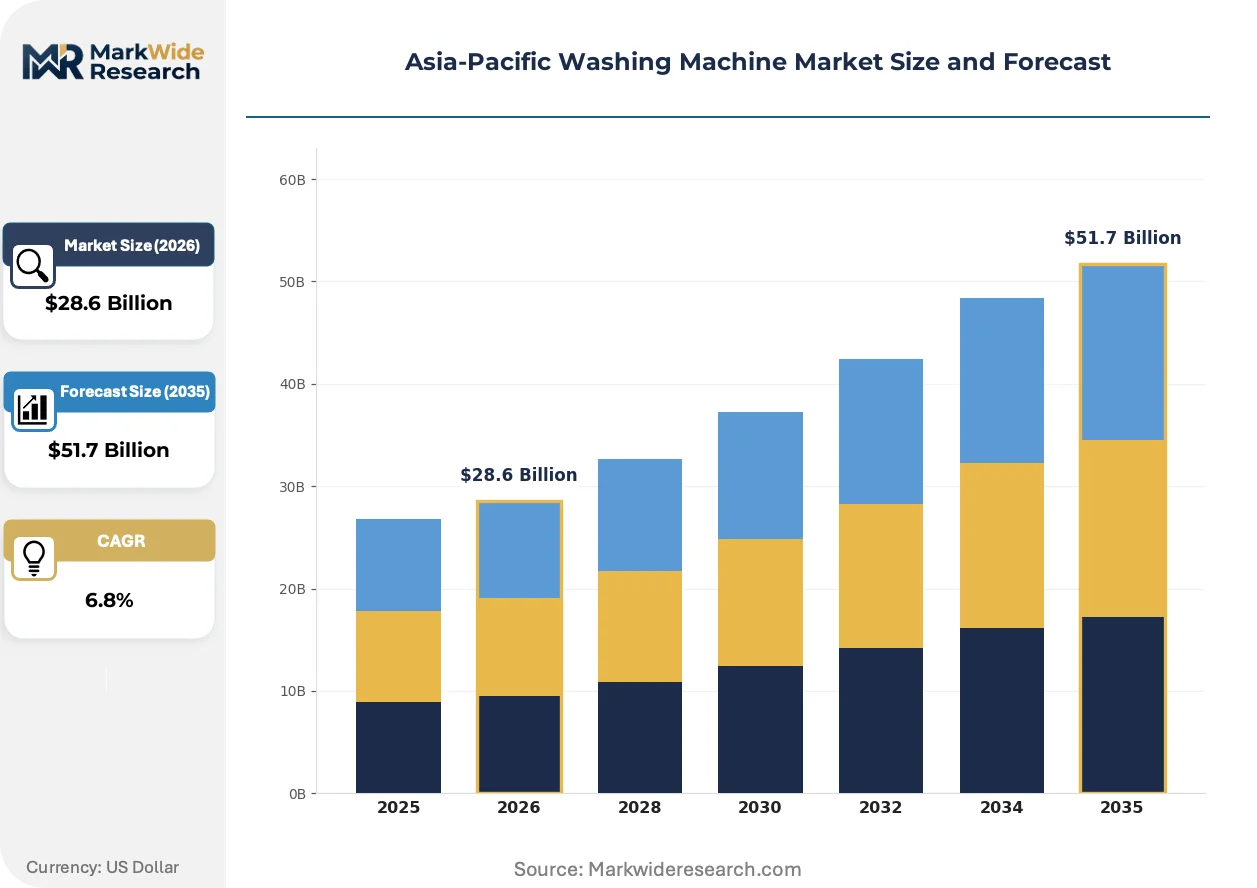
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Top-Loading, Front-Loading, Washer-Dryer Combo, Fully Automatic Technology: Smart Technology, Inverter, Energy Efficient, Conventional End User: Households, Commercial Laundries, Hotels, Educational Institutions Capacity: 5-7 kg, 8-10 kg, Above 10 kg, Below 5 kg |
| Companies Covered | Midea Group, Panasonic Corporation, Haier Smart Home, IFB, Hitachi, LG Electronics, Whirlpool Corporation, Godrej, Samsung Electronics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Washing Machine Market Strategic Shifts
Direct-drive motor architectures and AI-enabled load sensing are compressing the efficiency gap between premium and mass-market washing machines across Asia-Pacific, while regulatory labeling schemes reshape consumer decision frameworks.
Heat-pump drying technology is consolidating into mid-tier front-loading units as manufacturers transfer thermal-management expertise from air-conditioning divisions. Australian metropolitan buyers and Japanese condominium dwellers adopt these systems fastest, driven by space constraints and Australia's Water Efficiency Labelling and Standards star ratings. The technology is consolidating drying energy consumption by 40-50% versus conventional vented systems, forcing competitors to match thermal efficiency or retreat to price-only positioning.
Japan's METI Top Runner standards now mandate progressive efficiency improvements across successive product generations, with non-compliant models barred from domestic sale. Manufacturers must redesign inverter algorithms and drum insulation to meet tightening benchmarks. The policy most affects 8-10 kg capacity units targeting multi-person households, where volume concentration amplifies compliance costs.
Rental and subscription-based appliance access is displacing outright ownership among urban Australian millennials and Seoul apartment renters. Property developers bundle washer-dryer units into managed tenancy packages, shifting procurement authority from individual consumers to asset managers. This model concentrates purchase decisions in Sydney, Melbourne, and Seoul metropolitan planning offices, privileging suppliers with fleet-scale service networks over retail-channel specialists.
Asia-Pacific Washing Machine Market Segmentation
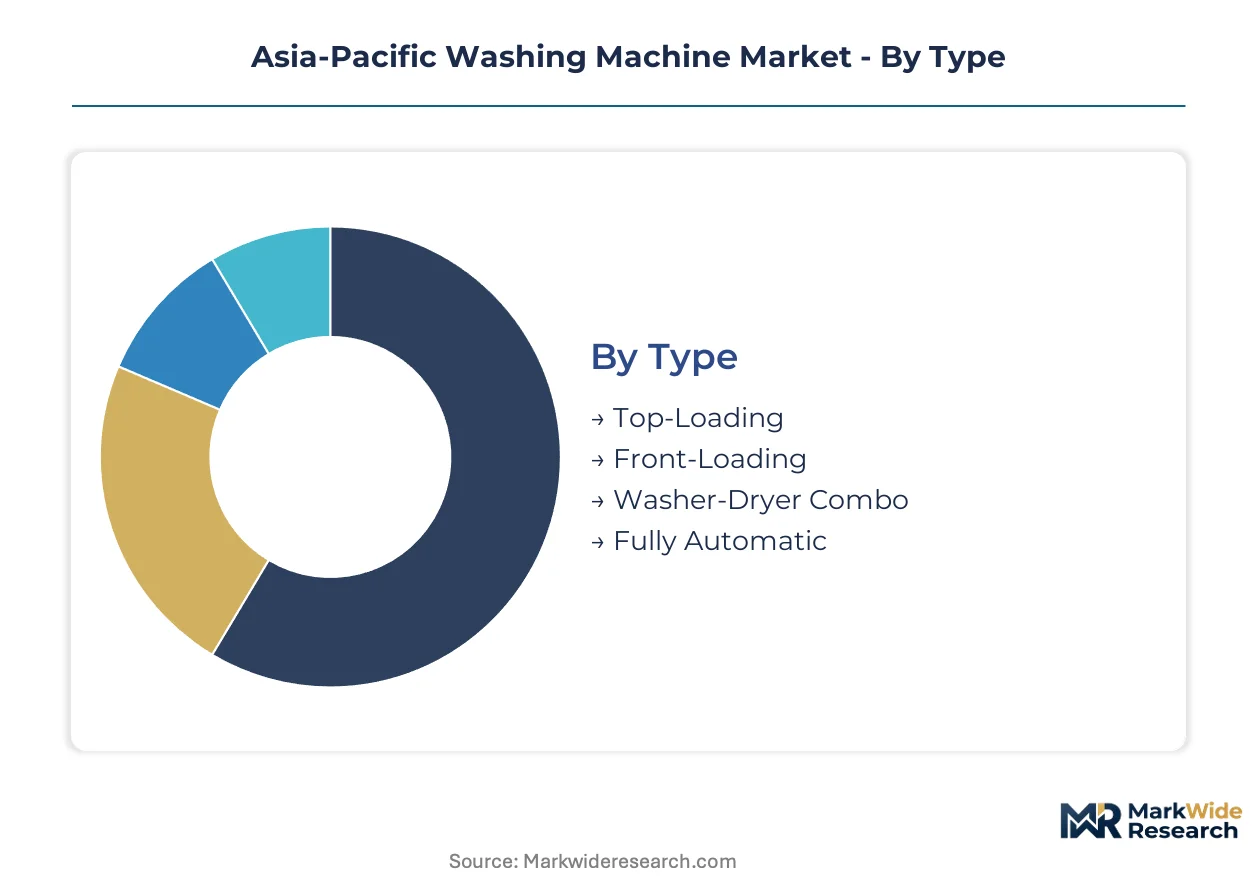
Segmentation in Asia-Pacific washing machines reveals divergent profit pools. Volume concentrates in mass-market configurations serving India's tier-2 cities, while margin accumulates in connected appliances targeting Australian and South Korean urban households. Understanding these splits guides portfolio allocation and channel investment.
Type:
Front-loading variants command premium positioning through water-efficiency advantages, while top-loading units anchor volume in price-sensitive Southeast Asian markets.
- Front-Loading:Horizontal-axis tumbling reduces water consumption by 40-50% versus conventional designs. Demand clusters in Japanese condominiums and Australian metropolitan apartments where space constraints and METI Top Runner compliance drive specification. BIS water-efficiency mandates in India are accelerating adoption among urban middle-class households.
- Top-Loading:Vertical drum orientation enables shorter wash cycles and lower entry price points. Penetration remains deepest in rural Indonesia and Philippines where hand-wash habits persist, though inverter-motor retrofits are narrowing the efficiency gap with front-loading alternatives.
- Washer-Dryer Combo:Integrated thermal cycling addresses space constraints in Seoul and Tokyo high-density housing. Heat-pump configurations are displacing vented systems in Australian rental-property bundles.
- Fully Automatic:Programmable control modules eliminate manual intervention between wash and spin cycles. Adoption is climbing fastest in Vietnam's manufacturing corridors and India's tier-2 cities as first-generation semi-automatic units reach replacement age.
Today's leader: Front-Loading. Tomorrow's challenger: Fully Automatic.
Technology:
Smart connectivity and inverter drives are bifurcating the technology stack, with efficiency mandates pushing conventional designs toward obsolescence.
- Smart Technology:Wi-Fi-enabled units integrate with home energy management systems and remote diagnostic platforms. Australian and South Korean metros show strongest uptake as property developers bundle connected appliances into managed tenancy packages.
- Inverter:Variable-frequency motor control cuts electricity consumption 20-30% versus fixed-speed alternatives. Southeast Asian households facing tariff escalations in Thailand and Vietnam are prioritizing inverter specification in purchase decisions.
- Energy Efficient:Broad category encompassing improved drum insulation, optimized water inlet systems, and heat-pump drying. Australia's Water Efficiency Labelling and Standards star ratings directly shape consumer choice through visible point-of-sale labeling.
- Conventional:Fixed-speed motors and mechanical timers retain presence in lowest-price tiers. Market share is compressing as BIS compulsory registration and China's dual carbon goals tighten minimum efficiency floors.
Smart Technology captures margin expansion. Inverter technology scales volume.
End User:
Household demand fragments across income tiers and urbanization gradients, while commercial segments concentrate purchase authority in asset managers and procurement departments.
- Households:Multi-person units in India and Indonesia drive 8-10 kg capacity dominance. Replacement cycles in Vietnam's manufacturing corridors and India's tier-2 cities are generating volume growth as first-generation appliances mature.
- Commercial Laundries:Industrial-capacity units with 10 kg-plus drums and extended durability cycles serve hospital chains and linen services in Thailand and Malaysia. Procurement emphasizes total cost of ownership over upfront capital expenditure.
- Hotels:Mid-scale and budget hotel chains in Southeast Asia seek reliable above-10 kg units with rapid cycle times. Fleet-scale service networks influence supplier selection more than retail channel presence.
- Educational Institutions:University dormitories and boarding schools in South Korea and Australia represent a concentrated but price-sensitive segment. Bulk procurement through facility management offices favors standardized specifications over feature differentiation.
Commercial Laundries concentrate margin. Households distribute volume.
Capacity:
Drum size correlates with household composition and water availability, creating distinct regional preference clusters.
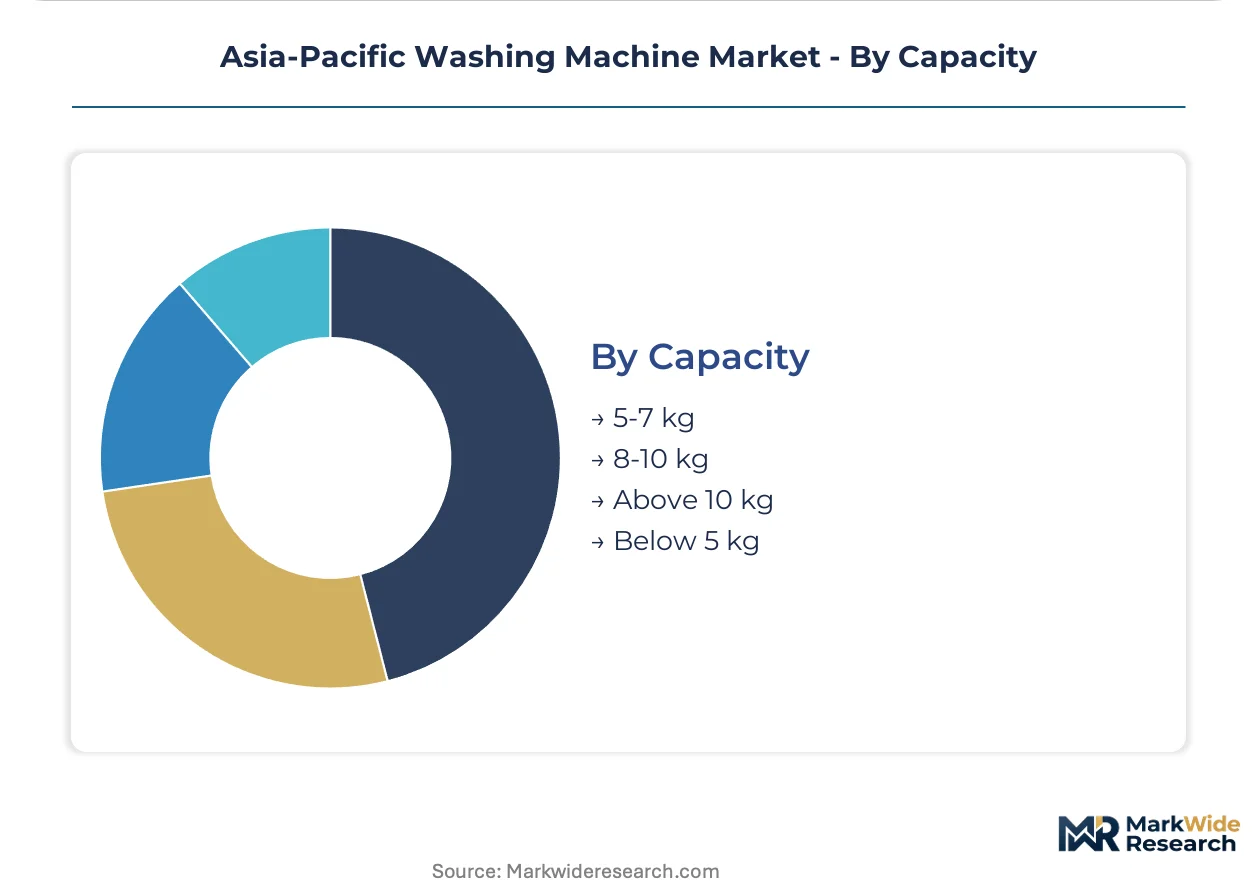
- 8-10 kg:Optimal for four-to-six-person households prevalent in India and Indonesia. This band leads unit volume across Asia-Pacific as nuclear family structures dominate urban migration patterns.
- 5-7 kg:Targets couples and single-person households in Japanese and South Korean cities. Space constraints in high-rise apartments limit physical unit dimensions regardless of household size.
- Above 10 kg:Industrial-grade specifications for commercial laundries, hotels, and hospital chains. Thai and Malaysian hospitality sectors are expanding installed base to support tourism recovery.
- Below 5 kg:Compact units for studio apartments and secondary vacation residences. Niche presence in Australian coastal markets and Japanese ski-resort towns.
8-10 kg holds volume leadership. Above 10 kg climbs fastest on commercial investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in Chinese manufacturing hubs and Indian industrial corridors anchor regional production capacity, while regulatory divergence across national standards bodies fragments compliance frameworks.
China
Domestic appliance demand concentrates in Yangtze River Delta and Pearl River Delta manufacturing belts. MIIT efficiency mandates and dual carbon goals tighten motor-performance standards for export-bound and domestic units alike. Guangdong and Jiangsu provinces host vertically integrated component ecosystems serving both mass-market and smart-appliance tiers.
India
Replacement cycles in tier-2 cities and Gujarat-Tamil Nadu manufacturing clusters drive volume expansion. BIS compulsory registration and water-efficiency labeling tighten market access for uncertified imports. The PLI scheme for white goods draws component suppliers toward Pune and Chennai assembly hubs.
Japan
Condominium dwellers in Tokyo and Osaka metros prioritize space-efficient front-loading configurations. METI Top Runner standards mandate progressive efficiency improvements across successive product generations. Kanto and Kansai industrial corridors retain precision-motor manufacturing expertise for premium-tier exports.
Vietnam
Manufacturing corridor workers in Hanoi and Ho Chi Minh City accelerate automatic-machine adoption as first-generation appliances mature. Low penetration in Central Highlands and Mekong Delta regions presents expansion headroom. Binh Duong and Dong Nai provinces concentrate assembly operations for regional supply.
Australia
Metropolitan renters in Sydney and Melbourne drive subscription-based appliance access models. Water Efficiency Labelling and Standards star ratings directly shape consumer purchase decisions through visible point-of-sale labeling. Property developers concentrate procurement authority in managed tenancy packages across southeastern capitals.
Asia-Pacific Washing Machine Market Competitive Environment
Top-tier vendors anchor premium smart-appliance positioning, while mass-market specialists compete on manufacturing scale and distribution density. The vendor base stratifies across three tiers: diversified conglomerates with home-appliance divisions, pure-play white-goods manufacturers, and component-focused fabricators supplying branded assemblers. Strategic archetypes include ecosystem integrators pursuing connected-home convergence, efficiency specialists leveraging inverter-motor expertise, and vertical manufacturers optimizing cost-to-performance ratios. Capacity expansion and portfolio diversification toward heat-pump and AI-enabled configurations represent dominant competitive moves.
Among Asia-Pacific-based conglomerates, Midea Group, Haier Smart Home, and Samsung Electronics occupy positions spanning mass-market scale and premium-tier innovation. Midea exemplifies vertical manufacturing optimization through captive component supply. Haier represents ecosystem-integration archetypes with connected-appliance portfolios. Samsung anchors inverter-technology differentiation targeting efficiency-conscious Southeast Asian households. These three entities collectively illustrate the region's competitive tension between manufacturing scale and smart-technology margin capture.
| Leading Market Players |
|---|
| Midea Group |
| Panasonic Corporation |
| Haier Smart Home |
| IFB |
| Hitachi |
| LG Electronics |
| Whirlpool Corporation |
| Godrej |
| Samsung Electronics |
| Others |
Value Chain & Pricing Dynamics
Heat-pump drying technology migration from air-conditioning divisions into mid-tier front-loading units is compressing manufacturing cost curves while concentrating thermal-management expertise in Guangdong and Jiangsu manufacturing belts. This production-method transition simultaneously elevates efficiency benchmarks and redraws component sourcing footprints across the Asia-Pacific washing machine market.
Pricing Analysis
The bundled-vs-unbundled service split separates subscription-based fleet procurement by Australian property developers from transactional retail purchases in Indian tier-2 cities. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade under BIS water-efficiency labeling and METI Top Runner compliance tiers. Pricing pressure stems from stainless steel input volatility squeezing mid-range unit margins. Rural Indonesian households exhibit highest price sensitivity, while Seoul apartment asset managers prioritize total cost of ownership over upfront capital.
Supply Chain Analysis
Logistics and freight cost differentials between containerized shipping from Yangtze River Delta ports and overland distribution into Central Highlands Vietnamese provinces shape regional pricing spreads. Manufacturing concentrates in China, India, and Vietnam, with component ecosystems drawing from captive motor production and imported stainless steel. Drum and chassis fabrication rests on nickel and chromium spot market exposure. Single-source vulnerability concentrates in precision inverter-motor controllers. Distribution runs through appliance retail chains in urban India and developer-direct fleet contracts in Australian metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific washing machine market offers margin-expansion pathways as inverter-motor cost curves decline and connected-appliance premiums harden in Australian and South Korean metros.
For Market Incumbents: To counter embedded software talent scarcity across the region, anchor defensive positioning through backward integration into firmware development capabilities and captive inverter-motor manufacturing in Gujarat-Tamil Nadu clusters. Certification investment in simultaneous BIS, JIS, and GB compliance shortens product launch cycles against pan-Asia-Pacific portfolios. For New Entrants and Emerging Players: Enter via underpenetrated Vietnamese provinces in the Central Highlands and Mekong Delta, where automatic-washer household penetration lags Hanoi and Ho Chi Minh City benchmarks. Target commercial laundry services in Thai hospital chains seeking industrial-capacity units with fleet-scale service network requirements as the most penetrable segment. For Investors and Strategic Acquirers: Valuations sit cheapest among component-focused fabricators supplying branded assemblers, particularly those with captive drum manufacturing and heat-pump thermal management expertise. Long-term viability hinges on ecosystem-integration capabilities converging washing machines with air conditioners and water heaters. Watch PLI scheme disbursement velocity in India as the signal indicating regional supply configuration shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Technology Transfer | Air-conditioning division expertise cuts drying energy consumption 40-50% versus vented systems in Australian units. |
| Smart-Home Ecosystem Integration | Wi-Fi-enabled convergence with water heaters creates stickier customer relationships in Seoul and Sydney metros. |
| PLI Scheme Capacity Expansion | Gujarat-Tamil Nadu manufacturing clusters shorten lead times for domestic assembly serving Indian replacement cycles. |
| Commercial Laundry Fleet Contracts | Asset-manager procurement authority in Thai hospitality sectors privileges suppliers with service network scale. |
| Multi-Standard Certification Investment | Simultaneous BIS, JIS, and GB compliance reduces product launch friction for pan-Asia-Pacific portfolios. |
Study Parameters
Coverage spans China, India, Japan, Vietnam, and Australia, with primary inputs from each market gathered through interviews with appliance manufacturing executives, white-goods procurement managers at retail chains, property developer asset managers, commercial laundry fleet operators, and regulatory affairs specialists at standards bodies. Secondary validation draws from BIS registration databases, METI efficiency filings, Australian Water Efficiency Labelling and Standards registry, customs trade records, and SEC 10-K disclosures from listed appliance manufacturers. Bottom-up unit shipment modeling triangulates against top-down market value estimates.
Granularity-level modeling captures type segmentation across front-loading, top-loading, washer-dryer combo, and fully automatic configurations; technology tiers spanning smart connectivity, inverter drives, energy-efficient designs, and conventional units; end-user splits between households, commercial laundries, hotels, and educational institutions; and capacity bands from below 5 kg through above 10 kg. CAGRs were derived from regression analysis against urbanization rates, electricity tariff trajectories, and replacement cycle maturation across the projection horizon. Forecast inputs incorporate PLI scheme disbursement schedules and METI Top Runner compliance phase-in timelines.
Inputs from BIS registration databases and METI efficiency filings were available through the study window; gaps in real-time stainless steel spot price series introduce uncertainty bands around margin compression assumptions. Forecasts reflect modeling assumptions regarding regulatory enforcement consistency and tariff stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
AI Washing Machine Market
Appliances
Built-In Large Cooking Appliance Market
Appliances
Germany Consumer Appliances Market
Appliances
Minibar Refrigerators Market
Appliances
Laundry Dryer Market
Appliances
Smart Refrigerator Market
Appliances
Mini Washing Machine Market
Appliances
US Electric Rice Cooker Market
Appliances
Cooker Hoods Market
Appliances
Asia-Pacific Microwave Oven Market
Appliances
Smart Massage Appliances Market
Appliances
Fully Integrated Dishwasher Market
Appliances
French Door Refrigerator Market
Appliances
United Kingdom Tumble Dryers Market
Appliances
Household Vacuum Cleaners Market
Appliances
Water Heater Market