
 Smart Dishwasher Market | 2026-2036
Smart Dishwasher Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Dishwasher Market Intelligence
China's expanding manufacturing base for smart home appliances is fragmenting the established competitive landscape. Robert Bosch GmbH leverages its engineering prowess to dominate the premium segment across several European markets. Meanwhile, Samsung Electronics Co Ltd competes aggressively on software integration and broad ecosystem connectivity. Whirlpool Corporation sustains its market position through extensive distribution networks and brand loyalty in North America.
A smart dishwasher is an appliance connecting to a home network via Wi-Fi or Bluetooth for remote control and monitoring. These units feature soil sensors that automatically adjust cycle times and water usage to optimize cleaning performance. Built-in models command the largest share within the residential end-user segment, aligning with modern kitchen renovation trends. Voice control technology represents the fastest-growing feature, driven by integration with smart home assistants.
Product design is heavily influenced by energy efficiency standards, including the EPA's Energy Star program in the United States and the EU Green Deal initiatives. Compliance with CE marking in Europe and mandatory GB standards in China is essential for market access, setting benchmarks for safety and performance. Manufacturers must now decide whether to prioritize deep integration with a single smart home platform or pursue broader compatibility across multiple ecosystems.
Market Dynamics
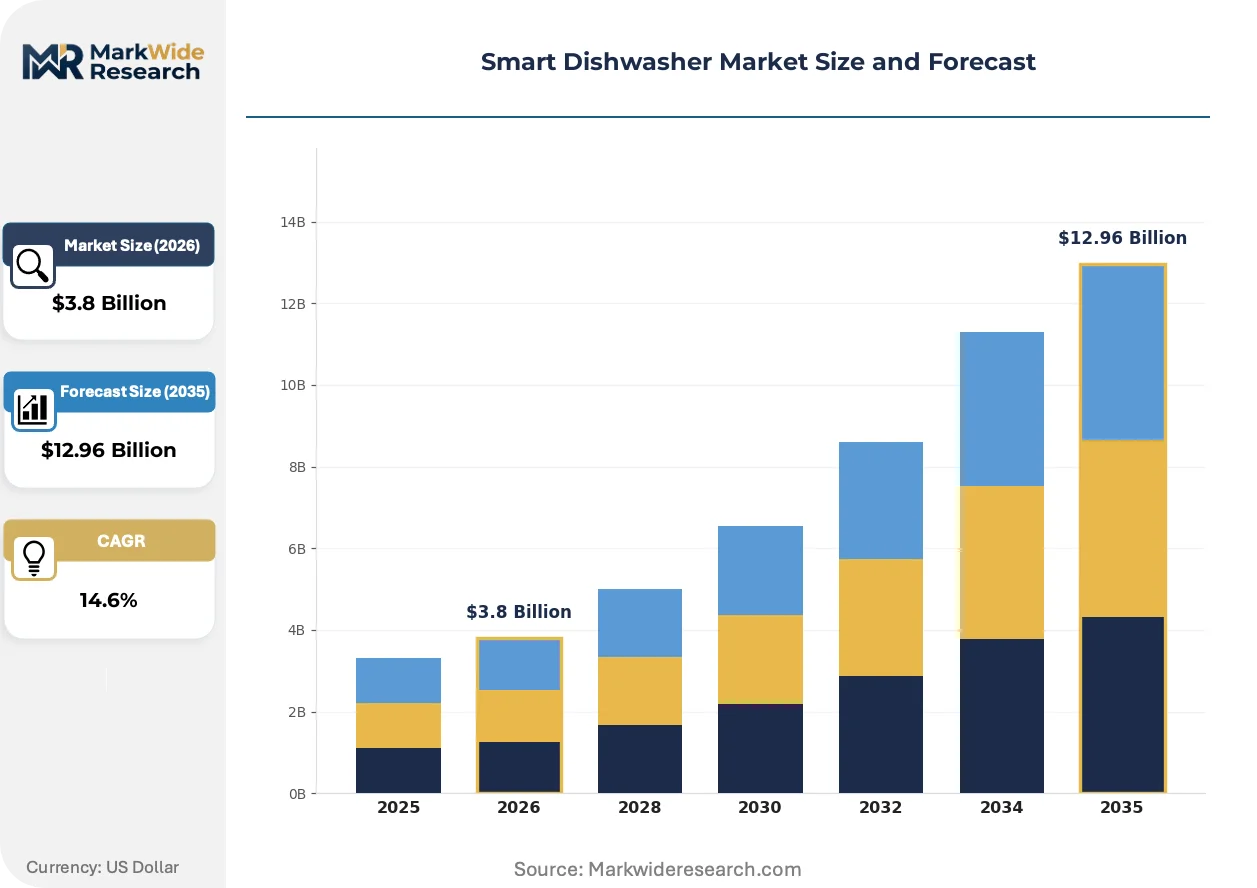
The convergence of stringent energy efficiency mandates, such as the EU Green Deal, with consumer demand for integrated smart home ecosystems is the central force defining the market's trajectory and competitive priorities for manufacturers.
Growth Catalysts
- Home Automation Adoption:The expansion of smart home ecosystems in the residential sector, particularly in North America, creates persistent demand for interconnected appliances that offer convenience and remote control features through platforms like Amazon Alexa or Google Assistant.
- Energy Efficiency Mandates:Regulatory frameworks, including the EPA's Energy Star program and EU ecodesign requirements, are accelerating the replacement of older, less efficient dishwashers, directly benefiting models with advanced, energy-saving smart features like soil sensors.
- Voice Control Integration:The rapid mainstreaming of voice assistant technology represents the fastest-growing feature set, appealing to a consumer base seeking hands-free operation and seamless integration with their existing connected home environment.
Market Restraints
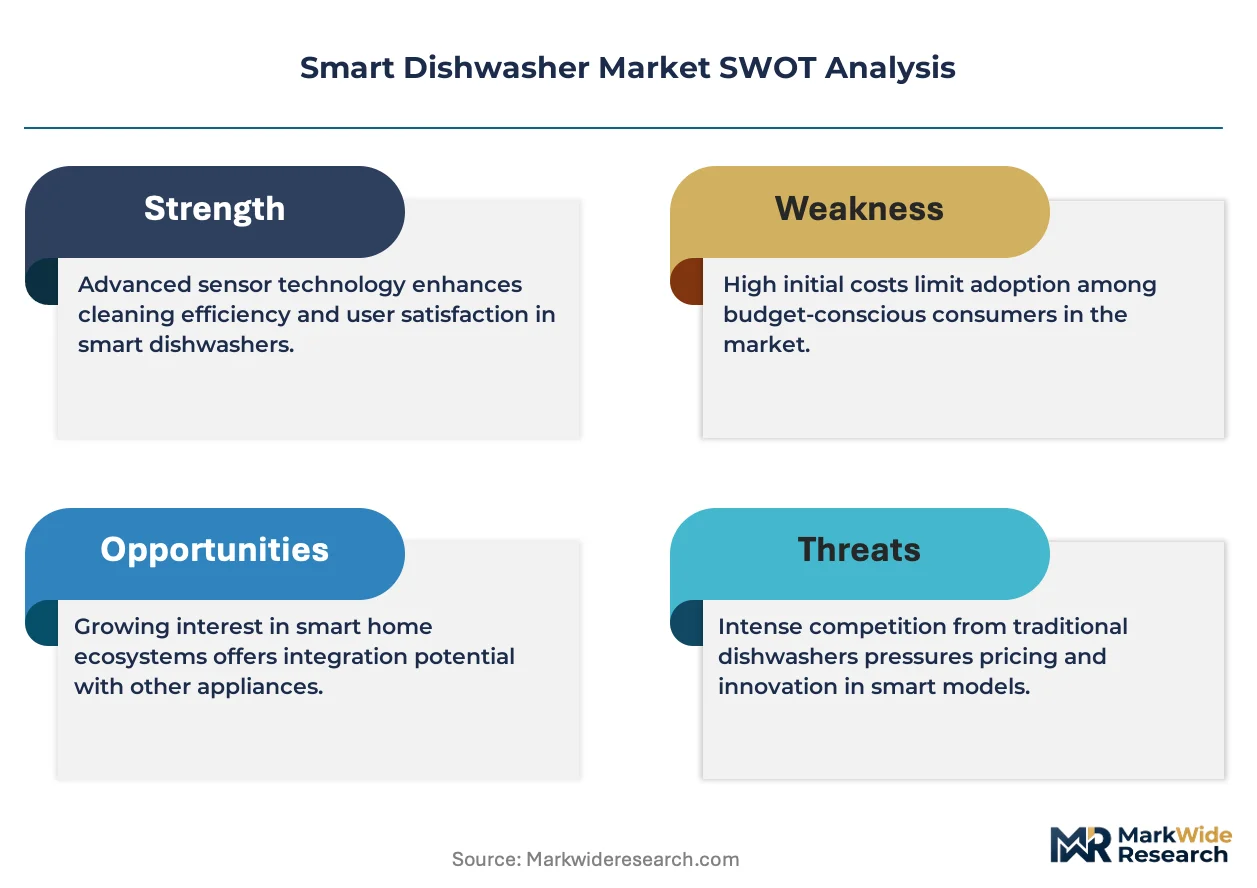
- Premium Price Point:The significant price gap between smart dishwashers and their conventional counterparts remains a primary barrier to adoption, particularly for budget-conscious households or in the multi-family housing and rental property segments.
- Interoperability Challenges:A lack of universal standards across smart home platforms creates fragmentation, forcing consumers to choose appliances within a single ecosystem and limiting connectivity options, which can deter purchase decisions.
- Semiconductor Dependency:Production of smart dishwashers relies on a steady supply of microcontrollers and Wi-Fi modules, making the appliance industry vulnerable to supply chain disruptions and price volatility in the global semiconductor market.
Strategic Opportunities
- Predictive Maintenance Services:Manufacturers can develop subscription-based services that use sensor data to predict component failure, schedule preventative maintenance, and automate service calls, creating new recurring revenue streams beyond the initial hardware sale.
- Water Quality Customization:Integrating water hardness sensors or linking to local utility data allows for the development of hyper-optimized wash cycles that adjust detergent and rinse aid dosage automatically, offering superior cleaning performance as a key differentiator.
- Expansion in Emerging Economies:Targeting the growing middle class in urban centers across Southeast Asia and Latin America presents a significant opportunity, as smart home technology adoption often coincides with first-time purchases of premium home appliances.
Industry Challenges
- Software Lifecycle Management:Ensuring long-term support, including security patches and firmware updates for connected appliances, poses a significant operational challenge that requires a fundamental shift from a hardware-centric to a software-and-service business model.
- Data Privacy Compliance:Collecting user data on appliance usage patterns requires strict adherence to privacy regulations like GDPR in Europe and similar frameworks elsewhere, adding legal and technical complexity to product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Dishwasher Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-in, Portable, Drawer, Countertop Technology: Wi-Fi Enabled, Bluetooth Connectivity, Voice Control, Touch Controls End User: Residential, Commercial, Industrial, Rental Properties Distribution Channel: Online Retail, Appliance Stores, Wholesale, Direct Sales |
| Companies Covered | Whirlpool Corporation, Electrolux AB, Samsung Electronics Co Ltd, Robert Bosch GmbH, Miele & Cie. KG, BSH Hausgeräte GmbH, LG Electronics Inc, Panasonic Corporation, GE Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Dishwasher Market Strategic Shifts & Innovations
Software-defined features and ecosystem connectivity are becoming primary differentiators over traditional hardware performance. This evolution redefines product value, shifting focus from mechanical reliability to intelligent automation and user experience, which is reshaping competitive positioning.
AI-powered soil and turbidity sensors provide real-time data on the cleanliness of the wash load. The premium residential segment, especially during kitchen renovations, is rapidly adopting this technology. This level of automated optimization is rendering obsolete the manual selection of fixed, pre-programmed wash cycles by ensuring ideal water and energy usage for every specific load.
The European Union's "Right to Repair" legislation is forcing a fundamental shift in appliance design. This directive mandates that manufacturers ensure the availability of spare parts for an extended period, promoting product longevity and serviceability. The built-in appliance category is most affected, compelling a move toward more modular internal designs that allow for easier component replacement by certified technicians.
Consumers are increasingly selecting home appliances based on their seamless integration with an existing smart home platform. This behavioral shift disrupts traditional brand loyalty, which was often based on hardware specifications, and instead favors manufacturers with robust and user-friendly software. This trend is most prominent in technologically advanced markets like South Korea and Germany, where connected home ecosystems are mature.
Smart Dishwasher Market Segmentation
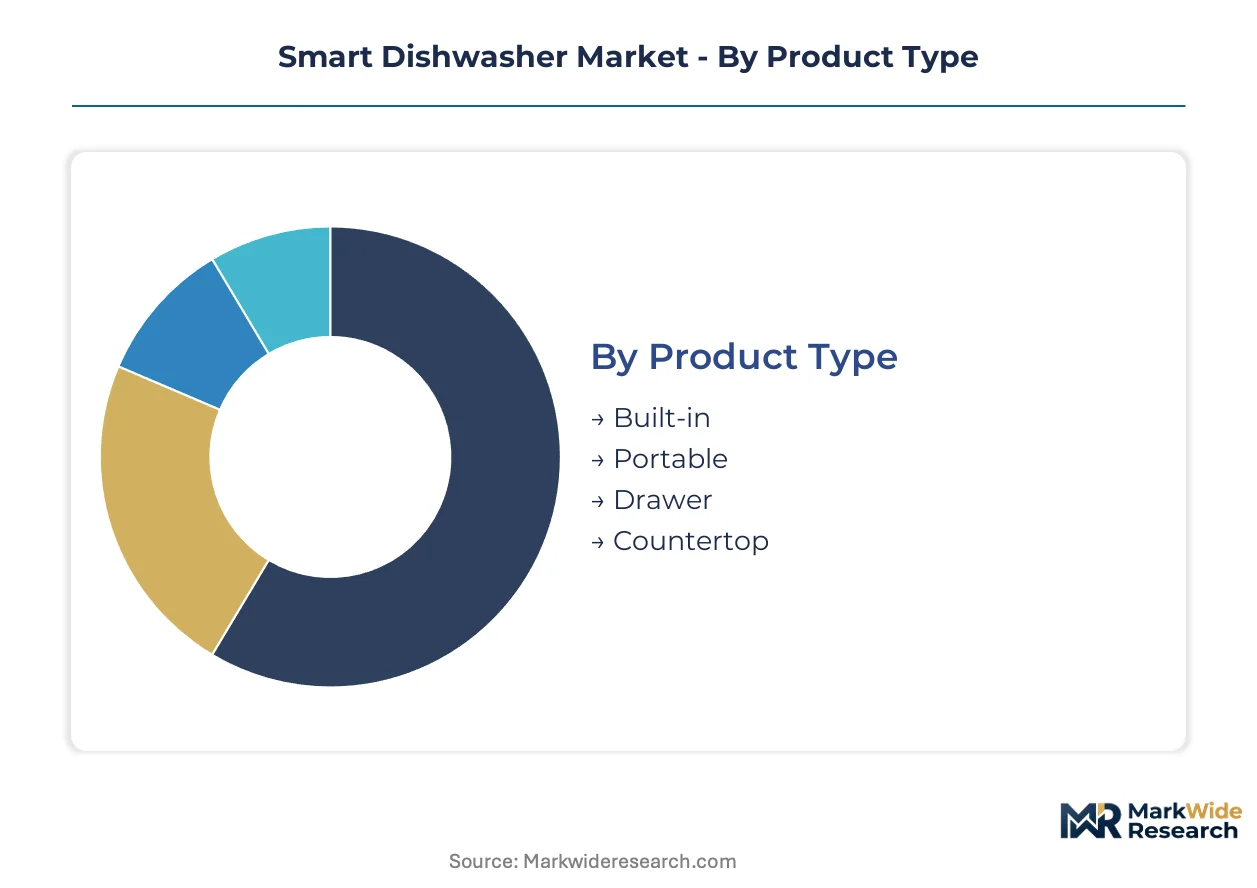
The Smart Dishwasher Market's segmentation provides a detailed lens into consumer preferences, technological adoption rates, and strategic distribution pathways. Understanding these distinct segments is crucial for manufacturers to tailor product development and market entry strategies effectively.
Product Type:
The product type segmentation for smart dishwashers reflects a diverse maturity spectrum, from established integrated designs to niche specialized formats.
- Built-in:These units integrate seamlessly into kitchen cabinetry, offering a streamlined aesthetic and maximizing counter space. Demand concentrates in Germany and South Korea, driven by modern kitchen renovation trends and consumer preference for minimalist design.
- Drawer:Drawer dishwashers feature one or two independent wash compartments, allowing for smaller loads and flexible operation. This design gains traction in urban centers like New York City, appealing to households with limited space or specific load requirements for energy efficiency.
- Portable:These freestanding units offer mobility and do not require permanent installation, serving rental properties and smaller apartments.
- Countertop:Compact countertop models provide convenient dishwashing solutions for very small living spaces or secondary washing needs.
Built-in models retain volume leadership; Drawer dishwashers hold the steepest expansion curve.
Technology:
Technology segmentation highlights the varying degrees of smart home integration and user interaction across different smart dishwasher offerings.
- Wi-Fi Enabled:Wi-Fi enabled dishwashers connect to the home network for remote monitoring, cycle management, and software updates via smartphone applications. This technology is essential in markets like the United States, where home automation platforms like Amazon Alexa are widely adopted.
- Voice Control:Voice control capabilities allow users to operate the appliance through spoken commands, integrating with smart home assistants like Google Assistant. Adoption is accelerating in technologically advanced markets such as South Korea, driven by consumer preference for hands-free operation and seamless ecosystem integration.
- Bluetooth Connectivity:Bluetooth enables direct, short-range communication with a smartphone for localized control without requiring a Wi-Fi network.
- Touch Controls:Touch-sensitive panels offer a sleek, modern interface for direct appliance operation, replacing traditional physical buttons and dials.
Wi-Fi connectivity forms the foundational layer for smart features; Voice Control technology provides a significant differentiator in user experience.
End User:
End-user segmentation delineates the distinct scales of operation and usage patterns for smart dishwashers across various customer types.
- Residential:This segment encompasses individual households using smart dishwashers for daily cleaning, emphasizing convenience, energy efficiency, and home integration. Demand is concentrated in developed economies like Germany, driven by high disposable incomes and a strong focus on smart home ecosystems.
- Rental Properties:Rental property owners and managers deploy smart dishwashers to offer modern amenities and reduce utility costs through optimized water and energy usage. This segment is expanding in urban rental markets such as London, where property managers seek appliance longevity and remote diagnostic capabilities.
- Commercial:Commercial applications include small businesses and offices requiring robust, efficient dishwashing solutions for staff and client facilities.
- Industrial:Industrial settings typically involve large-scale, heavy-duty dishwashing needs, which are less commonly met by current smart dishwasher offerings.
Residential users represent the core market for smart dishwashers; Commercial and Industrial segments remain niche applications.
Distribution Channel:
Distribution channel segmentation illustrates the diverse pathways through which smart dishwashers reach end consumers and institutional buyers.
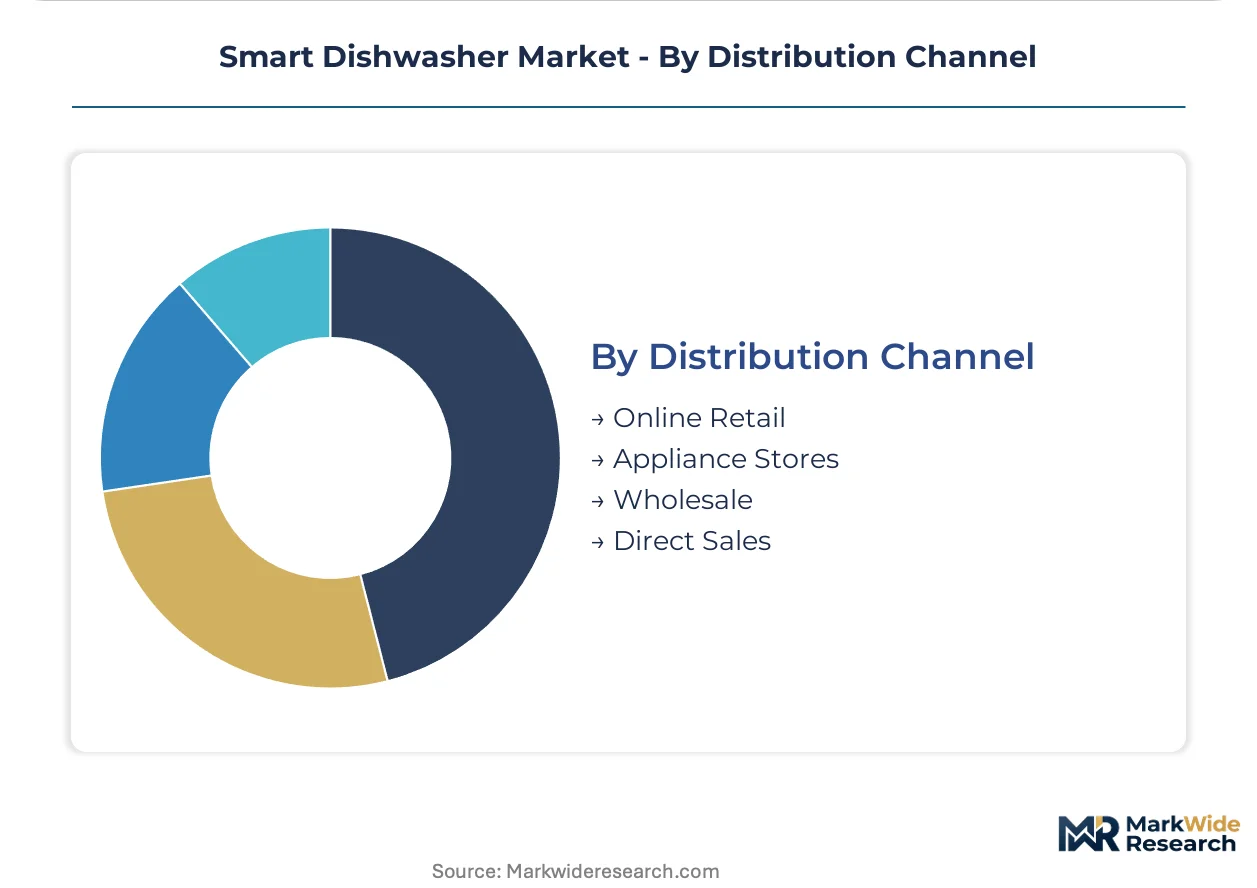
- Online Retail:E-commerce platforms provide a broad selection and competitive pricing, facilitating direct consumer purchases with home delivery options. This channel dominates in markets like the United States, driven by consumer preference for convenience and access to product reviews.
- Appliance Stores:Physical appliance stores offer hands-on product demonstrations, expert advice, and installation services, catering to consumers seeking a full-service experience. These stores maintain strong sales in European markets such as France, where consumers often prefer in-person consultation for major appliance purchases.
- Wholesale:Wholesale channels supply smart dishwashers in bulk to contractors, builders, and large property developers for new constructions or renovations.
- Direct Sales:Manufacturers engage in direct sales through their own websites or showrooms, offering exclusive models and direct customer support.
Online Retail streamlines consumer access to smart dishwashers; Appliance Stores provide essential consultative sales and service support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart dishwasher consumption patterns vary significantly across regions, with advanced economies demonstrating higher adoption rates due to integrated smart home ecosystems. Germany and South Korea lead in demand for built-in models, driven by modern kitchen aesthetics. Conversely, the United States prioritizes convenience and remote control features, influencing product development.
Germany
Demand for built-in smart dishwashers stems from a strong preference for minimalist design and high disposable incomes among consumers. The EU Green Deal and ecodesign requirements accelerate the replacement of older, less efficient appliances. Munich and Berlin represent key urban centers where sophisticated consumers actively seek seamless kitchen integration and energy-saving technologies.
South Korea
Smart home ecosystem maturity and a high propensity for voice control technology drive appliance adoption within South Korea. The country's national standards for smart home device interoperability promote broad connectivity across various platforms. Seoul's tech-savvy population consistently embraces advanced features, influencing global product development and user experience trends.
United States
Home automation adoption and the widespread use of platforms like Amazon Alexa fuel demand for interconnected appliances in the United States. The EPA's Energy Star program encourages consumers to upgrade to more efficient smart dishwasher models. Silicon Valley and other tech hubs show concentrated interest in cutting-edge smart appliance features and remote management capabilities.
China
An expanding middle class and rapid urbanization are generating new demand for smart home appliances across China. Mandatory GB standards ensure market access and set benchmarks for product safety and performance. Manufacturing bases in Shenzhen and Guangzhou are increasingly specializing in smart appliance production, supporting both domestic and export markets.
United Kingdom
The expansion of urban rental markets and a focus on utility cost reduction drive demand for efficient smart dishwashers in the United Kingdom. Local building codes and energy efficiency targets influence appliance choices in new residential developments. London's property managers increasingly seek models with remote diagnostic capabilities for managing multiple units efficiently.
Smart Dishwasher Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a tiered market structure. The smart dishwasher market exhibits consolidation among established appliance manufacturers, complemented by niche players focusing on specific technology integrations. Strategic archetypes include global conglomerates leveraging extensive brand recognition and technology specialists innovating in advanced smart features. Companies primarily employ strategic partnerships and portfolio diversification to maintain competitive relevance and expand market reach.
Among the prominent manufacturers, Robert Bosch GmbH, a German-based engineering and technology firm, exemplifies a premium segment focus, leveraging its engineering prowess and reputation for quality. Samsung Electronics Co Ltd, a South Korean conglomerate, represents a strong emphasis on software integration and broad ecosystem connectivity, appealing to tech-savvy consumers. Meanwhile, the US-based Whirlpool Corporation sustains its market position through extensive distribution networks and established brand loyalty in key North American markets. These entities collectively anchor the market's competitive dynamics across various geographic and technological fronts, influencing product development and consumer expectations.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Electrolux AB |
| Samsung Electronics Co Ltd |
| Robert Bosch GmbH |
| Miele & Cie. KG |
| BSH Hausgeräte GmbH |
| LG Electronics Inc |
| Panasonic Corporation |
| GE Appliances |
| Others |
Cost & Logistics Intelligence
Shenzhen and Guangzhou's expanding manufacturing capacity for smart home appliances directly influences the transactional pricing structure in the global smart dishwasher market. This concentration of production capability creates a competitive environment for hardware components.
Pricing Analysis
Geographic price-spreads for smart dishwashers often reflect regional disposable incomes and regulatory compliance costs. The dominant pricing structure is per-unit transactional, with premium-mid-economy pricing differentiation driven by software features, brand reputation, and energy efficiency certifications like Energy Star. Pricing pressure stems from China's expanding manufacturing base, which introduces lower-cost alternatives. Residential consumers in budget-conscious segments exhibit the highest price sensitivity, while premium segment buyers prioritize advanced features and integration.
Supply Chain Analysis
Semiconductor dependency represents a primary supply chain risk for smart dishwashers, making manufacturers vulnerable to global chip shortages. Production concentrates heavily in China, South Korea, and Germany, which source microcontrollers and Wi-Fi modules globally. Key raw material dependencies include specialized plastics for interiors and stainless steel for outer casings. Distribution runs through a hybrid model combining online retail for direct consumer access and physical appliance stores for consultative sales and after-sales support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart dishwasher market is at a platform-economics inflection point, driven by the increasing importance of seamless integration within smart home ecosystems like Amazon Alexa. This shift redefines product value beyond hardware specifications.
For Market Incumbents: Insulate core market share by investing heavily in software development and data privacy compliance, countering fragmentation from new entrants focused on niche integrations. Prioritize vertical integration into critical component manufacturing, such as proprietary soil sensors, to mitigate supply chain vulnerabilities. This strategy defends against margin pressure from lower-cost manufacturers and strengthens brand loyalty in premium segments. Robert Bosch GmbH can leverage its engineering prowess to maintain its premium segment dominance.
For New Entrants and Emerging Players: Pursue white-space opportunities in the rental properties segment by offering models with advanced remote diagnostics and predictive maintenance services. Target urban centers in Southeast Asia with compact, energy-efficient smart dishwashers, leveraging the region's growing middle class. A go-to-market angle focusing on subscription-based software features and extended warranties can differentiate offerings. This approach targets underpenetrated segments with specific pain points.
For Investors and Strategic Acquirers: Long-term, this sits as a technology integration play because consumer preference is shifting towards ecosystem compatibility over hardware brand loyalty. Acquisition targets should be software specialists with robust AI-powered sensor technology or strong smart home platform partnerships. A key signal to watch is the widespread adoption of universal interoperability standards across smart home devices. This indicates a maturing market ready for broader penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Software Ecosystem Integration | Enhances user experience and strengthens brand loyalty through seamless smart home connectivity. |
| Invest in Predictive Maintenance AI | Creates new recurring revenue streams and extends appliance lifespan for consumers. |
| Expand Manufacturing in Southeast Asia | Accesses emerging market demand and diversifies global production footprint. |
| Develop Modular Appliance Designs | Complies with "Right to Repair" legislation and improves long-term serviceability. |
| Secure Semiconductor Supply Contracts | Mitigates production risks and ensures consistent availability of smart components. |
Research Approach
Operator-level perspectives from product managers, R&D engineers, supply chain directors, and retail channel heads anchored the qualitative base of this study. Primary interviews were triangulated with comprehensive secondary research from company annual reports, patent databases, and regulatory filings from EPA and CE marking authorities. This approach provided a robust understanding of market dynamics and competitive positioning. Bottom-up and top-down data validation ensured accuracy.
Scenario-bracketing informed the quantitative forecast model, projecting market trajectory over the analysis window under various adoption rates. Segmentation dimensions modeled included product type, technology, end-user, and regional demand patterns for smart dishwashers. Compound Annual Growth Rates were derived from historical trends and projected technological advancements. Key forecast inputs included smart home adoption rates and energy efficiency regulatory timelines.
Macroeconomic conditions sit as an overlay; deviation in consumer disposable income or global semiconductor supply would shift the trajectory. Forecasts reflect assumptions documented in the report regarding technological maturity and regulatory stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
US Electric Rice Cooker Market
Appliances
Conveyor Dishwasher Market
Appliances
Household Beauty Appliances Market
Appliances
Small Appliances Market
Appliances
Personal Care Appliances Market
Appliances
Saudi Arabia Water Heater Market
Appliances
Sanitary Towel Machine Market
Appliances
Minibar Refrigerators Market
Appliances
Oman Dishwashers Market
Appliances
US Portable Washing Machines Market
Appliances
United States Multi-Functional Oven Market
Appliances
South Africa Laundry Appliances Market
Appliances
Fully Integrated Dishwasher Market
Appliances
North America Microwave Oven Market
Appliances
India Washing Machine Market
Appliances
Automatic Dishwasher Market