
 France Household Electric Grills Market | 2026-2036
France Household Electric Grills Market Size, Share, and Industry Trends Forecast 2026-2036
France Household Electric Grills Market Foresight
Subscription-based maintenance and software-enabled temperature control is pivoting how manufacturers monetize household electric grills beyond the initial hardware sale. Groupe SEB leverages its deep brand portfolio across premium and mid-market tiers to sustain recurring revenue through replacement parts and digital recipe platforms. Philips anchors its competitive stance with precision infrared heat source technology that differentiates its product line from conventional conduction models. Roller Grill International specializes in commercial-grade engineering adapted for residential use, occupying a niche where professional performance meets domestic kitchen constraints.
France household electric grills are electrically powered cooking appliances employing resistive heating elements, infrared quartz tubes, or ceramic plates to generate controlled surface temperatures between 150°C and 300°C for food preparation without open flame or fossil fuel combustion. Their primary purpose is to enable safe, smoke-reduced grilling in indoor environments and restricted outdoor spaces where gas or charcoal systems face regulatory or spatial limitations. Contact grills dominate volume sales due to compact footprints suited to French urban apartments, while smokeless grills represent the fastest-growing product type as consumers seek year-round indoor barbecue flavor without ventilation infrastructure. Infrared heat source technology leads in premium positioning because it delivers rapid preheat cycles and searing performance that command higher margin pools.
ANSM oversees electrical appliance safety certifications that determine market access for imported grills, while France's transposition of EU Ecodesign and REACH regulations mandates material compliance and energy consumption disclosures that shape product design investments. The EU F-Gas Regulation and national decarbonization targets under the EU Green Deal are accelerating R&D shifts toward induction and ceramic heating technologies that eliminate fluorinated gas dependencies and align with domestic net-zero building standards. Stakeholders must monitor how upcoming revisions to France's energy labeling framework and potential extensions of the AGEC anti-waste law to small domestic appliances will redefine compliance costs and consumer purchase criteria.
Market Dynamics
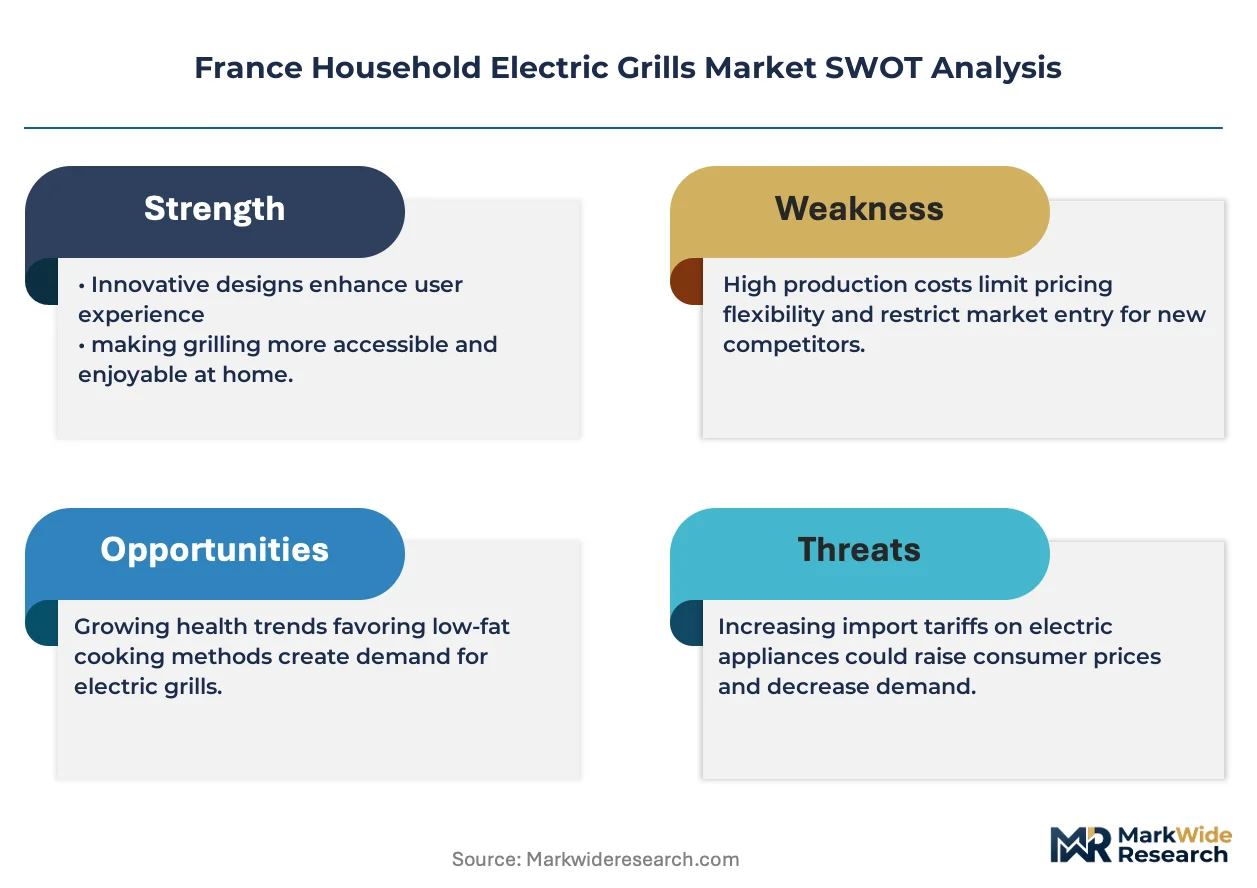
France's transposition of the EU Ecodesign Directive is compressing product development cycles as manufacturers redesign heating elements to meet tightening energy efficiency thresholds before the 2027 labeling revision deadline.
Growth Catalysts
- Île-de-France apartment density:Paris and inner-ring municipalities enforce strict balcony fire codes that prohibit charcoal and gas systems, channeling demand toward electric alternatives with compact footprints.
- EU Green Deal building standards:National decarbonization targets for residential energy consumption are accelerating landlord approvals of electric cooking appliances in rental units previously restricted to conventional stoves.
- Ceramic plate technology maturation:Advances in alumina-based heating surfaces are delivering infrared-level searing performance at mid-market price points, expanding addressable demand beyond premium tiers.
Market Restraints
- Copper and aluminum input volatility:Heating element manufacturing depends on conductive metal prices that have fluctuated sharply since 2022, compressing margin predictability for producers without long-term supply agreements.
- Chinese component concentration:Control boards and quartz infrared tubes source predominantly from Shenzhen and Dongguan manufacturing clusters, exposing French assemblers to shipping cost spikes and customs processing delays.
- Ventilation infrastructure gaps:Pre-1990s housing stock in Lyon and Marseille lacks exhaust systems adequate for smokeless grill marketing claims, limiting addressable households regardless of product performance.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur second-home market:Seasonal residences in Nice and Aix-en-Provence represent underpenetrated demand for portable electric grills that bypass municipal open-flame restrictions on terraces.
- AGEC anti-waste law extension:Pending inclusion of small domestic appliances would mandate repairability scoring and spare parts availability, favoring manufacturers with established service networks over import-only competitors.
- Smart kitchen ecosystem integration:Wi-Fi-enabled temperature logging and recipe synchronization with connected ovens are creating cross-selling opportunities through appliance retailer bundled financing programs.
Industry Challenges
- ANSM certification timelines:Electrical safety testing for new heating element configurations currently averages fourteen months, delaying product launches beyond seasonal demand windows.
- Embedded software talent scarcity:Firmware development for precision temperature control requires skill sets concentrated in automotive and industrial automation sectors, forcing compensation premiums for qualified engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Household Electric Grills Market |
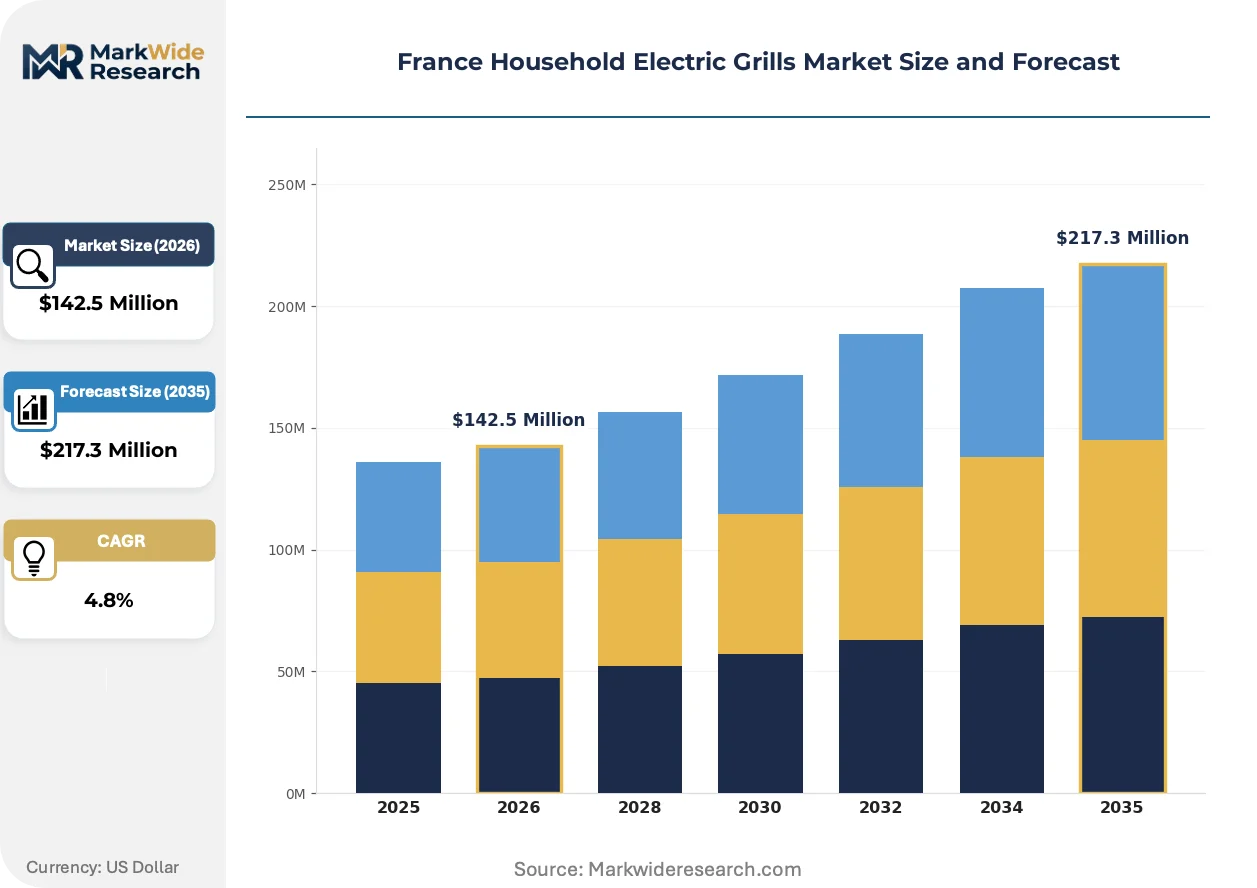
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Grills, Open Grills, Portable Grills, Smokeless Grills, Barbecue Grills Heat Source Technology: Infrared, Conduction, Convection, Induction, Ceramic Application: Indoor Cooking, Outdoor Cooking, Camping, Home Use, Small Scale Catering Customer Type: Individual Consumers, Rental Properties, Vacation Homes, Small Cafes, Specialty Retailers |
| Companies Covered | Philips, Roller Grill International, Groupe SEB, Char-Broil, Whirlpool, Brandt, Weber Inc, Tefal, Electrolux, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Household Electric Grills Market Shifts & Advancements
Product architecture is pivoting from standalone appliances toward connected cooking systems that capture usage data and monetize through subscription recipe platforms rather than hardware margins alone.
Infrared quartz tube arrays are integrating with ceramic diffusers to eliminate hot spots while maintaining rapid preheat cycles. Premium apartment buyers in Paris and Lyon are specifying these hybrid systems for kitchen renovations at accelerating rates. This convergence is integrating precision cooking capabilities into mid-tier price bands previously served by basic resistive elements.
France's energy labeling framework revision is mandating standby power consumption disclosures that disqualify legacy control board designs. Manufacturers are redesigning power management circuits to meet sub-1-watt thresholds. The Île-de-France retail channel is responding by clearing non-compliant inventory through promotional pricing ahead of enforcement deadlines.
Apartment dwellers are unbundling after-sales service from initial purchase decisions, prioritizing brands with documented repair networks over lowest acquisition cost. This behavioral shift is compressing replacement cycles for budget imports while extending effective lifespans for premium-tier products with available spare parts. The pattern is most visible in Marseille's dense arrondissements where word-of-mouth service quality drives repeat purchase intent.
France Household Electric Grills Market Segmentation
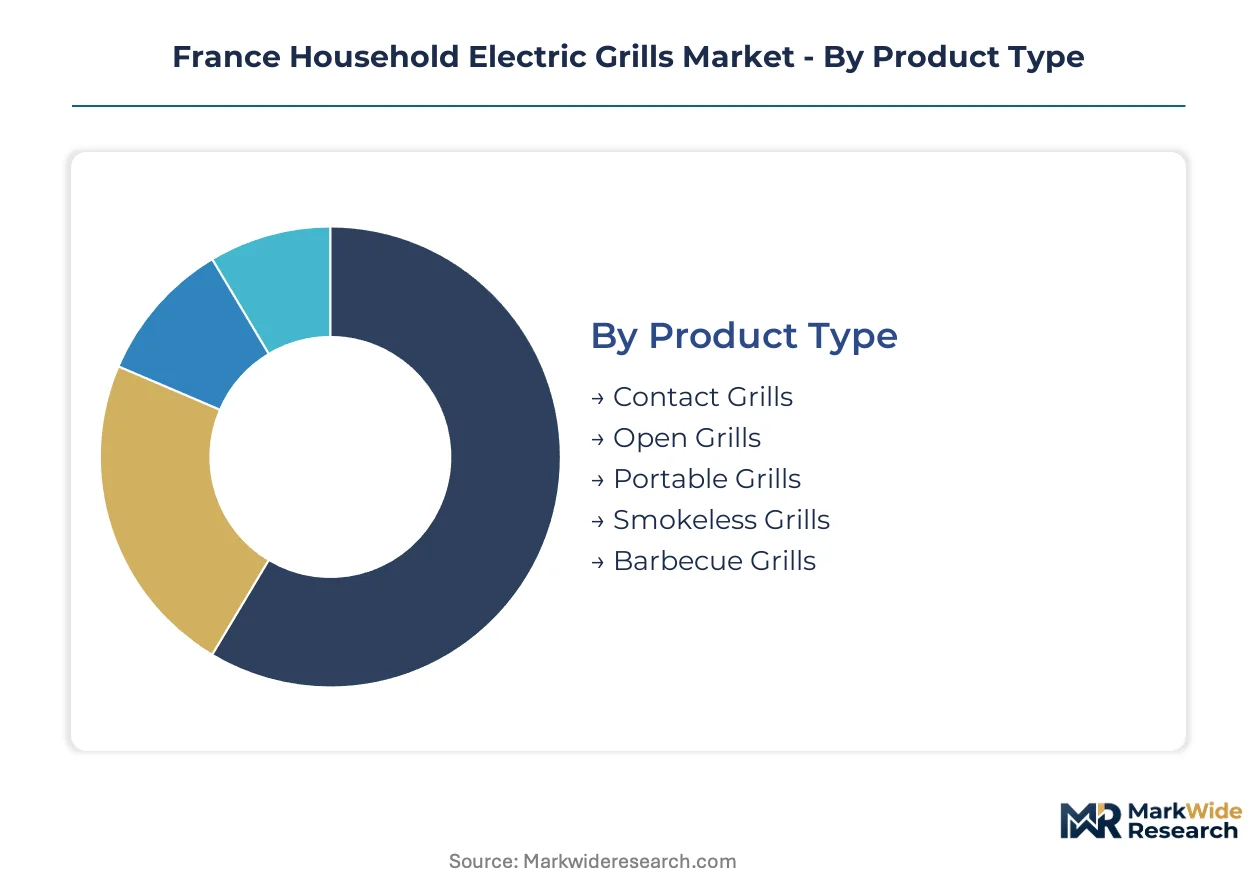
Segmentation in the France household electric grills market reveals how urban spatial constraints and energy efficiency regulations fragment demand across product architectures and customer profiles. Manufacturers align R&D investments with specific deployment contexts rather than pursuing universal designs.
Product Type:
Volume sales concentrate in compact formats suited to Parisian and Lyonnais apartment kitchens, while premium positioning attaches to performance-oriented configurations.
- Contact Grills:Dual heating plates apply simultaneous top-bottom thermal transfer through embedded resistive elements. Demand clusters in Île-de-France studio apartments where countertop footprint determines purchase viability. ANSM certification requirements for dual-element safety systems favor established assemblers over import-only distributors.
- Smokeless Grills:Integrated grease collection and catalytic filtration systems reduce particulate emissions below 5 mg/m³ for unventilated indoor operation. Marseille and Lyon pre-1990s housing stock without exhaust infrastructure drives adoption despite higher unit economics. This configuration is expanding most quickly as balcony fire codes tighten across French municipalities.
- Open Grills:Single-surface radiant heating mimics traditional barbecue geometry within electrical constraints. Provence-Alpes-Côte d'Azur second-home terraces generate seasonal demand spikes.
- Portable Grills:Battery-compatible or 12V automotive adapters enable mobile deployment. Camping retailers in the Alps and Pyrenees coordinate seasonal procurement cycles.
- Barbecue Grills:Larger-format electric alternatives to charcoal systems with hooded enclosures. Suburban detached housing in Grand Est and Nouvelle-Aquitaine sustains niche demand.
Mature deployment sits with Contact Grills. Newer deployment is concentrated in Smokeless Grills.
Heat Source Technology:
Technology selection determines margin structure and regulatory compliance trajectory under France's transposed EU Ecodesign thresholds.
- Infrared:Quartz tube arrays emitting 1.5-3 μm wavelength radiation achieve 300°C surface temperatures within 90 seconds. Philips anchors premium positioning through proprietary emitter geometry patents. Paris kitchen renovation contractors specify these systems for searing performance in compact footprints.
- Ceramic:Alumina-based plates with embedded heating coils distribute thermal energy through infrared-radiating surfaces. Mid-market price positioning in Toulouse and Bordeaux retail channels expands addressable demand beyond premium tiers. Ceramic surfaces eliminate fluorinated gas dependencies aligned with EU F-Gas Regulation phase-down schedules.
- Conduction:Direct resistive element contact with cooking surfaces represents legacy architecture. Budget imports from Chinese manufacturing clusters dominate volume.
- Convection:Forced-air circulation around heating elements enables uniform temperature distribution. Bakery-adjacent applications in small cafes drive specialized demand.
- Induction:Electromagnetic field generation through ferromagnetic cookware interfaces. R&D pipelines focus on eliminating rare-earth magnet dependencies.
Induction and ceramic configurations are gaining share fastest as energy labeling revisions approach. Conduction retains installed base concentration.
Application:
Usage context determines ventilation requirements, portability specifications, and power consumption profiles.
- Indoor Cooking:Year-round residential deployment in kitchens without external ventilation. Île-de-France apartment density sustains core demand.
- Outdoor Cooking:Terrace and balcony deployment subject to municipal open-flame prohibitions. Nice and Cannes municipal codes channel demand toward electric alternatives.
- Camping:Mobile recreational use requiring battery compatibility or generator interfaces. Seasonal demand patterns align with French school holiday calendars.
- Home Use:General residential cooking without specific mobility or commercial requirements. Broadest addressable segment with price-sensitive purchasing behavior.
- Small Scale Catering:Commercial-adjacent deployment in food trucks and event services. Roller Grill International adapts professional engineering for this niche.
Home Use maintains volume concentration. Small Scale Catering exhibits steepest expansion trajectory as gig economy food service formats proliferate.
Customer Type:
Procurement authority and replacement cycle length vary sharply across buyer categories.
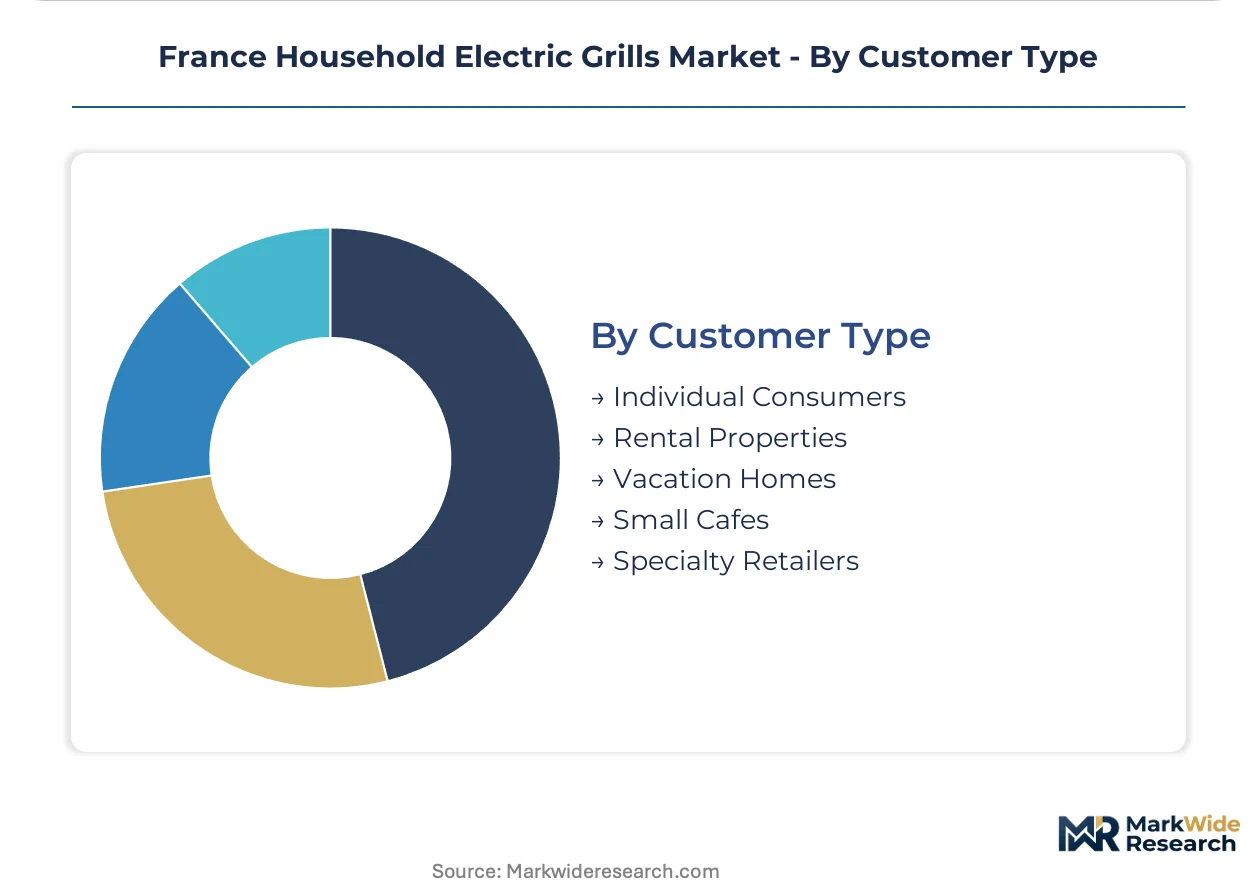
- Individual Consumers:End-user purchasers making discrete replacement decisions. Marseille arrondissement word-of-mouth networks prioritize brands with documented repair networks.
- Rental Properties:Landlord or property manager procurement for furnished units. EU Green Deal building standards accelerate electric cooking appliance approvals.
- Vacation Homes:Seasonal residence owners seeking low-maintenance alternatives to gas infrastructure. Provence-Alpes-Côte d'Azur penetration remains underdeveloped relative to primary residence markets.
- Small Cafes:Commercial food service operators with space-constrained kitchens. Breakfast-focused establishments in Lyon and Lille drive specialized demand.
- Specialty Retailers:Curated assortment buyers for kitchen and home goods channels. Fnac Darty and Boulanger buying committees determine seasonal inventory allocations.
Individual Consumers dominate transaction volume. Rental Properties show fastest-growing procurement authority as energy efficiency regulations reshape landlord equipment decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France consumes the majority of household electric grills produced across European manufacturing clusters, with domestic assembly concentrated in Île-de-France and Rhône-Alpes industrial zones. Production capacity in Poland and Germany supplies components, while Italian design houses influence premium product aesthetics.
Île-de-France
Parisian apartment density and strict balcony fire codes channel demand toward compact contact grills with sub-30cm footprints. ANSM certification requirements for dual-element safety systems favor established assemblers over import-only distributors. Fnac Darty and Boulanger buying committees in Saint-Denis determine seasonal inventory allocations for national retail.
Auvergne-Rhône-Alpes
Lyon's pre-1990s housing stock without exhaust infrastructure drives smokeless grill adoption despite higher unit economics. The EU Ecodesign Directive transposition accelerates R&D investment in ceramic heating surfaces at Saint-Étienne engineering clusters. Clermont-Ferrand polymer suppliers provide high-temperature housing materials for premium-tier manufacturers.
Provence-Alpes-Côte d'Azur
Nice and Cannes municipal codes prohibiting open flames on terraces generate seasonal demand spikes for portable electric alternatives. Vacation home owners in Aix-en-Provence represent underpenetrated demand for low-maintenance grilling equipment. Marseille's dense arrondissements exhibit strong word-of-mouth networks prioritizing brands with documented repair networks.
Hauts-de-France
Lille's compact urban core sustains contact grill volume comparable to Parisian levels on a per-capita basis. The region's logistics infrastructure at Calais and Dunkirk facilitates component import from Chinese manufacturing clusters. EU Green Deal building standards accelerate landlord approvals of electric cooking appliances in Lille's rental housing stock.
Nouvelle-Aquitaine
Bordeaux suburban detached housing sustains niche demand for larger-format barbecue grills with hooded enclosures. The region's wine tourism economy creates secondary demand from short-term rental property managers seeking durable kitchen equipment. Toulouse retail channels expand ceramic-plate technology into mid-market price bands previously served by basic resistive elements.
France Household Electric Grills Market Competitive Landscape
Top-tier vendors anchor premium positioning through proprietary heat source patents, while mid-market specialists compete on ceramic plate cost curves and compact form factors. The vendor base stratifies across three tiers: multinational appliance conglomerates with deep brand portfolios, regional specialists adapting commercial engineering for residential constraints, and import-assemblers competing on acquisition cost. Strategic archetypes include ecosystem integrators monetizing through subscription recipe platforms, component manufacturers backward-integrating into finished goods, and service-network builders extending effective product lifespans. Competitive moves concentrate on M&A for heating element technology access and strategic partnerships with connected kitchen platform providers.
Within the multinational conglomerate tier, Groupe SEB and Philips exemplify divergent technology strategies—SEB leveraging portfolio breadth across premium and mid-market tiers, Philips anchoring positioning through precision infrared heat source differentiation. Roller Grill International occupies a distinct specialization niche where commercial-grade engineering meets domestic kitchen constraints. These three represent the dominant competitive archetypes shaping R&D investment patterns and distribution channel access across French retail.
| Leading Market Players |
|---|
| Philips |
| Roller Grill International |
| Groupe SEB |
| Char-Broil |
| Whirlpool |
| Brandt |
| Weber Inc |
| Tefal |
| Electrolux |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists in Rhône-Alpes and Île-de-France anchor tiered pricing discipline through captive component production, insulating margin pools from Chinese import volatility while passing through copper and aluminum cost swings to end-users via seasonal promotional cycles.
Pricing Analysis
Margin tightening in mid-market tiers reflects ceramic plate technology diffusion that compresses premium positioning windows. Three-tier pricing structure across premium, standard, and economy levels separates infrared quartz systems from ceramic hybrids from basic resistive elements. ANSM certification costs and spare parts availability drive price differentiation between established assemblers and import-only distributors. Individual consumers in Marseille arrondissements exhibit highest price sensitivity, prioritizing repair network documentation over acquisition cost.
Supply Chain Analysis
France's transposition of EU Ecodesign and REACH regulations is accelerating domestic-content mandates that reshape sourcing from Shenzhen and Dongguan control board clusters toward Saint-Étienne ceramic plate engineering. Heating element manufacturing draws from Chinese quartz tube arrays, German conductive alloys, and Italian polymer housings. Single-source vulnerability concentrates in infrared emitter patents held by multinational conglomerates. Distribution runs through Fnac Darty and Boulanger buying committees determining seasonal inventory allocations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around repair-network scale and certification compliance as AGEC anti-waste extensions and ANSM testing timelines force import-assemblers toward exit.
For Market Incumbents: Anticipate ceramic-induction hybrid R&D pipelines displacing pure infrared positioning by securing Saint-Étienne engineering talent ahead of EU F-Gas Regulation phase-downs. Defend channel access through spare parts availability commitments that satisfy pending repairability scoring mandates. Vertical integration into alumina-based heating surfaces insulates margin pools from Chinese component volatility. For New Entrants and Emerging Players: Specialty camping retailers in the Alps and Pyrenees represent the most penetrable channel for battery-compatible portable formats bypassing established kitchen appliance distribution. Target Provence-Alpes-Côte d'Azur vacation home owners with low-maintenance terrace alternatives to gas infrastructure. White-space exists in connected kitchen ecosystem integration through Wi-Fi-enabled temperature logging bundled with appliance retailer financing programs. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-market ceramic specialists in Auvergne-Rhône-Alpes with established ANSM certification pipelines and documented service networks. Long-term viability across the analysis window rests on repairability compliance rather than hardware margin extraction. Watch AGEC implementation timelines as the signal for competitive shakeout velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Plate Production | Saint-Étienne engineering clusters reduce dependency on Chinese quartz tube imports under EU F-Gas schedules. |
| Repair Network Expansion | Marseille arrondissement service density drives repeat purchase intent ahead of AGEC spare parts mandates. |
| Smart Kitchen Platform Partnership | Fnac Darty bundled financing captures cross-selling opportunities with connected oven ecosystems. |
| AGEC Compliance Certification | Repairability scoring investment favors established assemblers over import-only competitors in retail channels. |
| Provence-Alpes-Côte d'Azur Distribution Push | Nice and Cannes municipal open-flame prohibitions channel seasonal demand toward portable electric alternatives. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs combining primary interviews with product development executives at Groupe SEB and Philips, category buyers at Fnac Darty and Boulanger, and aftermarket service heads with secondary validation through ANSM certification databases, EU Ecodesign transposition documents, and Île-de-France retail audit data. Bottom-up unit economics and top-down macroeconomic triangulation reconciled volume and value estimates.
Data-stream reconciliation across the projection horizon modeled product type, heat source technology, application context, and customer procurement authority dimensions. CAGRs derived from segment-level growth rate reconciliation with macroeconomic drivers including EU Green Deal building standards and municipal fire code enforcement patterns. Ceramic plate cost curves and infrared emitter patent expiry schedules informed technology transition assumptions.
Caveats apply where ANSM certification timeline extensions or AGEC anti-waste scope revisions could materially shift the outlook for new product launch windows and competitive entry barriers. Forecasts reflect documented assumptions about regulatory enforcement velocity and consumer repair behavior adoption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Smart Ceiling Fan Market
Appliances
Saudi Arabia Electric Water Heater Market
Appliances
Clothing Iron Market
Appliances
Laundry Dryer Market
Appliances
Asia Pacific Household Side by Side Refrigerator Market
Appliances
Qatar Microwave Ovens Market
Appliances
Refrigerator Door Seal Market
Appliances
Israel Laundry Appliances Market
Appliances
United Kingdom Compact Dishwasher Market
Appliances
Conveyor Dishwasher Market
Appliances
Fully Automatic Dishwasher Market
Appliances
Space Heaters Market
Appliances
Refrigerator Repair Service Market
Appliances
Dishwasher Market
Appliances
France Household Side by Side Refrigerator Market
Appliances
Water Dispenser Market