
 Portable Laptop Stands Market | 2026-2036
Portable Laptop Stands Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Laptop Stands Market Insights
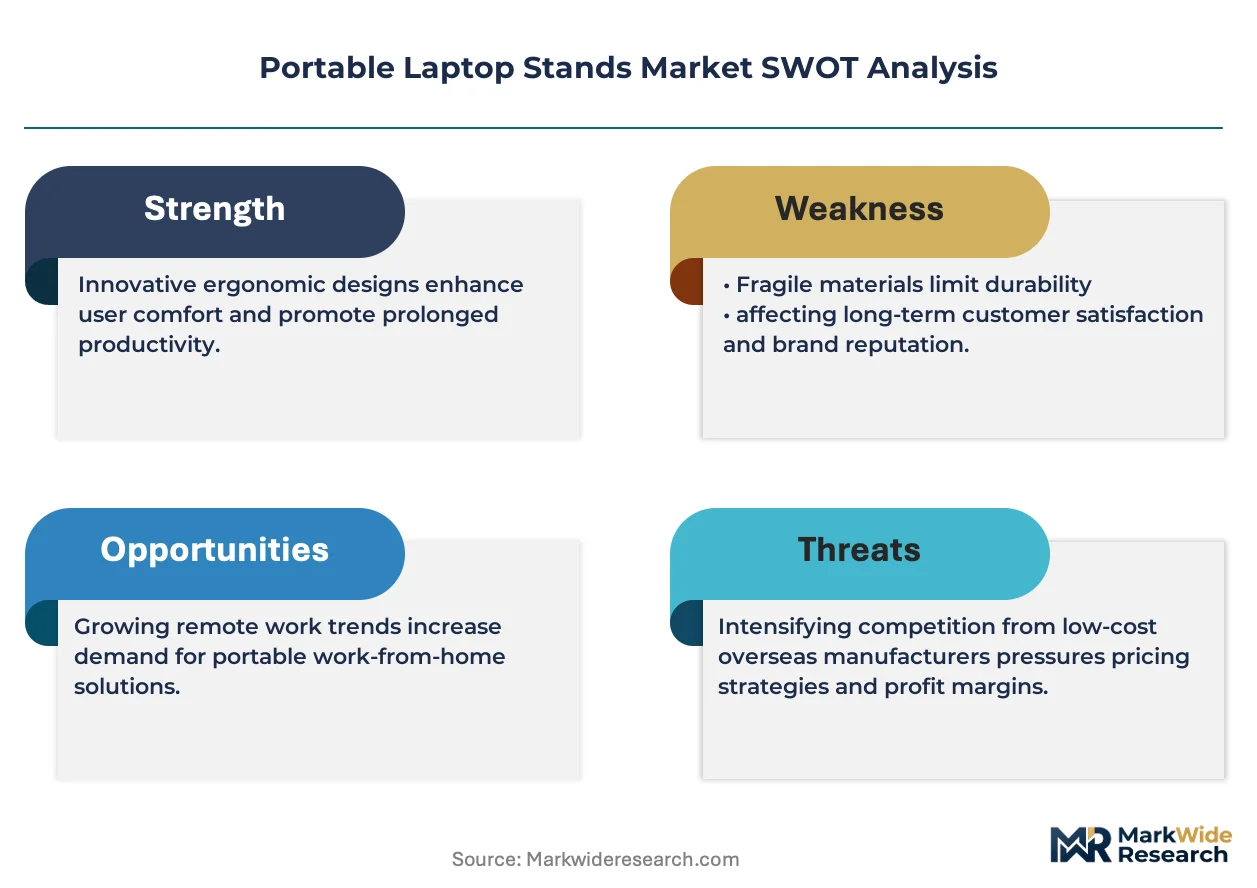
Buyer concentration across the portable laptop stand category is broadening from individual consumers toward enterprise procurement teams managing distributed workforces. Roost leverages direct-to-business channel partnerships to capture recurring corporate orders. MOFT anchors its position through minimalist design specialization that appeals to creative professionals. Ergotron, Inc. competes on adjustable-height engineering heritage drawn from full-scale workstation lines.
A portable laptop stand is a collapsible or compact elevating platform that positions notebook computers at ergonomic viewing angles, typically constructed from aluminum extrusions, injection-molded polymers, or laminated bamboo composites rated for loads between 10 and 44 pounds. The device reduces cervical strain and improves thermal ventilation in mobile and fixed work environments. Folding stands and adjustable stands command the widest margin pools due to premium positioning among professionals who prioritize packability and height customization. Aluminum dominates material selection for durability-conscious buyers, while plastic variants occupy entry-level price bands favored by student segments.
The U.S. Occupational Safety and Health Administration encourages ergonomic hazard mitigation in home-office settings, indirectly validating employer expenditure on elevated workstation accessories. The EU REACH regulation restricts certain phthalates and heavy metals in polymer formulations, pushing European-bound suppliers toward certified aluminum supply chains. California Proposition 65 labeling requirements add compliance overhead for wood-tray imports containing formaldehyde-based adhesives. Stakeholders must weigh material certification costs against channel-specific margin structures when allocating production capacity across export markets.
Market Dynamics
Enterprise procurement teams now mandate ergonomic accessories for distributed workforces, converting individual purchasing decisions into centralized bulk contracts with recurring replenishment cycles. This shift compresses price discovery and elevates compliance documentation requirements across supplier bases.
Growth Catalysts
- OSHA Home-Office Guidance:The U.S. Occupational Safety and Health Administration encourages employers to mitigate ergonomic hazards in remote settings, validating expenditure on elevated workstation accessories.
- Co-working Space Proliferation:Shared workspace operators in the United States equip hot-desking areas with portable stands to attract mobile professionals seeking plug-and-play ergonomics.
- Aluminum Extrusion Advances:Precision CNC machining of aircraft-grade alloys enables sub-one-kilogram stands rated for 44-pound loads, satisfying durability demands without packability penalties.
Market Restraints
- REACH Certification Burden:European-bound suppliers face elevated testing costs for polymer formulations, diverting capital from R&D toward compliance documentation.
- Raw Material Concentration:Primary aluminum smelting concentrates in China and the Gulf states, exposing manufacturers to energy-price volatility and export duty fluctuations.
- Smart Dock Substitution:Integrated laptop docks with built-in elevation mechanics threaten standalone stand volumes in corporate refresh cycles.
Strategic Opportunities
- EU Green Deal Procurement:Public-sector tendering across Germany, France, and the Netherlands now weights recycled-content thresholds, favoring suppliers with certified aluminum supply chains.
- Telehealth Workstation Bundles:Medical practices assembling mobile diagnostic kits create demand for antimicrobial-coated stands with cable management integration.
- Direct-to-Business Subscription:Channel innovation enables hardware-as-a-service models where employers lease stands with quarterly refresh guarantees and ergonomic training modules.
Industry Challenges
- Prop 65 Labeling Complexity:California's formaldehyde disclosure rules for bamboo-laminate imports delay container clearances and inflate legal review costs for wood-tray variants.
- Ergonomic Certification Timeline:Third-party validation from the Human Factors and Ergonomics Society extends product launch windows by four to six months.
- Freight Rate Volatility:Trans-Pacific container pricing swings compress landed margins for Asian-manufactured inventory destined for North American distribution centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Laptop Stands Market |
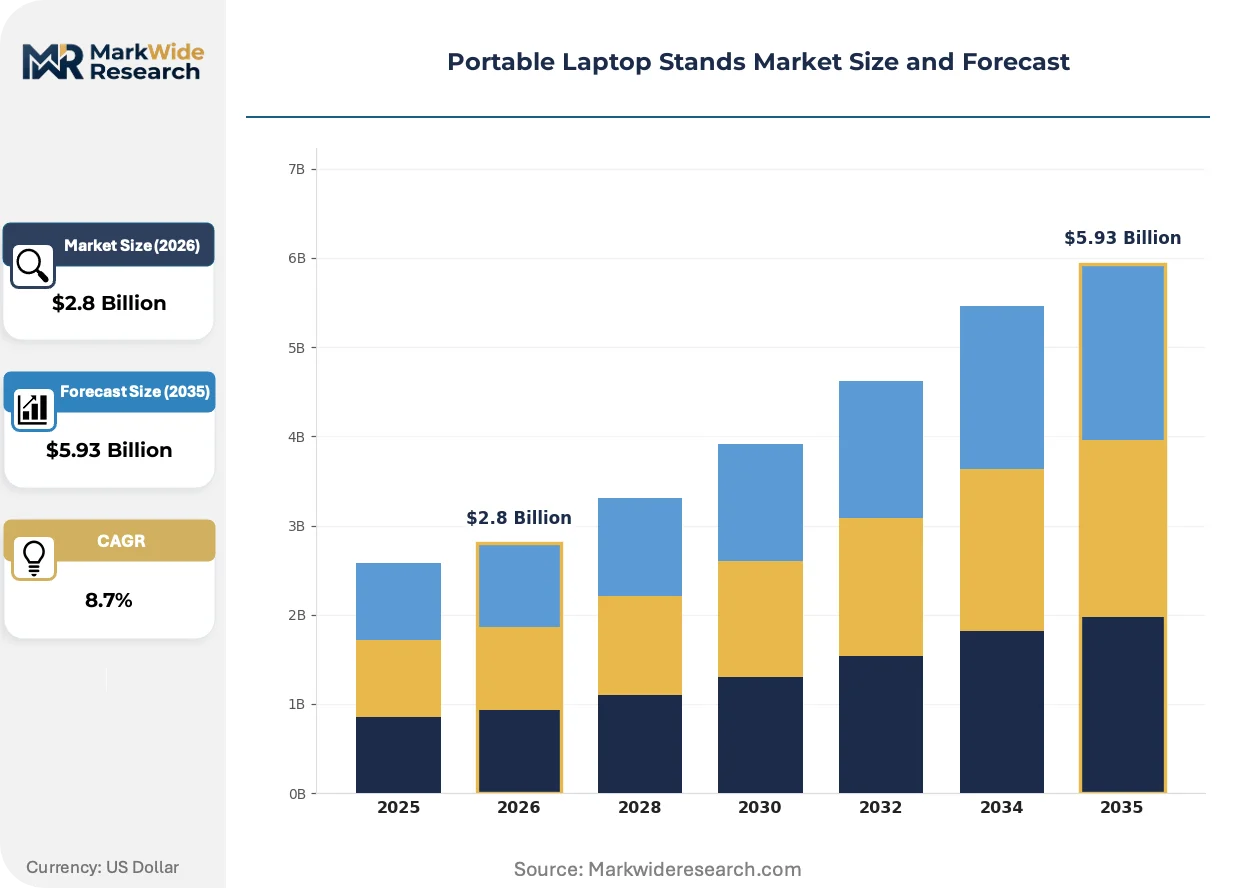
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adjustable Stands, Fixed Stands, Folding Stands, Portable Trays Material: Aluminum, Plastic, Wood, Steel End User: Students, Professionals, Freelancers, Gamers Distribution Channel: Online Retail, Specialty Stores, Mass Retailers, Direct Sales |
| Companies Covered | Roost, MOFT, Nulaxy, Nexstand, Lamicall, Rain Design Inc., Ergotron, Inc., Logitech International S.A., iVoler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Laptop Stands Market Trends and Innovations
Active redesign of portable laptop stands centers on material substitution, regulatory alignment, and procurement model transformation. These three vectors are compressing traditional product lifecycles and reshaping competitive positioning.
Carbon-fiber reinforced polymer is electrifying the premium tier by delivering 40% weight reduction against aluminum benchmarks without load-bearing compromise. Creative professionals and field engineers operating from backpacks and motorcycles are adopting these variants fastest. This material shift is enabling price stratification that separates ultralight specialists from commodity aluminum suppliers.
REACH Annex XVII restrictions on phthalates and heavy metals are forcing European-bound manufacturers toward certified aluminum supply chains with full material traceability. The regulation compresses polymer formulation options and elevates documentation overhead. German and Dutch distributors now require batch-level compliance certificates before accepting inbound inventory.
Centralized procurement teams at technology firms are displacing individual employee expense reimbursement for home-office equipment. Human resources departments negotiate master service agreements with ergonomic furniture vendors, consolidating supplier relationships and standardizing SKU selection. This concentration is most visible in the United States, where remote-first policies at software companies have normalized bulk stand deployment to residential addresses.
Portable Laptop Stands Market Segmentation
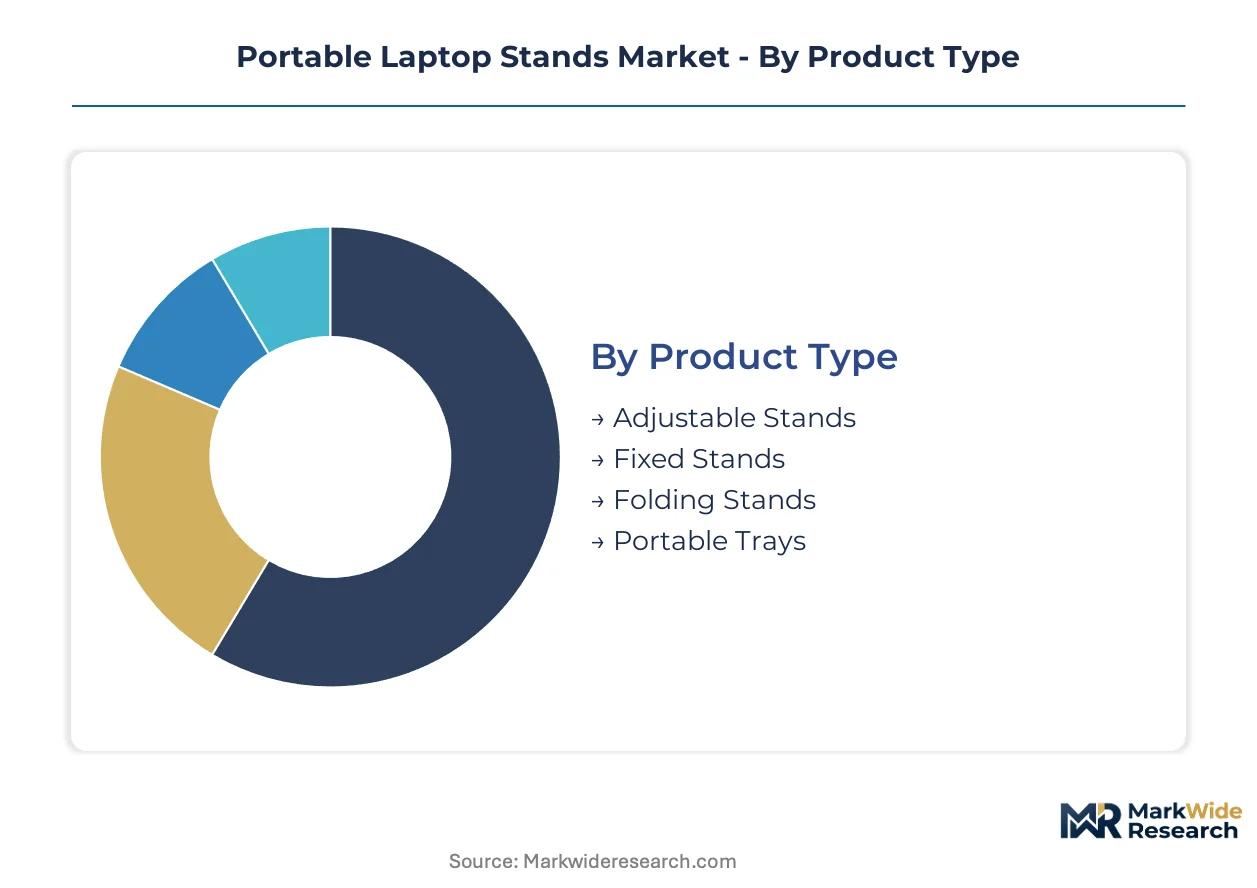
Portable laptop stands fragment across four structural dimensions that determine compliance pathways, margin profiles, and channel strategy. Each segmentation axis carries distinct certification burdens and procurement behaviors that suppliers must map precisely.
Product Type:
REACH Annex XVII and OSHA ergonomic guidance impose divergent testing protocols across mechanical configurations, with height-adjustable mechanisms triggering the most intensive validation cycles.
- Adjustable Stands:Telescoping aluminum columns and ratchet-lock hinges enable 6-to-16-inch height ranges for seated-to-standing transitions. Enterprise procurement teams at U.S. technology firms concentrate demand here, driven by OSHA home-office recommendations that validate employer expenditure on full ergonomic ranges.
- Folding Stands:Collapsible X-frame or Z-hinge architectures collapse to sub-2-inch profiles for backpack transport. Creative professionals and field engineers in co-working spaces across Austin, Berlin, and Singapore adopt these variants fastest, prioritizing packability over height range.
- Fixed Stands:Single-angle platforms molded from ABS or stamped aluminum occupy entry-level price bands. Student segments in India and Southeast Asia drive volume, with minimal compliance overhead beyond basic load-testing.
- Portable Trays:Lap-mounted surfaces with integrated cushioning target couch and bed use cases. Consumer demand concentrates in residential markets with limited regulatory exposure.
Leading the category by volume: Fixed Stands. Growing fastest: Adjustable Stands.
Material:
Raw material selection directly determines REACH documentation intensity, Prop 65 labeling exposure, and landed cost volatility for cross-border shipments.
- Aluminum:Aircraft-grade 6061-T6 extrusions dominate premium tiers, with CNC-machined joints rated for 44-pound loads. German and Dutch distributors now mandate batch-level REACH compliance certificates, favoring suppliers with certified smelter traceability.
- Plastic:Injection-molded ABS and polycarbonate formulations face ECHA scrutiny for phthalate content. Entry-level positioning in student segments minimizes margin absorption of testing costs.
- Wood:Bamboo-laminate trays trigger California Proposition 65 formaldehyde disclosure rules, delaying container clearances at Long Beach and Oakland ports.
- Steel:Powder-coated mild steel offers cost advantages but carries weight penalties that limit portability claims. Industrial procurement in manufacturing settings tolerates heft for durability.
Aluminum commands the premium tier by margin. Steel faces steepest share erosion.
End User:
Buyer archetypes diverge sharply in reimbursement pathways, with enterprise-provisioned professionals operating on centralized procurement contracts while freelancers and students remain individual purchasers.
- Professionals:Corporate remote-work policies at U.S. technology firms now mandate ergonomic home-office equipment, converting individual purchasing decisions into bulk contracts with recurring replenishment cycles.
- Freelancers:Independent contractors populate co-working spaces across American metropolitan areas, driving demand for packable solutions that travel between WeWork, Industrious, and residential locations.
- Students:Price-sensitive demand concentrates in back-to-school retail windows, with plastic variants favored for dormitory durability and theft tolerance.
- Gamers:RGB-integrated and cooling-optimized stands attract peripheral ecosystem spending, with demand clustering in South Korean and Taiwanese gaming hardware markets.
Professionals generate highest per-unit revenue. Freelancers are climbing fastest.
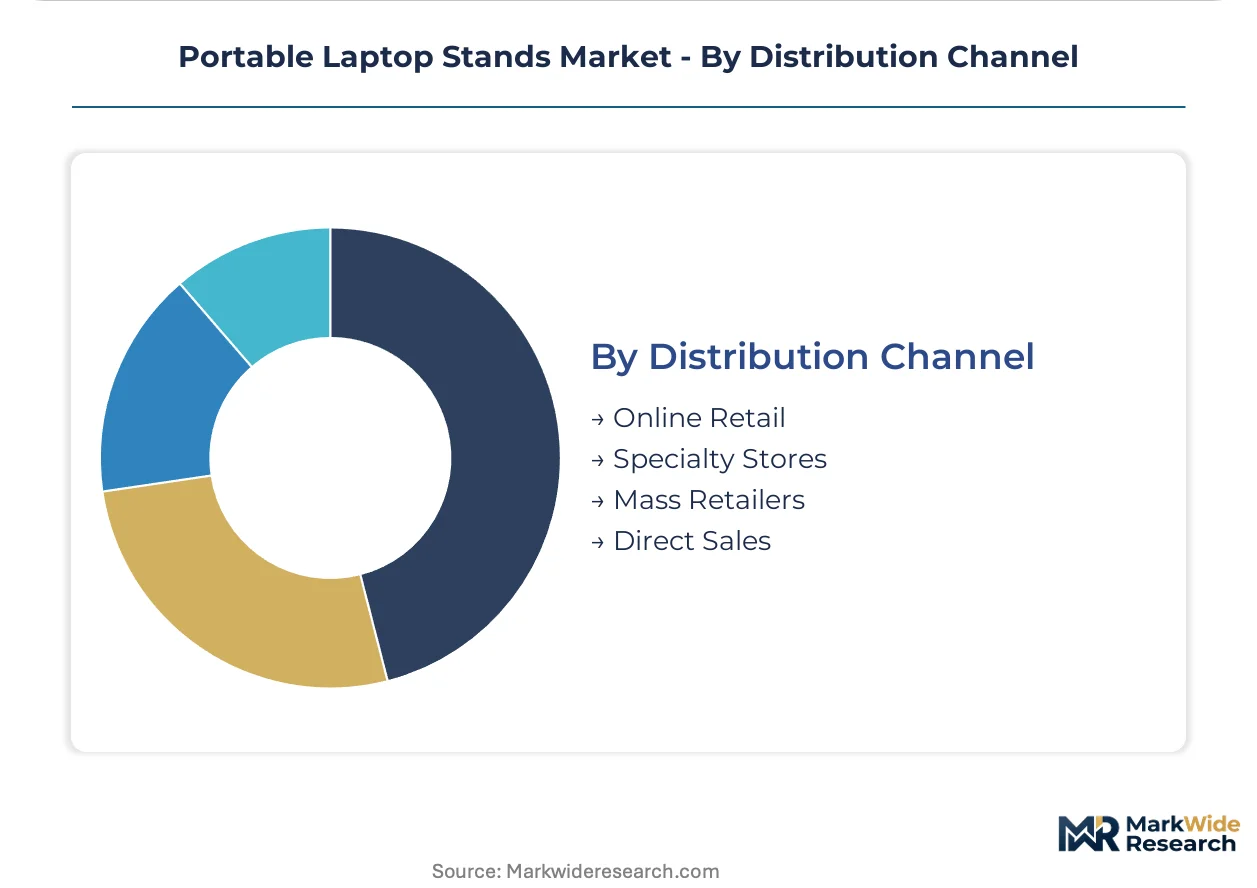
Distribution Channel:
Channel selection determines compliance documentation exposure, with direct sales to enterprises requiring the most intensive ergonomic certification files.
- Online Retail:Amazon and direct-to-consumer storefronts aggregate fragmented individual demand, with review velocity and return rates driving algorithmic visibility.
- Direct Sales:Master service agreements with human resources departments at distributed technology firms consolidate supplier relationships and standardize SKU selection across residential addresses.
- Specialty Stores:Ergonomic furniture retailers in urban centers provide tactile evaluation for premium aluminum and carbon-fiber variants.
- Mass Retailers:Best Buy and Target stock entry-level plastic and fixed-stand configurations for immediate pickup, with seasonal inventory turns aligned to academic calendars.
Online Retail leads by transaction volume. Direct Sales delivers steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States enterprise procurement teams now drive the highest per-unit expenditure, converting individual purchasing decisions into centralized bulk contracts with recurring replenishment cycles for distributed workforces.
United States
Technology firms in Seattle, Austin, and San Francisco mandate ergonomic home-office equipment under remote-first corporate policies. OSHA guidance on home-office hazard mitigation validates employer expenditure on elevated workstation accessories. Co-working space operators in New York City and Los Angeles equip hot-desking areas with portable stands to attract mobile professionals.
Germany
Public-sector tendering across Berlin, Munich, and Hamburg weights recycled-content thresholds under EU Green Deal procurement frameworks. ECHA REACH Annex XVII restrictions on phthalates push manufacturers toward certified aluminum supply chains with full material traceability. Ergonomic furniture distributors in the Rhine-Ruhr metropolitan region now require batch-level compliance certificates before accepting inbound inventory.
China
Primary aluminum smelting concentrates in Shandong and Xinjiang provinces, exposing manufacturers to energy-price volatility and export duty fluctuations. MIIT industrial standards govern precision CNC machining capabilities for aircraft-grade alloy extrusions. Shenzhen and Dongguan industrial clusters host the dominant share of folding stand and adjustable stand assembly operations.
Netherlands
Freelance workforce expansion in Amsterdam and Rotterdam sustains demand for packable solutions that travel between residential locations and shared workspaces. EU RoHS compliance pushes manufacturers toward aluminum alloys and recycled polymers in polymer formulations. The Randstad metropolitan region anchors distribution hub activity for European-bound inventory.
Japan
Creative professionals in Tokyo and Osaka adopt carbon-fiber reinforced polymer variants fastest, prioritizing ultralight packability for mobile work environments. METI industrial policy encourages material innovation in precision manufacturing sectors. The Kansai industrial corridor hosts specialized machining operations for premium-tier structural components.
Portable Laptop Stands Market Competitive Landscape
United States-based ergonomic specialists anchor one tier; East Asian fabricators hold cost-optimized volume positions. The vendor base stratifies across premium engineering heritage, direct-to-consumer agility, and mass-market scale. Three archetypes dominate: heritage workstation engineers, minimalist design specialists, and electronics peripheral integrators. Strategic moves concentrate on direct-to-business channel partnerships and certified supply chain verticalization.
Within the heritage engineering tier, Ergotron, Inc. and Rain Design Inc. represent decades of adjustable-height mechanical expertise translated into portable formats. MOFT occupies a position among design-forward specialists leveraging material minimalism for creative professional segments. Logitech International S.A. anchors the peripheral ecosystem integration archetype, bundling stand functionality with broader workstation accessory portfolios. These three exemplify how competitive positioning fragments across engineering credibility, aesthetic differentiation, and ecosystem lock-in rather than converging on uniform product specifications.
| Leading Market Players |
|---|
| Roost |
| MOFT |
| Nulaxy |
| Nexstand |
| Lamicall |
| Rain Design Inc. |
| Ergotron, Inc. |
| Logitech International S.A. |
| iVoler |
| Others |
Pricing and Supply Chain Analysis
Aircraft-grade aluminum extrusion costs cascade through three distinct pricing tiers, with Shandong and Xinjiang smelter energy-price volatility compressing margins for mid-market manufacturers while certified REACH-compliant suppliers command premium positioning in German and Dutch procurement channels.
Pricing Analysis
Volume concentrates in fixed ABS stands for student segments, while margin pools in adjustable aluminum and carbon-fiber variants for enterprise professionals. Three-tier pricing structure across premium, standard, and economy levels separates certified aerospace-grade suppliers from commodity extruders and entry-level molded plastic producers. Price differentiation hinges on REACH documentation depth and load-bearing certification tier. Cost compression in standard-tier aluminum stands is intensifying because Shenzhen assembly clusters face export duty fluctuations. Freelancers and students exhibit highest price sensitivity; U.S. technology firm procurement teams show lowest.
Supply Chain Analysis
Single-source vulnerability sits with primary aluminum smelting concentrated in China and Gulf states, exposing downstream fabricators to energy-price shocks and export duty revisions. Precision CNC machining of aircraft-grade 6061-T6 alloys draws from Shandong and Dongguan industrial clusters, with secondary finishing operations in Japan's Kansai corridor. Logistics chokepoint risk runs through Long Beach and Oakland ports, where California Proposition 65 formaldehyde disclosure rules delay bamboo-laminate container clearances. Distribution runs through direct-to-business master service agreements consolidating employer-provisioned procurement, alongside Amazon and specialty ergonomic retailers for individual purchasers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market occupies a material-transition phase where carbon-fiber reinforced polymers displace aluminum heritage in premium mobility segments, reshaping competitive moats around weight-to-strength engineering rather than commodity extrusion scale.
For Market Incumbents: Anchor defensible positioning through backward integration into certified aluminum supply chains with full REACH traceability, while accelerating carbon-fiber polymer R&D to counter ultralight specialist entrants. Prioritize direct-to-business channel control via master service agreements with technology firm HR departments, locking out commodity competitors from enterprise procurement consolidation. For New Entrants and Emerging Players: Antimicrobial coating integration for telehealth workstation bundles offers a technology-first wedge into medical practice procurement, an underpenetrated vertical with limited incumbent specialization. Target freelance workforce expansion in Amsterdam, Austin, and Singapore with sub-one-kilogram carbon-fiber variants, leveraging co-working space operator partnerships for bulk trial placement. For Investors and Strategic Acquirers: Enterprise procurement team formation at remote-first technology firms is the leading indicator that hardware-as-a-service subscription models will capture recurring revenue pools. Long-term viability favors vertically integrated specialists with captive aluminum certification and precision machining capabilities. Watch for MIIT industrial standard revisions in China as signals of supply-side consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Supply Chain Certification | Batch-level documentation unlocks German and Dutch public-sector tendering under EU Green Deal frameworks. |
| Carbon-Fiber Polymer Product Line Launch | Ultralight variants capture creative professional segments prioritizing motorcycle and backpack mobility. |
| Direct-to-Business Subscription Model | Hardware-as-a-service with quarterly refresh guarantees converts transactional sales into recurring revenue. |
| Telehealth Vertical Partnership | Antimicrobial stand bundles with cable management penetrate medical practice mobile diagnostic kit procurement. |
| Precision CNC Capacity Expansion | In-house aircraft-grade alloy machining reduces dependency on Dongguan assembly cluster volatility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across ergonomic furniture procurement managers, HR benefits administrators at distributed technology firms, co-working space operators, CNC machining plant engineers, and aluminum smelter sourcing directors. OSHA guidance documents, ECHA REACH Annex XVII restrictions, MIIT industrial standards, and California Proposition 65 enforcement records provided regulatory boundary conditions. Bottom-up SKU-level demand modeling and top-down macroeconomic triangulation validated volume estimates.
Reconciliation of shipment data from Shenzhen and Dongguan export clusters, U.S. enterprise procurement contract disclosures, and European distributor inventory flows informed the analytical framework across the projection horizon. Segmentation dimensions included product type, material grade, end-user archetype, and distribution channel complexity. CAGRs derived from curve-fitting historical growth patterns against remote-work policy adoption trajectories and co-working space expansion rates. Aluminum price volatility indices and trans-Pacific freight rate movements served as sensitivity inputs.
Several conditions sit outside the modeled scope, including potential smart dock substitution eliminating standalone stand demand, abrupt REACH regulatory expansion to carbon-fiber polymers, and sustained energy-price spikes forcing Chinese smelter output cuts. Forecasts reflect documented assumptions about remote-first policy persistence and enterprise reimbursement pathway evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Automated Laundromat Services Market
Consumer Electronics
Vape Cartridge Market
Consumer Electronics
Closed Back Studio Headphone Market
Consumer Electronics
Europe Gaming Headset Market
Consumer Electronics
Universal Remote Controls Market
Consumer Electronics
Global Speaker Market
Consumer Electronics
Global 4K TV Market
Consumer Electronics
Consumer Electronics Electric Motor Market
Consumer Electronics
Education PC Market
Consumer Electronics
DIY PC Gaming Chassis Market
Consumer Electronics
Global Wireless Headphones Market
Consumer Electronics
Global Polaroid Market
Consumer Electronics
Mobile Cases and Covers Market
Consumer Electronics
Instant Camera Market
Consumer Electronics
Consumer Electronics Repair and Maintenance Market
Consumer Electronics
Sleep Headphones Market