
 Global Power Adapter Market | 2026-2036
Global Power Adapter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Power Adapter Market Outlook
A capital-intensity divergence between integrated foundry operators and fabless design houses is rotating the competitive axis toward in-house GaN fabrication. Delta Electronics leverages vertical integration across magnetic component production to sustain margin control in high-wattage segments. Anker Innovates anchors its position through R&D intensity in gallium nitride topology, while Salcomp PLC dominates OEM supply relationships with major smartphone brands.
A power adapter is an electrical device that converts mains AC input to regulated DC output at specified voltage and current ratings, typically incorporating transformers, rectifiers, and switching regulators in compact thermal-managed enclosures. Its primary purpose is to safely deliver compatible electrical power to electronic devices while protecting against overvoltage, overcurrent, and thermal fault conditions. Wall-mounted adapters lead volume shipments due to their ubiquity in consumer electronics, yet fast charging technology captures disproportionate margin pools as OEMs differentiate on charge speed. USB adapters represent the fastest-expanding type category, driven by the IEC 62684 standardization of charging interfaces across device ecosystems.
The US Department of Energy enforces minimum efficiency standards under its External Power Supply program, while the EU Ecodesign Directive mandates standby power limits and active-mode efficiency tiers for adapters sold in member states. China's GB 20943 standard imposes analogous efficiency grades that manufacturers must satisfy for domestic market access. Stakeholders must monitor harmonization gaps between regional efficiency test protocols, as divergent certification requirements inflate compliance costs for multi-market product families.
Market Dynamics
Gallium nitride semiconductors are compressing thermal management requirements while multiplying power density, forcing incumbent silicon-based designs into obsolescence across consumer and industrial adapter segments simultaneously.
Growth Catalysts
- EU Ecodesign Directive:Mandatory standby power limits below 0.5W and active-mode efficiency tiers are compelling OEM adapter redesigns, creating replacement demand across existing installed bases.
- IEC 62684 standardization:Universal charging interface mandates for smartphones and laptops are consolidating connector types toward USB-C, expanding addressable market for multi-device compatible adapters.
- Shenzhen manufacturing cluster:Concentrated magnetic component and PCB assembly capacity enables rapid prototyping-to-production cycles, accelerating time-to-market for new GaN-based designs.
Market Restraints
- GaN wafer supply concentration:Epitaxial substrate fabrication remains captive to limited foundry capacity in Taiwan and the United States, creating input bottlenecks for adapter manufacturers scaling production.
- Copper and ferrite price volatility:Magnetic core materials and winding conductors constitute 35-40% of BOM costs, exposing margin stability to commodity exchange fluctuations.
- Regional certification fragmentation:Divergent efficiency test protocols between DOE External Power Supply program, EU Ecodesign, and China's GB 20943 inflate compliance engineering overhead for multi-market product families.
Strategic Opportunities
- India appliance electrification:Rural household appliance penetration and smartphone adoption are creating first-time adapter demand outside existing replacement cycles.
- Electric vehicle auxiliary charging:Onboard and portable EV supply equipment requires high-wattage adapters with automotive-grade thermal reliability, opening adjacent revenue pools.
- RoHS and REACH substance restrictions:Phased elimination of cadmium and certain flame retardants in EU markets advantages early-compliant manufacturers with pre-certified product platforms.
Industry Challenges
- GaN power electronics talent scarcity:RF and power semiconductor design expertise for high-frequency switching topologies remains concentrated among limited engineering pools, constraining R&D scaling.
- Multi-jurisdiction certification timelines:Sequential safety and efficiency approvals across UL, CE, and CCC marks extend product launch windows by 4-7 months.
- Legacy silicon inventory stranding:Existing adapter manufacturers face write-down pressure from obsolete stock as GaN designs achieve cost parity at equivalent wattages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Power Adapter Market |
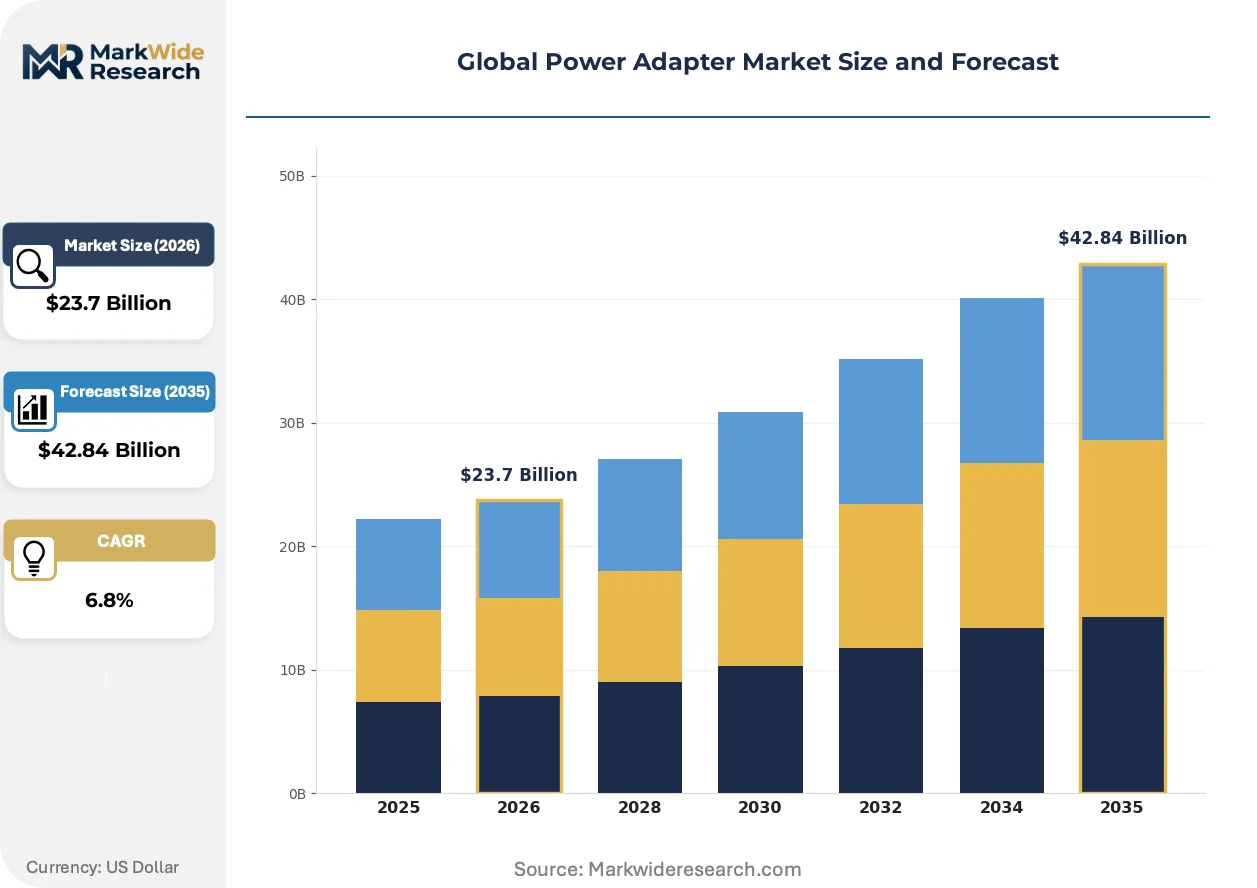
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: AC Adapter, DC Adapter, USB Adapter, Travel Adapter Application: Laptops, Smartphones, Cameras, Tablets Technology: Wall-mounted, Wireless, Fast Charging, Solar End User: Consumer Electronics, Industrial Equipment, Automotive, Healthcare |
| Companies Covered | Delta Electronics, Inc., Anker Innovations, Belkin International, Inc., Lite-On Technology Corporation, Salcomp PLC, Samsung Electronics Co., Ltd., MEAN WELL Enterprises, TDK Corporation, Huawei Technologies Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Power Adapter Market Strategic Shifts
Power adapter architecture is undergoing simultaneous transformation across semiconductor material, regulatory compliance framework, and procurement methodology, compressing product lifecycles while expanding performance boundaries.
GaN-on-silicon power transistors are fragmenting the traditional MOSFET-dominated adapter landscape by enabling switching frequencies above 1MHz with sub-10°C temperature deltas. Laptop and smartphone OEMs are accelerating adoption for 65W-140W fast-charging SKUs. This frequency multiplication is compressing transformer and capacitor volumes by 40-50%, collapsing enclosure sizes and logistics costs simultaneously.
China's GB 20943-2022 efficiency grades are mandating tiered standby and active-mode performance thresholds for domestic market access, with Grade 1 certification becoming a procurement prerequisite for state-affiliated electronics tenders. Manufacturers are redesigning feedback control loops and synchronous rectification stages to meet these thresholds. High-volume consumer electronics destined for Chinese retail channels are experiencing the most intensive redesign cycles.
Enterprise IT procurement is consolidating adapter sourcing through original design manufacturer direct contracts, bypassing traditional distributor markups for standardized 65W-90W laptop power supplies. This disintermediation is compressing channel margins while transferring specification ownership to end-user procurement teams. North American and European enterprise refresh cycles are exhibiting this pattern most prominently, with annual volume commitments replacing spot purchasing.
Global Power Adapter Market Segmentation
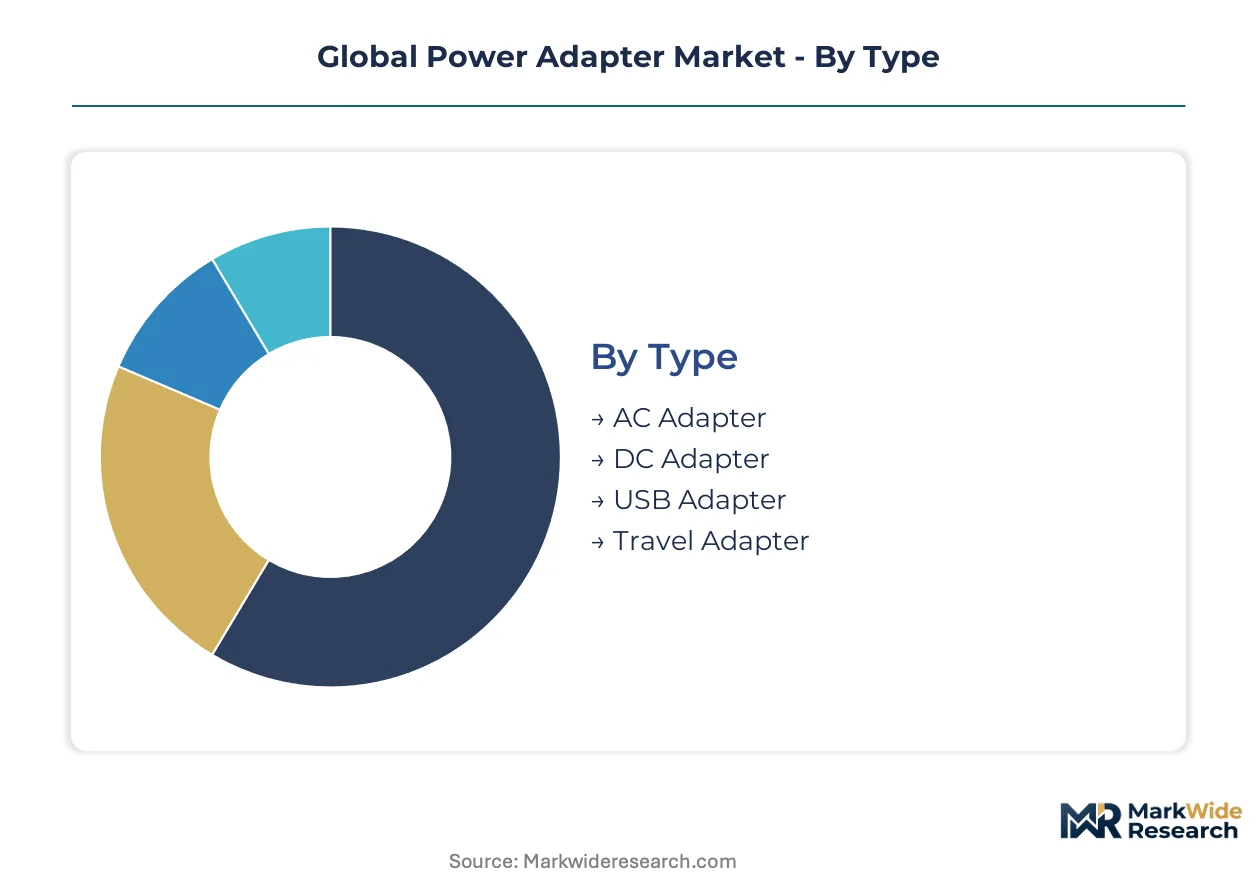
Adapter segmentation reveals divergent supply chain footprints across categories. Type and technology dimensions show stark domestic-export splits, while application and end-user segments map directly to manufacturing cluster proximity.
Type:
AC and DC adapters flow predominantly through export channels serving multinational OEMs, whereas USB and travel variants split between domestic retail and cross-border e-commerce.
- AC Adapter:Converts mains alternating current to regulated DC output through transformer-rectifier stages. Demand concentrates in industrial equipment procurement from Germany and Japan, constrained by IEC 62368-1 safety certification timelines for high-wattage units.
- DC Adapter:Accepts DC input for voltage step-up or step-down conversion in vehicle and solar applications. Automotive auxiliary systems in South Korea and photovoltaic installations in Australia drive specification requirements toward wide input voltage ranges.
- USB Adapter:Delivers standardized power delivery protocols through Type-C connectors. China's domestic smartphone refresh cycles and India's rural electrification programs generate parallel demand streams with distinct price elasticity.
- Travel Adapter:Integrates multi-region plug configurations with voltage switching. Cross-border tourism recovery in Southeast Asia and Middle East airport retail channels shapes inventory allocation.
AC Adapter holds the largest share; momentum sits with USB Adapter.
Application:
Cost tier stratification separates premium laptop adapters from economy smartphone units, with camera and tablet segments occupying intermediate positions.
- Laptops:Enterprise procurement contracts specify 65W-140W GaN-based units with ENERGY STAR qualification. North American corporate refresh cycles and European public sector tenders enforce efficiency tier minimums that exclude legacy silicon designs.
- Smartphones:OEM bundling policies and aftermarket replacement demand split volume between brand-certified and third-party channels. India's PLI scheme for domestic electronics assembly is redirecting supply chain origination from Shenzhen to Noida.
- Cameras:Professional imaging equipment requires stable voltage rails with minimal ripple. Broadcast and cinema production hubs in California and the United Kingdom maintain specialized procurement channels.
- Tablets:Education sector bulk purchasing in Brazil and Mexico competes with consumer retail in Japan for production slot allocation.
Laptop applications command premium pricing; smartphone volumes are climbing the fastest.
Technology:
Volume concentration favors wall-mounted units, while margin pools concentrate in fast charging and wireless segments with differentiated thermal management.
- Wall-mounted:Direct AC plug integration eliminates cable clutter for consumer electronics. Mass production economies in Dongguan and Chittagong serve price-sensitive retail channels across emerging markets.
- Wireless:Inductive coil alignment and foreign object detection circuits add BOM complexity. Automotive console integration in Germany and furniture embedding in Scandinavian markets drive coil specification divergence.
- Fast Charging:GaN semiconductors enable 100W+ delivery in palm-sized enclosures. Flagship smartphone launches in China and gaming laptop refreshes in Taiwan set power density benchmarks.
- Solar:Photovoltaic input regulation with maximum power point tracking for off-grid applications. Rural electrification projects in Kenya and humanitarian deployments in Yemen define durability requirements.
Wall-mounted technology dominates unit shipments; fast charging shows the steepest expansion trajectory.
End User:
Customer type splits procurement methodology: consumer electronics through retail and e-commerce, industrial and automotive through direct OEM contracts, healthcare through regulated distributor channels.
- Consumer Electronics:Brand loyalty and price sensitivity coexist in replacement purchasing. Amazon and Flipkart marketplace dynamics in India versus brick-and-mortary recovery in Japan create channel-specific SKU proliferation.
- Industrial Equipment:IP-rated enclosures and wide temperature operation specifications predominate. Factory automation deployments in Vietnam and oilfield instrumentation in Texas demand extended mean-time-between-failures certification.
- Automotive:Onboard charging modules and portable EV supply equipment require AEC-Q101 component qualification. Charging infrastructure rollout in France and fleet electrification in the United Kingdom set wattage targets.
- Healthcare:IEC 60601-1 medical safety isolation and leakage current limits constrain design flexibility. Diagnostic imaging OEMs in the Netherlands and patient monitoring device manufacturers in Massachusetts enforce traceability protocols.
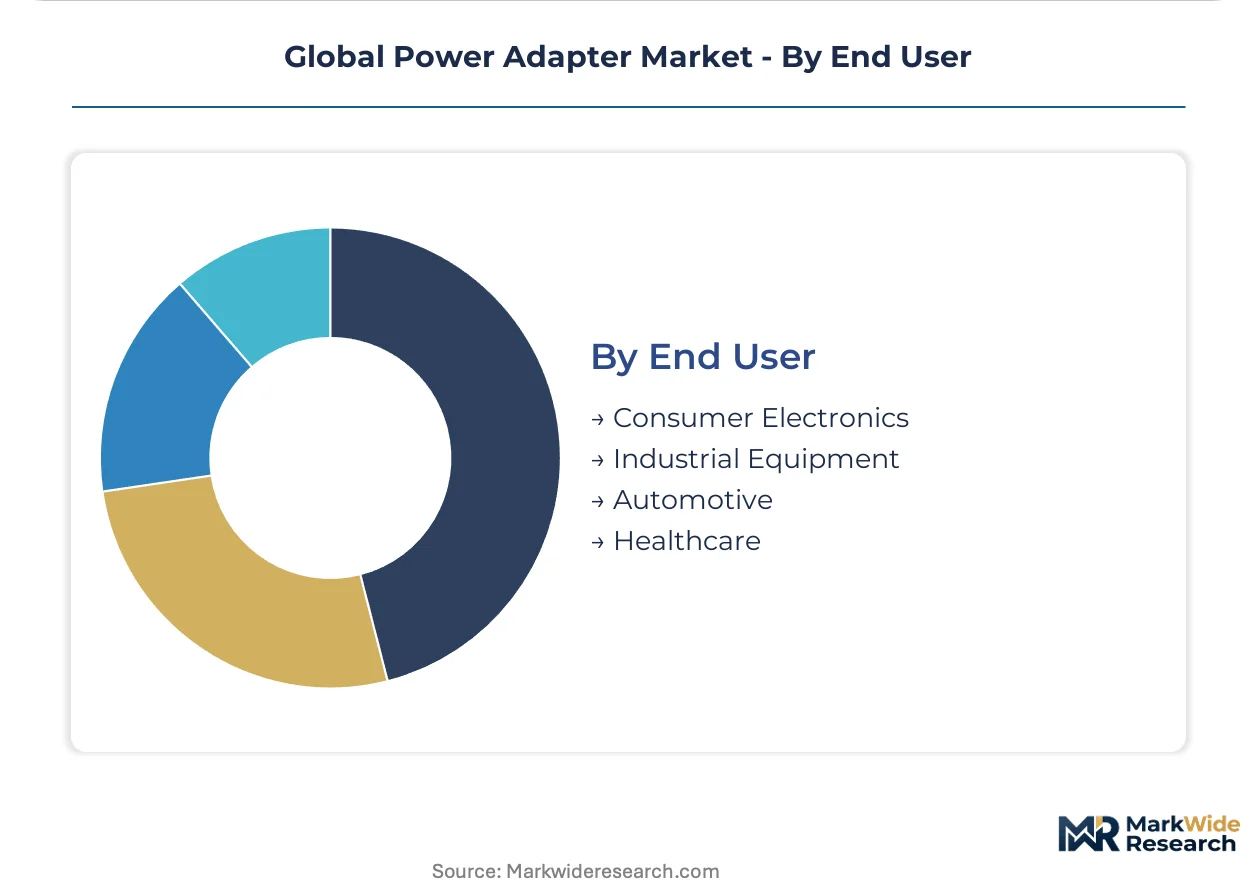
Consumer Electronics captures the largest volume; automotive applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies: Indian rural buyers demand sub-$5 smartphone adapters while German industrial purchasers absorb 40-60% premiums for ENERGY STAR-qualified laptop units. This divergence fragments regional go-to-market strategies.
China
Domestic smartphone refresh cycles and state-affiliated electronics tenders drive volume demand. GB 20943-2022 efficiency grades mandate Grade 1 certification for government procurement eligibility. Shenzhen's magnetic component and PCB assembly cluster enables rapid GaN prototyping-to-production cycles for export-bound adapters.
United States
Enterprise laptop refresh cycles and corporate sustainability mandates concentrate demand for 65W-140W GaN units. The Department of Energy's External Power Supply program enforces minimum active-mode efficiency standards. California's technology procurement offices and Texas-based industrial distributors shape specification requirements for premium segments.
Germany
Automotive console integration and industrial automation deployments sustain demand for high-reliability units. The EU Ecodesign Directive mandates standby power limits below 0.5W and tiered active-mode efficiency requirements. Bavaria's automotive electronics ecosystem and Baden-Württemberg's industrial machinery corridor concentrate adapter specification authority.
India
Rural household appliance penetration and PLI-scheme smartphone assembly expansion generate first-time adapter demand outside replacement cycles. The Bureau of Indian Standards enforces IS 13252 safety certification for domestic market access. Noida's emerging electronics manufacturing zone and Maharashtra's industrial corridors are redirecting supply chain origination from Shenzhen.
Japan
Consumer electronics retail recovery and enterprise IT standardization sustain replacement demand with low price sensitivity. METI's Top Runner program establishes efficiency benchmarks that exceed global minimums. Tokyo's procurement offices and Osaka's electronics distribution networks maintain specialized channels for low-ripple professional imaging equipment.
Global Power Adapter Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the former commanding captive magnetic component production and the latter competing on design agility. The market structure rewards backward integration into ferrite core and transformer winding capabilities while penalizing pure-play assemblers. Three archetypes dominate: vertically integrated component manufacturers, GaN topology specialists, and OEM-captive suppliers. Capacity expansion in Taiwan and mainland China, alongside strategic partnerships for GaN wafer access, constitute the primary competitive vectors.
Among Taiwan-based integrated electronics manufacturers, Delta Electronics, Inc. exemplifies the vertically integrated archetype through its magnetic component production capabilities. Anker Innovations occupies a position within the GaN-focused design specialist tier, while Salcomp PLC anchors the OEM-captive supplier category through its smartphone brand relationships. These three entities represent distinct strategic postures without implying specific market share positions or operational details.
| Leading Market Players |
|---|
| Delta Electronics, Inc. |
| Anker Innovations |
| Belkin International, Inc. |
| Lite-On Technology Corporation |
| Salcomp PLC |
| Samsung Electronics Co., Ltd. |
| MEAN WELL Enterprises |
| TDK Corporation |
| Huawei Technologies Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Mass production economies in Shenzhen's magnetic component cluster compress unit costs for high-volume USB-C adapters while simultaneously anchoring global price floors. This concentration enables rapid GaN prototyping cycles that accelerate premium-tier obsolescence of legacy silicon designs across consumer electronics procurement channels.
Pricing Analysis
Aftermarket replacement revenue and extended warranty bundling drive lifetime value capture in branded adapter portfolios. Three-tier pricing structure across premium GaN-enabled, standard silicon-based, and economy unbranded levels segments buyer archetypes by certification grade and thermal performance. Cost compression in economy tiers intensifies because Shenzhen assemblers compete on bill-of-material optimization for India's price-sensitive rural electrification programs. Enterprise procurement teams exhibit lowest price sensitivity, absorbing substantial premiums for ENERGY STAR-qualified laptop adapters with synchronous rectification.
Supply Chain Analysis
Strait of Malacca transit underwrites magnetic core and ferrite shipments from China to Southeast Asian assembly plants. Manufacturing gravity centers on China, Taiwan, and Vietnam, with raw material dependencies spanning copper windings, ferrite cores, and GaN-on-silicon wafers. Single-source vulnerability concentrates in Taiwan's epitaxial substrate foundries, where limited GaN wafer capacity constrains adapter manufacturer scaling. Distribution runs through original design manufacturer direct contracts to enterprise procurement teams, bypassing traditional electronics distributor markups for standardized laptop power supplies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GaN semiconductor displacement of silicon MOSFETs constitutes a high-growth disruption reshaping adapter competitive dynamics. The EU Ecodesign Directive's standby power mandates and IEC 62684 connector standardization accelerate this technological inflection across multi-device charging ecosystems.
For Market Incumbents: Consolidate backward integration into ferrite core production to defend margin control against commodity copper and magnetic material volatility. Capture GaN wafer supply agreements with Taiwan foundries before epitaxial substrate bottlenecks constrain high-wattage adapter scaling. Prioritize Grade 1 GB 20943 certification for Chinese state-affiliated electronics tenders.
For New Entrants and Emerging Players: Lead with automotive-grade thermal reliability specifications for electric vehicle auxiliary charging equipment, where AEC-Q101 component qualification creates defensible positioning. Target India's PLI-scheme smartphone assembly expansion in Noida and Maharashtra, where first-time adapter demand outside replacement cycles offers white-space penetration. Deploy direct OEM contracting to bypass entrenched distributor relationships in North American enterprise laptop refresh cycles.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated component manufacturers with captive magnetic production and GaN topology R&D capabilities over pure-play assemblers. Long-term viability across the projection horizon rests on backward integration depth and foundry partnership security rather than brand equity alone. Monitor GaN-on-silicon cost parity milestones against legacy silicon as the primary inflection signal for portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Topology R&D Investment | Enables 100W+ palm-sized enclosures for flagship smartphone launches in China. |
| Magnetic Component Backward Integration | Captures ferrite core and transformer winding supply for margin control in high-wattage segments. |
| Multi-Jurisdiction Certification Pre-Positioning | Accelerates UL, CE, and CCC mark acquisition to compress 4-7 month approval timelines. |
| Enterprise Direct Contracting | Bypasses distributor markups through ODM relationships with North American corporate procurement. |
| Automotive Thermal Reliability Qualification | Opens EV auxiliary charging revenue pools requiring AEC-Q101 component standards. |
Study Parameters
A standing panel of adapter procurement managers at smartphone OEMs, magnetic component sourcing leads, GaN semiconductor design engineers, and enterprise IT asset managers provided ongoing calibration across primary fieldwork. Secondary validation drew from SEC filings of publicly traded electronics manufacturers, China's GB standards documentation, EU Ecodesign regulatory texts, and customs trade data for ferrite core and copper winding imports. Bottom-up bill-of-material cost modeling and top-down OEM shipment aggregation were triangulated against efficiency certification databases.
Consistency checks validated volume and value outputs against external benchmarks including ENERGY STAR qualified product lists and Bureau of Indian Standards registration records. The analytical framework segmented by adapter type, application, technology, and end-user across the projection horizon, with CAGRs derived from shipment trajectory modeling and replacement cycle analysis. Forecast inputs incorporated GaN adoption curves, copper price volatility scenarios, and regulatory efficiency tier tightening schedules.
Forecasts assume regulatory continuity in EU Ecodesign, US DOE External Power Supply, and China GB 20943 regimes; material policy shifts would require re-modeling. Supply chain disruption from Taiwan foundry concentration or Malacca Strait logistics interruption represents specific revision triggers. Practitioners should keep alternative scenarios live as GaN cost parity milestones and India's PLI-scheme manufacturing relocation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic and Electrical
Video Doorbell Market
Electronic and Electrical
Global Personal Care Electrical Appliances Market
Electronic and Electrical
Electronic Weighing Scale Market
Electronic and Electrical
Computer Keyboard Market
Electronic and Electrical
Air Conditioner Remote Control Market
Electronic and Electrical
Europe Gaming Accessories Market
Electronic and Electrical
Mobile Phone Power Accessories Market
Electronic and Electrical
Sports Electronics Devices Market
Electronic and Electrical
3D Glasses Chargers Market
Electronic and Electrical
A/V Cassette Housings & Parts Market
Electronic and Electrical
USB Power Strips Market
Electronic and Electrical
Audio Jack Market
Electronic and Electrical
Active Damping Smartphone Case Market
Electronic and Electrical
Wireless Keyboard Market
Electronic and Electrical
Electronic Insect Killer Market
Electronic and Electrical
Electronic Equipment Repair Service Market