
 Cooler Connected to the Mains Market | 2026-2036
Cooler Connected to the Mains Market Size, Share, and Industry Trends Forecast 2026-2036
Cooler Connected to the Mains Market Analytics
The capital-intensity divergence between compressor-based and thermoelectric manufacturers is rotating competitive investment toward high-efficiency inverter platforms. Daikin Industries leverages captive semiconductor sourcing for variable-speed drive modules. Midea Group anchors volume production through automated sheet-metal stamping lines in Foshan. Symphony Limited dominates India's evaporative-to-compressor transition with localized R&D centers in Gujarat.
A cooler connected to the mains is a fixed-installation thermal management appliance drawing continuous electrical supply from building infrastructure, typically achieving cooling capacities between 2 kW and 15 kW through vapor-compression or absorption cycles. These units serve commercial and institutional spaces requiring sustained temperature control without portable unit limitations. Smart coolers with IoT-enabled energy management command premium positioning as building automation integration deepens. Compressor-based technology sustains the largest installed base while inverter variants capture fastest replacement-cycle growth. The hospitality segment concentrates margin pools through specification-driven procurement and service-contract bundling.
China's SAMR enforces GB standards on cooling efficiency and refrigerant containment, while India's BIS mandates energy-label compliance for commercial cooling equipment. The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants, forcing redesigns of compressor architectures across export-oriented manufacturers. Stakeholders must monitor refrigerant-transition timelines and efficiency-certification reciprocity between origin and destination markets.
Market Dynamics
Inverter compressor technology is compressing replacement cycles across commercial cooling infrastructure, while refrigerant phase-down mandates force simultaneous architecture redesigns. This dual pressure creates asymmetric capability gaps between manufacturers with captive semiconductor sourcing and those dependent on merchant supply.
Growth Catalysts
- China's dual carbon goals:National emissions targets accelerate building energy retrofits, driving specification upgrades to variable-speed systems in hospitality and healthcare facilities.
- India's commercial corridor expansion:Concentrated development in Gujarat and Maharashtra generates sustained demand for fixed-installation cooling in retail and institutional construction.
- Inverter drive modules:Semiconductor cost curves enable cost-competitive variable-speed platforms that cut operating expenditure for facility managers.
Market Restraints
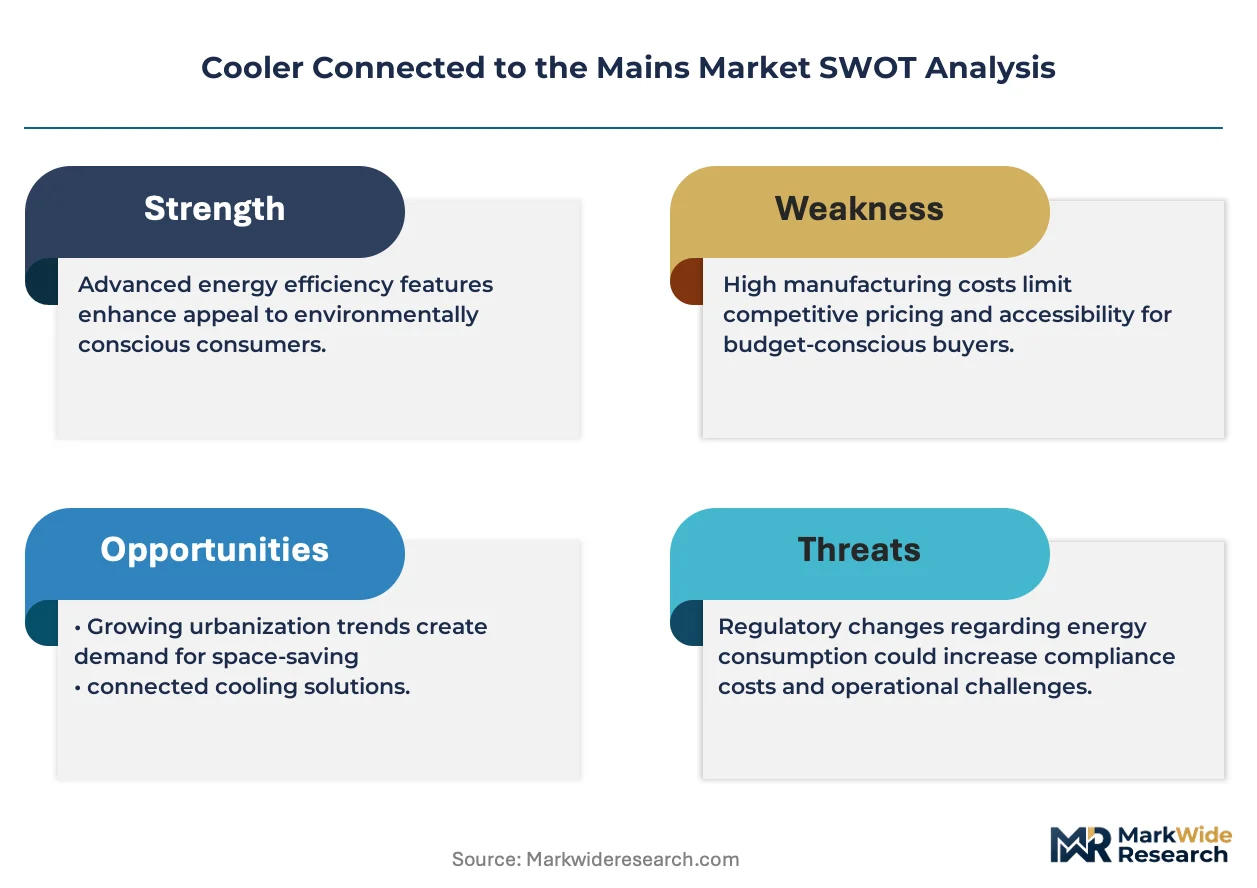
- Copper and rare-earth price volatility:Compressor winding materials and permanent-magnet motors expose manufacturers to commodity input swings.
- Refrigerant containment compliance:EU F-Gas Regulation enforcement tightens supply chains for hydrofluorocarbon-dependent equipment servicing.
- Thermoelectric efficiency ceiling:Peltier systems face fundamental coefficient-of-performance limits above small-capacity niche applications.
Strategic Opportunities
- India's evaporative-to-compressor transition:Rising ambient temperatures and humidity tolerance gaps in legacy evaporative units open upgrade pathways.
- IoT-enabled predictive maintenance:Sensor-embedded coolers allow energy-management-as-a-service bundling with hardware contracts.
- EU Green Deal building renovation wave:Member-state recovery funding channels toward HVAC efficiency improvements in existing commercial stock.
Industry Challenges
- Refrigerant transition engineering:R-32 and R-290 compatibility requires redesign of compressor lubrication systems and safety protocols.
- Power electronics integration:Variable-speed drive firmware development strains in-house embedded systems capabilities at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooler Connected to the Mains Market |
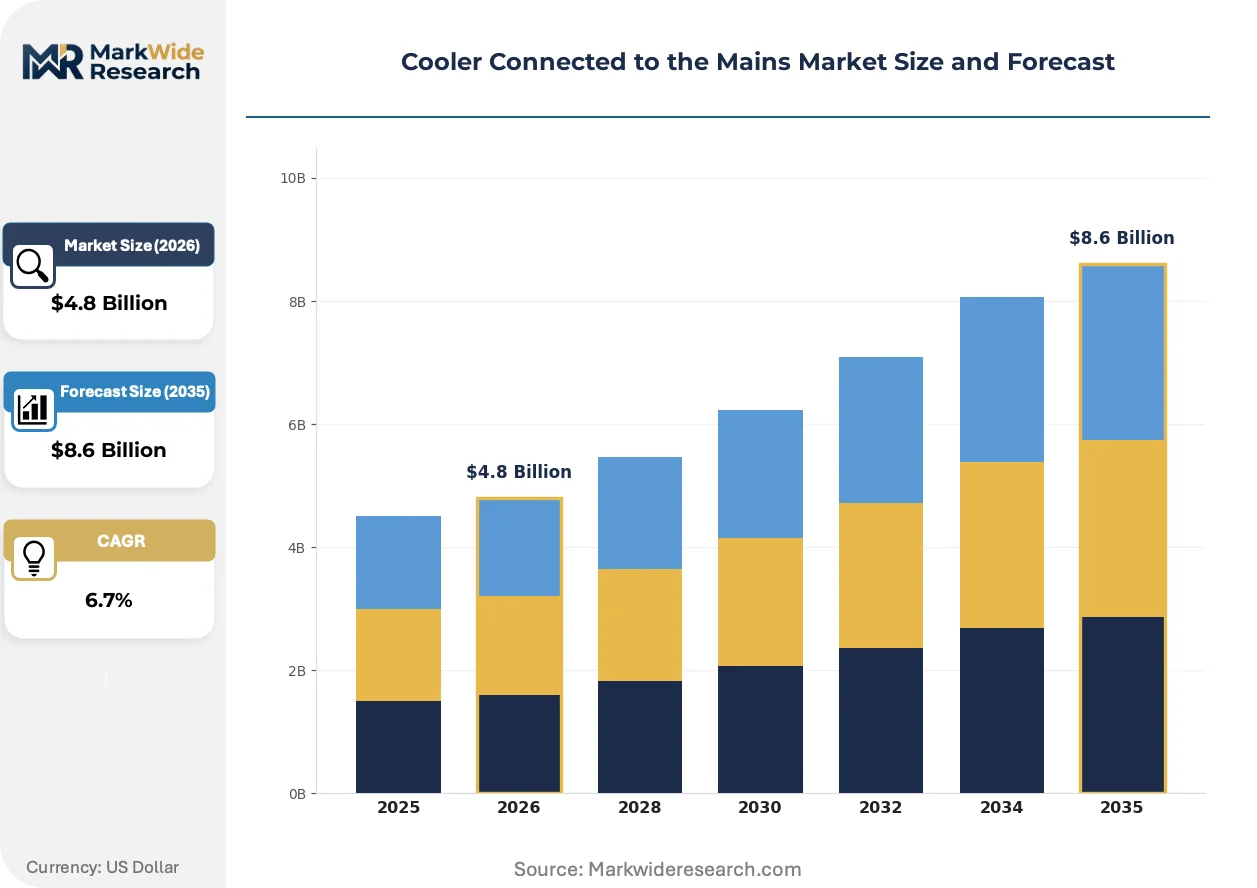
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Coolers, Smart Coolers, Mini Coolers, Large Capacity Coolers Technology: Inverter Technology, Thermoelectric, Compressor-Based, Absorption End User: Residential Users, Commercial Establishments, Hospitality Industry, Food Service Providers Distribution Channel: Online Retailers, Specialty Stores, Home Improvement Chains, Direct Sales |
| Companies Covered | Daikin Industries, Midea Group, Panasonic Corporation, Symphony Limited, Champion Cooler Corporation, Brize GmbH, Seeley International, Sterling Thermal Technology Limited, LANFEST Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooler Connected to the Mains Market Evolving Landscape
Building automation integration is compressing the boundary between cooling hardware and facility software, with specification decisions migrating from mechanical contractors to energy management consultants. This shift elevates data interoperability and API standardization in procurement criteria.
Variable-speed inverter drives are miniaturizing through silicon carbide power module adoption, enabling compact rooftop packaged units without capacity sacrifice. Hospitality chains with centralized procurement functions specify these platforms for portfolio-wide energy benchmarking. The technology is miniaturizing mechanical room footprints in urban hotels where square footage commands premium lease rates.
EU F-Gas Regulation phase-down schedules force refrigerant transition roadmaps across export-oriented manufacturers. Compressor architectures must accommodate lower-global-warming-potential working fluids with revised pressure envelopes and material compatibility. Commercial cold-chain operators in Germany and France face accelerated replacement timelines as service refrigerant stocks contract.
Specification authority is migrating from installation contractors to corporate sustainability officers with portfolio-level energy targets. Procurement committees now weight lifecycle carbon intensity alongside capital expenditure, compressing traditional equipment-margin structures. This pattern concentrates in India's IT park developments and China's LEED-certified commercial construction clusters.
Cooler Connected to the Mains Market Segmentation
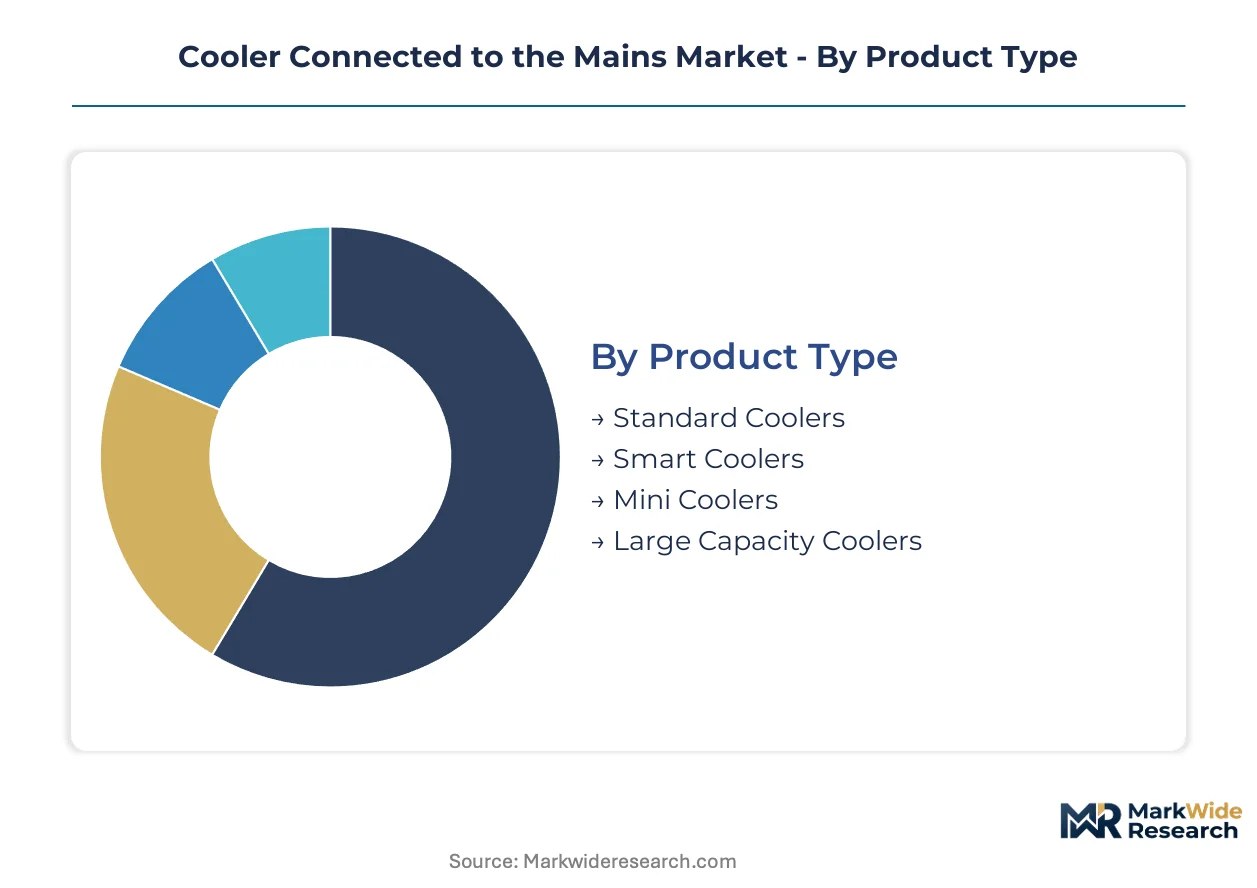
Segmentation in the cooler connected to the mains market reveals how regulatory pressure, efficiency mandates, and procurement authority shifts concentrate margin pools across distinct technology and customer configurations. Understanding these divides exposes where specification power resides and which platforms capture replacement-cycle premiums.
Product Type:
GB standards in China and BIS energy-label mandates in India create divergent compliance burdens across capacity classes, with larger units facing stricter efficiency verification protocols.
- Standard Coolers:Fixed-installation units with mechanical thermostats and single-speed compressors dominate legacy commercial stock. Hospitality procurement in India's Gujarat corridor specifies these for budget property retrofits where capital constraints override operating cost concerns.
- Smart Coolers:IoT-enabled platforms with embedded sensors and cloud-connected energy management command specification authority from corporate sustainability officers. China's LEED-certified commercial clusters in Shanghai and Shenzhen specify these for portfolio-wide benchmarking against dual carbon targets.
- Mini Coolers:Compact 2-4 kW units serve space-constrained urban retail in Mumbai and Delhi NCR.
- Large Capacity Coolers:10-15 kW systems address centralized cooling for hospital and institutional campuses.
Established volume favors Standard Coolers; emerging adoption favors Smart Coolers.
Technology:
Cost tier differentiation separates premium variable-speed platforms from commodity fixed-speed alternatives, with semiconductor integration driving the wedge.
- Inverter Technology:Variable-speed compressor drives modulate cooling output to thermal load, cutting energy consumption through partial-load operation. EU F-Gas Regulation enforcement in Germany and France accelerates replacement demand as facilities face refrigerant servicing constraints.
- Compressor-Based:Fixed-speed vapor-compression systems with on/off cycling sustain the largest installed base. India's commercial corridor expansion in Maharashtra generates sustained specification volume for mid-tier contractors without inverter sourcing relationships.
- Thermoelectric:Peltier-effect cooling faces coefficient-of-performance ceilings above small-capacity niches.
- Absorption:Heat-driven cycles serve waste-heat recovery applications in industrial co-location settings.
Installed base concentration rests with Compressor-Based systems; specification momentum gathers behind Inverter Technology.
End User:
Application-specific duty cycles and procurement authority patterns fragment demand across customer types with diverging technical sophistication.
- Hospitality Industry:Centralized procurement functions at hotel chains specify inverter platforms for portfolio energy benchmarking. China's SAMR efficiency enforcement drives specification upgrades in three-star and above properties across Beijing and Guangzhou.
- Commercial Establishments:Office and retail facilities with facilities management outsourcing favor service-contract bundling. India's IT park developments in Hyderabad and Bangalore weight lifecycle carbon intensity alongside capital expenditure in committee decisions.
- Residential Users:Individual homeowners with limited technical specification authority rely on contractor recommendations.
- Food Service Providers:Cold-chain reliability requirements dominate procurement criteria over efficiency optimization.
Contract bundling concentrates margin in Commercial Establishments; sustainability-linked procurement elevates Hospitality Industry specifications.
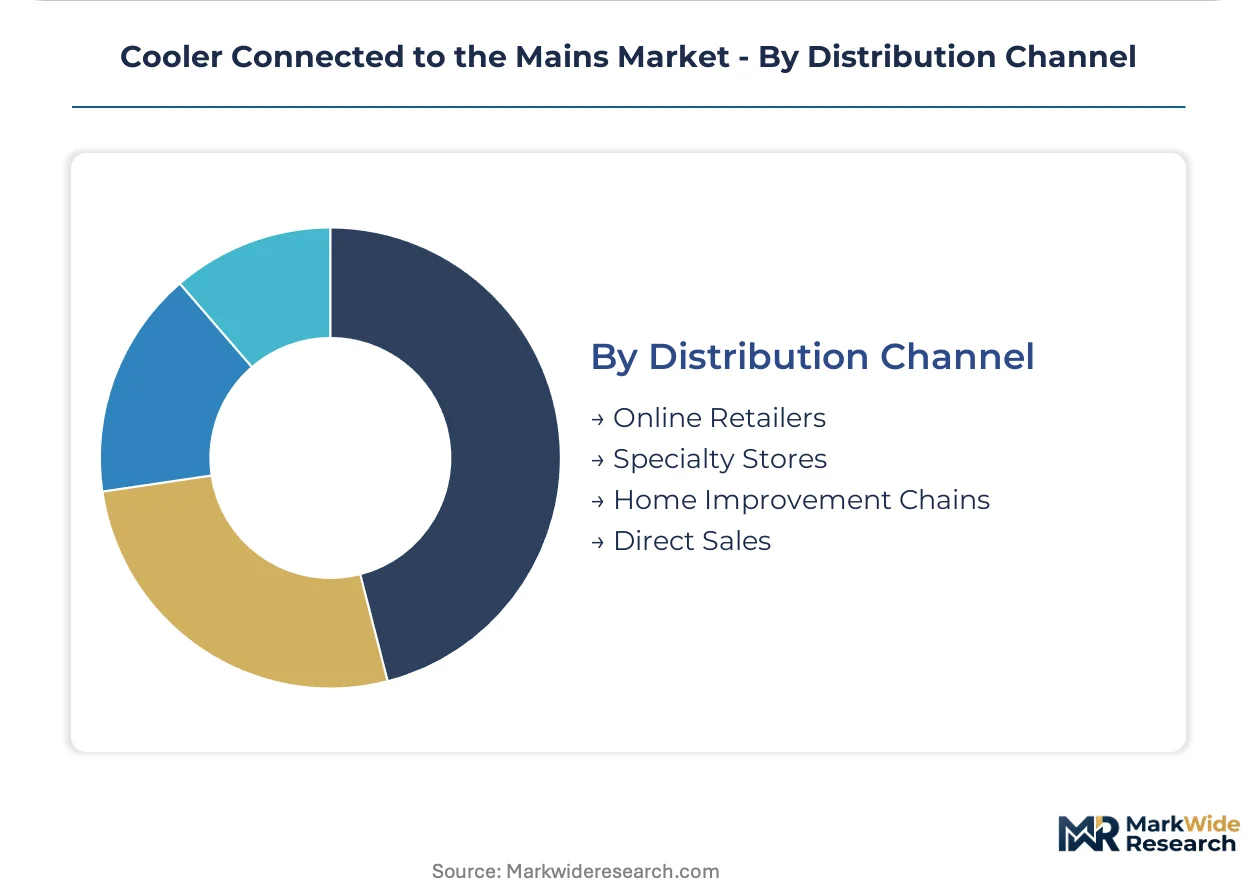
Distribution Channel:
Customer type concentration dictates channel viability, with project-scale sales requiring specification relationships unavailable through transactional retail.
- Direct Sales:Manufacturer-led specification engineering for large-format projects captures premium positioning. EU Green Deal renovation funding channels in France and Italy flow through direct relationships with energy service companies.
- Specialty Stores:HVAC-focused distributors with in-house application engineering serve mid-tier commercial contractors. India's state-level electrical licensing requirements in Tamil Nadu and Karnataka drive contractor loyalty to established supply relationships.
- Online Retailers:Transactional volume concentrates in standardized small-capacity units.
- Home Improvement Chains:Big-box retail captures residential replacement demand with limited customization.
Project complexity favors Direct Sales; standardized replacement volume flows through Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and French specification channels where EU F-Gas Regulation enforcement tightens refrigerant servicing, while Indian volume markets compress margins through contractor-driven procurement. China's dual carbon targets reshape building energy retrofits across hospitality and healthcare infrastructure. India's commercial corridor expansion sustains fixed-installation cooling demand in retail and institutional construction clusters.
China
SAMR enforces GB standards on cooling efficiency and refrigerant containment, accelerating specification upgrades to variable-speed systems. Shanghai and Shenzhen LEED-certified commercial clusters specify smart coolers for portfolio-wide energy benchmarking against national emissions targets. The Yangtze River Delta manufacturing base supplies inverter drive modules to domestic retrofit programs.
Germany
EU F-Gas Regulation phase-down schedules force accelerated replacement timelines as hydrofluorocarbon service stocks contract. Commercial cold-chain operators in Berlin and Munich face procurement pressure from corporate sustainability officers with portfolio-level carbon intensity targets. The country's building renovation wave channels recovery funding toward HVAC efficiency improvements.
India
BIS mandates energy-label compliance for commercial cooling equipment across Maharashtra and Gujarat corridor developments. IT park developments in Hyderabad and Bangalore weight lifecycle carbon intensity alongside capital expenditure in committee procurement decisions. Symphony Limited anchors localized R&D in Gujarat to capture evaporative-to-compressor transition demand.
United States
EPA refrigerant management regulations under the AIM Act drive transition planning for hydrofluorocarbon phase-down in commercial building stock. Hospitality chains with centralized procurement functions specify inverter platforms for portfolio-wide energy benchmarking. The Southeast construction corridor sustains demand for large-capacity institutional cooling systems.
France
EU Green Deal building renovation funding channels through energy service companies with direct manufacturer relationships. Corporate sustainability officers in Paris and Lyon commercial clusters elevate lifecycle carbon intensity in procurement criteria above capital expenditure considerations. The country's cold-chain operators face compressed replacement cycles from refrigerant containment enforcement.
Cooler Connected to the Mains Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with semiconductor-integrated inverter specialists commanding specification premiums while automated volume manufacturers anchor mid-tier contractor channels. The market structures around three tiers: captive-component integrated players, scale-driven sheet-metal fabricators, and regional evaporative-transition specialists. Consolidation pressure concentrates among mid-tier manufacturers lacking variable-speed drive firmware capabilities. Competitive moves center on backward integration into power electronics and strategic partnerships for refrigerant-transition engineering.
Among Japanese and German integrated manufacturers, Daikin Industries and Panasonic Corporation occupy positions defined by captive semiconductor sourcing relationships. Within the India-focused regional tier, Symphony Limited exemplifies the evaporative-to-compressor transition archetype through localized R&D infrastructure. Chinese volume manufacturers including Midea Group anchor cost-competitive positioning through automated production scale in the Pearl River Delta manufacturing cluster.
| Leading Market Players |
|---|
| Daikin Industries |
| Midea Group |
| Panasonic Corporation |
| Symphony Limited |
| Champion Cooler Corporation |
| Brize GmbH |
| Seeley International |
| Sterling Thermal Technology Limited |
| LANFEST Corporation |
| Others |
Value Network & Pricing Analysis
Automated sheet-metal stamping scale in Foshan and the Yangtze River Delta compresses unit production costs while simultaneously anchoring supply concentration in China's Pearl River Delta manufacturing cluster. This geographic clustering enables inverter drive module sourcing integration that shapes both floor prices for mid-tier contractors and premium positioning for specification-engineered projects.
Pricing Analysis
Configured-to-order pricing for smart coolers with IoT-enabled energy management commands spreads of 40-60 percent above standard fixed-speed mechanical thermostat units. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by GB efficiency certification grade and after-sales service bundling. Cost compression in standard compressor-based segments is intensifying because India's contractor-driven procurement channels prioritize capital expenditure minimization over lifecycle operating costs. Budget property retrofits in Gujarat's hospitality corridor exhibit highest price sensitivity, while LEED-certified commercial clusters in Shanghai demonstrate lowest sensitivity due to sustainability-linked procurement mandates.
Supply Chain Analysis
Rare-earth element processing for permanent-magnet inverter motors creates a chokepoint where Chinese domestic quota administration shapes global motor cost curves. Manufacturing draws from China for drive module assembly, India for evaporative-to-compressor transition units, and Germany for EU F-Gas Regulation-compliant compressor architectures. Copper winding materials, silicon carbide power semiconductors, and hydrofluorocarbon refrigerant alternatives constitute critical input dependencies. Single-source vulnerability concentrates in semiconductor power module fabrication. Distribution runs through direct manufacturer relationships for large-format projects and specialty HVAC distributors for mid-tier commercial contractor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Inverter compressor displacement of fixed-speed systems constitutes a high-growth disruption accelerated by China's dual carbon goals and EU F-Gas Regulation phase-down enforcement. These regulatory inflections compress replacement cycles while simultaneously forcing refrigerant transition engineering investments.
For Market Incumbents: Shield installed base relationships through captive semiconductor sourcing for variable-speed drive modules and backward integration into power electronics firmware development. Compressor-based legacy manufacturers face asymmetric capability gaps against inverter specialists with in-house embedded systems teams. Channel control through direct specification engineering relationships with energy service companies anchors premium positioning in EU Green Deal renovation funding flows. For New Entrants and Emerging Players: Differentiate on IoT-enabled predictive maintenance platforms bundled with hardware contracts. India's evaporative-to-compressor transition in Gujarat and Maharashtra corridor developments represents the most penetrable geography, with localized R&D infrastructure as the critical go-to-market angle. Symphony Limited's Gujarat-based development centers exemplify this archetype for replication. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with captive inverter drive module sourcing and refrigerant-transition engineering roadmaps. Five-to-ten year viability hinges on semiconductor integration depth and GB standards compliance certification. Acquisition targets should demonstrate variable-speed firmware capabilities and established specification authority with corporate sustainability officers. Watch inverter adoption rates in China's three-star and above hospitality properties as the inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Power Electronics | Captive semiconductor sourcing for variable-speed drive modules compresses cost curves against merchant-dependent competitors. |
| Refrigerant Transition Engineering Partnership | R-32 and R-290 compatibility investments align with EU F-Gas Regulation phase-down timelines in Germany and France. |
| Localized R&D Infrastructure Deployment | Gujarat-based development centers capture India's evaporative-to-compressor transition demand with humidity-tolerance optimization. |
| IoT Platform Integration | Cloud-connected energy management enables service-contract bundling with corporate sustainability officer specification authority. |
| LEED Certification Alignment | Portfolio-wide benchmarking integration targets Shanghai and Shenzhen commercial cluster procurement committees. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with facilities management directors, HVAC contractor procurement leads, corporate sustainability officers, energy service company specification engineers, and inverter drive module semiconductor sourcing managers. Secondary validation drew from SAMR GB standard filings, BIS energy-label compliance registries, EU F-Gas Regulation enforcement disclosures, SEC manufacturer filings, and customs trade data for compressor component flows. Bottom-up unit shipment modeling and top-down market value reconciliation ensured triangulation integrity.
Across the analysis window, projections integrated technology adoption curves for inverter displacement of fixed-speed systems, refrigerant transition timelines, and building retrofit funding cycle phasing. Segmentation dimensions spanned product type, technology platform, end-user procurement authority pattern, and distribution channel structure. CAGRs derived from logistic diffusion modeling of efficiency regulation compliance thresholds and replacement cycle compression rates. Industry-specific inputs included copper and rare-earth price volatility scenarios, semiconductor cost curve trajectories, and hospitality sector capital expenditure cycles.
Material uncertainties — commodity input swings, regulatory enforcement intensity variations, and refrigerant transition engineering delays — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding GB standards reciprocity and BIS energy-label compliance expansion timelines. Practitioners should keep alternative scenarios live as EU F-Gas Regulation phase-down schedules and China's dual carbon target enforcement mechanisms evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Global Massage Chairs Market
Appliances
Kuwait Microwave Ovens Market
Appliances
Consumer Appliances Market
Appliances
Under Counter Dishwasher Market
Appliances
Personal Care Appliances Market
Appliances
Portable Fridges Market
Appliances
United Kingdom Tumble Dryers Market
Appliances
Israel Laundry Appliances Market
Appliances
Mexico Laundry Appliances Market
Appliances
Electric Fan Market
Appliances
UAE Microwave Ovens Market
Appliances
Oman Dishwashers Market
Appliances
Smart Dishwasher Market
Appliances
Garments Steamer Market
Appliances
Gas Ranges Market
Appliances
Electric Iron Market