
 Shared Shoe Washing Machine Market | 2026-2036
Shared Shoe Washing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Shared Shoe Washing Machine Market Insights
The gap between premium and commodity tiers is shifting from motor durability alone to encompass IoT payment integration, antimicrobial drum coatings, and remote diagnostics capability. Haier leverages its smart-home ecosystem to bundle shared shoe washers with building management platforms in Chinese residential towers. Midea sustains cost leadership through captive compressor manufacturing and high-volume production lines serving Southeast Asian laundromat chains. Samsung Electronics differentiates via app-based usage analytics that help operators optimize pricing and maintenance schedules.
A shared shoe washing machine is a commercial-grade appliance engineered to clean multiple pairs of footwear per cycle, typically employing 40-60 liter stainless-steel drums, 800-1200 RPM spin speeds, and dedicated brush arrays to protect sole adhesives and upper materials. The primary commercial purpose is to deliver hygienic, standardized cleaning in high-traffic settings where individual ownership proves impractical. Commercial Units dominate current installed base due to their 15-30 kg daily throughput and coin-or-app payment readiness, while Ultrasonic Cleaning technology captures expanding margin pools as operators seek gentler processing for premium leather and knit uppers. The Home Appliance segment remains nascent but accelerates in Japanese and South Korean micro-apartments where floor space constraints eliminate conventional alternatives.
China's MIIT enforces GB standards on water and energy consumption for commercial cleaning equipment, compelling manufacturers to redesign heating elements and recirculation pumps. South Korea's MFDS and KTL certification bodies regulate antimicrobial claims and electrical safety for machines deployed in public athletic facilities, shaping product development priorities for ozone and steam-based sanitization modules. Japan's METI Top Runner program pushes efficiency benchmarks upward, favoring inverter-motor designs that reduce operating costs for laundromat owners. Stakeholders must weigh whether to prioritize regulatory compliance breadth across Northeast Asian markets or concentrate resources on single-country certification depth.
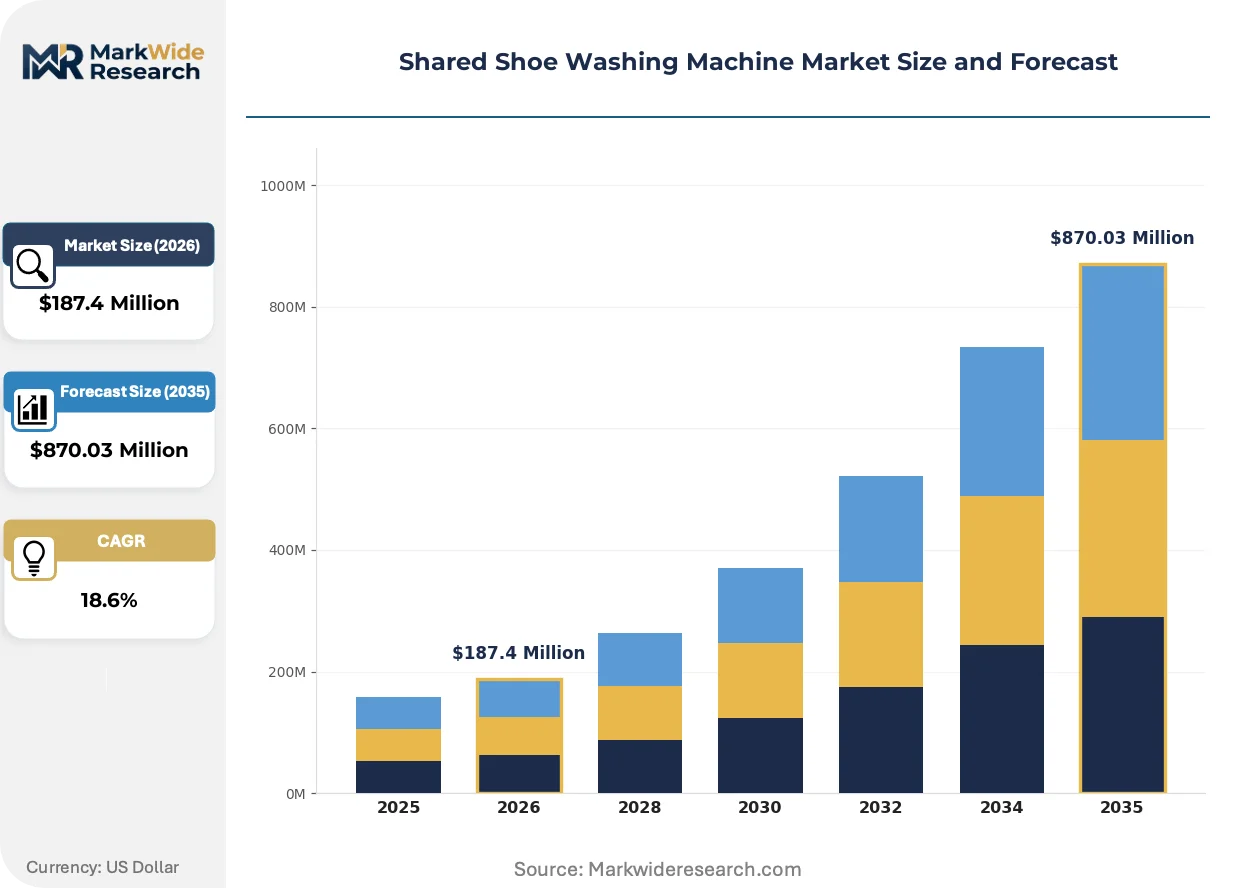
Market Dynamics
China's MIIT energy-efficiency mandates are compressing margins for conventional heating-element designs while redirecting R&D budgets toward ultrasonic and inverter-motor architectures. This regulatory pressure is the dominant structural force reshaping competitive positioning across the shared shoe washing machine supply base.
Growth Catalysts
- MFDS antimicrobial certification:South Korea's mandatory ozone-sanitization standards for public athletic facilities are accelerating deployment of premium machines in Seoul's basement laundry clusters.
- Sneaker culture density:Tokyo and Osaka micro-apartments generate concentrated demand for space-efficient cleaning appliances where individual ownership is physically impossible.
- Ultrasonic transducer advances:Gentler processing of knit uppers and leather soles is expanding addressable volume into premium footwear categories previously excluded from commercial cleaning.
Market Restraints
- Stainless-steel drum cost volatility:Raw material price swings for 304-grade steel constrain margin predictability for mid-tier manufacturers serving Southeast Asian laundromat chains.
- Compressor supply concentration:Captive production of rotary compressors by major appliance conglomerates limits independent OEM access to cost-competitive refrigeration-cycle components.
- Water recirculation pump durability:Technical limitations in sealing technology for high-turbidity footwear debris accelerate maintenance frequency and erode operator unit economics.
Strategic Opportunities
- Japanese single-person households:Underpenetrated deployment in 20-30 square meter Tokyo apartments represents white-space demand for compact home-appliance format machines.
- IoT-payment convergence:Integration of brush-array diagnostics with building management platforms creates new revenue streams from predictive maintenance subscriptions.
- Thailand condominium boom:Bangkok's vertical residential construction pipeline offers channel innovation through developer-preinstall partnerships bypassing traditional retail distribution.
Industry Challenges
- Antimicrobial coating application consistency:Drum surface treatment certification failures at KTL testing labs delay South Korean market entry by 4-6 months for new product launches.
- Legacy coin-op payment retrofit:Mechanical cash-box infrastructure in aging Japanese laundromats complicates app-based payment integration without full machine replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shared Shoe Washing Machine Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Commercial Units, Home Appliance, Portable Machines, Multi-User Models End User: Shoe Retailers, Laundromats, Households, Athletic Clubs Technology: Ultrasonic Cleaning, Steam Cleaning, Eco-Wash, Ozone Treatment Installation: Floor Mounted, Wall Mounted, Mobile Units, Built-in Options |
| Companies Covered | Haier, Midea, Hangzhou Xiaohan Technology Co., Ltd., Samsung Electronics, LG Electronics, Shenzhen Huagong Technology Co., Ltd., Audley, Whirlpool, Xingbang Shares, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shared Shoe Washing Machine Market Trends and Innovations
Hardware-software bundling is displacing standalone equipment sales across East Asian urban markets. Operators now prioritize connected machines that generate usage data over basic durability specifications.
Inverter-motor technology is consolidating control over energy consumption outcomes in commercial settings. Chinese residential tower operators are adopting these drives to preempt MIIT penalty exposure. The technology is consolidating supplier power among motor-controller specialists with firmware calibration expertise.
Japan's METI Top Runner efficiency benchmarks are tightening allowable power-draw thresholds for commercial cleaning equipment. Manufacturers must redesign heating elements or face exclusion from preferential procurement lists. Laundromat owners in Osaka and Nagoya are responding by accelerating replacement cycles for pre-2020 installed base machines.
Building management platform integration is reshaping how operators select equipment vendors. Property developers in Seoul and Shanghai now specify API-compatible machines that feed centralized facility dashboards. This specification pattern is most visible in newly constructed South Korean apartment complexes where basement laundry revenue is pooled under single ownership entities.
Shared Shoe Washing Machine Market Segmentation
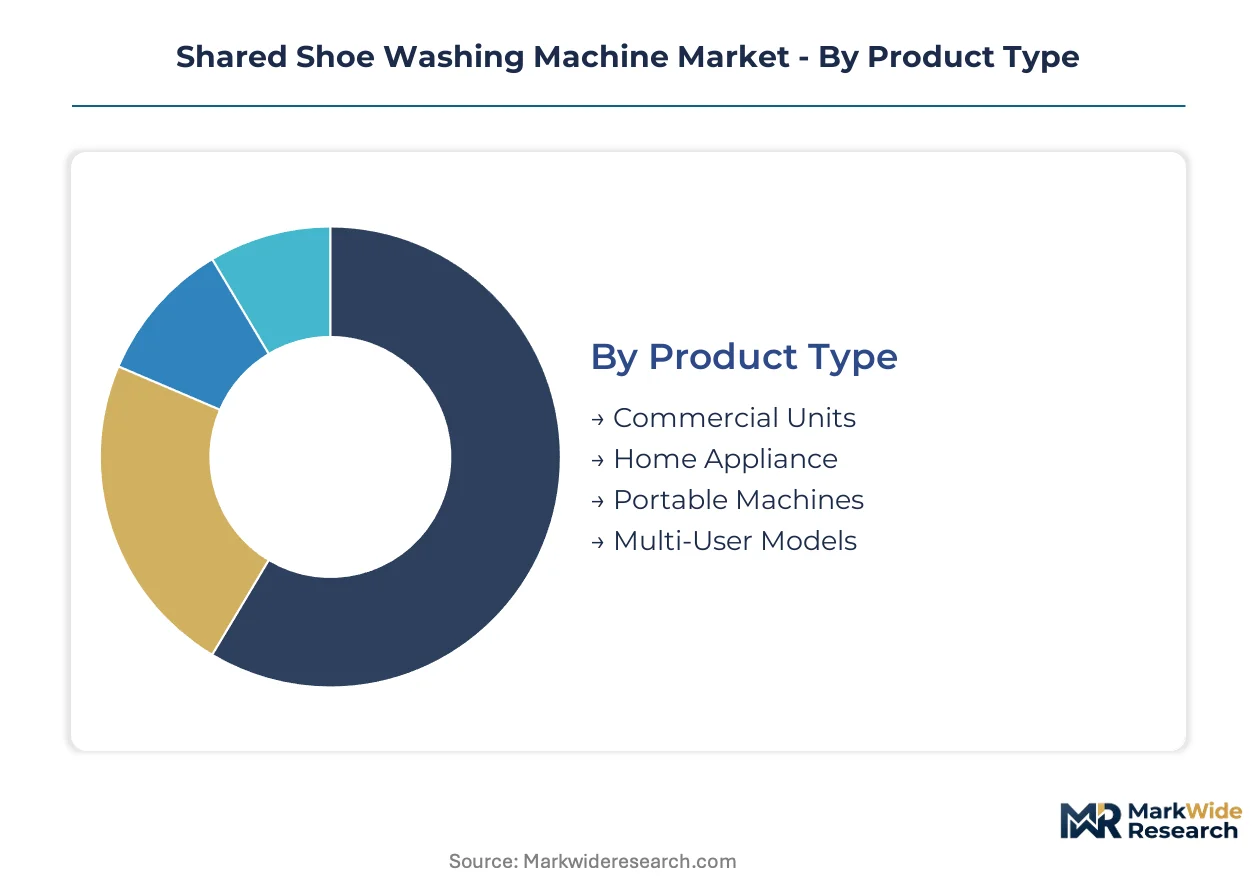
Segmentation in the shared shoe washing machine market reveals divergent engineering requirements between high-throughput commercial installations and space-constrained residential deployments. Each category carries distinct margin profiles, certification burdens, and integration complexity that reshape vendor priorities.
Product Type:
Standalone machines dominate embedded building management systems, while portable formats serve transient use cases without infrastructure dependencies.
- Commercial Units:These machines employ 40-60 liter stainless-steel drums and 800-1200 RPM spin speeds with dedicated brush arrays. Demand concentrates in Seoul basement laundry clusters and Shanghai residential tower basements where MIIT efficiency mandates drive replacement cycles.
- Home Appliance:Compact formats engineered for 20-30 square meter Tokyo and Osaka micro-apartments sacrifice throughput for footprint reduction. Japanese single-person households generate concentrated demand where individual ownership is physically impossible.
- Portable Machines:Battery-powered or manual-fill units target athletic clubs and temporary retail pop-ups lacking plumbed infrastructure.
- Multi-User Models:Coin-or-app payment readiness serves Southeast Asian laundromat chains with high daily throughput requirements.
Commercial Units lead volumes today; Home Appliance is gaining share fastest.
End User:
Cost tier differentiation separates premium service providers from commodity volume operators across the customer base.
- Shoe Retailers:In-store cleaning services leverage ultrasonic transducer technology for premium leather and knit upper processing. Seoul's sneaker boutiques and Tokyo streetwear retailers deploy these units as customer retention tools.
- Laundromats:Coin-op and app-payment infrastructure dominates this channel, with Bangkok vertical residential towers emerging as developer-preinstall partnership opportunities.
- Households:Japanese METI Top Runner efficiency benchmarks shape procurement for inverter-motor designs in single-person dwellings.
- Athletic Clubs:South Korea's MFDS ozone-sanitization standards mandate antimicrobial drum coatings for public facility deployment.
Laundromats anchor current installed base; Shoe Retailers show steepest expansion trajectory.
Technology:
Margin concentration follows gentler processing capabilities that expand addressable volume into premium footwear categories.
- Ultrasonic Cleaning:High-frequency transducer arrays eliminate mechanical agitation for delicate sole adhesives. China's MIIT R&D investment redirects toward these low-power architectures as conventional heating-element margins compress.
- Steam Cleaning:High-temperature sanitization modules meet Japanese and South Korean antimicrobial certification requirements for public athletic facilities.
- Eco-Wash:Water recirculation pump designs target MEE efficiency benchmarks in Chinese residential developments.
- Ozone Treatment:Chemical-free sanitization captures premium positioning in Seoul basement clusters under MFDS regulatory pressure.
Steam Cleaning leads commercial penetration; Ultrasonic Cleaning climbs the fastest as premium footwear volumes expand.
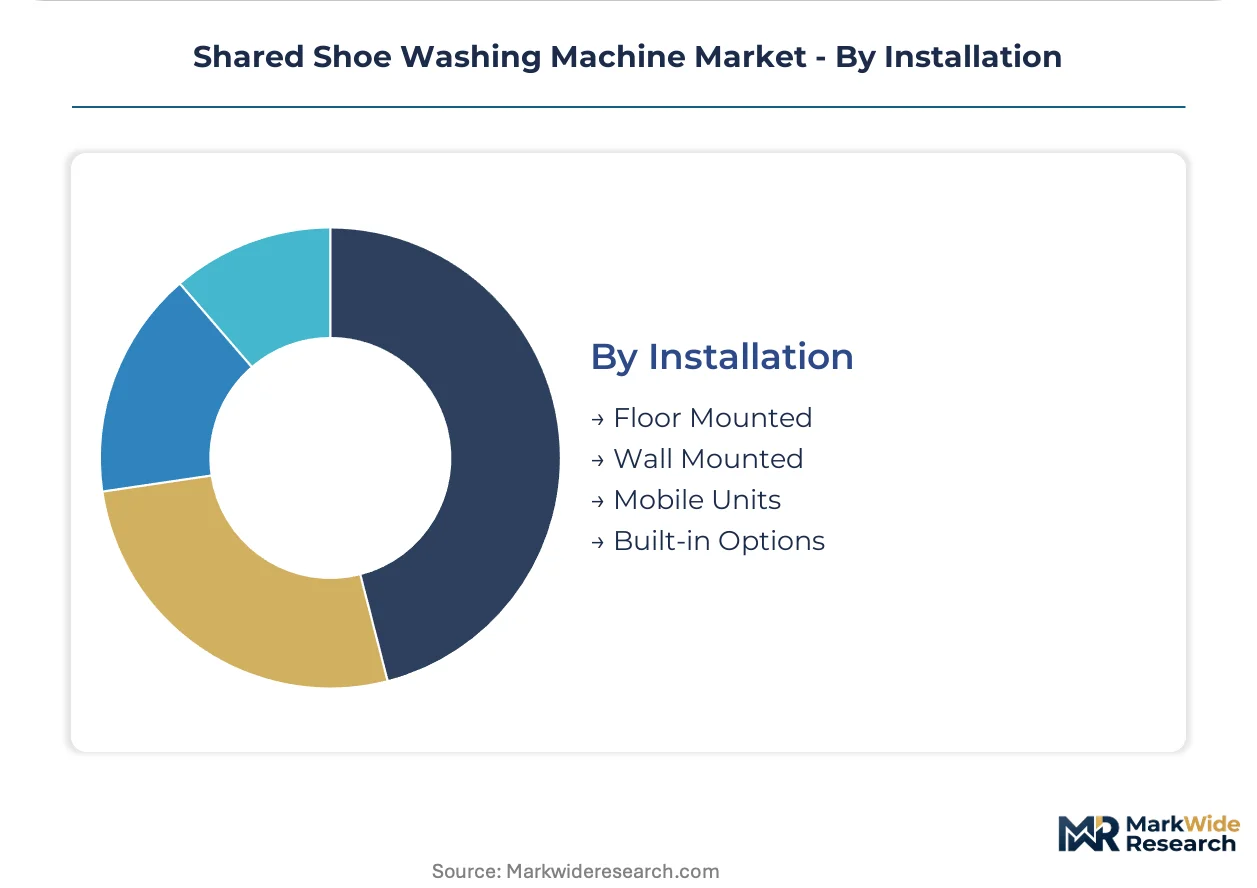
Installation:
Supply concentration in motor-controller firmware creates integration barriers for formats requiring API-compatible building management platforms.
- Floor Mounted:Standard 15-30 kg daily throughput configurations serve legacy laundromat infrastructure across East Asian urban markets.
- Wall Mounted:Vertical orientation recovers floor space in Tokyo micro-apartments and Seoul basement clusters with pooled ownership entities.
- Mobile Units:Castor-mounted designs enable seasonal repositioning for retail storefronts and pop-up athletic events.
- Built-in Options:Developer-specified API-compatible machines feed centralized facility dashboards in newly constructed Shanghai and Seoul residential towers.
Floor Mounted retains largest installed base; Built-in Options show strongest growth as property developers consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Seoul, Shanghai, and Tokyo anchor shared shoe washing machine deployment density. These metropolitan manufacturing and R&D hubs concentrate both appliance conglomerates and component specialists.
China
University dormitories and residential tower basements in Shanghai and Beijing generate concentrated machine placement. MIIT energy-efficiency labeling requirements for commercial laundry equipment compel manufacturers toward ultrasonic and inverter-motor architectures. Yangtze River Delta suppliers dominate stainless-steel drum fabrication for regional laundromat chains.
South Korea
Dense urban apartment layouts and sneaker culture drive basement laundry cluster expansion in Seoul. MFDS ozone-sanitization standards for public athletic facilities mandate antimicrobial drum coatings. Busan-Ulsan manufacturing corridors supply rotary compressors to domestic appliance assemblers.
Japan
Single-person households in 20-30 square meter Tokyo and Osaka micro-apartments create white-space demand for compact home-appliance formats. METI Top Runner efficiency benchmarks favor inverter-motor designs that reduce laundromat operating costs. Kansai region suppliers specialize in firmware-calibrated motor controllers.
Thailand
Bangkok's vertical residential construction pipeline offers developer-preinstall partnership opportunities bypassing traditional retail distribution. Central bank facility financing supports condominium amenity upgrades including shared cleaning infrastructure. Eastern Economic Corridor industrial zones host component assembly for Southeast Asian laundromat chains.
United States
Collegiate athletic facilities and urban co-living developments in California and Texas pilot shared shoe cleaning services. EPA water-efficiency guidelines for commercial cleaning equipment shape procurement specifications for campus sustainability officers. Pacific Northwest technology clusters incubate IoT-payment integration startups serving building management platforms.
Shared Shoe Washing Machine Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the shared shoe washing machine supply base. Appliance conglomerates with captive compressor manufacturing anchor the consolidated tier, while specialized OEMs occupy fragmented mid-market segments. Three archetypes dominate: vertically integrated home-appliance giants, component-specialist contract manufacturers, and IoT-platform integrators. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure motor-controller firmware expertise and building management API compatibility.
Among Chinese fabricators, Haier and Midea occupy positions reflecting divergent strategic postures. Haier exemplifies the ecosystem-integrated archetype through smart-home platform bundling with residential tower operators. Midea represents scale-driven cost leadership via captive supply chain control and high-volume production line deployment. Samsung Electronics anchors the premium-tier vector among Korean conglomerates, with app-based usage analytics capabilities distinguishing its market position.
| Leading Market Players |
|---|
| Haier |
| Midea |
| Hangzhou Xiaohan Technology Co., Ltd. |
| Samsung Electronics |
| LG Electronics |
| Shenzhen Huagong Technology Co., Ltd. |
| Audley |
| Whirlpool |
| Xingbang Shares |
| Others |
Pricing and Supply Chain Analysis
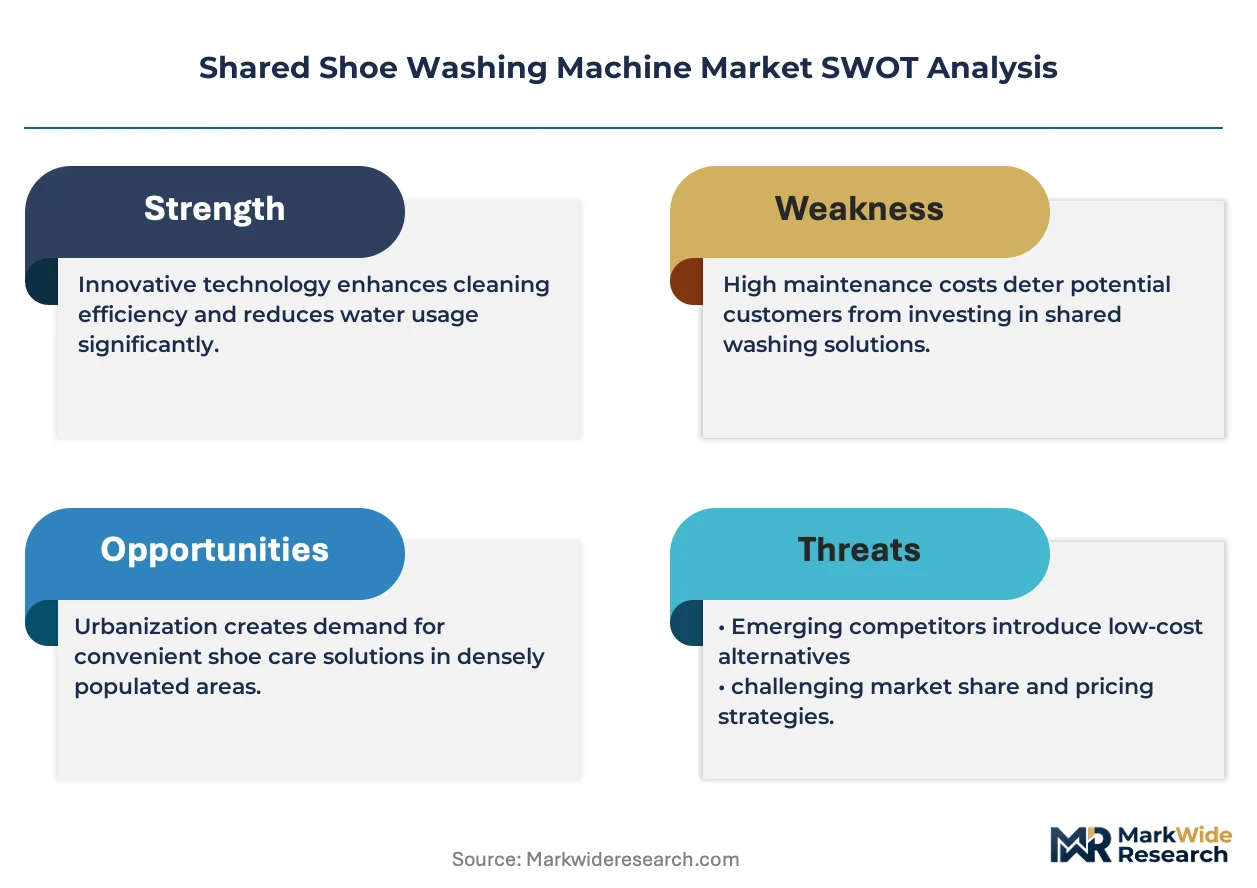
Captive compressor manufacturing by Chinese appliance conglomerates anchors both supply security and pricing power across the shared shoe washing machine value chain. Midea's in-house rotary compressor production insulates margin structures from component volatility while compressing procurement costs for Southeast Asian laundromat chains. This backward integration pattern forces independent OEMs toward ultrasonic transducer specialization or IoT-platform differentiation to escape commodity pricing traps.
Pricing Analysis
Hardware-software bundling splits the market between standalone equipment sales and subscription-based predictive maintenance services. Three-tier pricing structure across premium, standard, and economy levels separates API-integrated building management machines from basic coin-op units and portable manual-fill formats. Price differentiation hinges on MFDS antimicrobial certification tier and IoT diagnostic capability. Cost compression in mid-tier conventional heating-element designs is intensifying because MIIT efficiency mandates erode margins on legacy architectures. Laundromat chains in Bangkok and Jakarta exhibit highest price sensitivity, while Seoul basement cluster operators prioritize ozone-sanitization certification over unit cost.
Supply Chain Analysis
Workforce availability constraints in the Yangtze River Delta and Busan-Ulsan corridors concentrate stainless-steel drum fabrication and rotary compressor assembly. Manufacturing feeds from 304-grade steel sheet, high-frequency ultrasonic transducer arrays, and firmware-calibrated motor controllers. Single-source vulnerability in inverter-motor controller ICs creates procurement risk for mid-tier assemblers lacking direct foundry relationships. Distribution runs through developer-preinstall partnerships in Shanghai and Seoul residential towers, bypassing traditional appliance retail channels for built-in format machines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Chinese MIIT efficiency mandates compress margins faster than South Korean MFDS certification premiums expand them, rewarding dual-registered suppliers with regulatory optionality.
For Market Incumbents: To counter ultrasonic transducer commoditization by Yangtze River Delta component specialists, Haier and Midea should deepen API-compatible building management platform integration while accelerating KTL antimicrobial coating certification for South Korean market access. Capacity addition in Thailand's Eastern Economic Corridor secures Southeast Asian laundromat chain relationships before developer-preinstall partnerships consolidate procurement.
For New Entrants and Emerging Players: Capture white-space demand in Tokyo's 20-30 square meter single-person households where compact home-appliance formats remain underpenetrated. Bangkok's vertical residential construction pipeline offers the most penetrable geography through direct developer partnerships bypassing established retail distribution. Lead with inverter-motor energy efficiency credentials aligned with Japan's METI Top Runner benchmarks.
For Investors and Strategic Acquirers: Consolidation pressure builds where firmware-calibrated motor controller expertise concentrates among Kansai region specialists and Yangtze River Delta suppliers. Long-term viability favors acquisition targets with dual MIIT-MFDS certification capability and existing API integration with Seoul or Shanghai building management platforms. Watch ultrasonic transducer cost curves as the inflection signal for premium tier margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| API-Compatible Platform Integration | Enables centralized facility dashboard feeds for Seoul basement laundry clusters. |
| Dual Certification Investment | Secures MIIT efficiency and MFDS antimicrobial compliance for cross-border deployment. |
| Inverter-Motor Capacity Expansion | Preempts METI Top Runner exclusion risk for Osaka and Nagoya laundromat replacement cycles. |
| Developer-Preinstall Partnership | Bypasses retail distribution fragmentation in Bangkok's condominium construction pipeline. |
| Ultrasonic Transducer R&D | Captures premium footwear cleaning demand from Seoul sneaker boutiques and Tokyo streetwear retailers. |
Research Methodology
Direct dialogue with laundromat operators, residential tower facility managers, appliance procurement directors, and component manufacturing engineers grounded the qualitative foundation. Secondary validation drew from MIIT GB standard filings, MFDS certification registries, METI Top Runner efficiency benchmarks, and customs trade data for stainless-steel drum and compressor imports. Bottom-up machine placement counts across Seoul basement clusters and Shanghai residential towers were triangulated against top-down manufacturer shipment estimates.
Segment-level projections across commercial unit, home appliance, and portable formats were generated through the analytical framework. Technology splits modeled ultrasonic cleaning, steam sanitization, and ozone treatment adoption curves against regulatory compliance thresholds. End-user segmentation captured laundromat, shoe retailer, household, and athletic club demand patterns. CAGRs were derived from installed base replacement cycles and new construction penetration rates, with inputs from Yangtze River Delta supplier capacity announcements and Bangkok condominium pipeline data.
Raw material price volatility for 304-grade steel, KTL antimicrobial coating certification delays, and water recirculation pump durability failures are the dominant revision risks. Forecasts reflect assumptions about MIIT enforcement intensity and MFDS ozone-sanitization mandate expansion. Material deviation in stainless-steel cost trajectories or certification timeline slippage warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
GCC Dishwashers Market
Appliances
Refrigerator Repair Service Market
Appliances
Middle East Water Heater Market
Appliances
North America Tumble Dryers Market
Appliances
Induction Cooktops Market
Appliances
Residential Vacuum Cleaners Market
Appliances
Small Appliances Market
Appliances
Europe Tumble Dryers Market
Appliances
Germany Consumer Appliances Market
Appliances
Germany Compact Dishwasher Market
Appliances
Saudi Arabia Dishwasher Market
Appliances
Saudi Arabia Electric Water Heater Market
Appliances
Mini Washing Machine Market
Appliances
Gas Ranges Market
Appliances
Smart Refrigerator Market
Appliances
Built-In Large Cooking Appliance Market