
 North America Tumble Dryers Market | 2026-2036
North America Tumble Dryers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Tumble Dryers Market Insights
The capital-intensity divergence between heat pump specialists and conventional vented manufacturers is bifurcating competitive dynamics in the North America Tumble Dryers Market. Whirlpool leverages its captive component manufacturing to sustain margin pressure across mid-tier residential channels. LG anchors its position through vertical control over inverter compressor supply, while Electrolux specializes in compact systems targeting urban multi-family installations.
A tumble dryer is a forced-air drying appliance that removes moisture from textiles through heated air circulation, with heat pump variants achieving coefficient of performance ratings above three by recapturing exhaust thermal energy for reuse. The technology serves residential households, commercial laundromats, industrial linen processors, and hospitality operators requiring rapid fabric turnaround. Front load configurations command premium positioning due to stacking compatibility and space efficiency in dense housing markets, while heat pump technology captures expanding share as utility rebate programs intensify. The commercial end user segment offers concentrated margin pools, though residential volume dominates absolute unit flows across the region.
The United States Department of Energy sets minimum efficiency standards under appliance conservation regulations, while EPA ENERGY STAR certification creates tiered market access thresholds that manufacturers must clear for retail placement. Canada enforces parallel requirements through Natural Resources Canada and provincial utility rebate administrators, compressing demand toward certified heat pump and condenser models. Stakeholders must monitor pending federal efficiency rulemakings and provincial incentive program renewals to calibrate product portfolio timing and channel inventory commitments.
Market Dynamics
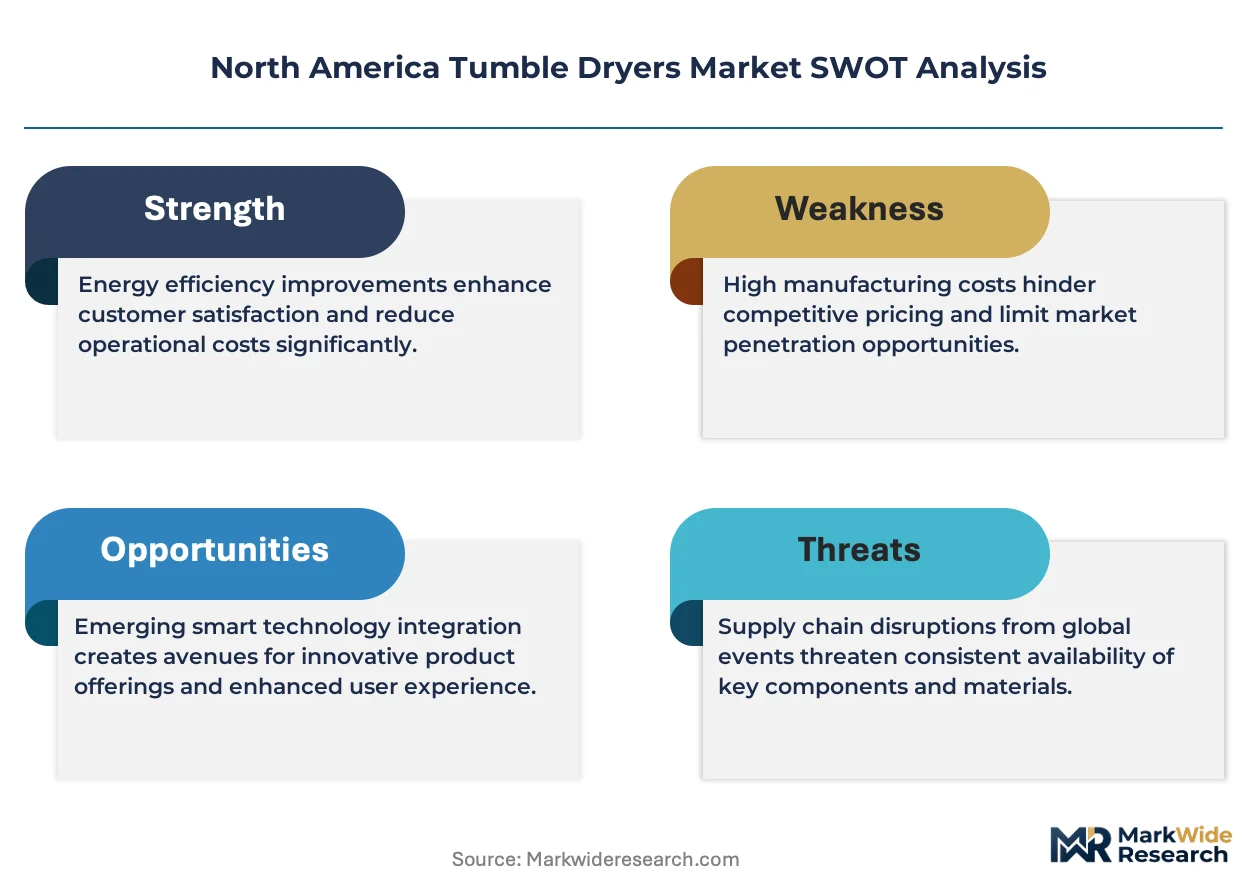
Heat pump technology transitions are restructuring competitive positioning in the North America Tumble Dryers Market as ENERGY STAR certification thresholds compress demand toward high-efficiency architectures and away from conventional vented systems.
Growth Catalysts
- EPA ENERGY STAR Rebate Programs:Utility administrators across the United States are expanding point-of-sale incentives for certified heat pump dryers, accelerating replacement cycles in residential channels.
- Multi-Family Housing Pipeline:Developers in Texas, Florida, and Georgia are mandating in-unit laundry installations in new construction, concentrating demand for compact ventless configurations.
- Refrigerant Circuit Optimization:Advances in inverter-driven compressor modulation are extending heat pump operational temperature ranges, improving drying performance in northern climates.
Market Restraints
- Copper and Steel Input Volatility:Heat exchanger manufacturing depends on commodity metals whose price swings compress margin predictability for component suppliers.
- Korean Compressor Supply Concentration:Inverter compressor sourcing clusters among a limited supplier base in South Korea, creating geographic concentration risk for North American assembly operations.
- Installation Infrastructure Gap:Conventional 240V vented dryer hookups dominate existing housing stock, creating technical friction for heat pump retrofits requiring drainage and electrical reconfiguration.
Strategic Opportunities
- Canadian Provincial Incentive Expansion:Natural Resources Canada and provincial administrators in Ontario and British Columbia are extending rebate programs for high-efficiency appliance replacements, opening underpenetrated replacement demand.
- Commercial Hospitality Retrofit Cycles:Hotel operators in the southeastern United States are unbundling linen processing from third-party contracts, creating direct procurement opportunities for on-premise heat pump installations.
- Smart Grid Integration:Demand-response capability convergence with home energy management systems is enabling utility-sponsored installation subsidies in California and Texas pilot programs.
Industry Challenges
- Heat Pump Technician Certification:Refrigerant handling credentials required for service calls exceed conventional appliance repair training, constraining field service capacity expansion.
- DOE Test Procedure Alignment:Revised Department of Energy efficiency measurement protocols are forcing manufacturers to recalibrate product development timelines and certification submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Tumble Dryers Market |
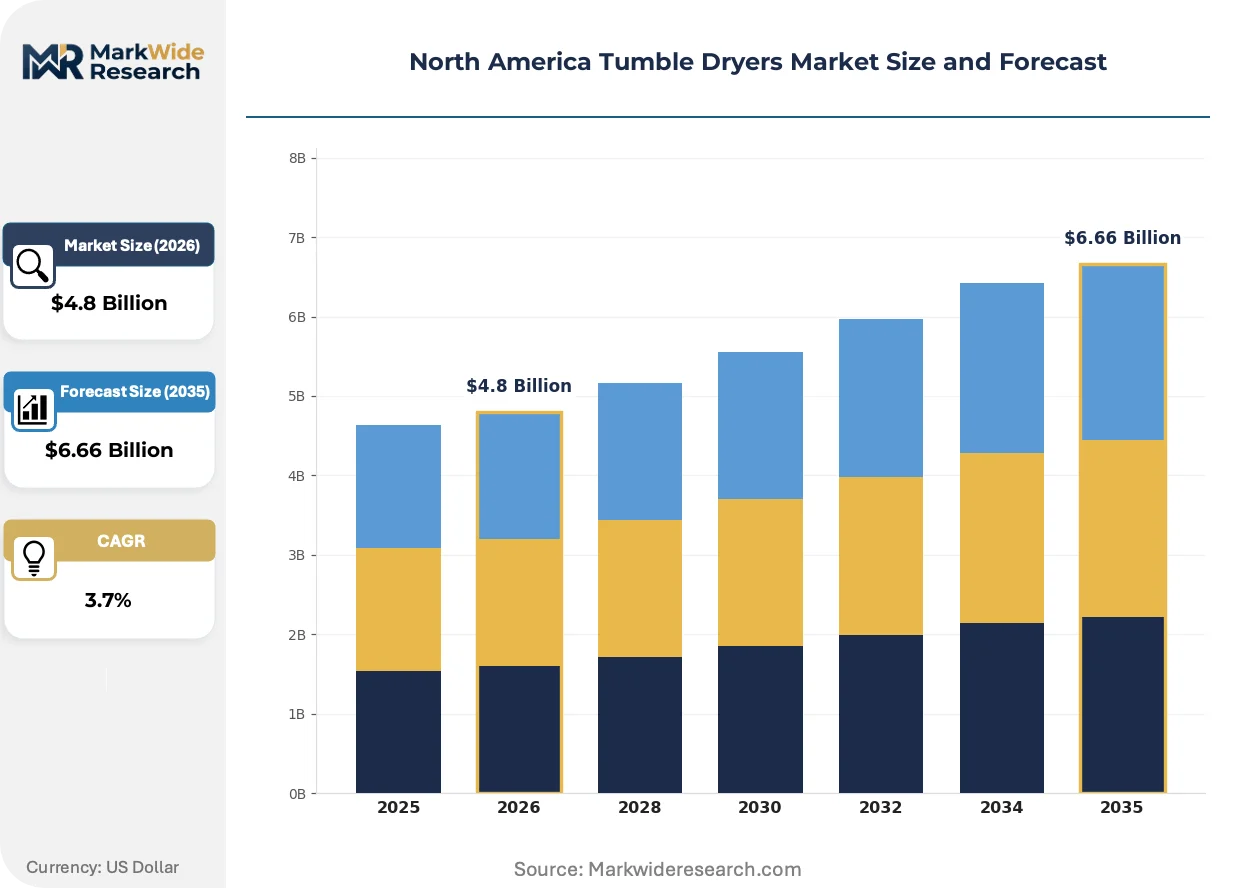
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Load, Top Load, Stackable, Compact Technology: Vented, Condenser, Heat Pump, Dryer Balls End User: Residential, Commercial, Industrial, Hospitality Capacity: 2-4 Kg, 5-7 Kg, 8-10 Kg, 11+ Kg |
| Companies Covered | Whirlpool, LG, Electrolux, Samsung, Maytag, Bosch, ASKO Appliances, GE Appliances, Haier, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Tumble Dryers Market Trends and Innovations
Technology trajectories in the North America Tumble Dryers Market center on thermal efficiency architectures, regulatory compliance automation, and procurement model restructuring across residential and commercial channels.
Inverter-driven heat pump systems are miniaturizing compressor and heat exchanger assemblies to fit within standard 24-inch residential footprints previously reserved for vented drums. Multi-family developers in urban markets are specifying these compact configurations to maximize leasable square footage. The technology is miniaturizing drying capacity without sacrificing load volume, enabling heat pump penetration into retrofit replacements where spatial constraints previously blocked adoption.
Natural Resources Canada and the EPA are tightening synchronized efficiency standards under harmonized North American appliance conservation frameworks. Manufacturers must now certify products against both federal minimums and ENERGY STAR tiered thresholds to maintain retail placement. The regulatory pressure is compressing product development cycles, with engineering resources concentrating on refrigerant selection and control system optimization to clear pending 2027 rulemakings.
Commercial end-users are unbundling equipment procurement from long-term service contracts, shifting toward direct capital purchase with third-party maintenance agreements. Hospitality operators in Florida and Arizona are leading this transition, seeking depreciation benefits and operational control over linen turnaround schedules. The purchasing pattern change is shortening sales cycles but intensifying price competition among manufacturers competing for specified project bids.
North America Tumble Dryers Market Segmentation
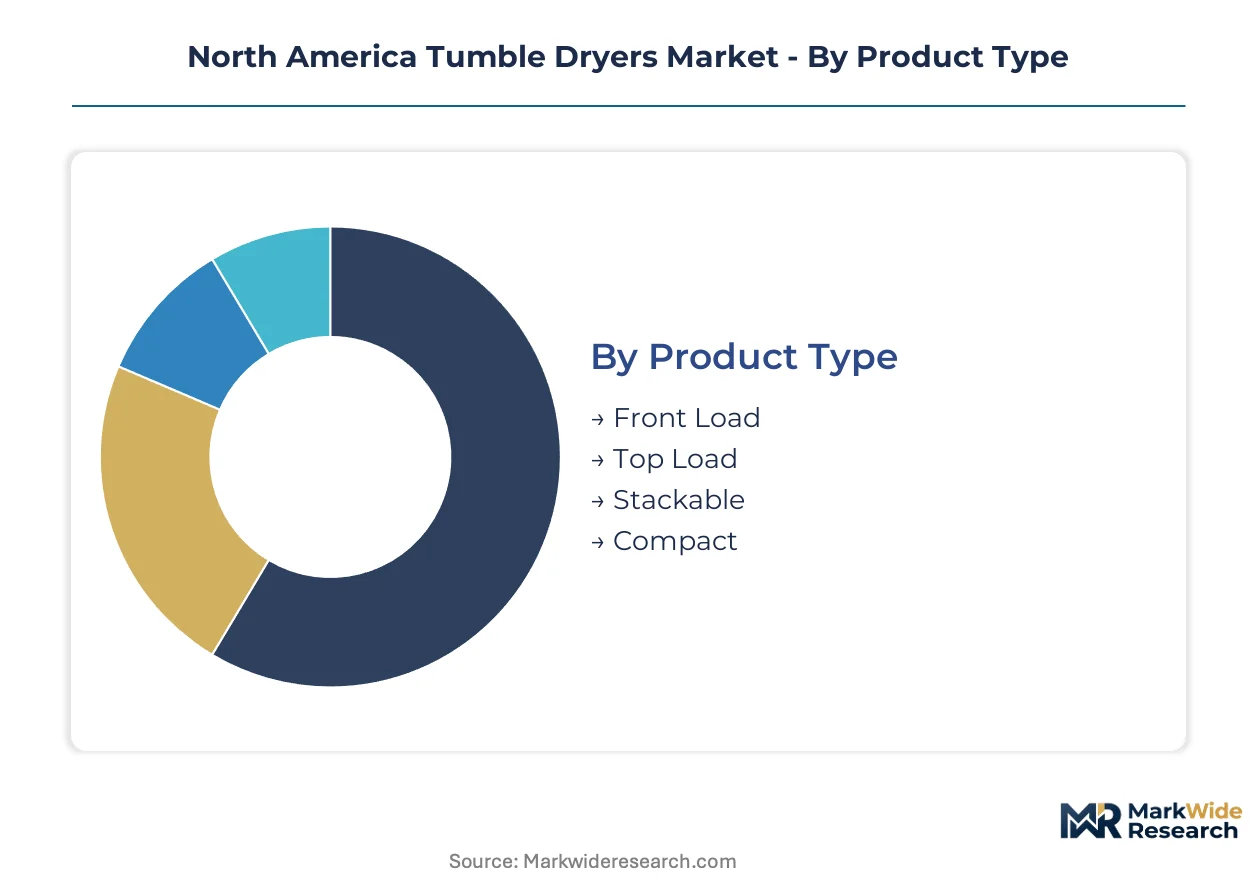
Segmentation in the North America Tumble Dryers Market reveals distinct procurement patterns across housing types, efficiency mandates, and operational scale. Regulatory thresholds and installation constraints create divergent growth trajectories within each category.
Product Type:
EPA ENERGY STAR certification thresholds and multi-family housing density requirements differentiate mechanical configurations across installation environments.
- Front Load:Horizontal drum orientation enables stacking compatibility and reduces floor space requirements. Demand concentrates in urban multi-family developments across Texas and Florida where square footage premiums drive specification. Heat pump integration is accelerating fastest in this configuration due to ventless operational requirements.
- Top Load:Vertical drum access dominates single-family residential replacement cycles in the southeastern United States. Conventional 240V vented hookups in existing housing stock sustain volume, though ENERGY STAR rebate eligibility is narrowing placement in new construction channels.
- Stackable:Paired washer-dryer vertical arrangements target closet installations in compact dwellings. Canadian provincial rebate programs in Ontario and British Columbia are expanding specification for certified configurations.
- Compact:Reduced 24-inch footprints serve studio apartments and secondary dwelling units. Natural Resources Canada efficiency standards are compressing demand toward heat pump variants in this segment.
Established volume favors top load configurations in replacement channels; emerging adoption favors front load systems in new multi-family construction.
Technology:
Cost tier differentiation separates conventional vented architectures from premium heat pump systems, with utility rebate programs compressing mid-market positioning.
- Vented:Exhaust duct configurations dominate existing housing infrastructure across the United States. Installation simplicity sustains replacement demand, though DOE minimum efficiency standards are eroding new construction placement.
- Condenser:Closed-loop moisture collection enables ventless operation without refrigerant circuits. Demand clusters in Canadian rental markets and US multi-family retrofits where external venting is structurally prohibitive.
- Heat Pump:Refrigerant-based thermal energy recapture achieves coefficient of performance ratings above three. EPA ENERGY STAR rebate administrators and provincial utility programs in Ontario are accelerating residential adoption fastest.
- Dryer Balls:Mechanical fabric separation accessories reduce drying cycle duration and static accumulation. Commercial hospitality operators in Florida and Arizona are specifying these for on-premise linen processing cost control.
Cost-driven procurement sustains vented technology in replacement cycles; rebate-aligned specification is climbing fastest for heat pump architectures.
End User:
Application scale determines equipment durability requirements, service contract structures, and capital depreciation treatment across procurement decisions.
- Residential:Single and multi-family household installations dominate absolute unit volume. ENERGY STAR certification is becoming mandatory for retail placement in major US appliance chains and Canadian distributors.
- Commercial:Laundromat and multi-housing common-area operations require continuous-duty cycle ratings. Demand concentrates in Texas and Georgia where population migration is expanding rental housing stock.
- Industrial:Healthcare and institutional linen processors specify heavy-duty drum constructions and fire suppression integration. Operational throughput requirements favor vented gas-fired systems where infrastructure permits.
- Hospitality:Hotel and resort operators are unbundling linen processing from third-party contracts in Florida and Arizona. Direct capital purchase with third-party maintenance agreements is shortening manufacturer sales cycles.
Residential channels capture highest unit volume; hospitality direct procurement is gaining share fastest among commercial segments.
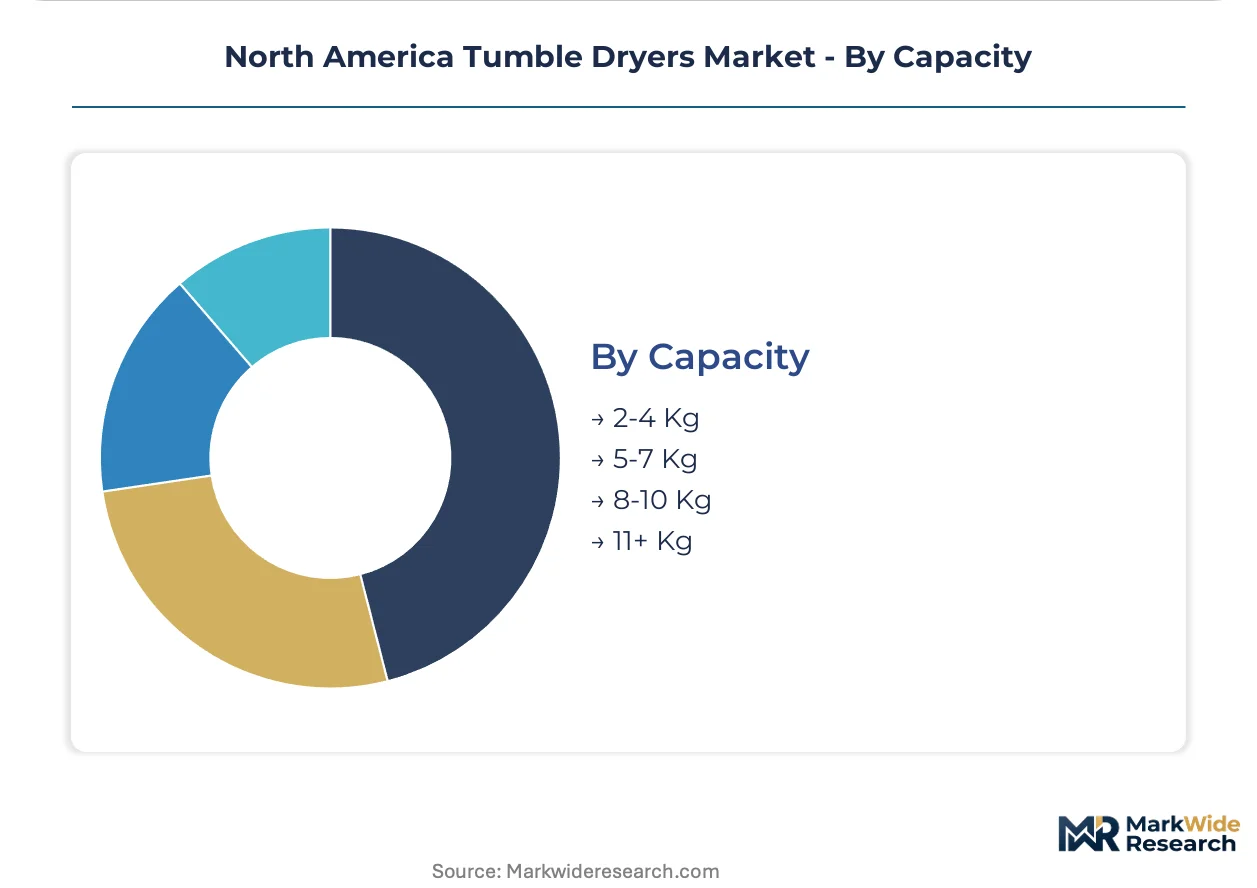
Capacity:
Customer type and housing unit size dictate load volume requirements, with density constraints in urban markets compressing specification toward smaller drums.
- 2-4 Kg:Compact drums serve studio apartments, RV installations, and secondary dwelling units. Canadian multi-family developers in Vancouver and Toronto are mandating these for in-unit laundry compliance.
- 5-7 Kg:Mid-range capacity matches average household load sizes across single-family dwellings. This segment captures the broadest replacement demand in both US and Canadian residential channels.
- 8-10 Kg:Large-family and light commercial applications specify expanded drum volumes. Heat pump technology miniaturization is enabling efficiency compliance in this previously vented-dominated range.
- 11+ Kg:Industrial and hospitality bulk processing requires reinforced drum suspensions and extended duty cycles. Commercial end-users in southeastern US hospitality markets are specifying these for on-premise linen operations.
Mid-capacity 5-7 Kg drums sustain broadest residential placement; compact 2-4 Kg configurations are expanding most quickly in urban multi-family development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across North America. Canadian buyers respond most aggressively to provincial rebate programs, while southeastern US purchasers prioritize installation speed over upfront cost. Mexican demand clusters in northern border cities where cross-border retail arbitrage shapes specification.
United States
Multi-family developers in Texas, Florida, and Georgia are mandating in-unit laundry installations in new construction. The EPA administers ENERGY STAR certification thresholds that manufacturers must clear for retail placement in major appliance chains. Atlanta and Dallas-Fort Worth concentrate hospitality renovation cycles where hotel operators are unbundling linen processing from third-party contracts.
Canada
Natural Resources Canada efficiency standards compress demand toward heat pump and condenser models in urban multi-family markets. Provincial utility rebate administrators in Ontario and British Columbia extend point-of-sale incentives for certified replacements. Vancouver and Toronto developers mandate compact 24-inch configurations for studio apartment compliance.
Mexico
Northern border cities including Monterrey and Tijuana absorb spillover demand from US specification standards through cross-border retail channels. The national energy efficiency regulator enforces minimum performance standards for imported appliances. Baja California and Nuevo León concentrate assembly operations supplying regional distribution networks.
North America Tumble Dryers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the North America Tumble Dryers Market. The upper tier commands captive component manufacturing and inverter compressor supply control. Mid-tier players compete on compact system specialization and urban multi-family channel access. Dominant competitive moves include vertical integration into heat exchanger production and strategic partnerships with utility rebate administrators.
Among North American appliance manufacturers, Whirlpool and GE Appliances exemplify integrated leaders with captive supply chains. LG anchors the Korean-origin tier through upstream compressor control. Electrolux occupies a specialist position in compact ventless configurations targeting dense housing markets.
| Leading Market Players |
|---|
| Whirlpool |
| LG |
| Electrolux |
| Samsung |
| Maytag |
| Bosch |
| ASKO Appliances |
| GE Appliances |
| Haier |
| Others |
Pricing and Supply Chain Analysis
Inverter compressor substitution for conventional induction motors is redrawing procurement geography toward South Korean suppliers while compressing mid-tier pricing economics across North American assembly operations. This component transition simultaneously elevates capital requirements for heat pump configurations and erodes margin buffers for manufacturers lacking captive compressor supply.
Pricing Analysis
After-sales service revenue from refrigerant handling and compressor replacement drives lifetime value capture for heat pump specialists. Three-tier pricing structure across premium heat pump, standard condenser, and economy vented levels stratifies the market, with ENERGY STAR certification tier and utility rebate eligibility serving as primary differentiation drivers. Cost compression in mid-tier condenser segments is intensifying because Korean compressor supply concentration limits sourcing alternatives. Commercial hospitality operators in Florida and Arizona exhibit lowest price sensitivity due to operational throughput requirements, while residential replacement buyers in southeastern states remain most cost-conscious.
Supply Chain Analysis
South Korea and China anchor inverter compressor fabrication and heat exchanger component manufacturing for North American dryer assembly. Copper tubing and steel drum assemblies draw from Mexican and Canadian metal forming operations, while electronic control modules source from Taiwan semiconductor packaging facilities. Single-source vulnerability clusters in Korean compressor suppliers creates geographic concentration exposure for US and Canadian OEMs. Distribution runs through big-box retail chains, regional appliance distributors, and direct commercial procurement channels serving multi-family developers and hospitality operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through ENERGY STAR certification and DOE efficiency standards creates substantial switching costs for established participants. The certification barrier protects incumbents while constraining agile repositioning by challengers.
For Market Incumbents: Consolidate backward integration into heat exchanger production to defend margin structures against Korean compressor supply concentration. Deepen channel control through exclusive arrangements with utility rebate administrators in Ontario and British Columbia. Refrigerant circuit optimization R&D and technician certification program expansion represent critical capability investments against emerging heat pump service competition. For New Entrants and Emerging Players: Compact ventless system service gaps in urban multi-family retrofits present viable white-space entry points. Target Canadian provincial incentive programs where established presence remains thinner than US southeast corridors. Direct-to-developer specification relationships bypass retail channel barriers that incumbent brands dominate. For Investors and Strategic Acquirers: Pending 2027 DOE efficiency rulemakings reshape the acquisition landscape toward heat pump-ready manufacturing footprints. Five-to-ten year viability favors targets with established refrigerant handling credentials and compact system engineering depth. Monitor Natural Resources Canada harmonization announcements as early inflection signals for portfolio rebalancing toward certified-efficient configurations.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Technology Transition | EPA ENERGY STAR certification requirements compress demand toward high-efficiency architectures and away from vented systems. |
| Utility Rebate Program Partnerships | Point-of-sale incentive alignment with Ontario and British Columbia administrators accelerates certified model penetration. |
| Compact System Miniaturization | 24-inch footprint heat pump configurations unlock urban multi-family retrofit demand previously blocked by spatial constraints. |
| Technician Certification Expansion | Refrigerant handling credential programs address field service capacity constraints constraining heat pump adoption velocity. |
| Commercial Hospitality Direct Procurement | On-premise linen processing unbundling in Florida and Arizona creates specified project bid opportunities outside retail channels. |
Research Methodology
Cross-validation between regulatory filing analysis and utility program documentation anchors the qualitative findings in this study. Primary interviews with product development executives at major appliance manufacturers, procurement directors at multi-family housing developers, and rebate program administrators at provincial utilities combined with secondary validation from DOE rulemaking dockets, Natural Resources Canada efficiency standards, and EPA ENERGY STAR certification databases. Bottom-up shipment data triangulates against top-down construction permit analysis across Texas, Florida, and Georgia metropolitan areas.
Sensitivity analysis around compressor supply concentration and rebate program renewal schedules informs the analytical framework. Segmentation dimensions span product configuration, technology architecture, end-user scale, and regional regulatory cluster across the projection horizon. CAGRs derive from installed base replacement modeling and new construction specification tracking, with heat pump adoption curves and multi-family housing permit velocity serving as industry-specific forecast inputs.
Underlying assumptions cover sustained ENERGY STAR certification relevance and provincial incentive program continuity, with deviation risk concentrated in Korean supply chain disruptions and federal efficiency rulemaking delays. Recalibration cycles align with material shifts in DOE test procedure announcements and Natural Resources Canada harmonization updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Window Air Conditioners Market
Appliances
Electric Rice Cooker Market
Appliances
United States Electronics and Appliance Stores Market
Appliances
Fully Integrated Dishwasher Market
Appliances
Egypt Microwave Ovens Market
Appliances
Global Vended Laundry Equipment Market
Appliances
UK Residential Vacuum Cleaner Market
Appliances
United States Multi-Functional Oven Market
Appliances
Triple Barrel Waver Market
Appliances
China Induction Hobs Market
Appliances
Asia-Pacific Tumble Dryers Market
Appliances
Qatar Dishwashers Market
Appliances
Portable Dishwasher Market
Appliances
Middle East Portable Washing Machines Market
Appliances
Smart Washing Machine Market
Appliances
Qatar Microwave Ovens Market