
 Portable Mini Fridge Market | 2026-2036
Portable Mini Fridge Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Mini Fridge Market Intelligence
E-commerce fulfillment networks is reconfiguring how portable mini fridges reach end buyers, with direct-to-consumer platforms capturing growing volume previously routed through appliance retailers. Midea Group leverages its massive manufacturing scale to dominate cost-efficient compressor-based units. Dometic Group AB anchors the premium automotive and RV channel with specialized 12V/24V designs. Cooluli differentiates through aesthetic-focused thermoelectric models targeting dormitory and cosmetic storage segments.
A portable mini fridge is a compact, mobile refrigeration unit typically spanning 4 to 50 liters in internal capacity, employing thermoelectric Peltier modules, absorption cycles, or miniature compressor systems to maintain temperatures between 35°F and 50°F below ambient conditions for beverage, cosmetic, or medication preservation. The thermoelectric product type occupies the entry-price tier and sustains volume leadership in personal and gift applications, though compressor variants command the margin pool through superior cooling performance and energy efficiency. The automotive end user segment is recording the fastest trajectory as electric vehicle manufacturers integrate dedicated 12V accessory ports and cabin storage solutions.
The US Department of Energy enforces minimum efficiency standards under its appliance certification program, while the EPA regulates refrigerant selections through SNAP approvals that constrain hydrofluorocarbon deployment in new cooling products. The EU F-Gas Regulation and CE marking requirements shape market access for imported units across European member states. Stakeholders must monitor evolving refrigerant phase-down schedules and battery compatibility standards as product portfolios pivot toward DC-powered and solar-integrated configurations.
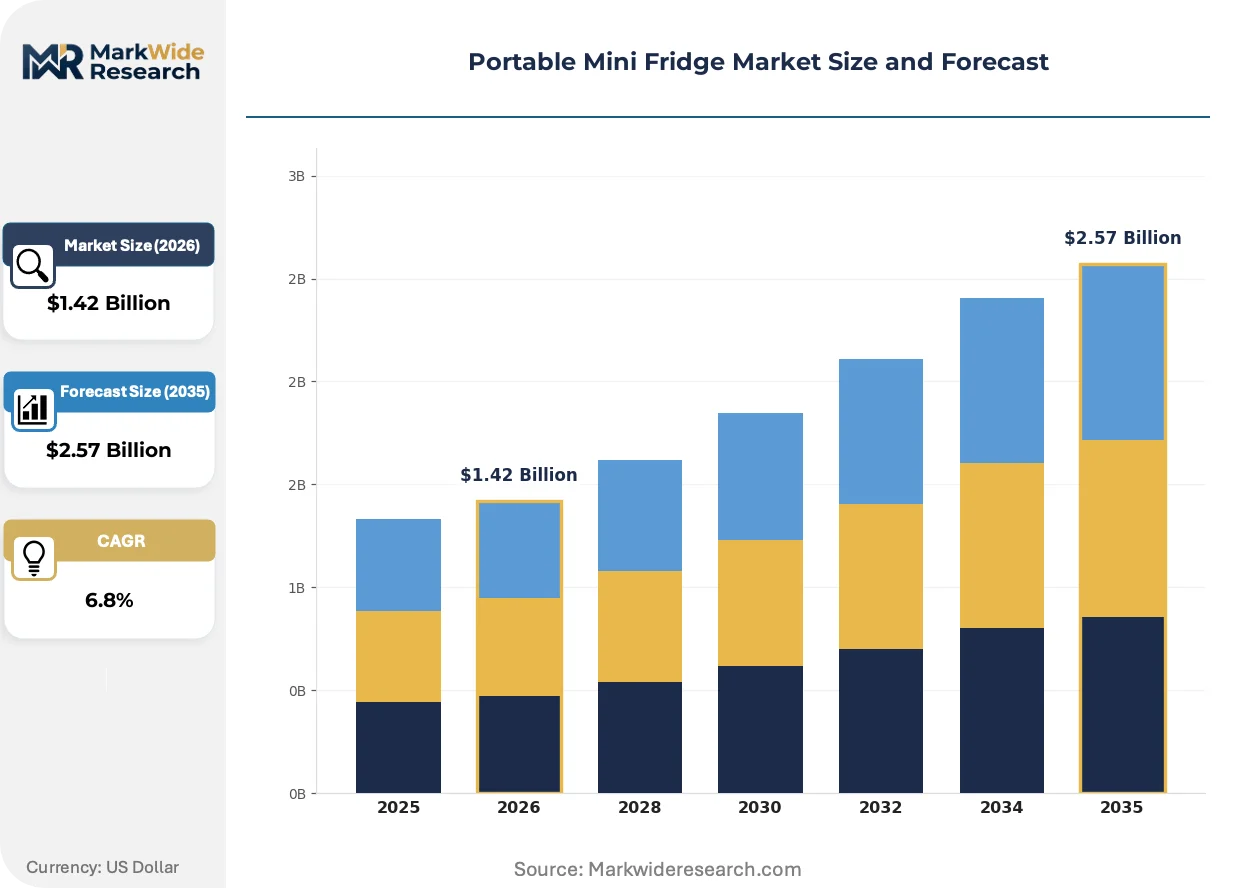
Market Dynamics
Thermoelectric cooling efficiency gains and semiconductor material advances are compressing the performance gap with compressor systems, forcing incumbents to reposition across price tiers and accelerating DC-native product architectures for mobile power ecosystems.
Growth Catalysts
- Electric vehicle 12V accessory port proliferation:OEM integration of dedicated cabin refrigeration circuits in battery-electric platforms creates factory-fit demand for compact DC cooling units.
- Remote work mobility normalization:Digital nomad infrastructure expansion across Portugal, Mexico, and Thailand sustains van-life equipment procurement cycles for mobile refrigeration.
- EU F-Gas Regulation phase-down schedules:Hydrofluorocarbon restrictions under Annex VI accelerate refrigerant transitions toward propane and isobutane alternatives in compressor-based designs.
Market Restraints
- Lithium-ion cell cost volatility:Battery pack input fluctuations constrain margin stability for solar-integrated and cordless product lines.
- Thermoelectric COP ceiling:Peltier module physics limit cooling differential to approximately 20°C below ambient, disqualifying the technology from tropical climate deployment.
- Absorption cycle manufacturing concentration:Specialized ammonia-hydrogen assembly capacity clusters in Southeast Asia, creating single-source vulnerability for hotel minibar and RV absorption units.
Strategic Opportunities
- India two-wheeler delivery fleet electrification:Swiggy and Zomato thermal box specifications create demand for 12V compressor modules in last-mile food logistics.
- Solar-DC microgrid convergence:Pairing photovoltaic generation with native 12V/24V refrigeration eliminates inverter losses in off-grid residential and mobile applications.
- Cosmetic cold-chain premiumization:Skincare ingredient stability requirements at 10-15°C open temperature-controlled vanity storage segments beyond beverage cooling.
Industry Challenges
- Multi-certification timeline compression:Simultaneous UL, CE, and PSE approval pathways extend product launch windows for universal voltage designs.
- Thermal management engineering scarcity:Finite talent pools for miniature vapor-compression system design constrain R&D velocity at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Mini Fridge Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Thermoelectric, Compressor, Absorption End User: Residential, Commercial, Medical, Automotive Capacity: 20L, 30L, 40L, 50L Power Rating: 30W, 45W, 60W, 75W |
| Companies Covered | Danby Products Limited, Midea Group, Whirlpool Corporation, LG Electronics, Haier Group Corporation, Cooluli, Dometic Group AB, Koolatron Corporation, Whynter LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Mini Fridge Market Strategic Shifts & Innovations
Product architectures are pivoting toward native DC operation as battery-electric mobility and distributed solar generation reshape power availability assumptions for mobile refrigeration.
Compressor-based cooling is migrating from AC-dominant residential and hospitality applications toward native 12V/24V automotive and marine platforms. RV manufacturers and overlanding outfitters specify DC-native units to eliminate inverter losses and shore power dependency. This technology shift compresses the addressable market for thermoelectric alternatives in performance-critical segments while opening margin pools for variable-speed inverter compressor designs.
REACH substance restrictions and RoHS recast directives are tightening material compliance obligations for thermoelectric modules containing bismuth telluride and ceramic substrates. Manufacturers serving European markets must reformulate solder alloys and substrate coatings to maintain CE marking validity. The regulatory pressure falls most heavily on entry-price tier suppliers lacking in-house toxicology and materials science capabilities.
Direct-to-consumer channel capture is accelerating as Amazon and specialty outdoor retailers displace traditional appliance distribution for personal-capacity units. Specialist merchants including REI and Backcountry curate editorial content around van-life and overlanding use cases, collapsing the information asymmetry that previously favored brick-and-mortar consultation. This behavioral shift concentrates most visibly in the United States, where recreational vehicle ownership rates and outdoor recreation expenditure sustain premium positioning for brand-direct mini fridge offerings.
Portable Mini Fridge Market Segmentation
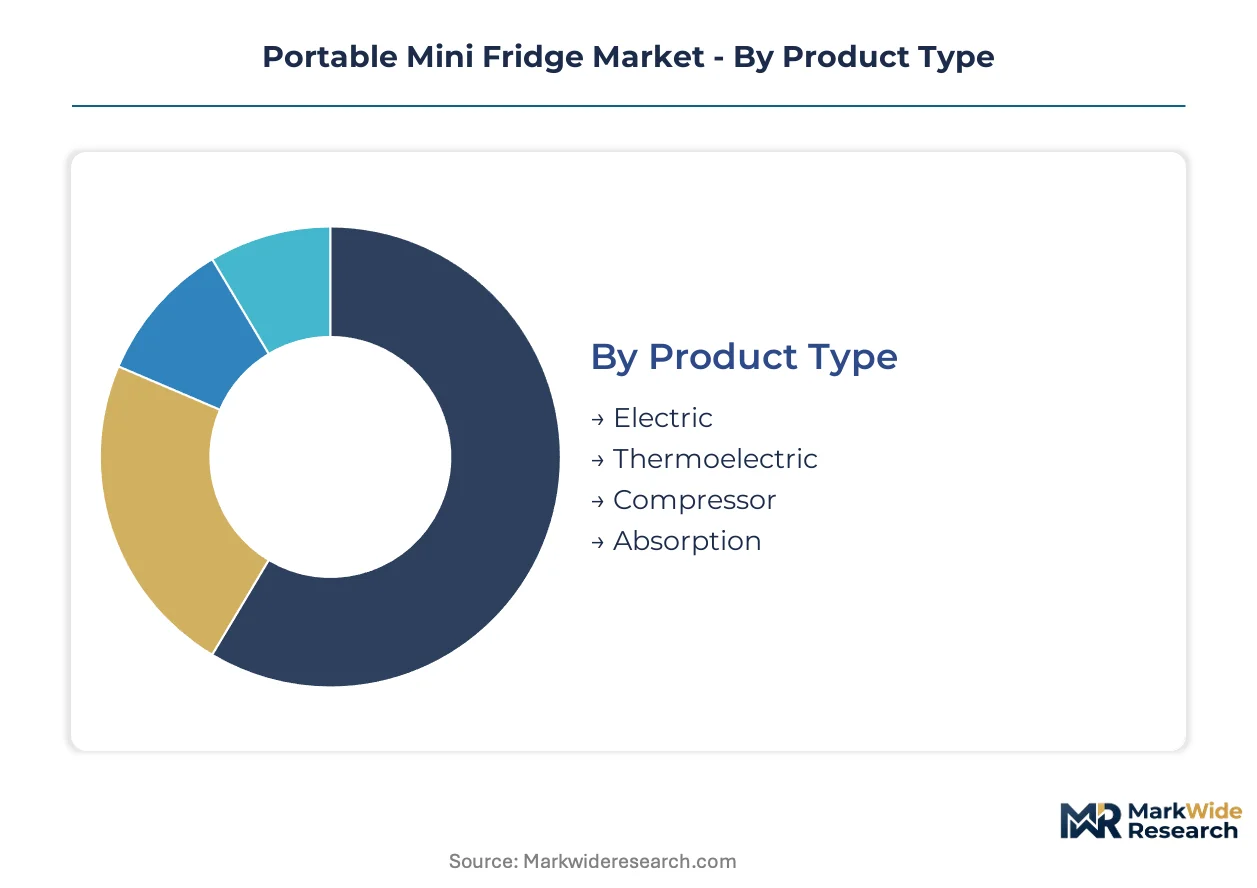
Portable mini fridge segmentation reveals how cooling technology, use environment, and power constraints split demand across radically different buyer expectations. Capacity and power specifications further stratify procurement decisions between personal mobility and commercial fleet applications.
Product Type:
Cooling mechanisms span a performance-cost spectrum from silent solid-state modules to vapor-compression systems engineered for thermal extremes.
- Electric:Broad category encompassing AC-powered units designed for household backup and office environments where grid access is stable. Demand clusters in Japanese apartment dwellings and German home-office conversions seeking supplementary beverage storage without HVAC integration.
- Thermoelectric:Peltier modules leveraging semiconductor junctions to pump heat without moving parts, enabling silent operation and extreme miniaturization for cosmetic and dormitory applications. Volume leadership persists in gift and personal-use channels across the United States, though the 20°C differential ceiling disqualifies deployment in tropical climates.
- Compressor:Miniature vapor-compression cycles using hermetic reciprocating or rotary designs to achieve sub-freezing temperatures with coefficient-of-performance values 3-5× superior to thermoelectric alternatives. Demand concentrates in automotive and RV channels across the United States and Australia, where electric vehicle manufacturers specify native 12V/24V units for cabin integration.
- Absorption:Ammonia-hydrogen diffusion cycles operating silently on propane, butane, or 12V heat sources, eliminating compressor noise for hotel minibar and marine sleeper-berth installations. Manufacturing concentration in Thailand and Vietnam creates supply vulnerability for European hospitality procurement.
The dominant share belongs to Thermoelectric, while Compressor is closing the gap fastest.
End User:
Buyer archetypes diverge sharply between stationary convenience and mobile necessity, with regulatory compliance layering additional complexity onto medical and automotive specifications.
- Residential:Secondary refrigeration for home bars, guest accommodations, and overflow storage during entertaining. Demand is accelerating in Australian suburban expansion corridors and Spanish coastal vacation properties.
- Commercial:Hospitality minibar installations, office pantry provisioning, and retail point-of-sale beverage cooling. Procurement in Germany and France prioritizes EU F-Gas Regulation compliance and energy labeling transparency.
- Medical:Temperature-controlled storage for vaccines, insulin, and temperature-sensitive biologics requiring 2-8°C stability with continuous monitoring. Indian clinic networks and Nigerian vaccination programs drive procurement of 12V solar-compatible units.
- Automotive:Cabin-integrated or trunk-mounted cooling for personal vehicles, RVs, overlanding rigs, and electric vehicle platforms. This segment is expanding most quickly as OEMs in the United States, South Korea, and Sweden embed dedicated 12V accessory circuits.
Automotive commands the steepest expansion trajectory, while Residential maintains the largest installed base.
Capacity:
Internal volume specifications align with duration of autonomy and party size, creating distinct mobility versus stationary trade-offs.
- 20L:Personal-scale units accommodating 6-8 beverage cans or a single meal-prep container. Dominates Japanese single-occupancy vehicle applications and Brazilian motorcycle delivery thermal boxes.
- 30L:Couple-scale capacity bridging personal and small-group use cases. Preferred specification for German camper-van conversions and Thai digital nomad co-living setups.
- 40L:Family-scale storage supporting multi-day provisions for four occupants. Standard specification for Australian caravan manufacturers and United States overlanding outfitters.
- 50L:Maximum portable format approaching residential refrigerator drawer capacity. Concentrated in commercial foodservice logistics and medical cold-chain applications across India and South Africa.
20L holds the dominant share, while 40L is gaining share fastest among RV and van-life buyers.
Power Rating:
Wattage specifications determine battery drain rates and solar array sizing, forcing explicit trade-offs between cooling speed and off-grid autonomy.
- 30W:Thermoelectric-dominated tier optimized for USB power banks and small vehicle accessory ports. Prevails in cosmetic storage and dormitory applications across the United States and United Kingdom.
- 45W:Mid-tier thermoelectric and entry compressor designs balancing cooling performance with moderate battery load. Standard for Japanese kei-car installations and Portuguese camper conversions.
- 60W:Variable-speed compressor tier achieving rapid pull-down without sustained high-wattage operation. Preferred by Australian 4WD expedition builders and Swedish electric vehicle aftermarket suppliers.
- 75W:High-performance compressor specification for tropical climate operation and medical-grade temperature stability. Concentrated in Indian pharmaceutical logistics and Nigerian solar-health clinic deployments.
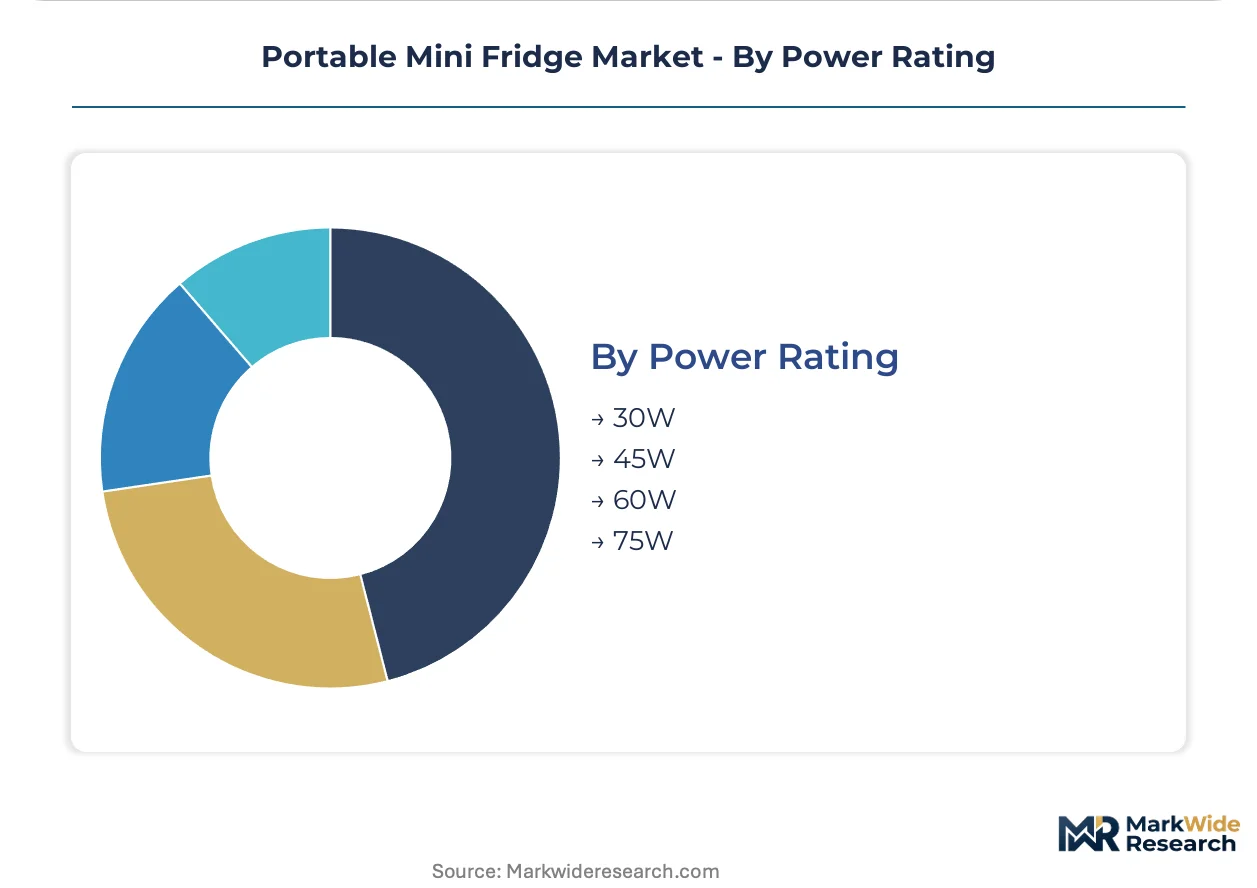
30W retains the dominant share, while 60W is climbing the fastest as DC-native compressor designs displace thermoelectric alternatives in automotive channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA refrigerant regulations under SNAP approvals and appliance efficiency standards anchor United States demand for DC-native portable cooling units. Road-tripping consumers and van-life enthusiasts drive procurement cycles across state markets.
United States
RV ownership rates and remote work mobility trends sustain pull for 12V/24V compressor designs. NHTSA vehicle accessory port standards and EPA SNAP refrigerant approvals shape product compliance requirements. Austin, Texas and Portland, Oregon anchor van-life equipment retail clusters where overlanding outfitters specify native DC refrigeration.
Germany
Camper-van conversion specialists and digital nomad infrastructure expansion drive 30L and 40L capacity demand. EU F-Gas Regulation phase-down schedules and REACH substance restrictions constrain thermoelectric module materials. Stuttgart and Munich manufacturing corridors host precision compressor engineering talent pools serving automotive OEM integration programs.
China
Manufacturing scale advantages and two-wheeler delivery fleet electrification create export and domestic demand for compact cooling modules. MIIT battery compatibility standards and GB appliance efficiency ratings regulate product design. Shenzhen and Dongguan electronics clusters concentrate thermoelectric semiconductor assembly capacity for global supply.
India
Swiggy and Zomato last-mile food logistics specifications drive 12V compressor procurement for electric two-wheeler thermal boxes. BIS appliance safety standards and CDSCO medical device regulations apply to vaccine storage applications. Bangalore and Hyderabad logistics hubs specify solar-compatible 75W units for pharmaceutical cold-chain deployments.
Australia
4WD expedition builders and caravan manufacturers sustain premium demand for 40L variable-speed compressor designs. TGA medical device standards apply to remote clinic refrigeration procurement. Perth and Brisbane overlanding retail clusters curate DC-native product lines for off-grid autonomy requirements.
Portable Mini Fridge Market Key Industry Players
Scale-driven appliance conglomerates and specialized mobility-cooling engineers split the market into divergent capability tiers. Consolidation pressure concentrates volume leadership among diversified manufacturers with captive compressor technology, while mid-tier specialists defend position through automotive channel relationships and DC-native design expertise. Two strategic archetypes dominate: diversified appliance groups leveraging manufacturing scale, and focused mobility-cooling specialists commanding premium positioning in RV and marine channels. Competitive moves center on backward integration into compressor technology and geographic expansion through direct-to-consumer platform capture.
Within the diversified appliance tier, Midea Group and Haier Group Corporation exemplify scale-driven manufacturing advantages spanning cost-efficient compressor-based units. Dometic Group AB occupies the specialized mobility-cooling position, anchoring premium automotive and RV channel relationships through dedicated 12V/24V design expertise.
| Leading Market Players |
|---|
| Danby Products Limited |
| Midea Group |
| Whirlpool Corporation |
| LG Electronics |
| Haier Group Corporation |
| Cooluli |
| Dometic Group AB |
| Koolatron Corporation |
| Whynter LLC |
| Others |
Cost & Logistics Intelligence
Shenzhen and Dongguan electronics clusters concentrate thermoelectric semiconductor assembly capacity, creating asymmetric pricing power for entry-tier suppliers while compressor engineering scarcity in Stuttgart and Munich sustains premium tier margins. This geographic bifurcation compresses mid-tier positioning and rewards backward integration into miniature vapor-compression technology.
Pricing Analysis
Price spreads between German-engineered compressor units and Chinese-manufactured thermoelectric alternatives span three performance tiers defined by cooling differential capability and certification grade. UL and CE marking tiers separate premium automotive OEM specifications from personal-use commodity imports. Cost compression in the thermoelectric tier intensifies because bismuth telluride substrate oversupply and REACH compliance burdens squeeze margin-stripped assemblers. Fleet procurement managers at Swiggy and Zomato exhibit highest price sensitivity, while RV overlanding outfitters in Austin and Portland absorb premium positioning for native DC-native designs.
Supply Chain Analysis
Supplier-financing facilities extended by Midea Group and Haier Group Corporation lock in component allocation priority for tier-two assemblers, compressing cash conversion cycles for unaffiliated competitors. Manufacturing gravity centers on China for thermoelectric modules, Thailand and Vietnam for absorption cycle assembly, and Germany for precision compressor engineering. Raw material dependencies span lithium-ion cells from South Korea, hermetic compressor housings from Japan, and semiconductor substrates from domestic Chinese refiners. Single-source vulnerability concentrates in ammonia-hydrogen diffusion assembly for hotel minibar applications. Distribution runs through Amazon and REI direct-to-consumer platforms for personal-capacity units, bypassing traditional appliance retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as electric vehicle OEMs proliferate 12V accessory port standards and remote work mobility normalizes van-life equipment procurement across Portugal, Mexico, and Thailand.
For Market Incumbents: Harden compressor technology moats through captive miniature vapor-compression R&D in Stuttgart and Munich engineering corridors. Secure automotive OEM integration slots before NHTSA vehicle accessory port standards solidify around dominant supplier specifications. Defend against thermoelectric efficiency gains by accelerating variable-speed inverter compressor deployment in 60W and 75W tiers. For New Entrants and Emerging Players: Build out solar-DC microgrid convergence offerings targeting Nigerian health clinics and Indian pharmaceutical logistics hubs where 75W medical-grade specifications remain underpenetrated. Exploit cosmetic cold-chain premiumization in skincare ingredient stability segments beyond beverage cooling. Lead with direct-to-consumer platform capture on Amazon and specialty outdoor retail to collapse incumbent channel control. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet logistics operators specifying thermal box standards for electric two-wheeler delivery networks. Long-term viability hinges on refrigerant transition timing as EU F-Gas Regulation phase-down schedules and EPA SNAP approvals constrain hydrofluorocarbon deployment. Target acquisition archetypes include DC-native design specialists with automotive channel relationships. Monitor battery-electric vehicle production ramp rates as the inflection signal for factory-fit demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Compressor Technology | Captive miniature vapor-compression engineering secures margin pool access against thermoelectric commoditization. |
| Direct-to-Consumer Platform Launch | Amazon and REI channel capture collapses information asymmetry favoring traditional appliance distribution. |
| Native DC Product Architecture Development | 12V/24V designs eliminate inverter losses for electric vehicle and solar-integrated applications. |
| REACH Compliance Reformulation Investment | Bismuth telluride and ceramic substrate alternatives preserve CE marking validity in European markets. |
| Fleet Logistics Partnership Program | Swiggy and Zomato thermal box specifications create anchored demand for 12V compressor modules. |
Research Approach
Desk research of customs trade records, SEC appliance manufacturer filings, and EU regulatory databases preceded structured interviews with RV manufacturer procurement directors, electric vehicle platform engineers, thermoelectric module plant managers, and hospitality minibar category buyers. Primary fieldwork validated cooling technology performance claims and DC-native design roadmaps against secondary data from EPA SNAP approval logs and MIIT battery compatibility standards. Bottom-up unit shipment estimates by capacity tier and power rating triangulated against top-down market value reconstruction.
Fixed assumptions across the projection horizon include EPA refrigerant phase-down adherence, lithium-ion cell cost stabilization, and NHTSA vehicle accessory port standard proliferation. Segmentation dimensions modeled span cooling mechanism, end-use environment, internal capacity, and wattage specification. CAGRs derived from logistic diffusion curves fitted to electric vehicle adoption patterns and remote work mobility normalization rates. Industry-specific inputs incorporated EU F-Gas Regulation compliance timelines and REACH substance restriction implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by diversified appliance conglomerates into captive compressor technology would shift outcomes through accelerated margin compression. Macroeconomic deviation in battery raw material costs, regulatory acceleration of hydrofluorocarbon restrictions, or breakthrough thermoelectric efficiency gains would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Residential Vacuum Cleaners Market
Appliances
Household Side by Side Refrigerator Market
Appliances
UK Residential Vacuum Cleaner Market
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
United Kingdom Compact Dishwasher Market
Appliances
Colombia Laundry Appliances Market
Appliances
Global Massage Chairs Market
Appliances
Japan Massage Equipment Market
Appliances
Cordless Vacuum Cleaner Market
Appliances
US Electric Rice Cooker Market
Appliances
Fully Integrated Dishwasher Market
Appliances
US Washing Machine Parts Market
Appliances
Laundry Kiosk Market
Appliances
Smart Washing Machine Market
Appliances
Conveyor Dishwasher Market
Appliances
French Door Refrigerator Market