
 Tumble Dryer Market | 2026-2036
Tumble Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Tumble Dryer Market Analysis
Capital-intensity divergence between integrated manufacturers and assembly-dependent competitors is bifurcating the competitive landscape. Whirlpool leverages captive component production across North American plants to sustain margin resilience. Electrolux anchors European market presence through specialized heat pump engineering. Samsung Electronics competes by extending semiconductor-controlled sensor platforms into smart drying cycles.
A tumble dryer is a forced-air textile-drying appliance that operates at drum temperatures between 50°C and 70°C for conventional cycles, using electric resistance elements, natural gas burners, or refrigerant-based heat pump systems to extract moisture from fabrics. Its primary commercial purpose centers on reducing garment drying time from hours to minutes while preventing mold propagation in humidity-sensitive environments. Heat pump technology now leads product type segmentation as efficiency standards harden, while ventless configurations capture fastest growth in urban residential installations where external venting proves impractical. Smart technology integration concentrates margin pools in connected-home ecosystems, whereas conventional drying remains mature with shrinking differentiation headroom.
EU Ecodesign requirements and ENERGY STAR certification in the United States tighten minimum efficiency thresholds, compelling manufacturers to redesign refrigerant circuits and insulation packages. Japan's Top Runner program accelerates heat pump adoption by benchmarking against best-in-class performance. Stakeholders must monitor refrigerant phase-down schedules under Kigali Amendment implementations and calibrate R&D budgets toward natural refrigerant architectures before compliance deadlines tighten.
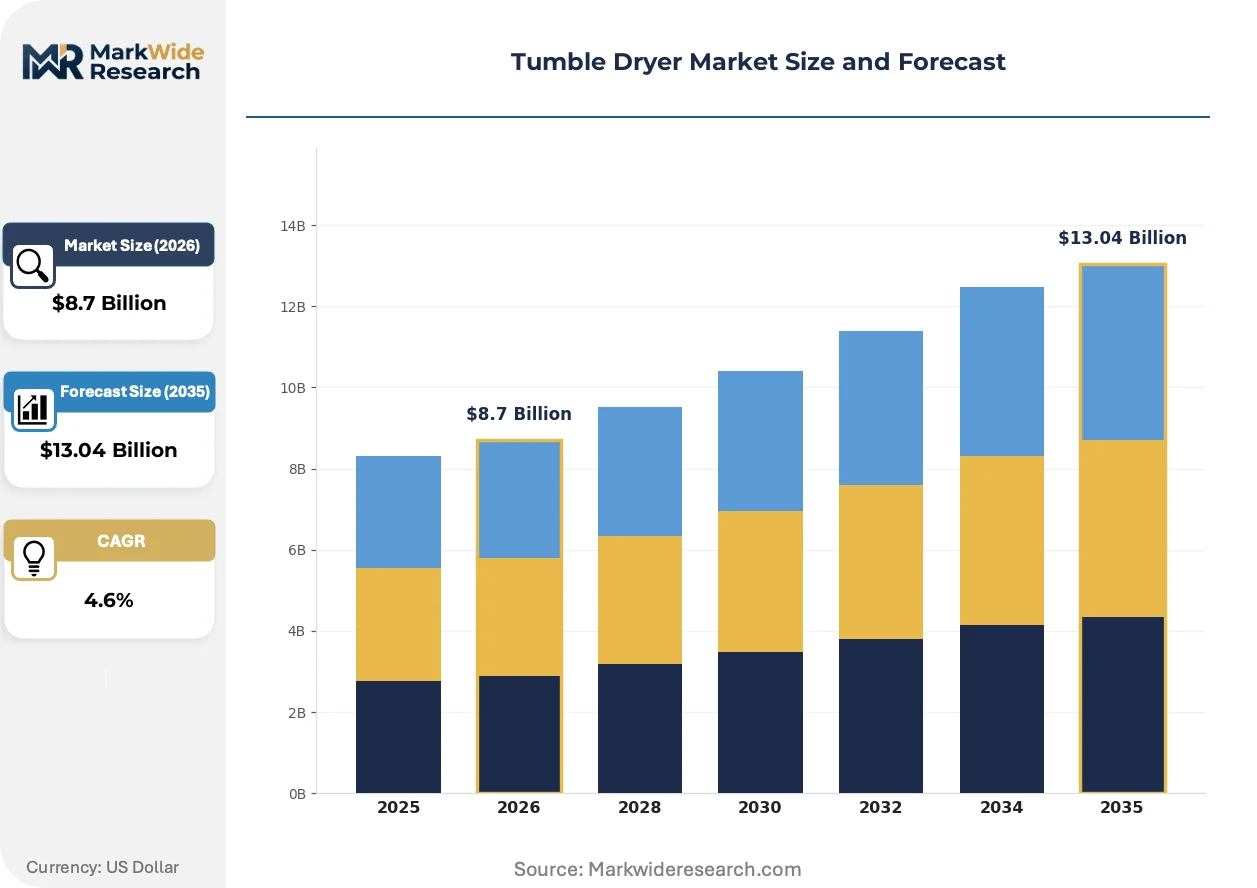
Market Dynamics
Heat pump refrigerant circuits are forcing wholesale redesign of manufacturing footprints as EU F-Gas Regulation and Kigali Amendment timelines compress the availability of high-GWP working fluids, compelling suppliers to retool assembly lines around propane and isobutane architectures before 2027 certification deadlines.
Growth Catalysts
- EU Ecodesign tightening:Minimum efficiency thresholds for household tumble dryers rose under the 2023 delegated regulation, compelling replacement cycles in Germany and France where older vented units face de facto obsolescence.
- Urban housing densification:Residential apartment construction in Tokyo, New York, and London prioritizes ventless condenser and heat pump configurations where external ducting is structurally prohibited.
- Heat pump engineering maturation:Coefficient of performance improvements in refrigerant-to-air heat exchangers now deliver drying parity with resistance heating at one-third the energy input, accelerating specification in utility rebate programs.
Market Restraints
- Refrigerant supply concentration:Specialty compressor manufacturing for R290 propane systems concentrates among Japanese and German component suppliers, creating single-source vulnerability for assembly-dependent OEMs.
- Copper and aluminum volatility:Heat pump coils require 40-60% more non-ferrous metal by weight than resistance dryers, exposing margin structures to London Metal Exchange price swings.
- Technical service gap:Refrigerant-handling certification requirements under EPA Section 608 in the United States and F-Gas certification in Europe constrain field technician availability for heat pump repairs.
Strategic Opportunities
- India residential electrification:Rising apartment ownership in Mumbai and Bangalore creates first-time dryer demand where ventless units bypass infrastructure constraints of older buildings.
- Smart grid integration:Demand-response-enabled dryers communicating with utility AMI networks qualify for time-of-use rate discounts in California and South Korea.
- Commercial laundry convergence:Heat pump technology scaling into on-premise laundromats and hospitality operations captures energy cost savings unavailable to conventional gas-fired tunnel systems.
Industry Challenges
- Refrigerant safety certification:IEC 60335-2-43 compliance for flammable refrigerant containment demands redesigned pressure vessel testing protocols that extend product development cycles by 8-12 months.
- Legacy venting infrastructure:Replacement demand in the United States confronts 120V electrical service limitations in pre-1990 housing stock that cannot support heat pump compressor loads without panel upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tumble Dryer Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventless, Vented, Heat Pump, Compact End User: Residential, Commercial, Industrial, Hospitality Technology: Energy Efficient, Smart, Conventional, Hybrid Installation Type: Stackable, Free-standing, Built-in, Under-counter |
| Companies Covered | Electrolux, Haier Electronics Group, Whirlpool, Speed Queen, Miele, LG Electronics, Bosch, Pellerin Milnor, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tumble Dryer Market Emerging Trajectories
Refrigerant architecture, sensor fusion, and service model unbundling are restructuring how dryers are engineered, sold, and maintained. These shifts favor integrated manufacturers with captive component capabilities while squeezing assembly-dependent competitors.
Variable-speed inverter compressors are displacing fixed-speed rotary units in heat pump dryers. German and Japanese OEMs have adopted these systems across premium product lines, enabling precise drum temperature modulation that protects delicate fabrics while cutting energy consumption. The technology is displacing conventional on-off compressor cycling as the default configuration in ENERGY STAR-certified models.
The EU F-Gas Regulation's phasedown schedule is accelerating natural refrigerant adoption. Manufacturers must redesign sealed systems around R290 propane or R600a isobutane to maintain market access, with compliance deadlines compressing engineering timelines. Heat pump dryer portfolios face the most acute retooling pressure, as these products rely entirely on refrigerant circuits unlike resistance-heated alternatives.
Appliance-as-a-service contracting is emerging in European multifamily housing. Property management firms in the Netherlands and Sweden now lease dryer capacity with maintenance bundled, shifting capital expenditure to operating budgets. This procurement model favors OEMs with captive service networks over pure manufacturing competitors lacking field technician density.
Tumble Dryer Market Segmentation
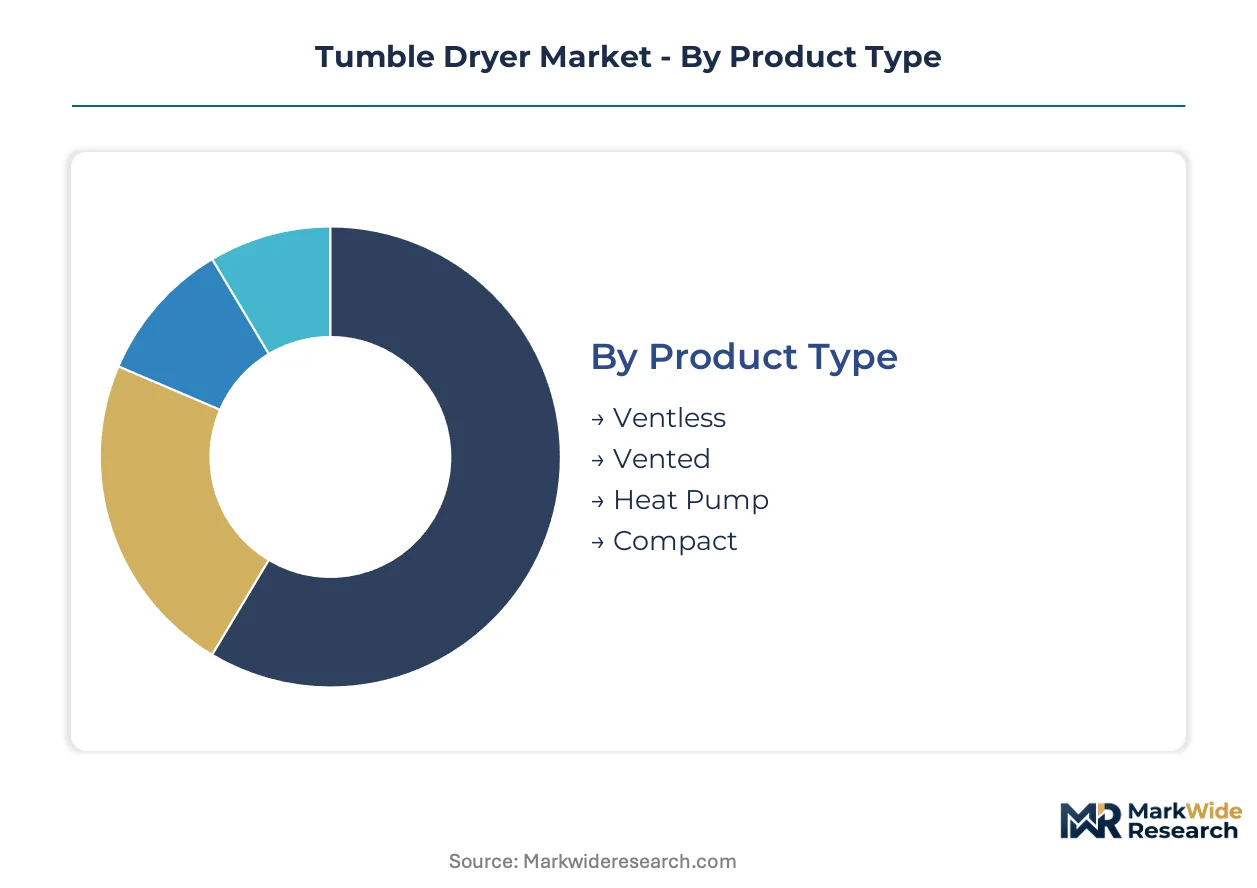
Tumble dryer segmentation reveals how regulatory pressure and housing constraints fragment demand across incompatible technical architectures. Product type and technology choices now lock buyers into decade-long infrastructure commitments that resist switching.
Product Type:
Substitution pressure from heat pump engineering is devaluing vented and conventional resistance-heated units in regulated markets where operating cost differentials compound over equipment life.
- Heat Pump:Refrigerant-based systems recover exhaust heat through closed-loop compression cycles, achieving coefficient of performance ratios above three-to-one versus resistance heating. Demand concentrates in Germany and France where EU Ecodesign regulations have rendered vented units economically obsolete for replacement cycles.
- Ventless:Condenser and heat pump configurations eliminate external ducting requirements, using closed air circulation with moisture extraction via condensation or refrigeration. Apartment installations in Tokyo, New York, and London specify these units where structural constraints prohibit vent penetration through exterior walls.
- Vented:Traditional ducted exhaust systems expel moist air directly outside through rigid or flexible metal piping. These units retain cost advantages in North American suburban housing with legacy vent infrastructure.
- Compact:Reduced-capacity units under 4.0 cubic feet designed for space-constrained installations in urban apartments and recreational vehicles. Japanese and South Korean manufacturers dominate this specification tier.
Vented units anchor the volume base in North American replacement markets while heat pump configurations gain share at the steepest rate across European regulatory jurisdictions.
End User:
Cost tier differentiation separates capital-light residential purchasers from commercial buyers calculating total cost of ownership across high-cycle utilization.
- Residential:Single-family and multifamily household installations drive replacement demand on ten-to-fifteen-year cycles, with purchasing decisions dominated by upfront acquisition cost and space constraints rather than energy economics.
- Commercial:On-premise laundromats, multi-housing laundry rooms, and institutional facilities operate equipment through continuous daily cycles where energy efficiency and durability specifications override initial price sensitivity.
- Industrial:Textile processing, manufacturing, and bulk laundry operations requiring specialized heavy-duty configurations with drum capacities exceeding residential units by factors of five-to-ten.
- Hospitality:Hotels and extended-stay properties balance guest convenience against housekeeping throughput requirements, increasingly specifying heat pump units to meet corporate sustainability mandates.
Residential installations anchor the volume base while commercial applications gain share at the steepest rate as energy cost accounting penetrates procurement criteria.
Technology:
Margin concentration follows the intelligence gradient from connected platforms toward commodity mechanical systems with eroding differentiation headroom.
- Smart:Sensor-integrated dryers communicate with utility demand-response networks and home automation systems, enabling time-of-use optimization and predictive maintenance alerts. California and South Korean rebate programs accelerate specification of AMI-connected units.
- Energy Efficient:ENERGY STAR-certified and EU A+++ rated systems incorporating heat pump cycles, inverter compressors, and advanced insulation packages to minimize per-cycle consumption.
- Conventional:Electromechanical timer-based and basic moisture-sensor configurations without network connectivity or variable-speed drives. These units face margin compression as efficiency regulations tighten minimum thresholds.
- Hybrid:Dual-mode systems combining heat pump efficiency with supplemental resistance heating for rapid cycle completion, bridging performance gaps in cold-ambient conditions.
Conventional technology anchors the volume base in price-sensitive replacement markets while smart configurations gain share at the steepest rate through utility incentive programs.
Installation Type:
Supply concentration in cabinet and control system manufacturing favors integrated producers over assembly-dependent competitors lacking captive metal fabrication.
- Free-standing:Self-supporting units with finished panels designed for flexible placement within utility rooms or closets, representing the default configuration for North American residential markets.
- Stackable:Front-loading designs engineered for vertical pairing with matching washers, maximizing floor space efficiency in urban apartments and commercial laundry rooms.
- Built-in:Panel-ready units integrated behind custom cabinetry to match kitchen or laundry room aesthetics, prevalent in European premium residential construction.
- Under-counter:Reduced-height configurations fitting beneath standard work surfaces, specified for compact European kitchens and North American multi-housing common areas.
Free-standing configurations anchor the volume base in suburban North American housing while stackable units gain share at the steepest rate through urban densification trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in tumble dryers tilt toward manufacturing concentration in East Asia and Germany, with the United States and Japan absorbing premium heat pump units while emerging markets import entry-level ventless configurations. Trade balances reflect divergent regulatory stringency and housing stock age across destination markets.
Germany
Replacement demand for A+++ rated heat pump units accelerates as EU Ecodesign mandates render vented models economically obsolete. The F-Gas Regulation compels OEMs to retool production lines around R290 propane refrigerants before certification deadlines. Manufacturing clusters in North Rhine-Westphalia and Bavaria anchor European heat pump engineering capabilities.
United States
Suburban housing with legacy 240V infrastructure sustains vented dryer replacement cycles, while urban multifamily construction in New York and Los Angeles specifies ventless condenser units. ENERGY STAR certification thresholds tighten under EPA guidance, pushing rebate programs toward heat pump adoption. Southeast regional utilities lag in incentive alignment, preserving conventional unit dominance.
Japan
Tokyo apartment densification drives compact heat pump specification where external venting is structurally prohibited. METI's Top Runner program benchmarks efficiency against best-in-class performance, accelerating inverter compressor deployment. Osaka-Kansai industrial corridors concentrate component manufacturing for domestic OEM supply.
China
Urban residential electrification in Shanghai and Shenzhen creates first-time dryer demand as apartment ownership rates climb. GB standards for energy efficiency remain less stringent than EU or Japanese benchmarks, preserving cost-competitive vented unit production. Yangtze River Delta manufacturing bases supply export markets with entry-level configurations.
India
Mumbai and Bangalore apartment construction specifies ventless units to bypass infrastructure constraints in older buildings. Bureau of Indian Standards certification requirements lag European efficiency mandates, limiting heat pump penetration to premium segments. Gujarat industrial corridors attract component assembly investments serving domestic replacement cycles.
Tumble Dryer Market Vendor Landscape
Concentration sits with integrated manufacturers possessing captive compressor and heat exchanger production, while assembly-dependent competitors face margin compression from refrigerant supply bottlenecks. Market structure divides between premium engineering specialists and scale-driven diversified appliance conglomerates. Two archetypes dominate: European heat pump engineering houses and East Asian electronics conglomerates extending semiconductor platforms into smart drying cycles. Competitive moves center on refrigerant architecture retooling and utility partnership formations for demand-response program qualification.
Within the integrated manufacturing tier, Electrolux and Whirlpool occupy positions anchored by captive component production across European and North American plants. Samsung Electronics exemplifies the platform-extension archetype, leveraging semiconductor-controlled sensor architectures into connected-home ecosystems. Miele represents the premium engineering specialist, concentrating heat pump refinement for high-cycle durability specifications. These three anchors illustrate how competitive positioning fragments across technical specialization versus scale economies versus smart home integration vectors.
| Leading Market Players |
|---|
| Electrolux |
| Haier Electronics Group |
| Whirlpool |
| Speed Queen |
| Miele |
| LG Electronics |
| Bosch |
| Pellerin Milnor |
| Samsung Electronics |
| Others |
Supply Flow & Price Mechanics
Long-term component offtake contracts between German compressor manufacturers and European OEMs lock in refrigerant circuit supply while fixing input cost visibility across multi-year procurement horizons. These arrangements insulate integrated producers from London Metal Exchange volatility while exposing assembly-dependent competitors to spot-market aluminum and copper swings.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Pricing stratifies across ENERGY STAR certification tiers, with A+++ rated heat pump units commanding substantial premiums over conventional resistance-heated alternatives. Cost compression in economy-tier vented units is intensifying because Chinese manufacturers are flooding export markets with undifferentiated configurations. Residential replacement purchasers exhibit highest price sensitivity, while commercial laundry operators prioritize total cost of ownership over upfront acquisition.
Supply Chain Analysis
Port congestion along the Yangtze River Delta-to-Rotterdam lane disrupts containerized shipments of compact dryer assemblies from Chinese contract manufacturers. Manufacturing gravity centers on China, Germany, and South Korea, with production drawing from specialty compressor fabrication in Japan and precision heat exchanger stamping in Italy. Single-source vulnerability concentrates in R290 propane compressor supply from Osaka-Kansai industrial corridors. Distribution runs through big-box retail chains in North America and specialized appliance dealers across European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as regulatory divergence between EU Ecodesign jurisdictions and lagging markets creates incompatible technical specifications. Urban housing densification across Tokyo, New York, and London generates niche demand for ventless configurations that resist commoditization.
For Market Incumbents: Secure captive heat pump compressor production through backward integration into Japanese or German component suppliers before F-Gas Regulation deadlines tighten. Anchor European market position by accelerating R290 refrigerant certification investments ahead of 2027 compliance thresholds.
For New Entrants and Emerging Players: Lead with smart-grid-integrated dryers targeting California and South Korean utility rebate programs where AMI connectivity qualifies for time-of-use rate discounts. Penetrate India's Mumbai and Bangalore apartment markets through ventless configurations that bypass legacy building infrastructure constraints.
For Investors and Strategic Acquirers: Component-captive mid-tier OEMs with established service networks represent prime acquisition targets as appliance-as-a-service contracting shifts procurement toward operating expenditure models. Monitor IEC 60335-2-43 certification completion rates as inflection indicator for refrigerant safety compliance readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Architecture Retooling | R290 propane system redesign secures EU market access under F-Gas Regulation phasedown schedules. |
| Smart Grid Integration | AMI-connected dryers qualify for California utility demand-response rebate programs. |
| Backward Integration into Compressors | Captive component production insulates margin structures from Japanese supplier concentration. |
| Appliance-as-a-Service Launch | Leasing models with bundled maintenance penetrate Netherlands multifamily housing procurement. |
| India Market Entry | Ventless configurations address Mumbai apartment infrastructure constraints for first-time dryer demand. |
Methodological Framework
Operator-level perspectives from plant engineers at OEM manufacturing facilities, procurement leads at commercial laundry operators, aftermarket service technicians, and utility demand-response program managers anchored the qualitative base. Primary fieldwork combined with secondary validation from SEC 10-K filings, EU Ecodesign regulatory texts, ENERGY STAR certification databases, and customs trade records. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Sensitivity analysis tested forecast robustness across refrigerant phase-down acceleration scenarios and copper price volatility bands throughout the projection horizon. Segmentation modeling incorporated product type, end-use application, technology tier, and installation configuration dimensions. CAGRs derived from regression analysis of historical replacement cycles against regulatory mandate timelines, with heat pump adoption curves calibrated to EU Ecodesign efficiency threshold trajectories.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated Kigali Amendment implementation would require recalibration. Forecasts reflect assumptions regarding technician certification availability for flammable refrigerant handling and utility rebate program continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
GCC Microwave Oven Market
Appliances
Saudi Arabia Gas Hobs Market
Appliances
Hairdryer Market
Appliances
AI Washing Machine Market
Appliances
Colombia Laundry Appliances Market
Appliances
Germany Consumer Appliances Market
Appliances
Bahrain Dishwashers Market
Appliances
Water Heater Market
Appliances
Cooler Connected to the Mains Market
Appliances
North America Microwave Oven Market
Appliances
Europe Garment Steamers Market
Appliances
Space Heaters Market
Appliances
Electric Iron Market
Appliances
China Induction Hobs Market
Appliances
Fully Automatic Dishwasher Market
Appliances
Clothing Iron Market