
 Smart Microwave Oven Market | 2026-2036
Smart Microwave Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Microwave Oven Market Insights
The EU Ecodesign for Energy-Related Products Directive is pivoting smart microwave oven procurement across European retail channels. Whirlpool leverages its in-house appliance connectivity platform to sustain market presence in North America. Panasonic anchors its position through sensor cooking R&D intensity across Asian manufacturing bases. Bosch differentiates via energy-efficient built-in configurations aligned with CE marking requirements.
A smart microwave oven integrates semiconductor-based magnetron control, Wi-Fi or Bluetooth communication modules, and voice recognition processors to enable remote operation, automated cooking programs, and energy management. Countertop units dominate unit volumes in residential settings, while built-in configurations command premium positioning in kitchen renovation projects. Wi-Fi-enabled models lead technology penetration as households prioritize smartphone integration, though voice control interfaces represent the fastest-expanding interface category among food service operators seeking hands-free kitchen workflows.
The EU Ecodesign Directive and CE marking framework shape product efficiency thresholds and market access conditions for manufacturers serving European households. The FCC governs wireless communication certifications for Wi-Fi and Bluetooth modules in units distributed across the United States. Stakeholders must monitor evolving interoperability standards between appliance OEMs and smart home platforms as the primary determinant of competitive defensibility.
Market Dynamics
Smart microwave oven procurement pivots on interoperability standards between appliance OEMs and smart home platforms, with FCC wireless certification requirements and EU Ecodesign Directive efficiency thresholds creating divergent product development tracks for North American and European households.
Growth Catalysts
- EU Ecodesign Directive:Tightening standby power limits under the Energy-Related Products framework accelerate replacement cycles across German, French, and Italian residential channels.
- Sensor cooking R&D:Semiconductor-based magnetron control systems enable automated cooking programs that reduce user intervention and expand addressable user bases.
- Voice recognition processors:Food service operators in the United States deploy hands-free kitchen workflows, compressing adoption timelines for voice control interfaces.
Market Restraints
- Magnetron supply concentration:Specialty semiconductor foundries in East Asia control critical magnetron control chip production, exposing OEMs to single-source risk.
- FCC certification timelines:Wi-Fi and Bluetooth module approvals for United States distribution extend product launch windows by four to six months.
- Built-in configuration costs:Kitchen renovation project integration requires specialized installation labor and custom cabinetry, limiting volume scalability.
Strategic Opportunities
- CE marking alignment:Energy-efficient built-in configurations that exceed EU efficiency thresholds capture premium positioning in kitchen renovation projects across Germany and France.
- Bluetooth Low Energy convergence:Mesh networking protocols paired with smartphone integration create entry points for households without Wi-Fi infrastructure.
- Smart home platform interoperability:Native integration with Amazon Alexa and Google Home ecosystems unlocks replacement demand in United States residential channels.
Industry Challenges
- RF engineering talent scarcity:Wi-Fi and Bluetooth module integration requires specialized electromagnetic compatibility expertise that appliance OEMs lack in-house.
- Legacy kitchen infrastructure:Existing electrical and spatial configurations in European residential stock complicate built-in microwave retrofit installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Microwave Oven Market |
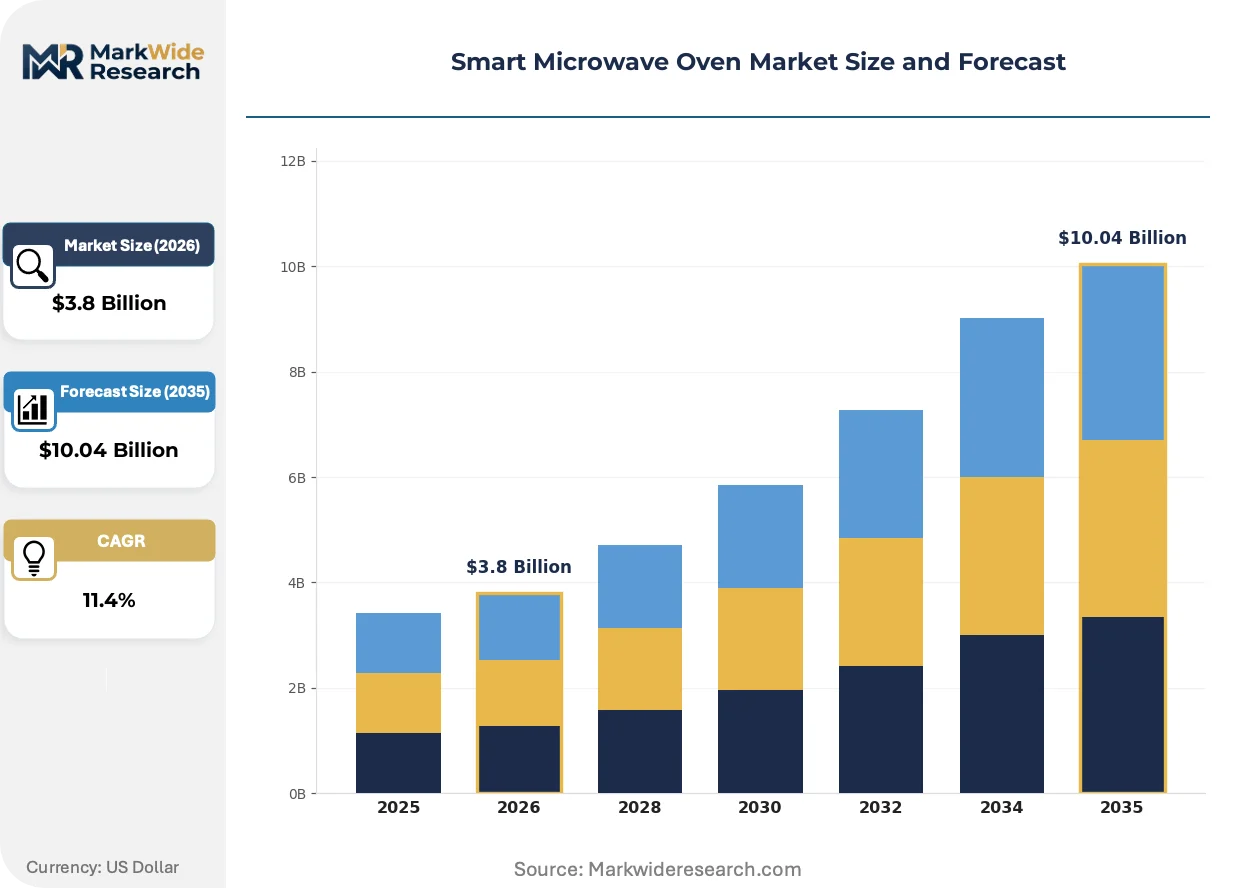
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Built-in, Over-the-Range, Drawer Technology: Wi-Fi, Bluetooth, Voice Control, Sensor Cooking Application: Residential, Commercial, Food Service, Hospitality End User: Households, Restaurants, Catering Services, Institutions |
| Companies Covered | Toshiba, Whirlpool, Panasonic, Sharp, Bosch, LG, GE, Thermador, Breville, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Microwave Oven Market Trends and Innovations
Magnetron control architectures and wireless communication modules are fragmenting into interchangeable subsystems, enabling appliance OEMs to source components from specialized semiconductor vendors rather than maintaining captive manufacturing.
Semiconductor-based magnetron control is modularizing the power management subsystem into discrete, firmware-upgradable components. Residential buyers in Germany and France now expect over-the-air cooking algorithm updates. This modularity compresses hardware refresh cycles while extending product lifespans through software-defined functionality.
REACH substance restrictions and RoHS compliance mandates in Europe are eliminating legacy solder materials and flame retardants from printed circuit board assemblies. Manufacturers serving EU households must redesign Wi-Fi module substrates to meet substance thresholds. Asian contract manufacturers are consolidating qualified material suppliers to maintain CE marking access.
Households now prioritize smartphone-native control interfaces over proprietary appliance apps, forcing OEMs to abandon closed ecosystems. United States retail channels are responding by bundling smart microwave ovens with smart home platform subscriptions. This unbundling of hardware from software services concentrates purchasing power with platform operators in North American markets.
Smart Microwave Oven Market Segmentation
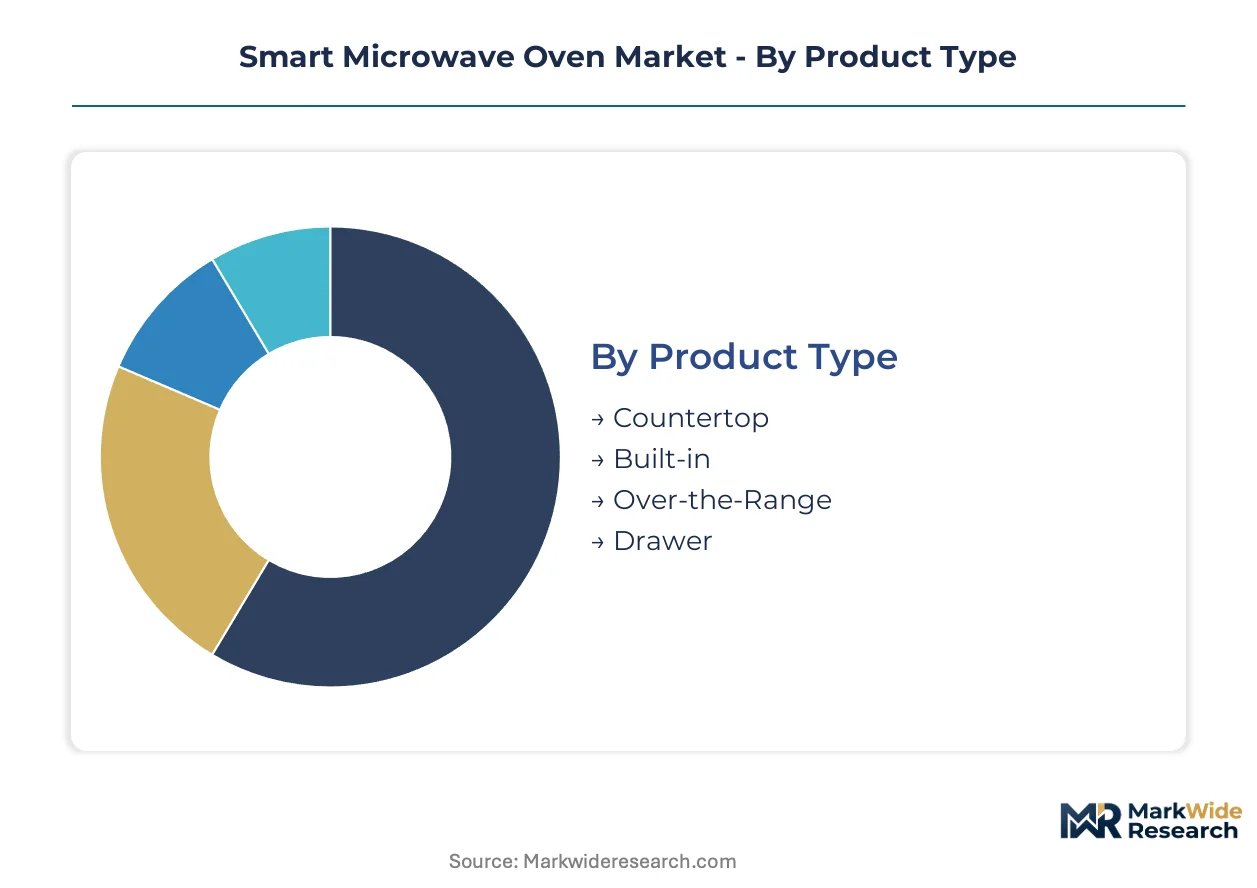
Smart microwave oven segmentation reveals divergent hardware requirements between retrofit-friendly standalone installations and architecturally integrated embedded systems. The four-dimensional segmentation framework—product type, technology, application, and end user—exposes how procurement criteria shift from consumer convenience metrics to commercial durability specifications.
Product Type:
Integration depth varies sharply: countertop and over-the-range units function as standalone appliances with minimal installation dependencies, while built-in and drawer configurations demand custom cabinetry and electrical planning.
- Countertop:Freestanding units with plug-and-play electrical requirements dominate unit shipments in residential replacement cycles. Demand concentrates in United States apartment rentals and German urban households where kitchen renovation permissions remain restricted.
- Built-in:Architecturally integrated units requiring custom millwork and dedicated ventilation channels command premium positioning in kitchen renovation projects. CE marking alignment for energy efficiency unlocks access to French and German premium retail channels where EU Ecodesign Directive thresholds filter non-compliant inventory.
- Over-the-Range:Space-consolidating units combining microwave function with range ventilation suit compact kitchen footprints in Japanese metropolitan apartments and United Kingdom terrace housing.
- Drawer:Ergonomically oriented pull-out configurations reduce bending requirements and capture aging-in-place renovation demand in Australian and Canadian suburban markets.
Volume placements concentrate in Countertop; the faster expansion belongs to Built-in.
Technology:
Connectivity sophistication stratifies procurement budgets, with wireless communication modules adding hardware cost and certification complexity that scales with protocol bandwidth and security requirements.
- Wi-Fi:High-bandwidth modules enabling cloud-based recipe synchronization and remote diagnostics require FCC certification in United States distribution and impose four-to-six-month approval timelines. Residential buyers prioritize smartphone-native control interfaces, forcing OEMs to abandon proprietary app ecosystems.
- Bluetooth:Low-energy mesh protocols create entry points for households lacking Wi-Fi infrastructure and reduce electromagnetic compatibility engineering burdens for manufacturers targeting price-sensitive European markets.
- Voice Control:Hands-free interfaces expanding most quickly among United States food service operators seeking workflow efficiency in high-throughput kitchen environments.
- Sensor Cooking:Semiconductor-based magnetron control systems automate power modulation based on moisture detection and thermal feedback, reducing user intervention in Japanese and South Korean residential channels.
Volume placements concentrate in Wi-Fi; the steepest expansion trajectory belongs to Voice Control.
Application:
Duty cycle intensity and regulatory exposure differentiate procurement specifications, with commercial environments demanding NSF sanitation compliance and continuous-duty electrical ratings absent from residential certifications.
- Residential:Intermittent-use appliances governed by consumer warranty terms and energy labeling requirements concentrate demand in United States single-family home replacement cycles and German efficiency-driven upgrade patterns.
- Commercial:High-cycle environments including corporate cafeterias and convenience stores require stainless steel construction and rapid-cook magnetron configurations that sustain throughput under continuous operation.
- Food Service:Quick-service restaurants and institutional kitchens prioritize voice control integration and automated cooking programs to compress labor training timelines and reduce operator error.
- Hospitality:In-room appliance specifications for hotels and extended-stay properties balance aesthetic integration with liability-minimizing safety interlocks and simplified user interfaces.
Volume placements concentrate in Residential; the fastest share gain belongs to Food Service.
End User:
Purchasing authority and total cost of ownership calculations diverge sharply between individual household decision-makers and procurement departments managing fleet deployments across distributed locations.
- Households:Individual buyers prioritize smart home platform interoperability and over-the-air update capabilities, with Amazon Alexa and Google Home integration unlocking replacement demand in North American retail channels.
- Restaurants:Independent and chain operators negotiate volume pricing through food service distributors and demand modular magnetron architectures that minimize field service downtime.
- Catering Services:Mobile and event-based food preparation requires portable power configurations and rapid-deployment installation standards distinct from fixed-location appliances.
- Institutions:School districts, hospitals, and government facilities impose public procurement regulations and extended warranty requirements that favor established OEMs with bonded service networks.
Volume placements concentrate in Households; the climbing demand belongs to Restaurants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in East Asian electronics clusters while consumption tilts toward North American and Western European residential replacement cycles. Regulatory divergence between FCC certification requirements and EU Ecodesign efficiency thresholds forces parallel product development tracks.
United States
Smart home platform integration drives replacement demand across single-family suburban households and apartment rental markets. FCC wireless certification timelines for Wi-Fi and Bluetooth modules extend product launch windows by four to six months. California and Texas metropolitan areas concentrate early adoption of voice control interfaces among food service operators seeking hands-free kitchen workflows.
Germany
EU Ecodesign Directive standby power limits accelerate upgrade cycles in urban residential channels where kitchen renovation permissions remain restricted. CE marking alignment filters non-compliant inventory from premium retail channels. Bavaria and North Rhine-Westphalia anchor demand for energy-efficient built-in configurations in kitchen renovation projects.
China
Domestic production of semiconductor-based magnetron control systems supplies global OEM assembly networks. GB standards and MIIT wireless certification frameworks govern module integration for both export and domestic distribution. Yangtze River Delta and Pearl River Delta electronics clusters concentrate contract manufacturing for Wi-Fi module substrates.
Japan
Sensor cooking R&D intensity sustains competitive positioning in automated power modulation technologies. METI energy labeling requirements shape product efficiency benchmarks for residential channels. Kanto and Kansai metropolitan markets concentrate demand for compact over-the-range units in space-constrained apartment housing.
France
REACH substance restrictions and RoHS compliance mandates eliminate legacy materials from printed circuit board assemblies. Energy-efficient built-in configurations command premium positioning in kitchen renovation projects. Île-de-France and Auvergne-Rhône-Alpes concentrate retail distribution for CE-marked appliances exceeding EU efficiency thresholds.
Smart Microwave Oven Market Competitive Landscape
The competitive structure tilts toward diversified appliance conglomerates with captive connectivity platforms. Market concentration remains moderate, with tiered positioning across premium built-in, mass-market countertop, and commercial food service segments. Three archetypes dominate: diversified home appliance OEMs with smart home ecosystem integration, specialized cooking equipment manufacturers with sensor technology depth, and electronics conglomerates leveraging semiconductor supply chain control. Capacity expansion in East Asian manufacturing clusters and strategic partnerships with smart home platform operators constitute the primary competitive moves.
Among diversified appliance OEMs, Whirlpool Corporation and Panasonic Corporation exemplify contrasting strategic positions. Whirlpool leverages its in-house appliance connectivity platform to sustain presence in North American residential channels. Panasonic anchors its competitive stance through manufacturing base concentration in Asian electronics clusters. Bosch GmbH occupies a distinct tier within European markets, differentiated by alignment with CE marking requirements and energy-efficient built-in configurations. These three entities collectively represent the archetype spectrum spanning platform integration, component supply chain depth, and regulatory compliance positioning.
| Leading Market Players |
|---|
| Toshiba |
| Whirlpool |
| Panasonic |
| Sharp |
| Bosch |
| LG |
| GE |
| Thermador |
| Breville |
| Others |
Pricing and Supply Chain Analysis
Mass-market OEM procurement departments concentrate purchasing power through volume commitments to contract manufacturers, locking in three-tier pricing structures across premium, standard, and economy levels. This buyer consolidation shapes margin distribution between semiconductor vendors and final assembly houses.
Pricing Analysis
Margin tightening in built-in configurations reflects CE marking compliance costs and specialized installation labor requirements. Price differentiation hinges on certification grade and after-sales service bundling. Cost-down pressure on countertop units accelerates because Wi-Fi module commoditization compresses hardware margins. Food service operators show least price sensitivity due to labor-cost savings from voice control integration.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for Wi-Fi and Bluetooth modules, bypassing distributor markups for tier-one appliance manufacturers. Manufacturing concentrates in China, South Korea, and Taiwan for semiconductor-based magnetron control systems. Raw material dependencies include rare earth magnets, high-frequency PCB substrates, and flame-retardant resins. Single-source vulnerability in East Asian foundry capacity exposes OEMs to allocation risk. Distribution runs through electronics manufacturing service providers with captive component sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty semiconductor foundry capacity constraints prop pricing power for magnetron control chip vendors, sustaining margin structures despite module commoditization elsewhere.
For Market Incumbents: To counter voice control interface commoditization by platform operators, deepen captive connectivity platform development and secure FCC pre-certification for module families. Prioritize backward integration into sensor cooking algorithm IP to defend differentiation against Asian contract manufacturers. For New Entrants and Emerging Players: Begin with Bluetooth Low Energy mesh configurations targeting German and French rental housing markets lacking Wi-Fi infrastructure. White-space exists in over-the-range units for Japanese metropolitan apartments. Pursue private-label partnerships with European kitchen renovation contractors as primary go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor semiconductor vendors with qualified CE marking substrates in Yangtze River Delta manufacturing clusters. Long-term viability centers on firmware-upgradable magnetron architectures extending replacement cycles. Monitor FCC certification backlog duration as inflection indicator for North American launch velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native Alexa and Google Home compatibility unlocks United States replacement demand cycles. |
| Backward Integration | In-house magnetron control chip production reduces single-source exposure to East Asian foundries. |
| CE Marking Pathway | EU Ecodesign Directive alignment filters non-compliant inventory from German premium retail channels. |
| Geographic Expansion | Bavaria and North Rhine-Westphalia concentrate demand for energy-efficient built-in configurations. |
| Strategic Partnership | Food service distributor alliances compress voice control adoption timelines among restaurant chains. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with appliance OEM product managers, semiconductor vendor sales engineers, FCC certification consultants, and European kitchen renovation contractors validated demand assumptions. Secondary sources included FCC equipment authorization databases, EU Ecodesign Directive compliance registries, and East Asian electronics cluster export statistics. Bottom-up unit shipment estimates triangulated against top-down consumer electronics spending patterns.
Reconciliation of production volume data from Yangtze River Delta contract manufacturers with United States import records established baseline calibration. Segmentation modeling spanned product type, connectivity technology, application intensity, and end-user purchasing authority across the projection horizon. CAGRs derived from fitted growth curves incorporating replacement cycle acceleration and smart home platform penetration rates. Sensor cooking R&D intensity and voice control processor adoption curves served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; residential countertop shipments carry tighter precision than commercial food service deployments. Forecasts reflect documented assumptions regarding interoperability standard convergence and regulatory timeline adherence. Periodic stress-testing of base assumptions is recommended given magnetron supply concentration and evolving FCC certification procedures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
South Africa Laundry Appliances Market
Appliances
Intelligent Electric Rice Cooker Market
Appliances
Wall Oven Market
Appliances
Household Side by Side Refrigerator Market
Appliances
Europe Induction Hobs Market
Appliances
China Induction Hobs Market
Appliances
Smart Massage Appliances Market
Appliances
Dishwasher Market
Appliances
UAE Dishwasher Market
Appliances
Water Heater Market
Appliances
Japan Massage Equipment Market
Appliances
UK Residential Vacuum Cleaner Market
Appliances
Microwave Market
Appliances
United States Electric Kettle Market
Appliances
Israel Laundry Appliances Market
Appliances
Body Dryer Market