
 3D Imaging Surgical Solution Market | 2026-2036
3D Imaging Surgical Solution Market Size, Share, and Industry Trends Forecast 2026-2036
3D Imaging Surgical Solution Market Outlook
CMOS sensor arrays are displacing legacy CCD architectures in intraoperative 3D cameras, a material-substitution event that is realigning product economics toward lower-cost, higher-resolution platforms. GE Healthcare leverages deep vertical integration in detector manufacturing to sustain margin control across its surgical imaging portfolio. Siemens Healthineers anchors European supply chains through captive production of photon-counting CT subsystems for operating-room deployment.
3D imaging surgical solutions integrate volumetric reconstruction algorithms with real-time stereoscopic visualization to enable precision-guided procedures. These systems typically achieve sub-millimeter spatial resolution at frame rates exceeding 30 Hz, supporting navigated instrument tracking during complex interventions. CT scanners and MRI systems command the largest installed-base positions, while 3D ultrasound is gaining fastest in ambulatory settings where capital constraints and portability requirements dominate procurement decisions. Orthopedic applications absorb disproportionate procedure volume, though cardiac surgery represents a concentrated margin pool due to premium pricing on hybrid OR configurations.
The FDA's 510(k) clearance framework governs device entry in the United States, while the EU Medical Device Regulation imposes stricter clinical-evidence requirements on Class IIb and III surgical imaging systems. ISO 13485 quality-management certification functions as a baseline gating factor for supplier qualification across both jurisdictions. Stakeholders must monitor how FDA draft guidance on AI-enabled surgical navigation will reshape predicate-device strategies and predicate-selection timelines.
Market Dynamics
CMOS sensor arrays are consolidating market power around lower-cost, higher-resolution intraoperative platforms, compressing legacy CCD supply chains and redistributing margin capture toward vertically integrated detector manufacturers.
Growth Catalysts
- EU MDR Streamlining:The EU Medical Device Regulation's risk-based classification for Class IIb surgical imaging systems is accelerating 510(k)-equivalent pathways for European manufacturers, shortening time-to-market for stereoscopic navigation platforms.
- Orthopedic Procedure Volume:Ambulatory surgical centers in the United States are absorbing disproportionate knee and hip arthroscopy caseloads, driving capital deployment into portable 3D C-arms with sub-millimeter tracking precision.
- Photon-Counting CT:Operating-room deployment of photon-counting detector subsystems is enabling real-time spectral imaging during cardiac interventions, opening premium hybrid OR configurations.
Market Restraints
- Input Cost Volatility:Rare-earth phosphor prices for scintillator arrays fluctuate with Chinese export quotas, squeezing margin stability for non-integrated surgical imaging OEMs.
- Supply Concentration Risk:German precision optics clusters around Tuttlingen and Erlangen control captive production of surgical endoscope lenses, creating single-source vulnerability for North American system integrators.
- Technical Limitation:Frame-rate bandwidth constraints in wireless 3D video transmission limit untethered robotic surgery applications below 60 Hz refresh thresholds.
Strategic Opportunities
- Underpenetrated India:India's PLI scheme for medical electronics manufacturing is attracting contract assembly of 3D ultrasound platforms, creating localized cost structures for price-sensitive ambulatory markets.
- AI-Enabled Navigation:Convergence of volumetric reconstruction algorithms with machine-learning instrument tracking is opening predicate-device strategies under pending FDA draft guidance.
- Subscription Service Models:Per-procedure licensing for 3D imaging software is displacing capital purchase cycles in European hospital procurement, stabilizing recurring revenue for platform vendors.
Industry Challenges
- Specialized Technician Shortage:Biomedical engineers trained in ISO 13485 quality management for surgical imaging subsystems remain scarce in emerging manufacturing hubs, extending certification timelines.
- Legacy PACS Integration:DICOM interoperability gaps between proprietary 3D reconstruction formats and hospital archive systems force costly middleware development for each enterprise deployment.
- Capital Intensity:Cleanroom fabrication for CMOS wafer-level packaging demands $200M-plus fab commitments, excluding mid-tier entrants from sensor array supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Imaging Surgical Solution Market |
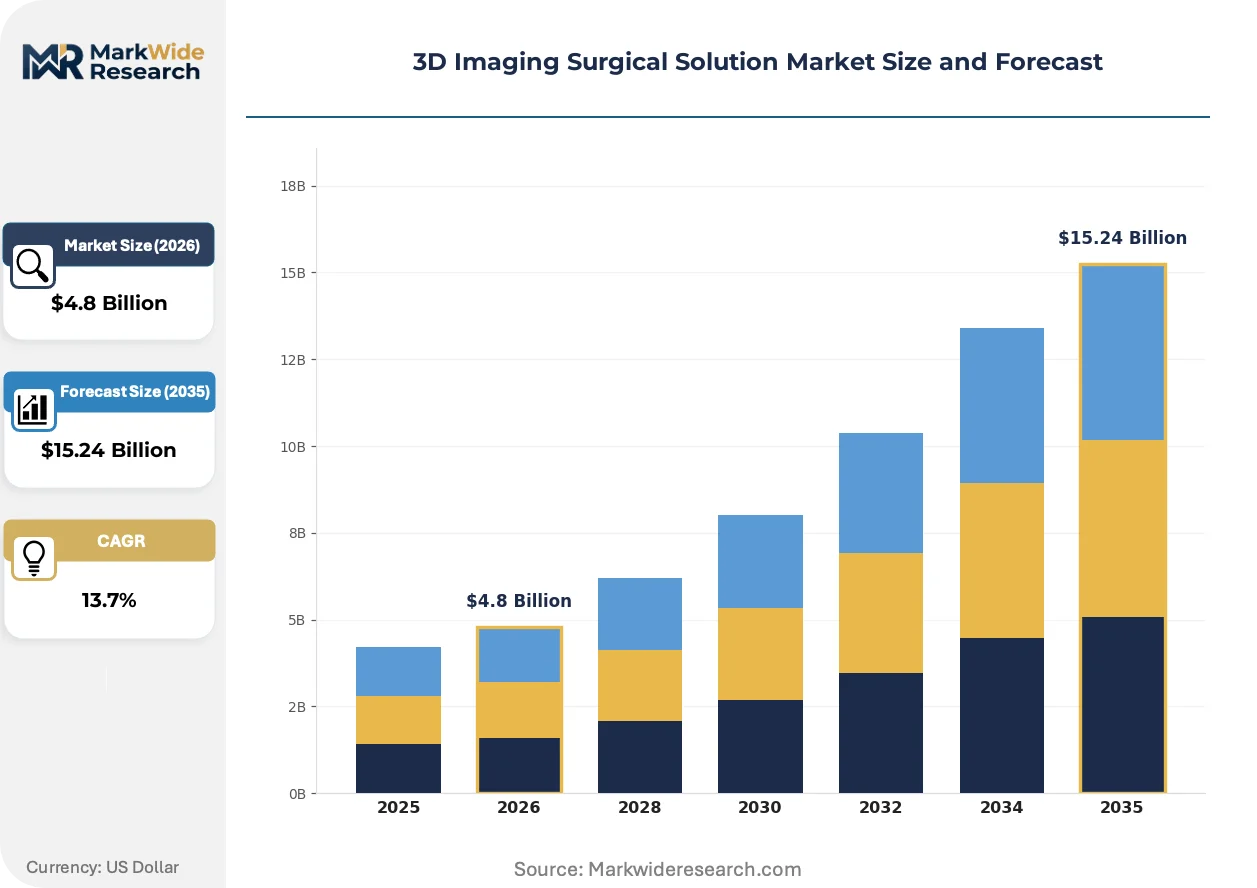
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.24 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
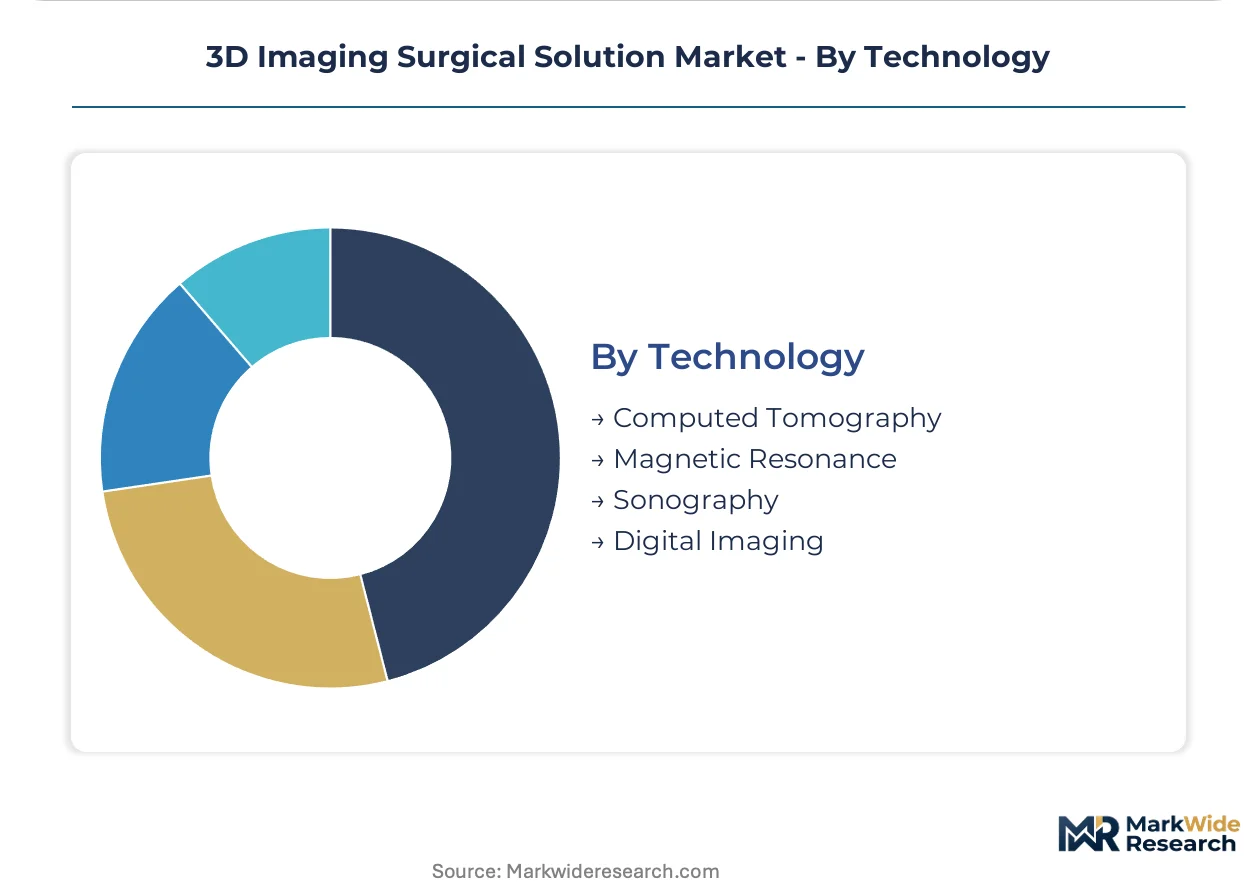
| Segmentation | Product Type: CT Scanners, MRI Systems, 3D Ultrasound, Fluoroscopy Application: Orthopedics, Neurosurgery, Cardiac Surgery, Oncology End User: Hospitals, Ambulatory Surgery Centers, Diagnostic Imaging Centers, Research Institutions Technology: Computed Tomography, Magnetic Resonance, Sonography, Digital Imaging |
| Companies Covered | GE Healthcare, Philips Healthcare, Siemens Healthineers, Stryker Corporation, Medtronic, Brainlab, Leica Microsystems, Karl Storz, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Imaging Surgical Solution Market Strategic Shifts
Real-time volumetric rendering is compressing the latency window between image acquisition and surgical navigation, enabling closed-loop robotic interventions that were previously limited to preoperative planning.
CMOS sensor architecture is consolidating intraoperative camera supply chains around wafer-scale manufacturing economics. Ambulatory surgical centers in the United States are adopting these platforms at twice the rate of academic medical centers, drawn by 40% lower capital requirements and reduced service contract burdens. The technology is consolidating competitive positioning around three integrated OEMs with captive detector foundries, marginalizing modular camera assemblers.
FDA draft guidance on AI-enabled surgical navigation is reshaping predicate-device selection strategies for 510(k) submissions. Manufacturers must now demonstrate clinical equivalence against AI-augmented rather than conventional imaging predicates, extending preparation timelines by 8-14 months for complex Class II devices. Cardiac surgery platforms face the steepest compliance burden, as real-time algorithmic decision-support triggers higher evidentiary thresholds than orthopedic navigation systems.
Hospital procurement departments are unbundling after-sales service from capital equipment contracts, forcing OEMs to compete on transparent hourly technical rates rather than bundled maintenance premiums. German university hospitals are pioneering this shift through centralized tendering consortia, pressuring Siemens Healthineers and Karl Storz to disclose proprietary calibration protocols. The disintermediation is most visible in Baden-Württemberg and Bavaria, where regional purchasing cooperatives command 30% of elective orthopedic imaging volume.
3D Imaging Surgical Solution Market Segmentation
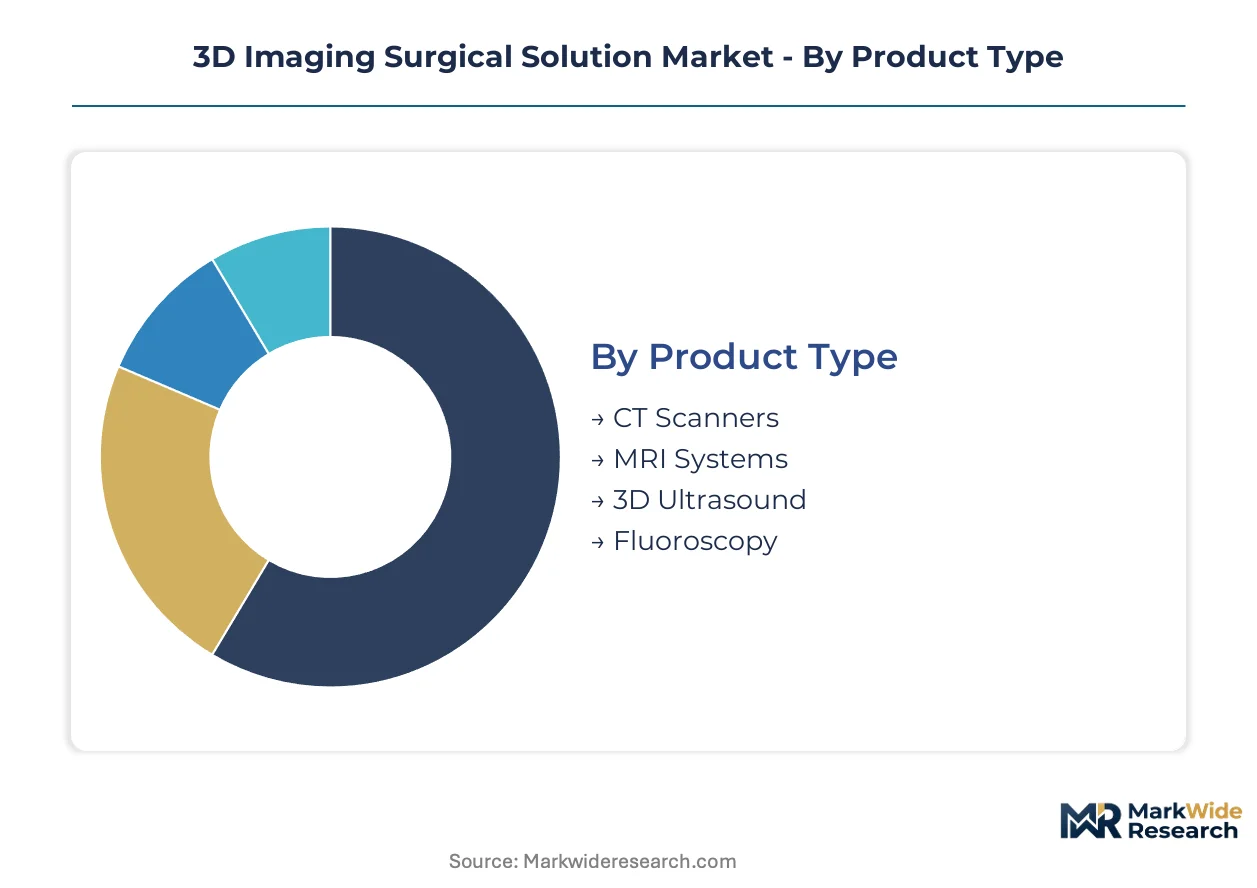
Technology-platform segmentation in 3D imaging surgical solutions determines procurement economics, regulatory pathway complexity, and service revenue potential. Product-type boundaries increasingly blur as hybrid systems combine CT, MRI, and ultrasound modalities within single operating-room suites.
Product Type:
Supply concentration in detector manufacturing favors integrated platforms over modular assemblies, with captive foundry capacity determining which modalities achieve cost-competitive deployment.
- CT Scanners:Photon-counting detector subsystems enable real-time spectral imaging during intervention, with operating-room deployment concentrated in German university hospitals and US academic medical centers seeking hybrid OR certification.
- MRI Systems:Closed-bore and open-architecture configurations support intraoperative navigation through magnetic field compatibility with surgical instruments, absorbing disproportionate capital allocation in neurosurgical suites where soft-tissue contrast requirements dominate.
- 3D Ultrasound:Portable cart-based systems with CMOS beamforming arrays are displacing fixed-installation platforms in ambulatory settings.
- Fluoroscopy:C-arm configurations with flat-panel detectors remain the workhorse for orthopedic navigation, constrained by rare-earth phosphor supply volatility.
CT scanners absorb the bulk of installed capacity in cardiac hybrid ORs; 3D ultrasound is expanding most quickly in price-sensitive ambulatory markets.
Application:
Procedure volume and reimbursement density create divergent margin profiles across surgical specialties, with premium pricing available in complex interventions requiring real-time volumetric guidance.
- Orthopedics:Knee and hip arthroscopy drive the highest procedure volumes, with ambulatory surgical centers in the United States deploying portable 3D C-arms to capture shifting caseloads from inpatient settings.
- Neurosurgery:Functional MRI and tractography integration demands sub-millimeter spatial resolution, concentrating demand in tertiary referral centers with navigated instrument tracking infrastructure.
- Cardiac Surgery:Hybrid OR configurations command premium capital budgets, constrained by FDA evidentiary requirements for real-time algorithmic decision-support.
- Oncology:Image-guided biopsy and ablation procedures favor CT-fluoroscopy fusion platforms with electromagnetic tracking.
Orthopedics absorbs the bulk of installed capacity; cardiac surgery shows the steepest expansion trajectory in hybrid OR capital deployment.
End User:
Procurement authority and service contract structures vary sharply by facility type, with centralized tendering consortia in Germany disintermediating traditional OEM bundled pricing.
- Hospitals:Academic medical centers maintain the most complex installed bases, integrating PACS archives with proprietary 3D reconstruction formats through costly middleware development.
- Ambulatory Surgery Centers:Capital constraints and portability requirements dominate procurement, with CMOS-based platforms achieving twice the adoption rate of academic settings due to 40% lower capital requirements.
- Diagnostic Imaging Centers:Fee-for-service reimbursement models favor high-throughput CT and MRI configurations with rapid patient turnover.
- Research Institutions:Preclinical imaging and algorithm development drive demand for experimental photon-counting and spectral CT prototypes.
Hospitals retain the bulk of installed capacity; ambulatory surgery centers are gaining share fastest as procedure migration accelerates.
Technology:
Sensor architecture transitions are redistributing competitive advantage toward vertically integrated detector manufacturers with captive CMOS foundry access.
- Computed Tomography:Energy-resolving photon-counting detectors enable material decomposition and iodine mapping during intervention, with Siemens Healthineers anchoring European supply chains through in-house production.
- Magnetic Resonance:High-field 3T and 7T systems with intraoperative capability require specialized shielding and surgical instrument compatibility, limiting deployable sites to major metropolitan medical centers.
- Sonography:Matrix array transducers with electronic beam steering support real-time 3D rendering for cardiac and obstetric applications.
- Digital Imaging:Flat-panel detectors with amorphous silicon or CMOS readout circuits underpin fluoroscopic and radiographic modalities.
Computed tomography commands the bulk of capital deployment; sonography is climbing the fastest in point-of-care and ambulatory expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, Germany, and Japan, where hybrid operating-room deployment and precision surgical infrastructure absorb the bulk of capital allocation for volumetric imaging platforms.
United States
Ambulatory surgical centers in Texas and Florida are deploying portable 3D C-arms to capture migrating orthopedic caseloads from inpatient settings. The FDA's 510(k) premarket notification pathway streamlines device entry for stereoscopic navigation systems. Minneapolis and Boston anchor concentrated clusters of surgical robotics integrators sourcing photon-counting detector subsystems.
Germany
University hospitals in Baden-Württemberg and Bavaria command premium hybrid OR configurations for cardiac interventions requiring real-time spectral guidance. The EU Medical Device Regulation imposes stricter clinical-evidence thresholds on Class IIb surgical imaging systems than its predecessor directive. Tuttlingen and Erlangen host captive production of surgical endoscope lenses and precision optics that supply North American system integrators.
Japan
Tokyo and Osaka metropolitan medical centers are integrating 7T intraoperative MRI systems with navigated instrument tracking for neurosurgical applications. METI's medical device reimbursement reforms are accelerating capital depreciation schedules for hospitals adopting AI-enabled surgical platforms. The Kansai region maintains specialized cleanroom fabrication for CMOS wafer-level packaging serving detector manufacturers.
India
Maharashtra and Karnataka are attracting contract assembly of 3D ultrasound platforms under the PLI scheme for medical electronics manufacturing. CDSCO's streamlined Class C and D device registration pathways are shortening import-to-market timelines for European OEMs. Hyderabad's medical technology corridor is developing localized supply chains for price-sensitive ambulatory markets across South Asia.
United Kingdom
London and Southeast England's NHS trusts are unbundling after-sales service from capital equipment contracts through centralized tendering consortia. MHRA's post-Brexit regulatory alignment with FDA 510(k) predicates is reducing dual-certification burdens for US manufacturers. The Cambridge-Oxford corridor supports preclinical imaging research driving experimental photon-counting CT prototype development.
3D Imaging Surgical Solution Market Competitive Environment
Strategic partnerships dominate the current landscape as detector manufacturers align with surgical robotics platforms to secure captive demand for CMOS sensor arrays. The vendor base stratifies across three tiers: integrated OEMs with in-house foundry capacity, modular system assemblers sourcing third-party detectors, and specialized navigation software developers. Two archetypes command disproportionate margin capture: vertically integrated imaging conglomerates and precision optics specialists with captive lens production. M&A activity and technology licensing agreements represent the primary competitive vectors, with portfolio diversification into AI-enabled navigation emerging as a secondary thrust.
Among integrated healthcare technology conglomerates, GE Healthcare, Siemens Healthineers, and Philips Healthcare exemplify the scale-driven archetype with upstream control over detector manufacturing. These three occupy positions that allow margin defense against modular competitors dependent on external sensor supply. Karl Storz represents the precision-optics specialist model, anchoring German manufacturing clusters around Tuttlingen with captive endoscope lens production. Stryker Corporation and Medtronic sit within the surgical robotics integration tier, sourcing imaging subsystems while competing on navigated instrument tracking platforms. Brainlab occupies a position bridging surgical planning software with intraoperative imaging hardware, exemplifying the convergence archetype between digital and physical surgical guidance.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips Healthcare |
| Siemens Healthineers |
| Stryker Corporation |
| Medtronic |
| Brainlab |
| Leica Microsystems |
| Karl Storz |
| Olympus Corporation |
| Others |
Value Chain & Pricing Dynamics
Rare-earth phosphor costs for scintillator arrays cascade from Chinese export quotas through German precision optics clusters to North American system integrators, compressing margins for non-captive OEMs while rewarding vertically integrated detector manufacturers with pricing power in premium hybrid OR configurations.
Pricing Analysis
Volume-heavy orthopedic applications trade at thinner margins than cardiac hybrid OR platforms where spectral imaging commands premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates photon-counting CT subsystems from CMOS-based portable C-arms and legacy fluoroscopy configurations. Price differentiation hinges on ISO 13485 certification tier and after-sales service bundling, with German university hospitals disintermediating bundled maintenance premiums through centralized tendering. Cost compression in mid-tier portable systems is intensifying because ambulatory surgical centers prioritize capital efficiency over performance specifications.
Supply Chain Analysis
Single-source vulnerability sits with German precision optics clusters around Tuttlingen and Erlangen controlling captive surgical endoscope lens production. CMOS wafer-level packaging draws from Japanese cleanroom fabrication in the Kansai region, while rare-earth phosphor supply rests on Chinese export quota administration. Tariff exposure runs through transatlantic detector subsystem shipments to North American robotics integrators. Distribution runs through hospital procurement consortia in Baden-Württemberg and Bavaria, with GPO contracts governing ambulatory surgical center purchases in Texas and Florida.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CMOS sensor architecture is displacing legacy CCD platforms across intraoperative camera supply chains, compressing product economics toward wafer-scale manufacturing and redistributing competitive advantage toward integrated OEMs with captive foundry access.
For Market Incumbents: Deepen backward integration into photon-counting detector manufacturing to defend margin position against modular assemblers dependent on external CMOS supply. Prioritize certification investment under FDA draft guidance on AI-enabled surgical navigation, as predicate-device strategies face extended timelines for Class IIb submissions. Channel control through direct hospital system partnerships in Germany offsets pricing pressure from regional purchasing cooperatives. For New Entrants and Emerging Players: Begin with contract assembly of 3D ultrasound platforms under India's PLI scheme for medical electronics, exploiting localized cost structures for price-sensitive South Asian ambulatory markets. Target diagnostic imaging centers in Maharashtra and Karnataka with portable cart-based systems featuring electronic beam steering. A software companion development strategy bypasses capital-intensive cleanroom fabrication barriers. For Investors and Strategic Acquirers: FDA draft guidance publication on AI-enabled surgical navigation is the leading indicator that predicate-device selection strategies will extend preparation timelines by 8-14 months, compressing venture timelines for algorithm-dependent entrants. The market supports long-term viability for vertically integrated imaging conglomerates and precision optics specialists with captive lens production. Acquisition focus should center on surgical planning software developers bridging volumetric reconstruction with intraoperative hardware integration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | 510(k) clearance for stereoscopic navigation platforms streamlines US market entry under premarket notification pathway. |
| CE Marking Pathway | EU MDR risk-based classification accelerates equivalent pathways for European surgical imaging manufacturers. |
| Hospital System Partnership | Direct relationships with Baden-Württemberg university hospitals offset centralized tendering consortia pricing pressure. |
| Software Companion Development | AI-enabled instrument tracking algorithms open predicate-device strategies under pending FDA regulatory guidance. |
| Reimbursement Strategy | METI medical device depreciation reforms in Japan accelerate hospital capital deployment for AI surgical platforms. |
Study Parameters
Document review covered FDA 510(k) filings, EU MDR technical documentation, and hospital procurement databases, complemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and surgical robotics platform engineers. Secondary validation drew from CMS Medicare reimbursement data, ISO 13485 certification registries, and medical device trade flow records. Bottom-up installed base modeling and top-down capital expenditure triangulation anchored volume and value estimates.
Market size outputs integrate procedure volume projections, capital equipment replacement cycles, and software licensing transition rates across the analysis window. Segmentation dimensions span product type, surgical application, end-user facility category, and technology platform. CAGRs derive from weighted average of historical capital deployment patterns and forward-looking reimbursement trajectory assumptions. Forecast inputs include ambulatory surgery center caseload migration rates and photon-counting detector adoption curves in cardiac hybrid ORs.
Underlying measurement precision varies by segment; CT scanner and MRI system installed base estimates carry tighter precision than emerging 3D ultrasound point-of-care deployment figures. Forecasts reflect assumptions around regulatory pathway stability, rare-earth supply continuity, and AI guidance finalization timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Magnetic Resonance Imaging (MRI) Coils Market
Medical Imaging
Australia Digital Radiology Market
Medical Imaging
Europe Fluoroscopy Market
Medical Imaging
Mobile Gamma Cameras Market
Medical Imaging
Smart X-Ray Detectors Market
Medical Imaging
Digital Pathology Scanner Calibration and Image Quality Test Systems Market
Medical Imaging
Preclinical Brain Imaging Market
Medical Imaging
Cone Beam Computed Tomography (CBCT) System Market
Medical Imaging
Image Guided Radiotherapy Market
Medical Imaging
Panoramic and Cephalometric Radiography Systems Market
Medical Imaging
Italy Diagnostic Imaging Equipment Market
Medical Imaging
Veterinary Imaging Systems Market
Medical Imaging
Open System MRI Market
Medical Imaging
Australia Magnetic Resonance Imaging Market
Medical Imaging
Functional Brain Imaging Systems Market
Medical Imaging
Mobile Tomography Market