
 Global Healthcare Data Storage Market | 2026-2036
Global Healthcare Data Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Global Healthcare Data Storage Market Foresight
ISO 27001 certification is reorganizing competitive access in healthcare data storage, as providers without accredited information security management systems face exclusion from procurement tenders at major hospital networks. Dell Technologies leverages its end-to-end infrastructure portfolio to anchor multi-site deployments across integrated delivery networks. IBM Corporation specializes in quantum-safe encryption layers for genomic data repositories, differentiating its offering against commodity cloud providers. Pure Storage competes on all-flash density for picture archiving and communication systems, sustaining sub-millisecond latency benchmarks that radiology departments require.
Healthcare data storage encompasses the systems, media, and software architectures designed to capture, retain, and retrieve patient information with 99.999% uptime availability and AES-256 encryption at rest. These infrastructures serve the primary commercial purpose of enabling real-time clinical decision support while satisfying legal retention periods that span decades for certain record categories. Cloud storage now leads deployment preference among mid-size hospitals seeking to offload capital intensity, yet hybrid storage captures the fastest expansion as organizations balance latency-sensitive imaging workloads against regulatory data-sovereignty constraints. Object storage architectures are displacing traditional file systems for unstructured genomic and telemedicine data streams, where flat namespaces and metadata-rich addressing improve retrieval efficiency across petabyte-scale repositories.
FDA 21 CFR Part 11 guidelines in the United States, combined with GDPR data-localization mandates in Europe and HIPAA security rule enforcement through the Office for Civil Rights, collectively elevate compliance infrastructure from cost center to competitive differentiator. The EU AI Act introduces additional algorithmic audit trails that storage platforms must preserve for clinical decision-support systems. Stakeholders must monitor how emerging interoperability frameworks from HL7 FHIR reshape data portability requirements and whether storage vendors can demonstrate lineage tracking without compromising retrieval performance.
Market Dynamics
Healthcare data storage architectures are bifurcating under the weight of divergent latency requirements—sub-millisecond imaging retrieval versus cold archival compliance—forcing infrastructure decisions that reshape vendor competitive positioning across hospital networks and research consortia.
Growth Catalysts
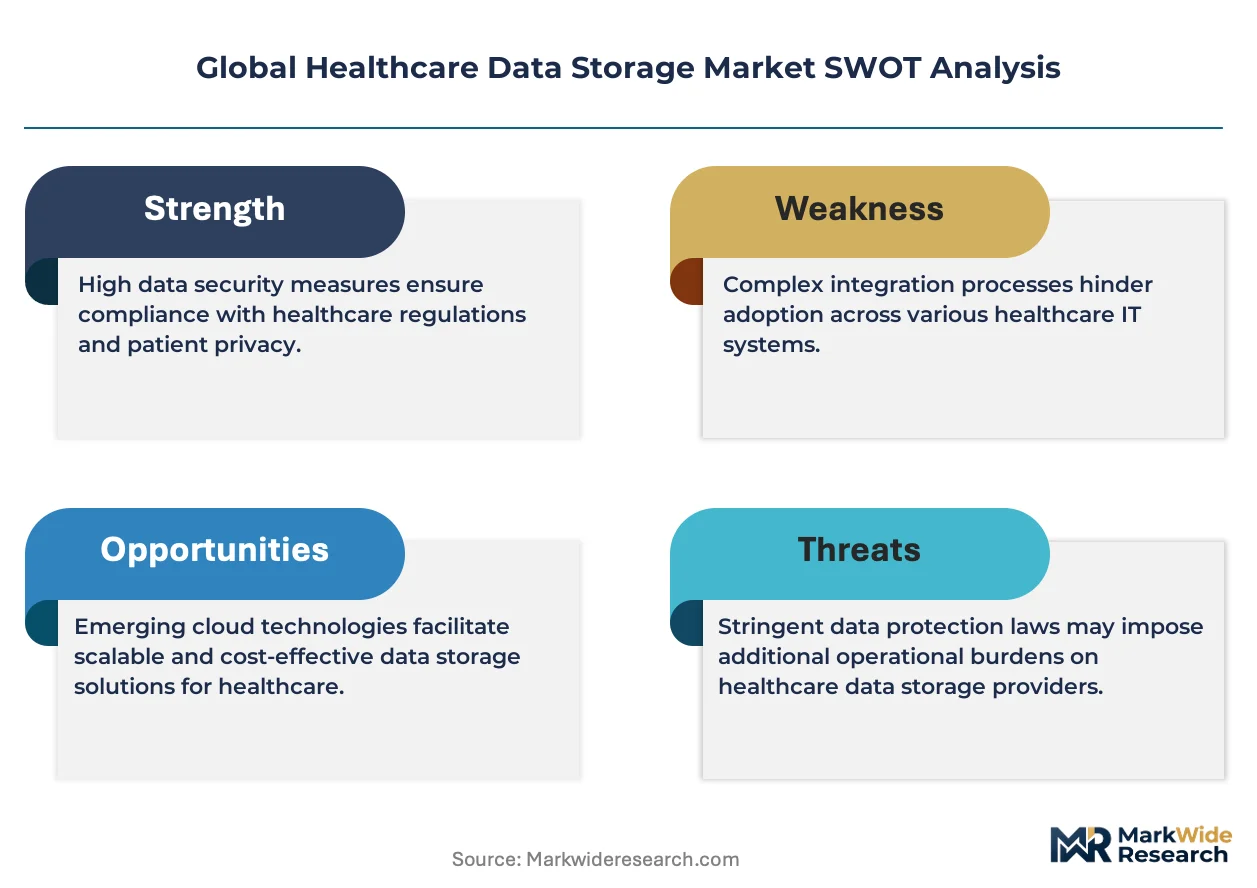
- EU AI Act algorithmic audit mandates:Clinical decision-support systems must preserve immutable data lineage, expanding storage platform requirements at academic medical centers and integrated delivery networks.
- Genomic data proliferation:Population-scale sequencing initiatives in research hospitals are generating petabyte-scale unstructured datasets that exceed traditional file system capacity.
- Hybrid cloud preference:Mid-size hospital systems balance capital expenditure relief against data sovereignty requirements, accelerating multi-environment deployment architectures.
Market Restraints
- Specialized engineering talent scarcity:Quantum-safe cryptography implementation and HIPAA technical safeguard configuration require skills concentrated at systems integrators and hyperscale cloud providers.
- Legacy infrastructure lock-in:Picture archiving systems running on proprietary hardware create migration friction that extends replacement cycles and defers cloud adoption.
- Input cost concentration:High-performance NAND flash supply concentrates among semiconductor foundries in Taiwan and South Korea, exposing storage array pricing to geographic supply risk.
Strategic Opportunities
- HL7 FHIR interoperability frameworks:Data portability mandates create demand for storage platforms with native API integration and semantic metadata tagging capabilities.
- Telemedicine data streams:Real-time video consultation archives require object storage architectures with intelligent tiering that incumbent file systems cannot deliver.
- India hospital digitization:Ayushman Bharat health mission infrastructure investments are expanding digital record requirements at district hospitals and primary health centers.
Industry Challenges
- ISO 27001 certification timelines:Hospital procurement tenders now require accredited information security management systems, disqualifying vendors with immature compliance programs.
- Interoperability integration complexity:Storage platforms must reconcile decades of heterogeneous electronic health record formats without disrupting clinical workflow continuity.
- Retention period management:Pediatric records, oncology trials, and implantable device files carry multi-decade legal mandates that exceed standard cloud lifecycle policy automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Healthcare Data Storage Market |
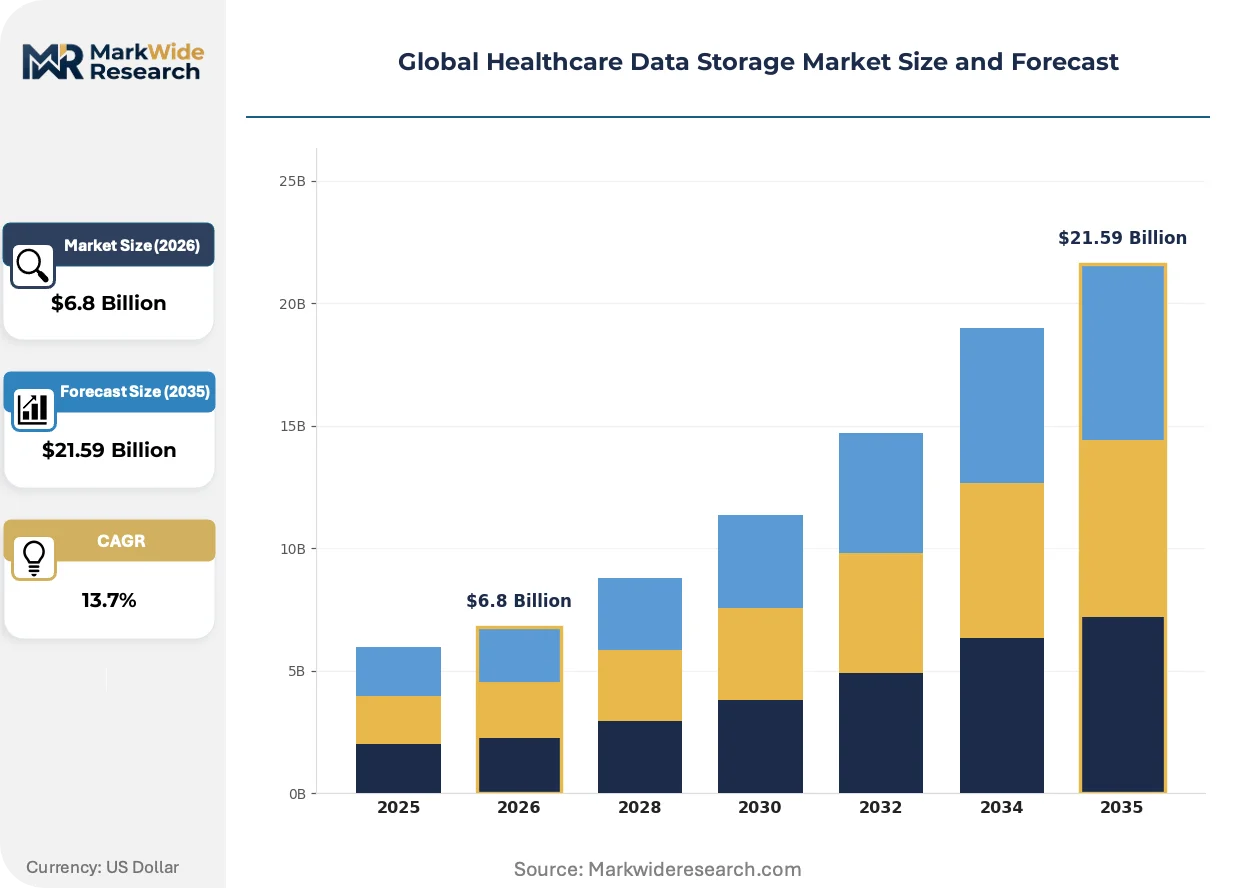
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $21.59 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Cloud Storage, On-Premise Storage, Hybrid Storage, Network Attached Storage, Direct Attached Storage Technology: Block Storage, File Storage, Object Storage, Tape Storage, Flash Storage, Optical Storage Application: Electronic Medical Records, Medical Imaging Archives, Genomic Data Repositories, Telemedicine Platforms, Research Databases End User: Hospitals, Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies, Health Insurance Providers |
| Companies Covered | Hewlett Packard Enterprise, Huawei Technologies, Dell Technologies, Hitachi, Fujitsu, IBM Corporation, Pure Storage, Western Digital, NetApp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Healthcare Data Storage Market Shifts & Advancements
Storage architecture evolution is compressing the gap between clinical performance requirements and regulatory compliance infrastructure, forcing technology convergence that redefines how hospital IT departments evaluate vendor proposals.
Object storage is bifurcating healthcare data management by separating hot imaging workloads from cold genomic archives within unified namespaces. Radiology departments at academic medical centers are adopting all-flash object arrays for sub-millisecond picture retrieval, while research biobanks exploit the same architecture's metadata richness for petabyte-scale sequence indexing. This technology is bifurcating vendor specialization—incumbent file-system suppliers face displacement by cloud-native platforms that span both performance tiers.
GDPR data-localization mandates combined with FDA 21 CFR Part 11 electronic record requirements are forcing storage vendors to architect region-specific sovereignty controls. European hospital networks must demonstrate physical data residency, while US clinical trial sponsors require audit trails that satisfy both jurisdictions. Multi-site pharmaceutical companies are responding by deploying federated storage fabrics that apply policy-driven data placement without sacrificing cross-border collaboration.
Subscription-based capacity planning is displacing capital-intensive procurement at mid-size hospital systems. Finance departments prefer operational expenditure models that align storage costs with patient volume fluctuations, while IT directors retain control over performance tiering. Germany's hospital digitization programs and US regional health information exchanges exhibit this shift most visibly, with five-year total-cost-of-ownership calculations now favoring managed service arrangements over on-premise ownership.
Global Healthcare Data Storage Market Segmentation
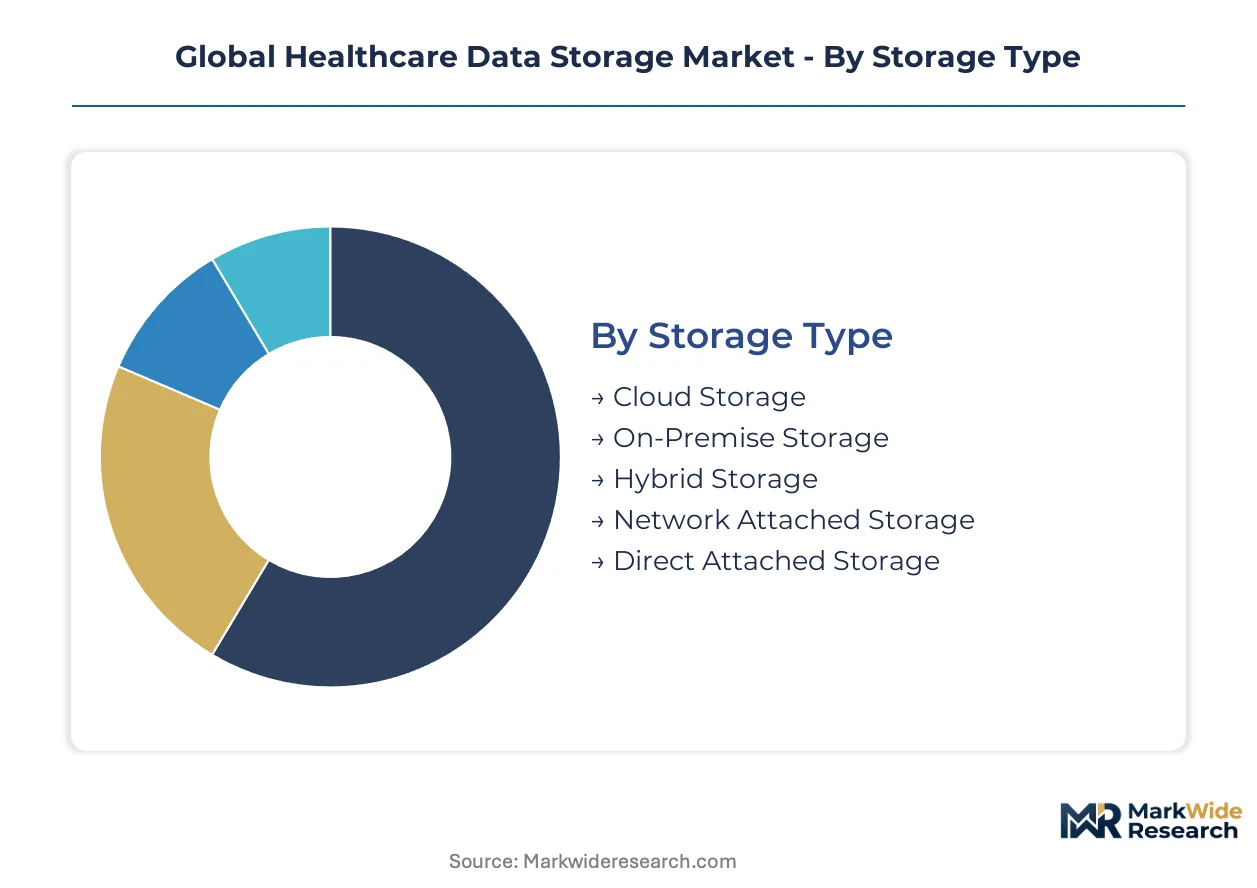
Healthcare data storage segmentation reveals how infrastructure choices bifurcate between latency-sensitive clinical workloads and compliance-heavy archival mandates. Storage procurement decisions increasingly hinge on whether organizations prioritize real-time retrieval performance or long-term data sovereignty.
Storage Type:
Cloud storage faces the most acute substitution pressure as hybrid architectures displace pure public cloud deployments at mid-size hospital systems seeking data residency controls.
- Cloud Storage:Public cloud deployments deliver elastic capacity scaling without capital expenditure commitment. Demand concentrates at US regional health information exchanges where HIPAA business associate agreements with hyperscale providers satisfy technical safeguard requirements.
- Hybrid Storage:Unified management planes span on-premise flash arrays and cloud object tiers under single namespace control. Germany's hospital digitization programs accelerate adoption as EU AI Act audit mandates require local data residency for algorithmic training sets.
- On-Premise Storage:Dedicated hardware installations retain full physical control over patient records.
- Network Attached Storage:File-level access protocols serve departmental imaging workstations.
- Direct Attached Storage:Server-internal drives address isolated high-performance compute nodes.
Cloud storage anchors the volume base while hybrid storage gains share at the steepest rate.
Technology:
Cost tiering across storage media creates sharp performance gradients that reshape procurement economics for different clinical use cases.
- Object Storage:Flat namespace architectures with metadata-rich addressing enable petabyte-scale genomic indexing. Research biobanks at academic medical centers exploit this technology for population-scale sequence repositories that exceed traditional file system limits.
- Flash Storage:NAND-based solid-state arrays deliver sub-millisecond latency for picture archiving systems. Radiology departments require this performance tier for real-time diagnostic image retrieval during surgical procedures.
- Block Storage:Raw volume access serves database-driven electronic health record systems.
- File Storage:Hierarchical directory structures persist in legacy departmental shares.
- Tape Storage:Linear magnetic media addresses decades-long retention mandates at lowest cost per terabyte.
- Optical Storage:Write-once formats satisfy FDA 21 CFR Part 11 immutability requirements for clinical trial archives.
Flash storage commands premium pricing while object storage expands most quickly across research and telemedicine workloads.
Application:
Volume concentration in electronic medical records creates infrastructure lock-in that slows migration to modern architectures.
- Electronic Medical Records:Structured patient data repositories require 99.999% uptime availability with AES-256 encryption. Hospital IT departments in the United States prioritize these systems for HIPAA security rule compliance audits conducted by the Office for Civil Rights.
- Medical Imaging Archives:DICOM-formatted radiology studies demand high-throughput retrieval for diagnostic workstations. Picture archiving systems at integrated delivery networks face replacement pressure as proprietary hardware reaches end-of-life.
- Genomic Data Repositories:Unstructured sequence files from next-generation sequencing platforms.
- Telemedicine Platforms:Real-time video consultation archives with intelligent tiering requirements.
- Research Databases:Multi-institutional collaborative datasets with cross-border access protocols.
Electronic medical records dominate installed capacity while genomic repositories climb the fastest as sequencing costs decline.
End User:
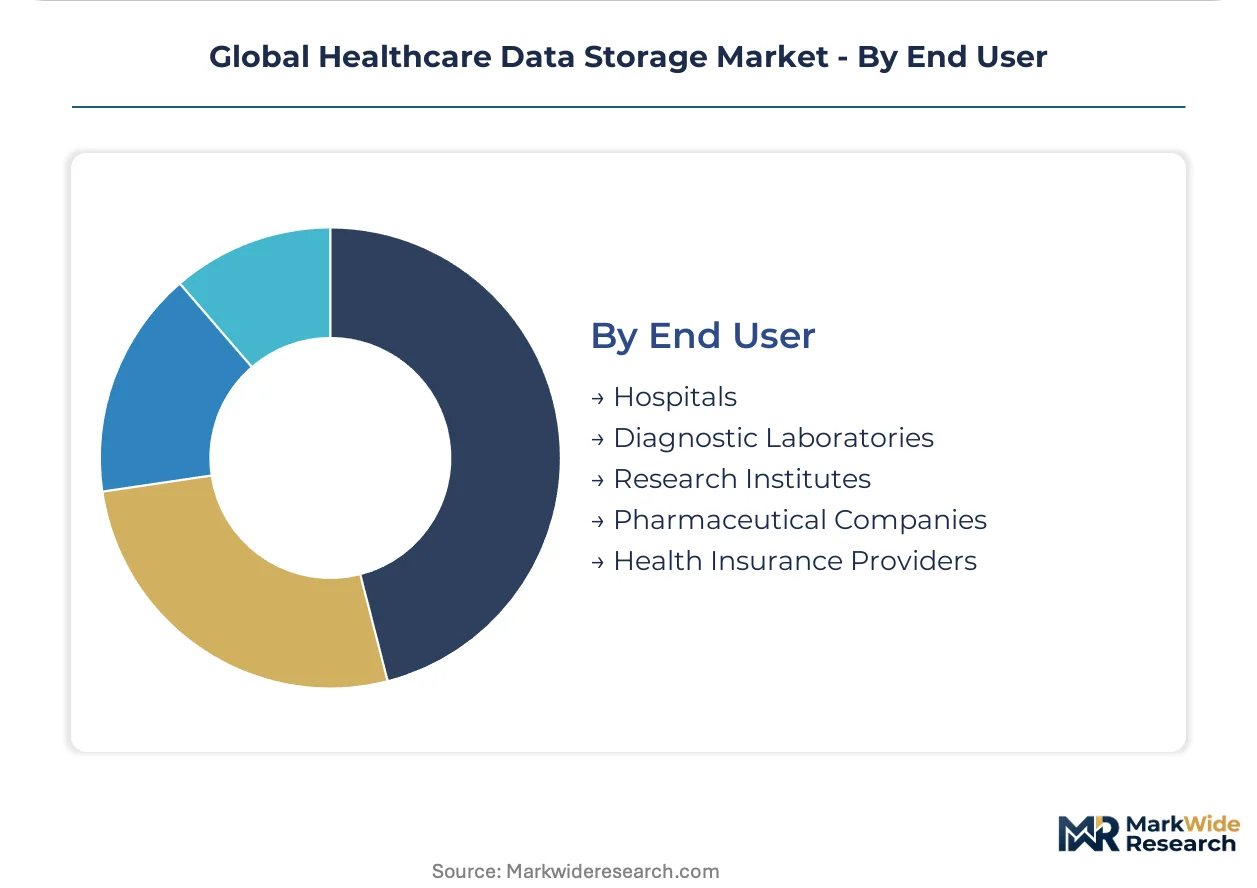
Customer type determines procurement authority and budget cycle timing across healthcare ecosystem participants.
- Hospitals:Integrated delivery networks consolidate storage procurement across radiology, pathology, and emergency departments. US hospital systems expanding digital infrastructure drive demand for multi-site disaster recovery configurations.
- Pharmaceutical Companies:Clinical trial sponsors require audit trails spanning FDA and EMA jurisdictions. Multi-site federated storage fabrics enable cross-border collaboration while satisfying GDPR data-localization mandates.
- Diagnostic Laboratories:High-throughput testing facilities with instrument-generated data streams.
- Research Institutes:Academic medical centers with grant-funded infrastructure refresh cycles.
- Health Insurance Providers:Claims analytics platforms with longitudinal patient record aggregation.
Hospitals anchor procurement volume while pharmaceutical companies expand most aggressively as trial complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital digitization incentives and tightening data sovereignty regulations are redrawing geographic demand patterns for healthcare data storage infrastructure. Procurement authority concentrates where public funding programs intersect with strict compliance mandates.
United States
Integrated delivery networks are consolidating multi-site storage deployments across radiology and pathology departments. HIPAA enforcement through the Office for Civil Rights elevates technical safeguard requirements for business associate agreements with cloud providers. The Greater Boston cluster anchors academic medical center procurement for genomic data repositories at Massachusetts General and Dana-Farber.
Germany
Hospital digitization programs are accelerating cloud migration for imaging archives at university hospitals and municipal clinic networks. The EU AI Act imposes algorithmic audit trail preservation that favors hybrid architectures with local data residency. The Munich-Stuttgart corridor concentrates vendor engineering resources for quantum-safe encryption integration.
India
Ayushman Bharat health mission investments are expanding digital record requirements at district hospitals and primary health centers. CDSCO guidance on electronic clinical trial data is aligning with FDA 21 CFR Part 11 standards for multinational pharmaceutical sponsors. The Hyderabad-Bengaluru corridor hosts hyperscale cloud regions serving South Asian hospital networks.
China
NMPA medical device data regulations are mandating localized storage for connected diagnostic equipment and implantable sensors. MIIT cybersecurity standards require domestic encryption certification for patient record platforms. The Yangtze River Delta cluster concentrates hospital IT procurement for tier-three municipal medical centers in Shanghai and Jiangsu.
United Kingdom
NHS digital transformation programs are standardizing cloud-first procurement for electronic patient record systems across integrated care systems. GDPR data localization requirements intersect with MHRA guidance on clinical trial master files for pharmaceutical sponsors. The Cambridge-Oxford-London triangle anchors research biobank infrastructure for population-scale genomic sequencing initiatives.
Global Healthcare Data Storage Market Competitive Landscape
Player mix skews toward diversified technology conglomerates with end-to-end infrastructure portfolios, though flash storage specialists and cloud-native platforms occupy distinct competitive tiers. Market structure exhibits moderate consolidation around vendors with ISO 27001 certification and multi-site deployment capabilities. Two strategic archetypes dominate: full-stack infrastructure providers anchoring enterprise hospital contracts, and performance-focused specialists capturing radiology department procurement. Competitive moves center on quantum-safe encryption licensing and managed service transitions that convert capital expenditure to operational expenditure models.
Within the full-stack infrastructure tier, Dell Technologies and Hewlett Packard Enterprise exemplify vendors with integrated server-storage-networking portfolios that satisfy integrated delivery network procurement requirements. Huawei Technologies occupies a position among Asia-Pacific headquartered conglomerates with domestic cloud regions serving hospital digitization programs. Pure Storage represents the performance-specialist archetype, with all-flash density configurations targeting sub-millisecond latency requirements in picture archiving systems. IBM Corporation anchors the encryption-differentiated segment, with quantum-safe layering for genomic data repositories distinguishing its positioning against commodity cloud alternatives.
| Leading Market Players |
|---|
| Hewlett Packard Enterprise |
| Huawei Technologies |
| Dell Technologies |
| Hitachi |
| Fujitsu |
| IBM Corporation |
| Pure Storage |
| Western Digital |
| NetApp |
| Others |
Supply & Pricing Matrix
ISO 27001 certification gates supplier qualification and price differentiation simultaneously, as hospital procurement tenders exclude uncertified vendors while awarding premium contract tiers to providers with accredited information security management systems and quantum-safe encryption capabilities.
Pricing Analysis
Cost-plus contracts with NAND flash indexation anchor enterprise storage array pricing, with three-tier pricing structure across premium, standard, and economy levels separating all-flash configurations from hybrid disk arrays and cold archival tiers. Price differentiation rests on ISO 27001 certification grade and after-sales service bundling. Cost compression in mid-tier hybrid arrays is intensifying because hyperscale cloud providers are absorbing volume discounts. Community hospital systems exhibit highest price sensitivity; academic medical centers prioritize latency performance over unit cost.
Supply Chain Analysis
Taiwan Strait transit risk underwrites supply security planning for healthcare storage infrastructure, as high-performance NAND flash fabrication concentrates in Taiwan and South Korea with controller logic sourced from US fabless designers. Raw material dependencies span silicon wafers, rare earth elements for drive magnets, and specialized epoxy resins for circuit boards. Single-source vulnerability in advanced node semiconductor foundries exposes array pricing to geopolitical disruption. Distribution runs through systems integrators and GPO contracts at integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare data storage operates as a defensive-moat market where regulatory entrenchment creates structural advantages—ISO 27001 certification timelines and HIPAA technical safeguard compliance erect barriers that compound over multi-year hospital procurement cycles.
For Market Incumbents: Fortify certification moats by accelerating quantum-safe encryption R&D at Munich and Stuttgart engineering clusters before EU AI Act audit mandates harden. Expand managed service arrangements in Germany's hospital digitization programs to convert capital expenditure customers to recurring revenue streams. Defend against cloud-native platform substitution by embedding storage platforms within broader infrastructure portfolios.
For New Entrants and Emerging Players: Lead with HL7 FHIR-native API integration targeting US regional health information exchanges where interoperability mandates create procurement urgency. India's Ayushman Bharat district hospital infrastructure offers the most penetrable geography for cloud-first storage architectures. Pursue telemedicine platform partnerships as the primary go-to-market angle, as real-time video archive requirements exceed incumbent file system capabilities.
For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward vendors with pre-built algorithmic audit trail capabilities and EU data residency controls. Long-term viability favors encryption-differentiated specialists with genomic data repository expertise over commodity cloud resellers. Watch FDA 21 CFR Part 11 enforcement intensity as the signal indicating whether compliance infrastructure valuations expand or compress.
| Strategic Initiative | Industry Significance |
|---|---|
| Quantum-Safe Encryption Licensing | IBM Corporation's genomic repository positioning differentiates against commodity cloud alternatives at academic medical centers. |
| Managed Service Transition | Five-year total-cost-of-ownership calculations in Germany favor operational expenditure models over on-premise ownership. |
| HL7 FHIR API Integration | Native semantic metadata tagging captures procurement from hospital systems facing interoperability mandate deadlines. |
| Hybrid Cloud Architecture Deployment | Unified namespace control satisfies EU AI Act local data residency requirements at university hospitals. |
| Object Storage Array Development | All-flash density configurations target sub-millisecond latency requirements in radiology department picture archiving systems. |
Research Methodology
A standing panel of hospital CIOs, biomedical engineers, GPO contracts managers, and hyperscaler healthcare solution architects provided ongoing calibration across primary interviews and secondary validation. Sources included hospital procurement databases, CMS Medicare reimbursement filings, FDA 510(k) and PMA submissions, GPO contract award records, and hyperscaler capex disclosures. Bottom-up triangulation across storage capacity deployments and top-down reconciliation against healthcare IT spending benchmarks ensured consistency.
External benchmark validation against hospital IT budget surveys and storage vendor revenue disclosures confirmed projection outputs across the analysis window. Segmentation dimensions modeled encompassed storage type, technology tier, clinical application, and end-user archetype. CAGRs derived from logistic adoption curves for cloud migration and linear replacement cycles for on-premise infrastructure. Forecast inputs included NAND flash pricing indices, hospital digitization program funding allocations, and regulatory compliance cost estimates.
Forecasts assume regulatory continuity in HIPAA enforcement, EU AI Act implementation, and FDA 21 CFR Part 11 guidance; material policy shifts would require re-modeling. Scenario risks span semiconductor export controls, data localization mandate expansion, and quantum computing timeline acceleration. Practitioners should keep alternative scenarios live as geopolitical conditions and encryption standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Hospital Management Software Market
Health Data Management
Healthcare Data Integration Market
Health Data Management
Clinical Trial Data Management Software Market
Health Data Management
Medical Record Management System Market
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
Global Healthcare Fraud Analytics Market
Health Data Management
Asia Pacific Healthcare Archiving and Ediscovery Market
Health Data Management
Europe Healthcare Analytics Market
Health Data Management
Patient Data Management Software Market
Health Data Management
Global Healthcare Data Analytics Market
Health Data Management
Europe Healthcare Big Data Analytics Market
Health Data Management
Healthcare Analytics Market
Health Data Management
Global Precision Medicine Software Market
Health Data Management
Point-Of-Care Data Management Software Market
Health Data Management
Global Healthcare Compliance Software Market
Health Data Management
Healthcare Data Annotation Tools Market