
 Healthcare Laboratory Informatics Market | 2026-2036
Healthcare Laboratory Informatics Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Laboratory Informatics Market Analysis
The capital-intensity divergence between cloud-native platforms and legacy on-premises installations is unwinding competitive dynamics across the sector. Thermo Fisher Scientific leverages its instrument-software bundling strength to anchor enterprise deployments in diagnostics laboratories. LabVantage Solutions competes through specialized SaaS architectures that reduce infrastructure overhead for mid-sized research institutions. LabWare sustains its position via deep configurability in regulated pharmaceutical quality control environments.
Healthcare laboratory informatics encompasses software systems that manage laboratory data workflows, instrument integration, and regulatory compliance through structured electronic records with audit trail capabilities and role-based access controls. These platforms serve primarily to ensure data integrity, accelerate sample turnaround, and maintain traceability across clinical diagnostics and life sciences research. Laboratory Information Management Systems dominate current revenue as the foundational infrastructure layer, while Cloud-Based Solutions represent the fastest-expanding technology dimension as hospitals migrate away from capital-heavy server installations. Data Analytics Software captures emerging margin pools where laboratories seek predictive quality control and operational optimization beyond basic data storage.
FDA 21 CFR Part 11 validation requirements shape product development roadmaps for vendors targeting United States clinical laboratories, while EU MDR traceability standards and GDPR data residency rules constrain cloud architecture choices for European deployments. ISO 15189 accreditation pressures in diagnostics laboratories create recurring demand for compliance management modules that automate documentation and proficiency tracking. Stakeholders must weigh interoperability investments against emerging AI-enabled analytics capabilities as laboratories consolidate vendor relationships around integrated platform ecosystems.
Market Dynamics
Cloud-native architecture is compressing capital deployment cycles for laboratory informatics, forcing vendors to abandon perpetual license models in favor of subscription revenue streams that align with hospital budget pressures.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic signature and audit trail mandates in United States clinical laboratories are accelerating replacement of paper-based quality systems with validated informatics platforms.
- Biopharmaceutical R&D concentration:Dense clustering of drug discovery operations in Massachusetts and California generates sustained demand for high-throughput data management infrastructure.
- EU MDR traceability requirements:Device history record mandates across European diagnostics laboratories are expanding deployments of compliant laboratory information management systems.
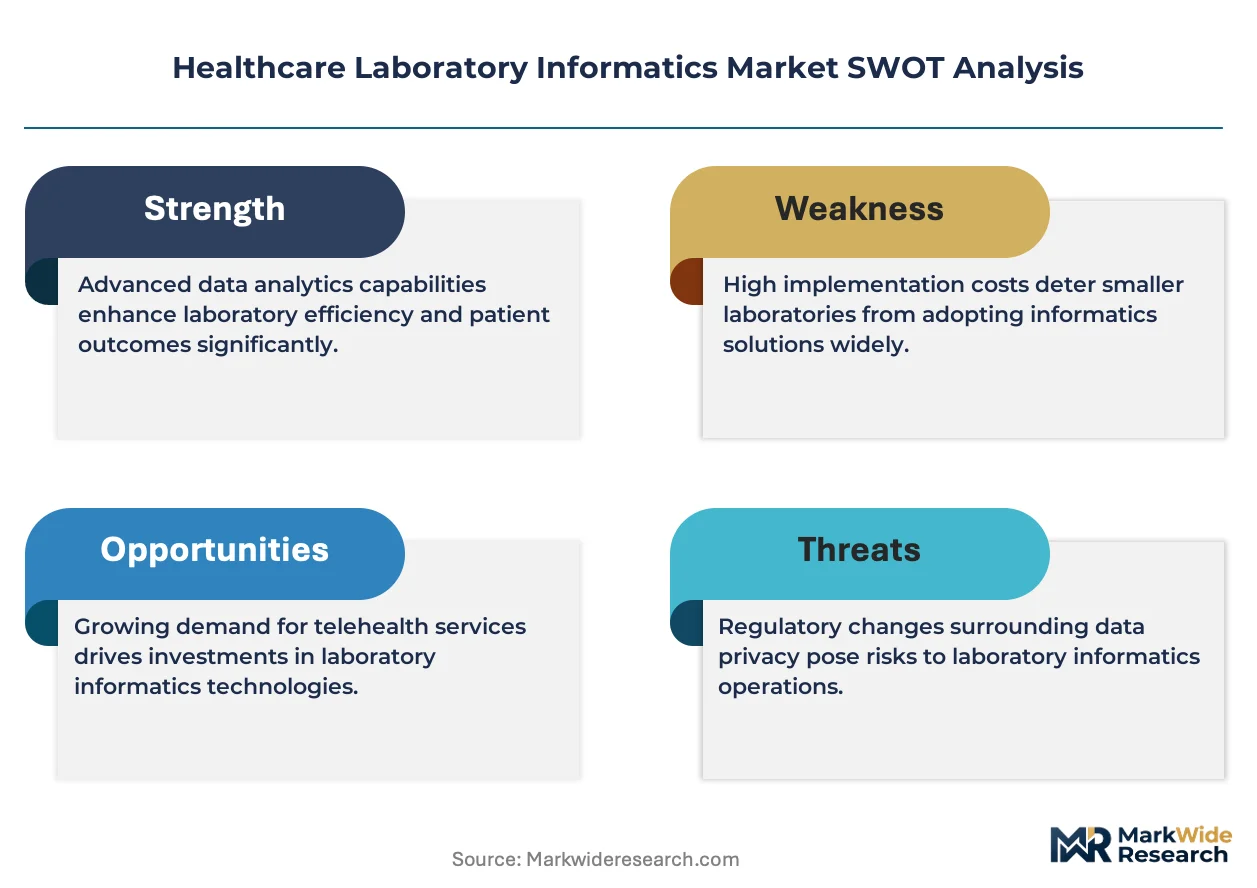
Market Restraints
- Data residency constraints:GDPR localization requirements fragment cloud architecture economics, forcing redundant infrastructure investments for European deployments.
- Legacy system entrenchment:Decades-old on-premises installations in hospital networks create switching costs that delay SaaS migration timelines.
- Specialized talent scarcity:Shortage of professionals qualified in both laboratory science and informatics system validation constrains implementation velocity.
Strategic Opportunities
- Predictive analytics convergence:Integration of machine learning with quality control workflows opens margin pools beyond basic data storage functions.
- Mid-sized research institutions:Underpenetrated academic medical centers in Texas and Florida present expansion targets for streamlined SaaS offerings.
- ISO 15189 automation modules:Accreditation pressures in clinical diagnostics create recurring revenue from compliance management subscriptions.
Industry Challenges
- Interoperability fragmentation:Proprietary instrument data formats from competing manufacturers impede seamless platform integration.
- Validation timeline compression:Compressed go-live schedules for FDA-regulated deployments strain quality assurance resources.
- Multi-site standardization:Consolidated health networks struggle to harmonize workflows across acquired facilities with divergent legacy systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Laboratory Informatics Market |
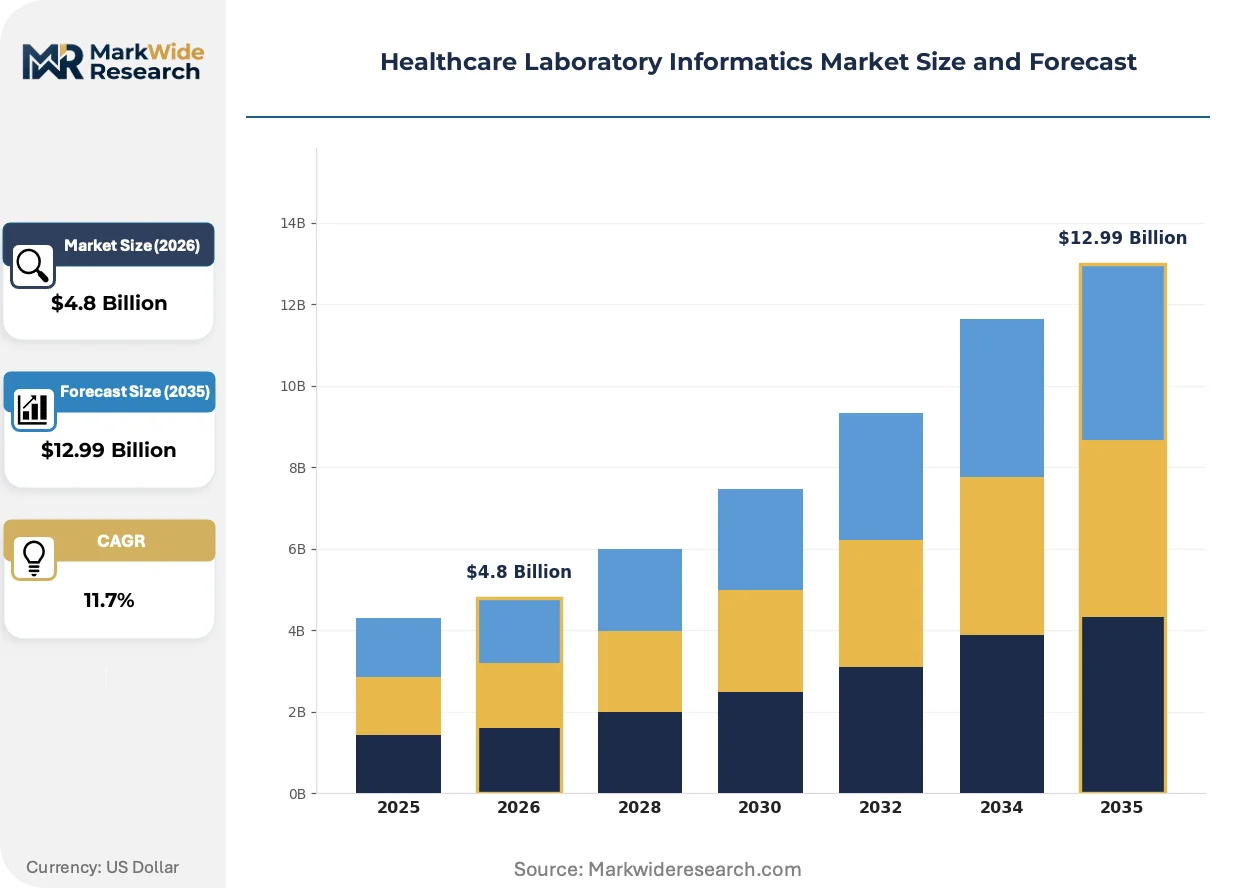
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laboratory Information Management System, Electronic Laboratory Notebook, Data Analytics Software, Laboratory Workflow Management End User: Hospitals, Diagnostics Laboratories, Research Institutions, Academic Institutions Technology: Cloud-Based Solutions, On-Premises Solutions, Hybrid Solutions, Big Data Integration Application: Sample Management, Data Management, Laboratory Integration, Compliance Management |
| Companies Covered | Thermo Fisher Scientific Inc., LabVantage Solutions Inc., LabWare, Agilent Technologies Inc., STARLIMS Corporation, LabLynx Inc., PerkinElmer Inc., Abbott Informatics, Core Informatics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Laboratory Informatics Market Emerging Trajectories
Artificial intelligence is penetrating laboratory operations at the point of data generation rather than retrospective analysis, reshaping how informatics platforms capture and structure experimental records.
Cloud-native software architecture is supplanting client-server installations in hospital laboratory environments. Academic medical centers in North Carolina and Ohio are migrating instrument integration and sample tracking to hosted platforms. This transition is compressing total cost of ownership curves and enabling real-time collaboration across multi-site networks.
EU AI Act risk classification rules are imposing documentation burdens on diagnostic algorithms embedded within laboratory workflows. Vendors must now maintain technical files and conformity assessments for decision-support modules previously treated as conventional software. German and French clinical laboratories are prioritizing vendors with established quality management systems to preempt regulatory friction.
Subscription pricing models are displacing perpetual licenses in procurement negotiations with integrated delivery networks. Hospital systems in Pennsylvania and Illinois now demand outcome-linked contracts that tie fees to uptime guarantees and turnaround time improvements. This shift transfers operational risk to vendors while accelerating platform consolidation around fewer supplier relationships.
Healthcare Laboratory Informatics Market Segmentation
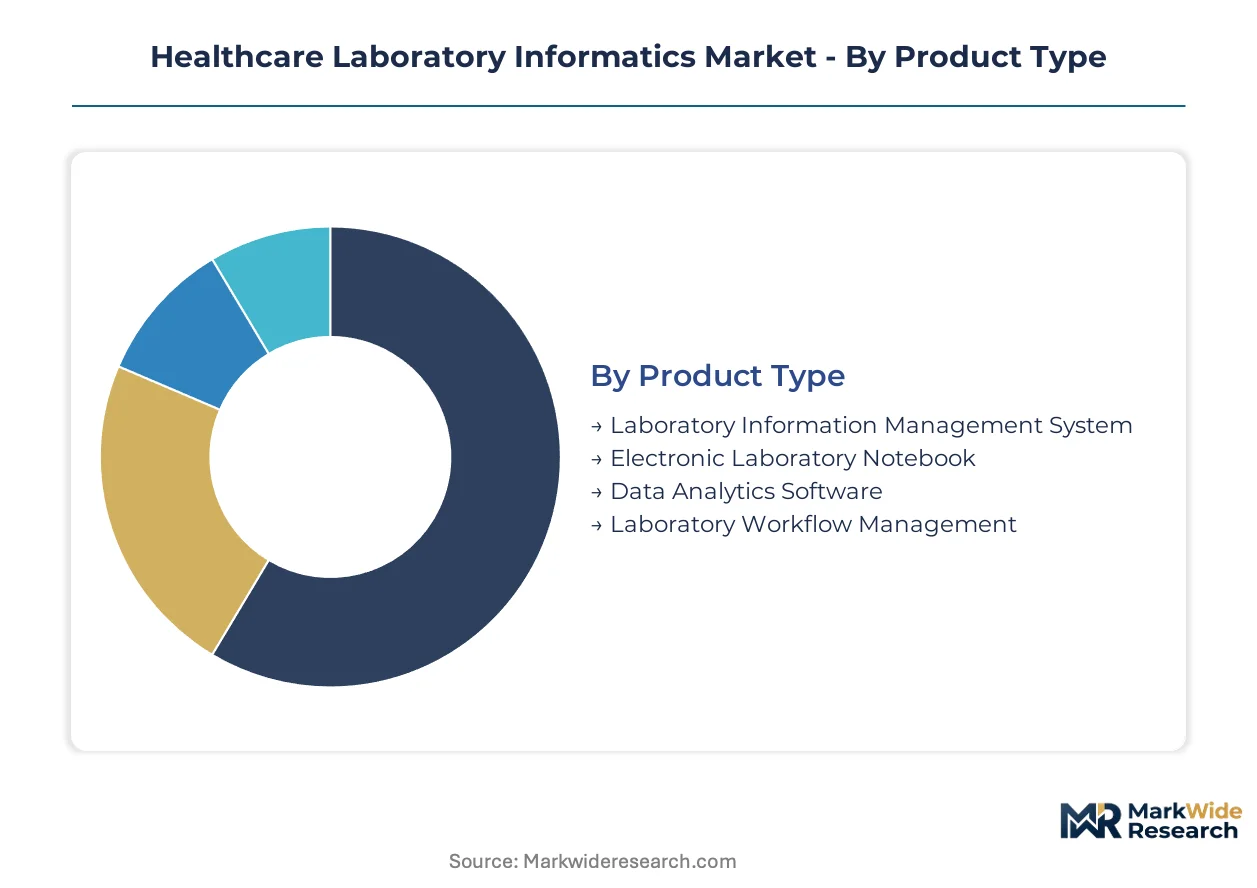
Segmentation in healthcare laboratory informatics reveals how procurement channels, compliance requirements, and infrastructure maturity diverge across customer types. Product architecture choices determine whether deployments flow through capital budgets or operational expenditure lines.
Product Type:
Laboratory Information Management Systems anchor enterprise procurement through multi-year capital cycles, while emerging categories penetrate via subscription channels aligned with compressed hospital budgeting.
- Laboratory Information Management System:Core infrastructure managing sample tracking, instrument integration, and audit trails with 21 CFR Part 11 validation. Diagnostics laboratories in Massachusetts and California drive replacement demand as integrated health networks consolidate vendor relationships around single platforms.
- Electronic Laboratory Notebook:Structured digital record systems capturing experimental protocols with version control and electronic signatures. Research institutions in Germany and Switzerland are expanding deployments to satisfy EU MDR traceability mandates for device history documentation.
- Data Analytics Software:Predictive quality control and operational optimization modules.
- Laboratory Workflow Management:Process orchestration tools for sample routing and turnaround optimization.
Laboratory Information Management Systems dominate installed base. Data Analytics Software is where expansion concentrates fastest.
End User:
Customer type determines deployment complexity, with hospital networks demanding multi-site standardization while academic centers prioritize cost flexibility.
- Hospitals:Integrated delivery networks requiring harmonized workflows across acquired facilities with divergent legacy systems. Consolidation in Pennsylvania and Illinois is compressing vendor lists to three or fewer suppliers per network.
- Diagnostics Laboratories:High-throughput operations with ISO 15189 accreditation pressures creating recurring demand for automated compliance modules. German clinical laboratories are prioritizing vendors with established quality management systems to preempt EU AI Act friction.
- Research Institutions:Drug discovery operations with instrument-software bundling preferences.
- Academic Institutions:Budget-constrained environments favoring SaaS architectures with reduced infrastructure overhead.
Diagnostics Laboratories capture the steepest expansion trajectory. Academic Institutions represent the most price-sensitive penetration target.
Technology:
Infrastructure architecture choices fragment across data residency constraints, with GDPR localization requirements forcing redundant deployments for European customers.
- Cloud-Based Solutions:Hosted platforms compressing total cost of ownership and enabling real-time multi-site collaboration. Academic medical centers in North Carolina and Ohio are migrating instrument integration to cloud-native architectures.
- On-Premises Solutions:Client-server installations retaining dominance in FDA-regulated pharmaceutical quality control where validation timelines and data sovereignty concerns delay SaaS migration.
- Hybrid Solutions:Mixed deployments balancing sensitive data on-premises with collaborative tools in cloud.
- Big Data Integration:Architecture layers enabling predictive analytics convergence with quality control workflows.
On-Premises Solutions retain majority installed base. Cloud-Based Solutions are climbing the fastest as subscription pricing displaces perpetual licenses.
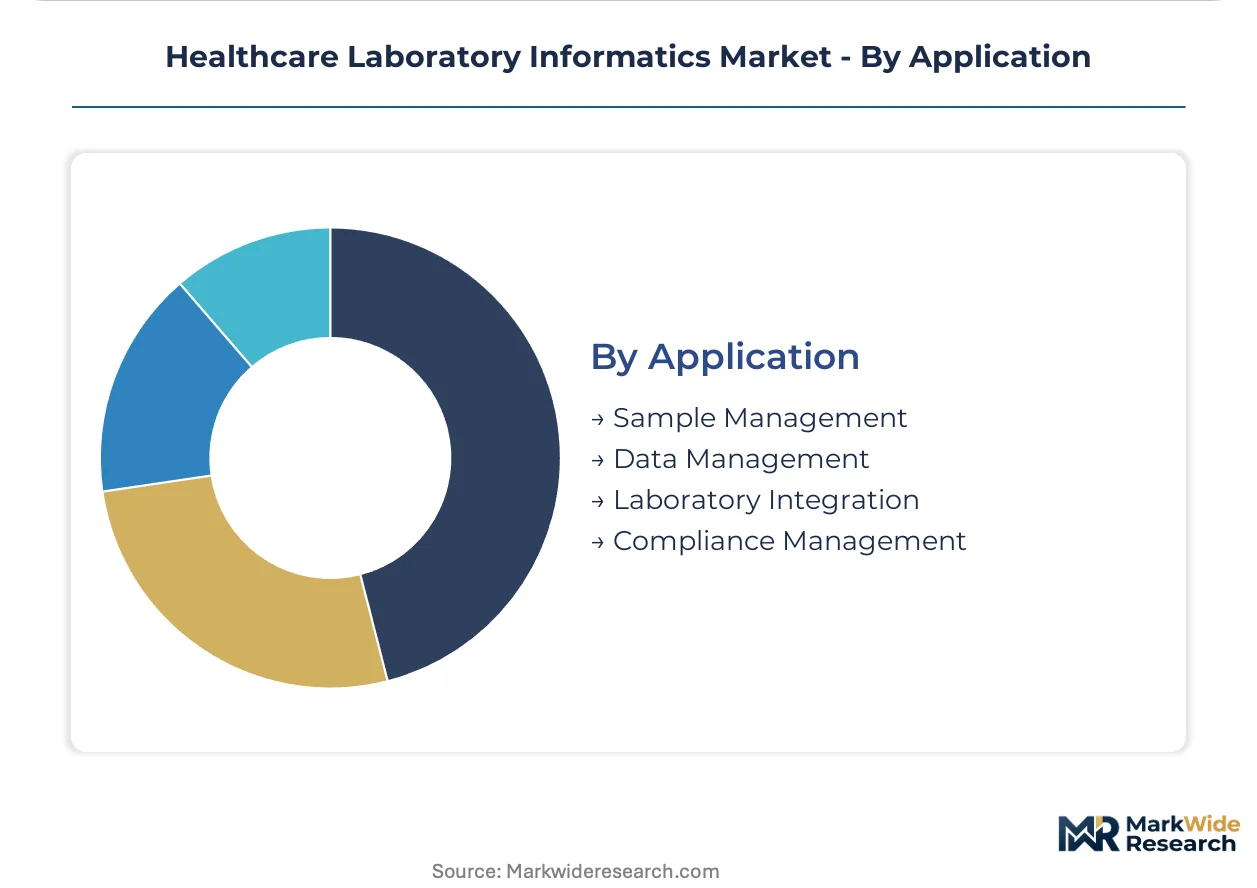
Application:
Functional modules align with regulatory pressure points, with compliance automation commanding premium pricing in clinical diagnostics.
- Sample Management:Tracking and chain-of-custody systems with barcode and RFID integration. Demand concentrates in United States clinical laboratories replacing paper-based quality systems with validated electronic records.
- Compliance Management:Automated documentation, proficiency tracking, and audit trail maintenance for accreditation pressures. ISO 15189 requirements in European diagnostics laboratories create recurring subscription revenue.
- Data Management:Structured storage with role-based access controls and data integrity safeguards.
- Laboratory Integration:Instrument connectivity and data format normalization across competing manufacturers.
Sample Management anchors current revenue. Compliance Management is gaining share fastest as regulatory documentation burdens intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in United States procurement channels where integrated health networks consolidate vendor relationships, while European deployments absorb GDPR-mandated infrastructure premiums that compress vendor margins.
United States
FDA 21 CFR Part 11 validation requirements drive replacement of paper-based quality systems in clinical diagnostics laboratories. Biopharmaceutical R&D spending clusters heavily in Massachusetts and California, generating sustained demand for high-throughput data management infrastructure. Hospital consolidation in Pennsylvania and Illinois compresses supplier lists to three or fewer vendors per integrated delivery network.
Germany
EU MDR traceability mandates expand deployments of compliant laboratory information management systems across device history record workflows. German clinical laboratories prioritize vendors with established quality management systems to preempt EU AI Act documentation burdens. The Rhine-Ruhr and Bavarian medical technology corridors concentrate diagnostics manufacturing and associated informatics procurement.
United Kingdom
NHS consolidation pressures accelerate migration from legacy on-premises installations toward subscription-based cloud architectures. MHRA alignment with FDA validation standards shapes procurement specifications for clinical laboratory software. London and Cambridge life sciences clusters drive demand for electronic laboratory notebook deployments in research settings.
Switzerland
Swissmedic quality system requirements reinforce stringent validation protocols for pharmaceutical quality control environments. GDPR data residency rules fragment cloud architecture economics despite Switzerland's partial adequacy status. Basel and Zurich anchor pharmaceutical R&D operations with dense instrument-software bundling preferences.
India
CDSCO medical device registration requirements are tightening documentation standards for diagnostic laboratory software imports. Academic medical centers in Maharashtra and Karnataka favor SaaS architectures to reduce infrastructure overhead. Hyderabad and Bangalore biotech corridors expand adoption of cloud-based sample tracking systems.
Healthcare Laboratory Informatics Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the healthcare laboratory informatics sector. Instrument-software bundling strength anchors enterprise deployments in diagnostics laboratories, while specialized SaaS architectures reduce infrastructure overhead for mid-sized research institutions. Deep configurability in regulated pharmaceutical quality control environments sustains position in high-compliance segments. Competitive moves concentrate on strategic partnerships for interoperability resolution and portfolio diversification into predictive analytics modules.
Within the instrument-integrated tier, Thermo Fisher Scientific Inc. and Agilent Technologies Inc. exemplify bundling strategies that anchor enterprise laboratory deployments. LabVantage Solutions Inc. occupies a position representing specialized SaaS architectures targeting mid-sized research institutions with compressed implementation timelines. LabWare sits within the configurability-focused segment serving pharmaceutical quality control environments with extensive validation requirements.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| LabVantage Solutions Inc. |
| LabWare |
| Agilent Technologies Inc. |
| STARLIMS Corporation |
| LabLynx Inc. |
| PerkinElmer Inc. |
| Abbott Informatics |
| Core Informatics |
| Others |
Supply Flow & Price Mechanics
Capacity utilization in cloud-native platform development creates scale economies that compress marginal delivery costs while anchoring price floors for on-premises alternatives. FDA 21 CFR Part 11 validation overhead and EU MDR traceability documentation burdens concentrate pricing power among vendors with established quality management systems, forcing mid-tier competitors toward standardized SaaS tiers with thinner margins.
Pricing Analysis
The customization-premium spread separates validated enterprise deployments from streamlined academic offerings by three-to-five-fold unit economics. Subscription SaaS models now dominate hospital procurement, with ISO 15189 certification tiers commanding premium positioning over basic sample-tracking modules. Price differentiation rests on validation depth and multi-site orchestration capability. Cost compression in mid-market SaaS tiers is intensifying because LabVantage and LabLynx compete aggressively on implementation timeline guarantees. Academic Institutions exhibit highest price sensitivity; integrated delivery networks in Pennsylvania and Illinois prioritize uptime-linked outcome contracts over sticker price.
Supply Chain Analysis
Just-in-time deployment preferences in cloud-native delivery contrast with strategic stockpiling of validation documentation and pre-certified module libraries for FDA-regulated environments. Software development concentrates in the United States, Germany, and India, with Hyderabad and Bangalore engineering centers feeding SaaS architecture development. Raw material dependencies include hyperscaler compute capacity from AWS and Azure, open-source database frameworks, and instrument-specific driver libraries. Single-source vulnerability in instrument-software bundling relationships with Thermo Fisher and Agilent creates supply chain risk. Distribution runs through direct enterprise sales teams for large hospital networks and value-added resellers for mid-sized research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare laboratory informatics sits in early-cycle expansion as cloud migration penetrates diagnostics laboratories previously locked in decade-old on-premises installations. FDA 21 CFR Part 11 compliance deadlines and EU MDR traceability mandates create irreversible replacement demand that extends the runway for platform consolidation.
For Market Incumbents: Shield installed base relationships by embedding predictive analytics modules that raise switching costs before competitors achieve interoperability parity. Deepen backward integration into instrument driver development to preempt data format fragmentation threats from competing hardware manufacturers. Prioritize certification investment in EU AI Act conformity assessment capabilities to capture German and French laboratory procurement specifications. For New Entrants and Emerging Players: Mid-sized academic medical centers in Texas and Florida represent the most penetrable white-space target, as these institutions lack capital budgets for enterprise LIMS but require ISO 15189-compliant SaaS alternatives. Cloud-native electronic laboratory notebook deployments for device history documentation in EU MDR-regulated workflows offer a second entry vector. Pursue channel partnerships with regional value-added resellers already embedded in hospital procurement committees rather than building direct sales capacity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among SaaS-native vendors serving diagnostics laboratories with automated compliance management subscriptions, suggesting superior cash-flow quality versus perpetual-license legacy players. Acquisition targets should display vertical integration into instrument connectivity layers or proprietary AI-enabled quality control algorithms. Watch for inflection when hospital consolidation in Pennsylvania and Illinois compresses vendor lists to two or fewer suppliers per network, triggering rollup opportunities among remaining independents.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates instrument data formats from competing manufacturers into unified laboratory workflows. |
| Regulatory Certification Pathway | EU AI Act conformity assessments preempt documentation burdens for diagnostic algorithm deployments in Germany. |
| Strategic Partnership | Hyperscaler alliances with AWS and Azure resolve GDPR data residency constraints for European cloud architectures. |
| Acquisition of Specialist Firm | Predictive analytics modules capture margin pools beyond basic data storage in quality control environments. |
| Geographic Expansion | Texas and Florida academic medical centers offer underpenetrated targets for streamlined SaaS offerings. |
Methodological Framework
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in documented compliance requirements. Laboratory informatics vendors, hospital procurement managers, biomedical engineers, and GPO contracts managers provided operational perspective. FDA 510(k) submissions, EU MDR technical file databases, hospital procurement records, and CMS Medicare laboratory spending data supplied secondary validation. Bottom-up deployment counts triangulate against top-down healthcare IT budget allocations.
Sensitivity analysis tested forecast robustness across cloud adoption pace scenarios and regulatory deadline shifts. The modeling framework spans product type, end user, deployment architecture, and regional regulatory cluster dimensions. CAGRs derive from fitted adoption curves calibrated to historical LIMS replacement cycles. Instrument-software bundling intensity and ISO 15189 accreditation penetration serve as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA 21 CFR Part 11 and EU MDR enforcement regimes; material policy shifts would require re-modeling. Cloud migration delays in hospital networks with entrenched legacy systems represent a specific risk factor. Revision becomes warranted when SaaS subscription renewal rates in academic medical centers cross threshold divergence from enterprise diagnostics laboratory benchmarks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Informatics
High Acuity Information Systems Market
Health Informatics
Indonesia Connected Healthcare Market
Health Informatics
Health Information Exchange (HIE) Market
Health Informatics
IT Spending on Clinical Analytics Market
Health Informatics
North America Laboratory Information System Market
Health Informatics
Health Intelligent Virtual Assistant Market
Health Informatics
Global Consumer Genomics Market
Health Informatics
Healthcare Application Programming Interfaces Market
Health Informatics
Electronic Health Record (EHR) Market
Health Informatics
Global Natural Language Processing (NLP) in Healthcare and Life Sciences Market
Health Informatics
EHR EMR Market
Health Informatics
Healthcare Cybersecurity Market
Health Informatics
AI in Epidemiology Market
Health Informatics
Asia Pacific Healthcare Analytics Market
Health Informatics
Global Healthcare Informatics Market
Health Informatics
Healthcare BI Market