
 Big Data Healthcare Market | 2026-2036
Big Data Healthcare Market Size, Share, and Industry Trends Forecast 2026-2036
Big Data Healthcare Market Intelligence
Market Context with Strategic Players
Payer organizations and pharmaceutical companies is bifurcating demand away from standalone hospital IT departments as the primary analytics buyers. Epic Systems Corporation leverages its dominant position in electronic health record integration to control inpatient data pipelines. Oracle Corporation sustains cloud infrastructure investments that anchor enterprise-scale healthcare data warehousing. IBM Corporation differentiates through specialized AI diagnostics platforms that compete for high-value imaging analytics contracts.
Technical Definition and Structural Segments
Big data in healthcare encompasses the capture, storage, and computational analysis of multi-terabyte datasets drawn from electronic health records, genomic sequencing outputs, real-time physiological monitoring, and medical imaging repositories, employing distributed computing architectures and machine learning algorithms to identify population-level disease patterns and individual patient risk trajectories. Predictive analytics solutions command the largest revenue share among solution types, though population health management platforms are expanding fastest as accountable care organizations assume greater financial risk. Cloud-based deployment models are displacing on-premises installations among mid-sized providers, while hybrid architectures dominate large integrated delivery networks that must balance latency-sensitive clinical workloads with elastic research computing demands.
Regulatory Frame and Forward Outlook
The FDA, HIPAA privacy framework, and ONC interoperability rules collectively shape data governance requirements, vendor certification pathways, and cross-institutional sharing protocols that determine market access conditions. The 21st Century Cures Act's information blocking provisions force incumbent platforms to open application programming interfaces, reducing switching costs for provider customers. Stakeholders must monitor emerging state-level biometric privacy statutes and federal AI governance proposals that will redefine permissible algorithmic decision-making in clinical settings.
Market Dynamics
The FDA's information blocking enforcement is decomposing data silos that protected incumbent electronic health record vendors for decades, forcing open application programming interfaces and accelerating third-party analytics integration across previously sealed clinical repositories.
Growth Catalysts
- Interoperability mandates:The 21st Century Cures Act's information blocking provisions compel health systems to expose standardized data interfaces, enabling multi-source analytics pipelines that were technically prohibited under prior platform architectures.
- Pharmaceutical R&D acceleration:Drug developers are expanding procurement of real-world evidence platforms to compress trial timelines, with genomic sequencing integration now standard in oncology pipeline decisions.
- Cloud infrastructure maturation:Elastic computing architectures allow mid-sized hospital networks to deploy enterprise-grade analytics without capital-intensive on-premises data center investments.
Market Restraints
- HIPAA compliance complexity:State-level biometric privacy statutes are layering conflicting requirements atop federal frameworks, fragmenting vendor certification pathways and extending sales cycles.
- Specialized talent scarcity:Health informaticists with dual clinical and machine learning expertise command compensation premiums that constrain provider IT department expansion.
- Legacy system technical debt:Decades-old electronic health record architectures resist API-native retrofitting, trapping analytics workloads in extract-transform-load batch processes with latency unsuitable for real-time clinical decision support.
Strategic Opportunities
- Real-world evidence commercialization:Payer organizations are monetizing de-identified claims datasets to pharmaceutical manufacturers seeking post-market surveillance inputs, creating subscription revenue streams independent of premium collection.
- Edge computing integration:Internet-of-medical-things devices with onboard inference capabilities are enabling latency-sensitive analytics at the point of care, bypassing cloud round-trip delays for critical monitoring applications.
- Federated learning architectures:Privacy-preserving machine learning techniques allow multi-institutional model training without centralizing protected health information, unlocking collaborative research across competing health systems.
Industry Challenges
- Algorithmic bias detection:Clinical AI deployments require continuous monitoring for demographic performance disparities, demanding specialized validation infrastructure that most provider organizations lack.
- Cross-platform integration friction:Health systems operating multiple electronic health record instances from different vendors face data model incompatibilities that fragment patient longitudinal records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Data Healthcare Market |
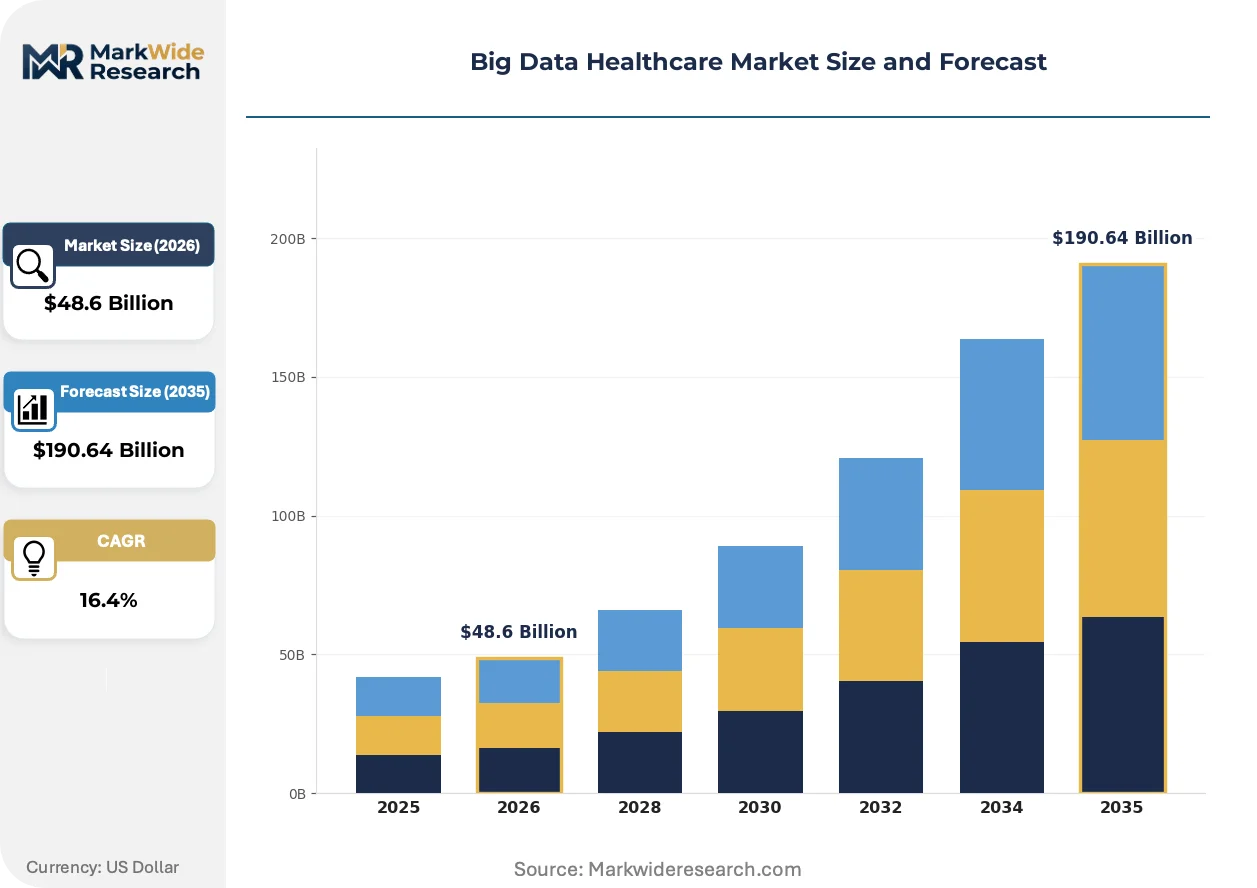
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $190.64 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Predictive Analytics, Population Health Management, Clinical Decision Support, Revenue Cycle Management Data Source: Electronic Health Records, Wearable Devices, Genomic Data, Medical Imaging Deployment Model: On-Premises, Cloud-Based, Hybrid, Hosted End User: Pharmaceutical Companies, Research Institutions, Diagnostic Laboratories, Telemedicine Providers |
| Companies Covered | Epic Systems Corporation, Oracle Corporation, IBM Corporation, Allscripts Healthcare Solutions, GE HealthCare, McKesson Corporation, IQVIA, Microsoft Corporation, Accenture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Data Healthcare Market Strategic Shifts & Innovations
Computational architectures and governance frameworks are converging to enable analytics workloads that were technically or legally infeasible under prior-generation infrastructure, compressing the gap between data generation and actionable insight extraction.
Natural language processing engines trained on clinical documentation are decomposing unstructured physician notes into codified phenotypes, enabling retrospective cohort identification at scale. Academic medical centers and contract research organizations are deploying these tools to accelerate patient recruitment for precision medicine trials. The structural consequence is a shift from manual chart review to automated eligibility screening, compressing study startup timelines from months to weeks.
The EU AI Act's risk classification framework is imposing conformity assessment requirements on clinical decision support systems marketed in member states. Manufacturers must now document training data provenance and performance metrics across demographic subgroups before CE marking. High-risk diagnostic algorithms face notified body scrutiny comparable to medical device regulations, favoring established vendors with regulatory affairs infrastructure over emerging competitors.
Hospital procurement departments are consolidating analytics vendor relationships through enterprise-wide platform licensing rather than departmental point solutions. Integrated delivery networks are negotiating master service agreements that bundle electronic health record modules with population health management and revenue cycle analytics. This concentration is most visible in United States health systems pursuing vertical integration strategies that internalize data science capabilities previously outsourced to consultancies.
Big Data Healthcare Market Segmentation
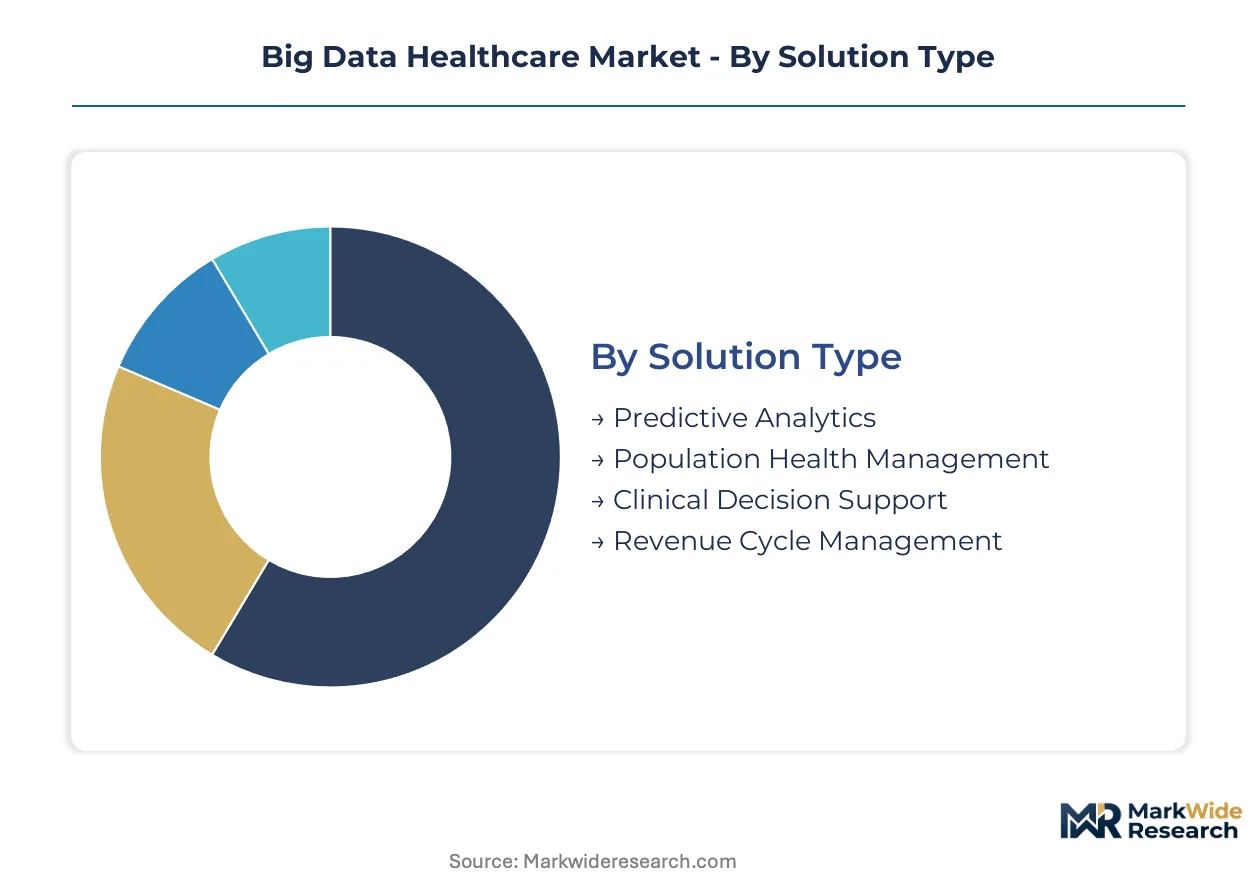
Big data healthcare deployments fragment across technical architectures, data provenance, and institutional buyer profiles. Each segmentation axis carries distinct regulatory certification burdens and margin structures that determine vendor competitive positioning.
Solution Type:
FDA's software-as-medical-device guidance and HIPAA business associate agreements create divergent compliance pathways across analytics categories.
- Predictive Analytics:Machine learning models forecasting patient deterioration, readmission probability, and disease progression. United States health systems concentrate procurement here as value-based reimbursement contracts penalize adverse outcomes. Cloud-native architectures dominate new deployments.
- Population Health Management:Platforms aggregating multi-source patient data to stratify risk and coordinate care across accountable care organizations. United States demand accelerates fastest as Medicare Advantage penetration expands risk-bearing entity formation.
- Clinical Decision Support:Real-time algorithmic recommendations embedded within electronic health record workflows. FDA oversight intensifies for diagnostic algorithms, extending certification timelines.
- Revenue Cycle Management:Analytics optimizing claims processing, denial prediction, and patient financial engagement. Mid-sized hospital networks prioritize this category to offset reimbursement compression.
Established volume favors predictive analytics; emerging adoption favors population health management.
Data Source:
Provenance determines interoperability complexity and consent management requirements under HIPAA and emerging state biometric statutes.
- Electronic Health Records:Structured clinical documentation from inpatient and ambulatory encounters. Epic Systems and Oracle Cerner control dominant data pipelines in United States health systems.
- Wearable Devices:Continuous physiological monitoring from consumer and clinical-grade sensors. FDA 510(k) clearance distinguishes medical-grade from wellness devices.
- Genomic Data:Sequencing outputs from tumor profiling and germline testing. Pharmaceutical oncology pipelines drive commercial demand fastest.
- Medical Imaging:Radiology, pathology, and ophthalmology DICOM repositories. NVIDIA and IBM compete for high-performance computing contracts.
Electronic health records anchor current analytical workloads; genomic data shows steepest expansion trajectory.
Deployment Model:
Latency requirements and data residency rules fragment infrastructure choices across provider scale tiers.
- On-Premises:Dedicated data centers within institutional firewalls. Large academic medical centers retain this model for genomic and imaging workloads with petabyte-scale datasets.
- Cloud-Based:Elastic compute and storage from hyperscale providers. Mid-sized United States hospital networks displace capital-intensive infrastructure fastest here.
- Hybrid:Split architectures balancing latency-sensitive clinical systems with elastic research computing. Integrated delivery networks standardize on this configuration.
- Hosted:Managed private cloud deployments from specialized healthcare infrastructure vendors. Smaller diagnostic laboratories favor operational simplicity.
Hybrid architectures command largest committed spend; cloud-based deployments gain share fastest among new buyers.
End User:
Procurement sophistication and budget scale vary sharply across institutional categories.
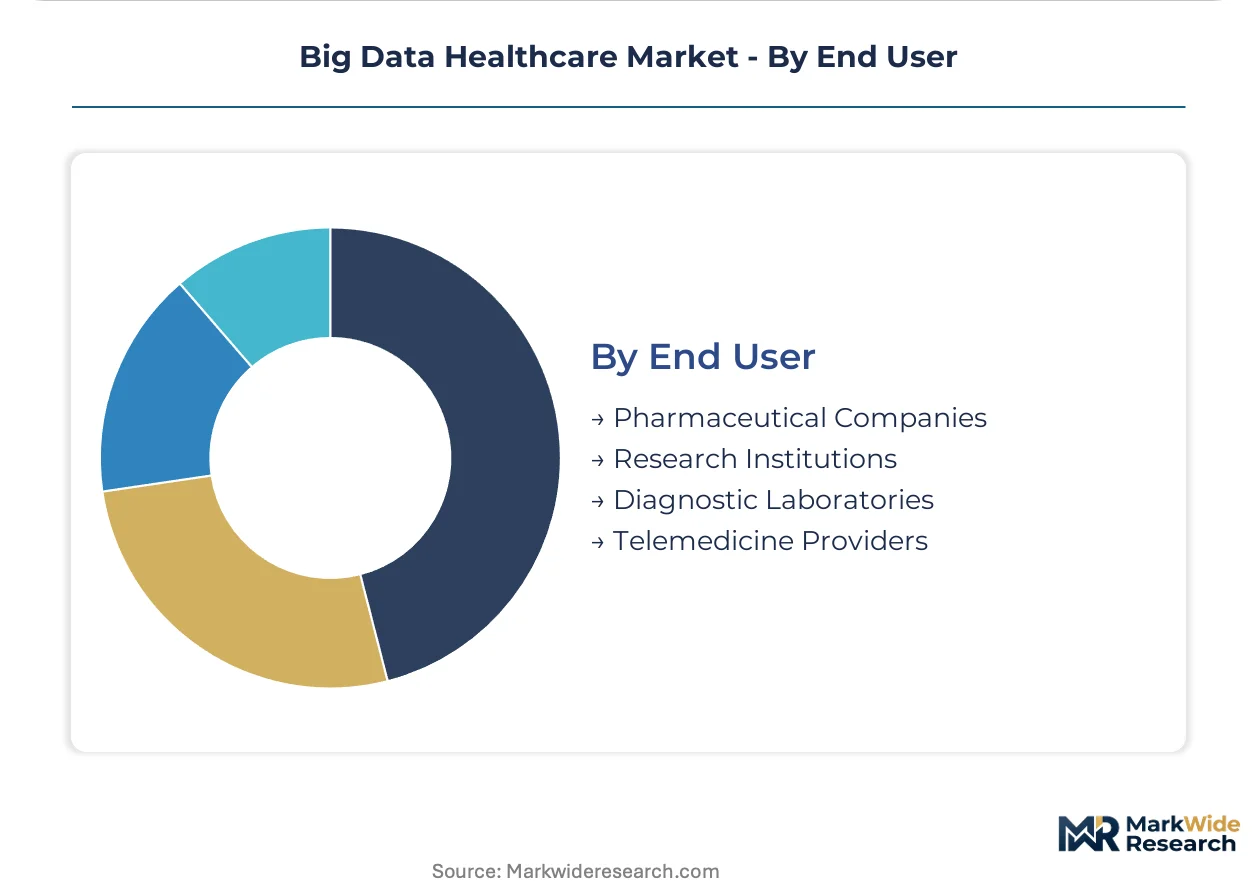
- Pharmaceutical Companies:Real-world evidence platforms and genomic analytics for pipeline acceleration. R&D procurement budgets expand fastest among all buyer categories.
- Research Institutions:Federated learning infrastructure and multi-institutional cohort discovery tools. NIH funding priorities shape demand concentration.
- Diagnostic Laboratories:Workflow automation and quality analytics for high-throughput testing. Quest Diagnostics and LabCorp scale standardize vendor relationships.
- Telemedicine Providers:Lightweight analytics for virtual care triage and chronic disease monitoring. Post-pandemic platform consolidation constrains standalone procurement.
Pharmaceutical companies deploy capital most aggressively; research institutions expand procurement most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Payer organizations and pharmaceutical companies concentrate procurement in the United States, while health system consolidation in Germany and cloud infrastructure expansion in Japan reshape regional demand patterns.
United States
Health system consolidation generates unified datasets spanning multiple states, enabling population-level analytics that smaller networks cannot replicate. The FDA's 21st Century Cures Act mandates interoperability standards that force open electronic health record APIs. The Boston-Cambridge corridor anchors pharmaceutical R&D procurement, where real-world evidence platforms compress clinical trial timelines.
Germany
Hospital networks prioritize revenue cycle analytics to offset statutory reimbursement compression under the Diagnosis-Related Groups system. The EU AI Act imposes conformity assessment requirements on clinical decision support systems marketed across member states. The Rhine-Ruhr metropolitan region concentrates health informatics talent pools that support multi-institutional federated learning deployments.
China
Domestic pharmaceutical manufacturers expand real-world evidence procurement to accelerate oncology pipeline decisions. NMPA software-as-medical-device guidance creates divergent certification pathways for AI diagnostics compared to Western frameworks. The Yangtze River Delta clusters academic medical centers deploying genomic analytics at scale for precision medicine initiatives.
United Kingdom
NHS Integrated Care Systems aggregate patient data across former Clinical Commissioning Group boundaries, creating larger analytics-ready populations. NHS England's Federated Data Platform procurement reshapes vendor relationships toward centralized national contracts. The Golden Triangle between London, Oxford, and Cambridge concentrates biotech startups commercializing academic research outputs.
Japan
Super-aging demographics drive demand for predictive analytics targeting frailty progression and long-term care resource allocation. PMDA guidelines on AI-enabled medical devices establish performance validation requirements that extend certification timelines. The Kanto region around Tokyo anchors cloud infrastructure investments from hyperscale providers serving mid-sized hospital networks.
Big Data Healthcare Market Key Industry Players
Player mix skews toward diversified technology conglomerates with healthcare verticals, creating a tiered structure where specialized health informatics vendors compete for niche contracts beneath platform-level incumbents. Three archetypes dominate: electronic health record natives controlling inpatient data pipelines, cloud hyperscalers anchoring enterprise data warehousing, and consulting firms integrating analytics into transformation engagements. Competitive moves concentrate on API-native interoperability certifications and strategic partnerships with academic medical centers for federated learning infrastructure.
Within the electronic health record tier, Epic Systems Corporation and Oracle Corporation occupy positions that exemplify divergent responses to information blocking mandates. IBM Corporation anchors the AI diagnostics specialist archetype. These three entities represent the dominant competitive anchors against which mid-sized vendors position differentiation strategies.
| Leading Market Players |
|---|
| Epic Systems Corporation |
| Oracle Corporation |
| IBM Corporation |
| Allscripts Healthcare Solutions |
| GE HealthCare |
| McKesson Corporation |
| IQVIA |
| Microsoft Corporation |
| Accenture |
| Others |
Cost & Logistics Intelligence
Petabyte-scale data infrastructure investments in United States hyperscale regions create asymmetric cost structures that concentrate supply among cloud-native vendors while compressing price floors for legacy on-premises alternatives. This scale dynamic forces mid-sized hospital networks toward subscription models that trade capital expenditure for operational flexibility, reshaping vendor margin structures across deployment tiers.
Pricing Analysis
Cost-plus contracts with annual CPI indexation dominate enterprise analytics procurement between integrated delivery networks and platform vendors. Three-tier pricing structure across premium, standard, and economy levels segments by data volume commitment and SLA guarantees, with pharmaceutical companies showing least price sensitivity due to R&D timeline acceleration imperatives. Pricing pressure stems from mid-sized providers consolidating vendor relationships through master service agreements that bundle electronic health record modules with population health analytics. Cloud-native entrants face acute price sensitivity among diagnostic laboratories prioritizing workflow automation over advanced machine learning capabilities.
Supply Chain Analysis
Implementation lead times for hybrid cloud deployments now stretch 8-14 months due to specialized health informaticist scarcity and HIPAA business associate agreement negotiations. Supply concentrates in the United States for electronic health record data pipelines, India for offshore analytics development centers, and Ireland for European Union data residency compliance. Raw material dependencies include NVIDIA GPU clusters for imaging analytics, genomic sequencing consumables from Illumina-anchored supply chains, and API middleware from specialized healthcare interoperability vendors. Single-source vulnerability runs through Epic Systems' dominant inpatient data pipeline position. Distribution runs through direct enterprise sales teams for large health systems and value-added resellers for mid-sized hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of clinicians with dual machine learning expertise constrains deployment velocity and inflates implementation costs across all buyer segments. This capability gap creates asymmetric returns for vendors investing in automated model deployment tools versus those dependent on manual configuration.
For Market Incumbents: Fortify API-native interoperability certifications ahead of FDA information blocking enforcement deadlines to preempt customer defection to cloud-native competitors. Pursue backward integration into federated learning infrastructure through academic medical center partnerships, locking in research computing demand that emerging entrants cannot replicate. Prioritize vertical integration of natural language processing engines trained on proprietary clinical documentation to defend against IBM's specialized AI diagnostics positioning. For New Entrants and Emerging Players: Differentiate on edge computing integration for Internet-of-medical-things devices, where latency-sensitive point-of-care analytics bypass incumbent cloud round-trip dependencies. Target telemedicine providers with lightweight chronic disease monitoring tools, the most penetrable segment given post-pandemic platform consolidation constraints. Pursue a channel partnership strategy with diagnostic laboratories seeking workflow automation without enterprise-grade infrastructure commitments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vendors with regulatory affairs infrastructure capable of navigating EU AI Act conformity assessments and FDA software-as-medical-device guidance simultaneously. Long-term viability hinges on federated learning architecture ownership that enables multi-institutional model training without protected health information centralization. Acquisition targets should demonstrate deployed revenue from pharmaceutical real-world evidence contracts. Monitor NIH funding priority shifts as the primary inflection signal for research institution procurement acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| API-Native Interoperability Certification | FDA 21st Century Cures Act mandates force open electronic health record data pipelines to third-party analytics integration. |
| Federated Learning Infrastructure Partnership | Privacy-preserving multi-institutional model training unlocks collaborative research across competing United States health systems. |
| Edge Computing Integration for IoMT Devices | Onboard inference capabilities bypass cloud latency for critical physiological monitoring applications at point of care. |
| Natural Language Processing Engine Development | Clinical documentation decomposition into codified phenotypes accelerates precision medicine trial patient recruitment timelines. |
| Real-World Evidence Platform Commercialization | Payer organizations monetize de-identified claims datasets to pharmaceutical manufacturers for post-market surveillance inputs. |
Research Approach
Desk research of FDA 510(k) clearance databases, CMS Medicare reimbursement filings, and hospital procurement contract disclosures preceded structured interviews with health system CIOs, pharmaceutical R&D analytics directors, and biomedical informatics program chairs. Primary fieldwork with accountable care organization executives and GPO contracts managers validated secondary estimates of population health management platform adoption. SEC filings from Oracle Corporation and IBM Corporation anchored cloud infrastructure investment tracking. Bottom-up triangulation across deployment model segmentation converged with top-down expenditure analysis from NIH and pharmaceutical R&D budget disclosures.
Variance decomposition across solution type, data source provenance, and end-user procurement sophistication shaped the analytical framework over the projection horizon. Modeled dimensions included predictive analytics versus population health management solution categories, electronic health record versus genomic data source dependencies, and pharmaceutical company versus hospital network buyer archetypes. CAGRs derived from logistic diffusion curves fitted to interoperability mandate compliance timelines and cloud infrastructure maturity indicators. Forecast inputs incorporated FDA information blocking enforcement intensity assumptions and state-level biometric privacy statute fragmentation patterns.
The analysis sits within stated boundaries; outcomes outside sustained HIPAA business associate agreement standardization or accelerated EU AI Act implementation timelines would require recalibration. Forecasts reflect documented assumptions regarding pharmaceutical R&D budget expansion rates and health system consolidation trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health Data Management
Hospital Management Software Market
Health Data Management
North America Clinical Data Analytics in Healthcare Market
Health Data Management
Patient Data Management Systems Market
Health Data Management
Medical Record Management System Market
Health Data Management
Data Monetization in Healthcare Market
Health Data Management
Global Healthcare Compliance Software Market
Health Data Management
Healthcare Data De-Identification Assurance Market
Health Data Management
Patient Data Management Software Market
Health Data Management
Global Chronic Care Management Software Market
Health Data Management
Healthcare Data Monetization Solutions Market
Health Data Management
Point-Of-Care Data Management Software Market
Health Data Management
Master Data Management in Healthcare Market
Health Data Management
Global Healthcare Data Storage Market
Health Data Management
Global Healthcare Financial Analytics Market
Health Data Management
Global Big Data Analytics in Healthcare Market
Health Data Management
Healthcare Data Annotation Tools Market