
 Healthcare Transportation Services Market | 2026-2036
Healthcare Transportation Services Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Transportation Services Market Outlook
CMS Emergency Medical Treatment and Labor Act certification is redrawing competitive boundaries for ambulance operators. MTM Inc. leverages its Medicaid broker footprint across multiple states to dominate non-emergency medical transport scheduling. Modivcare Inc. anchors its position through technology platforms that integrate ride coordination with payer systems. Global Medical Response Inc. sustains scale advantages via its nationwide emergency response infrastructure and air medical fleet coverage.
Healthcare transportation services encompass the organized movement of patients, medical specimens, equipment, and personnel across ground, air, and mobile clinic modalities, utilizing vehicles equipped with life-support systems, climate-controlled compartments, and HIPAA-compliant communication protocols to ensure continuity of care between facilities and homes. Non-emergency medical transport commands the largest volume share as Medicaid and Medicare programs mandate coverage for eligible beneficiaries traveling to dialysis, wound care, and behavioral health appointments. Mobile health clinics represent the fastest-expanding service type, converting commercial vehicle platforms into diagnostic and vaccination units that penetrate rural and underserved census tracts where fixed facility access remains limited.
FDA oversight of mobile medical device installations and DOT Federal Motor Carrier Safety Administration hours-of-service rules constrain operator fleet utilization and driver availability across interstate routes. CMS reimbursement coding under Healthcare Common Procedure Coding System directly determines revenue per trip for non-emergency transports, creating administrative complexity that favors large-scale contractors over fragmented local providers. Stakeholders must monitor evolving state Medicaid waiver structures and emerging Medicare Advantage supplemental benefit expansions that could shift volume toward managed care intermediaries and away from fee-for-service direct contracts.
Market Dynamics
Medicaid non-emergency medical transportation benefit rules in the United States are redrawing reimbursement flows and consolidating contractor networks around large-scale brokers capable of managing multi-state scheduling complexity.
Growth Catalysts
- CMS EMTALA certification expansion:Emergency Medical Treatment and Labor Act compliance requirements are filtering non-qualified ambulance operators from hospital contracting pools, concentrating volume among certified providers.
- Dialysis transport demand:Aging patient populations in Germany and Japan are expanding recurring trip volumes for chronic kidney disease treatment, creating predictable revenue streams for specialized fleet operators.
- Telehealth-integrated dispatch platforms:Real-time ride coordination systems linked to electronic health records are reducing no-show rates and optimizing vehicle utilization across Medicaid networks.
Market Restraints
- DOT FMCSA hours-of-service constraints:Federal Motor Carrier Safety Administration rules limit driver availability across interstate routes, compressing fleet utilization rates during peak demand windows.
- FDA mobile medical device oversight:Installation approval requirements for diagnostic equipment aboard mobile clinics extend deployment timelines and raise capital barriers for fleet expansion.
- Fuel cost volatility:Diesel and aviation fuel price fluctuations directly impact ground ambulance and air medical unit operating margins without proportional reimbursement adjustment mechanisms.
Strategic Opportunities
- Medicare Advantage supplemental benefit growth:Plan expansions covering non-emergency transport to wellness visits and preventive care appointments are opening new reimbursement channels outside traditional Medicaid.
- Rural mobile health clinic penetration:Underserved census tracts in the United States lacking fixed facility access present conversion opportunities for commercial vehicle platforms equipped with diagnostic capabilities.
- AI-powered predictive routing:Machine learning algorithms converging with real-time traffic and patient condition data are enabling dynamic dispatch optimization that reduces per-trip costs.
Industry Challenges
- EMT-Paramedic workforce scarcity:Certified emergency medical technician recruitment gaps in high-cost metropolitan markets are forcing wage inflation and service area contraction.
- HIPAA-compliant communication retrofitting:Legacy dispatch radio systems require expensive encryption upgrades to meet patient privacy mandates for electronic health information transmission.
- Air medical base certification timelines:FAA Part 135 operating certificate approvals for new helicopter emergency services locations extend 18-24 months, delaying geographic expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Transportation Services Market |
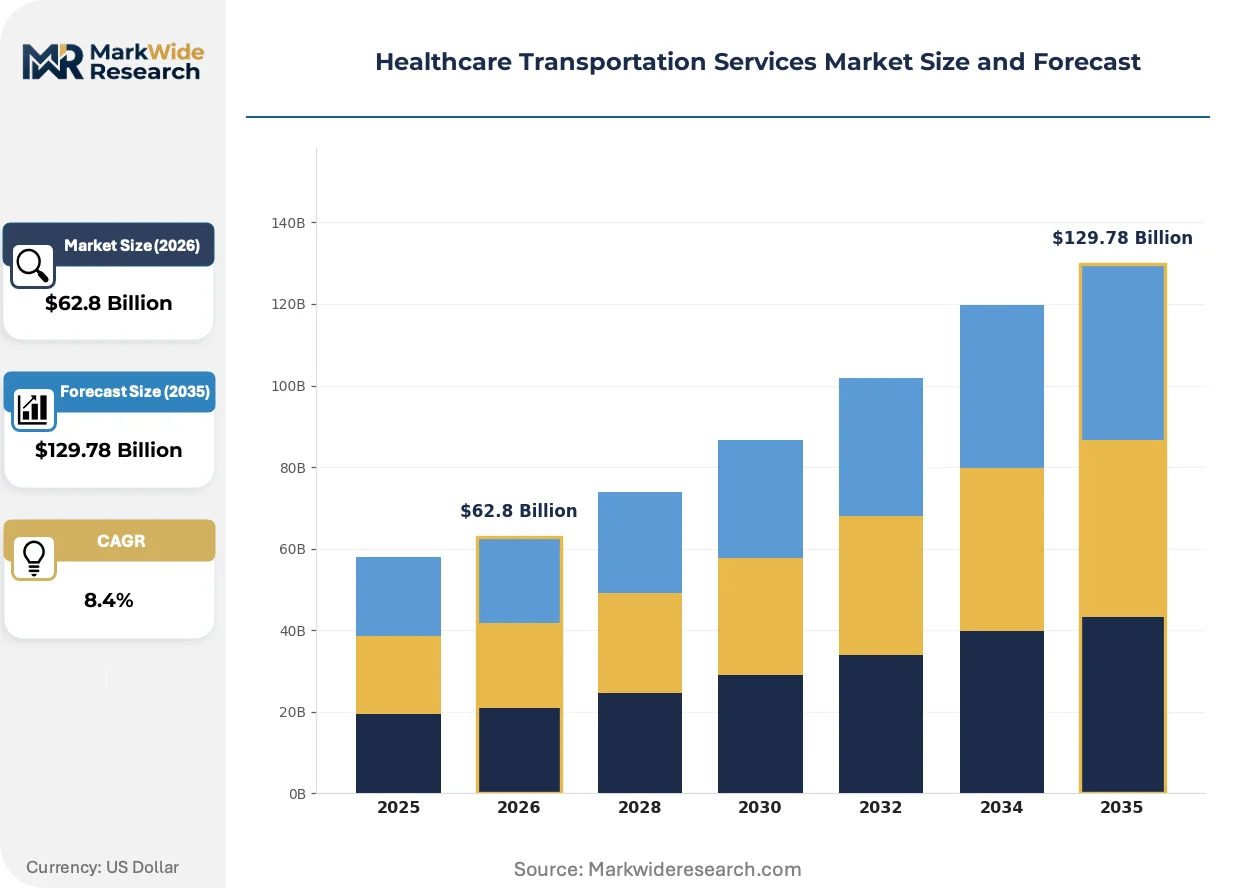
| Market Size in 2026 | $62.8 Billion |
| Market Size in 2035 | $129.78 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Non-Emergency Medical Transport, Ambulance Services, Air Medical Services, Patient Transfer, Mobile Health Clinics Application: Dialysis Transport, Organ Transplant, Emergency Response, Remote Patient Access, Chronic Care Access End User: Hospitals, Rehabilitation Centers, Nursing Facilities, Home Healthcare Providers, Medical Laboratories Distribution Channel: Direct Contracting, Third-Party Providers, Insurance Partnerships, Government Programs, Corporate Clients |
| Companies Covered | MTM Inc., Modivcare Inc., Global Medical Response Inc., Acadian Ambulance Service Inc., LogistiCare Solutions LLC, MedSpeed, DHL International GmbH, Falck USA Inc., Express Medical Transporters Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Transportation Services Market Strategic Shifts
Technology miniaturization and regulatory recalibration are compressing equipment footprints while expanding service modalities beyond traditional facility-to-facility transport.
Portable ventilators and cardiac monitors are miniaturizing to briefcase dimensions without sacrificing clinical functionality. Rural ambulance services and mobile health clinic operators are adopting these compact units to reduce vehicle payload and extend fuel range. The equipment downsizing is miniaturizing capital requirements for fleet conversion, enabling smaller contractors to enter markets previously dominated by hospital-affiliated systems.
EU MDR compliance deadlines for mobile medical devices are forcing manufacturers to resubmit technical documentation for equipment installed aboard cross-border transport vehicles. The recertification burden is delaying new mobile clinic deployments across Germany and France while favoring incumbent suppliers with established notified body relationships. Fleet operators are responding by consolidating procurement around MDR-compliant device portfolios to avoid stranded asset risk.
Hospital systems are unbundling after-hours discharge transport from inpatient billing, creating spot-market purchasing for non-emergency rides. This procurement fragmentation is displacing exclusive ambulance contracts with on-demand broker platforms that aggregate multiple vehicle classes. The shift is most visible in United States urban markets where Medicare Advantage penetration exceeds forty percent and plan administrators prioritize cost-per-trip metrics over relationship continuity.
Healthcare Transportation Services Market Segmentation
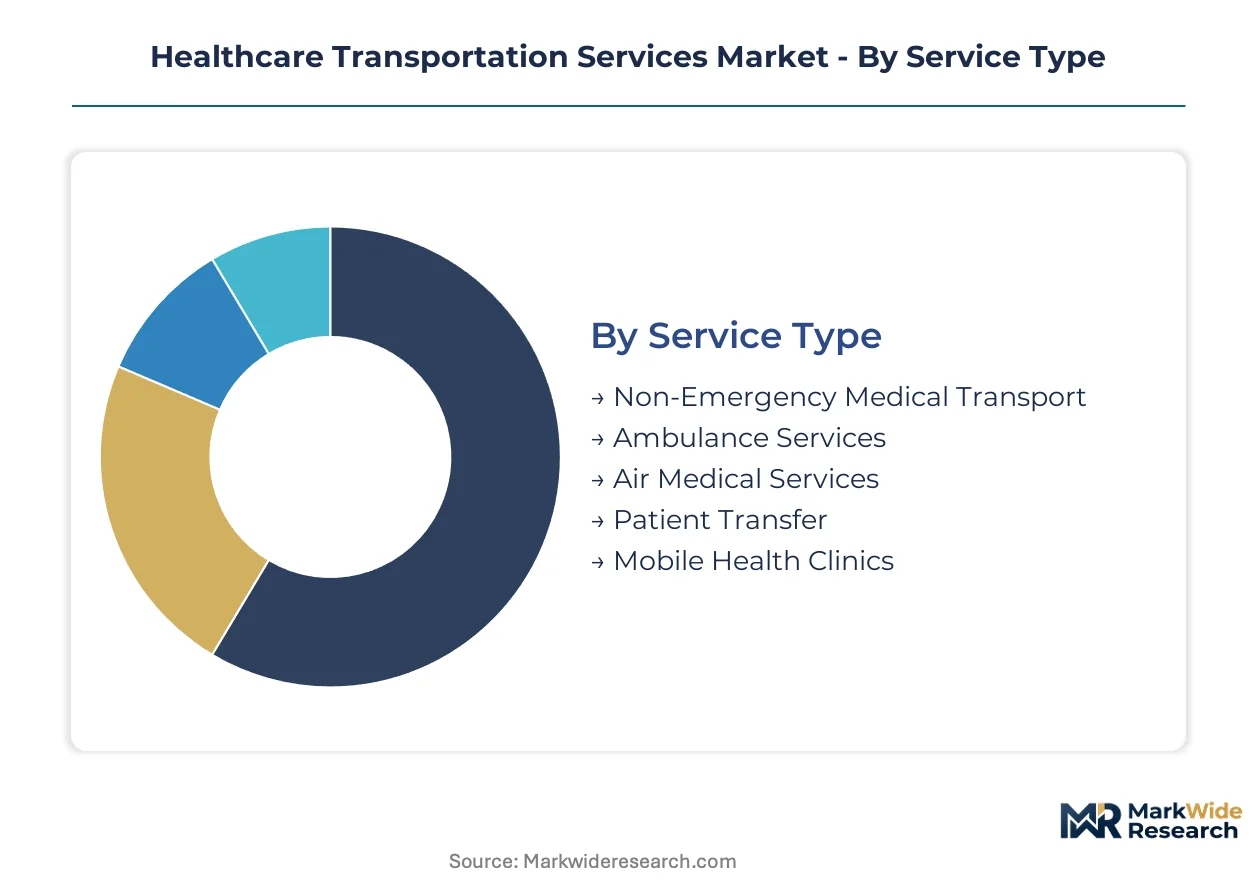
Service configuration determines reimbursement pathways and fleet investment intensity across the healthcare transportation services market. Segment boundaries shift as Medicaid brokers consolidate scheduling networks and Medicare Advantage plans expand supplemental transport benefits.
Service Type:
Channel flow varies sharply: government programs dominate non-emergency volume, while hospitals maintain direct contracts for emergency tiers.
- Non-Emergency Medical Transport:Scheduled patient movement utilizing wheelchair-accessible vans and sedans without life-support equipment. Demand concentrates among Medicaid beneficiaries traveling to dialysis and behavioral health appointments in the United States, where state broker networks mandate coverage.
- Mobile Health Clinics:Commercial vehicle platforms converted into diagnostic and vaccination units with climate-controlled compartments and portable medical devices. Rural census tracts in the United States lacking fixed facility access are driving fleet conversion, though FDA device installation approvals extend deployment timelines.
- Ambulance Services:Ground-based emergency response with EMT-paramedic crews and advanced life-support systems.
- Air Medical Services:Helicopter and fixed-wing transport for critical care transfers and remote access scenarios.
- Patient Transfer:Inter-facility movement for stable patients requiring medical monitoring during transit.
By volume, Non-Emergency Medical Transport leads. By growth pace, Mobile Health Clinics is ahead.
Application:
Cost tier stratification separates high-acuity emergency response from recurring chronic care routes with predictable scheduling.
- Dialysis Transport:Recurring thrice-weekly trips for end-stage renal disease patients utilizing specialized wheelchair vehicles. Aging demographics in Germany and Japan are expanding route density, creating revenue stability for fleet operators.
- Emergency Response:Time-critical dispatch for trauma, cardiac events, and acute medical crises requiring ALS-equipped vehicles and paramedic crews. Urban hospital systems in the United States concentrate demand, though EMT workforce scarcity is compressing service coverage.
- Chronic Care Access:Scheduled transport for wound care, diabetes management, and behavioral health appointments.
- Organ Transplant:Time-sensitive movement of recipients, donors, and preservation teams.
- Remote Patient Access:Connectivity solutions for geographically isolated populations.
Emergency Response commands premium pricing. Dialysis Transport delivers the steadiest utilization rates.
End User:
Customer type determines contract structure: health systems negotiate annual rates, while home health agencies purchase per-ride.
- Hospitals:Acute care facilities requiring 24/7 emergency response capacity and inter-facility transfer coordination. CMS EMTALA certification requirements in the United States are filtering non-qualified operators from contracting pools.
- Home Healthcare Providers:Agencies coordinating patient discharges and recurring medical appointments. Medicare Advantage supplemental benefit expansions are opening new reimbursement channels beyond traditional Medicaid.
- Nursing Facilities:Long-term care operators managing resident medical transport.
- Rehabilitation Centers:Post-acute facilities requiring specialized mobility equipment.
- Medical Laboratories:Specimen transport networks with temperature-controlled logistics.
Hospitals anchor contract value. Home Healthcare Providers are expanding fastest as site-of-care shifts accelerate.
Distribution Channel:
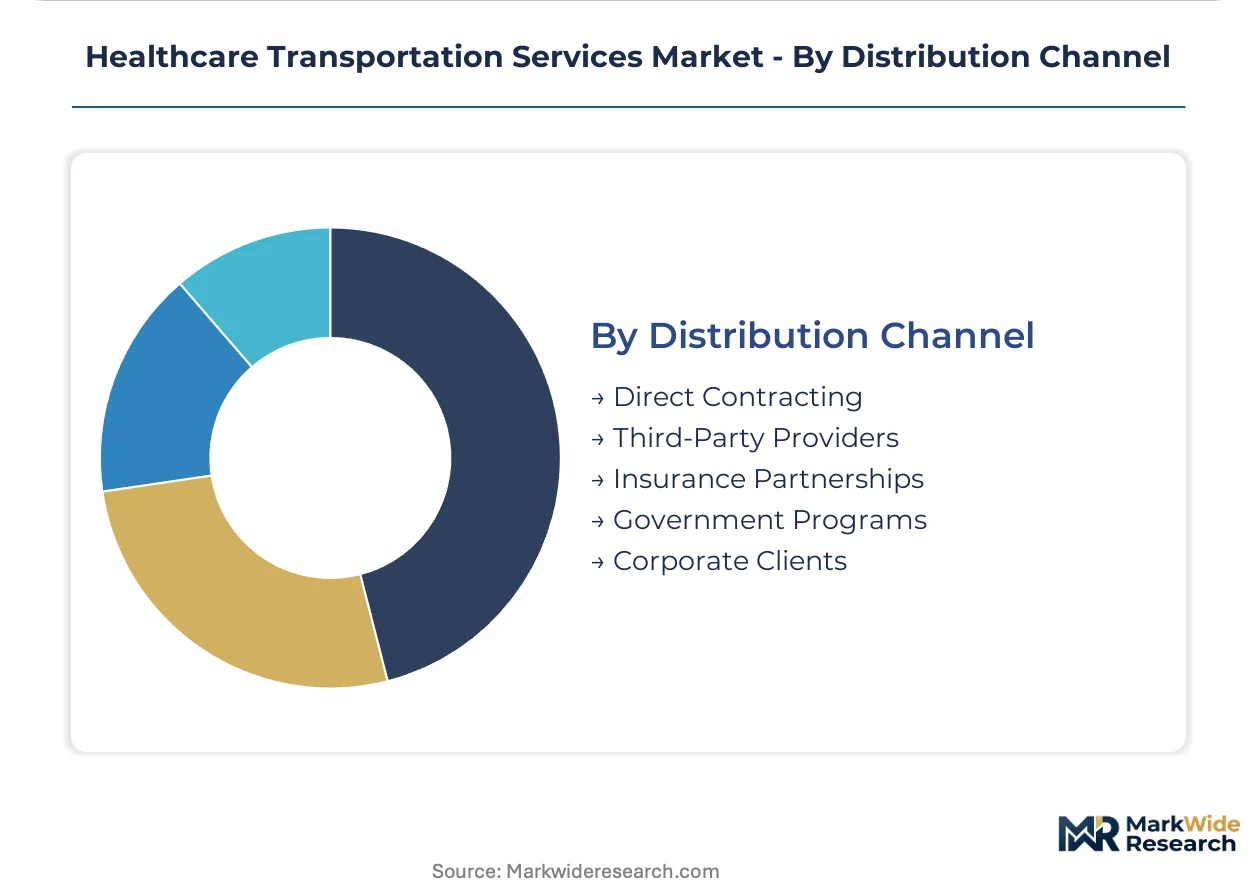
Supply concentration favors large-scale brokers capable of managing multi-state scheduling complexity and payer system integration.
- Government Programs:Medicaid and Medicare-funded transport with mandated eligibility criteria and regulated reimbursement rates. State waiver structures in the United States are consolidating contractor networks around brokers with multi-state footprints.
- Third-Party Providers:Independent brokers and transportation networks aggregating vehicle supply across multiple operators. Technology platforms integrating ride coordination with electronic health records are reducing no-show rates.
- Direct Contracting:Exclusive agreements between health systems and dedicated fleet operators.
- Insurance Partnerships:Managed care and commercial payer arrangements.
- Corporate Clients:Employer-sponsored transport for occupational health and wellness programs.
Government Programs dominate trip volume. Third-Party Providers are capturing share fastest as spot-market purchasing displaces exclusive contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital systems and Medicaid brokers concentrate purchasing power in the United States, while aging demographics in Germany and Japan sustain chronic care transport demand. Fleet operators prioritize these markets for contract density and reimbursement stability.
United States
Medicaid non-emergency medical transportation mandates drive recurring trip volumes for dialysis and behavioral health appointments. CMS EMTALA certification requirements filter non-qualified ambulance operators from hospital contracting pools. MTM Inc. and Modivcare Inc. anchor broker networks across multiple states, consolidating scheduling complexity under large-scale platforms.
Germany
Aging patient populations expand thrice-weekly dialysis transport routes with predictable revenue stability. EU MDR compliance deadlines for mobile medical devices delay new fleet deployments while favoring incumbent suppliers with established notified body relationships. Bavaria and North Rhine-Westphalia concentrate specialized wheelchair vehicle operators serving renal care networks.
Japan
Chronic kidney disease prevalence among elderly demographics sustains recurring transport demand for outpatient dialysis. METI guidelines on medical device quality management shape procurement standards for fleet conversion. Tokyo and Osaka metropolitan areas host the densest concentrations of scheduled non-emergency service providers.
United Kingdom
NHS England commissioning frameworks for patient transport services consolidate contracts around regional framework agreements. CQC registration requirements for ambulance operators constrain market entry for unqualified providers. London and the Southeast anchor contract value, while Midlands and Northern England present spot-market opportunities for on-demand brokers.
France
Regional health agencies (ARS) manage tender processes for non-emergency medical transport with standardized pricing grids. ANSM oversight of medical device installations aboard mobile clinics extends deployment timelines for diagnostic fleet conversion. Île-de-France and Auvergne-Rhône-Alpes concentrate ambulance cooperatives serving hospital discharge networks.
Healthcare Transportation Services Market Competitive Environment
Player mix skews toward Medicaid brokerage specialists with multi-state scheduling platforms and emergency response operators with CMS-certified infrastructure. The vendor base separates into three tiers: large-scale brokers managing payer system integration, hospital-affiliated ambulance systems with EMTALA certification, and regional fleet operators competing on per-trip cost. Dominant competitive moves include technology platform acquisitions for ride coordination and strategic partnerships with Medicare Advantage plans for supplemental benefit coverage.
Within the Medicaid brokerage tier, MTM Inc. and Modivcare Inc. exemplify platform-centric positioning through ride coordination systems integrated with state payer networks. Global Medical Response Inc. anchors the emergency response archetype with nationwide infrastructure and air medical fleet coverage. These three entities represent the concentration points around which contractor networks consolidate.
| Leading Market Players |
|---|
| MTM Inc. |
| Modivcare Inc. |
| Global Medical Response Inc. |
| Acadian Ambulance Service Inc. |
| LogistiCare Solutions LLC |
| MedSpeed |
| DHL International GmbH |
| Falck USA Inc. |
| Express Medical Transporters Inc. |
| Others |
Value Chain & Pricing Dynamics
Fleet utilization rates above seventy percent in United States Medicaid brokerage networks create scale thresholds that marginalize sub-scale operators and compress per-trip margins toward cost-plus floors. CMS reimbursement coding under HCPCS directly anchors price ceilings while fuel and labor cost pass-through clauses in state contracts determine margin volatility for ground transport providers.
Pricing Analysis
Cost-plus contracts with diesel fuel indexation dominate state Medicaid brokerage agreements, locking revenue per trip to regulated base rates plus variable cost adjustments. Pricing stratifies across ALS-equipped emergency tiers, wheelchair-accessible non-emergency vehicles, and unstaffed medical courier services based on crew certification levels and equipment payload. Cost compression in non-emergency tiers is intensifying because broker consolidation favors volume aggregators with technology platforms over asset-heavy local operators. Home healthcare agencies exhibit highest price sensitivity due to per-ride purchasing without annual volume commitments, while hospital systems negotiate multi-year exclusivity premiums.
Supply Chain Analysis
DOT-certified ambulance chassis manufacturing concentrates in the United States, Canada, and Germany, creating procurement bottlenecks when federal safety rule changes trigger redesign cycles. Fleet operators draw from specialized vehicle converters, portable medical device OEMs, and HIPAA-compliant communications hardware suppliers for platform assembly. Single-source vulnerability runs through sole-certified airframe providers for helicopter emergency services, constraining rapid fleet expansion. Distribution runs through state-procurement frameworks and hospital system contracting offices rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telehealth-enabled remote monitoring and hospital-at-home programs threaten recurring non-emergency transport volumes as payers substitute virtual care access for physical appointments. Incumbents must position technology platforms as care coordination hubs rather than ride brokers to defend against disintermediation.
For Market Incumbents: Shield recurring revenue streams by embedding predictive dispatch algorithms into electronic health record workflows, creating switching costs for health system customers facing EMT-Paramedic workforce scarcity. Pursue backward integration into driver training academies to captive-certify labor supply against wage inflation in high-cost metropolitan markets.
For New Entrants and Emerging Players: Lead with AI-powered dynamic routing platforms targeting rural census tracts where legacy brokers lack vehicle density and no-show rates exceed twenty percent. Penetrate Medicare Advantage supplemental benefit channels with per-member-per-month pricing models that displace fee-for-service spot purchasing.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Medicaid brokers with multi-state scheduling platforms and sticky payer system integrations. Long-term viability hinges on regulatory capture through state waiver relationships rather than asset-heavy fleet ownership. Monitor CMS Medicare Advantage supplemental benefit expansion rates as the inflection signal for volume migration away from traditional Medicaid contracting.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Platform Acquisition | MTM Inc. and Modivcare Inc. consolidate scheduling networks through proprietary ride coordination systems integrated with state Medicaid portals. |
| Air Medical Base Expansion | Global Medical Response Inc. extends FAA Part 135 certificate coverage to penetrate geographic gaps in emergency response infrastructure. |
| Mobile Health Clinic Conversion | Fleet operators retrofit commercial vehicle platforms with FDA-cleared diagnostic equipment to capture rural access reimbursement streams. |
| Medicare Advantage Partnership | Brokers negotiate supplemental benefit carve-outs with managed care plans for wellness visit transport outside traditional Medicaid eligibility. |
| Workforce Training Integration | Large-scale contractors establish in-house EMT certification programs to mitigate paramedic scarcity in high-wage metropolitan markets. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of CMS reimbursement databases, state Medicaid waiver filings, and DOT motor carrier safety records. Interviews with Medicaid program directors, ambulance fleet operations managers, hospital purchasing committee chairs, and Medicare Advantage plan administrators informed demand-side validation. Bottom-up trip volume estimates from state broker reporting systems triangulate against top-down market sizing derived from HCPCS claims data and GPO contract disclosures.
Segmentation dimensions modeled include service type, application acuity tier, end-user contract structure, and distribution channel concentration across the projection horizon. CAGRs derive from regression analysis of historical Medicaid enrollment growth, chronic disease prevalence trajectories, and Medicare Advantage penetration curves. Forecast inputs incorporate FDA mobile medical device approval timelines and FAA Part 135 certification backlog estimates for air medical fleet expansion.
The analysis sits within stated boundaries; outcomes outside sustained Medicaid funding levels and stable fuel cost pass-through mechanisms would require recalibration. Practitioners should keep alternative scenarios live as state waiver restructuring and telehealth substitution rates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Services
US Biopharmaceutical Third-Party Logistics Market
Healthcare Services
Global Sperm Bank Market
Healthcare Services
Europe Pharmaceutical Cold Chain Logistics Market
Healthcare Services
Healthcare Logistics Market
Healthcare Services
Chronic Disease Management Service Market
Healthcare Services
Asia-Pacific Healthcare Staffing Market
Healthcare Services
Hospital Workforce Management Market
Healthcare Services
Medical Spa Market
Healthcare Services
Life Science Trade Lane Design and Qualification Services Market
Healthcare Services
Healthcare Third-Party Logistics Market
Healthcare Services
Global Operating Room Management Market
Healthcare Services
Inhaled and Intranasal Products Contract Service Providers Market
Healthcare Services
Retail Clinics Market
Healthcare Services
United States Pharmaceutical Logistic Services Market
Healthcare Services
Acute Care Market
Healthcare Services
US Primary Care Physicians Market