
 Polypropylene Compounds Market | 2026-2036
Polypropylene Compounds Market Size, Share, and Industry Trends Forecast 2026-2036
Polypropylene Compounds Market Intelligence
Custom formulation development support is decoupling the sale of polypropylene compounds from a pure volume-based transaction. LyondellBasell Industries leverages its vast polymer portfolio to provide application-specific grades for automotive clients. Sumitomo Chemical specializes in high-purity compounds for the consumer electronics sector. SABIC positions its portfolio around circular economy solutions, including certified renewable and recycled-content products.
Polypropylene compounds are thermoplastic materials created by blending polypropylene resin with additives like glass fibers, mineral fillers, or flame retardants. This process enhances specific properties such as stiffness, impact strength, or thermal resistance beyond the base polymer's capabilities. Within product types, impact modified and heat stabilized grades command significant volume, driven by their use in automotive components. Injection molding remains the principal manufacturing process, essential for producing high volumes of consumer goods and electrical enclosures.
Regulatory frameworks like the EU’s REACH and China's GB standards govern chemical composition and material safety. In the United States, EPA regulations on volatile organic compounds directly influence the formulation of compounds used in automotive interiors. Compounders must now balance the demand for higher performance and recyclability with fluctuating feedstock costs and complex compliance landscapes.
Market Dynamics
The polypropylene compounds market is shaped by the structural tension between automotive sector demand for lightweighting and global regulatory pressure for circular economy-compliant materials. This dual mandate requires compounders to innovate beyond pure performance, embedding recyclability and verifiable recycled content into their core product offerings.
Growth Catalysts
- Automotive Lightweighting:The transition to electric vehicles necessitates the use of lighter materials to offset battery weight and extend range, driving adoption of glass fiber-reinforced PP compounds for structural and semi-structural components.
- EU End-of-Life Vehicles Directive:This regulation creates a direct incentive for automotive OEMs to design with recyclable thermoplastics like polypropylene compounds, ensuring higher recovery rates and stimulating demand for materials designed for disassembly.
- Consumer Electronics Miniaturization:Demand for smaller, thinner devices requires high-flow, flame-retardant PP compounds that can be injection molded into complex, thin-wall enclosures and internal structures, replacing heavier traditional plastics and metals.
Market Restraints
- Feedstock Price Volatility:The price of polypropylene resin is directly linked to fluctuations in propylene monomer, which is derived from volatile crude oil and natural gas markets, creating unpredictable production costs for compounders.
- Competition from Engineering Polymers:In applications requiring very high heat resistance or mechanical strength, engineering thermoplastics such as polyamides and polycarbonates present a significant substitution threat, capping the addressable market for PP compounds.
- Recycling Stream Contamination:The diversity of fillers, reinforcements, and colorants used in polypropylene compounds complicates sorting and reprocessing, hindering the creation of high-quality recycled feedstock and limiting circularity.
Strategic Opportunities
- Bio-based and Renewable Feedstocks:Developing polypropylene compounds from non-fossil, renewable sources provides a pathway for compounders to offer certified low-carbon products that align with corporate sustainability mandates and appeal to eco-conscious brands.
- Medical and Healthcare Grades:Expansion into specialized compounds for medical applications, such as sterilizable instrument trays and diagnostic consumables, offers a high-margin opportunity insulated from the cyclicality of the automotive sector.
- Functional Additive Integration:Incorporating advanced additives like conductive fillers or antimicrobial agents enables the creation of specialty compounds for smart surfaces in automotive interiors or hygienic applications in consumer goods and healthcare.
Industry Challenges
- Specialized Formulation Talent:A scarcity of polymer scientists and chemical engineers with expertise in balancing performance, cost, and sustainability attributes in compound formulations constrains the pace of custom product development.
- Navigating Global Regulations:Adhering to a complex and evolving web of chemical safety regulations, including REACH in Europe and various GB standards in China, requires significant compliance resources and continuous monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polypropylene Compounds Market |
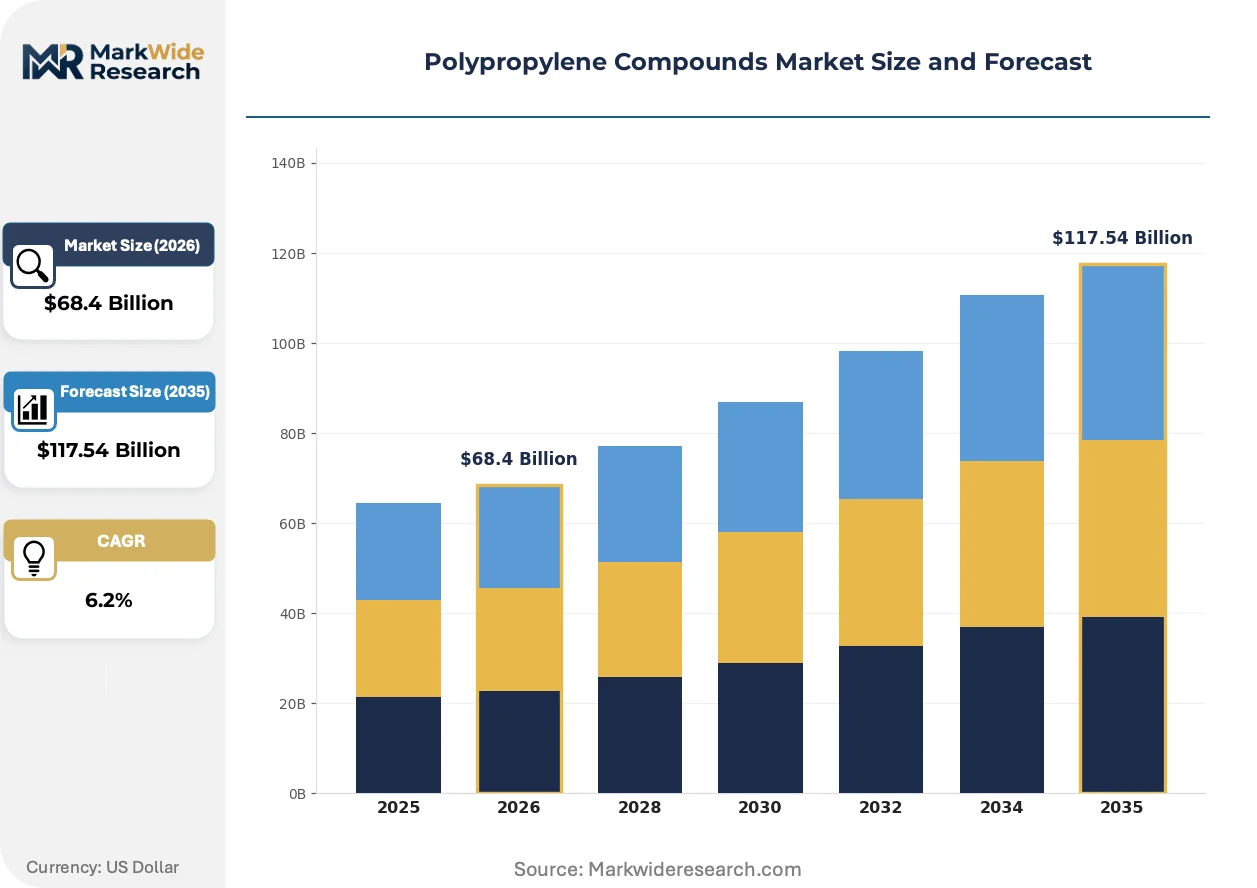
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $117.54 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Impact Modified, Flame Retardant, High Flow, Heat Stabilized, UV Stabilized Application: Automotive Components, Electrical Enclosures, Packaging Films, Consumer Goods, Construction Materials End User Industry: OEMs, Electrical Equipment Manufacturers, Packaging Firms, Consumer Electronics, Construction Contractors Manufacturing Process: Extrusion, Injection Molding, Blow Molding, Compression Molding, Calendering |
| Companies Covered | Sumitomo Chemical, Washington Penn, LyondellBasell Industries, Avient, Trinseo, ExxonMobil, Repsol, Kingfa Sci.&Tech., SABIC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polypropylene Compounds Market Strategic Shifts & Innovations
The evolution from a commodity product to an engineered material solution is reshaping the market. This shift is driven by demands for application-specific performance, particularly in automotive and electronics, and increasing regulatory requirements for supply chain transparency and end-of-life management.
Digital material passports provide a verifiable record of a compound's composition and lifecycle. Automotive OEMs and electronics manufacturers are adopting this technology to validate recycled content claims and meet sustainability targets. This innovation is decentralizing verification, shifting trust from paper certificates to a shared, immutable ledger that enables a more transparent and functional circular economy.
Regulatory frameworks like the European Union's Corporate Sustainability Reporting Directive (CSRD) are becoming a major market influence. The directive is forcing compounders to provide exhaustive data on raw material origins, manufacturing carbon footprint, and recyclability. The automotive and consumer packaging sectors are most affected, now demanding full material transparency from their suppliers to fulfill their own reporting obligations.
A notable behavioral shift involves end-users moving away from large-volume contracts for standard grades toward direct collaboration on smaller, custom-formulated batches. This trend disrupts the traditional distributor model, which is predicated on stocking high-volume materials. This direct engagement model is most visible in the medical device and specialty packaging sectors in North America and Europe, where application-specific properties are critical.
Polypropylene Compounds Market Segmentation
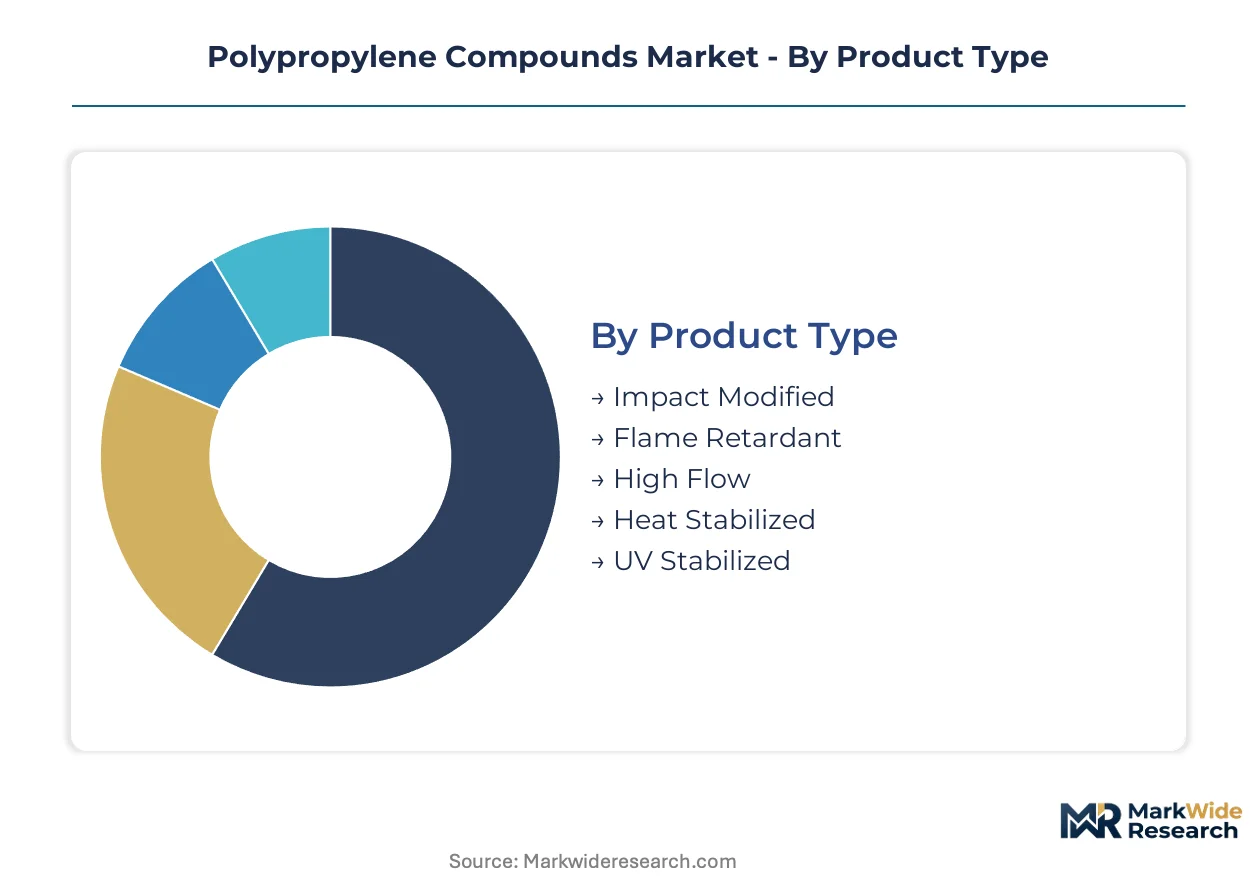
The polypropylene compounds market demonstrates diverse material requirements across its varied applications. Understanding this segmentation reveals how compounders tailor formulations to meet specific performance demands and regulatory compliance in end-use sectors. Performance attributes drive material selection for both new product development and material substitution initiatives.
Product Type:
The polypropylene compounds market often sees material upgrades driven by the need for enhanced performance over base resins. Compounders continuously develop new grades to replace older formulations or provide superior properties for demanding applications.
- Impact Modified:These compounds incorporate elastomers or other impact modifiers to significantly improve toughness and ductility, particularly at low temperatures, preventing brittle failure. Demand concentrates in automotive components, where impact resistance is critical for safety and durability in bumpers and interior panels.
- Heat Stabilized:Formulations with specialized additive packages protect polypropylene from thermal degradation during processing and extended high-temperature service, maintaining mechanical properties. This is crucial for under-the-hood automotive parts, where engine heat can compromise material integrity.
- Flame Retardant:These compounds contain additives that inhibit ignition and spread of flame, essential for safety-critical applications.
- High Flow:Designed for intricate geometries and thin-wall parts, these compounds offer reduced viscosity for faster cycle times in molding.
- UV Stabilized:Incorporating UV absorbers and hindered amine light stabilizers, these materials resist degradation from sunlight exposure.
Volume placements concentrate in Impact Modified compounds; the faster expansion belongs to Heat Stabilized grades.
Application:
The diverse applications for polypropylene compounds dictate specific material properties and processing requirements. Each sector demands tailored solutions to optimize product functionality and manufacturing efficiency.
- Automotive Components:Polypropylene compounds are widely used for interior, exterior, and under-the-hood parts due to their lightweighting potential, cost-effectiveness, and design flexibility. The shift to electric vehicles and stringent emissions regulations drive the adoption of these materials for structural and semi-structural parts.
- Electrical Enclosures:These compounds form protective housings for electronic devices and electrical systems, requiring properties like flame retardancy, insulation, and dimensional stability. Miniaturization in consumer electronics necessitates high-flow grades for complex, thin-walled designs.
- Packaging Films:Polypropylene compounds offer excellent barrier properties, clarity, and sealability for various food and non-food packaging.
- Consumer Goods:From appliances to furniture, these materials provide durability, aesthetic appeal, and processability for a wide range of household items.
- Construction Materials:Used in pipes, fittings, and roofing membranes, these compounds offer chemical resistance and weatherability.
Automotive Components command the largest share, while Electrical Enclosures demonstrate significant growth potential.
End User Industry:
The demand for polypropylene compounds is directly influenced by the manufacturing needs and product cycles of distinct end-user industries. Each industry requires specific material certifications and performance profiles.
- OEMs:Original Equipment Manufacturers, particularly in the automotive sector, drive substantial demand for custom-formulated polypropylene compounds for vehicle production. These companies prioritize materials that contribute to lightweighting, cost reduction, and compliance with regulations like the EU End-of-Life Vehicles Directive.
- Consumer Electronics:This industry requires high-purity, flame-retardant, and high-flow polypropylene compounds for casings, internal components, and accessories. Miniaturization and aesthetic demands push innovation in material design for devices.
- Electrical Equipment Manufacturers:These firms utilize compounds for insulation, connectors, and housings in various electrical systems.
- Packaging Firms:Companies producing flexible and rigid packaging solutions rely on PP compounds for their barrier properties and processability.
- Construction Contractors:This segment uses PP compounds for durable and weather-resistant building materials and infrastructure components.
OEMs represent the largest purchasing segment; Consumer Electronics is expanding most quickly.
Manufacturing Process:
The choice of manufacturing process dictates the rheological and mechanical properties required from polypropylene compounds. Processability is a critical factor for achieving efficient production and high-quality finished parts.
- Injection Molding:This process forms complex, high-precision parts by injecting molten polymer into a mold cavity, suitable for high-volume production of automotive and consumer goods components. The process demands compounds with specific melt flow rates and rapid solidification characteristics.
- Extrusion:Used for continuous profiles, sheets, films, and pipes, this process involves forcing molten polymer through a die. Extrusion requires compounds with consistent melt viscosity and thermal stability for uniform product dimensions.
- Blow Molding:This technique creates hollow parts like bottles and containers by inflating a parison inside a mold.
- Compression Molding:Primarily for thermosets but also used for large, flat thermoplastic parts, this process involves compressing material in a heated mold.
- Calendering:This process forms continuous sheets or films by passing polymer through a series of heated rollers.
Injection Molding dominates production volumes, while Extrusion processes maintain a steady demand across various applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The polypropylene compounds market exhibits a significant divide between production capacity and end-use consumption across various geographies. Manufacturing investments are increasingly concentrated in regions serving major automotive and electronics clusters. This dynamic influences material flow and supply chain strategies for compounders worldwide.
China
Demand for flame-retardant PP compounds surges in consumer electronics and EV battery housings. China's GB standards dictate material safety and performance for these applications. The Yangtze River Delta region, a major electronics manufacturing hub, drives innovation in high-flow and thin-wall compound formulations.
Germany
Automotive lightweighting initiatives propel the adoption of glass fiber-reinforced polypropylene compounds for vehicle interiors and exteriors. European Union REACH regulations ensure chemical safety and material compliance for compound producers. Bavaria, home to major automotive OEMs, sees advanced material development for new electric vehicle platforms.
United States
The automotive sector's shift to lighter materials for electric vehicles fuels demand for impact-modified PP compounds. EPA regulations on volatile organic compounds influence interior component formulations. Michigan's automotive manufacturing belt actively integrates specialized PP compounds for next-generation vehicle designs.
Mexico
Production capacity for polypropylene compounds is expanding to serve North American automotive OEMs. The country's favorable trade agreements incentivize local manufacturing of vehicle components. Mexico's Bajío region, a growing automotive manufacturing cluster, attracts significant investment in compounding facilities.
India
Consumer goods and emerging automotive sectors require robust and cost-effective polypropylene compounds. India's BIS standards guide material quality and performance for various industrial applications. Gujarat, a significant industrial state, experiences increased demand for customized PP compounds for appliance and vehicle parts.
Polypropylene Compounds Market Key Industry Players
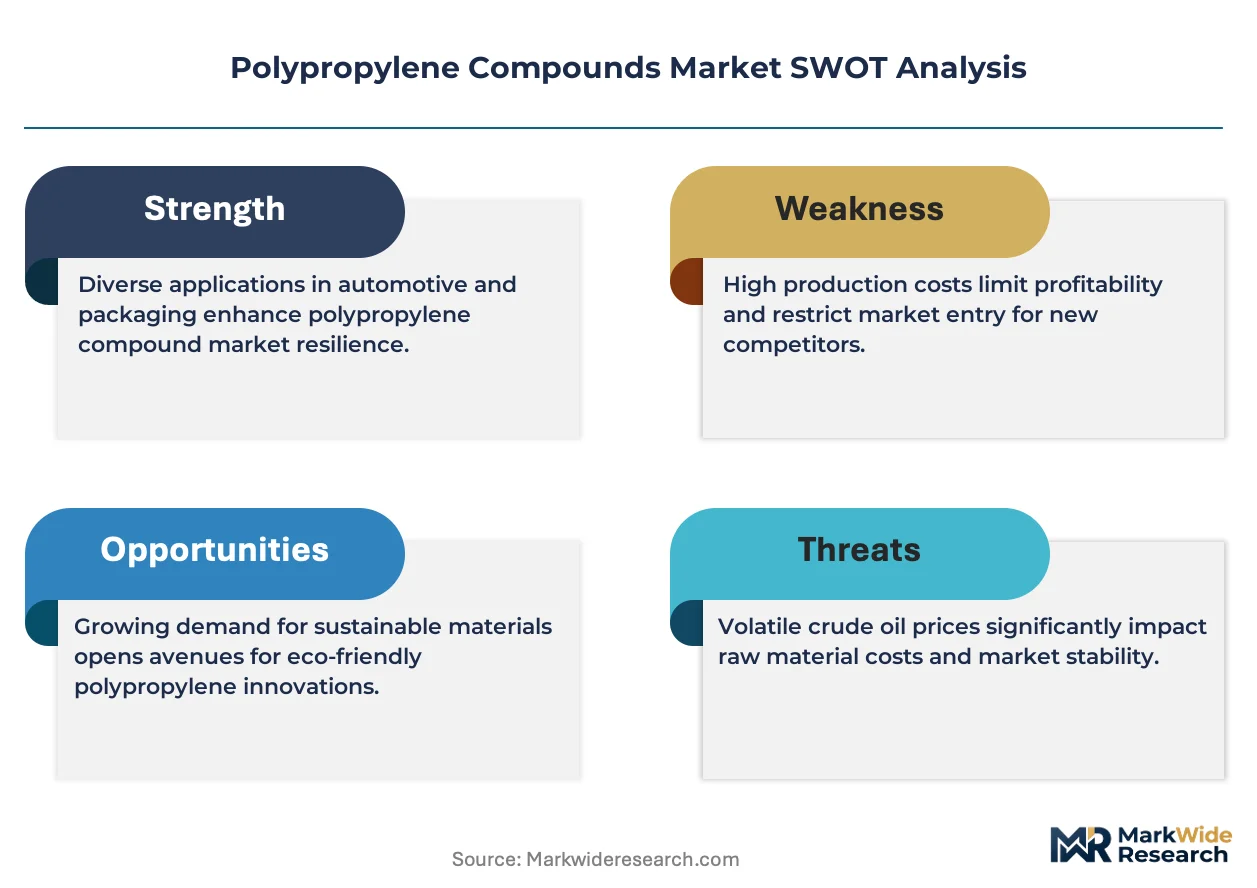
Capital-heavy producers compete with asset-light designers in the polypropylene compounds market, creating a tiered competitive landscape. Large integrated petrochemical companies often focus on raw material supply and high-volume standard grades. Specialized compounders differentiate through custom formulation development and application-specific solutions. Strategic partnerships for technology co-development and geographic expansion into emerging automotive manufacturing hubs are dominant competitive moves.
At the scale-driven end, LyondellBasell Industries, a global chemical company, exemplifies a broad portfolio approach, leveraging its extensive polymer assets for diverse automotive applications. Sumitomo Chemical, a Japan-based chemical group, occupies a position focused on high-purity compounds, particularly for the consumer electronics sector. SABIC, a Saudi Arabian multinational, represents a strategic emphasis on circular economy solutions, including certified renewable and recycled-content products within its offerings. These entities collectively demonstrate the varied strategies employed by major players to capture market share and respond to evolving sustainability mandates.
| Leading Market Players |
|---|
| Sumitomo Chemical |
| Washington Penn |
| LyondellBasell Industries |
| Avient |
| Trinseo |
| ExxonMobil |
| Repsol |
| Kingfa Sci.&Tech. |
| SABIC |
| Others |
Cost & Logistics Intelligence
Brent crude oil futures, a global commodity benchmark, directly influence propylene monomer costs, which then cascade into polypropylene resin prices and ultimately impact polypropylene compound pricing tiers. This foundational feedstock volatility creates significant cost uncertainty for compounders and their downstream customers.
Pricing Analysis
Margin tightening for standard polypropylene compounds reflects volatile feedstock costs, particularly propylene monomer. Pricing for these bulk materials often follows a contract-based long-term offtake model, heavily influenced by commodity spot prices. Custom-formulated grades, however, command value-based pricing, differentiating on customization level and specific certifications like REACH compliance or automotive OEM approvals. Automotive OEMs, purchasing high volumes, exhibit significant price sensitivity, while medical device manufacturers prioritize performance and certification over cost, showing lower price sensitivity.
Supply Chain Analysis
Workforce availability in key manufacturing geographies like China, Mexico, and Germany influences the operational efficiency of polypropylene compounders. The supply chain draws from a concentrated base of polypropylene resin producers and specialized additive suppliers globally. Single-source vulnerability for certain high-performance additives presents a structural risk, particularly for flame retardants or UV stabilizers. Distribution runs primarily through direct sales for custom-formulated solutions to OEMs and via specialized distributors for high-volume standard grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polypropylene compounds market presents a supply-constrained narrative, particularly for specialized grades. Limited production capacity for high-performance additives, such as certain flame retardants, creates a bottleneck that props up pricing for critical applications.
For Market Incumbents: Cement existing OEM relationships through advanced application engineering support, particularly for electric vehicle platforms. Invest in certified renewable and recycled-content polypropylene compounds to counter sustainability mandates and competitive threats from engineering polymers. Expand production capacity in automotive manufacturing hubs like Mexico to serve North American OEMs more efficiently. Pursue R&D in bio-based feedstocks to diversify away from volatile crude oil derivatives.
For New Entrants and Emerging Players: Capture niche opportunities by specializing in high-margin medical and healthcare grades, which require stringent certifications and offer insulation from automotive cyclicality. Target underpenetrated segments like specialty packaging in Europe with bio-based polypropylene compounds. Develop expertise in functional additive integration for smart surfaces in consumer goods. Leverage digital material passports as a go-to-market angle to ensure supply chain transparency.
For Investors and Strategic Acquirers: Distressed-cycle entries favor agile, specialized compounders in Europe with strong R&D capabilities in circular economy solutions. The market maintains long-term viability as polypropylene compounds remain essential for automotive lightweighting and consumer goods. Target companies with proprietary additive technologies or established relationships in high-growth medical applications. A key signal to watch is the increasing adoption rate of certified recycled content in major automotive OEM platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Mexico | Serves growing North American automotive manufacturing demand, leveraging favorable trade agreements. |
| R&D into Bio-based Feedstocks | Addresses corporate sustainability mandates and reduces reliance on volatile fossil fuel derivatives. |
| Application-Specific Grade Development | Decouples sales from pure volume, enabling premium pricing for specialized performance requirements. |
| Digital Material Passport Integration | Enhances supply chain transparency and validates recycled content claims for automotive OEMs. |
| Specialized Medical Grade Certification | Opens high-margin opportunities in healthcare, diversifying away from cyclical industrial sectors. |
Research Approach
Multi-period observation of polypropylene resin prices and automotive production volumes anchored the trend analysis, supplemented by interviews. Primary research engaged polymer scientists, automotive procurement leads, and regulatory compliance officers. Secondary validation involved chemical industry trade reports, EU REACH filings, and global automotive production databases. This approach utilized both bottom-up market sizing and top-down validation.
Segment-specific weighting across product type, application, end-user industry, manufacturing process, and regional production clusters formed the quantitative analytical framework across the analysis window. Compound annual growth rates were derived from historical data and projected forward based on identified market dynamics. Key forecast inputs included electric vehicle adoption rates and evolving regulatory mandates for material recyclability.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to feedstock price volatility and geopolitical shifts impacting trade. Forecasts reflect underlying assumptions regarding technological advancements and regulatory stability. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Conductive Plastic Compounds Market
Specialty Compounds
Potassium Gluconate Market
Specialty Compounds
Global Specialty Polymer Market
Specialty Compounds
GCC Specialty Chemicals Market
Specialty Compounds
US Non-Commercial Acrylic Paints Market
Specialty Compounds
Galactoarabinan Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
Special Effect Masterbatches Market
Specialty Compounds
Air-Laid Product Market
Specialty Compounds
Organosulfur Compounds Market
Specialty Compounds
Kokum Butter Market
Specialty Compounds
Resin Capsule Market
Specialty Compounds
United States Caustic Potash Market
Specialty Compounds
Collagen Hydrolysates Market
Specialty Compounds
North America Polyphenylene Sulfide Compounds Market
Specialty Compounds
Global Stable Isotope Labeled Compounds Market