
 Bio-Based Polypropylene Market | 2026-2036
Bio-Based Polypropylene Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Polypropylene Market Intelligence
Consolidated purchasing from major automotive and consumer packaged goods OEMs is hardening the qualification requirements for bio-based polypropylene suppliers. Braskem leverages its bio-based polymer expertise from its I'm green™ polyethylene platform. LyondellBasell competes on a global scale with its CirculenRenew portfolio. SABIC positions its certified renewable polypropylene within its TRUCIRCLE initiative to attract sustainability-focused customers.
Bio-based polypropylene is a polymer produced from renewable feedstocks, such as bio-naphtha derived from used cooking oil or other non-food biomass. It is chemically identical to its fossil-based counterpart, allowing it to function as a drop-in replacement in existing manufacturing processes without significant retooling. Within applications, packaging films and rigid automotive components represent the primary demand centers, driven by brand owner sustainability goals. The material is predominantly supplied in pellet and granule forms for high-volume injection molding and extrusion processes.
Regulations like the European Union's REACH framework and directives on single-use plastics directly incentivize the shift away from fossil-derived materials. In the United States, the EPA's oversight on chemical substances and the USDA's BioPreferred Program influence federal procurement. The critical decision for downstream users now centers on balancing the premium cost of bio-based grades against long-term supply chain resilience and consumer-facing brand value.
Market Dynamics
The central structural force shaping the bio-based polypropylene market is the collision between sustainability mandates from consumer-facing brands and the constrained supply of certified renewable feedstocks. This tension makes feedstock sourcing and certification the primary competitive battleground for suppliers.
Growth Catalysts
- Corporate ESG Mandates:Commitments from consumer packaged goods companies to reduce their carbon footprint create direct demand for bio-based polypropylene in food-grade packaging, particularly in the United States and Europe.
- Automotive Lightweighting:Pressure on automotive OEMs, especially within Germany, to meet emissions targets drives the specification of lightweight, sustainable materials for interior components, films, and under-hood parts.
- European Regulatory Pull:The EU Green Deal and associated directives on plastics create a strong incentive structure for brand owners to shift away from fossil-based polymers to avoid potential penalties and meet circular economy goals.
Market Restraints
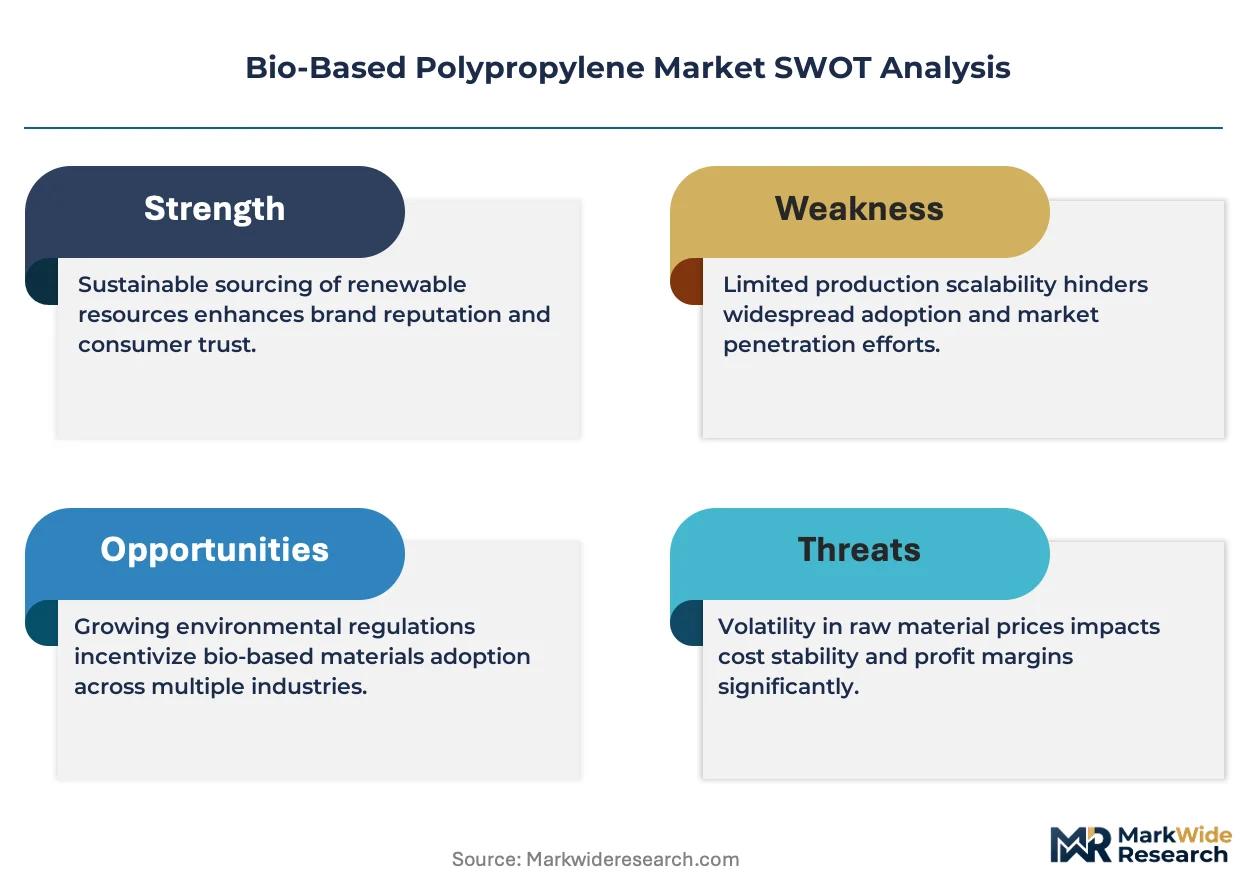
- Cost Premium:The production cost for bio-based polypropylene remains significantly higher than its fossil-fuel-derived equivalent, limiting adoption in price-sensitive applications without a strong brand or regulatory incentive.
- Feedstock Volatility:Reliance on a narrow set of feedstocks like bio-naphtha from used cooking oil exposes the supply chain to price fluctuations and competition from the biofuel industry, creating supply instability.
- Limited Production Scale:Global production capacity is concentrated among a few major chemical producers, creating a potential bottleneck that can hinder large-scale adoption by global OEMs requiring high-volume, multi-regional supply.
Strategic Opportunities
- Application Expansion:Developing specialized grades for high-value sectors such as medical devices, consumer electronics, and technical textiles offers a pathway to capture higher margins and diversify from packaging and automotive.
- Feedstock Diversification:Investment in second and third-generation feedstocks, including cellulosic biomass and waste-to-liquid technologies, can de-risk the supply chain and improve the overall sustainability profile.
- Asian Market Penetration:Targeting brand owners and regulators in Japan and South Korea, where consumer awareness of plastic waste is high, represents a significant growth vector for certified bio-based polymers.
Industry Challenges
- Certification and Auditing Burden:Navigating the complex and costly process of obtaining and maintaining chain-of-custody certifications, such as ISCC PLUS, across global supply chains presents a significant operational hurdle for suppliers.
- Infrastructure Integration:Integrating new bio-feedstock logistics and pre-processing with legacy petrochemical crackers and polymerization plants requires substantial capital investment and engineering expertise to manage co-processing effectively.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Polypropylene Market |
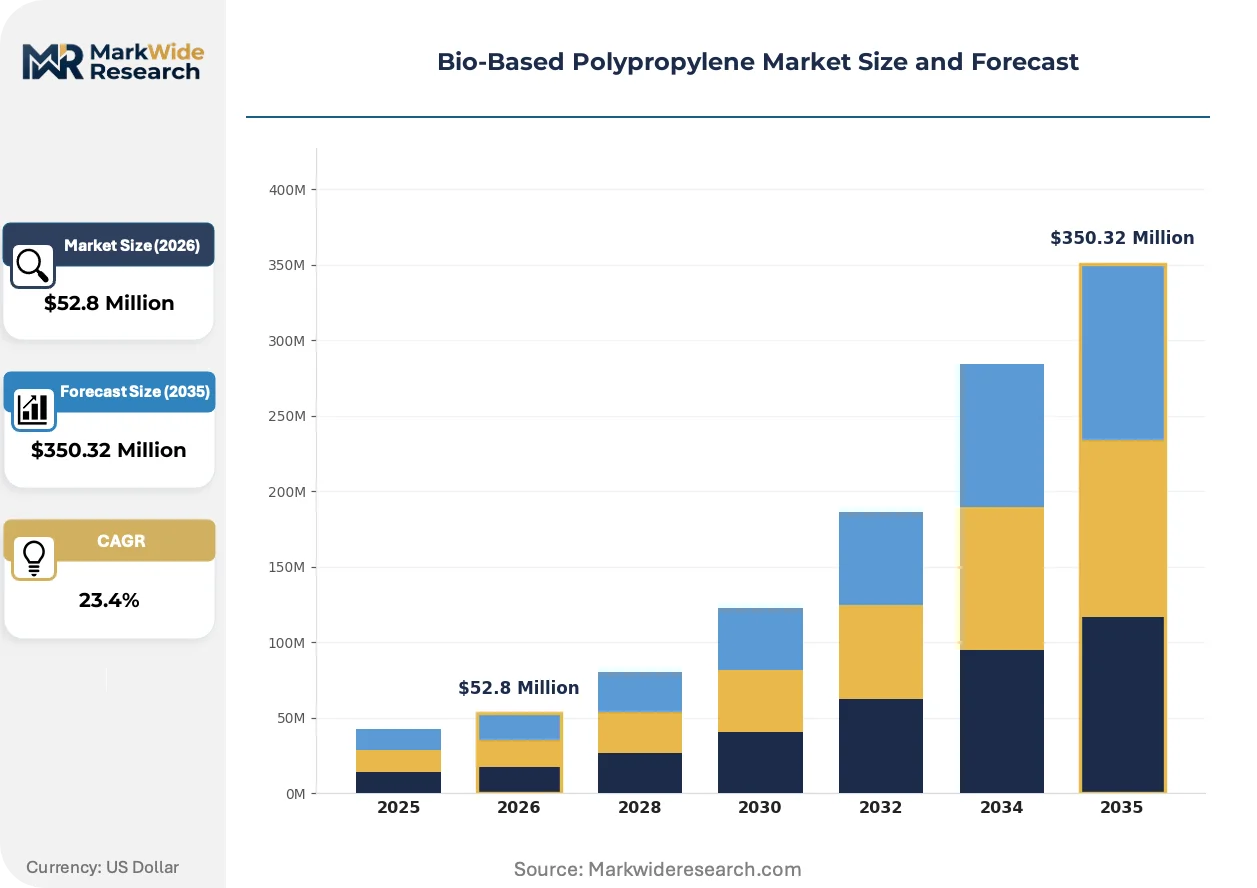
| Market Size in 2026 | $52.8 Million |
| Market Size in 2035 | $350.32 Million |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Homopolymer, Random Copolymer, Block Copolymer, Impact Copolymer Application: Packaging Films, Automotive Components, Consumer Goods, Electrical Appliances End User: Vehicle Assemblers, Electronics Manufacturers, Food & Beverage Producers, Textile Fabricators Form: Granules, Pellets, Powders, Sheets |
| Companies Covered | Braskem, LyondellBasell Industries Holdings B.V., Mitsui Chemicals, Inc., Borealis AG, SABIC, Neste Oyj, TotalEnergies, NaturePlast, CITRONIQ, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Polypropylene Market Strategic Shifts & Innovations
Material science is converging with supply chain logistics to make bio-based polymers commercially viable at scale. The market's innovation trajectory is defined by methods that allow renewable content to be introduced into existing industrial infrastructure with verifiable traceability for brand owners.
Mass balance accounting is the key chain-of-custody model enabling this transition. Major chemical producers and their downstream automotive and packaging clients are adopting this framework to claim bio-attributed content. This methodology is electrifying market entry by allowing certified bio-based materials to be produced in existing, commingled facilities, avoiding the prohibitive cost of building dedicated new plants.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is a significant regulatory driver. This mandate requires large companies to provide audited reports on their supply chain's environmental impact, including material sourcing. Consequently, procurement teams in the automotive and consumer goods sectors are demanding polymers with verifiable certifications, like bio-based polypropylene, to substantiate their public sustainability claims.
Design-for-circularity principles are altering material specification requirements beyond just renewable content. The traditional linear model is being displaced by demand for polymers that are both bio-based and compatible with existing recycling streams. This shift is most visible in the European food packaging industry, where brands are redesigning products to use monomaterial bio-PP to improve end-of-life recyclability.
Bio-Based Polypropylene Market Segmentation
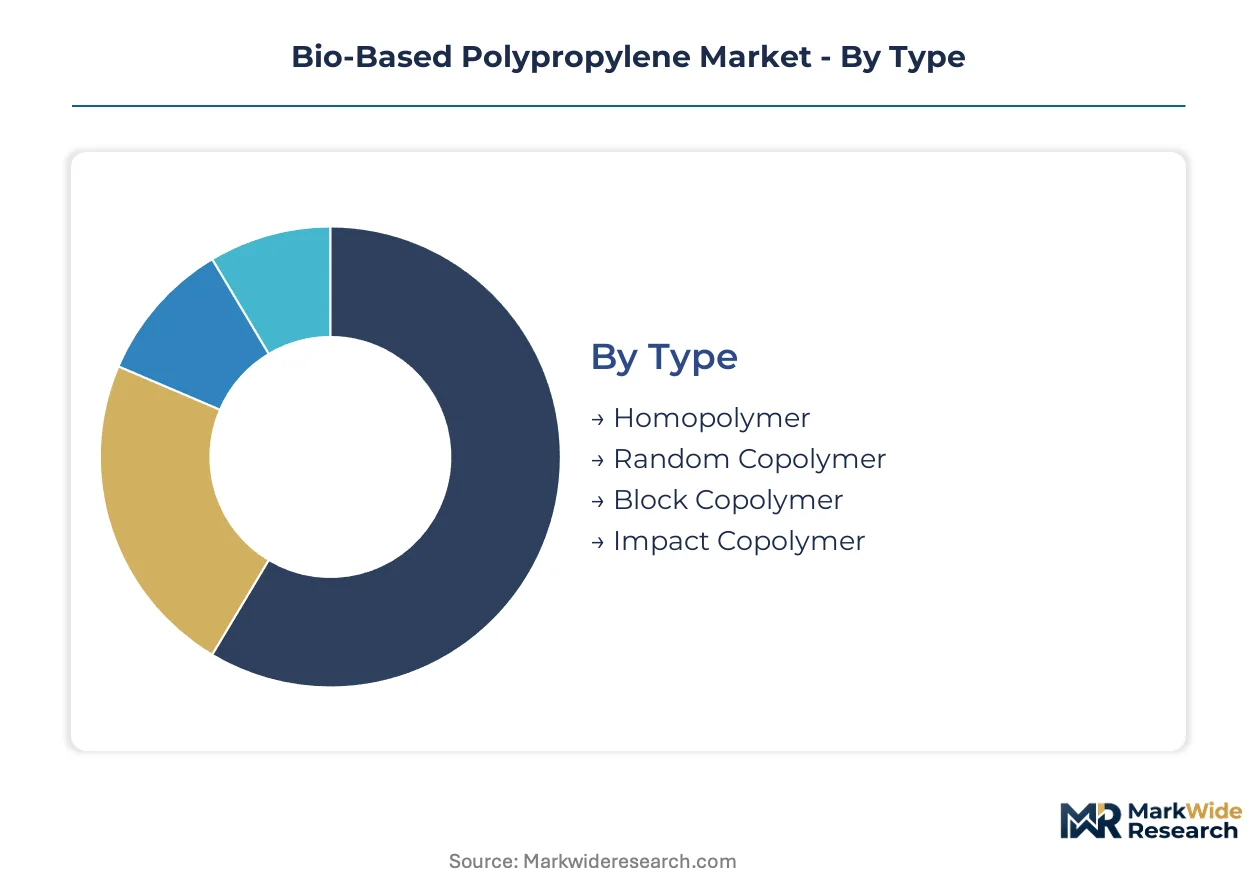
The bio-based polypropylene market exhibits distinct segmentation, reflecting the diverse technical requirements and end-use applications for sustainable polymer materials. Understanding these classifications provides clarity on where innovation and demand concentration are occurring across the industry value chain.
Type:
The classification of bio-based polypropylene by type reflects its molecular architecture and resulting performance characteristics.
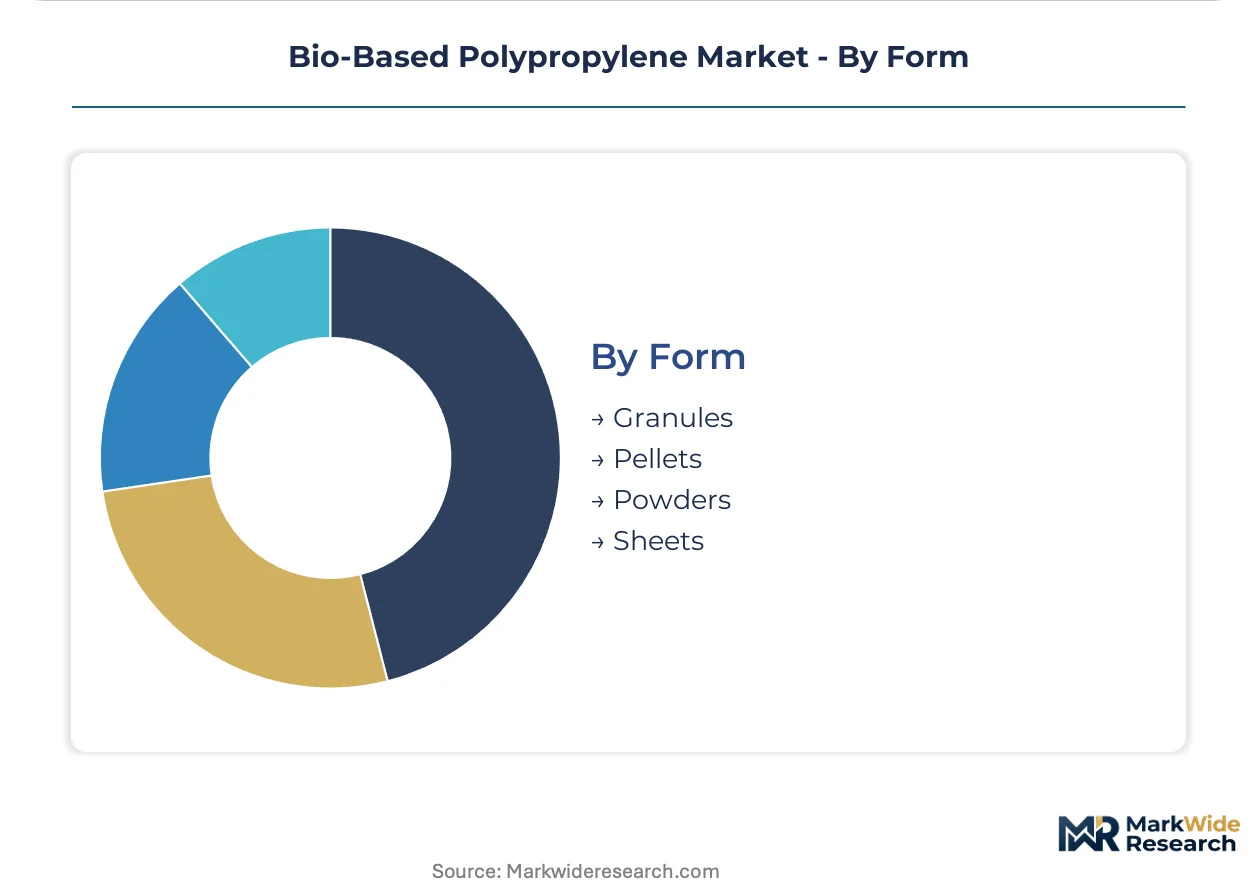
- Homopolymer:This type is known for its high stiffness and elevated melting point. Demand concentrates in rigid packaging and fiber applications, driven by requirements for mechanical strength and cost-efficiency in high-volume production.
- Impact Copolymer:Characterized by enhanced toughness and superior impact resistance. Automotive component manufacturers, particularly in Germany, specify this type for interior and under-hood parts, responding to stringent lightweighting and durability standards.
- Random Copolymer:Offers improved clarity and flexibility compared to homopolymers. This type finds application in packaging films and consumer goods requiring transparency and a softer feel.
- Block Copolymer:Combines properties from both homopolymers and random copolymers. It is utilized in specialized applications demanding a balanced blend of rigidity and impact strength.
Homopolymer leads on scale; Impact Copolymer leads on momentum.
Application:
Market demand for bio-based polypropylene is primarily shaped by its suitability across diverse application sectors.
- Packaging Films:Represents a major consumption area due to brand owner sustainability goals. Food-grade packaging in the United States drives significant volume, seeking drop-in replacements for fossil-based films.
- Automotive Components:Valued for lightweighting and reduced carbon footprint. German automotive OEMs integrate bio-based polypropylene into interior trim and under-hood parts, fulfilling emissions reduction mandates.
- Consumer Goods:Includes household items and durable products. Manufacturers integrate bio-based polypropylene for items requiring strong sustainability credentials.
- Electrical Appliances:Utilizes the material for housings and various internal components. This application seeks bio-based alternatives for enhanced environmental compliance.
Packaging Films command the largest share, while Automotive Components show the steepest expansion trajectory.
End User:
The end-user landscape for bio-based polypropylene reflects direct procurement by various manufacturing industries.
- Food & Beverage Producers:Primarily demand bio-based polypropylene for sustainable packaging solutions. Consumer packaged goods companies globally prioritize materials aligning with their ESG mandates and consumer preferences.
- Vehicle Assemblers:Integrate bio-based polypropylene into their supply chains for diverse automotive parts. OEMs in Europe, particularly Germany, seek these materials to meet stringent emissions targets and lightweighting objectives.
- Electronics Manufacturers:Incorporate bio-based polymers into device casings and internal components. This segment aims for reduced environmental impact in product design.
- Textile Fabricators:Explore bio-based polypropylene for non-woven fabrics and technical textiles. They seek sustainable alternatives for specialized material requirements.
Food & Beverage Producers drive substantial volume, with Vehicle Assemblers demonstrating increasing material specification.
Form:
The physical form of bio-based polypropylene dictates its suitability for various manufacturing processes and end-use applications.
- Pellets:Represent the most common form for high-volume processing methods. Injection molding and extrusion operations widely utilize pellets for efficient material handling and consistent quality.
- Granules:Offer similar processing advantages to pellets but often for specialized applications. These are critical for specific compounding and blending operations within the polymer industry.
- Powders:Used in specialized additive manufacturing and coating applications. This form allows for fine-tuned material properties and surface finishes.
- Sheets:Primarily utilized for thermoforming and vacuum forming processes. These are essential for rigid packaging and certain automotive interior components.
Pellets dominate the supply chain for their processing versatility, while Granules maintain a steady demand in niche applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States drives significant demand for bio-based polypropylene in food packaging, Germany spearheads its adoption within the automotive sector. This market's geographic spread reflects both regulatory incentives and specific industrial needs across key global economies. Regional dynamics influence material specification and supply chain development.
United States
Food-grade packaging and consumer goods producers create substantial demand for bio-based polypropylene. The USDA's BioPreferred Program influences federal procurement and encourages bio-based product development. California's advanced materials sector, particularly around Silicon Valley, drives innovation in sustainable polymer applications.
Germany
Automotive lightweighting and interior component manufacturing represent primary demand drivers. The KBA (Federal Motor Transport Authority) emissions targets and the broader EU Green Deal incentivize material shifts. Bavaria's automotive manufacturing hubs, including Munich and Stuttgart, increasingly specify bio-polypropylene for new vehicle platforms.
Japan
Consumer awareness of plastic waste and sustainability goals in electronics casings fuel demand. The METI (Ministry of Economy, Trade and Industry) promotes circular economy initiatives and bio-based material research. Tokyo's extensive consumer electronics industry integrates bio-based plastics for enhanced product environmental profiles.
South Korea
Packaging films and technical textiles are significant application areas for bio-based polypropylene. The MFDS (Ministry of Food and Drug Safety) influences standards for food contact materials, pushing for sustainable alternatives. Seoul's advanced manufacturing sector actively explores sustainable materials for diverse industrial and consumer applications.
France
Packaging films and consumer goods sectors drive demand, supported by European regulatory mandates. The EU's Corporate Sustainability Reporting Directive (CSRD) impacts French companies' material sourcing decisions. Lyon's chemical industry cluster focuses on developing and producing advanced bio-based polymers for the European market.
Bio-Based Polypropylene Market Key Industry Players
Global chemical giants anchor one tier; specialized bio-polymer developers hold another in this market's structure. The competitive environment is tiered, featuring large incumbent chemical producers alongside agile, innovative bio-material specialists. Strategic archetypes include diversified polymer manufacturers, dedicated bio-plastic innovators, and feedstock suppliers. Dominant competitive moves involve capacity expansion and the formation of strategic partnerships to secure feedstock supply and market access.
Within the diversified chemical conglomerate archetype, Braskem and LyondellBasell Industries Holdings B.V. exemplify companies leveraging extensive polymer expertise to develop bio-based offerings. These players utilize their global manufacturing footprints and existing customer relationships to introduce certified renewable polypropylene. Neste Oyj, on the other hand, anchors the feedstock supply side, providing bio-naphtha that enables other producers to create bio-attributed polymers through mass balance accounting.
| Leading Market Players |
|---|
| Braskem |
| LyondellBasell Industries Holdings B.V. |
| Mitsui Chemicals, Inc. |
| Borealis AG |
| SABIC |
| Neste Oyj |
| TotalEnergies |
| NaturePlast |
| CITRONIQ, LLC |
| Others |
Cost & Logistics Intelligence
German automotive OEMs' strong demand for bio-based polypropylene underpins a value-based pricing model. This approach prioritizes material performance and sustainability credentials over pure cost.
Pricing Analysis
Capacity additions in Europe are reshaping price floors for bio-based polypropylene. The dominant pricing model involves contract-based long-term offtake agreements, driven by supply security and volume scale. Price differentiation stems from ISCC PLUS certification levels and customized performance grades. Cost compression is intensifying for standard bio-based grades due to competition from conventional fossil-based polymers, making packaging film applications highly price-sensitive compared to automotive components.
Supply Chain Analysis
Single-source vulnerability sits with the limited global production capacity concentrated among a few major chemical producers in Europe and North America. The supply chain relies heavily on bio-naphtha derived from used cooking oil and other non-food biomass. A structural risk is feedstock volatility, exacerbated by competition from the biofuel industry. Distribution typically runs through direct sales channels to large automotive OEMs and consumer packaged goods manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bio-based polypropylene market is entering a late-cycle quality story, driven by demanding brand owner sustainability goals. This shift mandates premium specifications for verifiable bio-attributed content in packaging and automotive applications.
For Market Incumbents: Anchor existing market share by aggressively expanding certified production capacity in Europe and the United United States. Secure long-term feedstock contracts to mitigate volatility, a persistent threat to stable pricing. Invest in R&D for second and third-generation feedstocks, ensuring a sustainable supply chain against rising competition for bio-naphtha. Strengthen ISCC PLUS certification processes to meet evolving regulatory demands.
For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for specialized bio-based polypropylene grades targeting high-value sectors. Focus on underpenetrated applications like medical devices and consumer electronics, which demand specific material properties. Penetrate Asian markets, particularly Japan and South Korea, where consumer awareness of plastic waste is high. A go-to-market angle emphasizing verifiable certifications and superior performance in niche applications will be critical.
For Investors and Strategic Acquirers: Diversified chemical conglomerates are the most active acquirers in this space, seeking to expand their bio-polymer portfolios. The market demonstrates strong long-term viability, underpinned by increasing corporate ESG mandates and regulatory pull from Europe. Target specialized bio-polymer developers or feedstock technology innovators with proven commercialization pathways. The signal to watch is successful scale-up of second and third-generation feedstock processing technologies for cost parity.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases supply stability for high-volume automotive and packaging clients in Europe. |
| Long-term Feedstock Contracts | Mitigates price volatility and ensures consistent supply of bio-naphtha for production. |
| Green Manufacturing Transition | Enhances sustainability credentials, attracting brand owners with strict ESG mandates. |
| Specialized Grade Development | Captures higher margins in niche applications like medical devices and consumer electronics. |
| Asian Market Penetration | Addresses growing consumer awareness and regulatory incentives in Japan and South Korea. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary insights derive from interviews with procurement leads at automotive OEMs, R&D directors at chemical producers, and sustainability officers at CPG brands. Secondary validation utilizes EU Green Deal reports, EPA publications, and company sustainability disclosures. This approach ensures robust data triangulation across the market.
An input-output matrix frames the quantitative forecast, mapping supply-side capacity against demand across the analysis window. Segmentation dimensions include polymer type, application, end-user, and form, alongside regional regulatory frameworks. Compound annual growth rates are derived from historical trends, projected feedstock availability, and anticipated demand shifts. Key forecast inputs include bio-naphtha supply projections and automotive lightweighting mandates.
Revisions become necessary when significant shifts in feedstock availability or new regulatory incentives materialize. Forecasts reflect assumptions regarding production costs and adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Soil Release Polymer Market
Polymers & Resins
Polychlorotrifluoroethylene (PCTFE) Market
Polymers & Resins
Biaxially Oriented Polypropylene Market
Polymers & Resins
Non-Ionic Polyacrylamide Market
Polymers & Resins
Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Asia-Pacific Fluoropolymer Market
Polymers & Resins
Middle East Polyamide Market
Polymers & Resins
US Acrylic Solid Surface Market
Polymers & Resins
Polysulfide Market
Polymers & Resins
Europe Epoxy Resins Market
Polymers & Resins
Chlorinated Polyvinyl Chloride (CPVC) Market
Polymers & Resins
Polyvinyl Alcohol (PVA) Market
Polymers & Resins
Polyelectrolyte Market
Polymers & Resins
Global Unplasticized Polyvinyl Chloride (UPVC) Windows Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Bio-Based and Synthetic Polyamide Market