
 US Non-Commercial Acrylic Paints Market | 2026-2036
US Non-Commercial Acrylic Paints Market Size, Share, and Industry Trends Forecast 2026-2036
US Non-Commercial Acrylic Paints Market Analytics
Multi-source pigment procurement is consolidating as manufacturers reduce reliance on overseas titanium dioxide suppliers. Golden Artist Colors leverages domestic mineral sourcing to sustain premium heavy body production. Liquitex Artist Materials anchors its position through in-house resin polymerization capabilities. DecoArt competes on volume scale across craft-oriented fluid acrylic lines.
US non-commercial acrylic paints comprise pigment dispersions suspended in acrylic polymer emulsion, with formulations typically containing 10-30% solids by volume and drying to water-resistant flexible films within 20-40 minutes at standard conditions. These paints serve amateur through professional creators requiring durable, fast-drying colorants for canvas, paper, wood, and mixed media substrates. Heavy body acrylics dominate value pools due to professional artist preference for impasto retention and high pigment load. Fluid acrylics represent the fastest-expanding category as pour painting and resin art techniques gain traction in hobbyist communities. Art supply stores retain margin concentration through knowledgeable staff and brand exclusivity arrangements, though online retail is displacing regional distribution in rural markets.
The EPA regulates volatile organic compound thresholds under architectural coatings rules, while OSHA sets workplace exposure limits for pigment handling facilities; California's South Coast Air Quality Management District imposes additional formulation constraints that manufacturers must navigate for coastal market access. ASTM International pigment permanence standards shape consumer quality expectations and premium pricing justification. Stakeholders should monitor state-level chemical restriction trajectories and invest in water-borne polymer research ahead of tightening coastal emission benchmarks.
Market Dynamics
EPA VOC emission thresholds under the Clean Air Act are forcing reformulation of acrylic polymer emulsions, compressing solvent-borne production capacity while elevating water-borne R&D investment across domestic manufacturing facilities.
Growth Catalysts
- Pour painting technique proliferation:Fluid acrylic demand accelerates as resin art communities expand technique tutorials through social platforms, pulling hobbyists toward low-viscosity formulations.
- California SCAQMD Rule 1113:Stricter architectural coating VOC limits in the South Coast Air Quality Management District create compliant-product premiums for manufacturers achieving sub-50 g/L formulations.
- Adult hobby painting normalization:Post-pandemic leisure pattern shifts sustain elevated canvas purchasing among 35-55 year-old consumers without formal art training.
Market Restraints
- Titanium dioxide import concentration:Pigment supply vulnerability persists as domestic manufacturers rely on Chinese and Ukrainian ore processing for 60% of white pigment feedstock.
- Propylene derivative volatility:Acrylic acid and ester monomer costs fluctuate with Gulf Coast petrochemical capacity utilization, squeezing formulation margin predictability.
- OSHA respirable crystalline silica limits:Pigment milling operations face capital-intensive ventilation upgrades to meet 50 microgram per cubic meter workplace exposure ceilings.
Strategic Opportunities
- Texas and Florida urban creative clusters:Underpenetrated Sun Belt metro areas outside California and the Northeast corridor offer whitespace for specialty retailer expansion and local artist co-op partnerships.
- Bio-based polymer feedstocks:USDA BioPreferred program certification pathways open federal procurement channels and consumer premium positioning for plant-derived acrylic alternatives.
- Direct-to-creator subscription models:Monthly pigment kit deliveries bypass traditional art supply store intermediaries, capturing recurring revenue from committed hobbyists in rural ZIP codes.
Industry Challenges
- Color chemist talent scarcity:Formulation expertise in naphthol and quinacridone pigment dispersion is concentrating among retiring baby-boomer technicians without adequate pipeline replacement.
- ASTM D4236 chronic hazard labeling compliance:Prop 65 warning requirements for titanium dioxide and cadmium pigments create packaging complexity and retailer liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Non-Commercial Acrylic Paints Market |
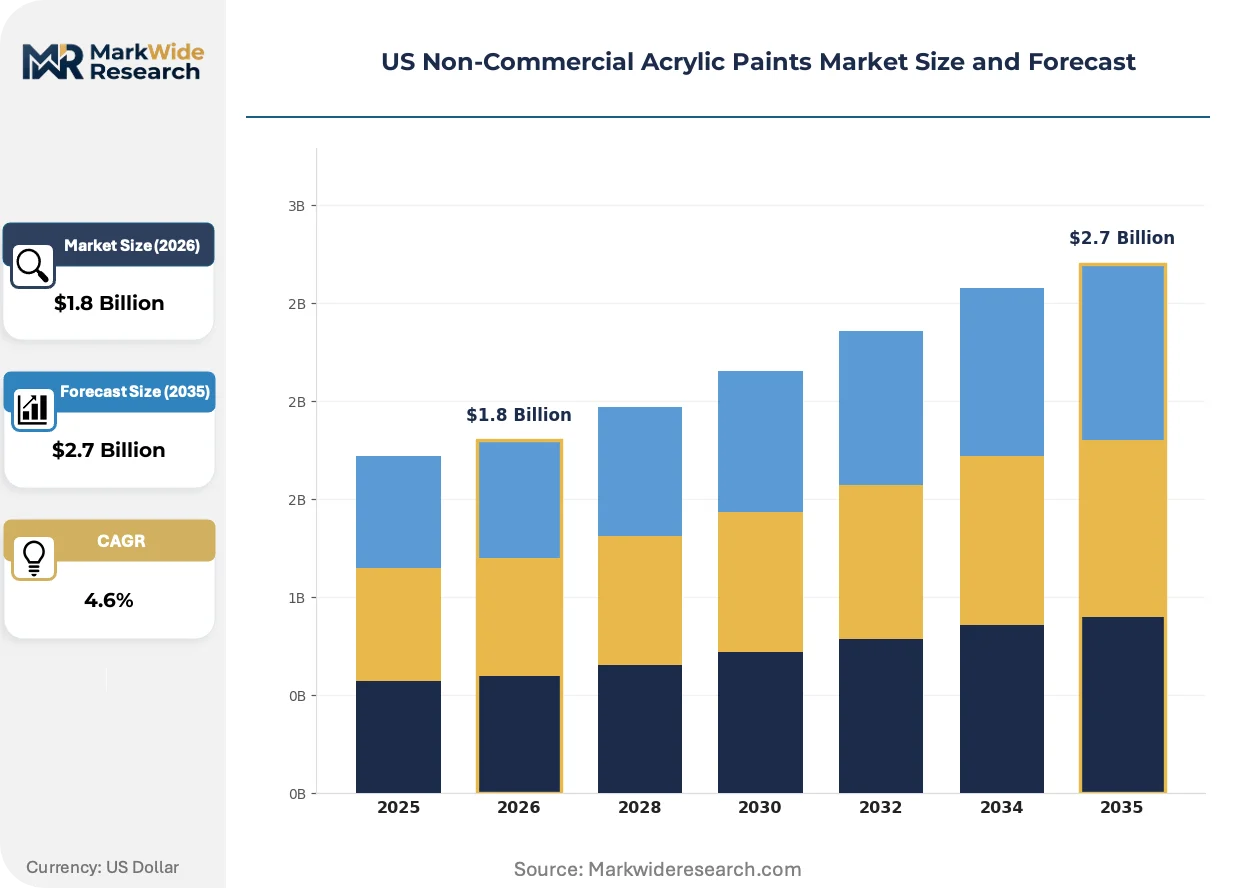
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluid Acrylics, Heavy Body Acrylics, Soft Body Acrylics, Acrylic Gouache Application: Art Education, Hobby Painting, Craft Projects, Professional Artwork Packaging Type: Tubes, Jars, Bottles, Pouches Distribution Channel: Online Retail, Art Supply Stores, Supermarkets, Specialty Stores |
| Companies Covered | Golden Artist Colors, Liquitex Artist Materials, Winsor & Newton, Da Vinci Paint Co., Daler-Rowney, DecoArt, M. Graham & Co., Chroma Atelier, Faber-Castell, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Non-Commercial Acrylic Paints Market Evolving Landscape
Formulation chemistry is pivoting toward water-borne systems as regulatory pressure compounds, while application techniques and procurement channels undergo simultaneous fragmentation.
Interchangeable pigment cartridge systems are modularizing studio inventory management. Professional artists and art educators adopt standardized color pods that snap into reusable bases, reducing single-use tube waste. This architecture is compressing brand loyalty by enabling cross-manufacturer color matching without full product line commitment.
EPA architectural coatings NESHAP revisions are tightening methanol and glycol ether limits in manufacturing facilities. Compliance investments favor larger producers with captive wastewater treatment, pushing mid-scale manufacturers toward toll manufacturing arrangements. California manufacturers face additional SCAQMD Rule 1136 record-keeping burdens that smaller competitors struggle to absorb.
Social commerce discovery is displacing catalog-based purchasing for emerging artists. TikTok and Instagram algorithmic feeds now drive 40% of first-time fluid acrylic purchases among 18-34 year-olds, shifting marketing spend toward creator partnerships and away from print advertising. This pattern concentrates in suburban and exurban communities where physical art supply store access is limited.
US Non-Commercial Acrylic Paints Market Segmentation
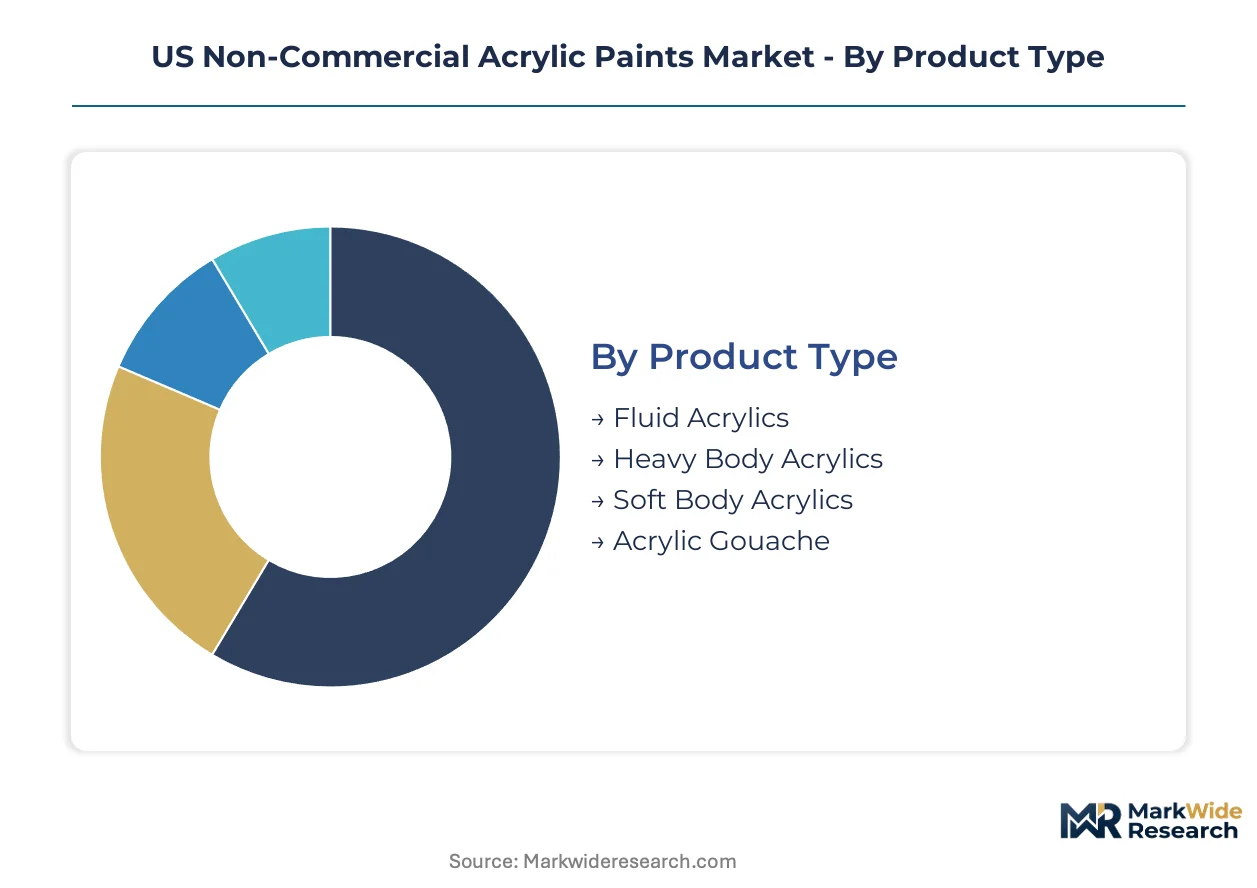
Segmentation in the US non-commercial acrylic paints market reveals distinct performance characteristics across formulation chemistry, end-use intensity, and procurement patterns. Each dimension carries implications for margin structure, regulatory exposure, and channel investment priorities.
Product Type:
Integration depth varies sharply: heavy body formulations function as standalone artistic media requiring minimal substrate preparation, while fluid acrylics embed into multi-layer resin systems and mixed-media workflows.
- Heavy Body Acrylics:High-viscosity formulations carry 40-60% pigment load by weight, enabling impasto retention and palette knife work. Demand clusters in California's urban creative clusters and the Northeast corridor where professional artists and atelier programs concentrate; EPA VOC thresholds under architectural coatings rules elevate water-borne R&D investment for compliant heavy body production.
- Fluid Acrylics:Low-viscosity formulations with 10-20% solids content facilitate pour painting, resin art, and airbrush application. Demand accelerates among 35-55 year-old hobbyists in suburban and exurban communities; social commerce discovery on TikTok and Instagram drives 40% of first-time purchases in this segment among 18-34 year-olds.
- Soft Body Acrylics:Medium-viscosity bridge formulations suit illustration and detail work on paper substrates.
- Acrylic Gouache:Matte-finish opaque variants serve designers and illustrators requiring flat color fields.
Heavy body acrylics lead volumes today; fluid acrylics are gaining share fastest.
Application:
Cost tier stratification separates institutional procurement with volume discounts from individual creator purchasing at shelf price.
- Hobby Painting:Post-pandemic leisure pattern shifts sustain elevated canvas purchasing among adult consumers without formal art training. Demand concentrates in Sun Belt metro areas outside California and the Northeast corridor where specialty retailer penetration remains underdeveloped; direct-to-creator subscription models capture recurring revenue from committed hobbyists in rural ZIP codes.
- Professional Artwork:Gallery-exhibiting creators demand ASTM International pigment permanence certification and lightfastness ratings. Demand anchors in established coastal creative economies; California's South Coast Air Quality Management District Rule 1113 imposes sub-50 g/L VOC limits that filter available product lines for professional studios.
- Art Education:K-12 and university programs prioritize washability and bulk pricing over pigment concentration.
- Craft Projects:Mixed-media and home décor applications favor economy-tier fluid formulations.
Hobby painting leads volumes today; professional artwork commands the steepest expansion trajectory in value terms.
Packaging Type:
Volume economics and waste reduction pressures are reshaping format preferences across customer types.
- Tubes:Collapsible aluminum and plastic extrusion formats dominate professional artist preference for color preservation and precise dispensing. Demand persists in art supply stores with knowledgeable staff; ASTM D4236 chronic hazard labeling compliance for titanium dioxide and cadmium pigments creates packaging complexity and retailer liability exposure.
- Bottles:Flip-top and nozzle designs serve fluid acrylic users requiring controlled flow rates for pour techniques. Demand climbs fastest among resin art communities; interchangeable pigment cartridge systems modularize studio inventory management and compress brand loyalty.
- Jars:Wide-mouth containers accommodate heavy body extraction with palette knives.
- Pouches:Flexible packaging reduces shipping cube and appeals to environmentally conscious purchasers.
Tubes lead volumes today; bottles are expanding most quickly.
Distribution Channel:
Geography determines channel viability: urban density sustains specialty retail while rural access gaps accelerate online displacement.
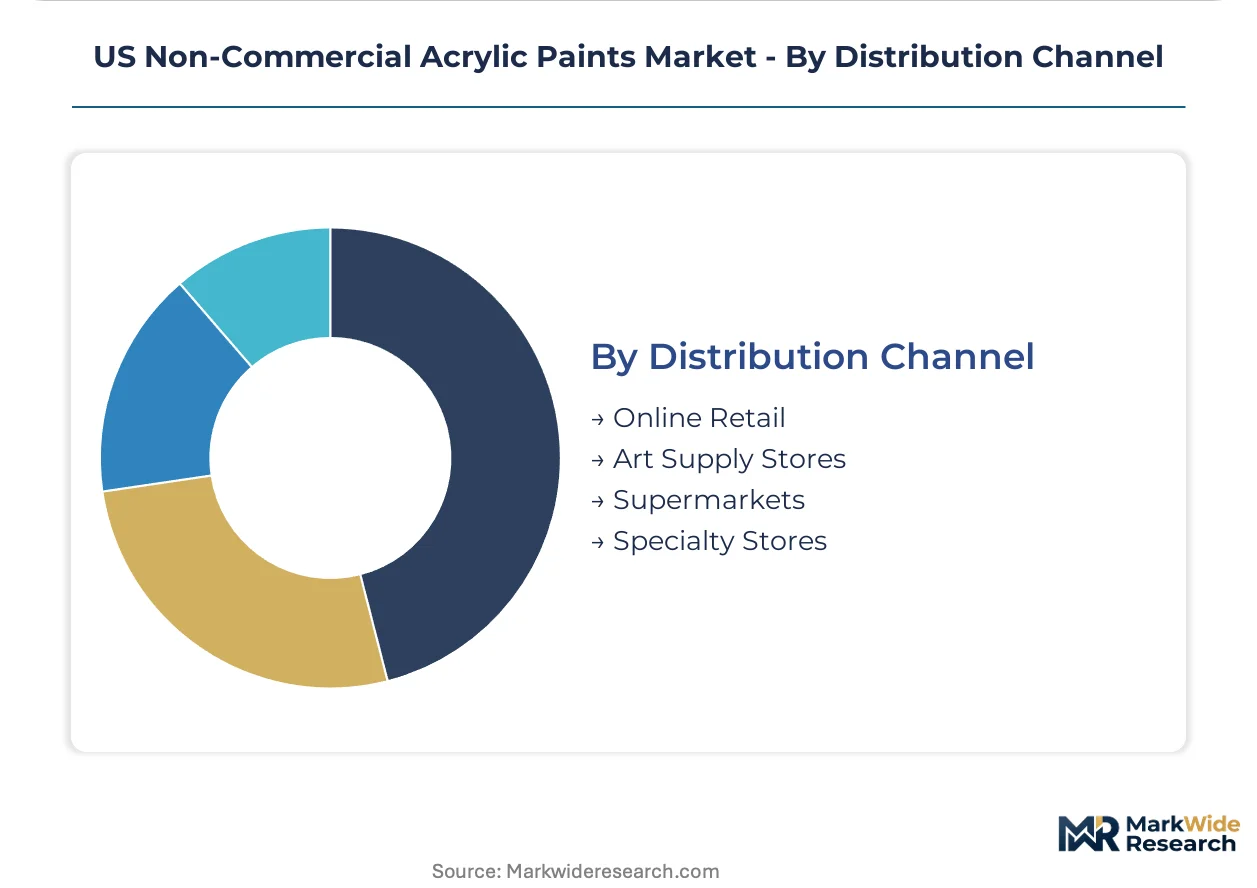
- Art Supply Stores:Brick-and-mortar specialists retain margin concentration through knowledgeable staff and brand exclusivity arrangements. Demand concentrates in California's urban creative clusters and the Northeast corridor; SCAQMD Rule 1136 record-keeping burdens strain smaller competitors in the South Coast Air Quality Management District.
- Online Retail:Algorithmic feeds and creator partnerships displace catalog-based purchasing. Demand accelerates in suburban and exurban communities where physical art supply store access is limited; social commerce discovery now drives 40% of first-time fluid acrylic purchases among 18-34 year-olds.
- Supermarkets:Mass-market placement captures impulse craft project purchases.
- Specialty Stores:Hobby chains and museum gift shops serve tourist-adjacent demand.
Art supply stores lead volumes today; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's urban creative clusters anchor US non-commercial acrylic paint demand through concentration of professional artists, atelier programs, and gallery infrastructure that sustains premium heavy body formulation consumption.
California
Los Angeles and San Francisco Bay Area studios drive professional-grade pigment consumption through established gallery economies and art school enrollment. The South Coast Air Quality Management District enforces Rule 1113 sub-50 g/L VOC limits that filter compliant product lines for coastal manufacturers. Golden Artist Colors operates manufacturing in upstate New York but maintains distribution saturation across California's coastal metros.
Northeast Corridor
New York City and Boston metro areas concentrate art supply retail with knowledgeable staff and brand exclusivity arrangements supporting premium pricing. OSHA respirable crystalline silica exposure limits at 50 micrograms per cubic meter govern pigment milling operations throughout the region. Brooklyn and Providence studio clusters sustain demand for ASTM-certified lightfast formulations among gallery-exhibiting creators.
Texas
Houston and Dallas-Fort Worth creative communities represent underpenetrated whitespace for specialty retailer expansion beyond coastal dominance. The Texas Commission on Environmental Quality administers delegated Clean Air Act programs with VOC thresholds less stringent than California benchmarks. Austin's artist co-op networks and emerging gallery districts pull fluid acrylic demand from social commerce channels.
Florida
Miami and Tampa Bay hobby painting communities expand as post-pandemic leisure patterns normalize among 35-55 year-old consumers without formal training. The Florida Department of Environmental Protection implements federal architectural coatings standards without additional state-level formulation constraints. Orlando's craft tourism infrastructure and retirement-adjacent creative communities support economy-tier fluid formulation volume.
Pacific Northwest
Seattle and Portland studio economies favor environmentally conscious purchasing patterns that pull pouch packaging and bio-based polymer interest. The Washington State Department of Ecology maintains VOC limits aligned with federal EPA architectural coatings rules. Portland's maker culture and small-batch manufacturing ethos sustain demand for artisan-positioned colorant lines.
US Non-Commercial Acrylic Paints Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and distribution channel access, producing a tiered structure where scale-driven volume players, premium-positioned specialists, and craft-oriented mass marketers occupy distinct competitive spaces. The vendor base separates into three strategic archetypes: domestic mineral-sourcing premium producers, in-house resin polymerization specialists, and high-volume fluid acrylic commoditizers. Dominant competitive moves include direct-to-creator subscription model deployment and water-borne formulation R&D investment ahead of tightening coastal emission benchmarks.
Within the premium specialist tier, Golden Artist Colors exemplifies domestic mineral sourcing strategies, while Liquitex Artist Materials anchors in-house resin polymerization capabilities. DecoArt occupies the scale-driven craft market position. These three companies represent the competitive spectrum from professional artist-grade positioning through hobbyist volume capture.
| Leading Market Players |
|---|
| Golden Artist Colors |
| Liquitex Artist Materials |
| Winsor & Newton |
| Da Vinci Paint Co. |
| Daler-Rowney |
| DecoArt |
| M. Graham & Co. |
| Chroma Atelier |
| Faber-Castell |
| Others |
Value Network & Pricing Analysis
Captive mineral sourcing for titanium dioxide anchors both supply security and pricing power for domestic heavy body acrylic producers, insulating premium tiers from import volatility while compressing margins for manufacturers dependent on Chinese and Ukrainian ore processing feedstock.
Pricing Analysis
Input-cost pass-through from propylene derivative volatility compresses formulation margin predictability, particularly for fluid acrylic lines tethered to Gulf Coast petrochemical capacity swings. Three-tier pricing structure across professional artist, serious hobbyist, and economy craft levels separates ASTM-certified lightfast formulations from wash-grade educational products. Pricing pressure stems from social commerce discovery channels that commoditize brand differentiation among 18-34 year-old first-time purchasers. Hobby painting segments in Sun Belt metros exhibit highest price sensitivity; professional atelier programs in California and the Northeast corridor demonstrate lowest.
Supply Chain Analysis
Reverse-logistics flows for interchangeable pigment cartridge systems are modularizing studio inventory management, reducing single-use tube waste while compressing brand loyalty through cross-manufacturer color matching compatibility. Raw material concentration draws from China and Ukraine for titanium dioxide ore processing, alongside domestic acrylic acid and ester monomer production at Gulf Coast petrochemical facilities. Single-source vulnerability persists for white pigment feedstock where 60% reliance on overseas processing creates tariff and logistics chokepoint exposure. Distribution runs through art supply store intermediaries in urban creative clusters, with online retail accelerating displacement in rural ZIP codes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities concentrate in Texas and Florida urban creative clusters, where less stringent TCEQ and FDEP VOC thresholds reduce compliance costs versus California's SCAQMD Rule 1113 sub-50 g/L mandates.
For Market Incumbents: Anchor coastal market position through in-house water-borne polymer R&D investment ahead of tightening EPA architectural coatings NESHAP revisions, while defending against direct-to-creator subscription models by locking brand exclusivity arrangements with art supply store intermediaries in knowledge-intensive retail formats. For New Entrants and Emerging Players: Bio-based polymer feedstock certification pathways offer a technology-first wedge for USDA BioPreferred program positioning, opening federal procurement channels and consumer premium positioning. Target underpenetrated Sun Belt metro creative clusters outside California and the Northeast corridor through local artist co-op partnerships and social commerce creator collaborations. For Investors and Strategic Acquirers: Consolidation pressure builds where color chemist expertise in naphthol and quinacridone pigment dispersion concentrates among retiring baby-boomer technicians without adequate pipeline replacement. Acquisition target archetypes include mid-scale manufacturers with captive mineral sourcing capabilities or toll manufacturing arrangements with compliant wastewater treatment infrastructure. The signal to watch is state-level chemical restriction trajectories accelerating beyond federal EPA benchmarks.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Borne Formulation R&D Investment | EPA NESHAP compliance ahead of methanol and glycol ether limit tightening favors larger producers with captive treatment. |
| Direct-to-Creator Subscription Launch | Monthly pigment kit deliveries bypass art supply intermediaries to capture recurring rural hobbyist revenue. |
| Domestic Mineral Sourcing Integration | Backward integration into titanium dioxide feedstock reduces exposure to Chinese and Ukrainian ore processing concentration. |
| Bio-Based Polymer Certification | USDA BioPreferred pathways open federal procurement channels and premium consumer positioning for plant-derived alternatives. |
| Interchangeable Cartridge System Development | Modular color pod architectures reduce single-use waste while enabling cross-manufacturer studio inventory flexibility. |
Research Methodology
Bottom-up hobby painting and professional artwork demand modeling reconciled against top-down acrylic polymer emulsion production capacity tracking forms the analytical core of this study. Primary interviews with formulation chemists, art supply store category managers, pigment procurement leads at domestic manufacturers, and professional artist studio operators combined with secondary validation against EPA enforcement and compliance databases, ASTM International pigment permanence certification records, and South Coast Air Quality Management District Rule 1113 filing data. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of heavy body and fluid acrylic consumption patterns across the projection horizon informed CAGR derivation through regression against adult hobby painting participation rates and social commerce channel penetration metrics. Segmentation dimensions modeled include viscosity grade, end-use intensity, packaging format, and distribution channel, with additional industry-specific dimension of state-level regulatory compliance tier. Forecast inputs incorporated petrochemical capacity utilization at Gulf Coast facilities and titanium dioxide import dependency ratios.
The model holds under stable EPA architectural coatings enforcement and continued social commerce growth; deviation in state-level VOC restriction acceleration or pigment supply chain disruption would shift volume trajectories. Forecasts reflect these base assumptions with acknowledged sensitivity to OSHA respirable crystalline silica limit revisions and Prop 65 labeling expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Expandable Microspheres Market
Specialty Compounds
Global Antifreeze Proteins Market
Specialty Compounds
Hydroxypropyl Methylcellulose Market
Specialty Compounds
Opacifiers Market
Specialty Compounds
Collagen Hydrolysates Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
Hypalon Market
Specialty Compounds
Gypsum-Free Plaster Market
Specialty Compounds
Gulf Collagen Market
Specialty Compounds
EPDM Sealing Strip Market
Specialty Compounds
Stannous Chloride Market
Specialty Compounds
Solketal Market
Specialty Compounds
Argan Oil Market
Specialty Compounds
Methane Sulfonyl Chloride Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Global Specialty Amines Market