
 Paint Rollers Market | 2026-2036
Paint Rollers Market Size, Share, and Industry Trends Forecast 2026-2036
Paint Rollers Market Analysis
Skilled applicator shortages across commercial painting crews is redrawing how manufacturers design tool ergonomics and training support. Wooster Brush Company leverages its Ohio-based production to sustain domestic supply continuity for professional-grade rollers. Purdy anchors premium positioning through consistent filament technology and painter loyalty programs. Hyde Group, Inc. competes across industrial maintenance channels with corrosion-resistant frame designs.
A paint roller is a cylindrical applicator tool comprising a rotating core, absorbent cover material, and handle assembly, engineered to transfer coatings across flat or textured surfaces with controlled film thickness. The device serves architectural finishing, protective coating, and decorative treatment applications across construction and maintenance sectors. Standard Rollers and 9 Inch formats dominate volume due to universal compatibility with residential walls and ceilings, while Specialty Rollers command margin pools in faux finishing and textured coating segments. Foam and Polyester materials lead material demand for water-based latex formulations, though Mohair retains niche strength in solvent-borne enamel applications where smooth leveling remains critical.
EPA VOC regulations constrain solvent-based coating formulations in the United States, indirectly shaping roller material compatibility requirements and product development priorities. OSHA workplace safety standards govern ladder and scaffolding protocols that influence Extension Roller design specifications for commercial painters. BIS certification requirements in India and CE marking obligations in Europe further fragment compliance burdens for multinational suppliers. Stakeholders must monitor evolving state-level environmental mandates and building code amendments that could accelerate material substitution timelines or reshape channel inventory requirements.
Market Dynamics
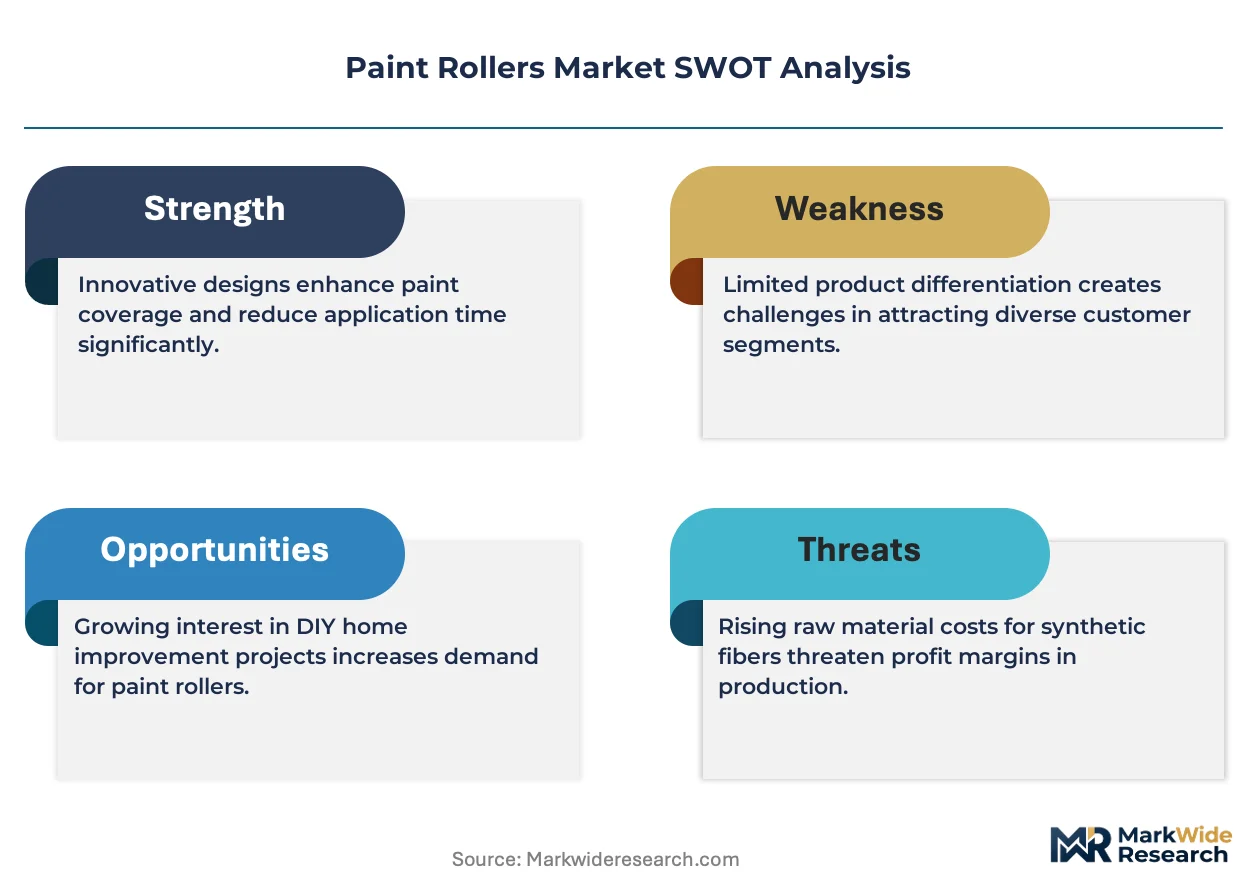
REACH compliance in Europe and evolving VOC standards in North America are tightening material specifications for roller covers and frames, forcing manufacturers to reformulate absorbent materials and accelerate solvent-compatible cover substitutions across production lines.
Growth Catalysts
- Residential renovation surge:Homeowners in the United States prioritize interior upgrades, sustaining volume leadership through DIY retail channels and housing stock turnover.
- EPA VOC regulations:Solvent-based coating constraints indirectly reshape roller material compatibility requirements, pushing development priorities toward water-based formulation compatibility.
- Foam and polyester innovation:Advanced synthetic fibers improve water-based latex application efficiency, expanding addressable use cases in architectural finishing segments.
Market Restraints
- Petrochemical input volatility:Polyester and polyurethane foam raw materials face price instability from crude oil fluctuations, compressing margin predictability for cover manufacturers.
- Skilled applicator shortages:Commercial painting crews lack trained professionals, limiting premium tool adoption velocity despite ergonomic advances.
- CE marking fragmentation:European compliance obligations multiply testing burdens for multinational suppliers seeking unified product platforms.
Strategic Opportunities
- India BIS certification pathway:Formal quality standards create tiered market entry for compliant foreign manufacturers targeting infrastructure and residential construction growth.
- Extension roller specification gaps:OSHA workplace safety standards governing ladder and scaffolding protocols open design innovation space for commercial-grade adjustable handle systems.
- Specialty roller white space:Faux finishing and textured coating segments command margin pools underserved by standard 9-inch format commoditization.
Industry Challenges
- Multi-jurisdiction compliance timelines:Simultaneous BIS, CE, and EPA certification requirements stretch product development calendars and inventory segmentation complexity.
- Mohair supply concentration:Natural fiber sourcing for solvent-borne enamel applications depends on limited geographic suppliers, creating raw material security exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paint Rollers Market |
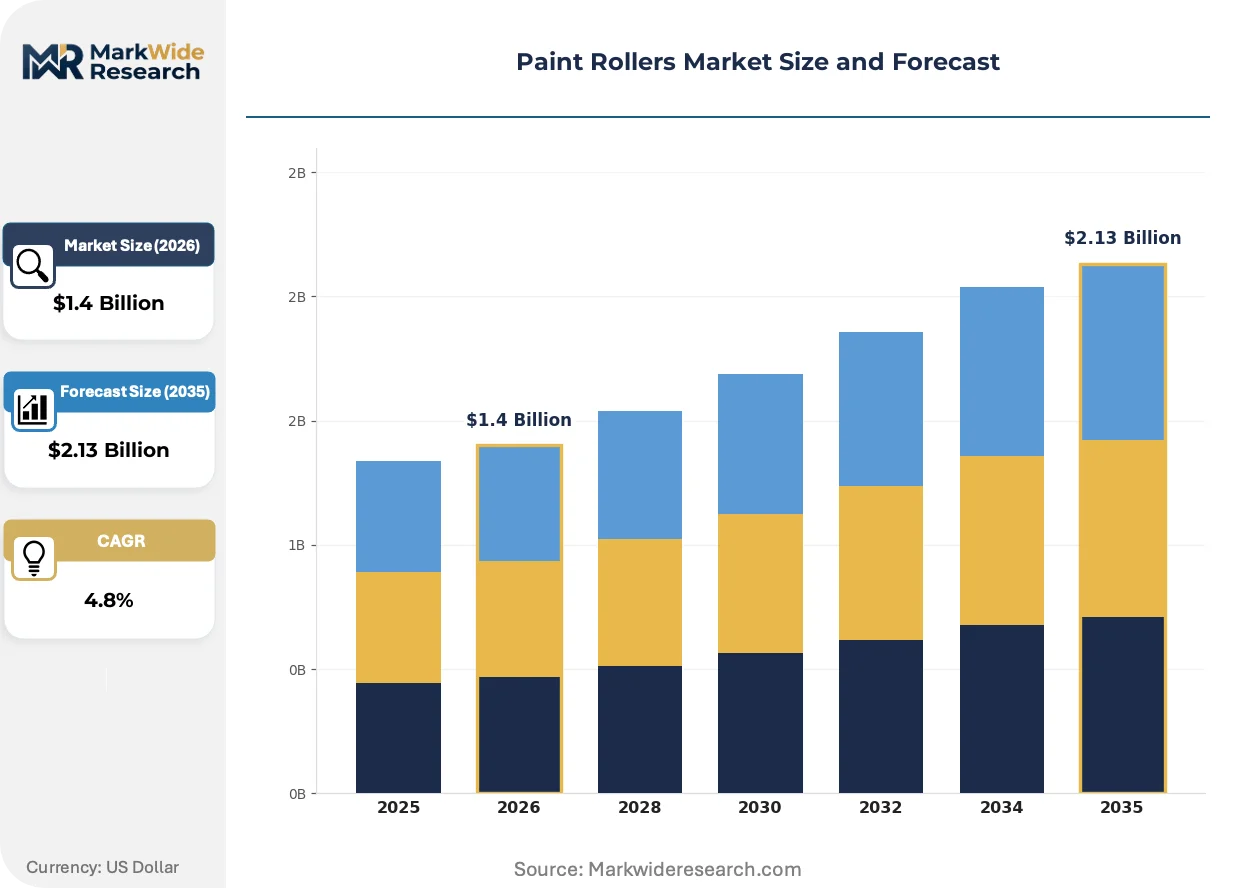
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Rollers, Standard Rollers, Extension Rollers, Specialty Rollers Material: Foam, Nylon, Mohair, Polyester Application: Residential, Commercial, Industrial, Decorative Roller Size: 4 Inch, 9 Inch, 12 Inch, 18 Inch |
| Companies Covered | Premier Paint Roller Co LLC, Hyde Group, Inc., Gordon Brush Mfg. Co., Inc., Anderson Products, Richard Tools, Wooster Brush Company, Mill-Rose Co, Pro Roller Company Inc., Purdy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint Rollers Market Emerging Trajectories
Tool ergonomics and training support architectures are redrawing manufacturer competitive positioning as labor scarcity forces product-service bundling. Material science advances and regulatory chemistry constraints are converging to redefine cover composition roadmaps.
Microfiber filament technology is miniaturizing surface texture control for precision finish applications. High-end residential contractors and automotive refinish specialists are adopting these denser weave structures faster than commercial crews. The technology is miniaturizing the distinction between brush and roller finish quality, compressing specialty brush demand in trim and detail work.
REACH substance restrictions are eliminating certain chemical treatments historically used in synthetic cover manufacturing. ECHA's evolving candidate list forces reformulation of dye carriers and antimicrobial additives. European professional-grade suppliers are responding with bio-based binder systems that maintain solvent resistance without restricted substances.
Painter loyalty programs now bundle digital training content with repeat purchase incentives. Pro-oriented retail channels in the United States are displacing pure product transactions with certification-credit ecosystems. This behavior shift concentrates most visibly among commercial maintenance contractors seeking crew standardization and warranty continuity.
Paint Rollers Market Segmentation
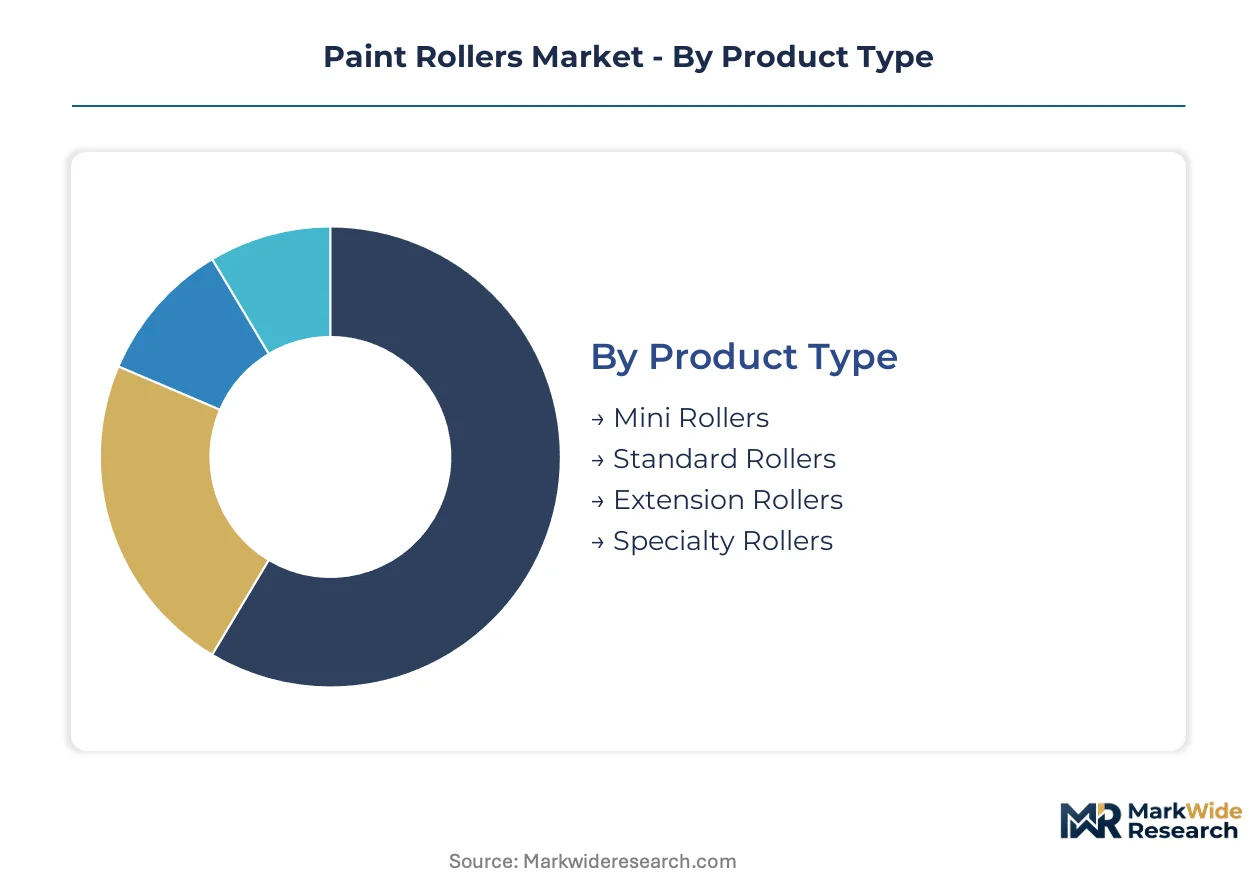
Paint roller segmentation reflects divergent technical requirements across coating chemistries, surface geometries, and applicator skill levels. Regulatory chemistry constraints and labor scarcity are fragmenting product architectures faster than historical commoditization patterns predicted.
Product Type:
EPA VOC restrictions and OSHA scaffolding protocols are bifurcating design specifications between residential DIY and commercial professional channels.
- Standard Rollers:The 9-inch cylindrical format with phenolic resin cores dominates residential wall and ceiling applications. United States housing stock turnover through big-box retail channels sustains volume leadership despite thinner margins.
- Specialty Rollers:Faux finishing and textured coating configurations command premium positioning through proprietary nap geometries and material laminates. Demand concentrates among high-end residential contractors seeking differentiation in decorative treatment segments.
- Mini Rollers:Compact 4-inch formats target trim, cabinetry, and tight-corner applications where brush-roller hybrid performance matters.
- Extension Rollers:Telescoping handle systems address OSHA ladder safety mandates for commercial maintenance crews working at elevation.
Standard Rollers handle the majority of throughput; Specialty Rollers are gaining share fastest on margin expansion.
Material:
Cost tiers separate commodity synthetics from performance-grade natural fibers with solvent compatibility premiums.
- Foam:Open-cell polyurethane structures optimize water-based latex pickup and release for residential repaint cycles. Formulation innovation targets improved tear resistance under high-sheen coating loads.
- Polyester:Thermoplastic filament weaves balance durability and cost for professional crews executing multi-room commercial projects. Petrochemical input volatility compresses margin predictability for cover manufacturers.
- Mohair:Natural goat-hair fibers retain solvent-borne enamel compatibility where smooth leveling remains critical. Limited geographic sourcing creates raw material security exposure.
- Nylon:Polyamide filaments offer abrasion resistance for textured surface applications and aggressive coating formulations.
Polyester covers the broadest application base; Specialty natural fibers climb fastest on solvent-regulation arbitrage.
Application:
Customer type determines specification stringency from warranty-backed commercial contracts to discretionary residential upgrades.
- Residential:Homeowner-driven interior renovation sustains DIY retail channel volume through 9-inch standard formats and foam cover preferences. Housing stock age in the United States supports consistent repaint frequency.
- Commercial:Maintenance contractors and facility managers specify ergonomic frames and extension systems to reduce labor injury exposure. Crew standardization programs favor repeat-purchase loyalty structures.
- Industrial:Protective coating applications in manufacturing facilities demand corrosion-resistant frame materials and solvent-compatible covers.
- Decorative:Faux finishing and artistic treatment segments drive specialty roller innovation with premium pricing tolerance.
Residential commands absolute volume; Commercial shows steepest expansion trajectory on skilled labor scarcity mitigation.
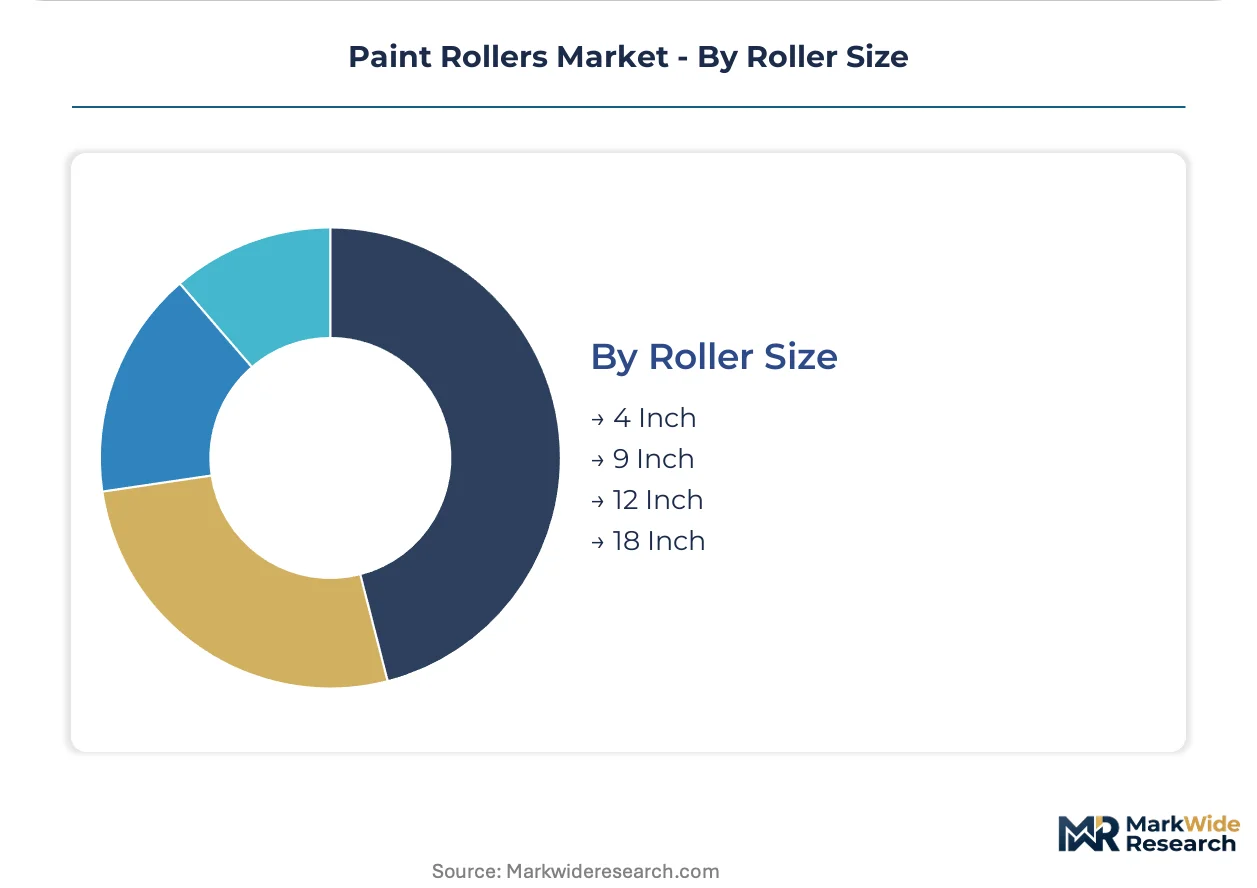
Roller Size:
Surface area economics and maneuverability constraints segment formats across room-scale versus detail-work applications.
- 9 Inch:Universal wall and ceiling compatibility makes this the default specification for residential and light commercial projects. Format standardization enables cover interchangeability across manufacturer frame systems.
- 4 Inch:Trim, door, and cabinetry work requires compact roller formats where brush-roller quality convergence matters most. Microfiber filament advances are compressing traditional brush demand in these applications.
- 12 Inch:Wider formats target open-plan commercial spaces and production painting environments where coverage velocity outweighs edge control precision.
- 18 Inch:Maximum-width configurations serve industrial floor coating and large-surface warehouse applications with mechanized frame support.
9 Inch formats dominate unit economics; 4 Inch configurations expand most quickly on finish-quality convergence trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA regulations in the United States anchor the dominant geography for paint roller demand, with housing stock turnover and DIY retail channels sustaining volume leadership. REACH compliance in Europe and BIS certification pathways in India are fragmenting multinational product platforms across divergent material specifications.
United States
Residential renovation activity concentrates in Sun Belt metros and Midwest manufacturing cities where aging housing stock drives repaint frequency. EPA VOC regulations constrain solvent-based coating formulations, indirectly reshaping roller material compatibility requirements toward water-based latex systems. Wooster Brush Company leverages Ohio-based production to sustain domestic supply continuity for professional-grade rollers serving commercial maintenance contractors.
Germany
Industrial maintenance and automotive refinish segments sustain demand for precision-finish applicators across Bavaria and Baden-Württemberg manufacturing corridors. ECHA's evolving REACH substance restrictions force reformulation of dye carriers and antimicrobial additives in synthetic cover manufacturing. Stuttgart-based coating specialists are piloting bio-based binder systems that maintain solvent resistance without restricted substances.
China
Infrastructure investment and commercial construction expansion concentrate roller demand in Yangtze River Delta and Pearl River Delta manufacturing clusters. GB standards and MIIT industrial policy guidelines shape domestic product quality tiers for architectural finishing applications. Zhejiang and Jiangsu provinces host fabricators supplying both domestic construction markets and export-oriented private-label programs.
India
Residential construction growth and infrastructure development drive roller consumption across Maharashtra, Gujarat, and Karnataka urban corridors. BIS certification requirements create tiered market entry for compliant foreign manufacturers targeting professional painting contractors. Mumbai and Bangalore metropolitan areas concentrate distribution networks serving both organized retail and informal construction labor channels.
United Kingdom
Home improvement retail and commercial maintenance sectors sustain roller demand across London-Southeast and Midlands construction markets. CE marking obligations and evolving UKCA transition requirements multiply testing burdens for suppliers seeking unified European product platforms. Manchester and Birmingham industrial zones host regional distribution hubs serving northern England renovation contractors.
Paint Rollers Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with domestic production assets and filament technology capabilities determining competitive position. The market structure stratifies between premium-grade specialists commanding painter loyalty and volume-oriented fabricators serving private-label retail programs. Three archetypes dominate: integrated manufacturers with captive cover production, specialist brands built on applicator training ecosystems, and regional fabricators competing on cost-positioned standard formats. Capacity expansion in synthetic fiber cover production and strategic partnerships with pro-oriented retail channels represent the dominant competitive moves reshaping market access.
Among Ohio-based manufacturers, Wooster Brush Company exemplifies the integrated production archetype, while Purdy occupies a premium positioning tier built on consistent filament technology and painter loyalty programs. Hyde Group, Inc. represents the industrial maintenance specialist segment with corrosion-resistant frame design capabilities. These three companies anchor distinct competitive vectors without overlapping strategic territory.
| Leading Market Players |
|---|
| Premier Paint Roller Co LLC |
| Hyde Group, Inc. |
| Gordon Brush Mfg. Co., Inc. |
| Anderson Products |
| Richard Tools |
| Wooster Brush Company |
| Mill-Rose Co |
| Pro Roller Company Inc. |
| Purdy |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between polyester filament suppliers and cover manufacturers lock in raw material access and price visibility for 18-24 month windows, insulating mid-tier producers from petrochemical volatility while constraining agility to reformulate for REACH-compliant dye systems.
Pricing Analysis
United States list prices for professional-grade 9-inch rollers command 40-60% premiums over comparable private-label formats in India, reflecting brand loyalty investments and domestic manufacturing overhead. Three-tier pricing structure across premium, standard, and economy levels separates Purdy's filament-technology positioning from Wooster's professional-grade bundles and mass-market imports. Cost compression in economy-tier foam covers is intensifying because Chinese fabricators are absorbing tariff exposure to maintain volume share. DIY retail channels exhibit highest price sensitivity, while commercial maintenance contractors prioritize warranty continuity and crew-standardization programs over unit cost.
Supply Chain Analysis
Inventory buffers for phenolic resin cores and chrome-plated frames stretch 8-12 weeks for United States distributors, compressing to 4-6 weeks for Zhejiang-based export fabricators serving European private-label programs. Manufacturing concentrates in China, the United States, and Germany, with Zhejiang province hosting captive cover-weaving operations and Ohio maintaining integrated frame-and-cover production for domestic professional markets. Raw material dependencies rest on Saudi Arabian petrochemical feedstocks for polyester filament, Belgian phenolic resin for high-temperature cores, and Turkish mohair for solvent-compatible specialty covers. Single-source vulnerability concentrates in natural fiber supply chains where limited goat-hair regions create sourcing concentration. Distribution runs through big-box retail for residential DIY, pro-oriented specialty distributors for commercial contractors, and direct OEM supply for industrial coating applicators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in specialty roller segments where regulatory chemistry constraints and finish-quality convergence create niches underserved by standard-format commoditization.
For Market Incumbents: Fortify filament-technology differentiation through microfiber weave patents that compress brush demand in trim applications, while anchoring supply continuity via backward integration into phenolic resin core production in Ohio or Zhejiang. CE marking and BIS certification investments create switching costs against emerging Asian competitors. Channel control through painter loyalty programs with embedded training content reinforces repeat-purchase velocity against private-label encroachment. For New Entrants and Emerging Players: Lead with faux-finishing and textured-coating specialty configurations where proprietary nap geometries command 2-3x standard roller margins and incumbent R&D investment lags. India's BIS certification pathway offers the most penetrable regulatory entry point among large construction markets, with Mumbai and Bangalore distribution networks still consolidating. A go-to-market angle bundling digital application technique certification with repeat-purchase incentives displaces pure product transactions in pro-oriented retail channels. For Investors and Strategic Acquirers: Capital is best deployed toward integrated manufacturers with captive cover-weaving capabilities and established pro-channel relationships, as labor scarcity accelerates product-service bundling requirements. Long-term viability over the next decade hinges on solvent-regulation arbitrage capabilities and bio-based binder development pipelines. The signal to watch is EPA state-level adoption of stricter VOC limits beyond federal baselines, which would accelerate material substitution timelines and reshape inventory segmentation for compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenolic Resin Production | Secures core supply continuity against Belgian import lead times and REACH reformulation costs. |
| Bio-Based Binder System Development | Positions European suppliers ahead of ECHA substance restrictions on synthetic cover treatments. |
| Microfiber Filament Patent Portfolio | Captures finish-quality convergence trend compressing brush demand in residential trim segments. |
| BIS Certification Pathway Investment | Unlocks tiered market entry in Maharashtra and Karnataka infrastructure growth corridors. |
| Painter Loyalty Program with Digital Training | Displaces pure product transactions in United States pro-oriented retail channels seeking crew standardization. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade databases, SEC manufacturing filings, and ECHA regulatory substance lists, cross-checking input from plant managers at cover-weaving facilities, procurement leads at commercial painting contractors, distribution channel partners in DIY retail, and technical R&D directors at frame manufacturers. Bottom-up unit economics from 9-inch standard roller production costs triangulate against top-down market sizing from housing stock turnover and repaint frequency models.
Segmentation dimensions modeled include product type, material chemistry, application end-use, roller size format, and regional regulatory cluster across the analysis window. CAGRs derive from elasticity-adjusted demand curves incorporating housing renovation cycles, commercial construction spend, and solvent-regulation phase-in schedules. Industry-specific forecast inputs capture EPA state-level VOC adoption trajectories and BIS certification penetration rates in Indian metropolitan distribution networks.
Forecasts assume regulatory continuity in EPA federal VOC frameworks, ECHA REACH substance restrictions, and India BIS quality standards; material policy shifts would require re-modeling of material substitution timelines and compliance cost burdens. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
Radar Absorbing Paint Market
Paints & Coatings
Nano Paints and Coatings Market
Paints & Coatings
Automotive Coatings Market
Paints & Coatings
Asia-Pacific Paints and Coatings Additives Market
Paints & Coatings
Faux Paints and Coatings Market
Paints & Coatings
Alkyd Coatings Market
Paints & Coatings
Furniture Wood Coatings Market
Paints & Coatings
India Architectural Coatings Market
Paints & Coatings
Iran Paints and Coatings Market
Paints & Coatings
Architectural Coatings Market
Paints & Coatings
Asia-Pacific Paint Thinner Market
Paints & Coatings
Nordic Countries Architectural Coatings Market
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
Small Paint Pail Market
Paints & Coatings
Global Texture Paint Market
Paints & Coatings
Global Paints and Coatings Fillers Market