
 Potassium Gluconate Market | 2026-2036
Potassium Gluconate Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Gluconate Market Analysis
Continuous manufacturing is narrowing the gap between pharmaceutical-grade and nutraceutical-grade potassium gluconate production, compressing batch-to-batch variability that once separated these supply tiers. GlaxoSmithKline plc leverages its respiratory and metabolic franchise infrastructure to anchor high-purity mineral salt sourcing for combination therapies. Novartis AG competes through integrated active pharmaceutical ingredient networks that sustain vertical control over excipient quality. Bayer AG specializes in consumer health applications, positioning its mineral supplement portfolio through pharmacy-centric distribution channels.
Potassium gluconate is the potassium salt of gluconic acid, typically supplied as a white crystalline powder with approximately 16.7% elemental potassium content by mass, manufactured through neutralization of gluconic acid with potassium carbonate or hydroxide for use as an electrolyte replenisher and mineral fortificant. Tablet formulations dominate pharmaceutical procurement due to dose precision and stability profiles, while powder grades capture nutraceutical blending operations where bulk handling efficiency determines contract economics. Liquid potassium gluconate occupies a narrower but defended position in pediatric and geriatric compliance segments where swallowing difficulties restrict solid dosage adoption.
FDA Current Good Manufacturing Practice regulations and USP monograph standards govern identity, strength, and purity specifications for clinical-grade potassium gluconate, while FAO-WHO Codex Alimentarius frameworks shape food additive specifications in international trade. The European Pharmacopoeia and ICH Q3D elemental impurity guidelines further constrain supplier qualification, elevating testing costs for market entrants. Stakeholders must monitor evolving EMA and FDA positions on mineral bioavailability substantiation claims, as these determinations will reshape permissible marketing language and reformulation requirements without warning.
Market Dynamics
FDA and EMA bioavailability guideline tightening is compressing supplier qualification timelines for clinical-grade potassium gluconate, forcing formulators to consolidate procurement around certified manufacturers with validated continuous processing lines.
Growth Catalysts
- Oral Electrolyte Therapy Expansion:Chronic disease management protocols in the United States elevate clinical-grade mineral salt consumption for hypertension and diuretic-induced hypokalemia treatment.
- REACH Compliance Convergence:European Pharmacopoeia standards for elemental impurities are accelerating supplier consolidation as sub-scale manufacturers exit the qualified vendor pool.
- Geriatric Compliance Formats:Liquid potassium gluconate demand is accelerating in pediatric and geriatric segments where swallowing difficulties restrict solid dosage adoption.
Market Restraints
- Potassium Carbonate Input Volatility:Feedstock price swings for the neutralization reagent compress margin predictability for batch manufacturers without long-term supply contracts.
- USP Monograph Testing Burden:Identity, strength, and purity verification requirements under FDA Current Good Manufacturing Practice regulations elevate fixed costs for market entrants.
- Magnesium Gluconate Substitution:Alternative mineral salts with overlapping electrolyte replenishment claims capture formulation share in nutraceutical applications where potassium specificity is not clinically mandated.
Strategic Opportunities
- Underpenetrated Indian Clinical Segment:CDSCO regulatory harmonization with ICH Q3D guidelines creates first-mover advantage for USP-certified suppliers establishing local technical partnerships.
- Continuous Manufacturing Technology:Integration of process analytical technology with real-time release testing is compressing batch-to-batch variability gaps between pharmaceutical and nutraceutical grades.
- Pharmacy-Centric Distribution Channels:Direct-to-pharmacist models in Germany and France bypass traditional wholesale markups for mineral supplement portfolios.
Industry Challenges
- Analytical Chemistry Talent Scarcity:ICP-MS and ion chromatography expertise for elemental impurity testing commands premium compensation, constraining in-house quality control scaling.
- Legacy Batch System Integration:Retrofitting continuous processing lines into existing FDA-validated facilities requires capital allocation for isolator technology and containment infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Gluconate Market |
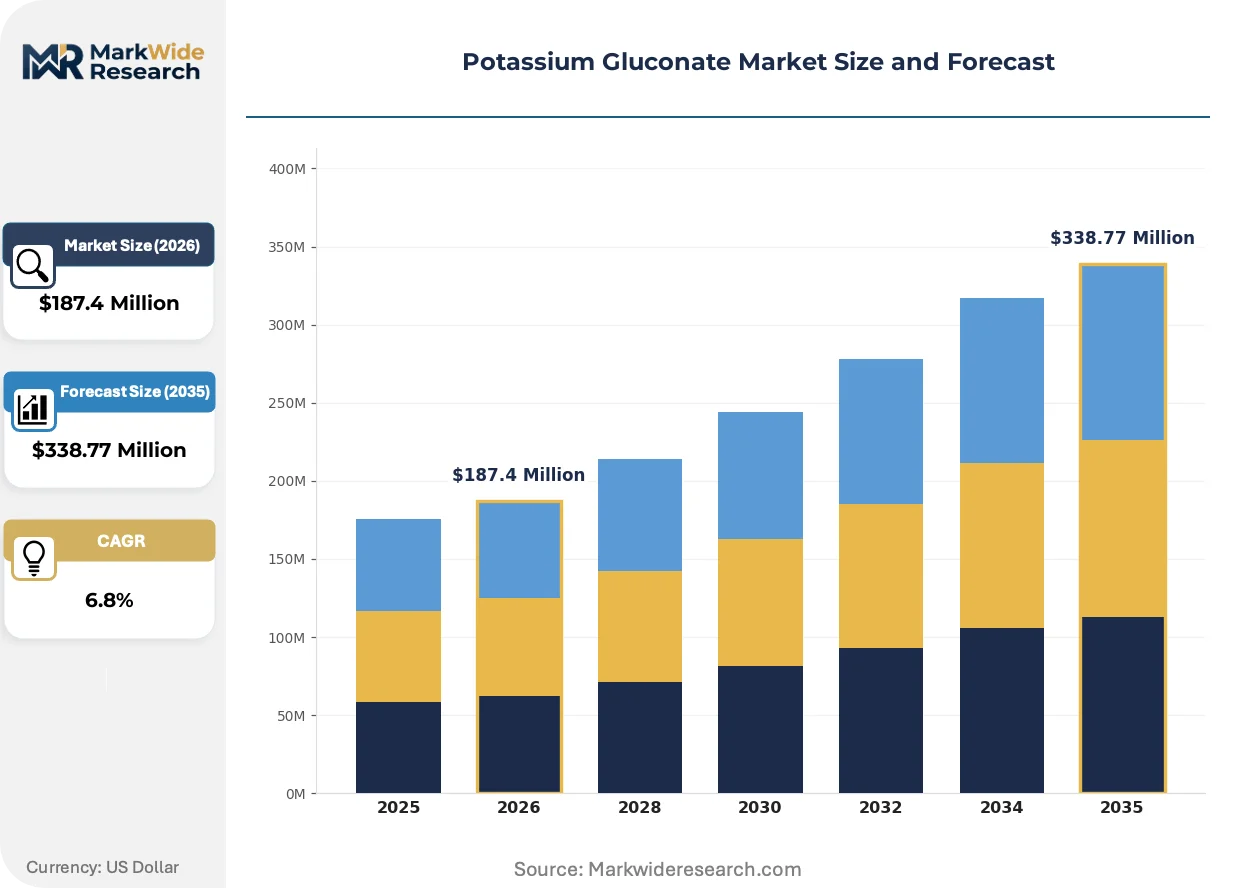
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Tablet, Granules End User: Pharmaceuticals, Food & Beverage, Nutraceuticals, Agriculture Application: Dietary Supplements, Electrolyte Replenishment, Fertilizers, Food Additives Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | GlaxoSmithKline plc, Novartis AG, Bayer AG, Merck & Co., Inc., Abbott Laboratories, Pfizer Inc., Sun Pharmaceutical Industries Ltd., Teva Pharmaceutical Industries Ltd., Dr. Reddy's Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Gluconate Market Emerging Trajectories
Process analytical technology deployment is compressing release timelines for potassium gluconate batches while regulatory bioavailability substantiation requirements reshape permissible marketing claims across oral electrolyte categories.
Continuous direct compression platforms are hybridizing pharmaceutical and nutraceutical production workflows. Contract manufacturers serving both segments adopt PAT-enabled lines that switch between tablet press configurations without full cleaning validation cycles. This equipment flexibility is collapsing the historical six-month supplier qualification gap between clinical-grade and food-grade mineral salt procurement.
EMA's evolving position on mineral bioavailability substantiation is forcing reformulation documentation updates across combination therapies. GlaxoSmithKline and Novartis filing strategies now preemptively include dissolution profile data packages that exceed current monograph requirements. The European over-the-counter mineral supplement segment bears the highest compliance burden as national competent authorities interpret guidance unevenly.
Hospital procurement consortia in the United States are consolidating electrolyte replenisher contracts around single-source agreements with penalty clauses for supply interruption. This buyer concentration is displacing fragmented distributor relationships that previously sustained mid-tier potassium gluconate suppliers. The Veterans Health Administration and regional GPOs like Vizient and Premier anchor this consolidation pattern.
Potassium Gluconate Market Segmentation
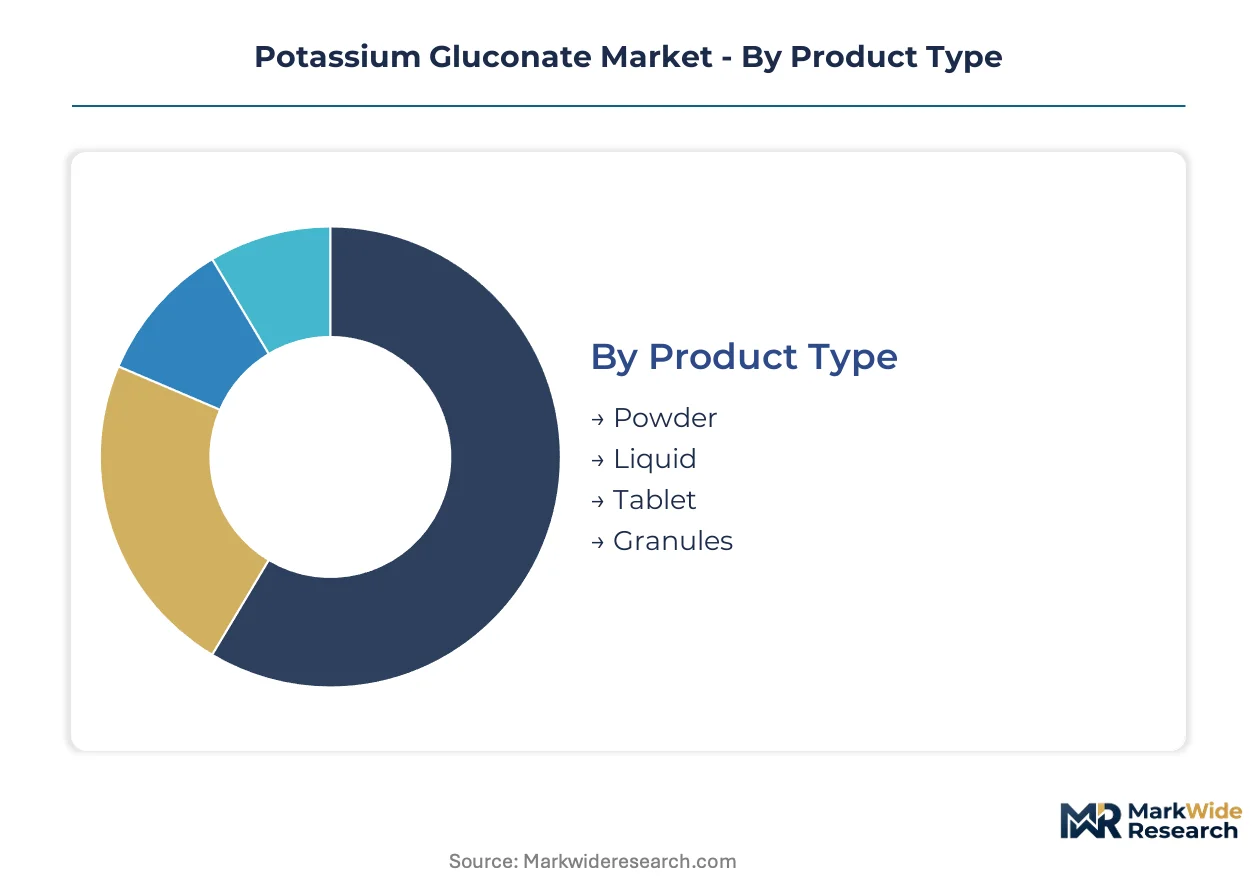
Potassium gluconate procurement patterns diverge sharply across formulation formats and end-use specifications. FDA bioavailability tightening and EMA elemental impurity rules are forcing buyers to segment suppliers by validated quality tiers rather than price alone.
Product Type:
Powder grades dominate bulk pharmaceutical procurement while liquid formats capture compliance-driven pediatric and geriatric prescribing.
- Tablet:Compressed dosage forms with precise 595mg potassium gluconate equivalence enable hypertension protocol adherence in United States Veterans Health Administration contracts. Hospital procurement consortia consolidate tablet sourcing around USP-certified continuous manufacturing lines to satisfy FDA Current Good Manufacturing Practice identity verification.
- Powder:Crystalline material with 16.7% elemental potassium content serves nutraceutical blending operations where bulk handling efficiency determines contract economics. Food additive specifications under FAO-WHO Codex Alimentarius frameworks govern international trade volumes for this grade.
- Liquid:Aqueous solutions occupy narrow but defended positions where swallowing difficulties restrict solid dosage adoption in pediatric and geriatric segments.
- Granules:Intermediate particle size distributions facilitate rapid dissolution in effervescent formulations and sachet-based electrolyte therapies.
The dominant share belongs to Tablet, while Liquid is closing the gap fastest through geriatric compliance demand.
End User:
Customer type determines specification stringency from pharmaceutical-grade USP monograph compliance to food-grade additive tolerances.
- Pharmaceuticals:Oral electrolyte therapy formulators procure clinical-grade material under ICH Q3D elemental impurity guidelines with validated supplier qualification timelines. FDA bioavailability substantiation requirements reshape permissible marketing claims for diuretic-induced hypokalemia indications.
- Nutraceuticals:Mineral supplement blenders source food-grade powder through pharmacy-centric distribution channels in Germany and France, bypassing traditional wholesale markups. EMA positions on mineral bioavailability force reformulation documentation updates across combination therapies.
- Food & Beverage:Fortification applications deploy potassium gluconate as a mineral salt under regional food additive frameworks with lower analytical testing burdens than clinical grades.
- Agriculture:Fertilizer compounders utilize technical-grade material for foliar feeding and hydroponic nutrient solutions where elemental purity requirements remain less stringent than human consumption specifications.
Pharmaceuticals commands the largest procurement volumes, though Nutraceuticals is expanding most quickly through direct-to-pharmacist distribution models.
Application:
Functional use cases span therapeutic electrolyte replenishment to crop nutrition, each imposing distinct purity and documentation requirements.
- Electrolyte Replenishment:Clinical protocols for diuretic-induced hypokalemia and chronic disease management drive pharmaceutical-grade consumption in United States aging demographics. Hospital procurement consortia impose penalty clauses for supply interruption, displacing fragmented distributor relationships.
- Dietary Supplements:Over-the-counter mineral portfolios position through pharmacy channels with dissolution profile data packages exceeding current monograph requirements. EMA national competent authorities interpret bioavailability guidance unevenly across European markets.
- Food Additives:Fortification applications in processed foods operate under FAO-WHO Codex Alimentarius specifications with reduced testing costs compared to clinical grades.
- Fertilizers:Agricultural nutrient solutions leverage potassium gluconate chelation properties for enhanced foliar absorption in hydroponic and precision farming systems.
Electrolyte Replenishment holds the leading position, while Dietary Supplements shows the steepest expansion trajectory through consumer health positioning.
Distribution Channel:
Channel selection reflects buyer concentration trends and regulatory documentation requirements across end-use segments.
- Wholesale:Traditional pharmaceutical distributor networks sustain mid-tier supplier relationships for generic mineral salt procurement, though hospital GPO consolidation compresses margins.
- Direct Sales:Single-source agreements with penalty clauses anchor United States hospital procurement consortia including Vizient and Premier, displacing fragmented relationships.
- Retail:Pharmacy-centric mineral supplement distribution in Germany and France captures consumer health volumes through bypassed wholesale markups.
- Online:E-commerce platforms serve nutraceutical blending operations and smaller compounders with reduced minimum order quantities and accelerated documentation access.
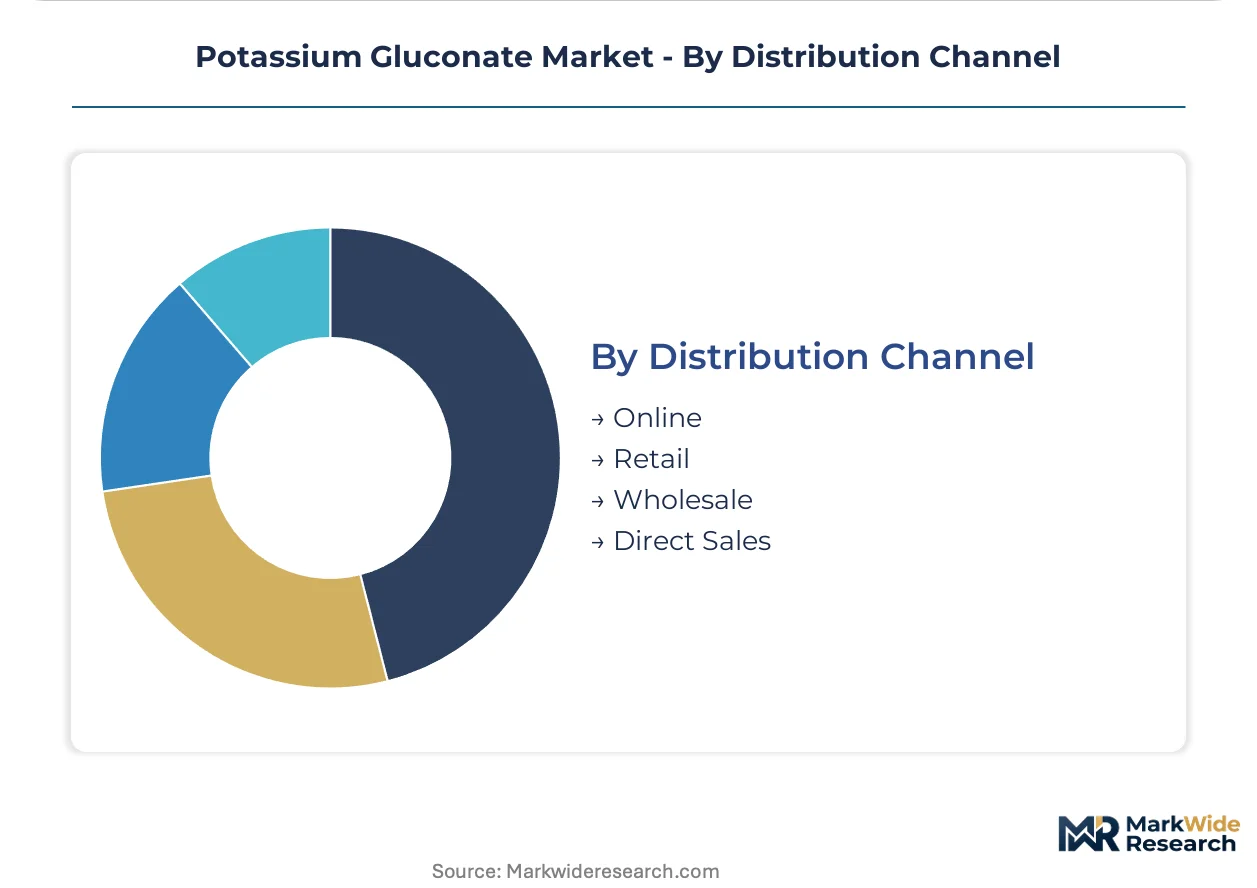
Wholesale retains the largest transaction volume, yet Direct Sales is gaining share fastest through hospital procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in potassium gluconate concentrate in pharmaceutical-grade corridors linking certified manufacturers in the United States, Germany, and India to formulation centers across Southeast Asia and Latin America. The United States maintains a structural deficit in clinical-grade mineral salts, sourcing validated material from European Union suppliers under mutual recognition agreements.
United States
Veterans Health Administration procurement contracts and regional hospital GPOs anchor pharmaceutical-grade consumption for diuretic-induced hypokalemia protocols. FDA Current Good Manufacturing Practice regulations enforce USP monograph compliance with escalating identity verification requirements. New Jersey and Pennsylvania host the densest clustering of oral electrolyte therapy formulators, where continuous manufacturing retrofits absorb capital allocations from mid-tier suppliers.
Germany
Pharmacy-centric distribution channels in Bavaria and North Rhine-Westphalia bypass wholesale markups for mineral supplement portfolios targeting geriatric compliance. EMA bioavailability substantiation guidance and European Pharmacopoeia elemental impurity standards constrain supplier qualification timelines. The Frankfurt-Rhine-Main corridor concentrates contract manufacturing organizations serving both pharmaceutical and nutraceutical grade demand.
India
CDSCO regulatory harmonization with ICH Q3D guidelines creates procurement opportunities for USP-certified suppliers establishing technical partnerships with domestic formulators. Maharashtra and Gujarat host the primary bulk pharmaceutical chemical manufacturing clusters, where batch-to-batch variability reduction investments target export qualification. The country's national pharmaceutical regulator accelerates abbreviated new drug application reviews for electrolyte replenishment therapies.
Japan
PMDA quality management system requirements for mineral salt excipients elevate testing costs for market entrants seeking pharmaceutical-grade contracts. The Kanto region around Tokyo concentrates finished dosage form manufacturing for geriatric populations with elevated hypokalemia incidence. METI industrial policy supports process analytical technology adoption in legacy batch facilities serving domestic nutraceutical blenders.
China
NMPA pharmaceutical excipient registration reforms since 2020 compress supplier qualification timelines for domestic potassium gluconate manufacturers seeking international certification. The Yangtze River Delta and Shandong Peninsula host technical-grade production for agricultural chelation applications, with selected facilities upgrading to food-grade additive specifications under GB standards. Dual carbon goals drive neutralization process energy efficiency investments at carbonate feedstock integration points.
Potassium Gluconate Market Vendor Landscape
On the supply side, the industry is consolidating around certified manufacturers with validated continuous processing lines as FDA and EMA bioavailability guidelines tighten procurement qualification timelines. Tiered supplier pools separate pharmaceutical-grade USP monograph compliance from nutraceutical-grade FAO-WHO Codex Alimentarius specifications, with mid-scale batch manufacturers exiting the qualified vendor pool. Three strategic archetypes dominate: vertically integrated pharmaceutical conglomerates with captive mineral salt sourcing, specialized excipient manufacturers with dedicated electrolyte portfolios, and diversified chemical suppliers serving technical-grade agricultural applications. Competitive moves concentrate on single-source hospital procurement contracts with penalty clauses and continuous manufacturing technology licensing to compress release timelines.
Within the pharmaceutical conglomerate tier, GlaxoSmithKline plc, Novartis AG, and Bayer AG occupy positions representing distinct strategic emphases. GlaxoSmithKline anchors high-purity mineral salt sourcing through respiratory and metabolic franchise infrastructure. Novartis exemplifies integrated active pharmaceutical ingredient network control sustaining vertical command over excipient quality. Bayer represents consumer health positioning through pharmacy-centric distribution channels in European mineral supplement markets.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| Novartis AG |
| Bayer AG |
| Merck & Co., Inc. |
| Abbott Laboratories |
| Pfizer Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Dr. Reddy's Laboratories |
| Others |
Supply Flow & Price Mechanics
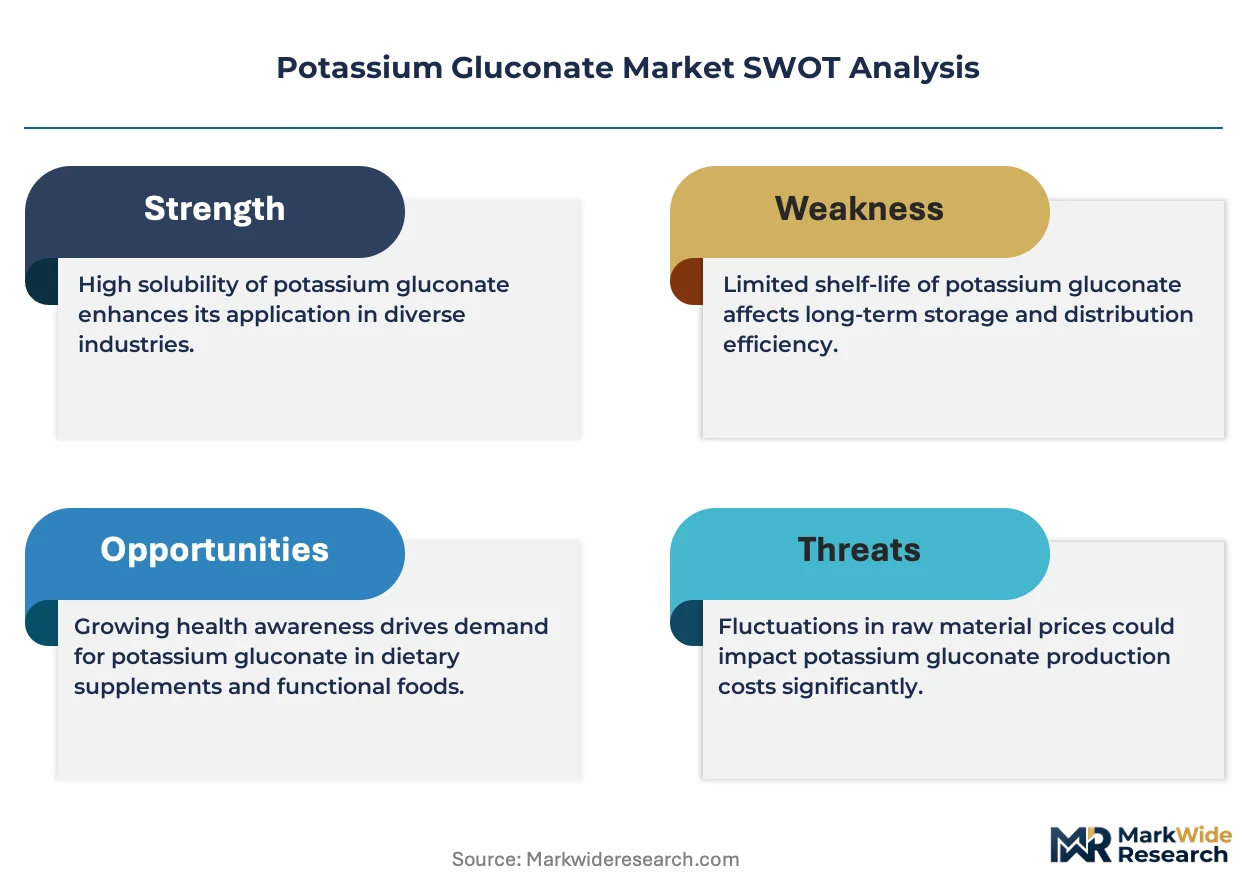
Potassium carbonate feedstock volatility compresses margin predictability for batch manufacturers without long-term supply contracts, forcing pricing stratification across pharmaceutical-grade USP-certified, nutraceutical-grade Codex-compliant, and technical-grade agricultural tiers while simultaneously concentrating procurement around validated continuous processing lines in the United States, Germany, and India.
Pricing Analysis
Hospital procurement consortia anchor contract-based long-term offtake structures with penalty clauses for supply interruption, compressing spot-market liquidity for clinical-grade material. Price differentiation hinges on USP monograph certification status and ICH Q3D elemental impurity testing depth, with FDA-validated suppliers commanding substantial premia over food-grade alternatives. Cost compression in nutraceutical powder grades is intensifying because magnesium gluconate substitution threats force competitive repricing. Generic mineral salt blenders exhibit highest price sensitivity, while Veterans Health Administration single-source agreements demonstrate lowest elasticity due to protocol adherence requirements.
Supply Chain Analysis
Export-control scrutiny on pharmaceutical-grade mineral salt processing equipment limits technology transfer to uncertified facilities, constraining capacity expansion in emerging manufacturing clusters. Supply concentrates in the United States for clinical-grade formulation, Germany for pharmacy-centric distribution infrastructure, and India for bulk pharmaceutical chemical production. Raw material dependencies center on potassium carbonate neutralization reagents, gluconic acid fermentation feedstocks, and analytical chemistry consumables for ICP-MS testing. Single-source vulnerability pervades hospital GPO procurement patterns. Distribution runs through direct sales channels for pharmaceutical-grade material and wholesale networks for nutraceutical blending operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Potassium gluconate sits in early-cycle expansion as geriatric compliance formats and continuous manufacturing adoption create penetration headroom previously blocked by batch-to-batch variability constraints.
For Market Incumbents: Build regulatory moats through preemptive USP monograph revision submissions and ICH Q3D elemental impurity data packages exceeding current EMA requirements. Consolidate procurement relationships with hospital GPOs like Vizient and Premier through single-source agreements embedding penalty clauses for supply interruption. Expand continuous manufacturing capacity in New Jersey and Pennsylvania to capture Veterans Health Administration contract renewals.
For New Entrants and Emerging Players: Establish a beachhead in Indian clinical segment partnerships with CDSCO-harmonized ICH Q3D compliance, where USP-certified supplier scarcity creates qualification gaps. Target Maharashtra and Gujarat bulk pharmaceutical chemical clusters with technical licensing arrangements for process analytical technology deployment. Pursue direct-to-pharmacist distribution in Germany and France to bypass wholesale markups in mineral supplement portfolios.
For Investors and Strategic Acquirers: EMA bioavailability substantiation guidance reshapes the acquisition landscape by elevating dissolution profile data capabilities above commodity manufacturing assets. Five-to-ten year viability favors specialized excipient manufacturers with dedicated electrolyte portfolios over diversified chemical suppliers lacking pharmaceutical-grade certification infrastructure. Monitor FDA positions on mineral bioavailability claims as the critical inflection signal for reformulation-driven demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Technology Licensing | PAT-enabled lines compress release timelines for hospital GPO contracts. |
| Backward Integration into Potassium Carbonate Sourcing | Captive supply of neutralization reagent insulates margin from feedstock volatility. |
| USP Monograph Preemptive Revision Submission | Early compliance with evolving FDA identity verification requirements locks out competitors. |
| Direct-to-Pharmacist Distribution Expansion | Bypassed wholesale markups capture consumer health volumes in Bavaria and North Rhine-Westphalia. |
| CDSCO Technical Partnership Establishment | ICH Q3D harmonization creates first-mover advantage in Indian clinical segment procurement. |
Methodological Framework
Initial hypotheses were tested against primary input from pharmaceutical formulators, hospital procurement managers, regulatory affairs leads at mineral salt suppliers, and contract manufacturing organization executives, and refined through secondary validation against FDA filings, EMA submission databases, USP monograph revision records, and customs trade data. Bottom-up demand modeling from end-use segment procurement patterns was triangulated with top-down supply-side capacity assessments across certified manufacturing facilities.
Demand-supply balance dynamics across the analysis window were assessed through segmented modeling of product type, end user specification tier, application function, and distribution channel concentration. CAGRs were derived from trajectory analysis of historical procurement volumes and projected protocol adoption rates in diuretic-induced hypokalemia management. Forecast inputs incorporated continuous manufacturing adoption curves and EMA bioavailability guidance implementation timelines.
Stress conditions across potassium carbonate price volatility bands, FDA inspection frequency scenarios, and hospital GPO consolidation rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization pace and substitution threat intensity from magnesium gluconate. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Galactoarabinan Market
Specialty Compounds
Potassium Monopersulfate (KMPS) Market
Specialty Compounds
Global Acetyls Market
Specialty Compounds
Arsenical Compounds Market
Specialty Compounds
Global Zinc Phosphate Market
Specialty Compounds
Asia-Pacific Collagen Market
Specialty Compounds
Specialty Monomer Market
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Thermoset Molding Compounds Market
Specialty Compounds
Oxygen Scavenger Masterbatch Market
Specialty Compounds
Dip Molding and Coating Market
Specialty Compounds
GCC Hydroxypropyl Methylcellulose Market
Specialty Compounds
Propylene Trimer Market
Specialty Compounds
Methane Sulfonyl Chloride Market
Specialty Compounds
Latin America Hydroxypropyl Methylcellulose Market
Specialty Compounds
N-Propyl Propionate Market