
 Galactoarabinan Market | 2026-2036
Galactoarabinan Market Size, Share, and Industry Trends Forecast 2026-2036
Galactoarabinan Market Foresight
ISO 16128 naturalness certification is redrawing competitive boundaries in botanical extract supply. Nexira leverages its Languedoc sourcing infrastructure to anchor European supply security for cosmetic-grade galactoarabinan. DuPont competes through R&D intensity in modified polysaccharide derivatives, while Cargill extends its agricultural raw-material networks into specialty gum arabic alternatives.
Galactoarabinan is a water-soluble arabinogalactan polysaccharide extracted primarily from larch wood, composed of galactose and arabinose units in a 6:1 ratio, functioning as a moisture-binding film former and stabilizer in cosmetic and food systems. Powder formulations dominate current volume due to superior shelf stability and handling economics for industrial buyers. Liquid extract grades represent the fastest-expanding category as cold-process cosmetics manufacturers seek ready-to-disperse formats that eliminate hydration steps.
EMA guidelines on excipient quality and REACH substance registration govern European market access, while FDA GRAS self-affirmation pathways shape United States food and nutraceutical deployment. These frameworks elevate documentation burdens for new suppliers and concentrate procurement relationships with established qualified vendors. Stakeholders must monitor evolving naturalness certification thresholds and regional biomass sustainability mandates to preserve formulation eligibility and sourcing continuity.
Market Dynamics
Clean-label formulation mandates and ISO 16128 naturalness certification are compressing supplier qualification timelines, forcing cosmetic formulators to consolidate procurement relationships with REACH-registered gum specialists who control larch wood sourcing infrastructure.
Growth Catalysts
- REACH substance registration:European ECHA compliance requirements are filtering out unqualified raw material traders, concentrating demand among certified botanical extract suppliers with documented biomass traceability.
- Cold-process cosmetics manufacturing:Ready-to-disperse liquid extract formats are eliminating hydration steps for mid-sized personal care producers seeking production efficiency gains.
- France:Premium skincare brands in this market are specifying film-forming polysaccharides for water-resistant sunscreen and foundation formulations.
Market Restraints
- Larch wood supply concentration:North American and Siberian forestry operations control primary galactoarabinan feedstock, exposing processors to pulp industry demand fluctuations and climate-related harvest disruptions.
- Technical substitution:Acacia senegal gum and modified starches compete in cost-sensitive food stabilizer applications where film-forming performance requirements are less stringent.
- EMA excipient quality documentation:European pharmaceutical-grade qualification timelines extend 18-24 months, freezing out new suppliers without established pharmacopeial master files.
Strategic Opportunities
- United States nutraceutical deployment:FDA GRAS self-affirmation pathways enable faster market entry for dietary fiber applications in functional beverages and gut health supplements.
- Biomass sustainability mandates:EU Green Deal due diligence requirements favor suppliers with FSC-certified larch forestry partnerships and verified carbon accounting.
- Encapsulation technology convergence:Spray-dried microencapsulation combined with galactoarabinan film-forming properties creates controlled-release delivery systems for active cosmetic ingredients.
Industry Challenges
- Analytical chemistry skill scarcity:Polysaccharide structural characterization and molecular weight distribution analysis require specialized chromatography expertise that competes with pharmaceutical biologics sectors for talent.
- ISO 16128 certification timeline:Natural origin index calculations and supply chain documentation audits demand 12-18 month preparation cycles before cosmetic brand qualification.
- Legacy hydration equipment:Powder-to-liquid processing lines at established manufacturers require capital retrofit to handle pre-hydrated extract grades without microbial contamination risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Galactoarabinan Market |
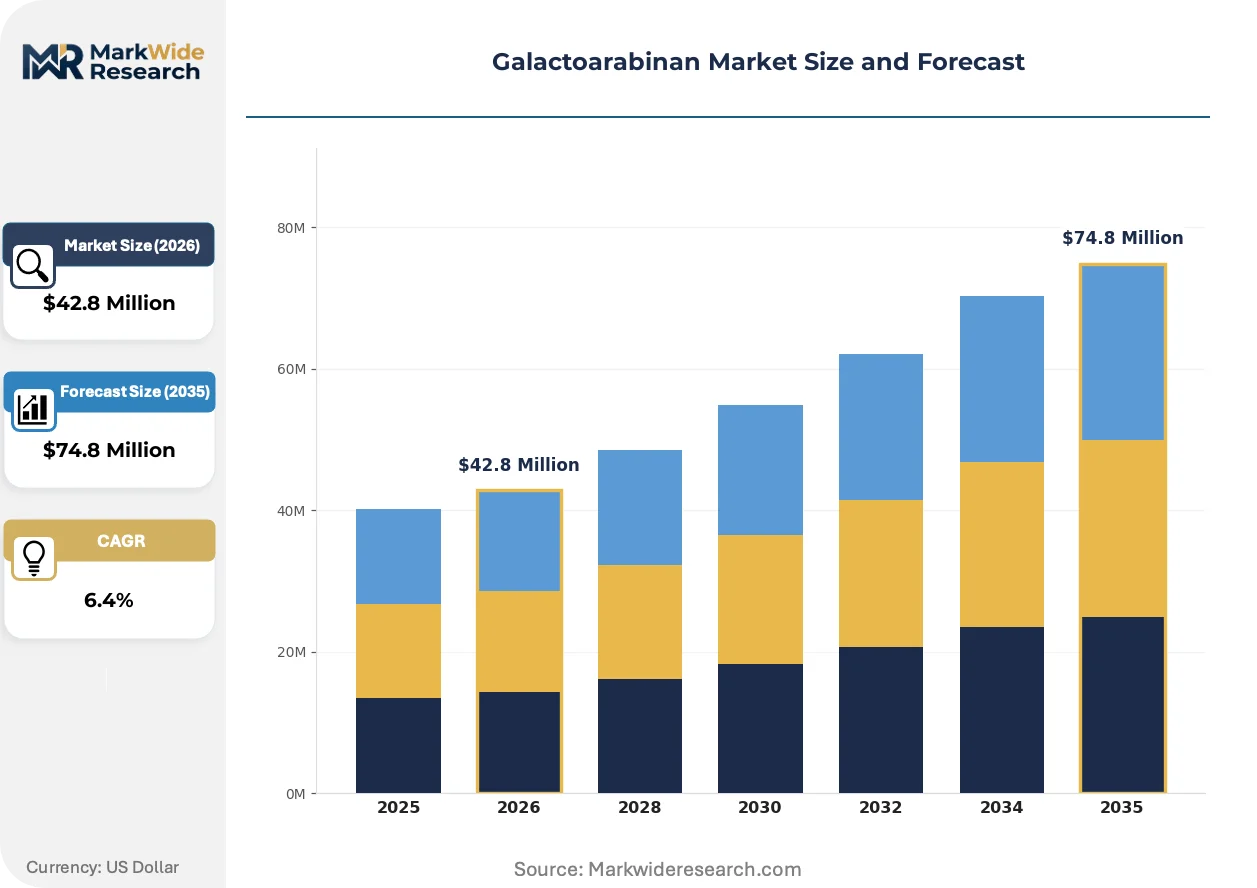
| Market Size in 2026 | $42.8 Million |
| Market Size in 2035 | $74.8 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Liquid Extract, Concentrate Application: Food & Beverage, Cosmetics Formulations, Pharmaceuticals, Nutraceuticals End User Industry: Personal Care Manufacturers, Dietary Supplement Producers, Pharmaceutical Companies, Food Processors Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | DuPont, Nexira, Lonza, Ingredion, TCI Chemicals, TRI-K Industries, Cargill, Tate & Lyle, MakingCosmetics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Galactoarabinan Market Shifts & Advancements
Formulation science and regulatory naturalness standards are rewriting raw material specifications across cosmetic and food applications, compressing the acceptable supplier base while opening premium positioning for certified botanical derivatives.
Enzymatic hydrolysis of arabinogalactan polymers is decomposing high-molecular-weight larch extracts into lower-viscosity fractions with enhanced skin penetration. Korean and French cosmetic laboratories are adopting these modified polysaccharides for serum formulations. This molecular weight fractionation is decomposing the traditional single-grade supply model into tiered performance categories.
EMA excipient quality guidelines and EU CSRD sustainability reporting obligations are tightening documentation requirements for botanical supply chains. Cosmetic and pharmaceutical manufacturers must now maintain batch-level traceability from forestry harvest to finished formulation. Small-volume gum traders without integrated sourcing infrastructure face exclusion from qualified vendor lists.
Brand procurement teams are consolidating supplier relationships around vertically integrated processors with captive larch forestry operations. Direct contracting replaces spot-market purchasing for film-forming agents. This concentration pattern is most pronounced in French and German premium personal care markets where formulation stability and supply continuity carry equal weight in sourcing decisions.
Galactoarabinan Market Segmentation
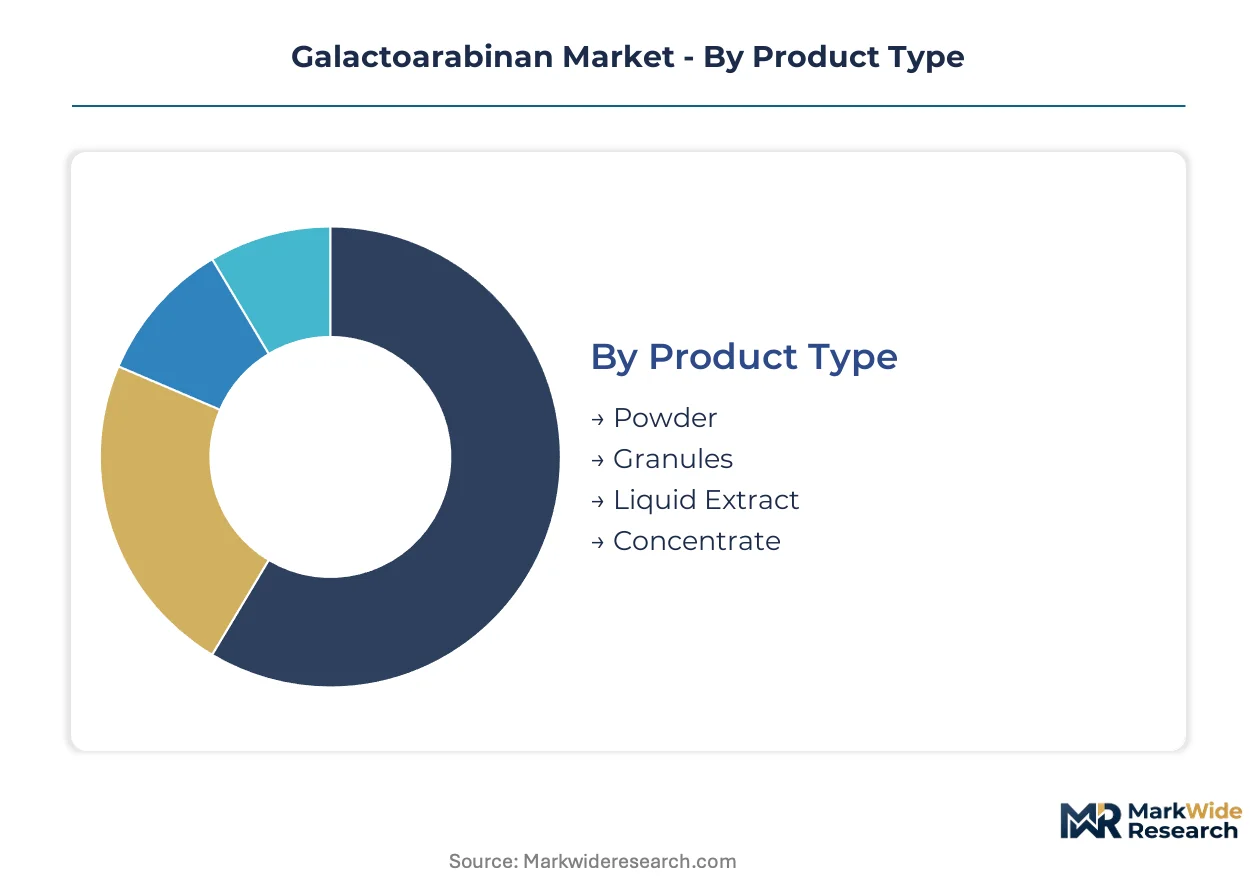
Segmentation in the galactoarabinan market reflects divergent technical specifications across regulatory jurisdictions. Powder grades face REACH registration burdens in Europe, while liquid extracts navigate FDA GRAS pathways in the United States.
Product Type:
REACH substance registration and FDA GRAS self-affirmation create divergent qualification timelines across physical formats, with powder grades facing stricter ECHA documentation for industrial-scale cosmetic deployment.
- Powder:Dry-fine particulate formulations with superior shelf stability and bulk handling economics dominate industrial procurement for food stabilizers and cosmetic film-formers. REACH-registered suppliers in France and Germany concentrate volume here for premium personal care brands requiring documented biomass traceability.
- Liquid Extract:Pre-hydrated aqueous solutions eliminate dissolution steps for cold-process cosmetics manufacturers. Korean and French serum formulators are specifying these grades for enzymatically hydrolyzed low-viscosity fractions with enhanced skin penetration characteristics.
- Granules:Intermediate moisture-resistant agglomerates serve mid-scale food processors seeking controlled hydration rates in bakery and beverage applications.
- Concentrate:High-solids preparations target encapsulation technology integrators building controlled-release delivery systems for active cosmetic ingredients.
Powder handles the majority of throughput; liquid extract is the fastest mover on share.
Application:
Cost tier differentiation separates pharmaceutical-grade excipients from food stabilizers, with EMA quality documentation extending qualification timelines for the former.
- Cosmetics Formulations:Film-forming polysaccharides for water-resistant sunscreen and foundation applications command premium positioning. French premium skincare brands specify ISO 16128-certified grades with verified larch wood sourcing from FSC-certified forestry partnerships.
- Food & Beverage:Clean-label stabilizers and emulsifiers compete against acacia senegal gum and modified starches in cost-sensitive applications. Acacia senegal substitution pressure is strongest here where film-forming performance requirements are less stringent.
- Pharmaceuticals:EMA excipient quality guidelines and pharmacopeial master file requirements freeze out new suppliers without 18-24 month qualification cycles.
- Nutraceuticals:Dietary fiber applications in functional beverages and gut health supplements leverage FDA GRAS self-affirmation for faster United States market entry.
Cosmetics formulations carry the highest margin tier; nutraceuticals are expanding most quickly on volume.
End User Industry:
Customer type concentration favors vertically integrated processors with captive larch forestry operations over spot-market traders.
- Personal Care Manufacturers:Mid-sized and large-scale cosmetic formulators consolidate procurement around REACH-registered gum specialists with documented supply chain traceability. German and French markets show pronounced supplier concentration.
- Food Processors:Industrial-scale stabilizer buyers balance cost against clean-label positioning, with acacia senegal gum and modified starches competing in price-sensitive segments.
- Dietary Supplement Producers:Functional beverage and gut health supplement manufacturers leverage FDA GRAS pathways for faster ingredient qualification.
- Pharmaceutical Companies:EMA documentation requirements and pharmacopeial master file maintenance favor established qualified vendors with analytical chemistry capabilities for polysaccharide structural characterization.
Personal care manufacturers dominate procurement volume; dietary supplement producers are gaining share fastest.
Distribution Channel:
Supply concentration favors direct contracting over intermediaries, with brand procurement teams eliminating small-volume gum traders lacking integrated sourcing infrastructure.
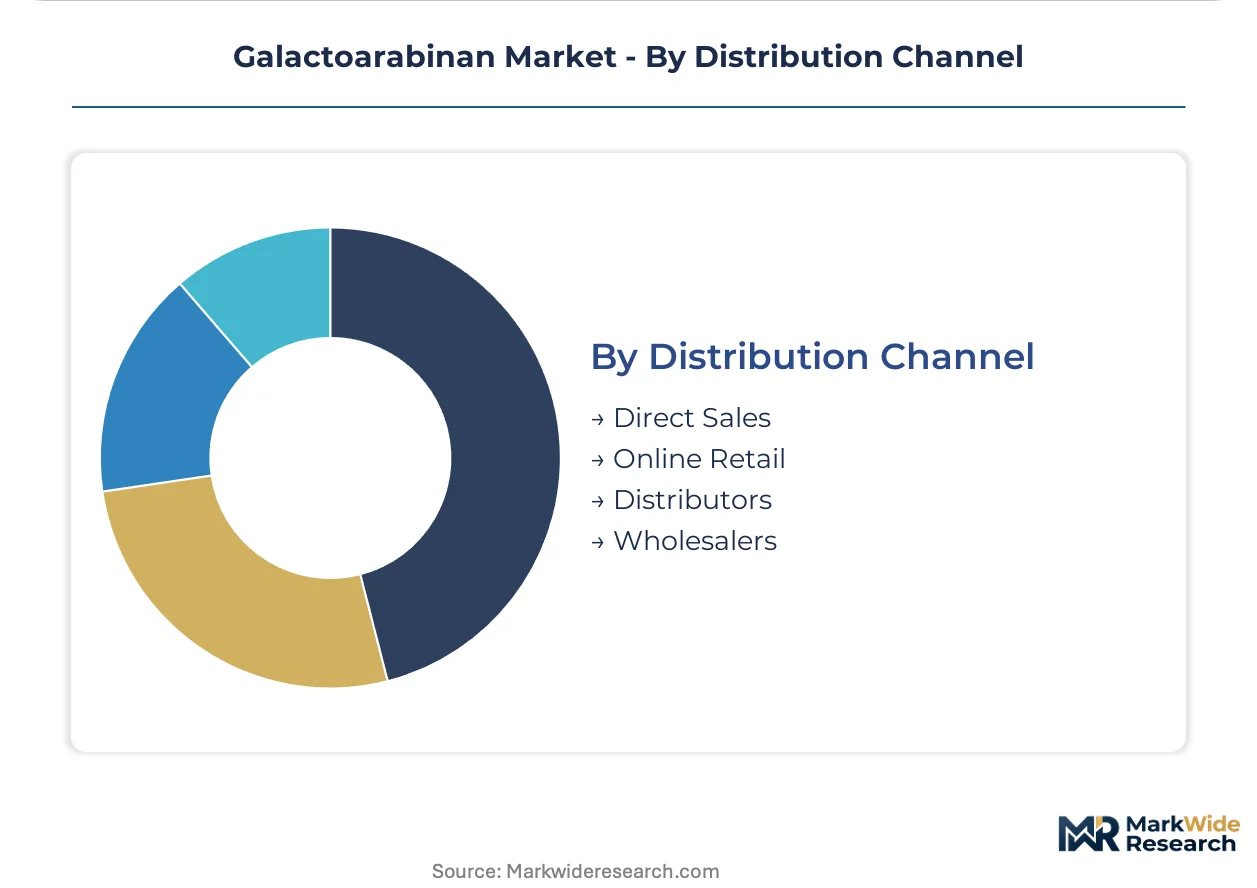
- Direct Sales:Long-term supply agreements between larch wood processors and premium cosmetic brands replace spot-market purchasing. French and German markets show this pattern most clearly.
- Distributors:Qualified botanical extract distributors with REACH registration and ISO 16128 certification capabilities serve mid-sized formulators lacking direct supplier relationships.
- Wholesalers:Bulk volume handlers serve cost-sensitive food processor segments where technical substitution pressures are highest.
- Online Retail:Small-volume specialty ingredient platforms target independent cosmetic formulators and research laboratories.
Direct sales channels command the steepest expansion trajectory; wholesalers retain position in food-grade volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal due diligence requirements and FDA GRAS self-affirmation pathways are redrawing procurement geography for galactoarabinan suppliers. REACH-registered processors with FSC-certified larch forestry partnerships command preferential access in premium cosmetic and pharmaceutical channels.
United States
Personal care manufacturers in New Jersey and California specify galactoarabinan for water-resistant sunscreen formulations. FDA GRAS self-affirmation enables faster nutraceutical deployment in functional beverages and gut health supplements. Midwest dietary supplement producers leverage these pathways for rapid ingredient qualification.
France
ISO 16128 naturalness certification mandates from premium skincare brands in Paris and Lyon drive specification of film-forming polysaccharides. ANSM cosmetic safety guidelines reinforce documentation requirements for botanical extract traceability. Cosmetic laboratories in Grasse and the Île-de-France cluster specify enzymatically hydrolyzed low-viscosity fractions for serum formulations.
Germany
EMA excipient quality guidelines extend pharmaceutical-grade qualification timelines to 18-24 months. REACH substance registration requirements filter out unqualified raw material traders. Chemical processors in North Rhine-Westphalia and Bavaria consolidate supply relationships with established gum specialists possessing pharmacopeial master files.
China
SAMR cosmetic ingredient registration and GB standards compliance create dual-track qualification requirements for imported botanical extracts. NMPA pharmaceutical excipient guidelines elevate documentation burdens. Manufacturers in the Yangtze River Delta seek REACH-registered suppliers for export-oriented cosmetic production.
South Korea
MFDS cosmetic safety standards and clean-label formulation trends from Seoul-based beauty brands specify plant-derived film formers. Korean cosmetic laboratories adopt enzymatically modified galactoarabinan for enhanced skin penetration in serum products. The Seoul Capital Area concentration of R&D facilities drives specification of liquid extract grades.
Galactoarabinan Market Competitive Landscape
Player mix skews toward vertically integrated botanical extract processors with captive larch wood sourcing infrastructure. Mid-sized specialty gum specialists compete through ISO 16128 certification and REACH registration capabilities. Three archetypes dominate: forestry-integrated processors, R&D-intensive modified polysaccharide developers, and agricultural network extenders. Competitive moves concentrate on direct long-term supply agreements with premium cosmetic brands and enzymatic hydrolysis technology licensing for molecular weight fractionation.
Within the forestry-integrated tier, Nexira anchors European supply security through Languedoc sourcing infrastructure. DuPont occupies a position among R&D-intensive developers of modified polysaccharide derivatives. Cargill exemplifies the agricultural network extender archetype, leveraging existing raw-material relationships into specialty gum alternatives. These three represent distinct strategic postures without implying specific market share or revenue claims.
| Leading Market Players |
|---|
| DuPont |
| Nexira |
| Lonza |
| Ingredion |
| TCI Chemicals |
| TRI-K Industries |
| Cargill |
| Tate & Lyle |
| MakingCosmetics Inc. |
| Others |
Supply & Pricing Matrix
Acacia senegal gum displacement in cost-sensitive food stabilizer applications simultaneously redraws supply geography toward larch wood processors and compresses pricing economics for non-certified grades. REACH-registered suppliers in France and Germany capture premium positioning through documented biomass traceability while unqualified traders face margin erosion.
Pricing Analysis
Certification level (ISO 16128, REACH registration, EMA excipient quality) creates the primary spread between pharmaceutical-grade and food-grade galactoarabinan. Three-tier pricing structure across premium cosmetic, standard food, and economy stabilizer levels dominates transactional flows. Cost compression in food-grade tiers is intensifying because acacia senegal gum and modified starches compete aggressively where film-forming requirements are less stringent. Food processors exhibit highest price sensitivity; premium cosmetic brands in France and the United States prioritize supply continuity over unit cost.
Supply Chain Analysis
Strategic stockpiling of larch wood feedstock prevails among integrated processors facing pulp industry demand fluctuations and climate-related harvest disruptions. Primary supply draws from North American forestry operations in the Pacific Northwest, Siberian timber zones, and Languedoc sourcing infrastructure controlled by Nexira. Raw material dependencies center on larch wood harvesting cycles, enzymatic hydrolysis reagents, and spray-drying equipment for microencapsulation. Single-source vulnerability concentrates in Siberian supply corridors exposed to geopolitical logistics chokepoints. Distribution runs through direct long-term supply agreements between captive forestry operators and premium cosmetic brands, with qualified botanical extract distributors serving mid-sized formulators lacking direct relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic hydrolysis technology for molecular weight fractionation is disrupting traditional single-grade supply models, compressing qualification timelines and opening white-space for certified entrants.
For Market Incumbents: Fortify supply security through backward integration into FSC-certified larch forestry partnerships in North America and Languedoc. Deepen analytical chemistry capabilities for polysaccharide structural characterization to defend against Korean and French cosmetic laboratories developing proprietary low-viscosity fractions. Prioritize ISO 16128 certification maintenance as emerging entrants without 12-18 month documentation cycles face automatic exclusion from qualified vendor lists. For New Entrants and Emerging Players: FDA GRAS self-affirmation fast-tracks offer the most penetrable entry pathway for United States nutraceutical deployment in functional beverages and gut health supplements. Target mid-sized dietary supplement producers in the Midwest seeking rapid ingredient qualification outside EMA's 18-24 month pharmaceutical-grade timelines. Lead with liquid extract grades for cold-process cosmetics manufacturers eliminating hydration steps. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated processors with captive larch wood sourcing infrastructure and established pharmacopeial master files. Long-term viability across a 5-10 year window favors forestry-integrated archetypes over spot-market traders as EU Green Deal due diligence requirements harden. Watch enzymatic hydrolysis technology licensing deals as the primary inflection signal for molecular weight fractionation capability gaps.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into FSC-Certified Forestry | EU Green Deal due diligence requirements favor suppliers with verified carbon accounting and traceable biomass partnerships. |
| Enzymatic Hydrolysis Technology Licensing | Korean and French cosmetic laboratories seek low-viscosity fractions with enhanced skin penetration for serum formulations. |
| Long-term Supply Agreement with Premium Brands | Paris and Lyon skincare manufacturers specify film-forming polysaccharides with documented larch wood sourcing. |
| ISO 16128 Certification Investment | Natural origin index calculations and supply chain documentation audits demand 12-18 month preparation cycles. |
| Liquid Extract Grade Capacity Expansion | Cold-process cosmetics manufacturers in Seoul and California seek ready-to-disperse formats eliminating hydration steps. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cosmetic formulators, food stabilizer procurement leads, dietary supplement manufacturers, pharmaceutical excipient specialists, and larch wood forestry operators. Secondary validation drew from EMA excipient quality guidelines, FDA GRAS notification databases, REACH substance registration records, FSC certification registries, and customs trade data for botanical extract flows. Bottom-up volume modeling triangulated against top-down market sizing across grade tiers and application segments.
Across the analysis window, forecasts integrated product type segmentation (powder, liquid extract, granules, concentrate), application tier differentiation (cosmetics, food and beverage, pharmaceuticals, nutraceuticals), and end-user industry concentration patterns. CAGRs derived from historical volume trajectories adjusted for regulatory inflection points and substitution dynamics. Industry-specific inputs included larch wood harvest yield fluctuations, enzymatic hydrolysis adoption curves in Korean and French cosmetic laboratories, and REACH registration timeline compression effects.
Decision-makers should treat outputs as directional under assumptions of sustained clean-label formulation mandates and ISO 16128 certification permanence; material deviation would warrant model refresh. Forecasts reflect biomass sustainability mandate enforcement intensity, pulp industry demand competition for larch wood, and analytical chemistry talent scarcity progression. Revision becomes warranted when acacia senegal gum substitution rates or enzymatic hydrolysis technology licensing velocity crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Specialty Nitriles Market
Specialty Compounds
Putty Fillers Market
Specialty Compounds
Silicone Potting Compounds Market
Specialty Compounds
Specialty Monomer Market
Specialty Compounds
Hydrotalcite Market
Specialty Compounds
Silk Protein Market
Specialty Compounds
Metasulphite Market
Specialty Compounds
Global Specialty Oilfield Chemicals Market
Specialty Compounds
Global Zinc Phosphate Market
Specialty Compounds
Carbon Black for Packaging Market
Specialty Compounds
Nonene (Propylene Trimer) and Tetramer Market
Specialty Compounds
Triallyl Isocyanurate Market
Specialty Compounds
Global Powder Injection Molding (PIM) Market
Specialty Compounds
Hypalon Market
Specialty Compounds
Stannous Chloride Market
Specialty Compounds
Sodium Stannate Market