
 GCC Specialty Chemicals Market | 2026-2036
GCC Specialty Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Specialty Chemicals Market Intelligence
The GCC Standardization Organization's updated conformity assessment scheme is realigning market entry requirements for specialty chemical importers, favoring producers with robust compliance capabilities. This dynamic benefits large incumbents like SABIC, which leverages its scale to navigate complex regulatory frameworks across the region. Petro Rabigh sustains its competitive position through its integrated refining and petrochemical operations. Meanwhile, Borouge differentiates with its advanced polyolefin solutions tailored for demanding applications in infrastructure and packaging.
GCC specialty chemicals are performance-driven formulations produced for specific end-use effects, distinct from high-volume commodity chemicals. These products, such as polymer additives and catalysts, are valued for their function rather than solely their chemical composition. The application segment for construction chemicals experiences consistent demand tied to the region's extensive infrastructure and real estate projects. Adhesives and sealants represent a mature but technically evolving category, with innovation focused on environmental compliance and enhanced durability.
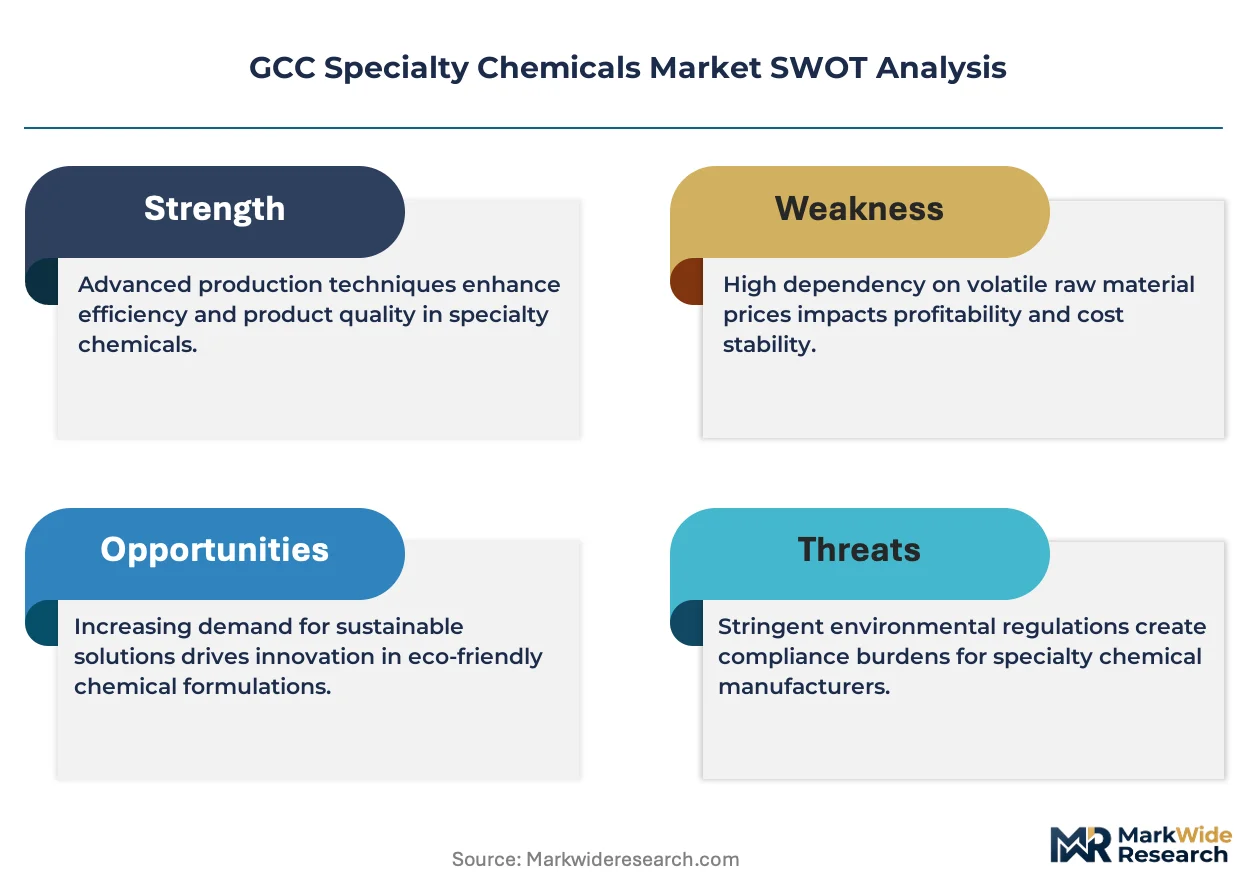
Regulatory oversight from bodies like the Saudi Food and Drug Authority (SFDA) and the UAE's Ministry of Health and Prevention (MOHAP) governs ingredients used in personal care and pharmaceutical applications. National sustainability frameworks, including Saudi Vision 2030 and the UAE Green Agenda 2030, are pushing for greener formulations and reduced volatile organic compound (VOC) content. Producers must now decide whether to lead with investments in sustainable chemistry or risk losing share in specification-driven procurements.
Market Dynamics
National diversification strategies across the GCC create a dual pressure on specialty chemical producers. These agendas, including Saudi Vision 2030 and the UAE Green Agenda 2030, simultaneously fuel demand for advanced formulations while tightening environmental and product conformity standards.
Growth Catalysts
- National Industrial Strategies:Programs like Saudi Vision 2030 fuel demand for construction chemicals and advanced polymers required for large-scale infrastructure projects.
- Downstream Sector Expansion:Growth in packaging and personal care manufacturing within industrial hubs like Jubail creates demand for specialized inputs like catalysts and surfactants.
- Logistics Infrastructure:Enhanced port capabilities in the UAE and Saudi Arabia improve the GCC's position as an export hub for specialty chemicals.
Market Restraints
- Feedstock Price Volatility:Dependence on hydrocarbon feedstocks exposes producers to global oil and gas price fluctuations, impacting production costs and margin stability.
- Regulatory Fragmentation:Disparate national standards from bodies like Saudi's SFDA and the UAE's MOHAP increase compliance costs and complicate pan-GCC market access.
- Commodity Chemical Competition:In certain applications, specialty formulations face substitution pressure from lower-priced commodity plastics and basic construction materials.
Strategic Opportunities
- Sustainable Formulations:Developing low-VOC coatings and bio-based polymers aligns with regional green building codes and sustainability mandates like the UAE Green Agenda 2030.
- Water Treatment Chemicals:Regional water scarcity creates demand for advanced coagulants and membrane chemicals for desalination and wastewater recycling plants.
- Process Digitalization:Adopting automation and data analytics in chemical plants can optimize production yields and improve supply chain efficiency for GCC producers.
Industry Challenges
- Specialized Talent Scarcity:A shortage of local talent in chemical engineering and R&D necessitates reliance on expatriate expertise, increasing operational costs for producers.
- High Capital Intensity:Building world-class specialty chemical facilities requires significant upfront capital investment, creating high entry barriers for new market entrants.
- Lengthy Certification Cycles:Securing product approvals from the GCC Standardization Organization (GSO) can be a protracted process, delaying new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Specialty Chemicals Market |
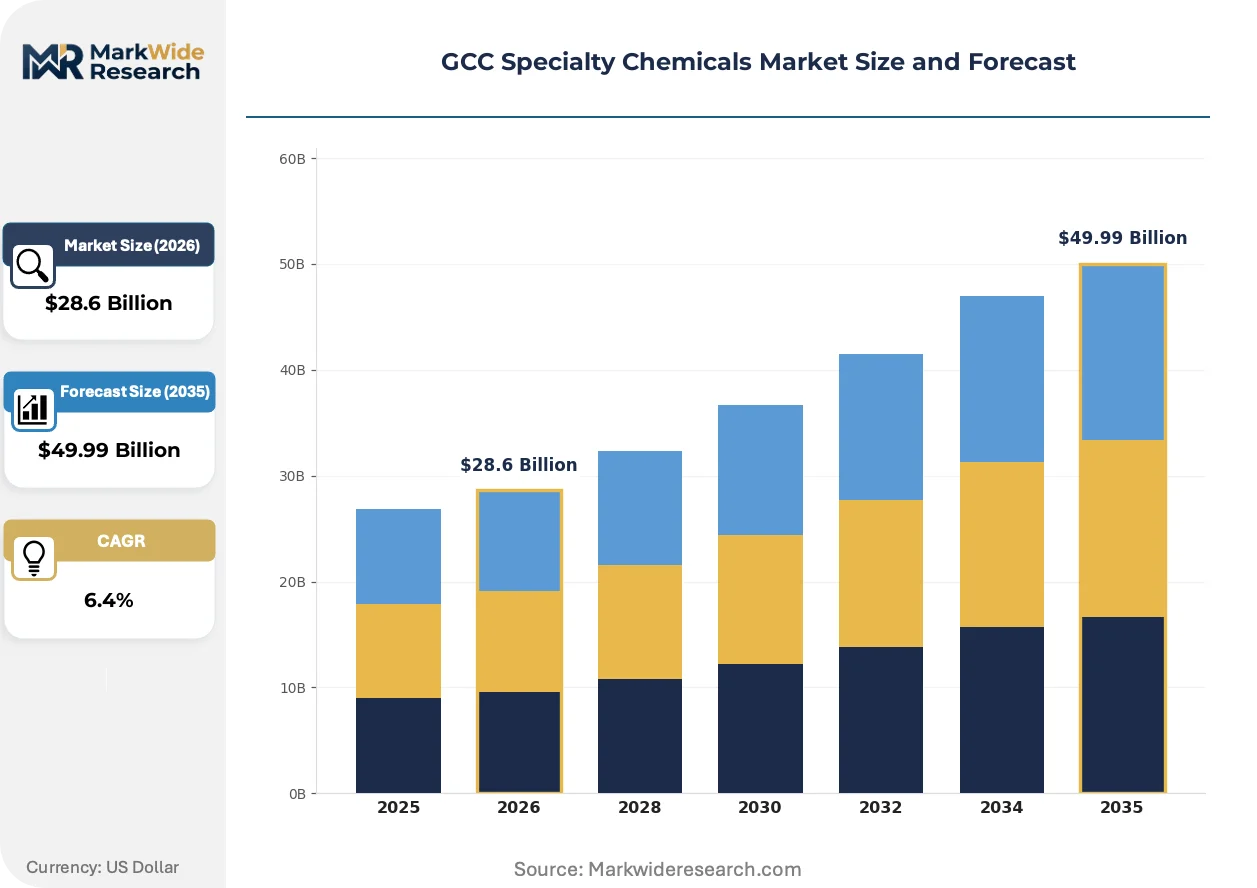
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $49.99 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adhesives, Coatings, Sealants, Surfactants Application: Automotive Coatings, Electronics Manufacturing, Personal Care Products, Construction Chemicals End User: Pharmaceuticals, Agrochemicals, Electronics, Plastics Distribution Channel: Direct Sales, Distributors, Online Sales, Retail |
| Companies Covered | Tasnee, SIPCHEM, SABIC, Yansab, SADAF, Saudi Aramco, Petro Rabigh, Advanced Petrochemical Company, Borouge, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Specialty Chemicals Market Strategic Shifts & Innovations
A fundamental shift toward performance-driven formulations is redefining the GCC's chemical sector. This transition is driven by sophisticated end-user requirements and national sustainability frameworks, pushing producers beyond bulk production toward specialized, high-value applications.
Digital twin technology, which creates virtual models of physical chemical processing units, is gaining traction for process simulation. Large-scale producers in industrial hubs like Jubail are the primary adopters, integrating these models into plant management systems. This technology is automating fault detection and predictive maintenance scheduling, reducing plant downtime and improving asset reliability.
The GCC Standardization Organization's updated conformity assessment scheme imposes stringent documentation and testing requirements for specialty chemicals. This regulation raises entry barriers, favoring established producers with dedicated compliance resources over smaller importers. Construction chemical and polymer additive suppliers are most affected, now needing extensive technical dossiers to secure market access across member states.
Specification-based purchasing is becoming standard in the region's construction sector, moving beyond simple product selection. This model disrupts traditional volume-based sales, forcing suppliers to provide system-level performance data tied to project outcomes like green building certifications. This shift is most prominent within large-scale developments in the UAE and Saudi Arabia's giga-projects.
GCC Specialty Chemicals Market Segmentation
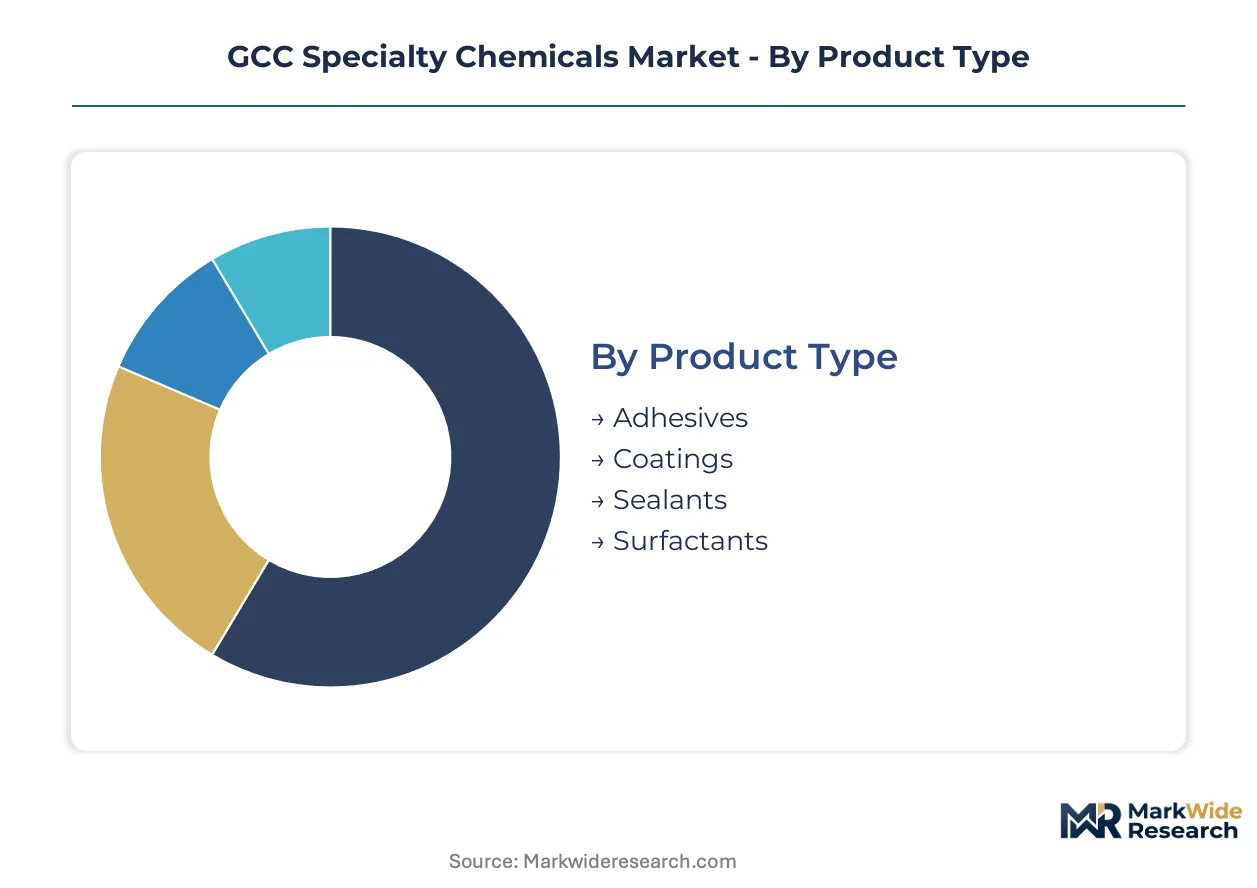
The GCC specialty chemicals market is a complex ecosystem, with distinct segments emerging based on product type, application, end-user industry, and distribution channels. Understanding these differentiations is crucial for navigating specific demand drivers and regulatory nuances within the region.
Product Type:
The GCC specialty chemicals market differentiates products based on their functional specifications and chemical formulations.
- Coatings:Formulated polymers and additives providing protective and aesthetic layers for various substrates. Demand is concentrating in Saudi Arabia's giga-projects, driven by stringent performance requirements for infrastructure and architectural applications.
- Adhesives:High-performance bonding agents designed for specific substrate interactions and environmental resistance. Demand is concentrating in the UAE's packaging sector, responding to requirements for enhanced durability and sustainability.
- Sealants:Flexible compounds used for gap filling, waterproofing, and joint sealing in construction projects across the GCC.
- Surfactants:Surface-active agents employed in personal care products, industrial cleaning formulations, and oilfield chemicals throughout the region.
Mature deployment sits with Adhesives. Newer deployment is concentrated in Coatings.
Application:
Specialty chemical applications across the GCC are defined by their specific end-use environments and performance requirements.
- Construction Chemicals:Performance-enhancing admixtures, waterproofing agents, and repair mortars essential for large-scale infrastructure and real estate developments. Demand is concentrating in Saudi Arabia and the UAE, driven by ambitious national building programs.
- Personal Care Products:Specialized ingredients like emollients, thickeners, and UV filters formulated for cosmetics and hygiene items. Demand is concentrating within the UAE's growing consumer goods manufacturing sector, responding to local consumer preferences.
- Automotive Coatings:Protective and decorative finishes applied to vehicle components, primarily supporting regional automotive assembly and repair industries.
- Electronics Manufacturing:High-purity chemicals and compounds used in circuit board fabrication and device assembly for the GCC's technology sector.
Construction Chemicals exhibit the steepest expansion trajectory, while Automotive Coatings maintain a consistent demand profile.
End User:
The end-user industries for specialty chemicals in the GCC dictate product specifications and volume requirements.
- Pharmaceuticals:High-purity excipients, active pharmaceutical ingredients (APIs), and specialized coatings critical for drug formulation and delivery systems. Demand is concentrating in Saudi Arabia's burgeoning healthcare sector, driven by national self-sufficiency initiatives.
- Plastics:Polymer additives, colorants, and processing aids that enhance the properties and performance of plastic materials. Demand is concentrating in the UAE's packaging and construction industries, supporting advanced material requirements.
- Agrochemicals:Formulations including pesticides and fertilizers designed to improve agricultural yield and crop protection in the region's food security programs.
- Electronics:Advanced materials such as specialty resins and high-performance adhesives vital for device manufacturing and component assembly within the GCC.
The Pharmaceuticals segment is expanding most quickly, driven by regional health initiatives.
Distribution Channel:
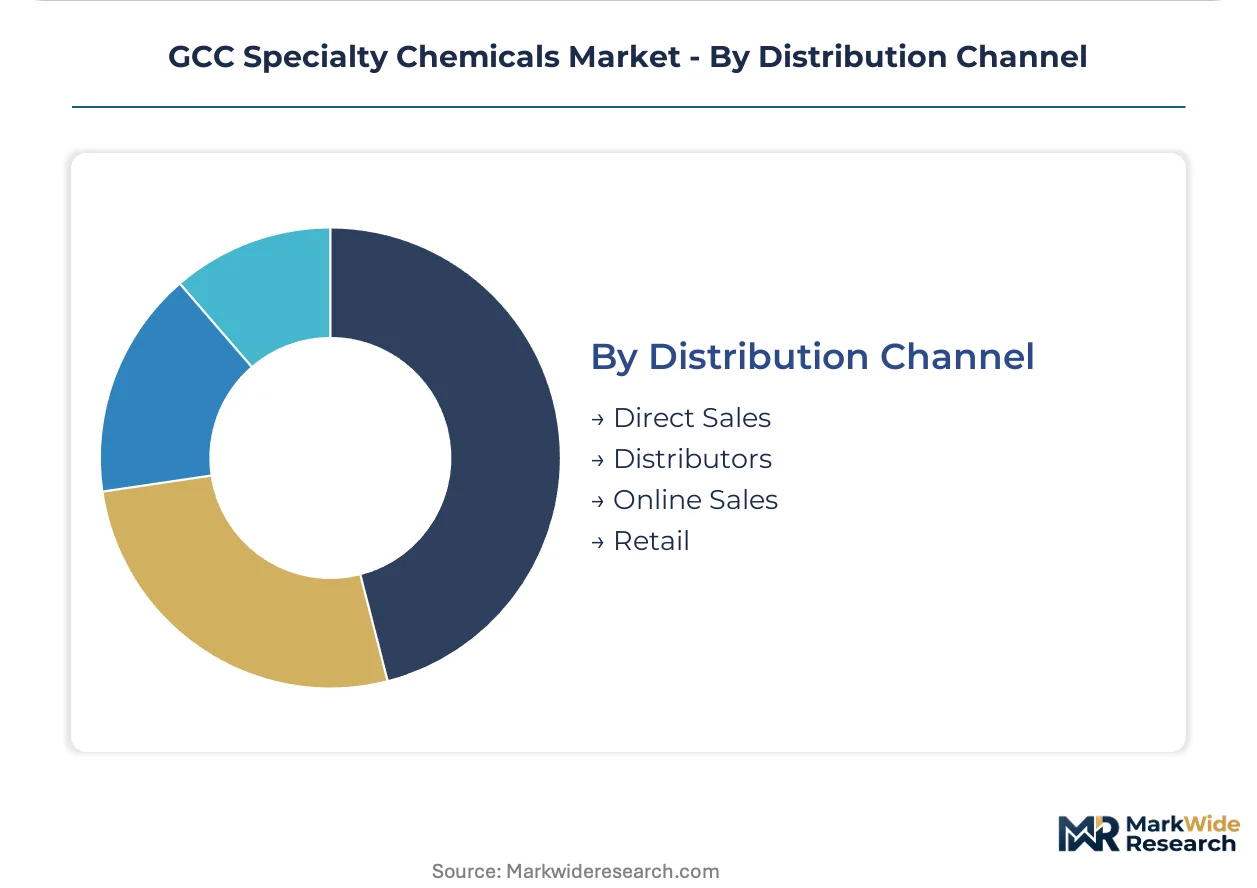
Distribution channels for specialty chemicals in the GCC are shaped by customer scale and logistical requirements.
- Direct Sales:Manufacturers engage directly with large industrial customers, offering tailored technical support and bulk supply agreements. This channel dominates for high-volume or highly specialized chemical products in Saudi Arabia's industrial hubs.
- Distributors:Third-party entities manage warehousing, logistics, and sales for a portfolio of specialty chemicals, serving a diverse customer base. This channel is crucial for market penetration across the broader GCC, especially for smaller and medium-sized enterprises.
- Online Sales:E-commerce platforms facilitate transactions for standardized or lower-volume specialty chemicals, gaining traction for efficiency in the UAE.
- Retail:Limited sales of specialized chemical products through physical stores, typically for smaller-scale or consumer-facing applications.
Direct Sales remain the primary mechanism for large-scale procurements, while Online Sales represent a nascent but growing channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for specialty chemicals in the GCC region concentrates heavily around ambitious national development strategies and burgeoning industrial hubs. These initiatives drive significant requirements for advanced formulations in construction, packaging, and personal care sectors. The region's focus on economic diversification fuels specific demand for high-value chemical products.
Saudi Arabia
Saudi Vision 2030 fuels substantial demand for construction chemicals and advanced polymers within Saudi Arabia. The Saudi Food and Drug Authority (SFDA) regulates ingredients for pharmaceutical and personal care applications, influencing product specifications. Industrial cities like Jubail and Yanbu are central to manufacturing and export activities, requiring a diverse range of specialized chemical inputs.
United Arab Emirates
The UAE Green Agenda 2030 drives demand for sustainable formulations and low-VOC coatings across the United Arab Emirates. The Ministry of Health and Prevention (MOHAP) oversees health and safety standards for chemical products, impacting market entry. Growing consumer goods manufacturing in Dubai and Abu Dhabi requires specialized ingredients for personal care and packaging.
Qatar
Qatar's extensive infrastructure projects generate consistent demand for construction chemicals and performance additives. Qatar National Vision 2030 encourages industrial diversification, creating new opportunities for specialty chemical applications. Industrial zones such as Ras Laffan and Mesaieed are expanding their petrochemical capabilities, increasing the need for catalysts and process chemicals.
Kuwait
Kuwait's national development plans stimulate demand for water treatment chemicals and construction materials. Kuwait Vision 2035 aims to transform the nation into a regional financial and commercial hub, necessitating advanced infrastructure. Industrial areas like Shuaiba and Mina Abdullah support petrochemical production and manufacturing, requiring specialized chemical inputs.
GCC Specialty Chemicals Market Key Industry Players
GCC producers anchor one tier, leveraging integrated operations and regional feedstock advantages; international specialists hold another, competing on advanced formulations and niche applications. The market structure favors large incumbents with robust compliance capabilities. Strategic archetypes include integrated petrochemical giants, specialized solution providers, and technology-driven innovators. Dominant competitive moves involve capacity expansion and strategic partnerships for market access.
Within the integrated petrochemical giant archetype, SABIC and Petro Rabigh exemplify significant scale and feedstock integration. SABIC, a large incumbent, leverages its extensive scale to navigate complex regulatory frameworks across the GCC. Petro Rabigh sustains its competitive position through its integrated refining and petrochemical operations, providing a stable supply chain. Borouge, another prominent player, differentiates with its advanced polyolefin solutions tailored for demanding applications in infrastructure and packaging sectors.
| Leading Market Players |
|---|
| Tasnee |
| SIPCHEM |
| SABIC |
| Yansab |
| SADAF |
| Saudi Aramco |
| Petro Rabigh |
| Advanced Petrochemical Company |
| Borouge |
| Others |
Cost & Logistics Intelligence
Saudi Arabia's giga-projects, as a major buyer archetype, drive project-based pricing for specialized construction chemicals. This procurement model prioritizes performance specifications over volume discounts.
Pricing Analysis
Short lead times for urgent infrastructure projects command premium pricing for specialty chemicals. The dominant pricing model for high-value formulations is value-based, reflecting specific performance outcomes rather than commodity spot rates. Price differentiation stems from certification levels, particularly for green building materials, and the extent of after-sales technical support. Pricing softness runs through basic construction materials due to local oversupply. Large industrial customers are less price-sensitive for mission-critical inputs, while smaller distributors purchasing standardized products exhibit higher sensitivity.
Supply Chain Analysis
Hydrocarbon feedstock supply for GCC specialty chemicals rests on regional oil and gas producers in Saudi Arabia and the UAE. Key dependencies include ethylene, propylene, and benzene, which are refined locally. Commodity price volatility poses a structural risk to margin stability for downstream chemical producers. Direct sales to large industrial customers dominate the distribution model for high-volume or highly specialized chemical products. Distributors manage logistics for a broader customer base, particularly for smaller and medium-sized enterprises across the GCC.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC specialty chemicals market is a vertical-integration race, with players actively pursuing upstream control over critical hydrocarbon feedstocks. This strategy aims to secure supply and manage cost volatility.
For Market Incumbents: Lock in long-term supply agreements for key feedstocks to mitigate global oil and gas price fluctuations. Invest in advanced R&D capabilities for sustainable formulations, addressing regulatory shifts like the UAE Green Agenda 2030. Capacity additions in industrial hubs like Jubail can further consolidate market share against smaller importers. The threat of commodity chemical competition requires continuous product differentiation.
For New Entrants and Emerging Players: Begin with niche applications in water treatment chemicals, targeting regional water scarcity solutions such as desalination. Focus on bio-based polymers for packaging, aligning with national sustainability frameworks. The personal care products segment in the UAE offers penetrable white space due to local consumer preferences. A digital-first go-to-market angle can efficiently reach smaller and medium-sized enterprises.
For Investors and Strategic Acquirers: The window for entry favors specialized solution providers with strong intellectual property in green chemistry over the next 5-10 years. Acquisition targets should include technology-driven innovators developing low-VOC coatings or advanced polyolefin solutions. These firms offer a competitive edge in specification-driven procurements. A key signal to watch is the acceleration of national sustainability framework mandates, indicating increased demand for compliant formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Jubail | Increases production volume for construction chemicals, supporting Saudi Vision 2030 infrastructure projects. |
| Green Manufacturing Transition | Aligns production processes with UAE Green Agenda 2030, reducing environmental impact and enhancing market access. |
| Long-term Feedstock Supply Agreements | Secures raw material inputs like ethylene, mitigating price volatility for petrochemical giants like SABIC. |
| Joint Venture for Water Treatment Technologies | Addresses regional water scarcity by developing advanced coagulants and membrane chemicals for desalination plants. |
| Digital Twin Technology Adoption | Optimizes plant operations in Yanbu, automating fault detection and improving asset reliability for large-scale producers. |
Research Approach
Independent corroboration across industry association reports, customs trade data, and national economic publications underwrites the qualitative findings. Primary interviews with R&D directors, procurement leads at construction companies, and distribution channel partners informed market dynamics. This primary data was validated through secondary research, including SEC 10-K filings from major chemical producers and national regulatory body publications. A bottom-up approach to market sizing was triangulated with top-down macroeconomic indicators.
Historical data from comparable periods anchored the forecast window, establishing baseline performance metrics. The analytical framework modeled segments by product type, application, end-user industry, and regional production hubs. Compound annual growth rates were derived through a regression analysis of historical trends and projected demand drivers. Regional infrastructure project pipelines and regulatory compliance costs served as key industry-specific forecast inputs.
Underlying measurement precision varies by segment; construction chemicals and personal care products carry tighter precision than others. Forecasts reflect assumptions regarding economic stability and regulatory enforcement. Geopolitical shifts and global feedstock price volatility represent specific risk factors that could revise projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Mexico Masterbatch Market
Specialty Compounds
Chemical Synthesis Methyl Salicylate Market
Specialty Compounds
Asia-Pacific Collagen Market
Specialty Compounds
Polypeptide Market
Specialty Compounds
Kokum Butter Market
Specialty Compounds
Middle East and Africa Specialty Chemicals Market
Specialty Compounds
3-Hydroxyphenyl Phosphinyl Propanoic Acid Market
Specialty Compounds
Air-Laid Product Market
Specialty Compounds
Additive Masterbatch Market
Specialty Compounds
Superacids Market
Specialty Compounds
Global Specialty Zeolites Market
Specialty Compounds
Germany Collagen Market
Specialty Compounds
Putty Fillers Market
Specialty Compounds
Silk Protein Market
Specialty Compounds
Potting Compound Market
Specialty Compounds
Strontium Chloride Market