
 Offset Ink Market | 2026-2036
Offset Ink Market Size, Share, and Industry Trends Forecast 2026-2036
Offset Ink Market Intelligence
The transition to UV-curable ink formulations to reduce volatile organic compound (VOC) emissions is rewriting production workflows in commercial printing. Flint Group leverages its broad portfolio to serve diverse printing needs. DIC Corporation specializes in high-performance pigments for the demanding packaging segment. Siegwerk Druckfarben AG & Co. KGaA positions its brand around sustainable and food-safe ink solutions.
Offset ink is a viscous paste designed for lithographic printing, a process where the ink is transferred from a metal plate to a rubber blanket before reaching the substrate. Its formulation relies on the principle of oil and water immiscibility to create sharp, clean images. The Packaging and Labeling applications exhibit higher growth than mature Publication Printing segments. In terms of product, UV-Curable Ink gains share from traditional Oil-Based Ink due to faster curing times.
Regulations from the US EPA on volatile organic compounds and Europe's REACH framework directly influence ink formulation. Compliance with China's GB standards is also critical for market access in its vast packaging sector. These rules mandate lower toxicity and safer chemical compositions. Suppliers must now balance print performance, substrate compatibility, and evolving environmental mandates.
Market Dynamics
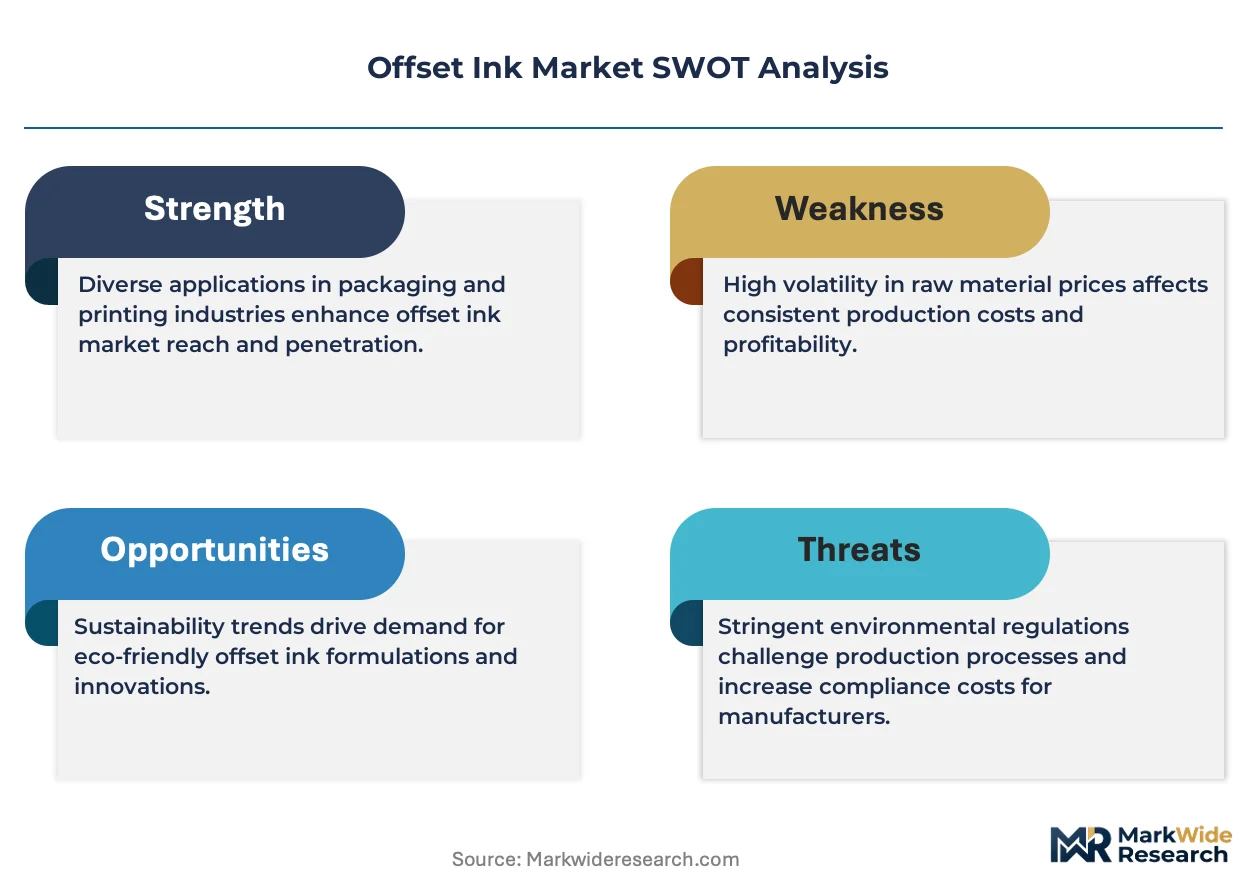
The collision between stringent environmental regulations and demand for high-fidelity graphics in packaging is the central structural force. Mandates like the EU's REACH and US EPA standards compel a fundamental reformulation of ink chemistry toward lower-VOC products.
Growth Catalysts
- UV-Curable Ink Adoption:These inks offer faster curing times and superior adhesion on non-porous substrates like plastics, driving their uptake in high-speed packaging and label printing applications.
- Packaging Sector Expansion:Growth in e-commerce and consumer goods elevates demand for high-quality printed packaging, particularly in the food and beverage sector where brand identity is critical.
- Chinese Export Economy:China's role as a major export hub creates concentrated demand for offset inks that comply with its domestic GB standards and international import rules.
Market Restraints
- Raw Material Volatility:The market's cost structure is exposed to price fluctuations in key inputs like vegetable oils, petroleum distillates, and pigments, impacting manufacturer margins.
- Digital Printing Substitution:The encroachment of digital printing for short-run and variable data jobs presents a substitution threat to traditional offset volumes in commercial printing.
- Formulation Complexity:Developing low-VOC and food-safe inks that maintain performance presents a significant technical hurdle for ink chemists.
Strategic Opportunities
- Bio-Based Formulations:Developing inks from renewable resources like soy or algae oil helps meet corporate sustainability goals and appeals to environmentally conscious brand owners.
- Functional Printing Applications:Expansion into functional inks for printed electronics or smart packaging opens new, high-value segments beyond traditional graphics.
- Southeast Asian Markets:Establishing supply chains in growing manufacturing economies like Vietnam and Indonesia offers access to underpenetrated markets for packaging printing.
Industry Challenges
- Regulatory Compliance Burden:Manufacturers must continuously reformulate products to meet a patchwork of evolving chemical safety standards, including Europe's REACH, US EPA rules, and China's GB standards.
- Capital Investment for Curing Systems:Retrofitting older offset presses with the required UV or LED-UV curing units to run new inks demands significant capital expenditure from printers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Offset Ink Market |
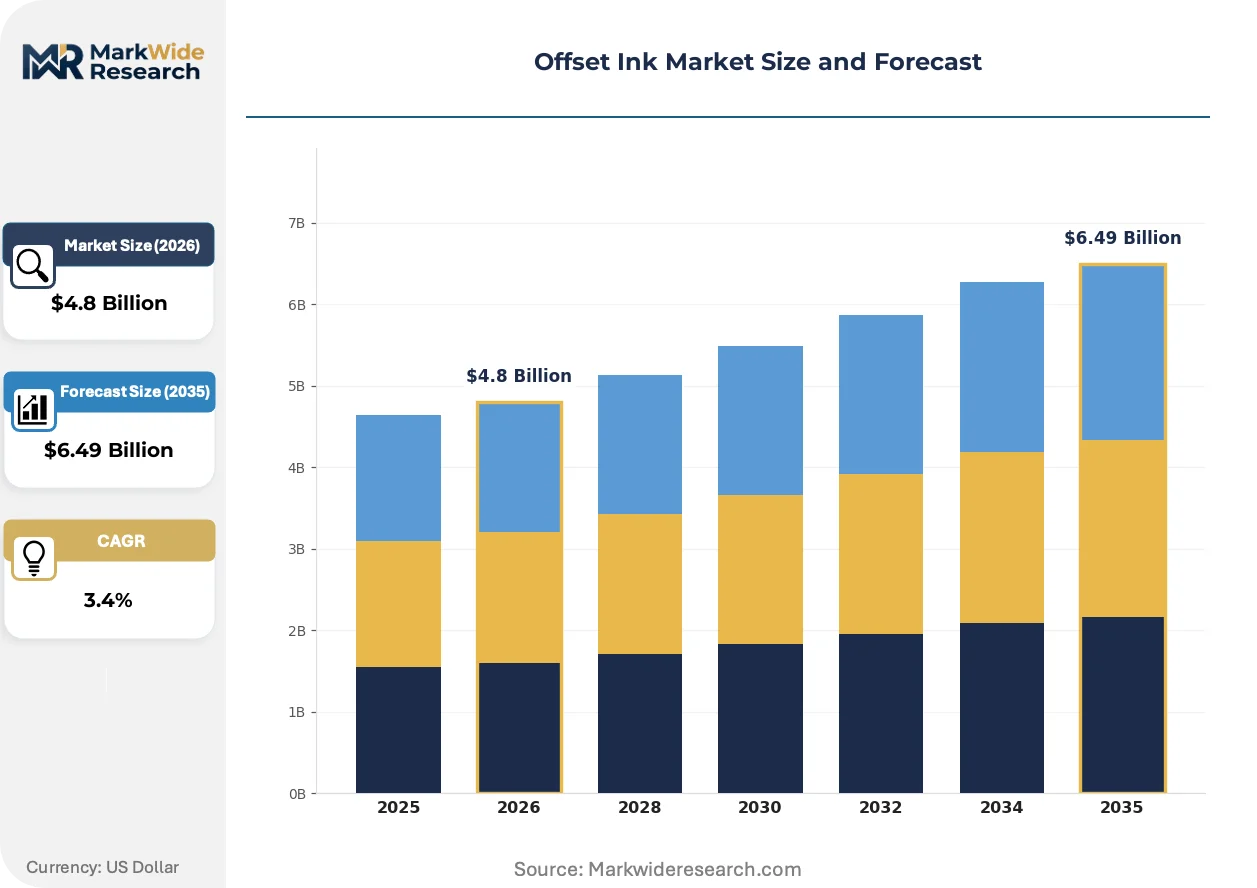
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.49 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Ink, Oil-Based Ink, UV-Curable Ink, Solvent-Based Ink Application: Commercial Printing, Packaging, Labeling, Publication Printing End User: Publishing Houses, Packaging Companies, Advertising Agencies, Commercial Printers Technology: Digital Printing, Flexography, Lithography, Screen Printing |
| Companies Covered | Fujifilm Holdings Corporation, T&K Toka Co., Ltd., Flint Group, Sakata INX Corporation, DIC Corporation, Huber Group, SICPA Holding SA, Dainichiseika Color & Chemicals Mfg. Co., Ltd., Siegwerk Druckfarben AG & Co. KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Offset Ink Market Strategic Shifts & Innovations
The industry's evolution is defined by a dual push towards sustainability and process automation. Innovations focus on reducing environmental impact while integrating ink performance data into digital pressroom workflows for greater efficiency and quality control.
Advanced color management software, integrated with inline spectrophotometers, provides real-time color measurement and automatic adjustment. Brand owners and commercial printers adopt these systems for consistency across global production runs. This integration is virtualizing the traditionally manual process of color proofing and matching.
European Union regulations for food contact materials, like the Swiss Ordinance, are setting global standards for ink safety. This intensifies scrutiny on chemical migration from the package into the food. Packaging ink suppliers are responding by developing specialized low-migration UV and conventional inks, requiring significant investment.
Just-in-time inventory models are altering ink buying patterns as printers reduce working capital. This disrupts traditional bulk purchasing, favoring online ordering or vendor-managed inventory for smaller, frequent deliveries. The trend is most pronounced among small and medium-sized commercial printers in North America and Europe.
Offset Ink Market Segmentation
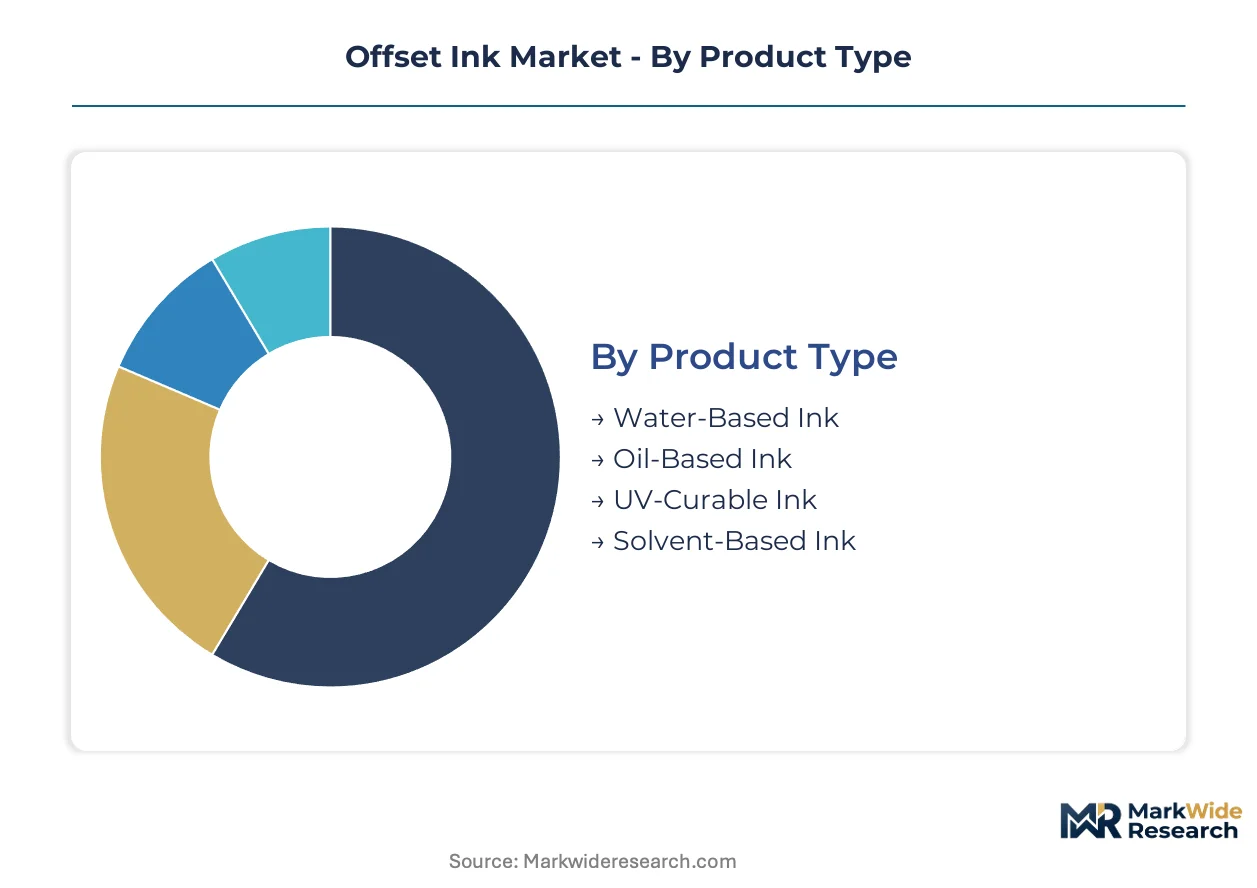
A detailed segmentation of the offset ink market reveals the diverse forces influencing product development and market dynamics. Understanding these distinct segments allows manufacturers to tailor formulations and sales strategies to specific end-use requirements and technological shifts. This granular view highlights areas of both robust expansion and mature stability within the industry.
Product Type:
The product type dimension reflects a blend of mature formulations and rapidly emerging ink chemistries driven by environmental mandates and performance demands.
- UV-Curable Ink:These formulations cure instantly under ultraviolet light, forming a durable film without solvent evaporation. Demand concentrates in high-speed packaging and label printing, driven by faster turnaround times and superior adhesion on non-porous substrates like plastics.
- Oil-Based Ink:Traditional offset inks utilize vegetable oils or petroleum distillates as their primary vehicle, providing excellent color density and stability on various paper stocks. This ink type remains prevalent in publication printing and general commercial applications due to its established performance and cost-effectiveness.
- Water-Based Ink:These inks incorporate water as the primary solvent, offering lower VOC emissions and easier cleanup for certain commercial printing jobs.
- Solvent-Based Ink:These inks offer fast drying times and strong adhesion for specific industrial applications requiring durability.
UV-Curable Ink handles the majority of throughput; Water-Based Ink is the fastest mover on share.
Application:
Application segments delineate where offset inks are consumed, reflecting varied volume requirements and performance expectations across different printing markets.
- Packaging:This segment utilizes offset inks for cartons, flexible packaging, and corrugated materials, demanding vibrant colors and food-safe formulations. Growth in e-commerce and consumer goods elevates demand for high-quality printed packaging, particularly in the food and beverage sector.
- Labeling:Offset inks provide sharp detail and durability for product labels, including pressure-sensitive and in-mold varieties. High-speed label presses increasingly adopt UV-curable inks for rapid curing and superior adhesion on diverse non-porous substrates.
- Commercial Printing:This category covers brochures, flyers, and marketing materials, where offset remains cost-effective for medium to long print runs.
- Publication Printing:Newspapers, magazines, and books represent this mature segment, characterized by high-volume, cost-sensitive production and traditional oil-based ink usage.
The Packaging sector drives significant innovation in ink formulation, while Publication Printing maintains a stable, high-volume base.
End User:
End user categories highlight the diverse customer base for offset inks, each with distinct purchasing patterns and technical requirements.
- Packaging Companies:These entities produce printed packaging for consumer goods, requiring inks that meet stringent food safety regulations and deliver consistent brand colors. Compliance with global standards, such as Europe's REACH and China's GB standards, is critical for market access.
- Commercial Printers:Serving a wide array of clients, these printers utilize offset inks for everything from business cards to direct mail campaigns. They face pressure to adopt low-VOC inks and invest in new curing technologies to remain competitive against digital alternatives.
- Publishing Houses:These users focus on large-volume book and magazine production, prioritizing cost-effectiveness and consistent print quality for long runs.
- Advertising Agencies:Agencies typically outsource printing, demanding high-fidelity color reproduction for promotional materials and brand campaigns.
Packaging Companies are actively driving demand for advanced, compliant ink solutions, whereas Publishing Houses represent a foundational, high-volume customer segment.
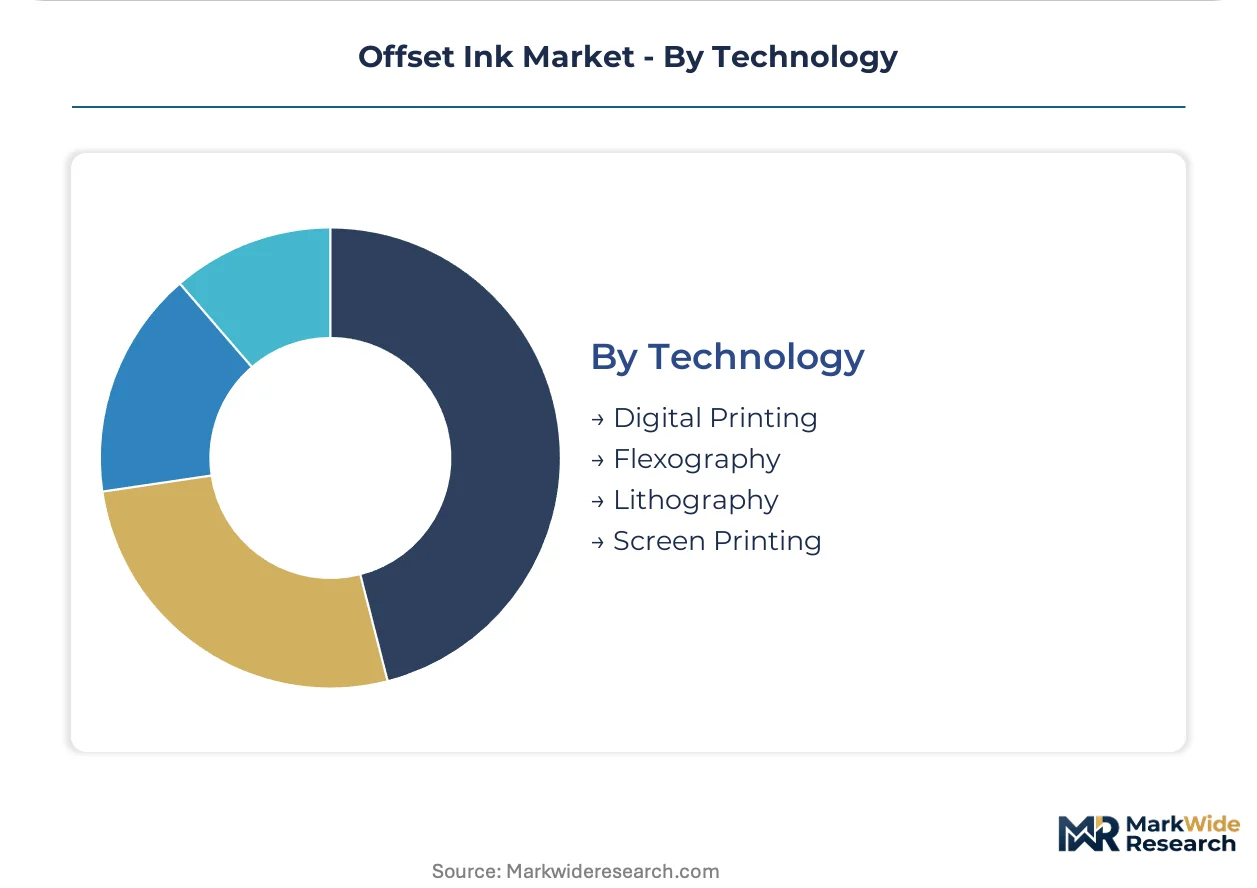
Technology:
Technology segments reveal varying levels of investment and margin potential, from established processes to specialized, high-value printing methods.
- Lithography:This is the dominant offset printing process, relying on the immiscibility of oil and water to transfer ink from a plate to a rubber blanket, then to the substrate. It remains essential for high-quality, long-run production in commercial and packaging sectors.
- Flexography:A versatile relief printing method, flexography often competes with offset in packaging and label applications, particularly for non-porous materials. Its ability to print on diverse substrates and use water-based inks makes it suitable for food packaging.
- Digital Printing:This technology offers short-run capabilities and variable data printing, presenting a significant substitution threat to traditional offset volumes in some commercial niches.
- Screen Printing:A stencil-based process, screen printing is used for thick ink deposits and specialty applications, distinct from the fine detail offered by offset methods.
Lithography forms the bedrock of offset ink consumption, while Digital Printing exerts competitive pressure on traditional offset volumes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging companies and commercial printers globally concentrate demand for offset inks, driven by evolving graphic requirements and regulatory pressures. This concentration reflects the need for advanced formulations that balance print performance with environmental compliance. Key regions demonstrate distinct growth trajectories based on industrial output and regulatory frameworks.
China
China's vast manufacturing and export capabilities generate substantial demand for offset inks in its packaging sector. Compliance with domestic GB standards is critical for market access. The Yangtze River Delta and Pearl River Delta regions are significant hubs for packaging production, driving concentrated ink consumption.
Germany
Germany demonstrates strong demand for high-performance offset inks in specialized industrial printing and premium packaging segments. Adherence to the EU's REACH framework compels manufacturers to develop low-VOC and sustainable formulations. Advanced manufacturing clusters in the Rhine-Ruhr area and Bavaria are crucial for innovation in print technology.
United States
The United States market for offset inks is influenced by its extensive consumer goods industry and e-commerce packaging. US EPA standards on volatile organic compounds directly shape ink formulation, pushing for greener alternatives. Commercial printing and brand packaging operations along the Northeast Corridor and in California drive significant ink consumption.
Japan
Japan's offset ink market emphasizes precision in packaging and high-quality publication printing, alongside stringent food safety. Adherence to JIS standards and METI environmental policies guides product development towards advanced, low-migration inks. The Tokyo-Yokohama region and Kansai area are key centers for printing and packaging industries.
India
India's burgeoning consumer market and expanding packaging sector are driving substantial demand for offset inks. Compliance with BIS standards and evolving environmental regulations is increasingly important for ink suppliers. Manufacturing and packaging clusters in Maharashtra and Gujarat represent significant growth areas for ink consumption.
Offset Ink Market Key Industry Players
Channel-controlling players compete with product-specialist players in the offset ink market, creating a complex competitive environment. The market exhibits a tiered structure, with large multinational corporations operating alongside numerous regional and niche manufacturers. Archetypes include diversified chemical conglomerates, specialized ink manufacturers, and regional suppliers focusing on specific application segments. Competitive moves often involve strategic partnerships to expand geographic reach and portfolio diversification to address evolving environmental regulations.
Among the established global entities, Flint Group represents a diversified approach, offering a broad portfolio across various printing needs. DIC Corporation exemplifies a focus on high-performance pigments, particularly for the demanding packaging segment. Siegwerk Druckfarben AG & Co. KGaA occupies a position centered on sustainable and food-safe ink solutions, aligning with stringent regulatory mandates. These companies navigate the tension between maintaining traditional product lines and investing in advanced, compliant formulations.
| Leading Market Players |
|---|
| Fujifilm Holdings Corporation |
| T&K Toka Co., Ltd. |
| Flint Group |
| Sakata INX Corporation |
| DIC Corporation |
| Huber Group |
| SICPA Holding SA |
| Dainichiseika Color & Chemicals Mfg. Co., Ltd. |
| Siegwerk Druckfarben AG & Co. KGaA |
| Others |
Cost & Logistics Intelligence
Volatility in key raw material inputs, such as pigments and petroleum distillates, directly impacts the cost structure and subsequent margin pools for offset ink manufacturers. This upstream concentration of price risk shifts cost burdens downstream to printers and ultimately to brand owners.
Pricing Analysis
Cost-plus contract patterns, often indexed to raw material prices, remain prevalent in the offset ink market. Price differentiation stems from superior ink performance, such as low-migration properties, and the volume scale of printer contracts. Pricing softness reflects the increasing substitution pressure from digital printing technologies in commercial segments. Publication Printing represents the most price-sensitive segment, while Packaging Companies prioritize performance and compliance over lowest cost.
Supply Chain Analysis
Stringent EU REACH and China GB standards act as de facto regulatory controls, limiting the flow of non-compliant chemical intermediates and finished ink formulations. Geographic supply concentration for key pigments and resins is anchored in China and specialized European chemical producers. The market relies heavily on petroleum distillates and vegetable oils for base vehicles. Commodity price volatility poses a significant structural risk to manufacturer margins. Distribution primarily runs through direct sales channels from ink manufacturers to large printers, supplemented by regional distributors for smaller accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The offset ink market is experiencing a platform-economics inflection, driven by the integration of advanced color management software and inline spectrophotometers into digital pressroom workflows.
For Market Incumbents: Entrench existing market positions by accelerating investment in R&D for bio-based and low-migration UV-curable ink formulations. This addresses both stringent environmental regulations and the threat of digital printing substitution. Consolidate market share through strategic acquisitions of smaller specialty formulators with patented sustainable technologies. Expand capacity in high-growth regions, particularly for compliant packaging inks.
For New Entrants and Emerging Players: Niche applications in functional printing, such as printed electronics or smart packaging, represent a penetrable entry point. Target the rapidly expanding Southeast Asian packaging sector, which exhibits high demand for compliant, high-quality graphics. Offer specialized low-VOC, food-safe ink solutions bundled with strong technical support and rapid regional distribution capabilities. Focus on custom formulations for specific brand owner requirements.
For Investors and Strategic Acquirers: Capital is best deployed toward specialty ink manufacturers with patented low-VOC or bio-based formulations, particularly those demonstrating strong adherence to food contact material regulations. The market offers long-term viability, anchored by essential packaging demand and continuous regulatory evolution over the next decade. A key signal to watch is the increasing investment in advanced curing technologies by commercial printers, indicating readiness for new ink chemistries.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Bio-Based Ink Portfolio | Addresses corporate sustainability goals and appeals to environmentally conscious brand owners. |
| Invest in Low-Migration UV Ink R&D | Ensures compliance with evolving food contact material regulations like the Swiss Ordinance. |
| Expand Production in Southeast Asia | Captures demand from rapidly growing manufacturing and export economies in the region. |
| Acquire Specialty Pigment Manufacturer | Secures supply chain for critical, high-performance inputs and enhances formulation control. |
| Integrate Color Management Software Solutions | Enhances print consistency across global production runs and improves workflow efficiency. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews with industry stakeholders and rigorous secondary validation through published reports. Primary data was gathered from R&D directors, procurement managers at packaging companies, commercial printers, and regulatory affairs specialists. Secondary sources included regulatory body publications from the US EPA and EU REACH, industry association reports, corporate financial filings, and specialized trade journals. Bottom-up and top-down triangulation ensured data accuracy and market sizing integrity.
Forecast inputs considered include technological advancements in ink chemistry, evolving regulatory landscapes, and shifts in consumer packaging trends across the analysis window. The analytical framework modeled segmentation dimensions such as product type, application, end user, technology, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical trends, projected market shifts, and expert consensus. Key industry-specific inputs included the adoption rates of UV-curable inks and the expansion of e-commerce packaging volumes.
Macroeconomic conditions sit as an overlay; deviation in global GDP growth or raw material commodity prices would shift the trajectory. Forecasts reflect underlying assumptions regarding regulatory stability and technological progression. Material shifts in major environmental regulations or significant geopolitical disruptions to raw material supply would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Functional Printing Market
Printing Inks
Commercial Printing Market
Printing Inks
Global Ceramic Inks Market
Printing Inks
Global Chemical Indicator Inks Market
Printing Inks
Molecular Ink Market
Printing Inks
UV Cured Inks Market
Printing Inks
Global Digital Textile Printing Inks Market
Printing Inks
Global Decorative Print Market
Printing Inks
Solder Resist for Inkjet Printer Market
Printing Inks
Returnable Glass Bottle Ink Market
Printing Inks
Ink Resins Market
Printing Inks
Flexo-Ink Market
Printing Inks
Plant Oil Based Printing Inks Market
Printing Inks
Screen Printing Inks Market
Printing Inks
Rotogravure Printing Inks Market
Printing Inks
Food Marking Inks Market