
 Collagen Hydrolysates Market | 2026-2036
Collagen Hydrolysates Market Size, Share, and Industry Trends Forecast 2026-2036
Collagen Hydrolysates Market Analysis
The collagen hydrolysates market is expanding along a widening rift between pharmaceutical-grade isolates and bulk commodity powders. Gelita AG leverages its vertically integrated gelatin-to-peptide pipeline to dominate premium medical nutrition contracts. Rousselot anchors European supply through specialized enzymatic hydrolysis facilities calibrated for low-molecular-weight fractions. Nitta Gelatin, Inc. competes aggressively in Asian cosmetics applications with marine-sourced type I collagen.
Collagen hydrolysates consist of enzymatically cleaved peptide chains derived from denatured collagen, typically exhibiting molecular weights below 10 kDa for enhanced bioavailability and cold-water solubility. Manufacturers deploy controlled proteolysis to preserve specific glycine-proline-hydroxyproline tripeptide motifs that signal fibroblast activity in skin and connective tissue applications. Powder formulations currently occupy the largest volume position, though liquid concentrates capture disproportionate margin pools in functional beverage formulations. Marine-derived hydrolysates represent the fastest-growing source category, propelled by halal-kosher compliance advantages and perceived clean-label positioning among Western consumers.
FDA GRAS self-affirmation pathways, EFSA novel food opinions, and China's SAMR food registration requirements collectively determine market access timelines for new collagen ingredients. These frameworks incentivize investments in batch-level peptide mapping and allergen documentation that smaller commodity processors struggle to maintain. Stakeholders must monitor evolving pharmacopeial monographs for collagen peptides, as compendial-grade specifications will likely bifurcate the supplier base into certified and uncertified tiers.
Market Dynamics
Pharmaceutical-grade peptide specifications are compressing margins for commodity collagen processors while rewarding manufacturers with batch-level peptide mapping capabilities and compendial-grade certifications.
Growth Catalysts
- EFSA Novel Food pathways:Streamlined safety opinions for enzymatically hydrolyzed collagen accelerate European nutraceutical launches, reducing time-to-shelf for functional beverage formulations.
- Marine-sourced type I collagen:Halal-kosher compliance advantages and clean-label positioning among Western consumers expand addressable markets beyond traditional bovine and porcine origins.
- Ready-to-drink beauty beverages:Direct-to-consumer wellness brands command premium shelf positioning in United States retail, driving disproportionate margin capture for liquid concentrate suppliers.
Market Restraints
- Bovine hide supply volatility:Tannery byproduct availability fluctuates with leather demand cycles, creating input cost instability for mammalian collagen processors.
- China SAMR registration timelines:Extended food safety documentation requirements delay market entry for new peptide ingredients, favoring incumbent suppliers with established dossiers.
- Plant-based protein alternatives:Fermented collagen mimics and precision fermentation-derived proteins threaten positioning in cosmetics and select nutraceutical segments.
Strategic Opportunities
- Medical nutrition contracts:Hospital and clinical feeding protocols increasingly specify low-molecular-weight hydrolysates for wound healing and sarcopenia management.
- India FSSAI functional food category:Emerging regulatory clarity around collagen-fortified foods opens underpenetrated markets for preventive wellness positioning.
- Cold-water solubility innovation:Instantized peptide formats enable single-serve sachet distribution through pharmacy and convenience channels.
Industry Challenges
- Peptide mapping expertise shortage:Analytical chemists capable of validating glycine-proline-hydroxyproline tripeptide motifs command premium compensation, constraining quality control scaling.
- Dual certification burden:Simultaneous FDA GRAS self-affirmation and EFSA novel food opinion processes drain regulatory affairs bandwidth at mid-cap processors.
- Legacy powder-to-liquid conversion:Beverage manufacturers struggle with solubility consistency when reformulating from established powder supply agreements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collagen Hydrolysates Market |
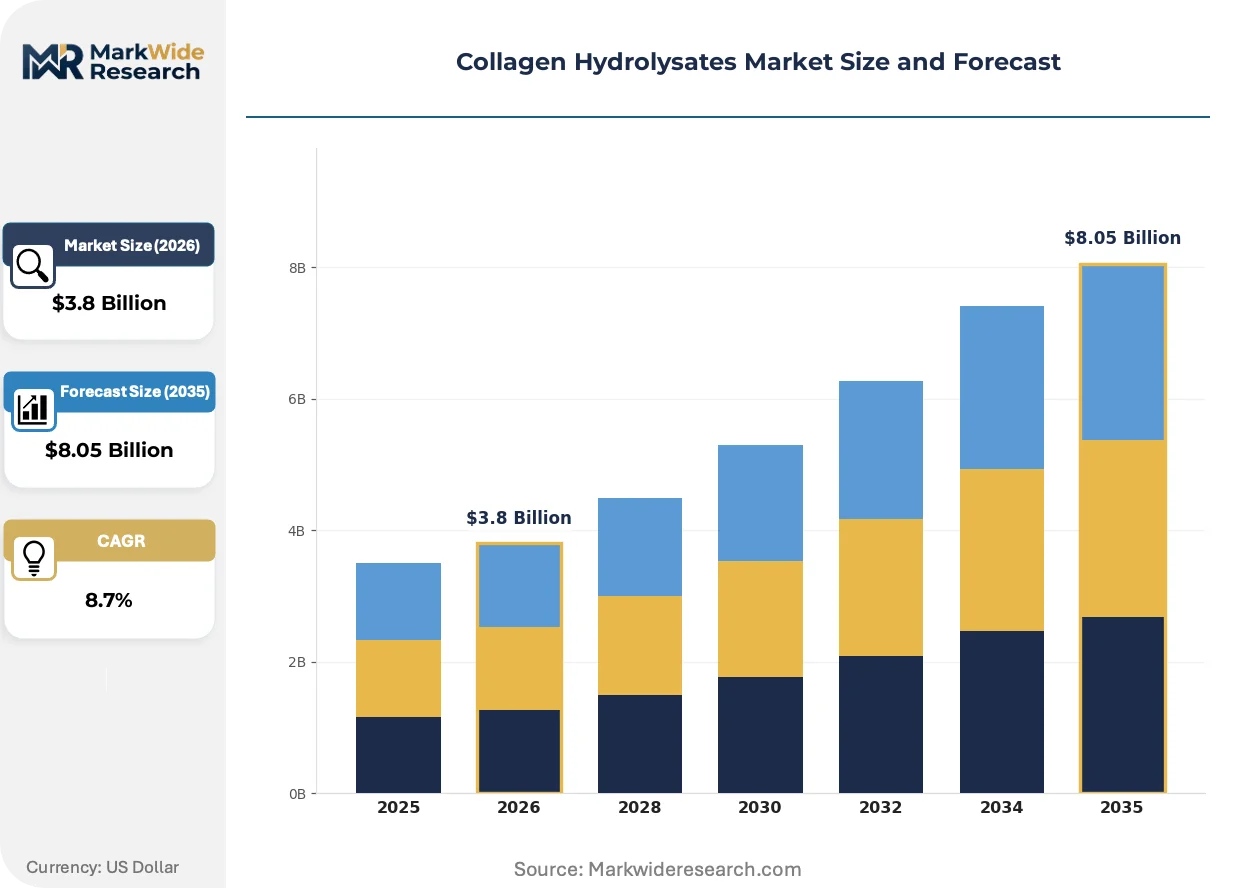
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Gel, Capsules Source: Bovine, Porcine, Marine, Poultry Application: Nutrition Supplements, Cosmetics, Food & Beverages, Pharmaceuticals Form: Hydrolyzed, Non-Hydrolyzed, Instantized, Fortified |
| Companies Covered | Gelita AG, Rousselot, Nitta Gelatin, Inc., Hainan Huayan Collagen Biotech Co., Ltd., NeoCell Corporation, PB Gelatins GmbH, Essen Nutrition, Foodmate Co., Ltd., Connoils LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collagen Hydrolysates Market Emerging Trajectories
Enzymatic specificity and molecular weight targeting are displacing commodity hydrolysis, while regulatory documentation requirements reshape supplier qualification protocols across pharmaceutical and nutraceutical channels.
Precision enzymatic hydrolysis calibrated for specific molecular weight fractions below 5 kDa is overtaking commodity acid-hydrolyzed collagen in dermocosmetic applications. European formulators now specify protease-cleaved peptides for fibroblast signaling efficacy. This specificity is compressing volumes for undifferentiated bulk powder traders.
REACH-aligned substance registration and EFSA novel food opinions now mandate allergen documentation and batch-level traceability for collagen peptides entering European markets. Cosmetic and food-grade suppliers must maintain separate production lines to prevent cross-contamination. Marine-derived ingredients face intensified scrutiny for heavy metal and iodine content thresholds.
Direct-to-consumer subscription models now capture significant share from traditional wholesale distribution in United States wellness markets. Beauty beverage brands bypass retail markup through influencer-driven e-commerce, compressing distributor margins. This channel rotation concentrates procurement power with vertically integrated contract manufacturers capable of flavor masking and stability testing.
Collagen Hydrolysates Market Segmentation
Collagen hydrolysate suppliers configure production lines around molecular weight specifications and solubility profiles that align with distinct end-use requirements. Formulation chemistry and regulatory compliance thresholds fragment procurement strategies across nutraceutical, cosmetic, and pharmaceutical channels.
Product Type:
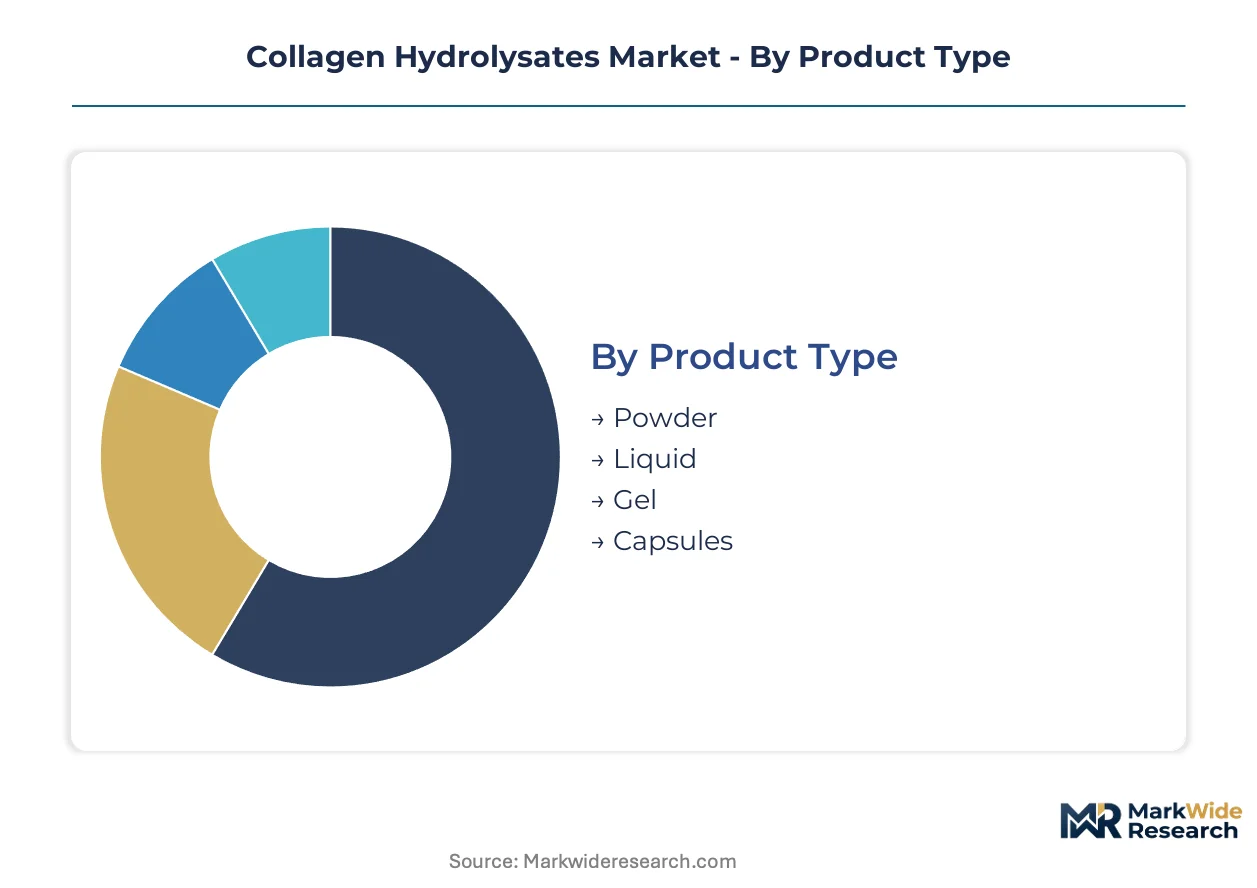
Powder formats dominate volume throughput while liquid concentrates capture disproportionate margin pools in functional beverage applications.
- Powder:Cold-water soluble peptide fractions below 10 kDa molecular weight serve bulk supplement manufacturers and dry-blend nutraceutical formulators. United States direct-to-consumer wellness brands command premium shelf positioning for instantized powder SKUs in pharmacy and convenience channels.
- Liquid:Ready-to-drink beauty beverages require sterile filtration and flavor masking systems that concentrate procurement power with vertically integrated contract manufacturers. EFSA novel food opinions and FDA GRAS self-affirmation pathways determine formulation stability timelines for European and North American launches.
- Gel:Semi-solid matrices support topical dermocosmetic applications and specialized wound care dressings.
- Capsules:Hard-shell and soft-gel encapsulation formats target precision dosing in clinical nutrition protocols.
Today's leader: Powder. Tomorrow's challenger: Liquid.
Source:
Raw material provenance determines halal-kosher compliance eligibility and clean-label positioning in Western consumer markets.
- Bovine:Tannery byproduct supply chains create cost volatility linked to leather demand cycles. Mammalian collagen processors face input instability from hide availability fluctuations.
- Porcine:Restricted addressable markets in Muslim-majority and Jewish dietary law jurisdictions limit geographic expansion.
- Marine:Type I collagen from fish skin and scales delivers halal-kosher compliance advantages and perceived sustainability credentials. Western clean-label positioning drives steepest expansion trajectory among source categories, though heavy metal and iodine content thresholds intensify analytical documentation burdens.
- Poultry:Emerging alternative for processors seeking mammalian-free positioning without marine supply chain complexity.
Marine sourcing gains share fastest where dietary law compliance intersects with sustainability marketing.
Application:
Pharmaceutical-grade specifications compress commodity processor margins while rewarding batch-level peptide mapping capabilities.
- Nutrition Supplements:Functional gummies and sports recovery formulations absorb the largest volume flows. India's FSSAI functional food category clarity opens preventive wellness positioning for fortified peptide products.
- Cosmetics:Dermocosmetic formulators specify protease-cleaved peptides below 5 kDa for fibroblast signaling efficacy. Precision enzymatic hydrolysis displaces commodity acid-hydrolyzed collagen in premium skin care.
- Food & Beverages:Beverage manufacturers struggle with solubility consistency when reformulating from established powder supply agreements.
- Pharmaceuticals:Hospital and clinical feeding protocols increasingly specify low-molecular-weight hydrolysates for wound healing and sarcopenia management. Compendial-grade certifications bifurcate supplier tiers.
Medical nutrition contracts concentrate where clinical evidence requirements filter out uncertified suppliers.
Form:
Degree of processing determines bioavailability claims and regulatory classification across food, cosmetic, and drug channels.
- Hydrolyzed:Standard enzymatic cleavage produces peptide chains with enhanced gastrointestinal absorption versus native collagen.
- Non-Hydrolyzed:Native triple-helix structures persist, limiting solubility and restricting applications to heat-processed food matrices.
- Instantized:Agglomeration and surface treatment enable single-serve sachet distribution through pharmacy and convenience channels. Cold-water solubility innovation opens underpenetrated markets for on-the-go consumption formats.
- Fortified:Vitamin C, hyaluronic acid, and mineral co-formulations support connective tissue synthesis claims in joint health positioning.
Instantized formats expand addressable channels where convenience consumption intersects with clinical compliance documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized enzymatic hydrolysis chemists and peptide mapping analysts concentrate in Germany, the United States, and Japan, anchoring the technical workforce that separates premium-grade suppliers from commodity processors.
United States
Direct-to-consumer wellness brands command premium shelf positioning for functional beverages and instantized powders. FDA GRAS self-affirmation pathways determine formulation stability timelines for new peptide launches. Greater Los Angeles and Austin clusters host vertically integrated contract manufacturers capable of flavor masking and sterile filtration systems.
Germany
Medical nutrition contracts increasingly specify low-molecular-weight hydrolysates for clinical feeding protocols. REACH-aligned substance registration and EFSA novel food opinions mandate batch-level allergen documentation for European market access. The Eberbach enzymatic hydrolysis corridor anchors specialized facilities calibrated for pharmaceutical-grade peptide fractions.
China
Cosmetics manufacturers absorb growing volumes of marine-sourced type I collagen for dermocosmetic applications. SAMR food registration requirements delay market entry for new peptide ingredients, favoring incumbent suppliers with established dossiers. The Yangtze River Delta concentrates marine collagen processing capacity serving both domestic beauty brands and export markets.
Japan
Aging demographics drive hospital and clinical demand for sarcopenia management formulations. PMDA pharmaceutical-grade specifications and METI industrial standards bifurcate supplier tiers into certified and uncertified categories. The Kansai region maintains legacy gelatin-to-peptide conversion facilities with deep expertise in controlled proteolysis.
India
Preventive wellness positioning opens underpenetrated markets for fortified peptide products in sports recovery and joint health. FSSAI functional food category clarity accelerates regulatory approvals for collagen-fortified formulations. Maharashtra and Gujarat clusters emerge as contract manufacturing hubs for instantized powder exports to Southeast Asian markets.
Collagen Hydrolysates Market Vendor Landscape
Top-tier vendors anchor pharmaceutical-grade medical nutrition contracts, while mid-cap commodity processors struggle to maintain batch-level peptide mapping capabilities. The supplier base compresses into three tiers: vertically integrated gelatin-to-peptide specialists, regional enzymatic hydrolysis facilities, and undifferentiated bulk powder traders. Dominant competitive moves include backward integration into tannery byproduct supply chains and strategic partnerships with direct-to-consumer wellness brands for co-development of ready-to-drink formats.
Within the premium-tier vector, Gelita AG and Rousselot occupy positions exemplifying European pharmaceutical-grade specialization, while Nitta Gelatin, Inc. anchors marine-sourced type I collagen expertise for Asian cosmetics applications. These three represent the archetypal segmentation between medical nutrition certification, dermocosmetic enzymatic precision, and halal-kosher compliance positioning that defines procurement strategies across nutraceutical and cosmetic channels.
| Leading Market Players |
|---|
| Gelita AG |
| Rousselot |
| Nitta Gelatin, Inc. |
| Hainan Huayan Collagen Biotech Co., Ltd. |
| NeoCell Corporation |
| PB Gelatins GmbH |
| Essen Nutrition |
| Foodmate Co., Ltd. |
| Connoils LLC |
| Others |
Supply Flow & Price Mechanics
Tannery byproduct availability traces a volatile path from leather demand cycles through bovine hide processors into mammalian collagen pricing tiers, compressing margins for undifferentiated bulk powder traders while pharmaceutical-grade peptide fractions command stability premiums.
Pricing Analysis
Bundled peptide mapping and certification services separate premium contract manufacturers from unbundled commodity powder suppliers. Pricing stratifies across pharmaceutical-grade, food-grade, and feed-grade tiers, with batch-level glycine-proline-hydroxyproline validation driving the premium spread. Cost compression in standard-grade powders intensifies because tannery input volatility passes through to spot-market traders. Direct-to-consumer wellness brands exhibit lowest price sensitivity, while bulk supplement manufacturers absorb highest procurement pressure.
Supply Chain Analysis
Dual-sourcing requirements from EFSA-registered buyers mandate simultaneous qualification of German enzymatic hydrolysis facilities and Chinese marine processing plants. Supply concentration centers on Germany, China, and Japan for specialized peptide production. Raw material flows draw from tannery byproducts, fish skin and scale harvests, and poultry processing residuals. Single-source vulnerability persists in low-molecular-weight fraction capacity. Distribution runs through vertically integrated contract manufacturers capable of sterile filtration and flavor masking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Hospital and clinical feeding protocols increasingly specify low-molecular-weight hydrolysates for wound healing applications, filtering procurement toward certified suppliers.
For Market Incumbents: To counter plant-based protein alternatives threatening cosmetics positioning, deepen backward integration into tannery byproduct supply chains and accelerate FDA GRAS self-affirmation investments for novel marine peptide fractions. Channel control through direct-to-consumer wellness brand partnerships secures premium shelf positioning.
For New Entrants and Emerging Players: Enter via India's FSSAI functional food category clarity, where preventive wellness positioning remains underpenetrated for fortified peptide products. Marine-sourced type I collagen for halal-kosher cosmetics applications offers the most penetrable white space. A co-development go-to-market angle with regional contract manufacturers bypasses established distributor networks.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-cap processors lack batch-level peptide mapping capabilities and dual FDA-EFSA certification bandwidth. Long-term viability favors vertically integrated gelatin-to-peptide specialists with captive tannery supply and established clinical nutrition contracts. Watch EFSA novel food opinion timelines as an inflection indicator for European market access acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tannery Supply | Captive bovine hide flows insulate Gelita AG from leather demand cycle volatility. |
| EFSA Novel Food Opinion Acceleration | Streamlined safety documentation compresses time-to-shelf for Rousselot's functional beverage launches. |
| Marine Sourcing Certification Investment | Heavy metal and iodine testing protocols enable Nitta Gelatin's halal-kosher clean-label positioning. |
| Direct-to-Consumer Channel Partnership | Beauty beverage co-development concentrates procurement power with sterile filtration-capable manufacturers. |
| Instantized Format R&D Expansion | Cold-water solubility innovation opens pharmacy and convenience distribution for single-serve sachets. |
Methodological Framework
Bottom-up nutraceutical and pharmaceutical demand modeling reconciled against top-down enzymatic hydrolysis capacity tracking forms the analytical core. Primary interviews with peptide mapping analysts, regulatory affairs directors at collagen processors, hospital procurement managers, and direct-to-consumer brand supply chain heads combined with secondary validation from FDA GRAS notifications, EFSA novel food opinions, SAMR registration databases, and customs trade records. Triangulation across stakeholder inputs and documentary sources anchors volume and value estimates.
Input-output matrices model peptide throughput from tannery and marine raw material flows through powder, liquid, and instantized format outputs across the projection horizon. Segmentation dimensions include molecular weight tier, source origin, application channel, and regional regulatory cluster. CAGRs derive from fitted growth curves against documented capacity expansions and end-use absorption rates. Forecast inputs incorporate EFSA opinion velocity, SAMR registration backlog clearance, and clinical protocol adoption timelines for sarcopenia management.
Inputs from FDA GRAS notifications and EFSA novel food opinions were available through the study window; gaps in real-time SAMR processing timelines introduce uncertainty bands around China market entry assumptions. Forecasts reflect documented regulatory pathways and disclosed capacity investments. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Compounds
Eggshell Membrane Derivatives Market
Specialty Compounds
Global Compound Management Market
Specialty Compounds
Middle East and Africa Color Masterbatch Market
Specialty Compounds
Silicone Masterbatches Market
Specialty Compounds
Compounds Market
Specialty Compounds
Global Hydrolyzed Collagen Market
Specialty Compounds
Hypalon Market
Specialty Compounds
Liquid Ammonium and Liquid Potassium Thiosulfate Market
Specialty Compounds
Resin Capsule Market
Specialty Compounds
Germany Collagen Market
Specialty Compounds
Global Engineering Plastic Compounds Market
Specialty Compounds
Air-Laid Product Market
Specialty Compounds
Compounding Systems Market
Specialty Compounds
Global Zinc Phosphate Market
Specialty Compounds
Fluoropolymer Masterbatch Market
Specialty Compounds
Middle East and Africa Polypropylene Compounds Market