
 Global Polycarbonate Market | 2026-2036
Global Polycarbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polycarbonate Market Outlook
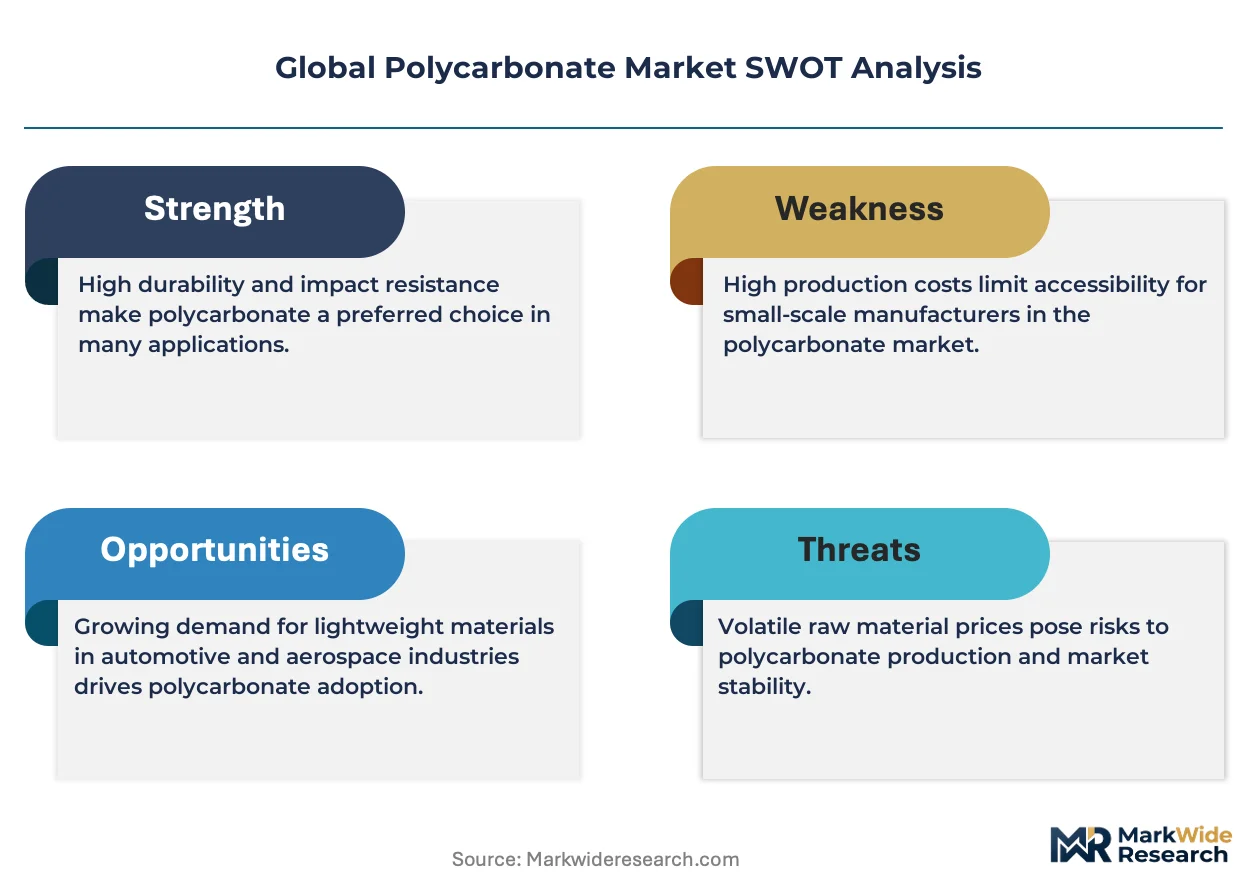
Modularization of polycarbonate product bundles is expanding buyer flexibility across resin, sheet, and film configurations. Covestro leverages its integrated precursor-to-polymer chain to sustain cost advantages in optical-grade materials. SABIC anchors its position through captive bisphenol A supply and large-scale Middle Eastern feedstock access. Mitsubishi Chemical Group differentiates via high-performance flame-retardant compounds for electric vehicle architectures.
Polycarbonate is a thermoplastic polymer synthesized from bisphenol A and phosgene or via melt transesterification, characterized by high impact resistance, optical clarity, and a glass transition temperature near 147°C, serving industries requiring lightweight transparent or structural components. Resin formulations dominate volume flows into injection molding and extrusion, while sheet products capture premium margin pools in architectural glazing and aircraft interiors. Medical-grade compounds represent the fastest-growing application segment as sterilization-resistant device housings gain regulatory traction.
REACH in Europe, EPA guidelines in the United States, and China's GB standards collectively restrict bisphenol A migration limits and mandate recycling content disclosures, reshaping formulation chemistry and import compliance burdens. ECHA's ongoing substance evaluations are pressuring producers to validate alternative feedstocks or absorb registration costs. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and misaligned capacity investments.
Market Dynamics
EU REACH chemical safety standards and China's dual carbon goals are forcing polycarbonate producers to reengineer feedstock sourcing and validate alternative bisphenol A supply chains before registration deadlines strand existing formulations.
Growth Catalysts
- Automotive lightweighting mandates:Electric vehicle battery housings are absorbing engineering-grade polycarbonate volumes as OEMs pursue mass reduction targets. NHTSA crashworthiness requirements favor high-impact thermoplastics over metal alternatives.
- REACH compliance deadlines:ECHA substance evaluations are accelerating producer investment in non-phosgene melt transesterification routes. Registration cost absorption is filtering out smaller compounders.
- Medical device sterilization protocols:Gamma and steam-resistant polycarbonate grades are capturing regulatory approvals for surgical instrument housings. FDA 510(k) pathway familiarity is concentrating supply among established medical resin specialists.
Market Restraints
- Bisphenol A feedstock concentration:Three integrated petrochemical corridors in China, Germany, and the United States control precursor supply. Disruption at any node propagates through optical-grade and flame-retardant compound pricing.
- Polymethyl methacrylate substitution:PMMA is capturing cost-sensitive signage and lighting applications where impact resistance requirements moderate. Acrylic sheet extruders are extending UV stabilization warranties to match polycarbonate performance claims.
- EPA emissions enforcement:Phosgene-based production routes face intensifying air quality scrutiny at Texas and Louisiana manufacturing sites. Permit renewal timelines are extending capital project horizons.
Strategic Opportunities
- India automotive corridor expansion:Tamil Nadu and Maharashtra state industrial policies are incentivizing polycarbonate glazing for domestic electric two-wheeler production. BIS certification harmonization with UN ECE regulations is reducing import qualification friction.
- Building-integrated photovoltaics:Transparent backsheet films combining polycarbonate weatherability with photovoltaic cell encapsulation are emerging in German and Japanese architectural demonstration projects. IEC 61215 certification protocols are adapting to accommodate polymer thermal expansion coefficients.
- Chemical recycling infrastructure:Pyrolysis-based bisphenol A recovery from post-consumer electronics housings is attracting project finance in Netherlands and South Korea. EU Green Deal circular economy mandates are creating offtake certainty for recycled content certificates.
Industry Challenges
- Optical-grade metrology talent scarcity:Haze and birefringence specification testing requires specialized interferometry expertise concentrated in German and Japanese laboratory networks. Training programs at technical universities are not matching compounder hiring velocity.
- Multi-jurisdiction registration synchronization:REACH dossier updates, EPA TSCA section 8(e) notifications, and China's MEE new chemical substance registrations operate on divergent timelines. Product launch coordination across regulatory zones demands dedicated compliance architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polycarbonate Market |
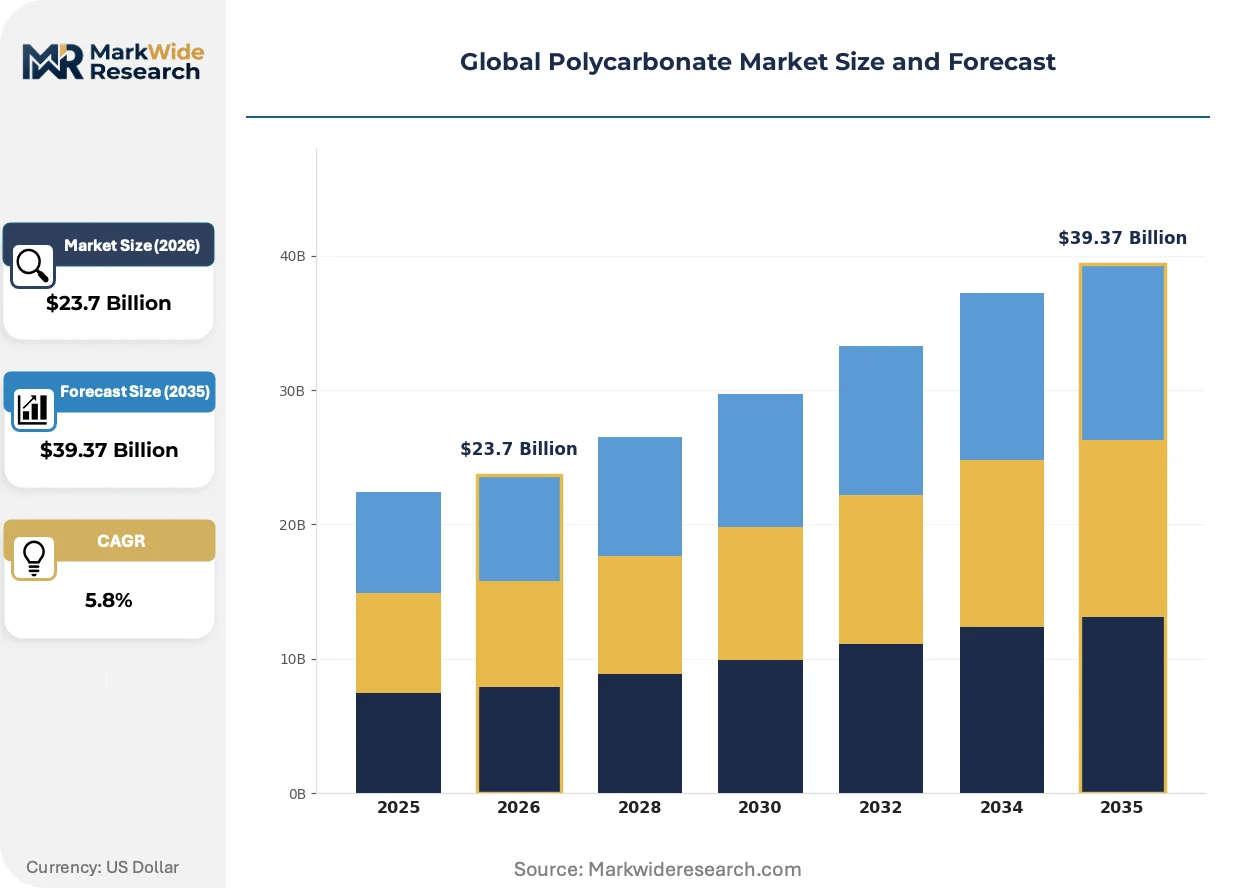
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $39.37 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet, Film, Resin, Compounds Application: Automotive, Electronics, Construction, Medical End User: OEMs, Retailers, Manufacturers, Distributors Distribution Channel: Online, Direct Sales, Retail, Wholesalers |
| Companies Covered | Mitsubishi Chemical Group, Chi Mei Corporation, Covestro, Asahi Kasei, Lotte Chemical, SABIC, LG Chem, Formosa Chemicals & Fibre Corporation, Teijin Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polycarbonate Market Strategic Shifts
Non-phosgene melt transesterification processes are reshaping capital deployment patterns as producers anticipate feedstock regulation tightening across multiple jurisdictions simultaneously.
Coextruded multi-layer polycarbonate sheets with embedded infrared-reflective interlayers are overtaking monolithic glazing in Middle Eastern and Australian commercial construction specifications. Façade engineering consultancies in Dubai and Sydney are specifying these assemblies for solar heat gain coefficient compliance. The technology is compressing specification cycles for standard polycarbonate monolithic products in premium architectural segments.
China's GB standards for bisphenol A migration limits in food-contact applications are tightening ahead of anticipated EU REACH alignment. Domestic resin producers are accelerating copolyester-polycarbonate blend development to maintain kitchen appliance market access. The policy divergence is fragmenting formulation portfolios between export-oriented and domestically focused Chinese compounders.
Automotive Tier 1 suppliers are consolidating polycarbonate procurement under long-term resin-plus-compounding contracts with specified recycled content tiers. Direct mill relationships are displacing distributor-mediated spot purchasing for headlamp lens and interior trim programs. The concentration is most visible in Germany's Baden-Württemberg automotive supplier cluster where BMW and Mercedes-Benz electrification timelines are compressing supplier qualification windows.
Global Polycarbonate Market Segmentation
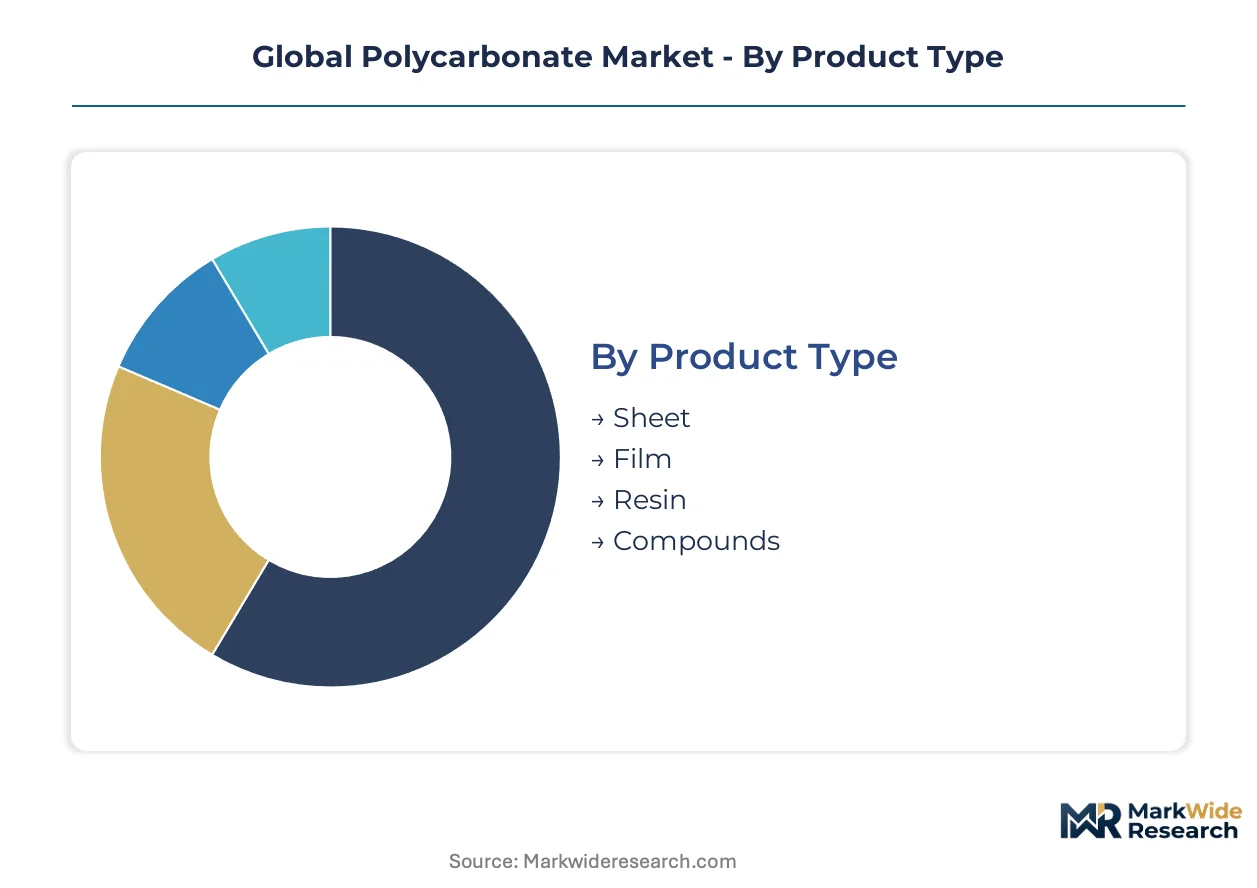
Polycarbonate market segmentation reveals divergent margin architectures across product configurations and end-use applications. Each category reflects distinct specification requirements, regulatory compliance burdens, and customer procurement behaviors that reshape competitive positioning.
Product Type:
Resin formulations dominate volume flows while sheet products command premium pricing pools in specialized applications.
- Resin:Injection-molding and extrusion-grade pellets constitute the foundational feedstock for automotive and electronics manufacturing. Demand concentrates in Germany's Baden-Württemberg automotive corridor and China's Yangtze River Delta electronics manufacturing belt, driven by electric vehicle battery housing programs and consumer device enclosure specifications.
- Sheet:Extruded monolithic and multi-layer panels serve architectural glazing, aircraft interiors, and industrial safety barriers. German and Australian façade engineering consultancies are specifying infrared-reflective interlayer configurations for solar heat gain coefficient compliance in Middle Eastern commercial construction.
- Film:Thin-gauge optical and packaging films leverage polycarbonate clarity for display substrates and sterilizable medical pouches.
- Compounds:Flame-retardant and glass-filled formulations target electric vehicle architectures requiring UL94 V-0 ratings and dimensional stability under thermal cycling.
Today's leader: Resin. Tomorrow's challenger: Sheet.
Application:
Automotive electrification timelines and medical device sterilization protocols are redistributing demand across end-use verticals.
- Automotive:Battery housings, headlamp lenses, and interior trim components absorb engineering-grade volumes as OEMs pursue mass reduction targets. NHTSA crashworthiness requirements favor high-impact thermoplastics over metal alternatives in electric vehicle platforms.
- Medical:Gamma and steam-resistant grades are capturing regulatory approvals for surgical instrument housings and drug delivery devices. FDA 510(k) pathway familiarity concentrates supply among established medical resin specialists with validated sterilization protocols.
- Electronics:Smartphone enclosures, laptop housings, and connector components demand thin-wall moldability and EMI shielding compatibility.
- Construction:Greenhouse glazing, skylight systems, and noise barrier applications exploit polycarbonate weatherability and impact resistance versus glass.
Automotive commands current volume leadership. Medical represents the steepest expansion trajectory.
End User:
Procurement centralization among large-scale manufacturers is displacing fragmented distributor-mediated purchasing.
- OEMs:Automotive and electronics original equipment manufacturers negotiate long-term resin-plus-compounding contracts with specified recycled content tiers. Direct mill relationships compress supplier qualification windows for electrification programs.
- Manufacturers:Tier 2 component producers and independent molders source spot volumes through regional distribution networks.
- Distributors:Specialized polymer distributors maintain inventory positions for quick-turn prototyping and small-batch production runs.
- Retailers:DIY and professional construction channels stock sheet products for replacement glazing and fabrication applications.
OEM direct procurement dominates strategic volume. Distributor channels retain fragmentation value.
Distribution Channel:
Channel selection correlates with order scale, specification complexity, and technical service requirements.
- Direct Sales:Large-volume automotive and electronics programs require dedicated technical support, custom color matching, and just-in-time delivery scheduling. Covestro and SABIC field sales organizations manage these relationships directly.
- Wholesalers:Regional polymer distributors aggregate demand from mid-tier processors and compounders, offering credit terms and inventory financing.
- Online:E-commerce platforms capture small-lot prototyping and replacement part demand, though technical consultation remains limited.
- Retail:Big-box and specialty construction retailers stock standard sheet dimensions for consumer and light commercial applications.
Direct sales anchors premium program capture. Digital channels are gaining share fastest in fragmented demand pools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polycarbonate production scaled first in Germany and the United States during the 1960s, with Asian capacity surging from the 1990s onward as electronics manufacturing concentrated in East Asia. Today's demand geography reflects this inherited industrial base overlaid with electric vehicle supply chain reconfiguration.
China
Yangtze River Delta electronics manufacturers absorb resin volumes for smartphone enclosures and laptop housings. GB standards for bisphenol A migration limits in food-contact applications are tightening formulation requirements ahead of anticipated EU REACH alignment. Zhejiang and Jiangsu provinces host expanding compounding capacity serving domestic appliance and automotive Tier 1 suppliers.
Germany
Baden-Württemberg automotive suppliers procure engineering-grade polycarbonate for BMW and Mercedes-Benz electrification programs. ECHA substance evaluations under REACH are accelerating investment in non-phosgene melt transesterification routes. Bavaria's chemical corridor maintains optical-grade metrology expertise concentrated in specialized interferometry laboratories.
United States
EPA emissions enforcement at Texas and Louisiana manufacturing sites is extending permit renewal timelines for phosgene-based production routes. NHTSA crashworthiness requirements favor high-impact thermoplastics over metal alternatives in electric vehicle battery housings. Detroit-area automotive OEMs negotiate long-term resin-plus-compounding contracts with specified recycled content tiers.
Japan
METI industrial policy supports flame-retardant compound development for electric vehicle architectures requiring UL94 V-0 ratings. Chubu region chemical producers supply medical-grade sterilization-resistant formulations for surgical instrument housings. Kansai-based engineering consultancies specify infrared-reflective interlayer configurations for Middle Eastern commercial construction exports.
India
Tamil Nadu and Maharashtra state industrial policies incentivize polycarbonate glazing for domestic electric two-wheeler production. BIS certification harmonization with UN ECE regulations is reducing import qualification friction for automotive applications. Gujarat chemical corridors are attracting project finance for pyrolysis-based bisphenol A recovery infrastructure.
Global Polycarbonate Market Competitive Environment
Premium-margin players sit above commodity-margin players across optical clarity and flame-retardant certification tiers. The vendor base stratifies into three archetypes: integrated petrochemical majors with captive bisphenol A supply, specialized compounders with medical-grade sterilization protocols, and regional sheet extruders serving architectural glazing. Consolidation pressure is accelerating as registration cost absorption under REACH and EPA guidelines filters out smaller compounders. Dominant competitive moves include backward integration into precursor supply and long-term OEM contracting with recycled content specifications.
Within the integrated petrochemical tier, Covestro and SABIC exemplify scale-driven positioning through European and Middle Eastern manufacturing footprints respectively. Mitsubishi Chemical Group occupies a specialist position in high-performance flame-retardant formulations. These three entities represent contrasting geographic and capability anchors: German integrated chain control, Saudi feedstock access, and Japanese compound engineering expertise.
| Leading Market Players |
|---|
| Mitsubishi Chemical Group |
| Chi Mei Corporation |
| Covestro |
| Asahi Kasei |
| Lotte Chemical |
| SABIC |
| LG Chem |
| Formosa Chemicals & Fibre Corporation |
| Teijin Limited |
| Others |
Value Chain & Pricing Dynamics
Non-phosgene melt transesterification adoption is compressing capital costs for new entrants while fragmenting pricing power among established phosgene-route producers in Texas and Louisiana. This technology shift simultaneously enables Chinese compounders to bypass import-dependent precursor supply and forces German optical-grade specialists to defend premium positioning through metrology differentiation.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates polycarbonate commerce, with optical-grade certification and flame-retardant UL94 V-0 ratings driving tier separation. Price differentiation hinges on haze specification compliance and captive bisphenol A integration, with automotive OEM direct contracts commanding stability while distributor-mediated spot resin faces compression from PMMA substitution in signage. Cost compression in standard extrusion grades is intensifying because of Chinese capacity additions and REACH registration cost absorption. Tier 2 molders exhibit highest price sensitivity; medical resin specialists with FDA 510(k) validation show least.
Supply Chain Analysis
Dual-sourcing mandates from BMW and Mercedes-Benz electrification programs are forcing Baden-Württemberg Tier 1 suppliers to qualify secondary polycarbonate streams beyond Covestro's integrated German chain. Geographic supply concentration centers on China, Germany, and the United States, with bisphenol A feedstock, phosgene or diphenyl carbonate intermediates, and optical-grade metrology equipment anchoring upstream dependencies. Single-source vulnerability runs through Middle Eastern bisphenol A corridors controlled by SABIC. Distribution runs through direct mill relationships for automotive programs and regional polymer distributors for construction sheet.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polycarbonate market represents a late-cycle quality story as electric vehicle battery housings and medical sterilization protocols concentrate demand among specification-intensive buyers. Premium-grade flame-retardant and optical clarity tiers capture expanding margin pools while commodity resin faces substitution pressure.
For Market Incumbents: Anchor position through backward integration into bisphenol A recovery infrastructure and captive compounding capacity in Zhejiang or Bavaria. PMMA substitution in cost-sensitive lighting applications threatens standard-grade pricing; defend through UL94 V-0 certification investment and long-term OEM contracting with specified recycled content tiers. Prioritize optical-grade metrology talent acquisition in German laboratory networks. For New Entrants and Emerging Players: Mid-tier Indian automotive compounders represent the most penetrable buyer archetype as Tamil Nadu electric two-wheeler production scales and BIS certification harmonization reduces import friction. Target medical device sterilization protocols where FDA 510(k) pathway familiarity concentrates supply among few established specialists. Pursue pyrolysis-based chemical recycling joint ventures with Netherlands or South Korean project finance to secure EU Green Deal offtake certainty. For Investors and Strategic Acquirers: Valuations sit cheapest among regional sheet extruders lacking flame-retardant compound engineering capabilities. Long-term viability favors assets with REACH-registered non-phosgene routes and automotive OEM direct relationships. The signal to watch is ECHA substance evaluation timelines that could strand phosgene-based capacity and trigger forced seller dynamics among non-compliant compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bisphenol A Recovery | Pyrolysis infrastructure in Netherlands and South Korea secures EU Green Deal circular economy offtake. |
| Non-Phosgene Melt Transesterification Capacity | ECHA REACH evaluations favor producers with validated alternative feedstock routes. |
| Medical-Grade Sterilization Protocol Investment | FDA 510(k) pathway familiarity concentrates supply among established resin specialists. |
| Long-Term OEM Direct Contracting | BMW and Mercedes-Benz electrification timelines compress supplier qualification windows. |
| Optical-Grade Metrology Laboratory Expansion | Haze and birefringence specification testing expertise concentrates in German and Japanese networks. |
Study Parameters
Multiple input streams — plant manager interviews at compounding facilities, procurement lead discussions at automotive Tier 1 suppliers, technical R&D director consultations, and distribution channel partner assessments — were reconciled against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA REACH registration databases. Bottom-up resin volume modeling and top-down end-use demand aggregation were cross-validated through triangulation.
Historical production capacity trajectories were cross-referenced against expert panel assessments of electric vehicle battery housing adoption and medical device sterilization protocol expansion. Segmentation dimensions modeled include product configuration, end-use industry vertical, regional production hub, and certification tier. CAGRs were derived through regression analysis of correlated industrial output indicators. Key forecast inputs encompassed NHTSA crashworthiness requirement evolution and EU Green Deal circular economy mandate implementation.
Underlying measurement precision varies by segment; medical-grade and optical-grade categories carry tighter precision than commodity resin due to regulatory filing transparency. Forecasts reflect documented assumptions regarding REACH registration timeline adherence and phosgene-route permit renewal success. Deviation in ECHA substance evaluation outcomes or EPA emissions enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
PP Homopolymer Market
Polymers & Resins
Global Resin Market
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
MDI, TDI, and Polyurethane Market
Polymers & Resins
Chelating Resins Market
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
Polymer Microspheres Market
Polymers & Resins
Global Polybutene Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
Water-Borne Resins Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
Saturated Polyester Resin Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
CO2-Based Polycarbonate Polyols for Flexible PU Foam Market
Polymers & Resins
Germany Engineering Plastics Market