
 Virgin Resin Market | 2026-2036
Virgin Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Virgin Resin Market Analysis
Middle Eastern petrochemical producers are pivoting toward higher-margin specialty grades as feedstock advantages narrow. Dow leverages integrated Gulf Coast cracking complexes to sustain cost leadership in polyethylene. LyondellBasell anchors European supply through its Rotterdam hub, while SABIC competes aggressively in Asian markets with differentiated polypropylene portfolios.
Virgin resin denotes polymer synthesized directly from monomer feedstock rather than recycled material, typically achieving melt flow indices between 0.3 and 50 g/10 min and virgin-grade purity exceeding 99.5 percent for medical and food-contact applications. Polyethylene leads volume globally due to its dominance in flexible packaging films, though polycarbonate commands premium pricing in automotive glazing and electronics housings where optical clarity and impact resistance justify higher resin costs. Specialty-grade formulations capture disproportionate margin pools as electronics miniaturization intensifies demand for engineered thermal properties.
The EPA regulates resin manufacturing emissions under Clean Air Act Title V permitting, while REACH restricts phthalate plasticizers and persistent organic pollutants in European polymer imports. FDA food-contact notifications govern virgin resin approval for US packaging applications, creating compliance bottlenecks for new suppliers. Stakeholders must monitor feedstock volatility and regulatory divergence between jurisdictions when committing to long-term capacity investments.
Market Dynamics
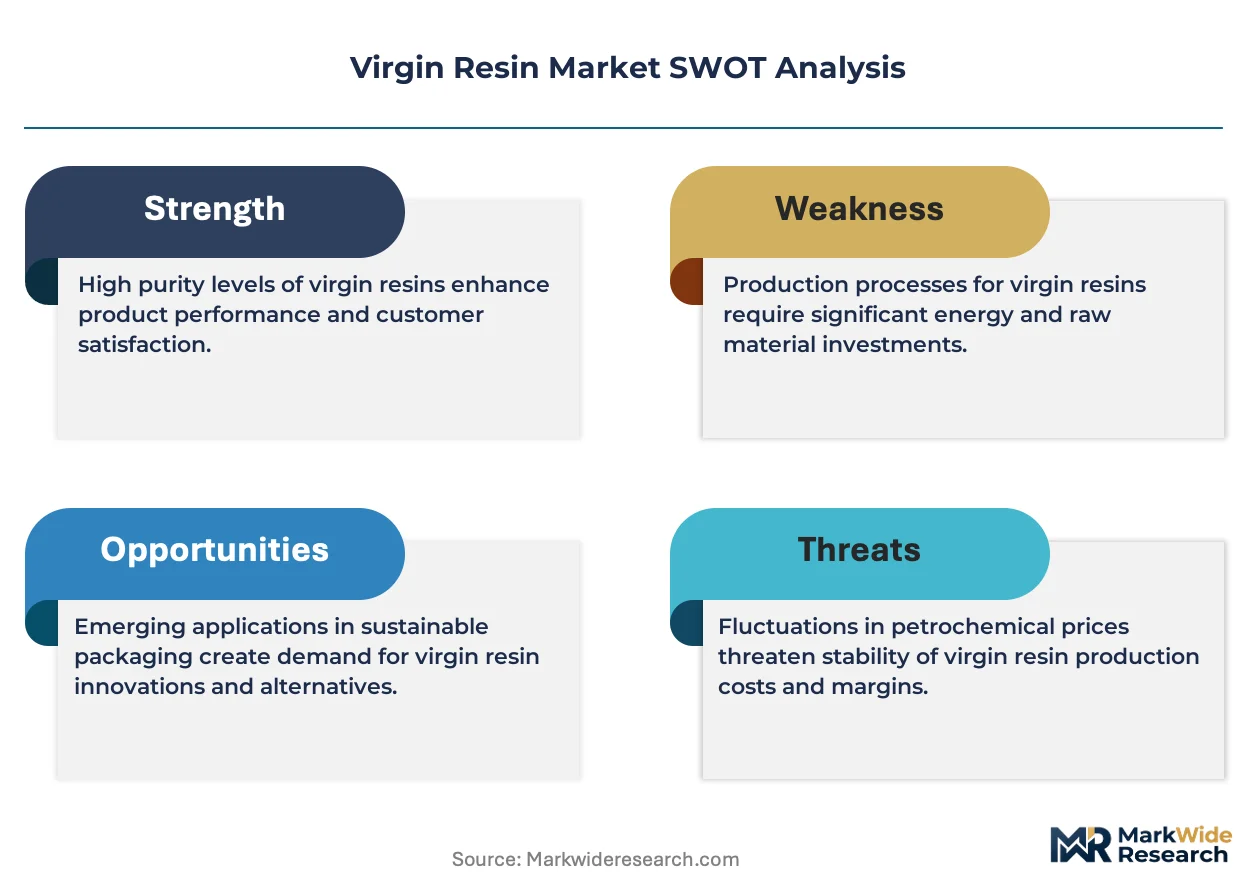
The EU Green Deal's tightening REACH amendments are compressing import windows for virgin polymer grades while simultaneously accelerating investment in high-purity compounding capacity across Asia-Pacific packaging hubs.
Growth Catalysts
- Food-contact compliance mandates:FDA notification requirements for virgin resin purity above 99.5 percent are locking in supplier relationships with certified converters in US flexible packaging.
- Electronics miniaturization:Thermal management specifications for polycarbonate housings are pulling specialty-grade formulations into 5G infrastructure and automotive sensor clusters.
- India:Reliance Industries and SABIC have expanded local compounding facilities to serve domestic packaging converters scaling purchases of high-performance polyethylene grades.
Market Restraints
- Naphtha feedstock volatility:Middle Eastern producers face narrowing ethane cost advantages as regional gas pricing benchmarks converge with global LNG indices.
- Supply concentration:Gulf Coast cracking complexes controlled by integrated majors create bottlenecks for independent compounders seeking spot polyethylene volumes.
- Mechanical recycling substitution:Post-consumer recycled PET flake is displacing virgin polyester in non-food bottle applications where optical clarity requirements have relaxed.
Strategic Opportunities
- Medical-grade polycarbonate:Sterile device manufacturers in Germany and Switzerland are qualifying new resin sources as legacy suppliers face EMA inspection backlogs.
- Biopolymer hybrid formulations:PLA-PE blends are opening shelf-stable packaging segments previously closed to pure bioplastics due to moisture barrier limitations.
- Direct-to-converter digital platforms:Resin distributors are bypassing traditional broker networks to offer real-time pricing and lot traceability to mid-tier film extruders.
Industry Challenges
- Clean Air Act Title V permitting:EPA emission controls on cracking furnaces are extending construction timelines for new ethylene capacity by 18-24 months.
- Melt flow index certification:Medical device OEMs require batch-level testing documentation that smaller compounders struggle to generate without laboratory infrastructure investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virgin Resin Market |
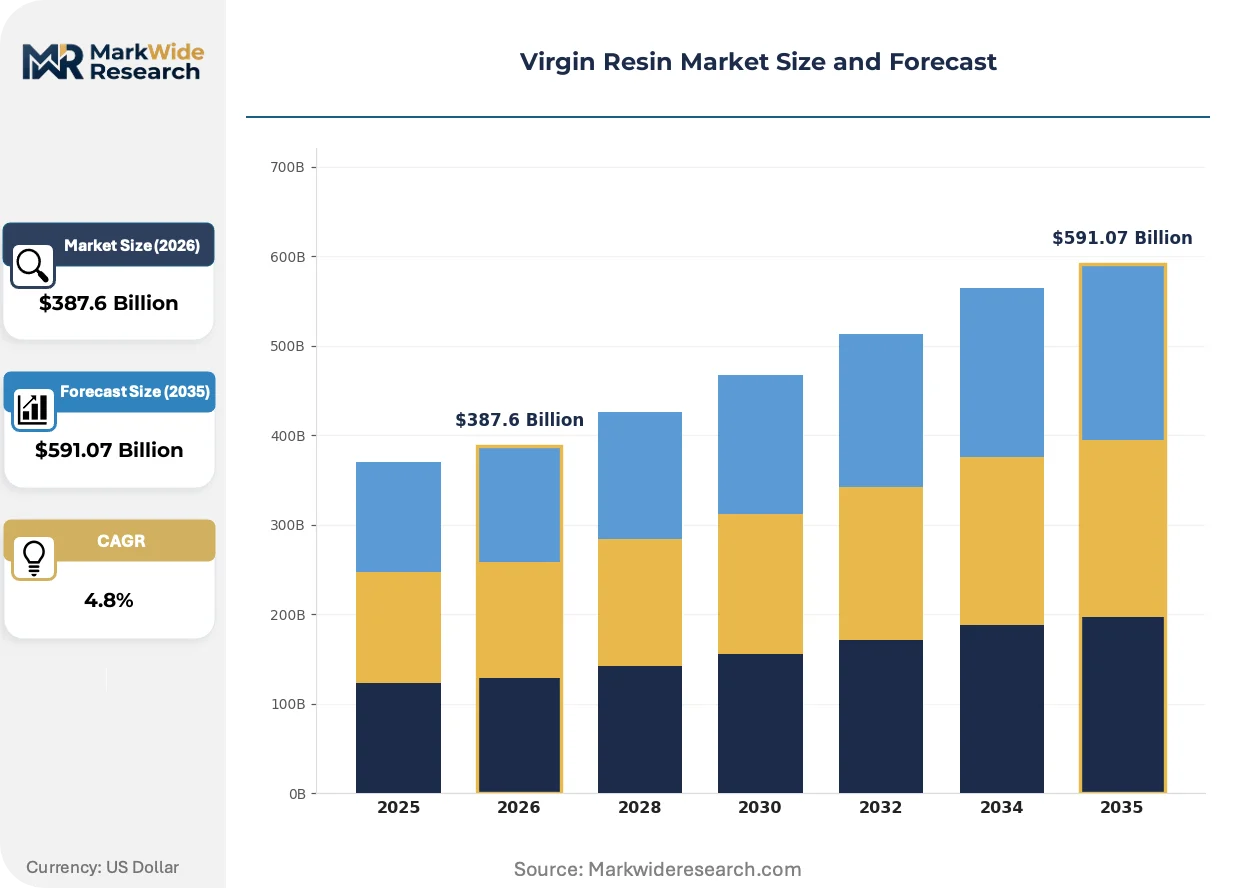
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $591.07 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, Polystyrene, Polycarbonate Grade: High-Grade, Standard-Grade, Specialty-Grade, Engineering-Grade Form: Pellets, Granules, Powder, Liquid Application: Packaging, Automotive Components, Consumer Goods, Electronics |
| Companies Covered | Dow, ExxonMobil, LyondellBasell, SABIC, TotalEnergies, BASF SE, Reliance Industries Ltd, INEOS, Sinopec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virgin Resin Market Emerging Trajectories
Advanced catalyst systems and modular production architectures are fragmenting the historical scale advantages of integrated petrochemical complexes while enabling regional supply autonomy.
Single-site metallocene catalyst technology is decentralizing polyethylene production economics by allowing smaller crackers to achieve narrow molecular weight distributions previously exclusive to world-scale facilities. Specialty film converters in Southeast Asia are adopting these grades for multilayer barrier structures. The technology is decentralizing procurement patterns as regional compounders bypass traditional import dependencies on US Gulf Coast supply.
REACH restrictions on phthalate plasticizers and persistent organic pollutants are forcing reformulation of flexible PVC compounds across European automotive and construction applications. Compounders are accelerating migration to non-phthalate alternatives including DINCH and bio-based plasticizers. Medical tubing and blood bag manufacturers face the steepest compliance costs and are consolidating supplier bases to audited specialty resin distributors.
Packaging converters are unbundling resin procurement from legacy annual volume contracts toward spot-indexed purchasing with embedded price caps. This behavioral shift is compressing working capital cycles for mid-tier extruders while squeezing margin predictability for producers. The pattern is most visible in India and Vietnam where converter consolidation has created purchasing consortiums with direct negotiating leverage against regional sales offices of major resin suppliers.
Virgin Resin Market Segmentation
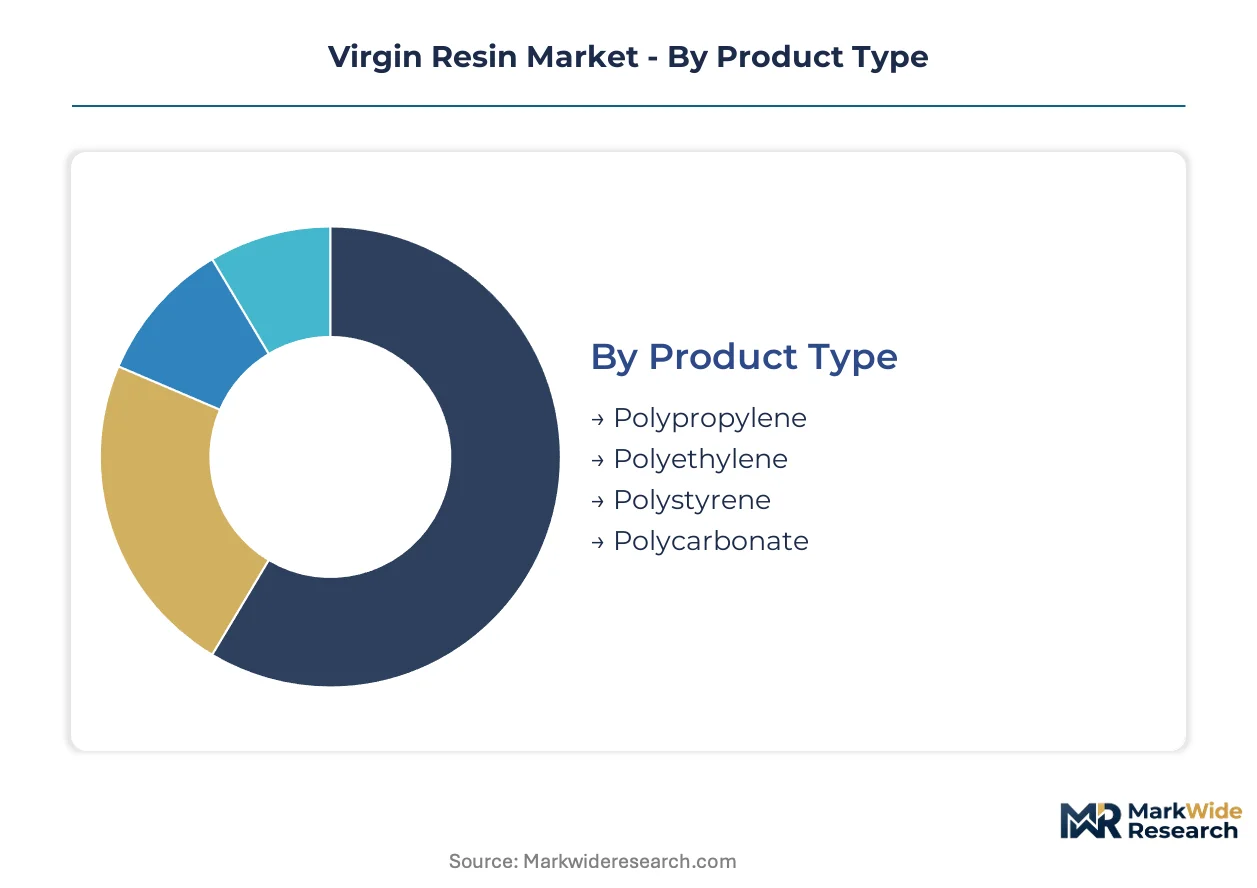
Virgin resin procurement patterns fragment sharply across product chemistry and purity thresholds. Converter specifications for melt flow indices and compliance certifications determine supplier selection more than bulk volume pricing.
Product Type:
Supply concentration in ethane-based cracking complexes favors commodity polyethylene producers along the US Gulf Coast and Middle Eastern feedstock corridors.
- Polyethylene:Linear low-density and high-density grades dominate flexible film extrusion for food-contact packaging. Indian packaging converters at Reliance Industries' Jamnagar complex are scaling purchases of high-performance metallocene grades for multilayer barrier structures. Polyethylene absorbs the bulk of installed capacity; polycarbonate is expanding most quickly.
- Polypropylene:Copolymer and homopolymer variants serve injection-molded automotive interior components and rigid consumer packaging. SABIC's differentiated portfolio targets Asian appliance manufacturers requiring high crystallinity and thermal stability. Polypropylene absorbs the bulk of installed capacity; polycarbonate is expanding most quickly.
- Polystyrene:General-purpose and high-impact grades supply disposable food service items and appliance housings where cost minimization overrides mechanical performance.
- Polycarbonate:Optical-grade formulations command premium positioning in automotive glazing, medical device housings, and 5G infrastructure thermal management applications.
Polyethylene absorbs the bulk of installed capacity; polycarbonate is expanding most quickly.
Grade:
Cost tier stratification separates certified medical-grade supply from commodity packaging resins, with specialty formulations capturing disproportionate margin pools.
- Specialty-Grade:Engineered thermal properties and narrow molecular weight distributions serve electronics miniaturization and automotive sensor clusters. Electronics miniaturization is pulling these formulations into 5G base station housings and LiDAR enclosures. Specialty-grade absorbs the bulk of value concentration; high-grade is expanding most quickly.
- High-Grade:Virgin purity exceeding 99.5 percent satisfies FDA food-contact notifications and EMA medical device requirements. German and Swiss sterile device manufacturers are qualifying new sources as legacy suppliers face inspection backlogs. Specialty-grade absorbs the bulk of value concentration; high-grade is expanding most quickly.
- Standard-Grade:General-purpose formulations serve non-critical packaging and construction applications where mechanical recycling substitution pressures are intensifying.
- Engineering-Grade:Reinforced and filled compounds meet structural load-bearing specifications in automotive underhood components and industrial machinery.
Specialty-grade absorbs the bulk of value concentration; high-grade is expanding most quickly.
Form:
Volume concentration in pellet supply reflects converter preference for dust-free handling and precise dosing in automated extrusion systems.
- Pellets:Uniform cylindrical shape enables consistent melt flow in twin-screw compounding and direct film extrusion lines across Southeast Asian packaging hubs.
- Granules:Irregular particle geometry suits batch mixing operations in smaller compounders lacking precision feeding infrastructure.
- Powder:Fine particle size distribution serves rotational molding and coating applications where surface finish uniformity is critical.
- Liquid:Unsaturated polyester and epoxy resin systems supply fiberglass-reinforced composite manufacturers in marine and wind energy blade fabrication.
Pellets absorb the bulk of converter demand; powder is expanding most quickly.
Application:
Customer type divergence separates specification-driven automotive and electronics OEMs from price-sensitive packaging converters.
- Packaging:Flexible films, rigid containers, and barrier layers consume the majority of polyethylene and polypropylene volumes. Indian and Vietnamese converters are consolidating into purchasing consortiums with direct negotiating leverage against regional sales offices of major suppliers.
- Electronics:Polycarbonate housings and thermal interface materials demand engineered optical clarity and heat dissipation properties. 5G infrastructure deployment and automotive sensor proliferation are accelerating specialty-grade qualification cycles.
- Automotive Components:Interior trim, underhood applications, and lightweight structural parts require heat-stabilized and glass-reinforced formulations meeting OEM emission and durability specifications.
- Consumer Goods:Durable household items and personal care packaging balance aesthetics with cost constraints, often sourcing standard-grade resins through spot-indexed purchasing arrangements.
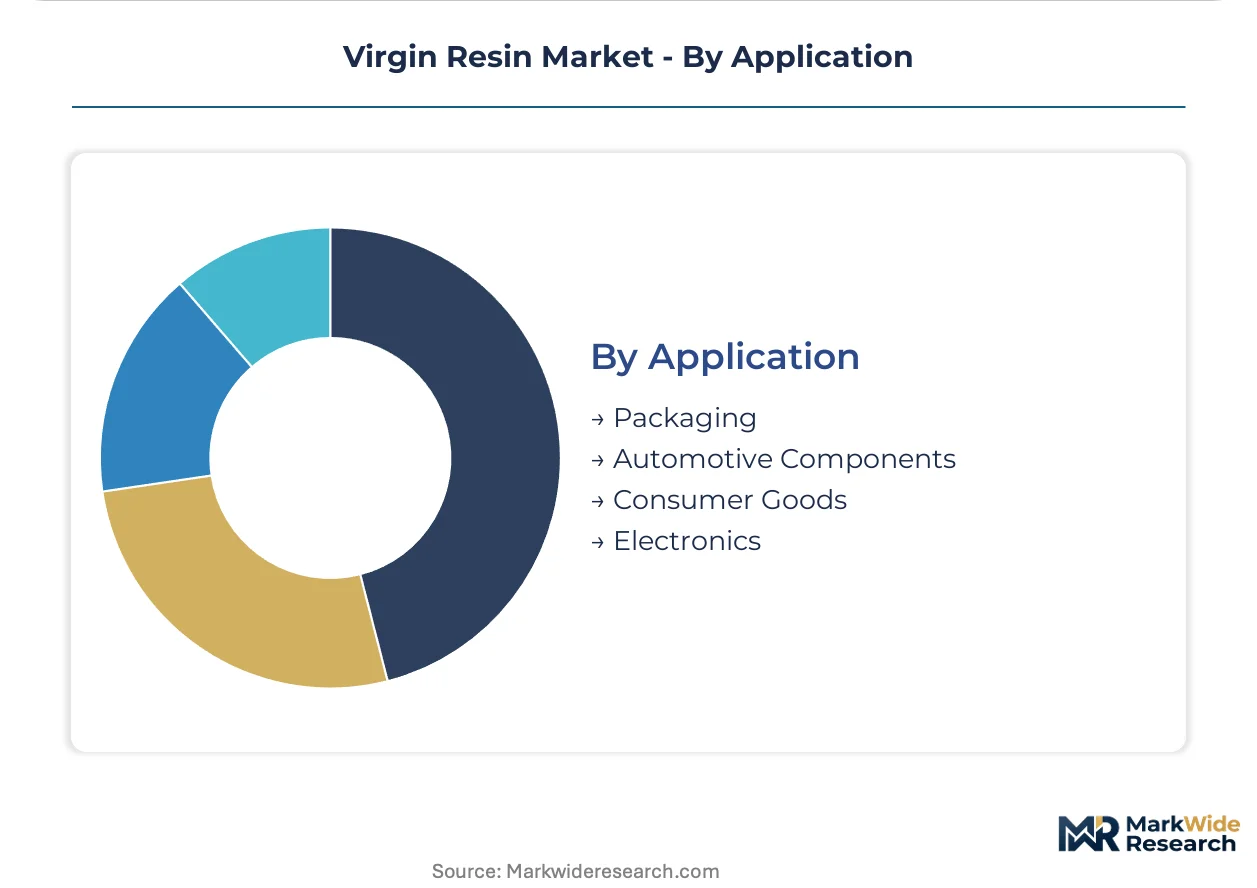
Packaging absorbs the bulk of volume consumption; electronics is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethane-rich shale formations along the US Gulf Coast anchor global polyethylene supply, while naphtha-dependent crackers in Northeast Asia and Europe face narrowing feedstock cost differentials. Regional regulatory divergence—REACH amendments in Europe, FDA purity mandates in the US, and BIS certification requirements in India—are fragmenting procurement standards and accelerating localized compounding investments.
United States
Integrated Gulf Coast petrochemical complexes leverage abundant ethane feedstock to sustain cost leadership in linear low-density polyethylene production. EPA Clean Air Act Title V permitting extends construction timelines for new ethylene capacity by 18-24 months, constraining supply expansion. The Houston-Beaumont-Port Arthur corridor concentrates world-scale cracking infrastructure serving domestic flexible packaging converters and export markets.
Germany
Automotive glazing and medical device manufacturers in Baden-Württemberg and Bavaria drive specialty-grade polycarbonate demand for optical clarity applications. EMA inspection backlogs on legacy resin suppliers are forcing German and Swiss sterile device manufacturers to qualify alternative high-purity sources. The Ludwigshafen chemical cluster anchors European supply chain coordination for REACH-compliant polymer formulations.
China
Packaging converters in the Yangtze River Delta and Pearl River Delta are scaling purchases of metallocene-grade polyethylene for multilayer barrier films. MIIT industrial standards and evolving GB specifications for food-contact materials are tightening compliance documentation requirements. Sinopec's integrated refining-petrochemical complexes along the eastern seaboard dominate domestic supply, though specialty grades remain import-dependent.
India
Domestic packaging demand concentrates in Gujarat and Maharashtra, where Reliance Industries has expanded Jamnagar compounding capacity to serve high-performance polyethylene requirements. BIS certification mandates for virgin resin purity are locking in supplier relationships with audited domestic converters. The Delhi-Mumbai Industrial Corridor is attracting regional distribution hubs for spot-indexed procurement by mid-tier film extruders.
Saudi Arabia
SABIC maintains feedstock-integrated polyethylene and polypropylene production serving Asian export markets as regional ethane pricing converges with global LNG indices. The country's national industrial regulator enforces emission controls on cracking complexes aligned with Gulf Cooperation Council environmental frameworks. Jubail Industrial City hosts world-scale petrochemical infrastructure targeting differentiated polypropylene portfolios for appliance manufacturers in East Asia.
Virgin Resin Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty-grade formulations and regional compounding partnerships. The market exhibits tiered concentration with integrated petrochemical majors controlling commodity polyethylene supply and independent compounders capturing niche medical and electronics applications. Three archetypes dominate: Gulf Coast ethane-integrated majors, European naphtha-based diversified chemical conglomerates, and Asia-Pacific feedstock-advantaged national champions. Competitive moves center on backward integration into cracker capacity and geographic diversification of compounding assets to bypass trade barrier exposure.
Among US-based integrated majors, Dow and ExxonMobil exemplify the ethane-advantaged archetype with captive Gulf Coast cracking infrastructure. LyondellBasell occupies a position bridging Atlantic supply corridors through its Rotterdam hub. SABIC represents the Middle Eastern feedstock-integrated model with Asian market orientation. Reliance Industries Ltd anchors the India-centric national champion archetype with expanding domestic compounding capabilities.
| Leading Market Players |
|---|
| Dow |
| ExxonMobil |
| LyondellBasell |
| SABIC |
| TotalEnergies |
| BASF SE |
| Reliance Industries Ltd |
| INEOS |
| Sinopec |
| Others |
Supply Flow & Price Mechanics
Indian packaging converter consortiums consolidating into direct negotiating collectives are forcing regional sales offices of major resin suppliers to unbundle legacy annual contracts and adopt spot-indexed purchasing with embedded price caps. This procurement shift compresses working capital cycles for mid-tier film extruders while squeezing margin predictability for producers across Asia-Pacific markets.
Pricing Analysis
Certification and lot-traceability bundling now separates premium resin tiers from unbundled commodity supply. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA food-contact notification status and batch-level melt flow index documentation. Cost compression in standard-grade polyethylene is intensifying because mechanical recycling substitution pressures mount in non-food bottle applications. Spot-indexed purchasing consortiums in India and Vietnam demonstrate highest price sensitivity; German medical device OEMs purchasing optical-grade polycarbonate show lowest.
Supply Chain Analysis
BIS certification mandates for virgin resin purity are reshaping sourcing toward audited domestic Indian compounders and away from unqualified import channels. Feedstock supply draws from US Gulf Coast ethane corridors, Middle Eastern gas-based complexes, and Northeast Asian naphtha crackers. Cracker furnace emissions controls and REACH amendment compliance create regulatory chokepoints extending capacity construction timelines. Distribution runs through regional compounding hubs in Gujarat, Rotterdam, and Jubail Industrial City serving downstream film extruders and injection molders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around feedstock-integrated majors as EPA permitting delays and REACH compliance costs force smaller compounders into acquisition or exit. Regulatory burden concentration favors scaled players with captive laboratory infrastructure.
For Market Incumbents: Lock in converter relationships through multi-year offtake agreements embedding price caps and lot-traceability guarantees. Deepen backward integration into modular metallocene catalyst production to defend against single-site technology disruptors. Prioritize Rotterdam and Singapore hub expansions to bypass tariff exposure on trans-Atlantic and intra-Asian flows.
For New Entrants and Emerging Players: Capture medical-grade polycarbonate qualification opportunities in German and Swiss sterile device markets where EMA inspection backlogs have destabilized legacy supplier relationships. Target specialty-grade thermal management formulations for 5G infrastructure and automotive LiDAR enclosures. Lead with direct-to-converter digital platforms offering real-time pricing and batch documentation to mid-tier Southeast Asian film extruders.
For Investors and Strategic Acquirers: The window for entry favors India-centric national champions with expanding Jamnagar compounding capacity and BIS-certified supply relationships. Long-term viability rests on feedstock-advantaged positioning and regulatory compliance infrastructure. Watch for spot-indexed procurement adoption rates among Vietnamese converter consortiums as inflection indicator toward pricing transparency and margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cracker Capacity | Gulf Coast ethane-advantaged majors secure captive polyethylene supply against naphtha cost volatility. |
| Medical-Grade Certification Investment | German sterile device manufacturers qualify alternative polycarbonate sources amid EMA inspection delays. |
| Regional Compounding Hub Expansion | Rotterdam and Singapore facilities bypass REACH and tariff exposure for European and Asian converters. |
| Direct-to-Converter Digital Platform Launch | Real-time pricing and lot traceability targets mid-tier Indian and Vietnamese film extruder procurement shifts. |
| Metallocene Catalyst Technology Adoption | Single-site systems enable smaller crackers to achieve narrow molecular weight distributions for barrier films. |
Methodological Framework
Trade databases, SEC filings, and ECHA REACH substance registrations formed the secondary backbone, supplemented by customs records tracking virgin resin import flows into Indian and Vietnamese packaging hubs. Primary interviews with plant managers at integrated petrochemical complexes, procurement leads at downstream film extruders, distribution channel partners, and technical R&D directors at catalyst system suppliers validated demand assumptions. Bottom-up volume modeling across grade tiers and end-use applications triangulated against top-down macroeconomic elasticity estimates.
Historical trendline analysis of polyethylene and polycarbonate consumption patterns informed elasticity assumptions across the projection horizon. Segmentation dimensions modeled include product chemistry, purity grade tier, packaging format, and regional production hub clustering. CAGRs were derived from fitted trend extrapolation adjusted for feedstock cost differential convergence and regulatory compliance cost inflation. Industry-specific forecast inputs incorporated EPA Title V permitting queue lengths and BIS certification approval timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ethane-naphtha price convergence rates and mechanical recycling substitution thresholds in flexible packaging. Forecasts reflect documented assumptions regarding catalyst technology diffusion and regional regulatory harmonization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
India Polyacrylamide Copolymer Market
Polymers & Resins
Polyether Ketone (PEK) Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market
Polymers & Resins
Thermoplastic Polyimide Market
Polymers & Resins
Global Polyethylene Glycol Market
Polymers & Resins
High-Purity Epoxy Resin Market
Polymers & Resins
Global Opaque Polymers Market
Polymers & Resins
Global Epoxy Primer Market
Polymers & Resins
Polymer Antioxidants Market
Polymers & Resins
Poly Alpha Olefin (PAO) Market
Polymers & Resins
Isosorbide-Based Engineering Polymer Monomers Market
Polymers & Resins
Thermoplastic Starch (TPS) Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
Polyethylene Furanoate Market
Polymers & Resins
Fire Resins Market