
 Poly(P-Phenylene Ether) (PPE) Market | 2026-2036
Poly(P-Phenylene Ether) (PPE) Market Size, Share, and Industry Trends Forecast 2026-2036
Poly(P-Phenylene Ether) (PPE) Market Analytics
Polycarbonate is repositioning PPE blends in automotive under-the-hood applications where hydrolytic stability and dimensional precision matter most. SABIC leverages its vertically integrated resin portfolio to control formulation consistency across Middle Eastern and Asian production nodes. Asahi Kasei Corporation anchors Japanese supply through proprietary alloy technologies that extend heat deflection temperatures beyond conventional PPE limits. BASF SE competes on compounding scale, operating regional facilities that customize flame-retardant grades for appliance and electrical OEMs.
Poly(p-phenylene ether) is a high-performance thermoplastic characterized by a glass transition temperature near 210°C and inherent flame resistance without halogenated additives, manufactured primarily through oxidative coupling polymerization of 2,6-dimethylphenol. The material serves industrial markets requiring structural integrity under thermal and electrical stress, particularly in connector housings, relay blocks, and fluid handling components. PPE compounds dominate current revenue streams, reflecting established demand from automotive and electrical sectors where pre-engineered formulations reduce customer processing complexity. PPE alloys represent the fastest-expanding category, driven by hybridization with polyamides and polystyrenics that broaden the property envelope for EV thermal management parts. Granule form occupies the largest share of physical deliveries, though pelletized grades tailored to specific injection molding equipment are gaining traction among precision component manufacturers.
REACH restrictions on halogenated flame retardants in Europe and EPA assessments of persistent organic pollutants in the United States are redirecting formulation investments toward phosphorus-based and metal hydrate systems compatible with PPE chemistry. China's GB standards for electronic product safety and SAMR enforcement of material labeling requirements are raising compliance costs for non-domestic compounders while creating preference for certified local production. IEC 60695 glow-wire ignition specifications for unattended appliances are tightening globally, pushing OEMs toward PPE grades that meet elevated test temperatures without additive loading that degrades mechanical properties. Stakeholders must monitor how battery pack architectures and thermal runaway containment standards evolve, as these design choices will determine whether PPE displaces incumbent materials or cedes position to newer high-heat polymers.
Market Dynamics
Automotive electrification is compressing material qualification cycles as battery thermal management systems demand polymers that withstand 150°C continuous operating temperatures without hydrolytic degradation. This pressure is forcing compounders to pre-certify formulations against evolving OEM specifications rather than responding to individual RFQs.
Growth Catalysts
- EV Battery Housing Demand:Chinese EV original equipment manufacturers in the eastern manufacturing corridor specify PPE alloys for module enclosures requiring flame resistance without halogenated additives.
- REACH Flame-Retardant Restrictions:ECHA enforcement against brominated compounds in Europe redirects appliance manufacturers toward inherently fire-resistant PPE grades meeting IEC 60695 glow-wire ignition thresholds.
- Charging Infrastructure Buildout:SAE J1772 and IEC 62196 connector specifications favor PPE's dimensional stability across temperature cycling for high-voltage charging hardware.
Market Restraints
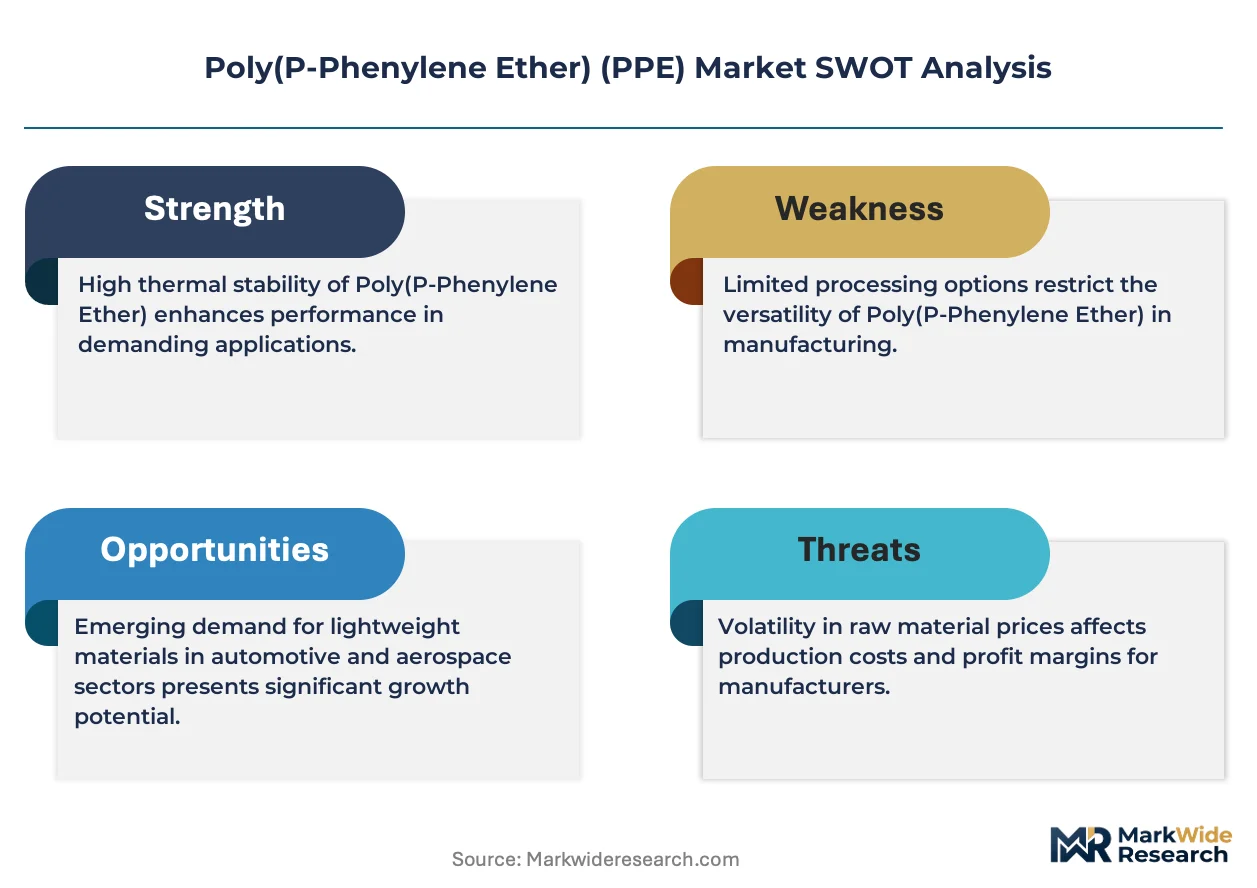
- 2,6-Dimethylphenol Feedstock Concentration:Oxidative coupling polymerization relies on cresol derivatives supplied by a limited set of Asian petrochemical producers, creating price volatility exposure.
- Polyamide Hybrid Competition:PA66 and PA46 compounds with glass fiber reinforcement challenge PPE alloys in under-the-hood applications where cost-per-part dominates supplier selection.
- REACH Registration Burden:ECHA compliance costs for novel PPE formulations exceed €100,000 per substance, blocking mid-tier compounders from European market entry.
Strategic Opportunities
- India EV Component Localization:PLI scheme incentives for domestic automotive electronics manufacturing create demand for certified PPE compounds in battery management system housings.
- Solid-State Battery Thermal Barriers:Next-generation cell architectures require interstitial materials with dielectric strength above 20 kV/mm, a specification PPE formulations can target.
- SAMR Certification Preference:China's State Administration for Market Regulation enforcement of material labeling standards disadvantages uncertified imports, favoring domestic compounders with established GB compliance.
Industry Challenges
- Polymer Rheology Expertise Scarcity:Compounding facilities lack sufficient process engineers capable of optimizing PPE alloy viscosity for thin-wall injection molding of connector housings.
- IEC 60695-2-12 Certification Timelines:Glow-wire flammability testing for unattended appliance applications requires 12-18 month qualification cycles that delay product launches.
- Legacy Equipment Retrofit Costs:Converting polystyrene-oriented molding lines to handle PPE's higher processing temperatures demands capital expenditure that small processors cannot justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poly(P-Phenylene Ether) (PPE) Market |
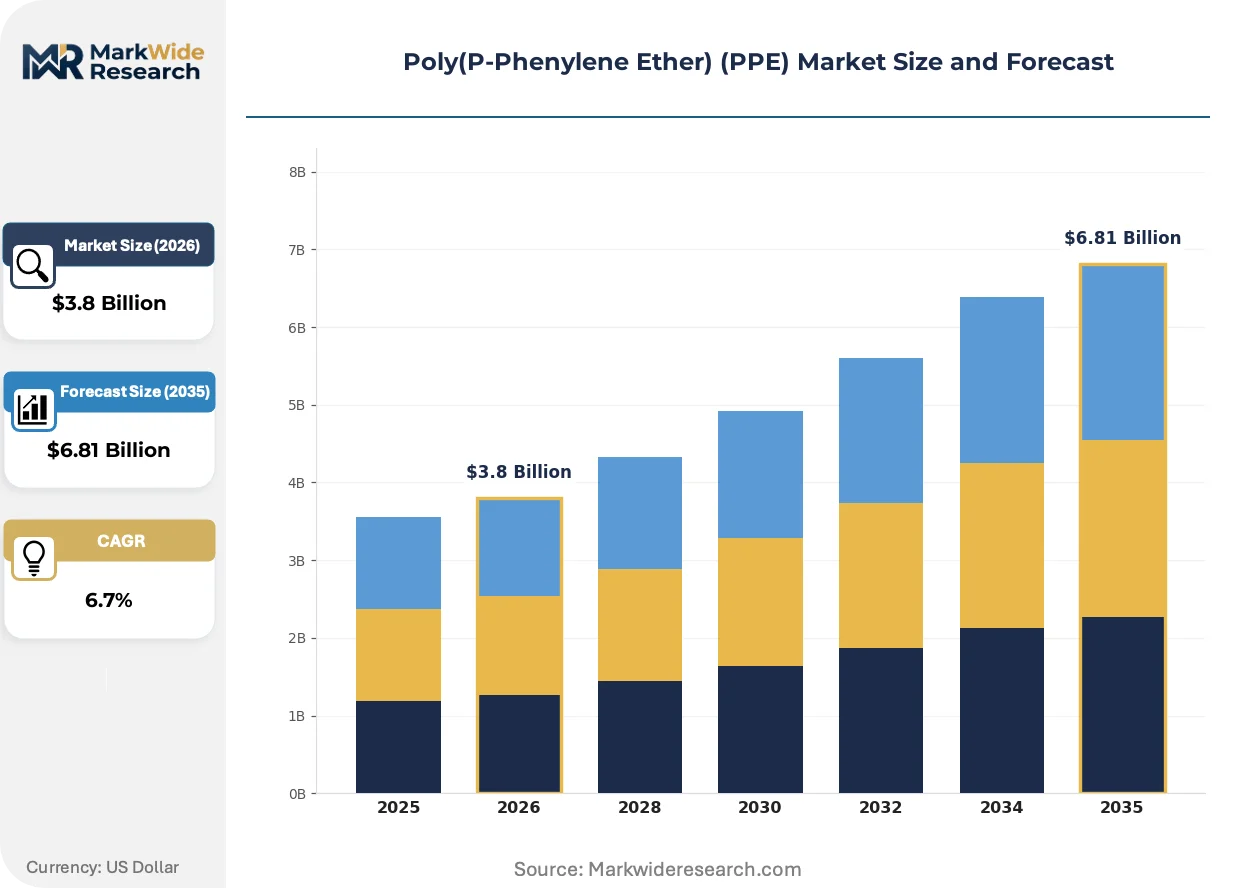
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compounds, Blends, Alloys, Homopolymers Application: Electrical Insulation, Automotive Components, Consumer Goods, Industrial Equipment End User: Electrical, Automotive, Consumer Electronics, Industrial Form: Granules, Pellets, Sheets, Films |
| Companies Covered | SABIC, Asahi Kasei Corporation, BASF SE, Evonik Industries AG, LyondellBasell Industries Holdings B.V., Mitsubishi Chemical Corporation, Sumitomo Chemical Co., Ltd., Polyplastics Co. Ltd, Entec Polymers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poly(P-Phenylene Ether) (PPE) Market Evolving Landscape
Material hybridization is redefining performance boundaries as compounders fuse PPE with engineering polymers to capture thermal management applications previously reserved for higher-cost alternatives. This convergence is accelerating qualification timelines and compressing the addressable market for incumbent specialty resins.
Phosphorus-based flame-retardant systems are electrifying formulation development by enabling UL94 V-0 ratings at lower additive loadings than metal hydrate alternatives. Automotive wiring harness suppliers in Germany and Japan are adopting these grades for high-density connector blocks where space constraints limit wall thickness. The technology is electrifying competitive positioning by allowing PPE to displace polycarbonate in applications requiring both transparency and ignition resistance.
EPA assessments of persistent organic pollutants under the Toxic Substances Control Act are restricting halogenated additive use in electrical enclosures exported to the United States. Appliance manufacturers serving North American markets are reformulating toward PPE grades with inherent flame resistance to preempt regulatory disqualification. This policy pressure is most acute in residential HVAC control modules where NRTL certification requires documented compliance with evolving EPA substance restrictions.
Direct compounder relationships are displacing distributor-centric procurement as EV battery manufacturers seek technical collaboration during early design phases. Tier-1 automotive suppliers in South Korea and China now require resident engineers from material vendors to co-develop thermal runaway containment solutions. This intimacy model is visible most clearly in the Yangtze River Delta manufacturing cluster where domestic battery producers consolidate supplier panels to three qualified compounders per material family.
Poly(P-Phenylene Ether) (PPE) Market Segmentation
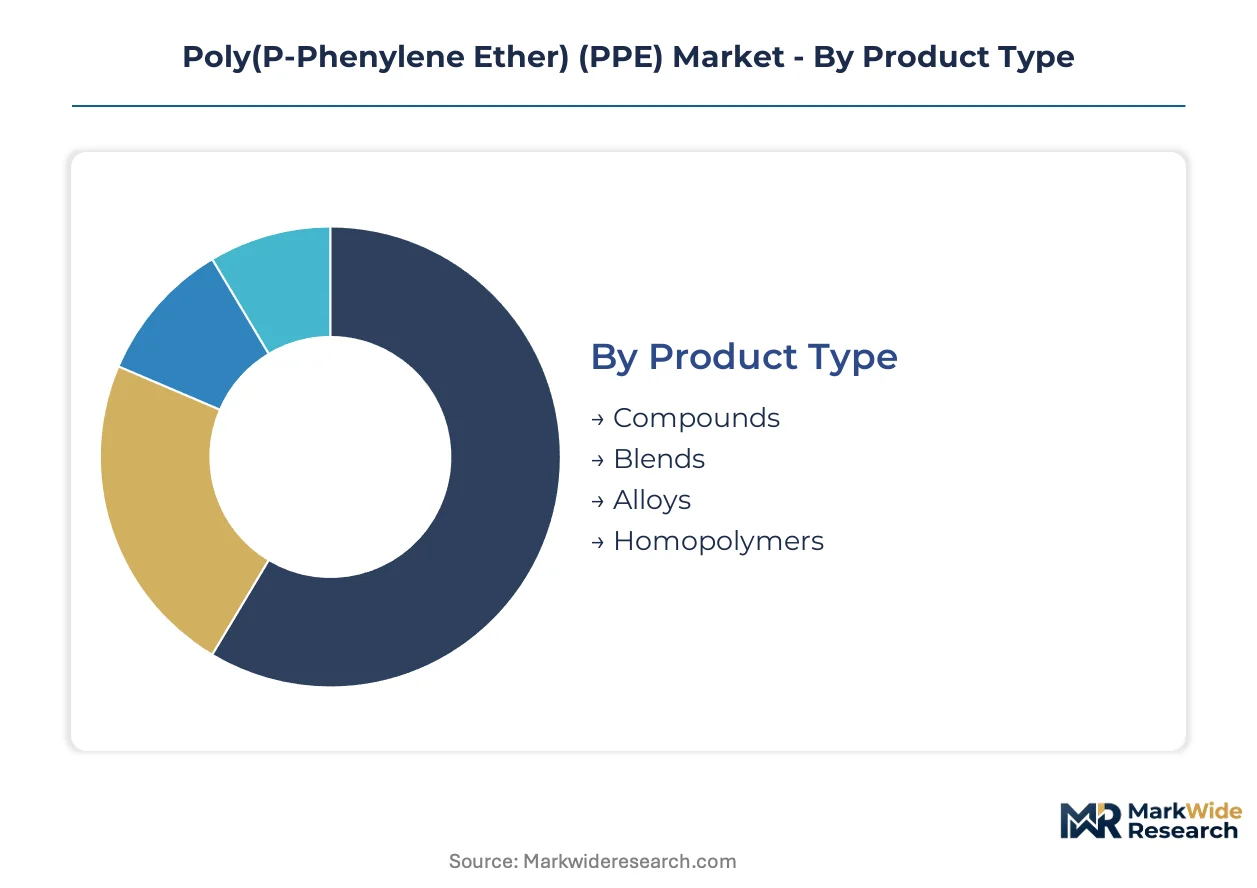
Poly(p-phenylene ether) market segmentation reveals how certification requirements fragment procurement patterns across product categories. Formulation complexity and end-use specifications determine which segments carry heavier regulatory burdens.
Product Type:
PPE compounds demand UL94 V-0 and IEC 60695 glow-wire ignition certification for electrical applications, while alloys require additional OEM thermal cycling validation for automotive qualification.
- Compounds:Pre-engineered formulations with flame-retardant additives dominate connector housing production. Chinese EV battery manufacturers in the Yangtze River Delta specify certified grades for module enclosures requiring 150°C continuous operating temperatures.
- Alloys:Hybridized systems with polyamides or polystyrenics extend heat deflection temperatures beyond base PPE limits. German automotive wiring harness suppliers adopt these for high-density connector blocks where space constraints limit wall thickness.
- Blends:Polycarbonate-PPE combinations target automotive under-the-hood applications requiring hydrolytic stability.
- Homopolymers:Unmodified resin serves specialized research and niche industrial applications.
Compounds sit at the top of the volume ranking, with alloys climbing the fastest.
Application:
Cost tier differentiation separates premium certified grades from standard formulations across end-use markets.
- Electrical Insulation:Relay blocks and connector housings require dielectric strength above 20 kV/mm. Appliance manufacturers reformulate toward inherently flame-resistant grades to preempt EPA restrictions on halogenated additives in HVAC control modules.
- Automotive Components:Battery thermal management systems and charging connectors demand polymers with dimensional precision across temperature cycling. SAE J1772 and IEC 62196 specifications favor PPE for high-voltage hardware.
- Consumer Goods:Small appliance housings and kitchen equipment components utilize standard flame-retardant grades.
- Industrial Equipment:Fluid handling components and pump housings exploit PPE's chemical resistance.
Electrical insulation commands the largest volume position, with automotive components expanding most quickly.
End User:
Customer procurement sophistication varies sharply across sectors, with automotive and electrical buyers imposing the most stringent qualification protocols.
- Electrical:OEMs require 12-18 month IEC 60695-2-12 certification cycles for unattended appliance applications.
- Automotive:Tier-1 suppliers demand resident engineers from material vendors for co-development of thermal runaway containment solutions.
- Consumer Electronics:Portable device manufacturers prioritize thin-wall injection molding compatibility.
- Industrial:Process equipment builders emphasize long-term dimensional stability under thermal stress.
Electrical end users generate the highest volume throughput, with automotive buyers gaining share fastest.
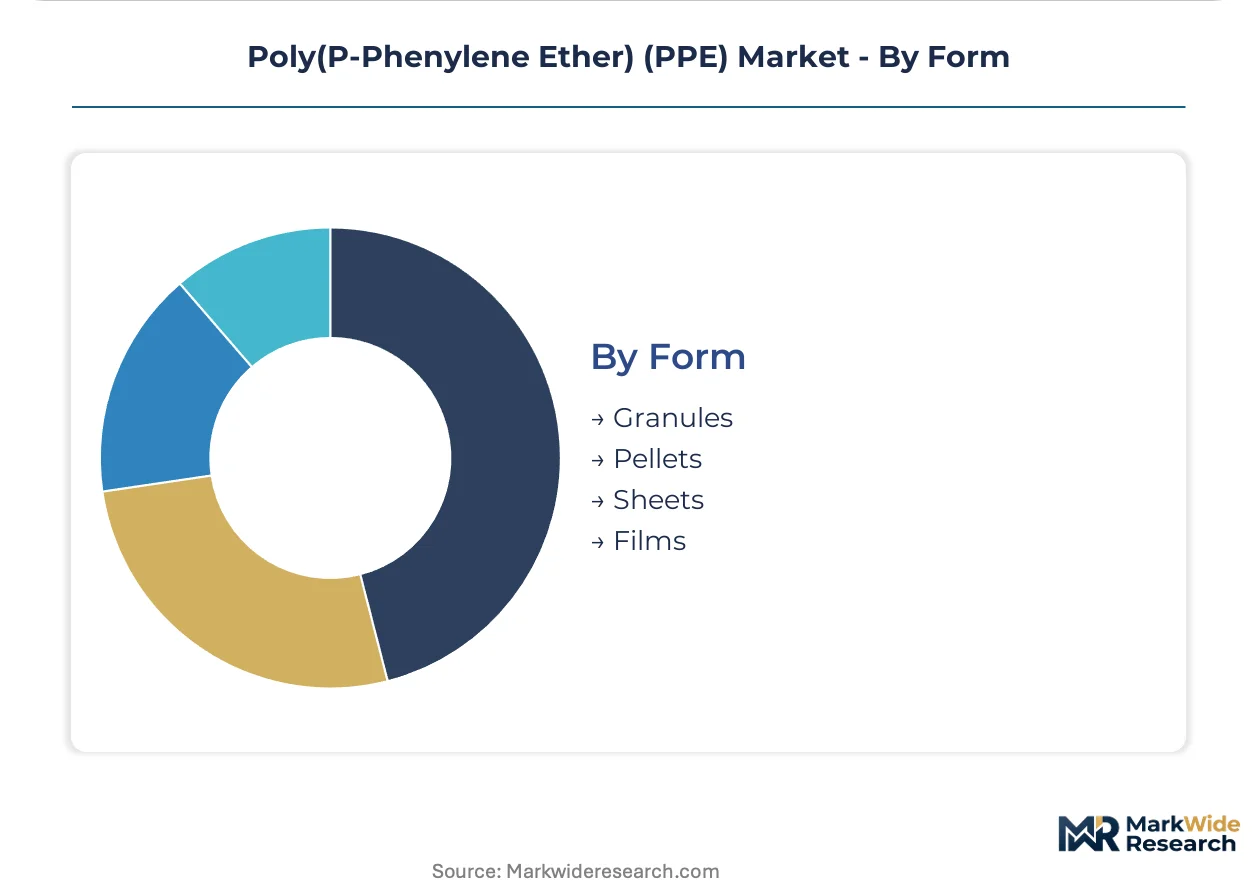
Form:
Supply concentration in granule production reflects established compounding infrastructure, while pelletized grades target precision manufacturers with specialized equipment.
- Granules:Standard physical delivery format occupies the largest processing equipment installed base across injection molding facilities.
- Pellets:Tailored grades for specific injection molding equipment are gaining traction among precision component manufacturers in South Korea and Japan.
- Sheets:Compression molding feedstock serves industrial equipment fabricators requiring thick-section parts.
- Films:Specialty format for electrical insulation laminates and flexible circuit substrates.
Granules maintain the volume leadership position, with pellets showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta anchors PPE demand through its concentration of EV battery manufacturers and domestic compounding infrastructure serving automotive OEMs.
China
Domestic EV producers in Jiangsu and Zhejiang provinces specify PPE alloys for battery module enclosures requiring 150°C continuous operating temperatures. SAMR enforcement of GB standards for electronic product safety raises compliance costs for imported compounds while favoring certified local production. The Suzhou-Ningbo manufacturing corridor hosts compounders supplying BYD and CATL with flame-retardant grades.
Germany
Automotive wiring harness suppliers adopt phosphorus-based PPE formulations for high-density connector blocks serving Volkswagen and BMW electrification programs. ECHA restrictions on brominated flame retardants under REACH redirect appliance manufacturers toward inherently fire-resistant grades. The Rhine-Ruhr industrial region concentrates compounding facilities customizing IEC 60695-certified materials for unattended appliance applications.
United States
Battery thermal management system suppliers specify PPE grades meeting SAE J1772 connector specifications for high-voltage charging hardware. EPA assessments of persistent organic pollutants under the Toxic Substances Control Act restrict halogenated additive use in electrical enclosures. The Michigan-Ohio automotive belt hosts Tier-1 suppliers demanding resident engineers from material vendors for co-development programs.
Japan
Precision connector manufacturers in the Chubu region utilize pelletized PPE grades tailored to thin-wall injection molding equipment for high-density relay blocks. METI guidance on next-generation vehicle technologies accelerates qualification cycles for thermal management materials. The Nagoya industrial cluster anchors domestic supply through proprietary alloy technologies extending heat deflection temperatures.
South Korea
EV battery producers in the Seoul Capital Area consolidate supplier panels to three qualified compounders per material family for thermal runaway containment solutions. MFDS alignment with international electrical safety standards streamlines certification for export-oriented manufacturers. The Busan-Ulsan chemical processing hub supports backward integration into cresol derivative feedstocks for oxidative coupling polymerization.
Poly(P-Phenylene Ether) (PPE) Market Competitive Landscape
Global majors compete with regional champions across formulation certification and automotive qualification timelines. The vendor base separates into three tiers: petrochemical conglomerates with captive resin production, specialized compounders with OEM-approved grades, and regional distributors serving fragmented appliance markets. Two strategic archetypes dominate: vertically integrated resin producers controlling formulation consistency across multiple production nodes, and alloy specialists leveraging proprietary hybridization technologies. Competitive moves concentrate on pre-certification investments against evolving OEM specifications and direct technical collaboration models displacing distributor-centric procurement.
Among Middle Eastern and Asian resin producers, SABIC exemplifies the integrated-petrochemical archetype through its control of formulation consistency across regional production nodes. Asahi Kasei Corporation anchors the Japanese supply position through proprietary alloy technologies. BASF SE occupies the European compounding tier with regional facilities customizing flame-retardant grades. These three represent distinct competitive positioning vectors: upstream integration, technology specialization, and geographic scale.
| Leading Market Players |
|---|
| SABIC |
| Asahi Kasei Corporation |
| BASF SE |
| Evonik Industries AG |
| LyondellBasell Industries Holdings B.V. |
| Mitsubishi Chemical Corporation |
| Sumitomo Chemical Co., Ltd. |
| Polyplastics Co. Ltd |
| Entec Polymers |
| Others |
Value Network & Pricing Analysis
Oxidative coupling polymerization technology transitions from batch to continuous processing configurations, simultaneously compressing unit production costs and concentrating supply among compounders with capital to retrofit reactor systems. This dual effect tightens margins for legacy batch operators while rewarding integrated producers with captive 2,6-dimethylphenol supply.
Pricing Analysis
Input-cost pass-through from cresol derivative feedstocks dominates PPE pricing mechanics, with Asian petrochemical producers adjusting monomer contract rates quarterly. Three-tier pricing structure across certified automotive grades, standard electrical formulations, and economy appliance compounds reflects UL94 and IEC 60695 certification burdens. Pricing pressure stems from polyamide hybrid competition in under-the-hood applications where cost-per-part dictates supplier selection. Appliance OEMs exhibit highest price sensitivity, while EV battery manufacturers prioritize thermal performance over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and South Korean petrochemical complexes supplying the majority of 2,6-dimethylphenol feedstock for oxidative coupling polymerization. Manufacturing concentrates in China, Germany, and Japan, with each hub serving distinct regional qualification protocols. Raw material dependencies include cresol derivatives, phosphorus-based flame retardants, and polyamide blending resins. Tariff exposure on specialty chemical imports into Europe creates supply chain risk for non-integrated compounders. Distribution runs through direct compounder relationships with Tier-1 automotive suppliers, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PPE market functions as a stable compounder, with automotive electrification providing durable volume expansion through battery thermal management material specifications.
For Market Incumbents: Anticipate polyamide hybrid encroachment in under-the-hood segments by deepening captive resin production and accelerating IEC 60695 pre-certification investments. Prioritize resident engineer placements with Yangtze River Delta battery producers to lock in thermal runaway containment co-development programs. Defend formulation consistency advantages through backward integration into cresol derivative supply. For New Entrants and Emerging Players: Launch via technical partnership models targeting India's PLI-subsidized EV component manufacturing, where certified domestic compounders remain scarce. Penetrate the solid-state battery interstitial materials segment before incumbent qualification cycles complete. Exploit SAMR certification gaps to establish GB-compliant production ahead of European and Japanese competitors. For Investors and Strategic Acquirers: Valuations sit cheapest among regional compounders with OEM-approved grades but limited geographic footprint. Long-term viability favors specialists with proprietary alloy technologies and established automotive qualification timelines. Watch battery pack architecture shifts toward cell-to-pack designs as the signal for PPE displacement risk versus expansion opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cresol Feedstocks | Captive 2,6-dimethylphenol supply insulates compounders from Asian petrochemical price volatility. |
| IEC 60695 Pre-Certification Investment | Pre-qualified flame-retardant grades compress OEM qualification cycles from 18 months to 6 months. |
| Resident Engineer Placement Programs | Direct technical collaboration with CATL and BYD displaces distributor-centric procurement in China. |
| Phosphorus-Based Formulation Development | Low-additive-load UL94 V-0 systems enable thin-wall connector applications previously reserved for polycarbonate. |
| India PLI-Aligned Manufacturing Scale-Up | Domestic certified production captures battery management system housing demand from Tata and Mahindra electrification programs. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polymer plant managers, procurement leads at automotive Tier-1 suppliers, distribution channel partners, and technical R&D directors at major compounders. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and IEC certification registries. Bottom-up volume modeling triangulated against top-down market sizing across product categories.
Historical reference periods anchored the projection horizon, with growth rates derived from segment-level demand elasticity analysis and input-cost trajectory modeling. Segmentation dimensions included product type (compounds, alloys, blends), application category (electrical insulation, automotive components, consumer goods), end-user sophistication tier, and regional production hub. Forecast inputs incorporated EV battery production schedules, REACH regulatory phase-in timelines, and cresol derivative capacity expansion announcements.
Several conditions sit outside the modeled scope, including breakthrough high-heat polymer commercialization, abrupt cresol supply disruptions from geopolitical events, and faster-than-anticipated solid-state battery thermal barrier material substitution. Forecasts reflect documented assumptions about OEM qualification cycle durations and regulatory enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Binders Market
Polymers & Resins
Global Polybutene Market
Polymers & Resins
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market
Polymers & Resins
South America Polyvinyl Chloride (PVC) Market
Polymers & Resins
Modified Alkyd Resin Market
Polymers & Resins
Global Polyurethane Dispersions Market
Polymers & Resins
Europe Cyclic Olefin Copolymer Market
Polymers & Resins
Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
PEKK Market
Polymers & Resins
Glutathione Resin Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
Antiviral Polymers for Packaging Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Asia-Pacific Epoxy Resins Market
Polymers & Resins
Polysulfide Resin Market
Polymers & Resins
North America and Europe Phenolic Resin Market