
 PEG 3500 Market | 2026-2036
PEG 3500 Market Size, Share, and Industry Trends Forecast 2026-2036
PEG 3500 Market Analytics
Propylene glycol is repositioning certain industrial lubricant applications where PEG 3500 traditionally served, yet pharmaceutical-grade specifications are tightening and preserving premium economics. Dow Chemical Company leverages captive ethylene oxide supply chains to sustain cost discipline across glycol polymerization. BASF SE anchors its position through pharma-grade certification depth in Ludwigshafen. Croda International Plc specializes in high-purity lipid and glycol conjugates for biopharma clients.
PEG 3500 denotes a polyethylene glycol polymer with an average molecular weight of 3,500 g/mol, synthesized via anionic ring-opening polymerization of ethylene oxide with water or ethylene glycol initiators under alkaline catalysis. It functions primarily as a solubilizing agent, plasticizer, and ointment base across pharmaceutical and personal care formulations. Liquid PEG 3500 commands the largest volume share due to ease of handling in aqueous drug delivery systems, while pharma grade captures the deepest margin pool as endotoxin and peroxide specifications tighten. Powder and flake formats are gaining traction in solid dosage manufacturing where precise dosing and reduced moisture content matter.
FDA excipient guidelines, REACH substance registration thresholds, and USP-NF monograph revisions collectively elevate compliance costs for non-pharma grade producers while rewarding certified suppliers with preferred-supplier status. The EU Green Deal's embodied carbon tracking extends to petrochemical feedstocks, pressuring glycol producers to document Scope 3 emissions or risk exclusion from European pharmaceutical supply chains. Stakeholders must monitor regulatory divergence between FDA purity standards and emerging EMA sustainability disclosure rules when allocating capacity across grade tiers.
Market Dynamics
Pharmaceutical-grade purity mandates are compressing supply eligibility, bifurcating the PEG 3500 landscape between certified excipient suppliers and commodity glycol producers facing exclusion from drug formulation supply chains.
Growth Catalysts
- USP-NF Monograph Revisions:Updated United States Pharmacopeia standards for peroxide and endotoxin limits are disqualifying uncertified producers and consolidating demand among qualified suppliers.
- India's Generic Drug Export Engine:Domestic formulation manufacturers scaling output for regulated markets are pulling pharmaceutical-grade PEG 3500 through dedicated supply agreements with local glycol producers.
- Aqueous Drug Delivery Systems:Liquid PEG 3500 is gaining preference in biologic injectable formulations where solubility enhancement and viscosity control prove critical.
Market Restraints
- Ethylene Oxide Feedstock Volatility:Crude oil-linked ethylene pricing transmits directly to PEG 3500 production economics, compressing margins for non-integrated manufacturers.
- REACH Registration Burden:European Chemicals Agency substance registration thresholds and documentation requirements impose fixed compliance costs that disadvantage smaller volume producers.
- Propylene Glycol Substitution:Industrial lubricant and coolant applications are migrating to propylene glycol alternatives where freeze-point depression and lower toxicity specifications permit.
Strategic Opportunities
- Bioconjugation Chemistry:PEGylation of therapeutic proteins and lipid nanoparticles is opening high-value niches for activated PEG 3500 derivatives in mRNA delivery systems.
- EU Green Deal Carbon Tracking:Early adopters documenting Scope 3 emissions across ethylene oxide supply chains are securing preferred-supplier status with sustainability-conscious pharmaceutical formulators.
- Direct Procurement Platforms:API manufacturers are bypassing traditional distributors to contract directly with certified glycol producers, compressing channel margins and improving lot traceability.
Industry Challenges
- Endotoxin Control Expertise:Pharmaceutical-grade production requires specialized cleanroom infrastructure and pyrogen testing capabilities that commodity producers lack.
- Multi-Jurisdiction Certification Overlap:Simultaneous compliance with FDA excipient guidelines, EMA quality documentation, and CDSCO import requirements extends approval timelines for new supply relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PEG 3500 Market |
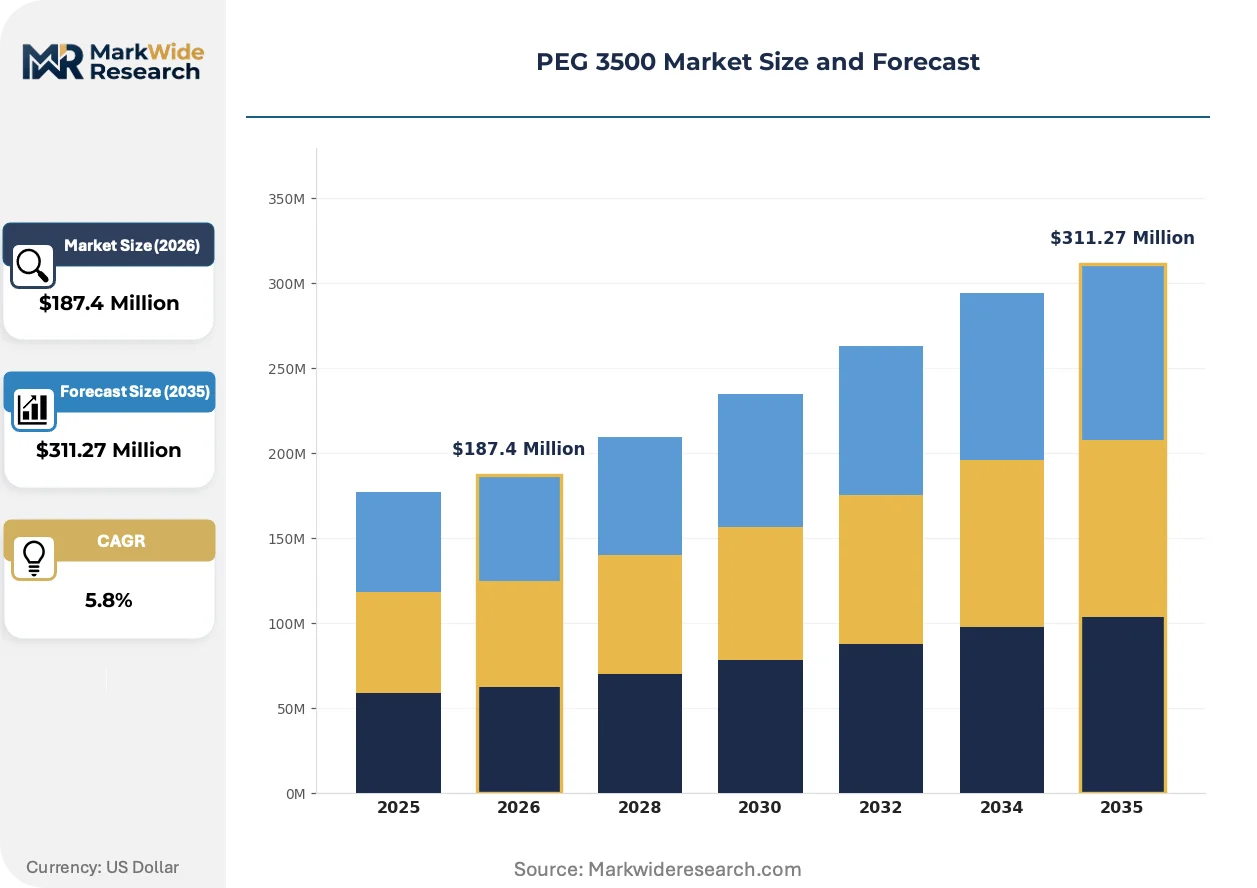
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Granule, Flake End Use Industry: Pharmaceuticals, Cosmetics, Food, Personal Care Packaging Type: Drum, Bag, Bottle, Tote Grade: Pharma Grade, Food Grade, Industrial Grade, Technical Grade |
| Companies Covered | Dow Chemical Company, BASF SE, Lotte Chemical Corporation, India Glycols Limited, Clariant AG, Croda International Plc, SABIC, Huntsman Corporation, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PEG 3500 Market Evolving Landscape
Continuous processing technologies and sustainability-linked procurement criteria are reconfiguring how PEG 3500 is manufactured, validated, and contracted across pharmaceutical supply chains.
Activated PEG 3500 derivatives with functionalized terminal groups are expanding into biopharma conjugation workflows. Contract development and manufacturing organizations are adopting these reagents at accelerating pace for antibody-drug conjugate and lipid nanoparticle programs. This chemistry is expanding into therapeutic categories previously served by lower-molecular-weight PEGs, compressing the addressable market for traditional grades.
REACH substance registration thresholds and evolving endpoint documentation requirements are tightening purity benchmarks for polyethylene glycol derivatives entering European pharmaceutical supply chains. ECHA scrutiny of ethylene oxide residual limits is forcing reformulation of polymerization protocols. Suppliers with Ludwigshafen and Antwerp production assets are responding with dedicated pharma-grade lines and enhanced analytical certification packages.
Formulation developers are consolidating supplier relationships around single-source certified producers with documented audit trails. Large generic drug manufacturers in India are replacing spot-market purchases with multi-year supply agreements incorporating quality and sustainability KPIs. This concentration is most visible in Mumbai and Hyderabad manufacturing clusters serving USFDA-inspected facilities.
PEG 3500 Market Segmentation
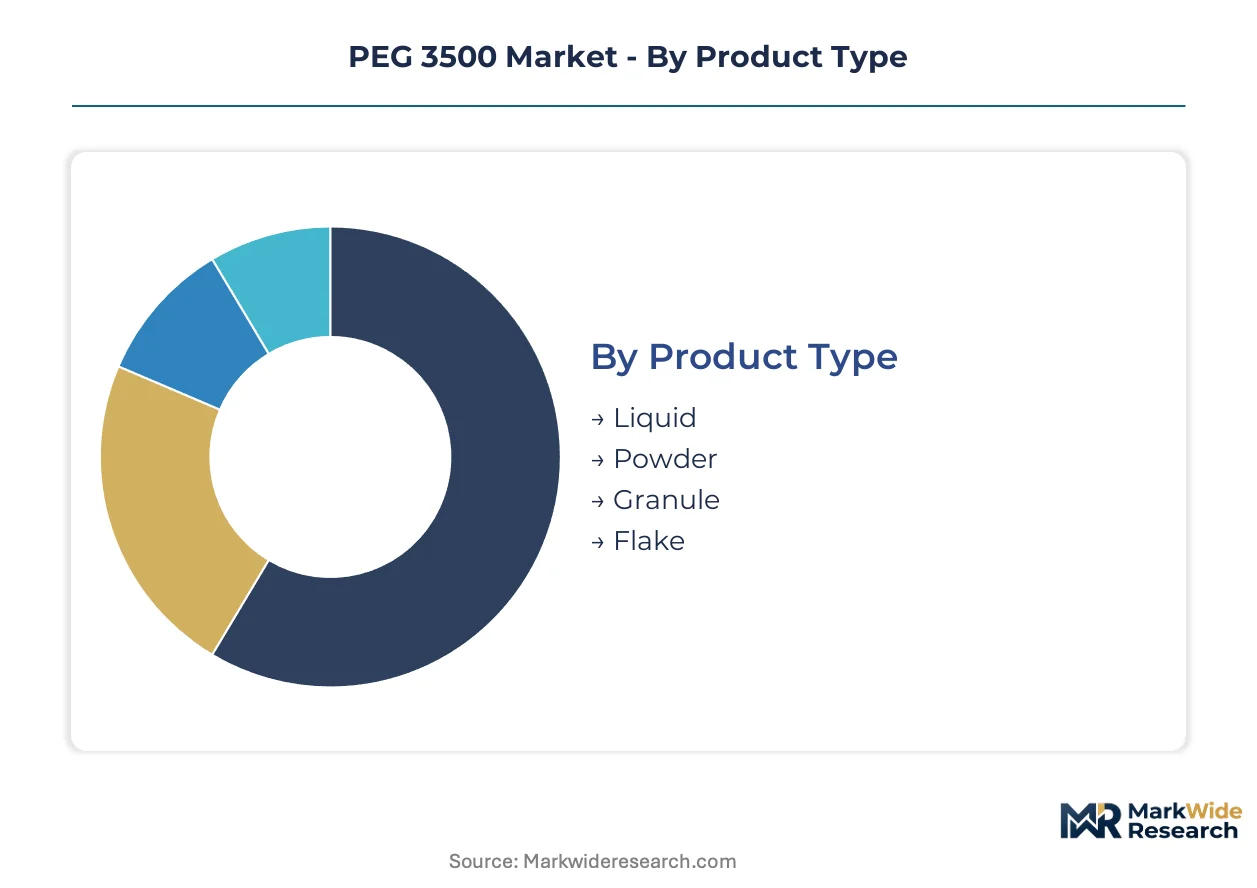
Formulation developers select PEG 3500 variants based on handling characteristics, purity thresholds, and regulatory compliance requirements. Each segment carries distinct margin structures and certification burdens that reshape supplier economics.
Product Type:
Manufacturers upgrade from solid formats to liquid handling systems where aqueous solubility and dosing precision dominate formulation workflows.
- Liquid:Aqueous solution format with viscosity optimized for injectable drug delivery and continuous processing lines. Demand concentrates in Hyderabad and Mumbai pharmaceutical clusters serving USFDA-inspected facilities, driven by biologic solubility enhancement requirements.
- Powder:Spray-dried particulate with controlled moisture content for solid dosage manufacturing. Adoption is climbing fastest in Indian generic export facilities where powder flowability and tablet compression uniformity prove critical.
- Granule:Agglomerated particles with reduced dusting characteristics for high-shear mixing operations.
- Flake:Cast solid format with slow dissolution kinetics for topical ointment bases and controlled-release matrices.
Liquid sits at the top of the volume ranking, with Powder climbing the fastest.
End Use Industry:
Customer procurement patterns split between regulated pharmaceutical channels demanding audit trails and personal care buyers prioritizing cost efficiency.
- Pharmaceuticals:Excipient applications governed by USP-NF monographs and FDA IIG listings for oral and parenteral formulations. Volume concentrates in CDSCO-regulated Indian facilities exporting to regulated markets, constrained by endotoxin and peroxide specification tightening.
- Cosmetics:Humectant and emulsifier functions in skincare and color cosmetic formulations.
- Food:Antifoam and coating applications under FSSAI and FDA food additive regulations.
- Personal Care:Toothpaste bases and hair conditioning agents with milder purity requirements than pharmaceutical grades.
Pharmaceuticals commands the deepest margin pool, with Cosmetics expanding most quickly in Southeast Asian manufacturing hubs.
Packaging Type:
Container selection tracks batch size economics and cleanroom handling protocols across formulation facility scales.
- Drum:Standard 200-liter steel containers for bulk pharmaceutical manufacturing with nitrogen blanket options.
- Bag:Flexible intermediate bulk containers with liner systems for powder and flake formats.
- Bottle:Laboratory and pilot-scale packaging for R&D sampling and clinical trial material supply.
- Tote:Intermediate volume disposable containers reducing cleaning validation burdens in multi-product facilities.
Drum formats dominate current procurement volumes, with Tote systems gaining share fastest among contract manufacturing organizations.
Grade:
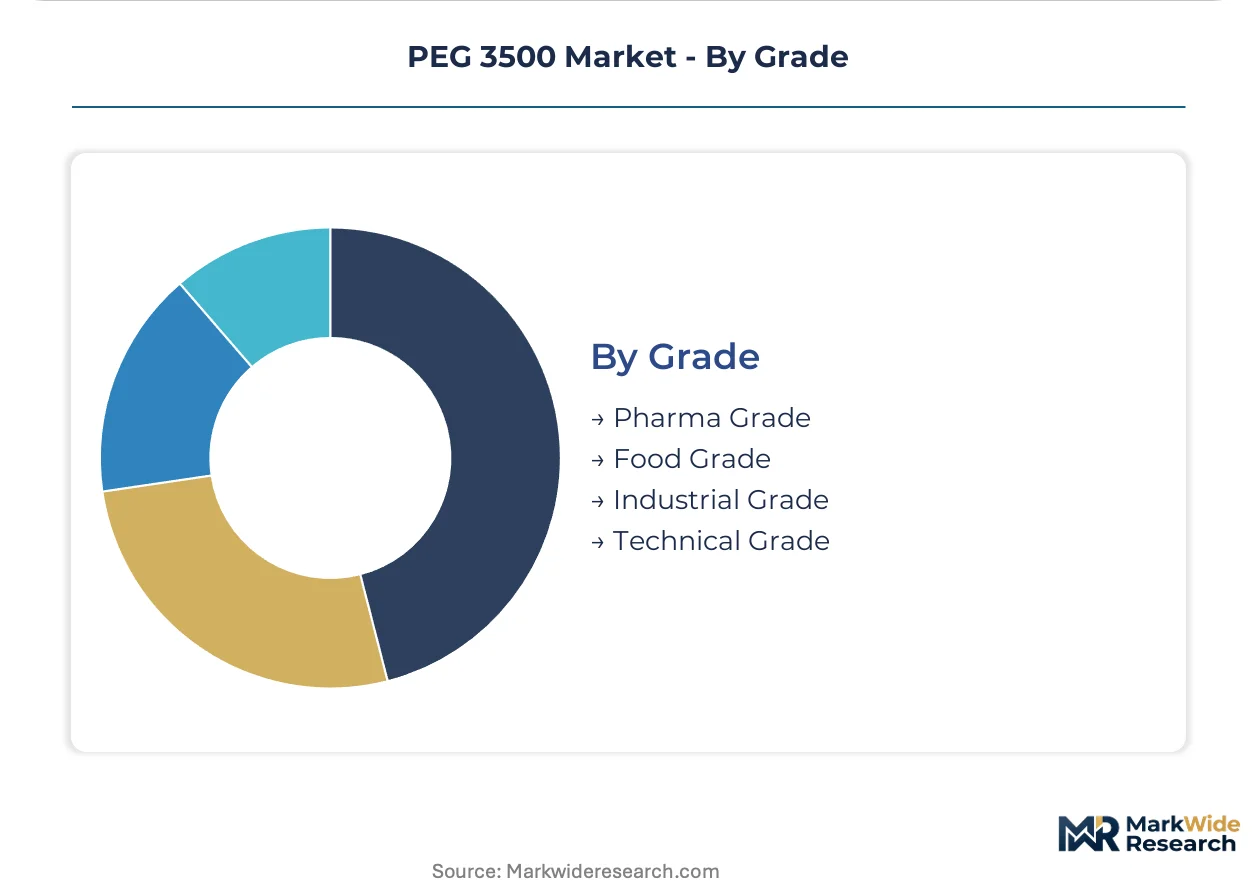
Certification tiers separate suppliers capable of pharmaceutical documentation from commodity producers facing exclusion from drug supply chains.
- Pharma Grade:Endotoxin-tested, peroxide-controlled material with batch-specific CoA documentation and IPEC-PQG GMP compliance. Demand aggregates with EMA and FDA-registered manufacturers in Ludwigshafen and Antwerp, pressured by REACH substance registration thresholds and evolving residual solvent limits.
- Food Grade:FSSAI and FDA food additive compliance with heavy metal and microbial specifications.
- Industrial Grade:Lubricant and coolant applications where propylene glycol substitution is eroding traditional PEG 3500 positions.
- Technical Grade:Lowest purity tier for adhesive and textile processing with minimal regulatory documentation.
Pharma Grade sits at the top of the value ranking, with Food Grade climbing the fastest amid clean-label formulation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad and Mumbai pharmaceutical clusters pull disproportionate PEG 3500 volumes through dedicated supply agreements with domestic glycol producers. Regulatory divergence between FDA purity standards and emerging EMA sustainability disclosure rules reshapes capacity allocation across grade tiers.
United States
Injectable biologic formulations drive liquid PEG 3500 consumption through Boston and Research Triangle Park manufacturing hubs. FDA excipient guideline revisions tighten peroxide and endotoxin specifications, disqualifying uncertified suppliers from drug formulation supply chains. New Jersey and Puerto Rico facilities consolidate procurement around single-source certified producers with documented audit trails.
Germany
Ludwigshafen production assets anchor European pharmaceutical-grade supply with enhanced analytical certification packages responding to ECHA scrutiny. REACH substance registration thresholds and evolving endpoint documentation requirements pressure reformulation of polymerization protocols. Antwerp-connected distribution networks serve EMA-registered manufacturers with dedicated pharma-grade lines.
India
Domestic generic drug export engines in Hyderabad and Mumbai scale pharmaceutical-grade PEG 3500 output through CDSCO-regulated facilities serving USFDA-inspected destinations. Multi-year supply agreements replace spot-market purchases with quality and sustainability KPIs. Gujarat-based glycol producers expand capacity to capture formulation manufacturing growth.
China
Yangtze River Delta chemical parks concentrate industrial-grade PEG 3500 production facing propylene glycol substitution in lubricant applications. NMPA alignment with USP-NF monographs enables selective pharma-grade qualification for export-oriented facilities. Dual carbon goals pressure ethylene oxide feedstock documentation for European pharmaceutical supply chain access.
Switzerland
Basel-centered biopharma conjugation workflows absorb activated PEG 3500 derivatives for antibody-drug conjugate programs. Swissmedic quality documentation requirements exceed standard EU thresholds, preserving premium economics for certified suppliers. Geneva-based procurement platforms facilitate direct API manufacturer contracting with certified glycol producers.
PEG 3500 Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated petrochemical majors and specialized excipient suppliers race to capture pharma-grade certification premiums. The vendor base splits between ethylene oxide-integrated conglomerates with captive feedstock economics and regional specialists with deep pyrogen control expertise. Three archetypes define positioning: integrated petrochemical majors, pharmaceutical-grade certification specialists, and regional glycol producers scaling for generic export markets. M&A activity concentrates on activated PEG derivative capabilities, while backward integration into ethylene oxide supply secures margin discipline.
Within the integrated petrochemical tier, Dow Chemical Company and BASF SE exemplify scale-driven positioning through captive ethylene oxide supply chains and Ludwigshafen-based pharma-grade certification depth. Croda International Plc occupies the specialization vector, representing high-purity lipid and glycol conjugate expertise for biopharma clients. Among Asia-Pacific-based suppliers, Lotte Chemical Corporation and India Glycols Limited sit within the regional scale archetype, leveraging domestic formulation manufacturing growth and export-oriented generic drug demand.
| Leading Market Players |
|---|
| Dow Chemical Company |
| BASF SE |
| Lotte Chemical Corporation |
| India Glycols Limited |
| Clariant AG |
| Croda International Plc |
| SABIC |
| Huntsman Corporation |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
Indian generic drug manufacturers consolidating procurement around single-source certified producers have compressed spot-market liquidity and shifted PEG 3500 pricing toward long-term contract structures with embedded quality and sustainability KPIs. This buyer concentration amplifies margin pressure on non-integrated commodity producers while rewarding ethylene oxide-integrated suppliers with captive feedstock economics.
Pricing Analysis
Ethylene oxide feedstock volatility transmits directly to PEG 3500 production economics through crude oil-linked ethylene pricing, compressing margins for non-integrated manufacturers. Three-tier pricing structure across pharma, food, and industrial grades separates certified excipient suppliers from commodity producers. Cost compression in industrial-grade tiers is intensifying because propylene glycol substitution erodes traditional lubricant applications. Generic drug manufacturers in India exhibit the highest price sensitivity, while Swiss biopharma conjugation workflows demonstrate the lowest due to stringent Swissmedic documentation requirements.
Supply Chain Analysis
Reverse-logistics flows for pharmaceutical-grade PEG 3500 remain minimal given batch-specific CoA documentation and pyrogen control requirements that prevent material reuse. Supply concentrates in Germany, India, and China, with Ludwigshafen and Antwerp assets serving EMA-registered manufacturers and Gujarat-based producers scaling for USFDA-inspected export destinations. Raw material dependencies center on ethylene oxide, ethylene glycol initiators, and alkaline catalysts. Single-source vulnerability characterizes pharmaceutical-grade supply chains where endotoxin control expertise limits qualified producer pools. Distribution runs through direct procurement platforms that bypass traditional distributors and improve lot traceability for API manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The PEG 3500 market functions as a geographic-arbitrage play between REACH-registered European supply and CDSCO-regulated Indian manufacturing, where compliance cost differentials of 15-25 percentage points separate certified and uncertified producer economics.
For Market Incumbents: Anchor pharmaceutical-grade certification depth against propylene glycol substitution threats in industrial lubricant applications by expanding captive ethylene oxide supply chains and securing multi-year supply agreements with Mumbai and Hyderabad formulation clusters. Prioritize Scope 3 emissions documentation to meet EU Green Deal procurement criteria and defend margin position against emerging regional glycol producers scaling capacity. For New Entrants and Emerging Players: Direct procurement platforms offer the most penetrable channel route for qualified producers seeking to bypass distributor margins and establish direct relationships with API manufacturers. Target activated PEG 3500 derivative niches serving antibody-drug conjugate and lipid nanoparticle programs in Basel-centered biopharma workflows. Pursue CDSCO registration pathways for export-oriented Indian generic drug facilities as the fastest qualification route. For Investors and Strategic Acquirers: Integrated petrochemical majors are the most active acquirer in this space, seeking activated PEG derivative capabilities to capture bioconjugation chemistry premiums. Long-term viability hinges on sustainability-linked procurement criteria becoming standard across pharmaceutical formulators. Monitor EMA-FDA regulatory divergence on residual solvent limits as the critical inflection signal for capacity allocation decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Dow and BASF leverage captive feedstock to sustain cost discipline across glycol polymerization. |
| Pharma-Grade Certification Investment | REACH substance registration thresholds reward early adopters with preferred-supplier status in Ludwigshafen. |
| Activated PEG Derivative Development | Bioconjugation chemistry opens high-value niches in mRNA delivery systems and lipid nanoparticles. |
| Direct Procurement Platform Launch | API manufacturers bypass distributors to contract directly with certified glycol producers for improved traceability. |
| Scope 3 Emissions Documentation | EU Green Deal carbon tracking requirements pressure producers to document petrochemical feedstock emissions. |
Research Methodology
Bottom-up pharmaceutical formulation modeling reconciled against top-down ethylene oxide supply tracking forms the analytical core of this study. Primary interviews with drug development executives, regulatory affairs leads at CDSCO and FDA-registered facilities, procurement managers at Indian generic manufacturers, and technical R&D directors at glycol producers combined with secondary validation from USP-NF monograph revisions, REACH substance registration databases, FDA IIG listings, and SEC filings from integrated petrochemical majors. This triangulation ensures demand-side consumption patterns align with supply-side capacity announcements and certification timelines.
Input-output matrix framing connects ethylene oxide feedstock availability to PEG 3500 grade-tier production across the analysis window. Segmentation dimensions modeled include product type (liquid, powder, flake), grade tier (pharma, food, industrial), end-use industry (pharmaceuticals, cosmetics, personal care), and regional production hub (Ludwigshafen, Antwerp, Gujarat, Yangtze River Delta). CAGRs derive from regression analysis against pharmaceutical excipient demand drivers and ethylene pricing correlation models. Forecast inputs incorporate USP-NF monograph revision implementation timelines and CDSCO inspection capacity expansion for USFDA-aligned facilities.
The model assumes a particular technology adoption path for continuous processing in pharmaceutical-grade manufacturing; alternative pathways for batch-based pyrogen control would alter the outlook. Forecasts reflect assumptions about REACH-FDA regulatory convergence and sustained Indian generic drug export momentum. Practitioners should monitor ECHA scrutiny of ethylene oxide residual limits and propylene glycol substitution rates in industrial applications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyphenylene Market
Polymers & Resins
Global PEEK Market
Polymers & Resins
Chlorinated Polyolefins Market
Polymers & Resins
Hydrogenated Styrene Block Copolymers Market
Polymers & Resins
Global Chlorinated Polyethylene Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
China Geopolymer Market
Polymers & Resins
Polyether Ketone (PEK) Market
Polymers & Resins
Thermoplastic Polyester Engineering Resin (TPER) Market
Polymers & Resins
Polyphenylene Oxide (PPO) Market
Polymers & Resins
Polydicyclopentadiene (Pdcpd) Market
Polymers & Resins
Polycarbonate Diols Market
Polymers & Resins
Photopolymers Market
Polymers & Resins
Nonchlorinated Polyolefins Market
Polymers & Resins
Medical Polyoxymethylene (POM) Market
Polymers & Resins
Polyvinyl Butyral (PVB) Market