
 Welan Gum Market | 2026-2036
Welan Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Welan Gum Market Analytics
Oilfield drilling fluid formulation is repositioning welan gum demand away from traditional construction applications. CP Kelco U.S. dominates North American supply chains through captive fermentation capacity and direct oilfield service relationships. Hebei Xinhe Biochemical Co. Ltd anchors Chinese export volumes with cost-optimized industrial-grade production. DSM leverages dual food-grade and pharmaceutical-grade certifications to sustain premium positioning in European nutrition markets.
Welan gum is a high-molecular-weight extracellular polysaccharide produced by Sphingomonas elodea fermentation, composed of repeating tetrasaccharide units with L-rhamnose, D-glucose, D-glucuronic acid, and L-mannose, functioning primarily as a temperature-stable viscosifier and suspension agent across industrial and food systems. Powder formulations lead volume consumption due to extended shelf stability and ease of bulk handling in oilfield logistics, while pharmaceutical-grade material commands the deepest margin pools driven by injectable and controlled-release excipient validation requirements. Food-grade welan gum competes primarily on texture modification in dairy alternatives and shelf-stable sauces where thermal processing demands exceed xanthan gum performance thresholds.
The FDA's food additive regulations and EPA's oilfield chemical discharge frameworks shape product purity benchmarks and environmental compliance costs for U.S. market participants, while China's SAMR and GB standards govern domestic production licensing and export certification validity. REACH registration in Europe imposes full toxicological dossier requirements that filter smaller suppliers from direct EU access. Stakeholders must monitor fermentation yield improvements and alternative polysaccharide substitution threats as the primary variables affecting long-term contract economics and capacity planning decisions.
Market Dynamics
Oilfield operators are consolidating procurement around fermentation-derived rheology modifiers that tolerate calcium chloride brines above 150°C, forcing suppliers to validate batch consistency under API RP 13I protocols.
Growth Catalysts
- Deepwater drilling resurgence:Exploration campaigns in the Gulf of Mexico and offshore Brazil require welan gum's thermal stability in synthetic-based mud systems. Operators specify it for hole-cleaning efficiency in extended-reach laterals.
- EU F-Gas Regulation phase-down:Refrigeration lubricant formulators are substituting welan gum for synthetic thickeners with higher global warming potential. This creates pull from compressor OEMs serving cold chain logistics.
- Cell-cultured meat scaffold demand:Bioprocess engineers are validating welan gum as a temperature-stable hydrogel for muscle tissue engineering. Singapore's food safety authority has cleared pilot-scale trials.
Market Restraints
- Fermentation substrate cost volatility:Corn syrup and yeast extract prices swing with agricultural commodity cycles. Chinese producers face margin compression when glucose feedstock spikes during planting season disruptions.
- Single-source supply concentration:Food-grade certification requires specific Sphingomonas elodea strain documentation. European buyers depend on two validated fermentation facilities for pharmaceutical-grade material.
- Xanthan gum substitution in construction:Dry-mix mortar producers are reverting to xanthan for standard-grade applications where thermal stability is not specified. This compresses volume in building materials.
Strategic Opportunities
- Saudi Arabia localization mandates:Vision 2030 industrial content rules require oilfield chemical manufacturing within the Kingdom. Joint ventures with local fermentation partners unlock Aramco drilling contract eligibility.
- Lithium brine extraction thickening:Direct lithium extraction operations in Chile's Atacama are testing welan gum for brine viscosity control during solar evaporation. This application is absent from current supplier portfolios.
- Carbon capture solvent formulation:Amine-based CO2 capture systems need thickeners that survive oxidative degradation. Welan gum's stability profile matches solvent regeneration loop conditions.
Industry Challenges
- Pharmaceutical-grade validation timelines:USP-NF excipient certification requires 18-24 months of stability data. Accelerated aging protocols do not satisfy FDA Type II drug master file requirements.
- Fermentation yield optimization talent scarcity:Industrial microbiologists with Sphingomonas strain engineering experience command premium compensation. Chinese and Korean biotech firms are recruiting from the same limited pool.
- REACH dossier maintenance burden:ECHA's updated tonnage band reporting demands fresh toxicological studies every five years. Smaller exporters lack internal regulatory affairs capacity to manage submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welan Gum Market |
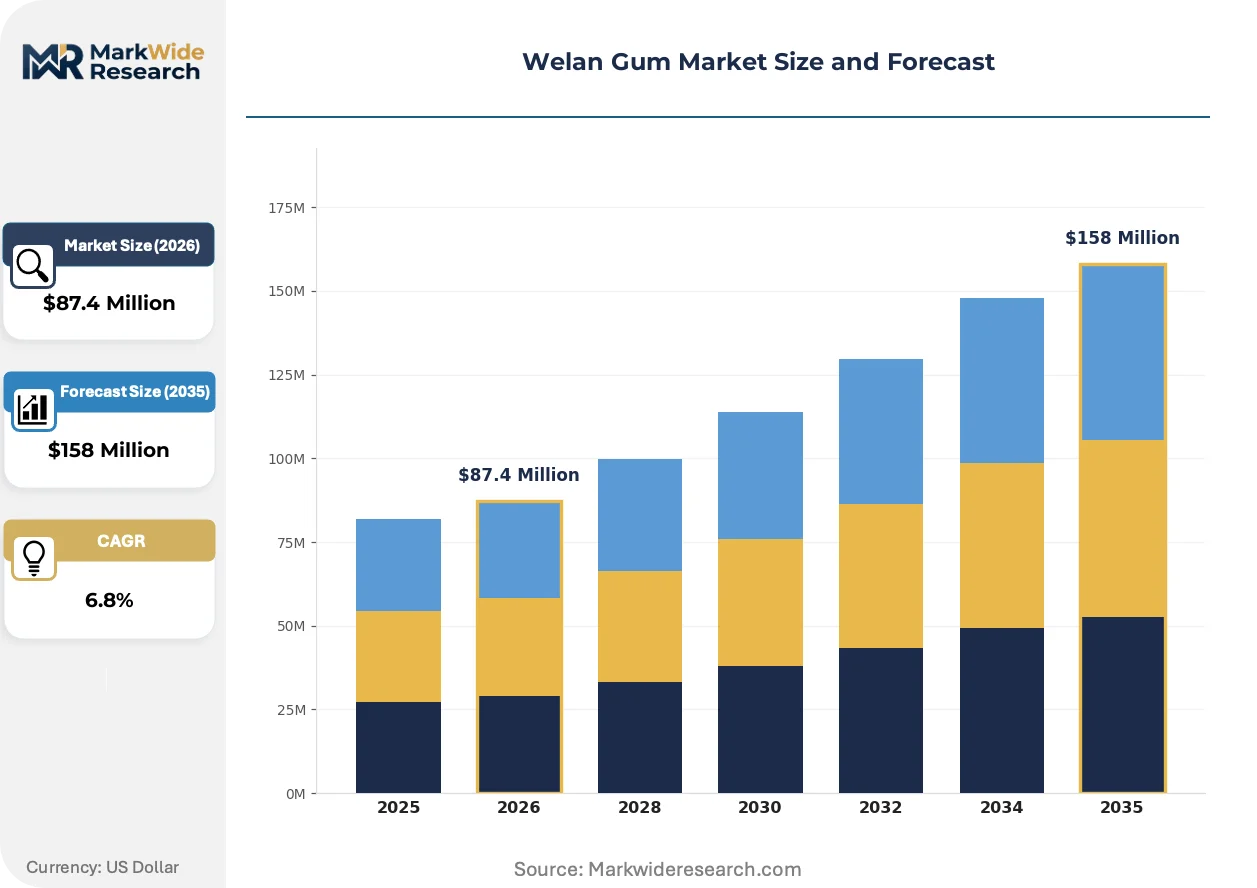
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $158 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Granules, Beads End Use Industry: Food & Beverage, Pharmaceuticals, Cosmetics, Oilfield Packaging Type: Bags, Drums, Totes, Plastics Grade: Food Grade, Pharmaceutical Grade, Industrial Grade, Technical Grade |
| Companies Covered | DSM, CP Kelco U.S., Sidere Technology Inc, Sancai Industry Co. Ltd, Hebei Ebio Biotechnology Co. Ltd, AVANSCHEM, Hebei Xinhe Biochemical Co. Ltd, Royal DSM N.V., Jinan Boss Chemical Industry Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welan Gum Market Evolving Landscape
Fermentation process control and downstream purification advances are compressing cost structures while regulatory divergence between jurisdictions is fragmenting product grade specifications.
Continuous fermentation with real-time rheology monitoring is overtaking batch processing in new capacity installations. Oilfield chemical distributors in Texas and Alberta are specifying tank-farm delivery of live-culture broth to reduce powder handling costs. This shift is enabling just-in-time inventory models that reduce working capital requirements for drilling contractors.
China's SAMR has tightened GB 1886.98-2024 purity thresholds for food-grade welan gum exports. European importers must now submit third-party heavy metal testing for every container. The certification burden falls hardest on industrial-grade producers seeking to upgrade into nutrition applications.
Buyers are consolidating annual contracts around performance-based specifications rather than historical supplier relationships. Major oilfield service companies in the Permian Basin now require guaranteed viscosity retention after 72-hour hot-roll testing. This procurement compression is disqualifying smaller fermentation houses lacking in-house application laboratories.
Welan Gum Market Segmentation
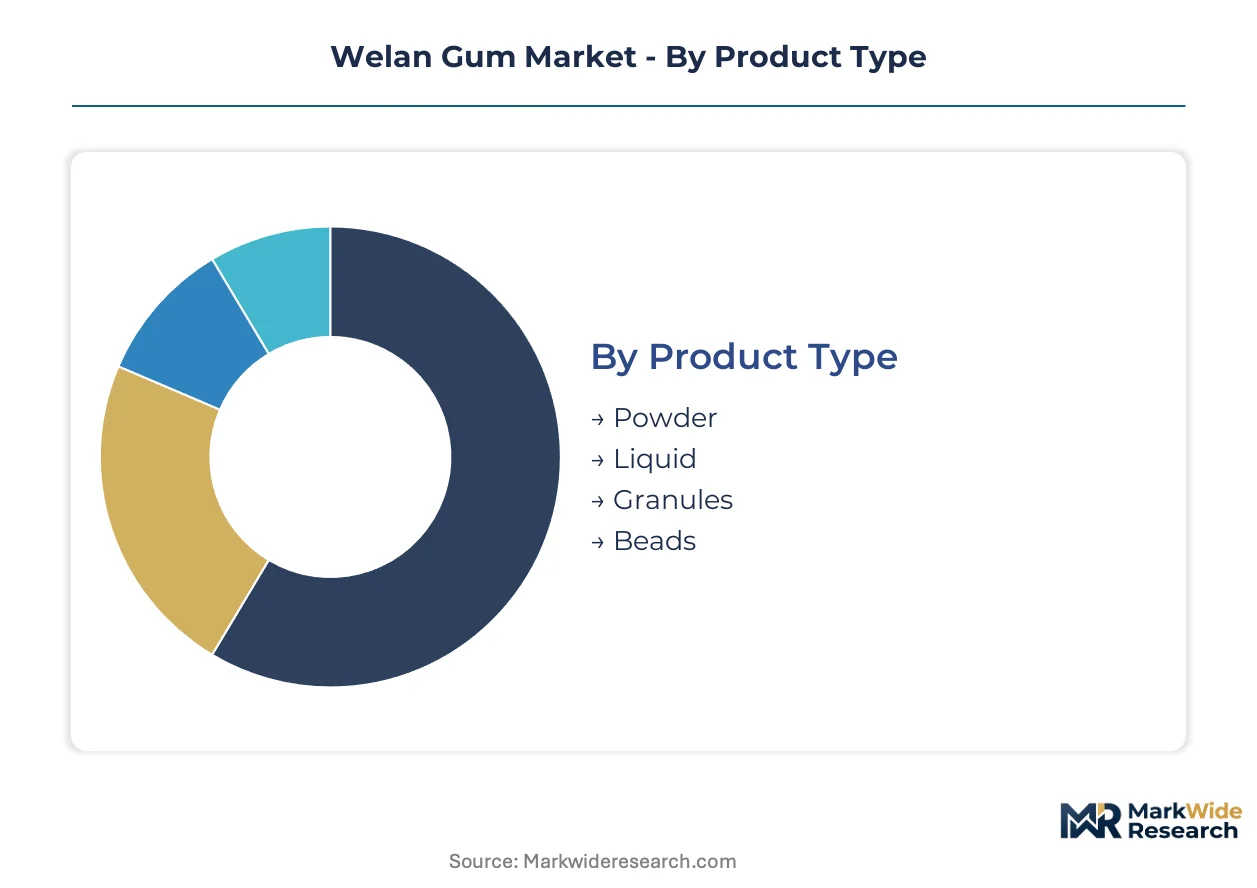
Welan gum buyers segment procurement by performance specification and regulatory compliance tier rather than commodity pricing. Oilfield service companies, food manufacturers, and pharmaceutical formulators each maintain distinct qualification protocols that reshape supplier economics across grade and format categories.
Product Type:
Logistics cost and handling infrastructure drive format selection more than unit pricing.
- Powder:Spray-dried particles with moisture content below 10% enable extended shelf stability in humid climates. Demand concentrates in Texas and Alberta oilfield supply chains where bulk pneumatic handling reduces labor costs.
- Liquid:Live-culture fermentation broth delivered in ISO tank containers eliminates powder reconstitution steps. Permian Basin drilling contractors are adopting tank-farm delivery models to cut hot-mix preparation time.
- Granules:Agglomerated particles improve flowability in automated dry-mix mortar plants serving Saudi construction projects.
- Beads:Spherical particles manufactured via prilling technology target controlled-release pharmaceutical excipient applications in European markets.
Volume sits with powder; growth tilts toward liquid.
End Use Industry:
Application temperature tolerance separates premium-grade demand from commodity substitution.
- Oilfield:Synthetic-based mud systems require viscosity retention above 150°C in calcium chloride brines. Gulf of Mexico and offshore Brazil exploration campaigns specify welan gum for extended-reach lateral cleaning efficiency.
- Pharmaceuticals:USP-NF excipient certification demands 18-24 month stability data for injectable and controlled-release formulations. FDA Type II drug master file requirements filter supplier pools to validated fermentation facilities.
- Food & Beverage:China's SAMR GB 1886.98-2024 purity thresholds and EU heavy metal testing requirements compress margins for industrial-grade upgraders.
- Cosmetics:Temperature-stable thickening in emulsion systems competes with xanthan and scleroglucan in Korean skincare manufacturing.
Revenue concentrates in oilfield; expansion is steepest in pharmaceuticals.
Packaging Type:
Handling automation and contamination risk shape procurement specifications.
- Bags:Multi-wall paper sacks with polyethylene liners dominate food-grade distribution to dairy alternative processors.
- Drums:Steel containers with epoxy phenolic lining serve pharmaceutical-grade shipments requiring inert atmosphere preservation.
- Totes:Intermediate bulk containers enable just-in-time delivery to oilfield chemical blending plants in North Dakota shale basins.
- Plastics:High-density polyethylene pails target laboratory-scale cosmetic formulation sampling.
Unit economics favor totes at scale; drums command premium positioning.
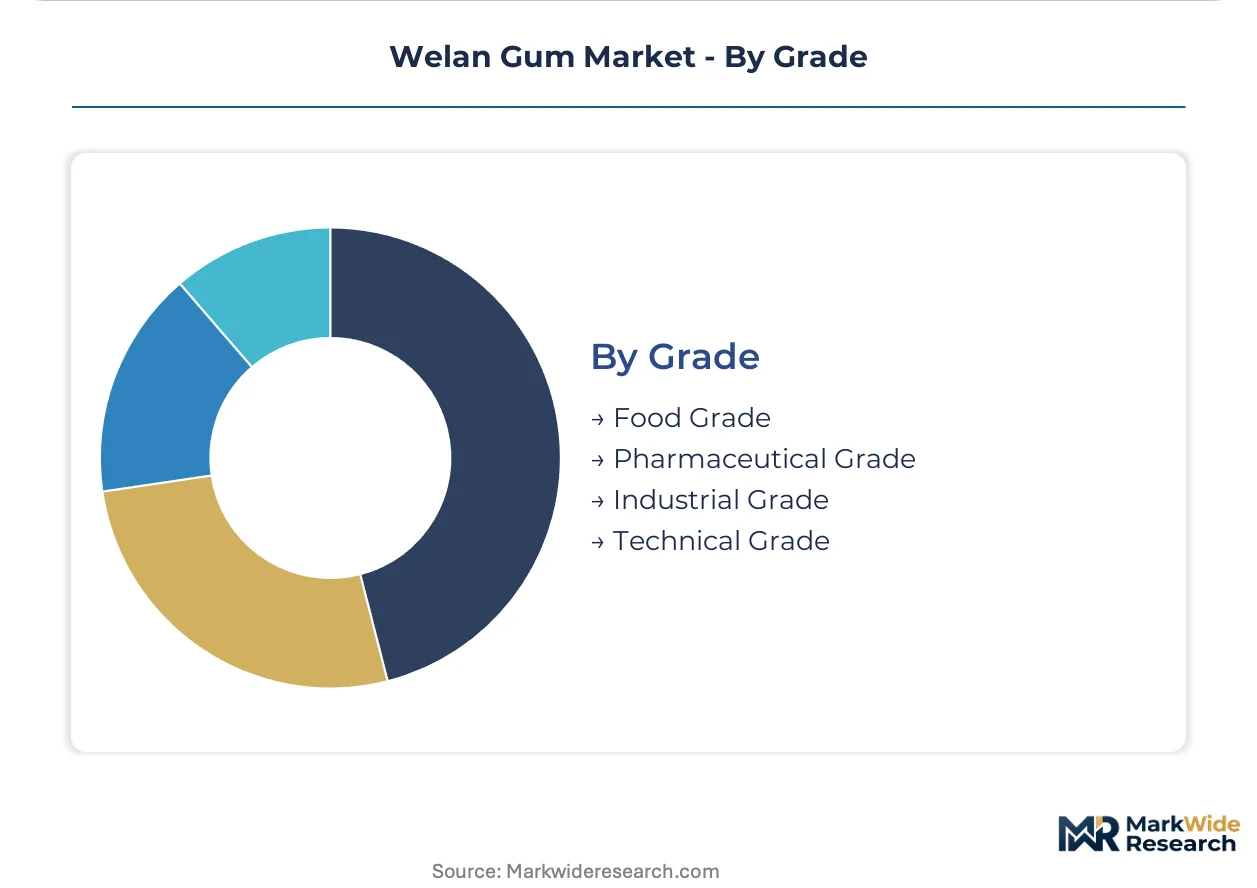
Grade:
Certification depth determines accessible end-use markets and margin structure.
- Technical Grade:API RP 13I protocol compliance suffices for drilling fluid applications without food or pharmaceutical contact. Hebei Xinhe Biochemical anchors supply through cost-optimized fermentation.
- Pharmaceutical Grade:Full toxicological dossier submission to ECHA REACH and USP-NF monograph alignment creates dual-hemisphere access barriers. DSM sustains premium positioning through strain documentation and GMP fermentation.
- Food Grade:Dual certification under FDA 21 CFR 172.655 and EU 1129/2011 enables cross-border dairy and sauce applications.
- Industrial Grade:Construction adhesive and textile printing thickener applications face xanthan substitution pressure where thermal stability is unspecified.
Shipments cluster at technical grade; value accrues to pharmaceutical grade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Chinese fermentation corridors while consumption tilts toward North American oilfield basins and European pharmaceutical corridors. This geographic mismatch shapes trade flows and regulatory compliance investments across supplier networks.
United States
Permian Basin drilling contractors drive technical-grade consumption through synthetic-based mud specifications. EPA oilfield chemical discharge frameworks enforce batch testing protocols for service companies operating in federal waters. Houston anchors the largest distribution hub, with tank-farm delivery models reducing powder handling costs for West Texas operators.
China
Hebei and Shandong provinces host cost-optimized fermentation capacity serving industrial-grade export markets. SAMR GB 1886.98-2024 purity thresholds now govern food-grade export certification, with third-party heavy metal testing mandatory for EU-bound containers. Zhengzhou chemical clusters are upgrading strain documentation capabilities to access pharmaceutical-grade segments.
Germany
REACH registration requirements filter supplier pools through full toxicological dossier demands, with ECHA tonnage band reporting refreshed every five years. Frankfurt-Rhine-Main pharmaceutical corridors source USP-NF certified material for injectable excipient applications. Bavarian bioprocess engineering firms are piloting continuous fermentation controls for premium-grade output.
Saudi Arabia
Vision 2030 localization mandates require oilfield chemical manufacturing within the Kingdom for Aramco drilling contract eligibility. SFDA import certification protocols align with API RP 13I validation standards for technical-grade material. Eastern Province industrial cities are attracting joint venture proposals from Asian fermentation partners seeking regional production bases.
Brazil
Offshore pre-salt exploration campaigns specify welan gum for extended-reach lateral cleaning in high-temperature synthetic mud systems. ANVISA pharmaceutical excipient regulations create compliance barriers for unvalidated fermentation sources. Rio de Janeiro service company clusters are consolidating procurement around performance-based viscosity retention guarantees.
Welan Gum Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade certification tiers, while cost-optimized industrial-grade producers compete on fermentation yield and substrate sourcing. The structure splits between strain-documented GMP facilities and commodity-grade exporters serving construction and oilfield applications. Three archetypes dominate: vertically integrated biotech conglomerates with dual food-pharma certifications, regional fermentation houses with captive oilfield service relationships, and industrial bioprocessors optimizing glucose feedstock conversion. Capacity expansion and regulatory dossier filing represent the dominant competitive moves, with smaller players facing exclusion from EU and US pharmaceutical channels.
Within the premium certification tier, DSM and Royal DSM N.V. exemplify dual-hemisphere regulatory positioning through REACH dossier maintenance and USP-NF alignment. CP Kelco U.S. anchors North American supply chains through direct oilfield service relationships and API protocol validation. Among Chinese industrial-grade exporters, Hebei Xinhe Biochemical Co. Ltd and Hebei Ebio Biotechnology Co. Ltd occupy positions defined by cost-optimized fermentation and SAMR export licensing. Sancai Industry Co. Ltd and Jinan Boss Chemical Industry Co. Ltd represent regional chemical distributors bridging technical-grade supply with construction and oilfield procurement channels. Sidere Technology Inc and AVANSCHEM sit within specialist trading and custom synthesis archetypes serving qualified material sourcing for formulation houses lacking direct fermentation access.
| Leading Market Players |
|---|
| DSM |
| CP Kelco U.S. |
| Sidere Technology Inc |
| Sancai Industry Co. Ltd |
| Hebei Ebio Biotechnology Co. Ltd |
| AVANSCHEM |
| Hebei Xinhe Biochemical Co. Ltd |
| Royal DSM N.V. |
| Jinan Boss Chemical Industry Co. Ltd |
| Others |
Value Network & Pricing Analysis
API RP 13I hot-roll testing mandates from Permian Basin drilling contractors are compressing supplier pools to fermentation houses with in-house application laboratories, forcing capacity investments that widen spreads between validated and unvalidated material.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as Gulf of Mexico operators pay up for guaranteed viscosity retention certificates within 30 days. Three-tier pricing structure across pharmaceutical, food, and technical grades separates USP-NF certified material commanding the deepest margins from industrial-grade product facing xanthan substitution pressure. Cost compression in technical-grade supply is intensifying because Hebei fermentation corridors optimize glucose feedstock conversion. Oilfield service companies show least price sensitivity due to performance-based procurement, while construction adhesive formulators remain most sensitive to unit economics.
Supply Chain Analysis
Dual-sourcing requirements from European pharmaceutical formulators mandate qualification at both DSM and CP Kelco U.S. facilities to mitigate single-source vulnerability. Production gravity centers on China, the United States, and Germany, with fermentation broth drawing from corn syrup and yeast extract agricultural commodities. Single-source vulnerability concentrates in Sphingomonas elodea strain documentation controlled by limited validated facilities. Distribution runs through Houston tank-farm terminals for Permian Basin just-in-time delivery and Frankfurt-Rhine-Main corridors for pharmaceutical-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. REACH registration dossier maintenance with ECHA creates a barrier-to-entry moat filtering smaller exporters from direct EU pharmaceutical access.
For Market Incumbents: Deepen strain documentation capabilities to defend pharmaceutical-grade positioning against emerging Korean biotech recruiters competing for Sphingomonas engineering talent. Anchor capacity expansion in Eastern Province industrial cities to capture Aramco drilling contract eligibility under Vision 2030 localization mandates. Prioritize continuous fermentation controls to compress cost structures against Chinese industrial-grade exporters. For New Entrants and Emerging Players: EU F-Gas Regulation phase-down opens a window for refrigeration lubricant thickener applications serving compressor OEMs in cold chain logistics. Target lithium brine extraction operations in Chile's Atacama testing welan gum for solar evaporation viscosity control, an application absent from incumbent portfolios. Lead with tank-farm delivery partnerships to bypass powder handling infrastructure requirements. For Investors and Strategic Acquirers: The window for entry favors dual-certified fermentation facilities with existing USP-NF and REACH alignment. Long-term viability hinges on regulatory dossier capacity rather than commodity scale. Watch for accelerated FDA Type II drug master file submissions as the inflection signal for pharmaceutical-grade supply tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glucose Feedstock | Corn syrup price volatility in Chinese agricultural cycles compresses margins for non-integrated producers. |
| Continuous Fermentation Scale-Up | Real-time rheology monitoring overtakes batch processing in new Permian Basin capacity installations. |
| Pharmaceutical-Grade Certification Investment | USP-NF excipient validation creates dual-hemisphere access barriers filtering commodity competitors. |
| Joint Venture Localization | Vision 2030 mandates in Saudi Arabia require Kingdom-based manufacturing for Aramco eligibility. |
| Alternative Application Development | Cell-cultured meat scaffold validation in Singapore opens bioprocess engineering revenue streams. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews with fermentation plant managers, oilfield procurement leads, pharmaceutical regulatory affairs directors, and bioprocess R&D heads. API RP 13I protocol documentation, SAMR GB 1886.98-2024 purity thresholds, and ECHA REACH dossier submissions provided compliance benchmarking. Bottom-up grade-tier volume estimates reconciled against top-down oilfield chemical consumption patterns.
Reconciliation of customs export volumes, fermentation capacity utilization surveys, and end-use procurement data shaped the analytical framework across the projection horizon. Segmentation dimensions spanned grade tier, end-use industry, packaging format, and regional production hub. CAGRs derived from elasticity modeling against drilling activity indices and pharmaceutical excipient demand curves. Strain yield improvements and alternative polysaccharide substitution threats served as primary forecast sensitivity inputs.
The model assumes a particular technology adoption path; alternative pathways for continuous fermentation with live-culture broth delivery would alter the outlook for powder format demand. Forecasts reflect assumptions around API drilling activity persistence and pharmaceutical-grade validation timeline stability. Deviation in SAMR export certification stringency or ECHA tonnage band reporting requirements would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Unsaturated Polyester Resins Market
Polymers & Resins
Global Bio-Based Polyethylene Market
Polymers & Resins
Global Epoxy Primer Market
Polymers & Resins
France Engineering Plastics Market
Polymers & Resins
Conditioning Polymers Market
Polymers & Resins
Melamine Formaldehyde Resin Powder Market
Polymers & Resins
Hair Styling Biopolymers Market
Polymers & Resins
Macroporous Strong Acid Cation Exchange Resin Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
Europe Polyvinyl Chloride (PVC) Market
Polymers & Resins
Global Polyethyleneimine Market
Polymers & Resins
Polymeric Sand Market
Polymers & Resins
Polyolefin Compound Market
Polymers & Resins
Polyether Polyols Market
Polymers & Resins
Middle East Fluoropolymer Market
Polymers & Resins
Biobased Polypropylene PP Size Market