
 Liquid Polybutadiene [LPBD] Market | 2026-2036
Liquid Polybutadiene [LPBD] Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Polybutadiene [LPBD] Market Foresight
South Korea is fragmenting LPBD supply influence as Kumho Petrochemical and LG Chem expand domestic reactor capacity. ARLANXEO leverages backward integration into butadiene feedstock across its European sites. JSR Corporation sustains technology leadership in solution-polymerized grades for specialty adhesive applications.
Liquid polybutadiene is a low-molecular-weight synthetic elastomer with terminal functional groups, typically manufactured via anionic or free-radical polymerization to viscosities ranging from hundreds to tens of thousands of centipoise, serving primarily as a reactive modifier for thermoset resins and rubber compounding. Low viscosity grades dominate volume consumption in adhesive formulations where processing speed governs line economics, while modified variants capture disproportionate margin pools in aerospace sealant specifications. The automotive end-user segment anchors bulk demand through tire and under-the-hood elastomer applications, though construction-grade emulsions represent the fastest-expanding consumption category.
REACH in Europe and K-REACH in South Korea govern residual monomer limits and substance registration, directly elevating compliance costs for non-specialty producers and advantaging firms with captive analytical capabilities. EPA New Chemicals program reviews in the United States constrain novel modified-grade introductions, extending commercialization timelines for reformulated products. Stakeholders must monitor evolving tire-labeling schemes and carbon-border adjustments, as these mechanisms will progressively sort suppliers by lifecycle data transparency rather than unit cost alone.
Market Dynamics
REACH residual monomer thresholds are compressing formulation flexibility across European tire and adhesive applications, forcing producers toward low-viscosity reactor grades with tighter process control.
Growth Catalysts
- High-performance tire compounding:Asian tire manufacturers are expanding LPBD procurement for advanced rubber formulations that improve wet grip and rolling resistance metrics under evolving tire-labeling schemes.
- REACH compliance differentiation:ECHA registration requirements advantage producers with captive analytical capabilities, creating procurement preference for registered suppliers in European adhesive markets.
- Aerospace sealant specifications:Terminal-functionalized grades command disproportionate margins in aviation applications where outgassing and thermal stability requirements exclude conventional modifiers.
Market Restraints
- Butadiene feedstock volatility:Crude-linked naphtha cracking economics transmit price instability to LPBD producers lacking backward integration into C4 olefin supply.
- South Korean supply concentration:Kumho Petrochemical and LG Chem reactor expansions are tightening regional availability for third-party offtake, elevating contract negotiation leverage for domestic majors.
- Silane-terminated polyurethane substitution:Moisture-cure sealant formulators in construction applications are displacing LPBD modifiers where ambient temperature curing governs application economics.
Strategic Opportunities
- India construction emulsions:BIS standards evolution for waterproofing membranes is opening specification windows for low-viscosity grades in infrastructure-grade formulations.
- Carbon-border adjustment preparation:EU importers are demanding lifecycle data transparency that rewards producers with verified low-carbon butadiene feedstock sourcing.
- UV-curable hybrid systems:Acrylate-LPBD oligomer convergence is enabling rapid-cure coatings for electronics assembly where thermal sensitivity excludes conventional thermal initiators.
Industry Challenges
- Anionic polymerization expertise scarcity:Solution-polymerized specialty grade production requires reactor engineering talent concentrated among Japanese and Korean technical staff.
- K-REACH substance notification timelines:MFDS-aligned registration procedures extend commercialization cycles for novel modified grades in South Korean adhesive markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Polybutadiene [LPBD] Market |
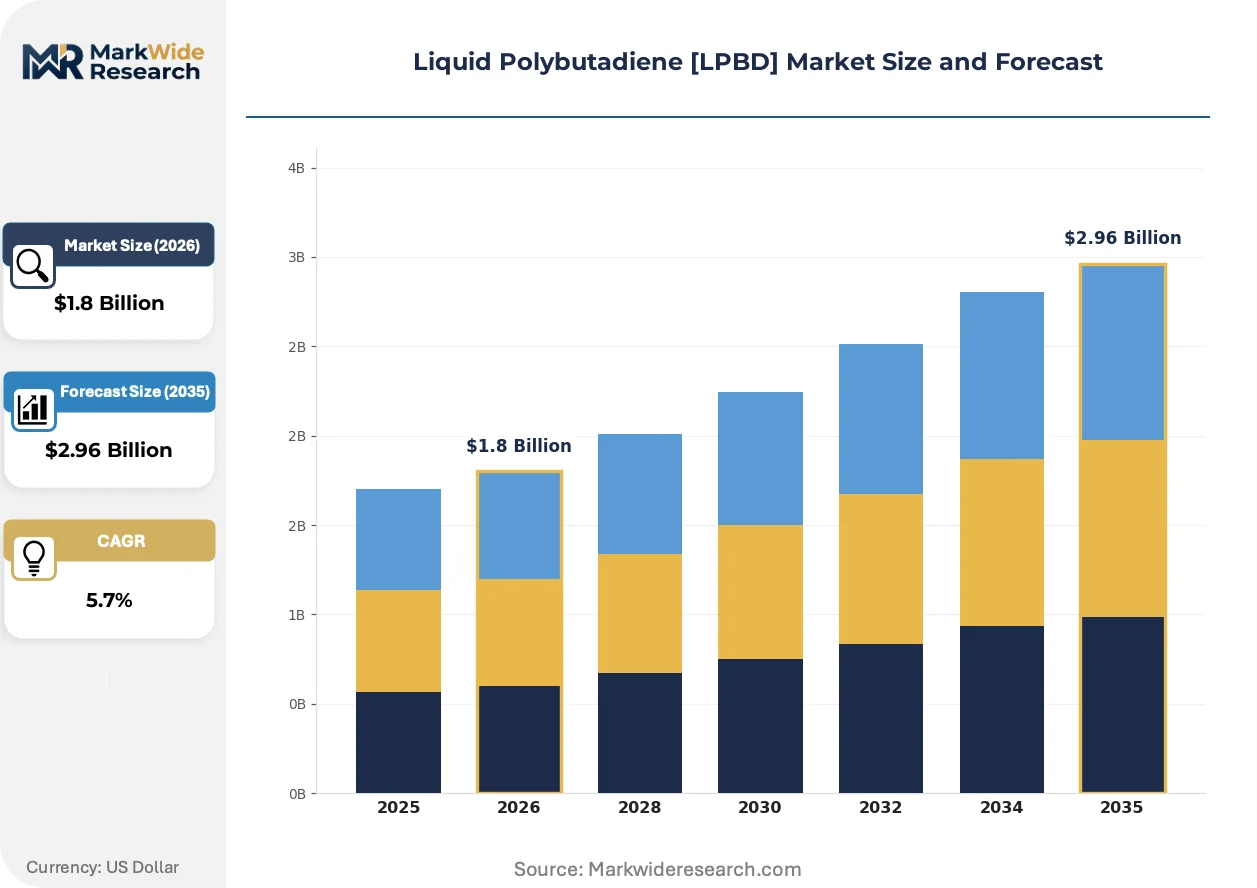
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Viscosity, Low Viscosity, Modified, Specialty Application: Adhesives, Coatings, Sealants, Elastomers End User: Automotive, Consumer Goods, Aerospace, Construction Form: Liquid, Emulsion, Solution, Gel |
| Companies Covered | ARLANXEO, JSR Corporation, UBE Corporation, Kumho Petrochemical, LG Chem, Evonik Industries, SABIC, Kuraray Co., Ltd., LANXESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Polybutadiene [LPBD] Market Shifts & Advancements
Formulation chemistry is pivoting toward reactive modifiers that bridge thermoset processing speed with elastomeric performance, compressing traditional material category boundaries.
Telechelic liquid polybutadiene with hydroxyl terminal functionality is hybridizing polyurethane network formation in high-performance casting elastomers. Mining equipment manufacturers in Australia are specifying these hybrids for abrasion-resistant liner applications. The technology is hybridizing procurement categories that previously separated epoxy, polyurethane, and rubber modifiers into distinct sourcing decisions.
ECHA REACH Annex XVII restrictions on residual 1,3-butadiene monomer are tightening maximum permissible concentrations in consumer-facing adhesive formulations. This industrial consequence elevates analytical validation costs for non-specialty producers while advantaging firms with in-house gas chromatography protocols. Low-viscosity grades for DIY construction adhesives face the steepest compliance burden, redirecting R&D toward reactor designs with enhanced stripping efficiency.
Specification-driven procurement is consolidating buyer power among tier-one automotive suppliers who unbundle compounding decisions from raw material selection. Japanese tire manufacturers are centralizing LPBD qualification through designated compounder relationships rather than direct producer contracts. This pattern is most visible in Kobe and Osaka industrial corridors where Keiretsu supply structures persist.
Liquid Polybutadiene [LPBD] Market Segmentation
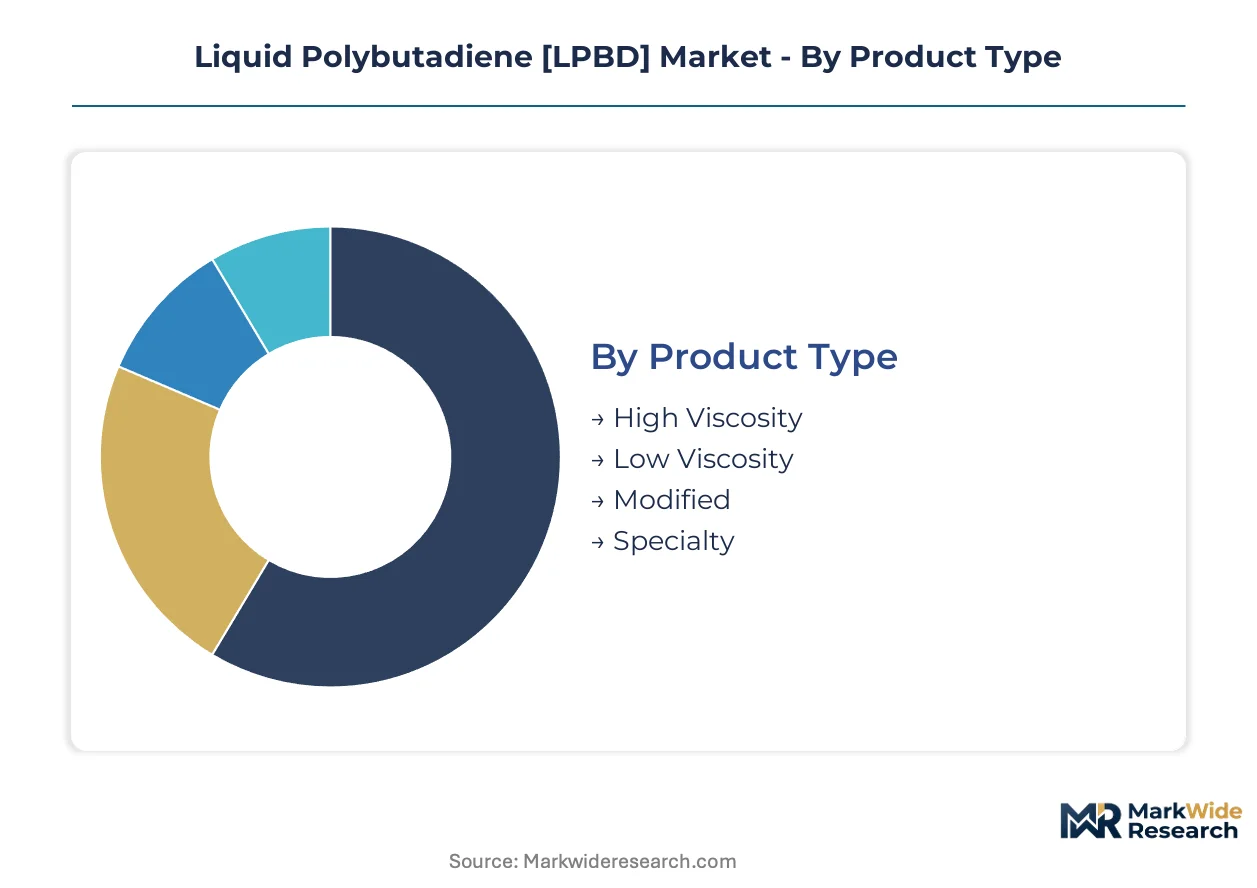
LPBD procurement patterns diverge sharply across viscosity grades and terminal functionality, with tire compounders, adhesive formulators, and aerospace sealant manufacturers each imposing distinct specification windows that reshape supplier prioritization.
Product Type:
Cycle times compress toward low-viscosity reactor grades where adhesive line economics demand rapid dispensing, while modified variants endure multi-year aerospace qualification protocols.
- High Viscosity:Molecular weights exceeding 10,000 centipoise serve tire sidewall reinforcement and industrial belting where green strength retention governs compound processing. Demand concentrates in Japanese tire manufacturing corridors where Keiretsu compounders specify these grades for truck and bus radial formulations.
- Low Viscosity:Ranging from 500 to 5,000 centipoise, these grades dominate construction adhesive and DIY sealant applications where pumpability and rapid wet-out determine line speed. South Korean adhesive manufacturers are expanding procurement for waterproofing membrane formulations under evolving BIS standards alignment.
- Modified:Terminal-functionalized variants with hydroxyl, carboxyl, or vinyl end-groups command specification in polyurethane hybrid networks and epoxy toughening. Australian mining equipment manufacturers specify these for abrasion-resistant casting elastomers.
- Specialty:Solution-polymerized anionic grades with ultra-low residual monomer serve pharmaceutical packaging and food-contact adhesives where ECHA REACH Annex XVII thresholds apply.
Low viscosity dominates installed base. Modified grades are where expansion concentrates.
Application:
Margin structures stratify across application categories, with construction sealants running on thin formulation economics and aerospace specifications capturing disproportionate value pools.
- Adhesives:Hot-melt and reactive formulations consume the largest volume share, with South Korean and Japanese adhesive compounders driving specification evolution toward low-odor, low-VOC grades. ECHA registration requirements advantage suppliers with captive gas chromatography capabilities.
- Coatings:UV-curable LPBD-acrylate oligomers are gaining specification in electronics assembly coatings where thermal sensitivity excludes conventional thermal initiators. German automotive electronics suppliers are qualifying these for sensor encapsulation.
- Sealants:Moisture-cure construction sealants face displacement pressure from silane-terminated polyurethanes in ambient-temperature curing applications. Aerospace fuel tank and pressure cabin sealants retain LPBD specification for thermal stability and outgassing performance.
- Elastomers:Solution-polymerized grades serve castable polyurethane mining liners and industrial rollers where abrasion resistance and dynamic load tolerance converge.
Adhesives anchor volume consumption. Coatings are climbing the fastest.
End User:
Procurement centralization varies sharply, with automotive tire manufacturers consolidating through designated compounders while construction formulators fragment across regional distributors.
- Automotive:Tire and under-the-hood applications absorb the majority of non-modified volume, with Japanese and South Korean tire manufacturers centralizing LPBD qualification through Keiretsu-aligned compounders.
- Consumer Goods:DIY construction adhesives and footwear bonding applications face the steepest REACH compliance burden for residual monomer limits.
- Aerospace:OEM specification lock-in through Boeing, Airbus, and tier-one sealant suppliers creates multi-year barriers to grade substitution.
- Construction:Infrastructure waterproofing membranes in India represent the steepest expansion trajectory as BIS standards evolve to accept synthetic elastomer modifiers.
Automotive commands the largest share. Construction is gaining share fastest.
Form:
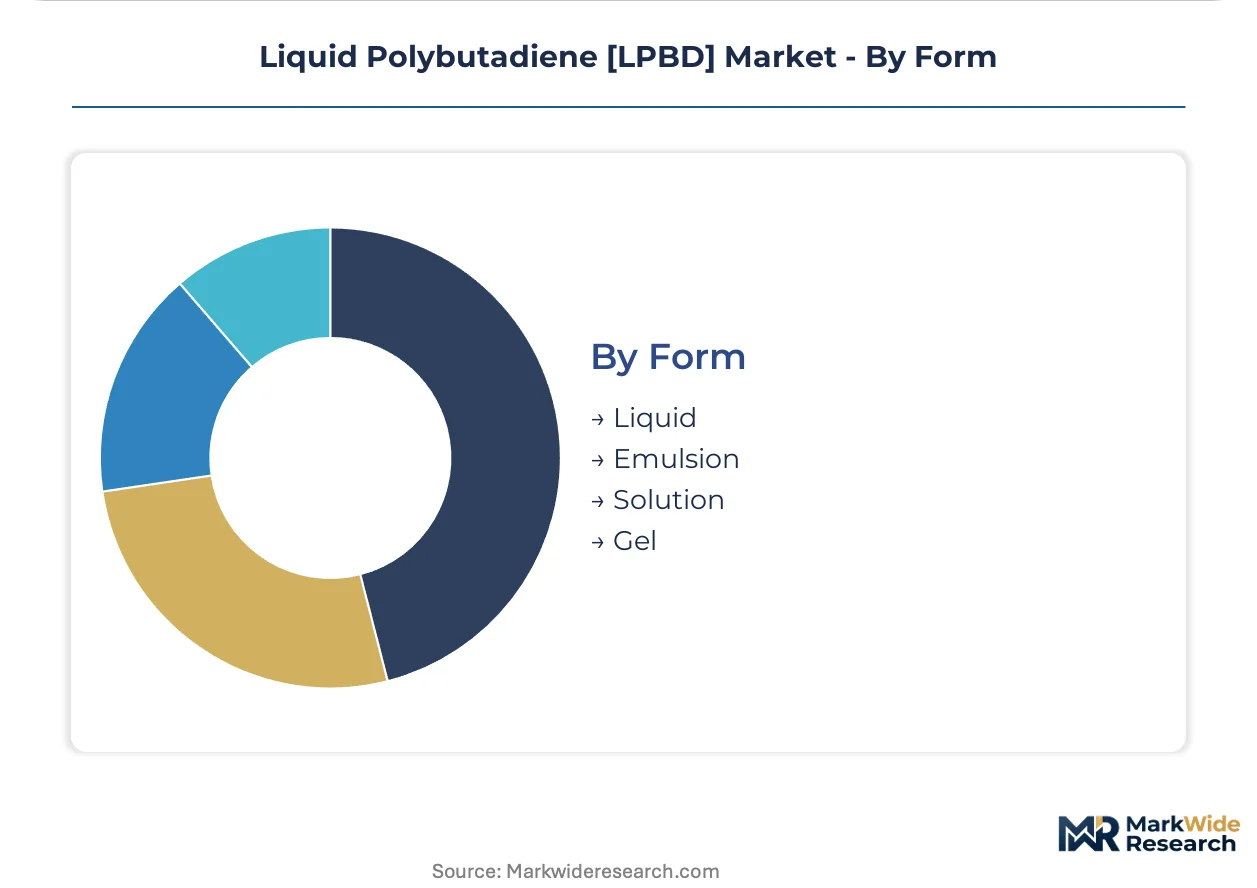
Physical state determines logistics economics and formulation latitude, with emulsion forms enabling waterborne system compatibility at the cost of shortened shelf stability.
- Liquid:Bulk reactor grades shipped in ISO tanks dominate tire and industrial compounding, with viscosity specification enabling direct meter-mix dispensing.
- Emulsion:Waterborne dispersions serve construction-grade waterproofing and textile backing where solvent-free formulation is mandated by site safety protocols.
- Solution:Solvent-cut grades facilitate high-solids coating formulation for automotive underbody sealant applications.
- Gel:Thixotropic preparations target vertical surface sealant application where sag resistance governs specification.
Liquid forms dominate installed base. Emulsion is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH compliance anchors European procurement decisions, while Asian tire manufacturers concentrate demand in South Korea and Japan. The market's geographic footprint reflects petrochemical infrastructure density and automotive manufacturing clustering.
South Korea
Kumho Petrochemical and LG Chem reactor expansions tighten domestic supply availability for third-party offtake. MFDS-aligned K-REACH substance notification procedures extend commercialization timelines for novel modified grades. The Ulsan petrochemical complex anchors regional production capacity expansion.
Japan
JSR Corporation sustains technology leadership in solution-polymerized specialty grades for aerospace sealant applications. METI industrial standards govern residual monomer thresholds in consumer-facing adhesive formulations. The Kobe-Osaka industrial corridor centralizes LPBD qualification through Keiretsu-aligned compounder relationships.
Germany
ARLANXEO leverages backward integration into butadiene feedstock across European manufacturing sites. ECHA Annex XVII restrictions on residual 1,3-butadiene monomer elevate analytical validation costs for non-specialty producers. The Cologne-Dormagen chemical cluster concentrates formulation R&D toward low-viscosity reactor grades.
United States
EPA New Chemicals program reviews constrain novel modified-grade introductions, extending commercialization timelines. Tire manufacturers in the Southeast automotive corridor expand procurement for high-performance rubber compounds. The Texas-Louisiana petrochemical belt supplies C4 olefin feedstock to domestic LPBD producers.
India
BIS standards evolution for waterproofing membranes opens specification windows for low-viscosity grades in infrastructure-grade formulations. Construction-grade emulsions represent the fastest-expanding consumption category across the subcontinent. The Gujarat-Maharashtra industrial corridor concentrates adhesive formulator demand for synthetic elastomer modifiers.
Liquid Polybutadiene [LPBD] Market Competitive Landscape
Capability concentration sits with Japanese and Korean specialists; scale advantage sits with European and Korean petrochemical majors. The market structures around three tiers: integrated petrochemical conglomerates with captive butadiene supply, solution-polymerization specialists with anionic reactor expertise, and regional compounders serving construction adhesive markets. Dominant competitive moves include reactor capacity expansion in South Korea and strategic partnerships between tire manufacturers and designated compounders in Japan.
Within the integrated petrochemical tier, ARLANXEO and Kumho Petrochemical exemplify backward integration into C4 olefin feedstock. JSR Corporation occupies a position among solution-polymerization specialists, representing the capability concentration in anionic reactor technology for aerospace and specialty adhesive applications. These three anchors illustrate the geographic and technological bifurcation shaping procurement decisions across tire, adhesive, and sealant end markets.
| Leading Market Players |
|---|
| ARLANXEO |
| JSR Corporation |
| UBE Corporation |
| Kumho Petrochemical |
| LG Chem |
| Evonik Industries |
| SABIC |
| Kuraray Co., Ltd. |
| LANXESS |
| Others |
Supply & Pricing Matrix
Butadiene feedstock volatility tied to naphtha cracking economics compresses margin buffers across non-integrated producers while simultaneously widening price spreads between spot-indexed and contract-anchored supply tiers. This volatility vector forces procurement officers to weight backward integration premiums against volume commitment discounts, reshaping how tire compounders and adhesive formulators structure their supplier portfolios.
Pricing Analysis
Geographic price spreads between South Korean reactor-grade exports and European REACH-registered specialty grades reflect compliance cost differentials rather than raw material disparities alone. Contract-based long-term offtake dominates tire manufacturer procurement, with volume scale and certification tier (ECHA registration status) serving as the primary price differentiation levers. Cost compression in standard-grade construction adhesives is intensifying because silane-terminated polyurethane substitutes erode LPBD volume share in ambient-cure applications. DIY construction formulators exhibit the highest price sensitivity, while aerospace sealant OEMs demonstrate minimal elasticity due to multi-year qualification lock-in.
Supply Chain Analysis
Extended payment terms from South Korean petrochemical majors are squeezing working capital for third-party distributors serving Southeast Asian adhesive markets. Supply concentrates in South Korea, Japan, and Germany, with C4 olefin feedstock, anionic polymerization catalysts, and analytical validation equipment serving as critical input dependencies. Single-source vulnerability around solution-polymerized specialty grades from Japanese producers exposes aerospace sealant formulators to allocation risk during capacity constraints. Distribution runs through designated compounder relationships in Japanese Keiretsu structures and direct mill procurement in South Korean tire corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon-border adjustment mechanisms and tire-labeling scheme evolution are accelerating specification bifurcation between lifecycle-data-transparent suppliers and commodity-grade producers. This regulatory inflection compresses commercialization timelines for reformulated products while rewarding early movers with verified low-carbon feedstock sourcing.
For Market Incumbents: Harden analytical validation capabilities to defend ECHA-registered supplier status against emerging low-cost entrants from India and Southeast Asia. Expand reactor capacity in Ulsan or backward integration into C4 olefin supply to offset butadiene price volatility exposure. Prioritize K-REACH substance notification completion ahead of MFDS-aligned deadlines to secure South Korean adhesive market access. For New Entrants and Emerging Players: Pursue specification windows in Indian construction-grade emulsions as BIS standards evolve to accept synthetic elastomer modifiers for waterproofing membranes. Target UV-curable hybrid oligomer segments in German automotive electronics supply chains where thermal sensitivity excludes incumbent thermal-initiator systems. Lead with lifecycle data transparency and verified low-carbon butadiene sourcing to differentiate against established commodity suppliers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors solution-polymerization specialists with captive anionic reactor expertise and aerospace qualification heritage. Long-term viability hinges on regulatory compliance moats rather than scale economics alone, positioning Japanese and Korean technical-grade producers as durable value anchors. Watch EU carbon-border adjustment implementation timelines as the critical inflection signal for procurement preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into C4 Olefins | ARLANXEO and Kumho Petrochemical anchor margin stability through captive butadiene supply. |
| Solution-Polymerization Capacity Expansion | JSR Corporation sustains technology leadership in aerospace sealant grade production. |
| ECHA REACH Registration Investment | Registered suppliers capture procurement preference in European adhesive markets. |
| Low-Viscosity Reactor Grade Development | South Korean producers target construction adhesive line speed requirements. |
| Lifecycle Data Transparency Programs | EU importers demand verified carbon intensity documentation for border adjustment compliance. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with tire compound procurement directors, adhesive formulator technical leads, aerospace sealant qualification engineers, and petrochemical plant operations managers; alongside secondary validation through customs and trade flow databases, ECHA registration filings, SEC 10-K chemical segment disclosures, and ACC/Cefic regional production reports. Bottom-up volume modeling triangulated against top-down petrochemical capacity assessments anchored the market sizing framework.
Forecast inputs considered viscosity grade tier, terminal functionality modification, end-use industry concentration, and regional regulatory cluster alignment across the projection horizon. CAGRs derived from segment-level elasticity modeling incorporating butadiene feedstock price scenarios, REACH compliance cost trajectories, and substitution elasticity estimates for silane-terminated polyurethane systems. Modeled outputs reflect volume and value convergence across tire compounding, adhesive formulation, and aerospace sealant application channels.
Macroeconomic conditions sit as an overlay; deviation in naphtha cracking margins, carbon-border adjustment implementation pace, or tire-labeling scheme enforcement stringency would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory timeline adherence and feedstock price regime stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
North America Flame Retardant Thermoplastics Market
Polymers & Resins
South America Fluoropolymer Market
Polymers & Resins
Flame Retardant Thermoplastics Market
Polymers & Resins
Global Chlorinated Polyethylene Market
Polymers & Resins
PP Homopolymer Market
Polymers & Resins
Polyglycerates Market
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
North America Thermoplastics Market
Polymers & Resins
Asia-Pacific Polycarbonate (PC) Market
Polymers & Resins
Middle-East and Africa Epoxy Resins Market
Polymers & Resins
Sugar Polymers Market
Polymers & Resins
Europe Polyacrylamide Market
Polymers & Resins
Water-Borne Resins Market
Polymers & Resins
Agar Resin Market
Polymers & Resins
Glycolide Polymers Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market