
 Lactic Acid and Polylactic Acid Market | 2026-2036
Lactic Acid and Polylactic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Lactic Acid and Polylactic Acid Market Foresight
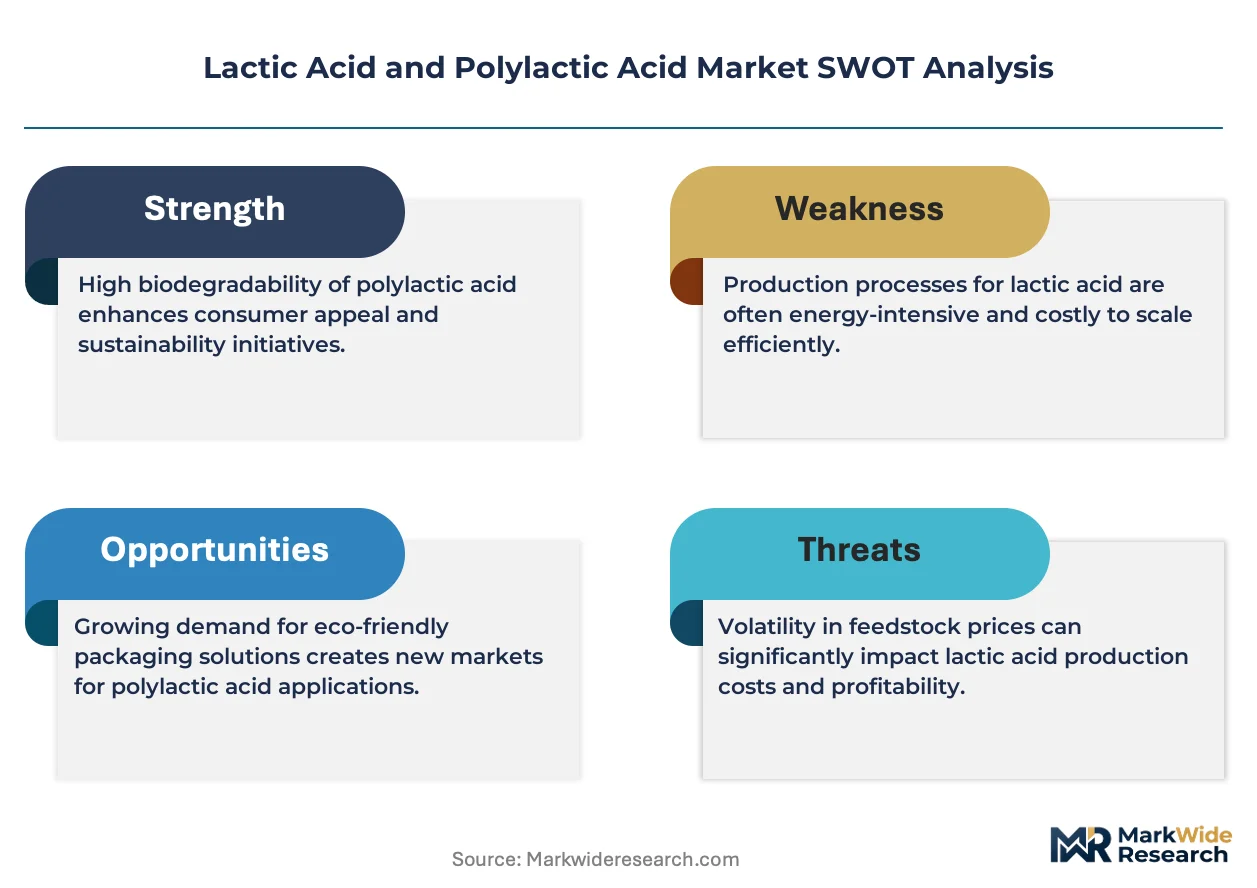
China's expanding fermentation capacity is fragmenting the traditional supply geography of lactic acid and polylactic acid. NatureWorks LLC leverages its integrated corn-to-PLA model to sustain cost leadership across North American packaging accounts. TotalEnergies Corbion anchors European supply through its Thai manufacturing base, while Corbion competes on food-grade acid purity for pharmaceutical and cosmetic precursors.
Lactic acid and polylactic acid comprise alpha-hydroxy acid and its thermoplastic aliphatic polyester derivative, typically synthesized through carbohydrate fermentation followed by condensation or ring-opening polymerization to achieve molecular weights between 100,000 and 300,000 g/mol for durable resin applications. Polylactic acid serves as a drop-in replacement for polystyrene and PET in rigid packaging, textiles, and medical devices where compostability or bio-based content carries procurement premiums. The application dimension shows packaging commanding the dominant volume share, though medical devices generate superior margin pools due to stringent USP Class VI and ISO 10993 validation requirements. Grade stratification reveals food-grade lactic acid as the mature revenue base, while medical-grade PLA resin commands pricing multiples driven by implantable device OEM qualification cycles.
The US FDA regulates PLA for food contact through its food additive and food contact notification pathways, while the EPA administers bio-preferred procurement standards under the Farm Bill. REACH registration requirements in Europe govern monomer purity thresholds, and China's NMPA enforces medical device master file standards for implant-grade resins. Stakeholders must monitor how divergent compostability certification schemes across Germany's DIN CERTCO, the US BPI, and Japan's JBPA reshape market access conditions for traded resin volumes.
Market Dynamics
The EU Green Deal's packaging waste directives are compressing substitution timelines for fossil-based plastics, forcing brand owners to validate biodegradable alternatives against stricter material specifications and accelerated compliance deadlines.
Growth Catalysts
- EU Green Deal packaging mandates:Binding reduction targets for single-use plastics are pulling food-grade PLA into rigid packaging applications across German and French supply chains.
- Fermentation technology maturation:Continuous processing advances are lowering carbohydrate-to-acid conversion costs, improving unit economics for polymer-grade lactic acid.
- Medical device qualification:USP Class VI and ISO 10993 validation pathways are opening premium margin pools for implant-grade resin in cardiovascular and orthopedic OEMs.
Market Restraints
- Corn feedstock price volatility:Carbohydrate input costs fluctuate with agricultural commodity cycles, compressing margins for fermentation-based producers without long-term supply contracts.
- Thai manufacturing concentration:European PLA supply anchors through a single Southeast Asian production base, creating geographic risk exposure for REACH-registered resin volumes.
- Performance ceiling in high-temperature applications:PLA's thermal deformation limitations below 60°C restrict substitution potential in hot-fill beverage and microwaveable food packaging.
Strategic Opportunities
- Underpenetrated Indian packaging market:FSSAI's emerging biodegradable packaging guidelines and BIS standards development create first-mover positioning for fermentation-derived resins.
- Textile fiber applications:PLA's moisture management properties and compostability credentials are displacing polyester in sportswear and nonwoven hygiene products.
- 3D printing filament grade development:Material extrusion systems are adopting bio-based polymers for prototyping and low-volume manufacturing in design studios and medical modeling.
Industry Challenges
- Composting infrastructure mismatch:Industrial composting facility scarcity in the United States creates a gap between product certification and actual end-of-life processing capability.
- Multi-certification compliance burden:Divergent compostability standards across DIN CERTCO, BPI, and JBPA force resin producers to maintain parallel validation pathways for market access.
- Polymerization scale-up complexity:Ring-opening polymerization reactor design and catalyst recovery systems require specialized engineering talent with limited availability in traditional chemical engineering labor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lactic Acid and Polylactic Acid Market |
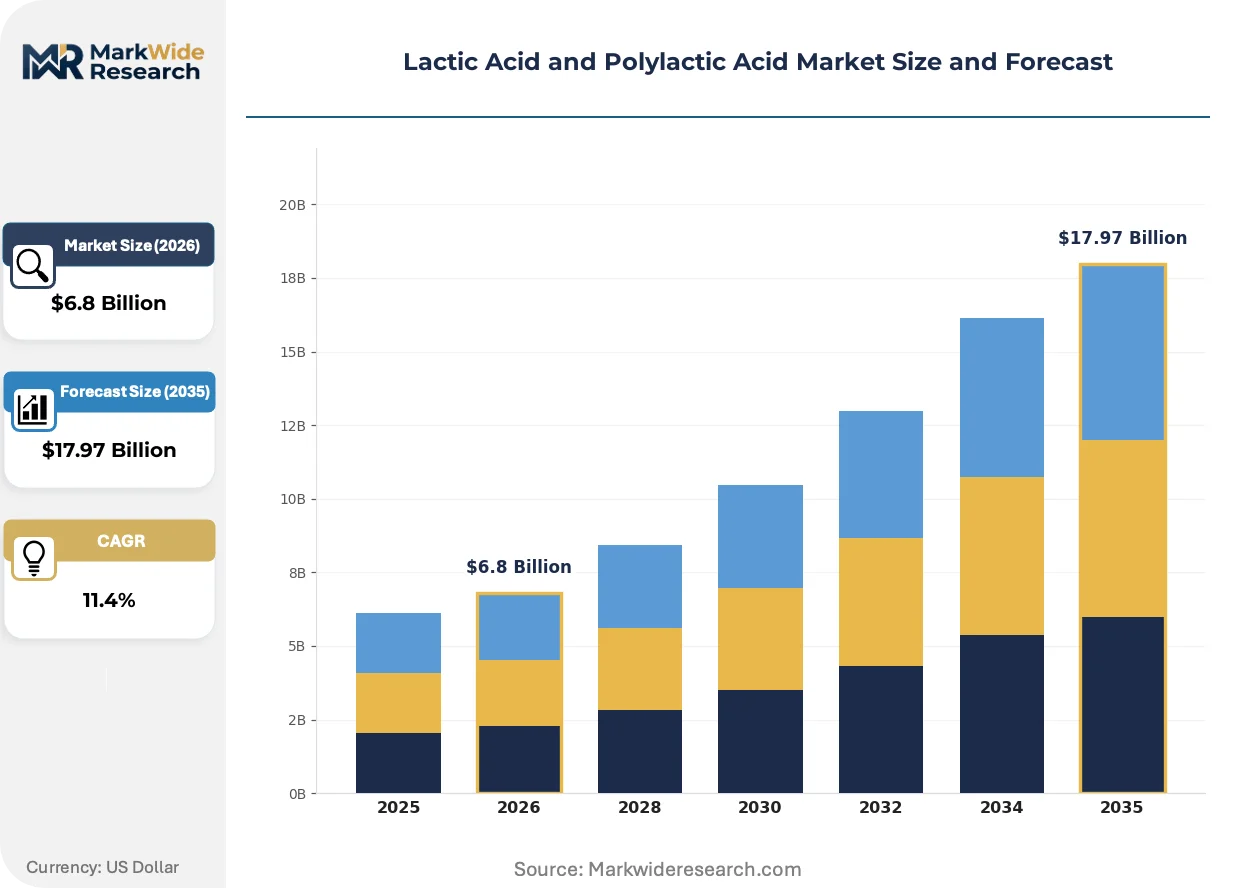
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lactic Acid, Polylactic Acid, Blends, Esters Application: Packing, Textiles, Agriculture, Medical Devices End User: Food Industry, Pharmaceutical, Consumer Goods, Automotive Grade: Food Grade, Industrial Grade, Medical Grade, Technical Grade |
| Companies Covered | NatureWorks LLC, TotalEnergies Corbion, BASF SE, Corbion, Galactic, Futerro, Cargill, COFCO, Danimer Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lactic Acid and Polylactic Acid Market Shifts & Advancements
Digital process control systems and advanced fermentation analytics are compressing development cycles for next-generation lactic acid strains, while regulatory pressure and buyer behavior shifts are restructuring how bio-based polymers enter commercial supply chains.
Next-generation continuous fermentation technology is virtualizing batch-to-batch variability through real-time metabolite monitoring and automated pH control. Bioprocess engineers at major carbohydrate processors are adopting these systems to stabilize acid titers above 180 g/L. This virtualization is compressing quality assurance timelines and reducing downstream purification load.
REACH registration amendments for polymer monomers are tightening purity thresholds for residual lactide content in food-contact applications. ECHA's updated dossier requirements are forcing resin producers to invest in chromatographic separation capacity. Medical device master file submissions in Germany and France are experiencing extended review cycles as notified bodies apply stricter impurity profiling standards.
Brand-owner sustainability scorecards are elevating bio-based content percentages above recyclability metrics in packaging procurement decisions. Major beverage and fresh-food retailers are rewriting supplier qualification protocols to prioritize compostable alternatives. This preference shift is most visible in German and Nordic retail chains where private-label packaging specifications now mandate DIN CERTCO or OK Compost certification as a baseline tender requirement.
Lactic Acid and Polylactic Acid Market Segmentation
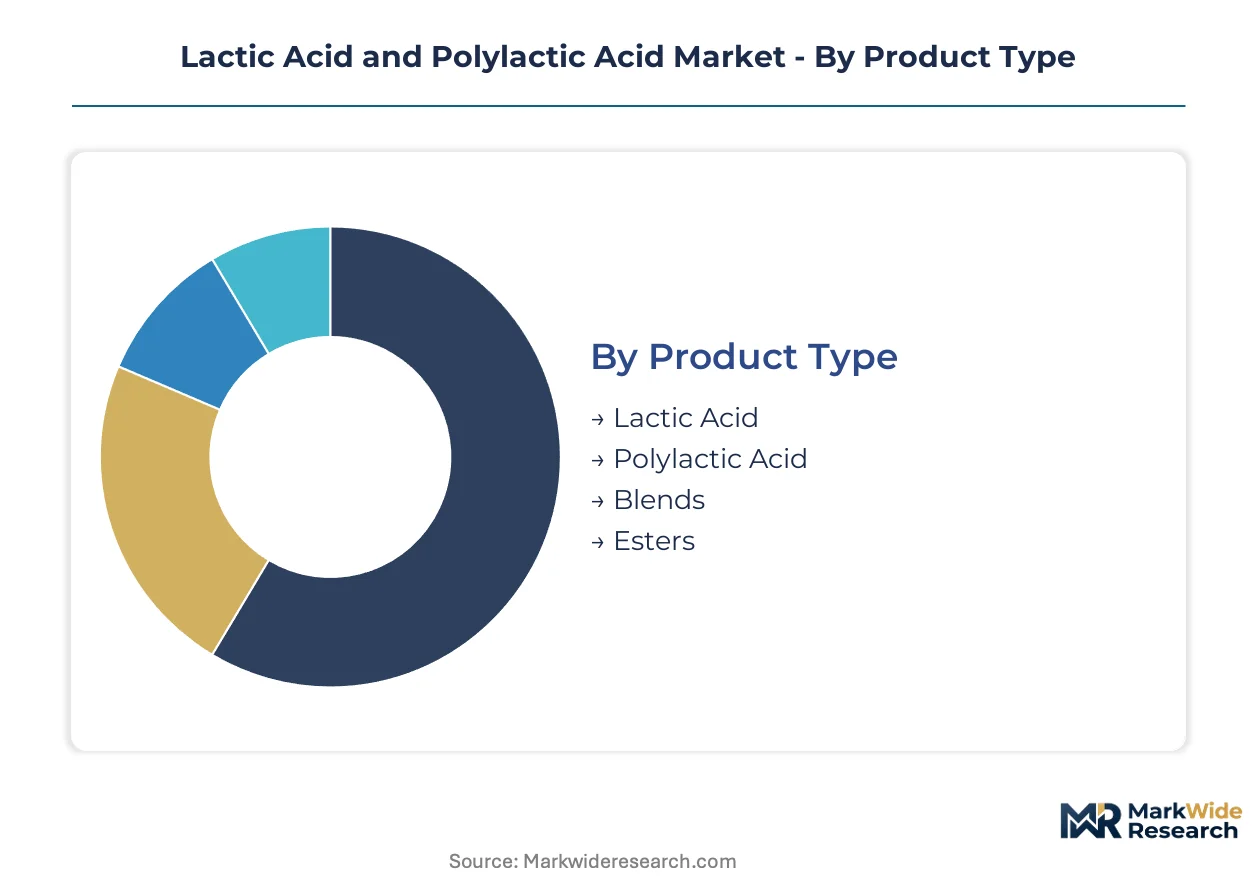
Segmentation in lactic acid and polylactic acid markets reveals how technical specifications, regulatory pathways, and end-use requirements fragment commercial opportunities. Each dimension carries distinct margin structures and qualification barriers that reshape competitive positioning across supply chains.
Product Type:
Mature commodity streams coexist with emerging specialty derivatives across this category.
- Lactic Acid:Alpha-hydroxy acid produced through carbohydrate fermentation, typically achieving 80-88% purity in commercial grades. Food and beverage preservative applications in Germany and France absorb the dominant volume share, pulled by EU Green Deal packaging waste directives that accelerate substitution away from synthetic acidulants.
- Polylactic Acid:Thermoplastic aliphatic polyester synthesized via lactide ring-opening polymerization, achieving molecular weights between 100,000 and 300,000 g/mol for durable resin applications. Rigid packaging specifications from German and Nordic retail chains now mandate DIN CERTCO certification as a baseline tender requirement.
- Blends:Compound formulations with PBAT or starch modifiers that extend PLA's thermal performance ceiling and accelerate biodegradation rates in soil-contact applications.
- Esters:Derivative chemicals including ethyl lactate and butyl lactate serving solvent and fragrance carrier functions in pharmaceutical and cosmetic precursor supply chains.
Polylactic Acid handles the majority of throughput; Blends are expanding most quickly as compounders engineer performance bridges for hot-fill packaging.
Application:
Volume concentration and margin premium diverge sharply across end-use sectors.
- Packing:Rigid food containers, flexible films, and thermoformed trays replacing polystyrene and PET in fresh-food retail. German private-label specifications and French supermarket procurement protocols now embed compostability credentials as mandatory supplier qualification criteria.
- Textiles:PLA fiber applications in sportswear and nonwoven hygiene products leverage moisture management properties and industrial compostability. Nordic apparel brands are rewriting material sourcing guidelines to prioritize bio-based polyester alternatives.
- Agriculture:Mulch films, plant clips, and controlled-release fertilizer coatings that eliminate soil plastic accumulation. Field trials in the Netherlands and Belgium are validating decomposition rates under local climatic conditions.
- Medical Devices:Implant-grade resins for cardiovascular stents, orthopedic fixation screws, and drug delivery systems. USP Class VI and ISO 10993 validation pathways create 18-36 month OEM qualification cycles that lock in premium pricing multiples.
Packing commands the dominant volume position; Medical Devices deliver the steepest margin expansion trajectory.
End User:
Customer procurement sophistication and specification stringency stratify across industrial segments.
- Food Industry:Preservative acidulants, pH regulators, and biodegradable packaging films. Major beverage and fresh-food retailers in Germany are elevating bio-based content percentages above recyclability metrics in supplier scorecards.
- Pharmaceutical:Excipients, active pharmaceutical ingredient precursors, and implantable device substrates. EMA and national competent authorities enforce impurity profiling standards that extend master file review cycles.
- Consumer Goods:Personal care formulations, disposable tableware, and household cleaning product packaging. BIS standards development in India is creating first-mover positioning for fermentation-derived resin suppliers.
- Automotive:Interior trim components, fastener clips, and acoustic insulation with end-of-life compostability targets. German OEM sustainability roadmaps are integrating bio-based polymer specifications into tier-one supplier contracts.
Food Industry absorbs the greatest resin tonnage; Pharmaceutical qualification pathways are climbing the fastest on value contribution.
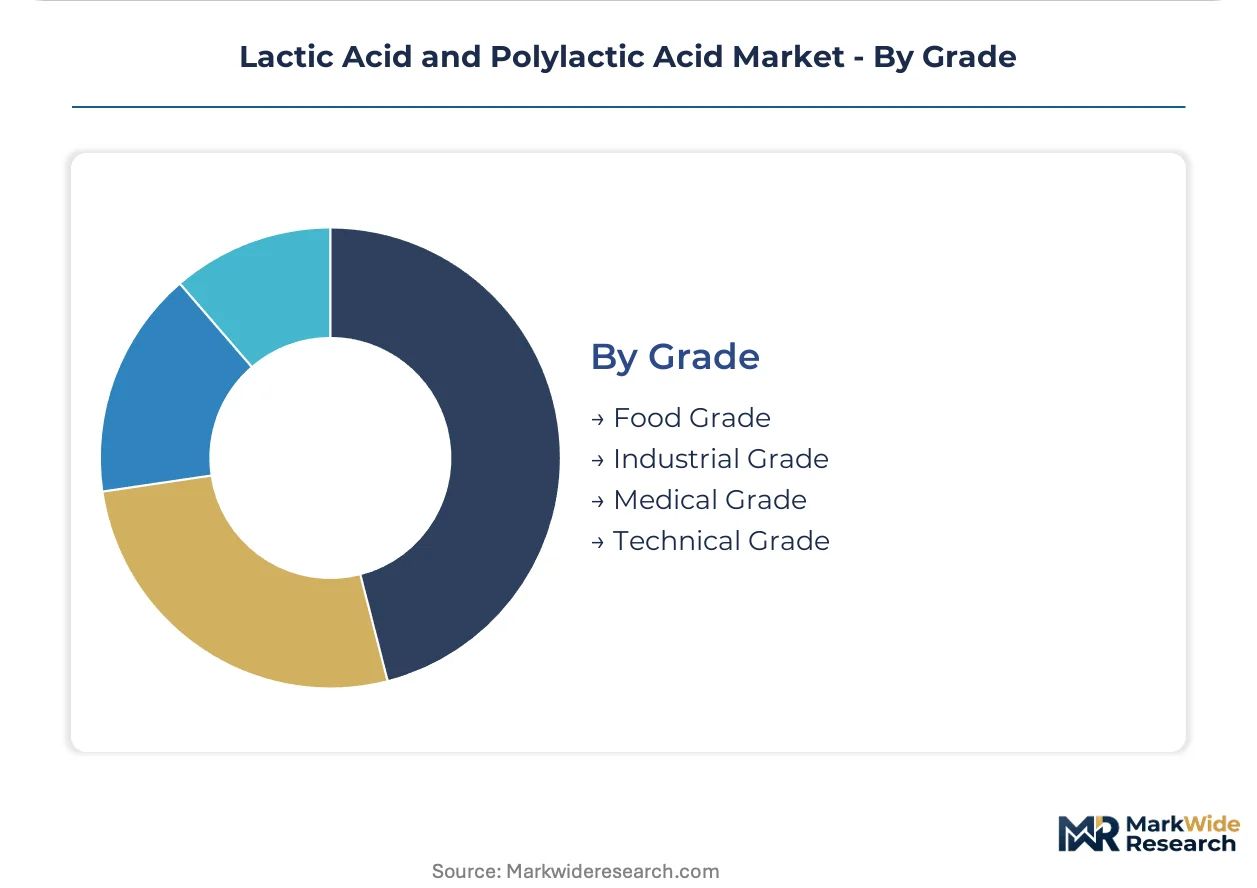
Grade:
Purity thresholds and certification requirements segment pricing architectures.
- Food Grade:Lactic acid meeting EFSA and FDA specifications for direct food contact, with residual protein and carbohydrate limits below 0.1%. REACH registration amendments are tightening residual lactide thresholds, forcing chromatographic separation investments.
- Industrial Grade:Technical acid for chemical synthesis, leather tanning, and metal finishing applications. Price volatility in corn feedstock compresses margins for producers without long-term carbohydrate supply contracts.
- Medical Grade:Resins validated to USP Class VI and ISO 10993 biocompatibility standards for implantable and blood-contacting devices. Notified bodies in Germany and France are applying stricter impurity profiling standards that extend review timelines.
- Technical Grade:Intermediate purity for polymerization feedstock and non-critical industrial applications. Continuous fermentation advances are stabilizing acid titers above 180 g/L, compressing quality assurance timelines for this segment.
Food Grade maintains the established revenue base; Medical Grade is gaining share fastest on pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany absorbs PLA resin through rigid packaging mandates while China scales fermentation capacity for export acid; the United States concentrates medical-grade validation cycles, creating divergent consumption patterns across geographies.
Germany
Private-label packaging specifications from Aldi and Lidl now mandate DIN CERTCO certification as a baseline tender requirement. The EU Green Deal's packaging waste directives compress substitution timelines for fossil-based plastics. Chemical clusters near Ludwigshafen and Leipzig are integrating fermentation-derived feedstocks into existing polymer infrastructure.
United States
Medical device OEMs drive premium resin demand through USP Class VI and ISO 10993 qualification pathways. The FDA regulates PLA for food contact through food additive and food contact notification pathways. NatureWorks LLC leverages its integrated corn-to-PLA model to sustain cost leadership across North American packaging accounts.
China
Expanding fermentation capacity is fragmenting traditional supply geography for lactic acid and polylactic acid. The NMPA enforces medical device master file standards for implant-grade resins. COFCO and regional carbohydrate processors are scaling continuous fermentation systems to stabilize acid titers above 180 g/L.
Thailand
European PLA supply anchors through TotalEnergies Corbion's Southeast Asian manufacturing base, creating geographic risk exposure for REACH-registered resin volumes. The country's Board of Investment incentives attracted bio-based polymer capital ahead of EU regulatory tightening. Bangkok-adjacent chemical zones now serve as the primary export hub for compostable packaging resin bound for German and French supply chains.
India
FSSAI's emerging biodegradable packaging guidelines and BIS standards development create first-mover positioning for fermentation-derived resins. Import substitution policies favor domestic acid production for pharmaceutical excipient applications. Gujarat and Maharashtra chemical corridors are attracting PLA compounding investments to serve food-industry packaging demand.
Lactic Acid and Polylactic Acid Market Competitive Landscape
Capability concentration sits with integrated fermentation-to-polymer specialists; scale advantage sits with diversified chemical conglomerates with existing carbohydrate supply chains. The vendor base stratifies across three tiers: captive agribusiness processors, standalone biopolymer pure-plays, and diversified chemical majors leveraging existing polymer infrastructure. Dominant competitive moves include backward integration into corn processing and geographic expansion through Thai manufacturing bases to secure European market access.
Among integrated biopolymer specialists, NatureWorks LLC exemplifies the captive feedstock model, while TotalEnergies Corbion anchors European supply positioning. Corbion occupies a distinct tier competing on food-grade acid purity for pharmaceutical and cosmetic precursor applications.
| Leading Market Players |
|---|
| NatureWorks LLC |
| TotalEnergies Corbion |
| BASF SE |
| Corbion |
| Galactic |
| Futerro |
| Cargill |
| COFCO |
| Danimer Scientific |
| Others |
Supply & Pricing Matrix
Underutilized fermentation capacity in China's Shandong and Jiangsu provinces is compressing spot lactic acid prices and forcing European polymer-grade producers toward longer contract structures. This utilization imbalance simultaneously erodes margin buffers for corn-dependent North American operators while creating procurement leverage for German packaging compounders.
Pricing Analysis
Long-term offtake contracts dominate medical-grade PLA resin transactions, while food-grade acid trades on quarterly price negotiations indexed to corn futures. Price differentiation separates USP Class VI-validated implant resin from technical-grade polymer feedstock, with certification tier and volume scale as primary drivers. Pricing pressure stems from Chinese fermentation overcapacity flooding Asian export markets. Small Indian compounders exhibit the highest price sensitivity; German medical device OEMs demonstrate the least.
Supply Chain Analysis
Tariff exposure between Thailand and the European Union dominates supply chain risk calculations for REACH-registered resin volumes. Manufacturing concentrates in Thailand, China, and the United States, with raw material dependencies on corn starch, cane sugar, and specialized lactide purification catalysts. Distribution runs through Rotterdam and Hamburg port terminals for European packaging accounts, with direct rail links to Ludwigshafen chemical clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compostability certification services and technical validation consulting are expanding faster than base resin production, creating recurring revenue layers that outpace hardware margins. This service-attach dynamic reshapes how stakeholders capture value across the value chain.
For Market Incumbents: Pre-empt Chinese fermentation entrants by locking German retail chains into exclusive DIN CERTCO-certified supply agreements. Secure captive corn processing through backward integration into Midwestern agricultural cooperatives. Invest in continuous fermentation R&D to maintain titer advantages above 180 g/L against emerging Asian competitors.
For New Entrants and Emerging Players: Establish a beachhead in Indian food packaging by aligning FSSAI biodegradable guidelines with BIS standards development. Target Gujarat chemical corridors for compounding investments. Pursue white-label resin supply to European compounders lacking Thai manufacturing access.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated fermentation-to-polymer specialists with existing USP Class VI validation pathways. Medical-grade resin producers offer superior long-term viability given 18-36 month OEM qualification cycles that entrench supplier relationships. Monitor ECHA REACH amendment timelines as inflection indicators for chromatographic separation capacity investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Processing | Captive carbohydrate supply insulates NatureWorks from commodity volatility in Iowa and Nebraska. |
| Continuous Fermentation Scale-Up | Real-time metabolite monitoring stabilizes acid titers above 180 g/L for COFCO and regional processors. |
| DIN CERTCO Certification Investment | Compostability validation unlocks Aldi and Lidl private-label specifications as mandatory tender requirements. |
| USP Class VI Validation Pathway | Biocompatibility certification creates 18-36 month lock-in cycles with cardiovascular and orthopedic OEMs. |
| Thai Manufacturing Base Expansion | TotalEnergies Corbion's Bangkok-adjacent capacity anchors European REACH-registered resin supply chains. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fermentation plant managers, polymer procurement leads at German packaging OEMs, distribution channel partners in Rotterdam and Hamburg, technical R&D directors at medical device compounders, and regulatory affairs specialists navigating ECHA dossier requirements. Secondary validation drew from customs trade data, SEC 10-K filings of listed chemical producers, ECHA REACH registration databases, and DIN CERTCO certification records. Bottom-up capacity assessments and top-down demand modeling were triangulated to reconcile volume estimates.
Calibration against historical price realizations and capacity utilization rates informed the analytical framework across the analysis window. Segmentation dimensions modeled include grade tier, end-use industry, and regional production hub. CAGRs were derived from slope analysis of year-over-year growth trajectories. Forecast inputs incorporated corn starch price volatility indices and EU Green Deal packaging mandate implementation schedules.
Sensitivities concentrate around Chinese fermentation capacity additions, REACH purity threshold amendments, and Indian BIS standards finalization timelines. Forecasts reflect assumptions about regulatory enforcement consistency and OEM qualification cycle durations. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Corrosion Resistant Resin Market
Polymers & Resins
North America Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
Europe Epoxy Resins Market
Polymers & Resins
Nylon-6 Market
Polymers & Resins
France Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
Polyether Polyols Market
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
Medical Styrenic Polymers Market
Polymers & Resins
Global Vinyl Ester Market
Polymers & Resins
Mixed-Mode Chromatography Resin Market
Polymers & Resins
Silicone Resins Market
Polymers & Resins
Conditioning Polymers Market
Polymers & Resins
Water-Borne Resins Market