
 Global Hydroxypropyl Cellulose Market | 2026-2036
Global Hydroxypropyl Cellulose Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydroxypropyl Cellulose Market Intelligence
The gap between pharmaceutical-grade and industrial-grade hydroxypropyl cellulose is rebalancing as purity thresholds diverge and pricing power shifts toward excipient-certified supply. Ashland Global Holdings Inc. leverages its vertical integration across cellulose ether chemistry to sustain premium positioning in drug formulation channels. Shin-Etsu Chemical Co., Ltd. anchors its competitiveness through proprietary manufacturing scale in high-viscosity grades for controlled-release applications.
Hydroxypropyl cellulose is a non-ionic water-soluble cellulose ether produced by reacting alkali cellulose with propylene oxide, typically substituting hydroxypropoxyl groups at 4.0–8.0 weight percent to achieve viscosity ranges from 150 to 3,000 mPa·s. It functions primarily as a binder, film-former, and viscosity modifier across oral dosage forms, food systems, and architectural coatings. Low viscosity grades dominate volume in tablet binding applications where rapid dissolution governs performance, while ultra-high viscosity variants command margin premiums in sustained-release matrices and ophthalmic formulations. The pharmaceutical excipients segment leads value generation as regulatory scrutiny on excipient functionality intensifies, with food additives representing a mature, price-sensitive consumption pool.
FDA excipient guidelines, REACH substance registration requirements, and IPEC-PQG GMP standards collectively shape market access by mandating traceable impurity profiles and documented supply chain qualification. India's CDSCO alignment with ICH Q3D elemental impurity limits is reshaping import specifications for multinational pharmaceutical manufacturers sourcing from subcontinent suppliers. Stakeholders must monitor evolving pharmacopeial harmonization between USP-NF, EP, and JP monographs to anticipate reformulation costs and qualification timelines.
Market Dynamics
Pharmaceutical formulation complexity is the dominant structural force reshaping hydroxypropyl cellulose demand, as controlled-release matrix systems and hot-melt extrusion processes displace conventional tablet binders across generic and innovator drug pipelines.
Growth Catalysts
- CDSCO's ICH Q3D alignment:India's pharmaceutical regulator is tightening elemental impurity limits, forcing domestic manufacturers to upgrade to excipient-certified HPC grades and accelerating import substitution for multinational supply chains.
- Hot-melt extrusion adoption:Continuous processing technology in oral solid dosage manufacturing is consuming ultra-high viscosity HPC grades as thermal binders and release-modifying matrices, displacing solvent-based coating methods.
- Ophthalmic formulation expansion:Artificial tear and ocular drug delivery pipelines in Japan and South Korea are specifying low-particulate HPC grades for viscoelastic solutions, creating specification premiums beyond standard pharmaceutical monographs.
Market Restraints
- Propylene oxide feedstock volatility:Crude oil derivative pricing swings directly compress HPC producer margins, with alkoxylation capacity concentration in China and Germany amplifying regional supply shocks.
- Cellulose ether substitution:Hydroxypropyl methylcellulose (HPMC) and ethyl cellulose variants are capturing sustained-release applications where thermal gelation profiles overlap, pressuring HPC differentiation.
- REACH registration cost barriers:ECHA's full substance registration requirements for tonnage bands above 100 metric tons are excluding smaller Asian manufacturers from European pharmaceutical supply chains.
Strategic Opportunities
- Brazil's ANVISA excipient prequalification pathway:Latin America's largest pharmaceutical market is establishing formal excipient quality certification, creating first-mover advantage for suppliers with existing USP-NF and EP documentation.
- 3D printed pharmaceutical dosage forms:Binder jetting and fused deposition modeling processes are trialing HPC as printable matrix formers, opening additive manufacturing channels outside conventional tablet press supply chains.
- PLI scheme downstream incentives:India's production-linked incentive scheme for active pharmaceutical ingredients is expanding domestic formulation capacity, concentrating regional demand for excipient-qualified HPC within a 500-kilometer radius of Hyderabad and Ahmedabad clusters.
Industry Challenges
- Pharmacopeial harmonization timelines:Divergent USP-NF, EP, and JP monograph update cycles are forcing manufacturers to maintain multiple analytical method validations, extending qualification periods for new grade introductions.
- Cleanroom-grade production capex:Excipient GMP compliance under IPEC-PQG standards requires dedicated low-bioburden manufacturing lines, with single-purpose equipment utilization rates below 60% for mid-tier producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydroxypropyl Cellulose Market |
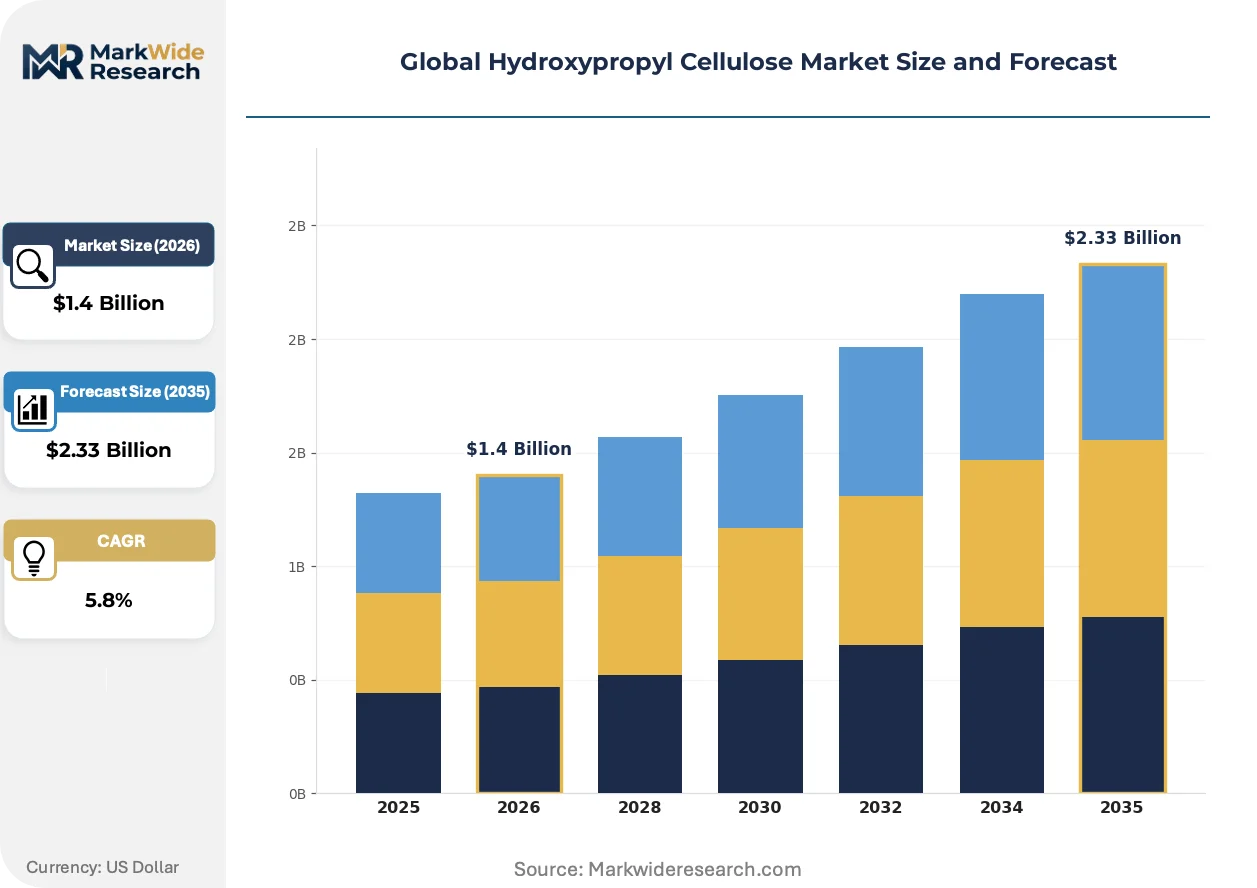
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Viscosity, Medium Viscosity, High Viscosity, Ultra-High Viscosity Application: Pharmaceutical Excipients, Food Additives, Cosmetic Formulations, Paints & Coatings, Adhesives End User Industry: Drug Manufacturers, Food Processing Companies, Personal Care Brands, Chemical Producers Form: Powder, Granules, Film, Pellet |
| Companies Covered | Ashland Global Holdings Inc., Nippon Soda Co., Ltd., Shin-Etsu Chemical Co., Ltd., Dow Chemical Company, DuPont, Shandong Head Europe BV, CP Kelco U.S. Inc., Akzo Nobel, Sidley Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydroxypropyl Cellulose Market Strategic Shifts & Innovations
Continuous manufacturing integration and real-time release testing are compressing batch cycle times and redefining excipient functionality specifications across oral dosage form development.
Solvent-free hot-melt extrusion technology is integrating hydroxypropyl cellulose as a thermal processing aid and controlled-release matrix former. Generic drug manufacturers in India and contract development organizations in North America are adopting twin-screw extrusion lines at 40% faster qualification cycles than conventional fluid bed coating. This technology is integrating HPC into formulation workflows previously dominated by solvent-based ethyl cellulose coatings, compressing capital equipment footprints and volatile organic compound emissions simultaneously.
REACH substance evaluation under ECHA's 2024-2026 rolling action plan is scrutinizing residual propylene oxide and 1,4-dioxane impurity thresholds in cellulose ethers. European pharmaceutical manufacturers are demanding certificates of analysis with quantified sub-ppm levels, forcing alkoxylation process optimization and distillation upgrades. High-purity HPC grades with documented genotoxic impurity profiles are commanding 15-25% specification premiums in German and French formulation supply chains.
Buyer consolidation among multinational pharmaceutical companies is compressing excipient supplier qualification timelines and consolidating purchase volumes toward dual-source strategies. Procurement teams at top-20 generic manufacturers are unbundling technical services from material supply, demanding standalone regulatory documentation packages. This pattern is most visible in US and European markets where three-customer concentration exceeds 60% of excipient-grade HPC volume.
Global Hydroxypropyl Cellulose Market Segmentation
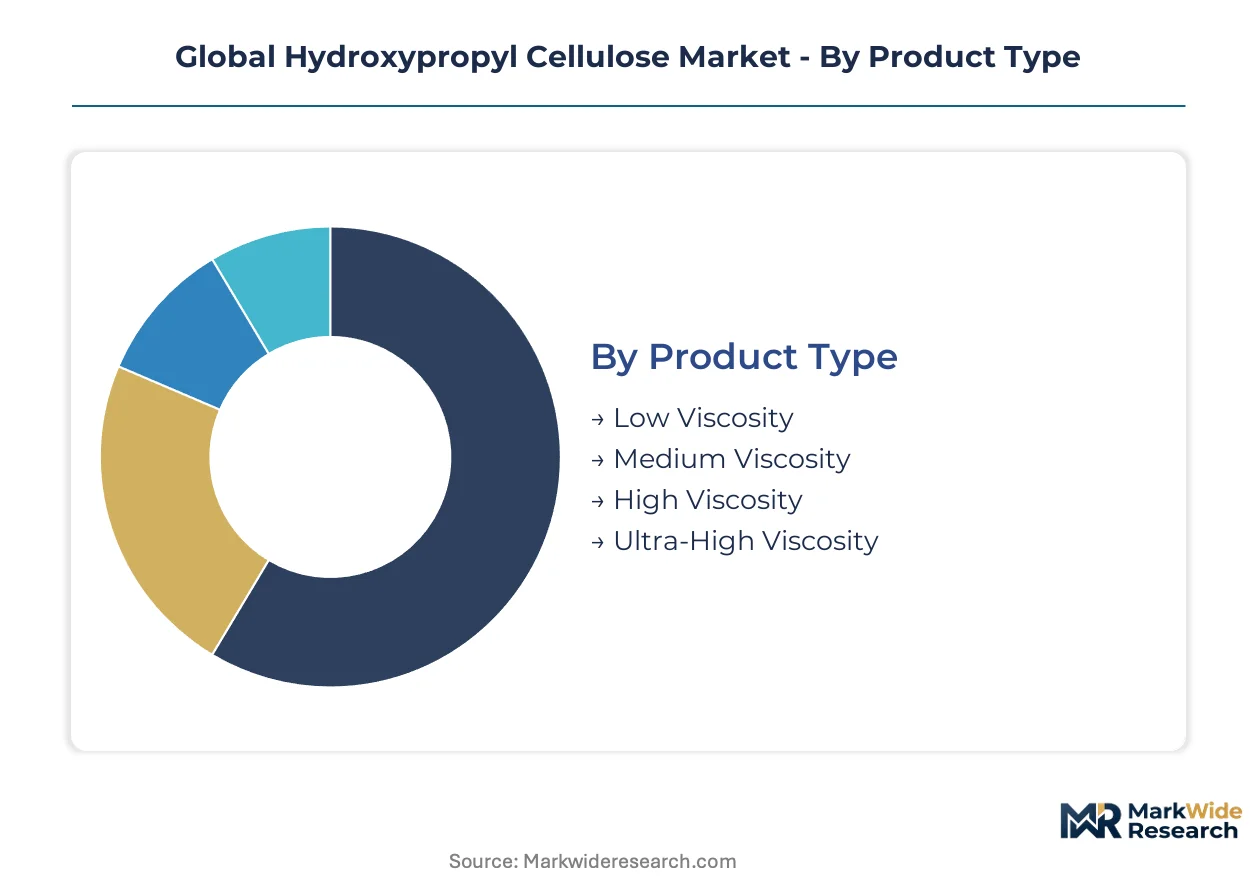
Hydroxypropyl cellulose grades diverge sharply in pricing power and qualification burden. Pharmaceutical certification separates premium supply from commodity volume, while viscosity specifications determine functional deployment across dosage forms and industrial applications.
Product Type:
Low viscosity grades dominate tonnage throughput, yet ultra-high viscosity variants capture disproportionate margin through controlled-release specialization.
- Low Viscosity:Molecular weight ranges of 80,000–140,000 Da deliver rapid dissolution profiles ideal for immediate-release tablet binding. Indian generic manufacturers under PLI scheme expansion consume this grade in high-volume oral solid dosage lines around Hyderabad.
- Ultra-High Viscosity:Molecular weights exceeding 1,000,000 Da create thermoplastic matrices for hot-melt extrusion and ophthalmic viscoelastic solutions. Japanese and South Korean artificial tear formulators specify low-particulate variants, paying specification premiums beyond standard pharmaceutical monographs.
- Medium Viscosity:Intermediate molecular weights serve multipurpose coating and thickening applications across food and industrial channels.
- High Viscosity:Sustained-release matrix formers for oral dosage applications where gel layer formation governs drug liberation kinetics.
Mature deployment sits with Low Viscosity. Newer deployment is concentrated in Ultra-High Viscosity.
Application:
Regulatory certification intensity stratifies applications into excipient-grade premiums and commodity-priced industrial consumption pools.
- Pharmaceutical Excipients:USP-NF, EP, and JP monograph compliance mandates documented genotoxic impurity profiles and IPEC-PQG GMP manufacturing. FDA guidance on excipient functionality is forcing reformulation toward performance-qualified supply, with certificates of analysis now specifying sub-ppm residual propylene oxide and 1,4-dioxane.
- Food Additives:FSSAI in India and FDA GRAS listings govern food-grade HPC deployment as stabilizers and film-formers. European EFSA evaluations on cellulose ether safety in processed foods are tightening purity documentation for imports.
- Cosmetic Formulations:Personal care applications exploit HPC film-forming and rheology modification in hair styling and skincare emulsions.
- Paints & Coatings:Architectural waterborne coatings utilize HPC as associative thickeners and pigment suspension aids.
- Adhesives:Water-based construction and packaging adhesives incorporate medium-viscosity grades for open-time extension and bond strength development.
Revenue concentration aligns with Pharmaceutical Excipients. Volume concentration remains with Food Additives.
End User Industry:
Customer scale and technical service requirements separate multinational pharmaceutical procurement from regional industrial purchasing.
- Drug Manufacturers:Top-20 generic companies consolidate excipient purchasing toward dual-source strategies, unbundling regulatory documentation from material supply. CDSCO's ICH Q3D alignment in India is upgrading domestic formulation quality standards, accelerating excipient-certified HPC qualification timelines.
- Personal Care Brands:Multinational cosmetic houses specify cosmetic-grade HPC with documented microbiological and heavy metal profiles for global formulation consistency.
- Food Processing Companies:Regional bakery and confectionery manufacturers drive commodity-grade consumption with price-sensitive purchasing patterns.
- Chemical Producers:Industrial cellulose ether distributors blend and repackage HPC for downstream coating and adhesive compounders.
Procurement sophistication peaks with Drug Manufacturers. Price sensitivity dominates Food Processing Companies.
Form:
Physical presentation determines handling economics, dissolution kinetics, and equipment compatibility across manufacturing workflows.
- Powder:Standard pulverized grades offer maximum surface area for rapid hydration in aqueous systems, dominating pharmaceutical and food processing throughput.
- Granules:Agglomerated forms reduce dusting and improve flow properties for direct compression tablet manufacturing and dry blend applications.
- Film:Pre-cast HPC films serve as edible packaging and rapid-dissolve oral strips, with Japanese developers advancing functional film dosage forms.
- Pellet:Spheronized extrudates enable precise dosing in capsule filling and multiparticulate controlled-release systems.
Processing flexibility concentrates in Powder. Differentiation potential sits with Film.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyderabad anchors pharmaceutical-grade hydroxypropyl cellulose consumption as India's PLI scheme concentrates formulation capacity within a 500-kilometer radius of the Telangana capital. Domestic excipient demand is accelerating as CDSCO tightens ICH Q3D elemental impurity standards. Multinational drug manufacturers are requalifying supply chains around this southern Indian cluster.
United States
FDA excipient functionality guidance is forcing reformulation toward performance-qualified HPC supply with documented sub-ppm residual propylene oxide profiles. Generic drug manufacturers in New Jersey and Pennsylvania are consolidating purchasing toward dual-source strategies. The Northeast corridor dominates excipient-grade consumption as procurement teams unbundle technical services from material supply.
Germany
ECHA's 2024-2026 rolling action plan is scrutinizing residual 1,4-dioxane thresholds in cellulose ethers under REACH substance evaluation. Pharmaceutical manufacturers in Frankfurt and Ludwigshafen are demanding certificates of analysis with quantified genotoxic impurity profiles. High-purity HPC grades command specification premiums across German formulation supply chains.
Japan
PMDA oversight of ophthalmic formulations is driving low-particulate ultra-high viscosity HPC demand for artificial tear and ocular drug delivery pipelines. Tokyo and Osaka pharmaceutical clusters specify grades beyond standard USP-NF and EP monographs. Japanese formulators pay premiums for documented microbiological and heavy metal profiles in viscoelastic solutions.
China
NMPA alignment with ICH Q3D is reshaping import specifications for multinational pharmaceutical manufacturers sourcing from domestic suppliers. Alkoxylation capacity concentration in Shandong and Jiangsu provinces amplifies regional supply shocks from propylene oxide feedstock volatility. CDMO expansion in Suzhou and Shanghai is upgrading excipient-certified HPC qualification timelines.
Brazil
ANVISA's emerging excipient prequalification pathway is establishing formal quality certification for Latin America's largest pharmaceutical market. São Paulo and Rio de Janeiro formulation clusters are demanding standalone regulatory documentation packages. First-mover advantage accrues to suppliers with existing USP-NF and EP documentation.
Global Hydroxypropyl Cellulose Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification-grade stratification, with excipient-certified supply commanding 15-25% specification premiums over industrial-grade volume. The vendor base concentrates around cellulose ether chemistry specialists and diversified chemical conglomerates with alkoxylation capabilities. Three archetypes dominate: vertically integrated cellulose ether specialists, diversified multinational chemical producers, and regional alkoxylation-focused manufacturers. Capacity expansion and pharmacopeial documentation investments constitute the dominant competitive moves as qualification timelines compress.
Within the premium-tier vector, Ashland Global Holdings Inc. and Shin-Etsu Chemical Co., Ltd. exemplify vertically integrated positioning across cellulose ether chemistry. Ashland occupies a position anchored in North American pharmaceutical formulation channels, while Shin-Etsu represents Japanese manufacturing scale in high-viscosity grades. Dow Chemical Company sits within the diversified multinational tier, leveraging broad chemical production infrastructure. Nippon Soda Co., Ltd. and Shandong Head Europe BV exemplify regional specialists with alkoxylation-focused capabilities in their respective geographies.
| Leading Market Players |
|---|
| Ashland Global Holdings Inc. |
| Nippon Soda Co., Ltd. |
| Shin-Etsu Chemical Co., Ltd. |
| Dow Chemical Company |
| DuPont |
| Shandong Head Europe BV |
| CP Kelco U.S. Inc. |
| Akzo Nobel |
| Sidley Chemical Co., Ltd. |
| Others |
Cost & Logistics Intelligence
Top-20 generic drug manufacturers consolidating toward dual-source excipient strategies are compressing supplier margins while amplifying specification premiums for certified grades. This buyer concentration rewards documented pharmacopeial compliance with pricing power that commodity cellulose ether producers cannot access.
Pricing Analysis
Performance-qualified supply with certificates of analysis specifying sub-ppm residual propylene oxide and 1,4-dioxane anchors value-based pricing in pharmaceutical channels. Three-tier pricing structure across excipient-certified, food-grade, and industrial-grade levels separates premium HPC from standard and economy tiers. Pricing pressure stems from HPMC and ethyl cellulose substitution in sustained-release applications where thermal gelation profiles overlap. Regional industrial buyers in coatings and adhesives exhibit highest price sensitivity, while Japanese ophthalmic formulators pay least.
Supply Chain Analysis
India's PLI scheme domestic-content incentives are reshaping regional sourcing patterns around Hyderabad and Ahmedabad formulation clusters. Alkoxylation capacity concentrates in China and Germany, drawing feedstock from propylene oxide derivatives tethered to crude oil pricing. Single-source vulnerability runs through Shandong and Jiangsu province concentration, where regional supply shocks propagate rapidly. Distribution runs through excipient distributors maintaining IPEC-PQG documentation for pharmaceutical qualification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration cost barriers and ECHA substance evaluation timelines have erected a cost-of-compliance moat that favors incumbent cellulose ether specialists with existing pharmacopeial documentation.
For Market Incumbents: Deepen backward integration into alkoxylation capacity to secure propylene oxide supply continuity against feedstock volatility. Expand dedicated low-bioburden manufacturing lines in India to capture PLI scheme downstream concentration, defending margin position against Shin-Etsu Chemical's high-viscosity grade dominance. For New Entrants and Emerging Players: Contract development organizations in North America offer the most penetrable channel for ultra-high viscosity HPC qualification, given their 40% faster twin-screw extrusion adoption cycles. Target Brazil's ANVISA prequalification pathway with standalone USP-NF and EP documentation packages to establish first-mover position in Latin America's largest pharmaceutical market. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional alkoxylation specialists with captive cellulose supply in India and China over diversified chemical conglomerates lacking excipient-grade certification infrastructure. Watch CDSCO enforcement of ICH Q3D elemental impurity limits as the inflection signal for domestic Indian manufacturer consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacopeial Documentation Investment | USP-NF and EP alignment accelerates qualification timelines for multinational pharmaceutical procurement. |
| Backward Integration into Alkoxylation | Captive propylene oxide reaction capacity insulates margins from petrochemical derivative volatility. |
| Low-Bioburden Production Line Expansion | IPEC-PQG GMP compliance unlocks excipient-certified premiums in controlled-release formulation channels. |
| Hot-Melt Extrusion Partnership Programs | Twin-screw extrusion technology adoption by Indian generics displaces solvent-based coating demand. |
| ANVISA Prequalification Pathway Entry | Formal Brazilian excipient quality certification creates defensive positioning in Latin American supply chains. |
Research Approach
Document review covered FDA guidance documents, ECHA REACH registration databases, and USP-NF monograph updates, complemented by interviews with pharmaceutical formulation scientists, excipient procurement managers at generic manufacturers, regulatory affairs specialists, and cellulose ether plant operations directors. Secondary validation drew from SEC 10-K filings of disclosed cellulose ether producers, CDSCO circulars on ICH Q3D implementation, and trade data from Indian pharmaceutical export registries. Bottom-up grade-level demand modeling and top-down pharmaceutical production capacity triangulation anchored volume estimates.
Segmented outputs across viscosity grades, application certifications, and regional production hubs were generated through the analytical framework over the projection horizon. CAGRs were derived from regression against pharmaceutical formulation output indices and excipient intensity ratios per dosage form. Forecast inputs incorporated PLI scheme capacity expansion timelines and hot-melt extrusion technology penetration curves.
Caveats apply where propylene oxide feedstock volatility, REACH substance evaluation outcomes, or pharmacopeial harmonization delays could materially shift the outlook. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Global Bio-Based Polyethylene Market
Polymers & Resins
Rigid Colored PU Foam Market
Polymers & Resins
Cellulosic Polymers Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
Fire Resins Market
Polymers & Resins
Emulsion PVC Market
Polymers & Resins
France Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
GCC Vinyl Flooring Market
Polymers & Resins
Flexible Polymer Foam Market
Polymers & Resins
China Engineering Plastics Market
Polymers & Resins
Global Resin Market
Polymers & Resins
North America and Europe Phenolic Resin Market
Polymers & Resins
Polymer Foam Market
Polymers & Resins
Polylactic Acid Market
Polymers & Resins
EVA Foam Market